
 Polycrystalline Solar Panel Market | 2026-2036
Polycrystalline Solar Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Polycrystalline Solar Panel Market Insights
Photovoltaic engineering talent is rotating from monocrystalline lines back into polycrystalline optimization as cost-sensitive markets regain share. JA Solar leverages its integrated ingot-to-module footprint to protect margin pools in emerging economies. Trina Solar anchors its competitiveness through high-volume manufacturing scale across multiple continents. JinkoSolar differentiates via R&D intensity directed at passivated emitter and rear contact upgrades for polycrystalline cells.
Polycrystalline solar panels consist of silicon wafers formed from multiple crystal structures, typically manufactured through directional solidification of molten silicon in square ingots, yielding module efficiencies ranging from 15% to 18% with lower production costs than monocrystalline alternatives. These panels serve commercial and utility-scale installations where levelized cost of electricity dominates procurement decisions over peak efficiency metrics. The utility end-user segment leads volume absorption due to solar farm developers prioritizing capital expenditure minimization across multi-hundred-megawatt projects. Bifacial product variants represent the fastest-growing category as albedo capture mechanics improve energy yield without abandoning polycrystalline cost structures. Ground-mounted installations occupy the dominant installation type position, though floating solar deployments are gaining traction in markets with land scarcity constraints.
China's MIIT enforces GB standards that dictate minimum efficiency thresholds and environmental compliance for domestic panel manufacturing, while India's BIS certification requirements create non-tariff barriers protecting local producers like Adani Solar from import competition. The EU Green Deal's carbon border adjustment mechanism will reshape export economics for polycrystalline producers serving European utility tenders. Stakeholders must monitor whether efficiency mandates from Beijing and Brussels converge sufficiently to obsolete legacy polycrystalline capacity or preserve its role in price-sensitive demand corridors.
Market Dynamics
Efficiency mandates from Beijing and Brussels are bifurcating polycrystalline capacity into compliant and legacy tiers, forcing manufacturers to choose between upgrade investments and geographic market abandonment.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for domestic module assembly are drawing capital toward Gujarat and Rajasthan manufacturing clusters, reducing import dependency for utility-scale developers.
- Bifacial albedo capture:Rear-side energy yield improvements are extending polycrystalline viability in high-reflectivity desert installations without efficiency premium penalties.
- Grid parity achievement:Southeast Asian utilities in Vietnam and Thailand now procure polycrystalline volumes based on levelized cost competitiveness against coal baseload.
Market Restraints
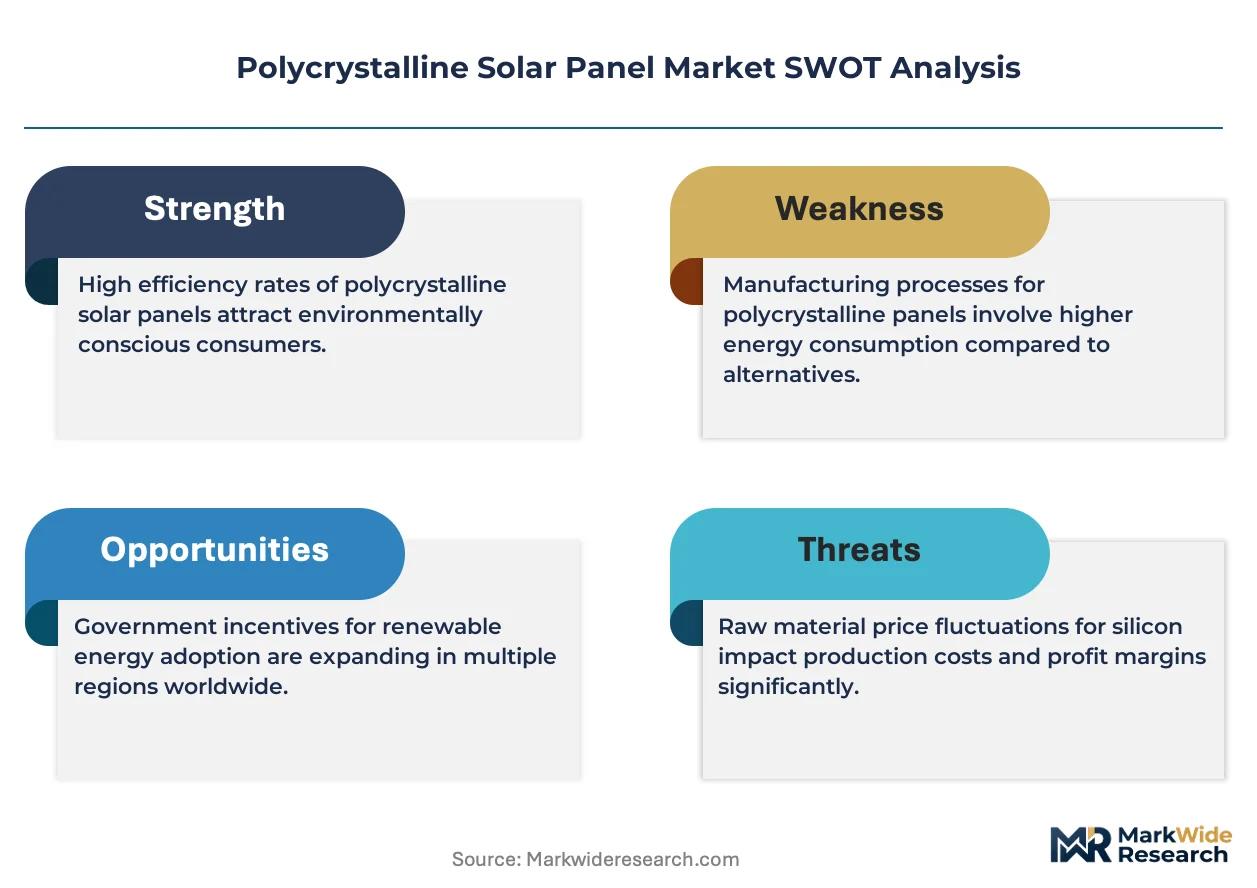
- Polysilicon input volatility:Metallurgical-grade silicon price swings transmit directly to wafer margins, compressing profitability during upstream supply crunches.
- Monocrystalline substitution:Passivated emitter and rear contact cell architectures are capturing cost-sensitive segments previously reserved for polycrystalline procurement.
- EU carbon border adjustment:The Green Deal's embodied carbon tariffs are raising landed costs for Chinese-manufactured panels entering European utility tenders.
Strategic Opportunities
- Floating solar deployment:Reservoir and coastal installations in land-constrained Japan and South Korea favor polycrystalline cost structures for buoyant platform economics.
- Agrivoltaic convergence:Dual-use agricultural installations are absorbing lower-efficiency panels where shading tolerance outweighs peak output metrics.
- India's CEA mandates:Central Electricity Authority domestic content requirements for government-backed projects are creating protected demand corridors for local polycrystalline assembly.
Industry Challenges
- Passivated emitter and rear contact engineering talent:Cell optimization expertise concentrates in monocrystalline-focused fabs, creating recruitment friction for polycrystalline R&D teams.
- BIS certification timelines:India's Bureau of Indian Standards testing queues extend project commissioning schedules, locking working capital in pre-approved inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycrystalline Solar Panel Market |
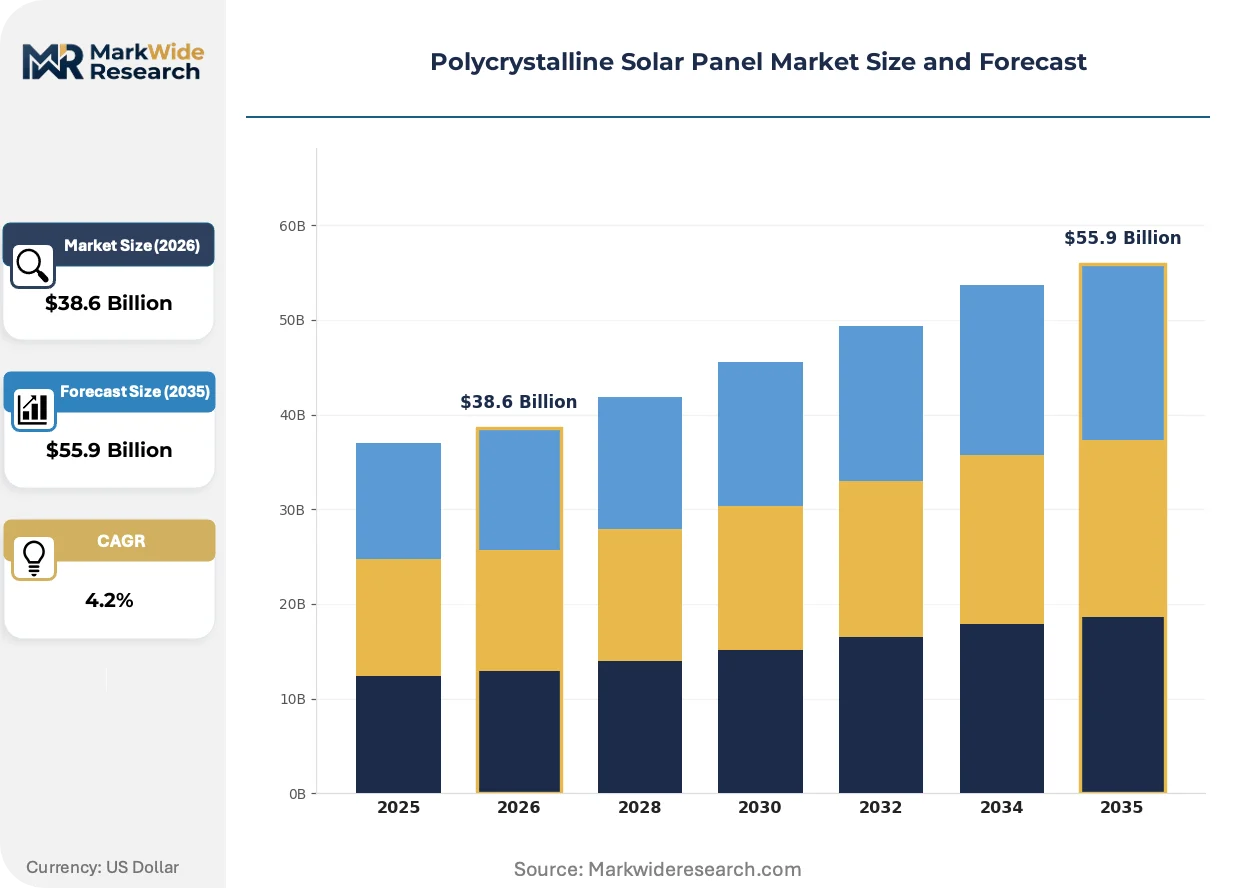
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $55.9 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Bifacial, Building-Integrated, High-Efficiency End User: Residential, Commercial, Industrial, Utility Installation Type: Ground-Mounted, Rooftop, Floating, Solar Farms Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | JA Solar, Trina Solar, JinkoSolar, Canadian Solar, LONGi Green Energy Technology, Hanwha Q CELLS, Risen Energy, Adani Solar, DMEGC Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycrystalline Solar Panel Market Trends and Innovations
Manufacturing process intensification and procurement model restructuring are redrawing competitive boundaries between integrated producers and specialized component suppliers across cost-sensitive solar markets.
Half-cut cell architectures with multi-busbar interconnection are supplanting traditional full-cell designs in polycrystalline module assembly. Indian and Southeast Asian utility developers are specifying these configurations for 1500-volt system architectures. The shift is compressing silver paste consumption per watt while maintaining compatibility with existing string inverter infrastructure.
China's MIIT is tightening GB/T 9535 efficiency thresholds for domestic panel certification, effective for new manufacturing lines commissioned after regulatory publication. Producers must achieve minimum conversion rates or forfeit eligibility for state-backed project procurement. The policy is accelerating equipment replacement cycles in legacy ingot-to-module facilities.
Engineering-procurement-construction firms are consolidating module purchasing through multi-gigawatt master supply agreements rather than project-specific tenders. This concentration is disintermediating regional distributors and compressing price discovery transparency. The pattern is most pronounced in Indian solar park developments where state nodal agencies aggregate offtake across pooled land parcels.
Polycrystalline Solar Panel Market Segmentation
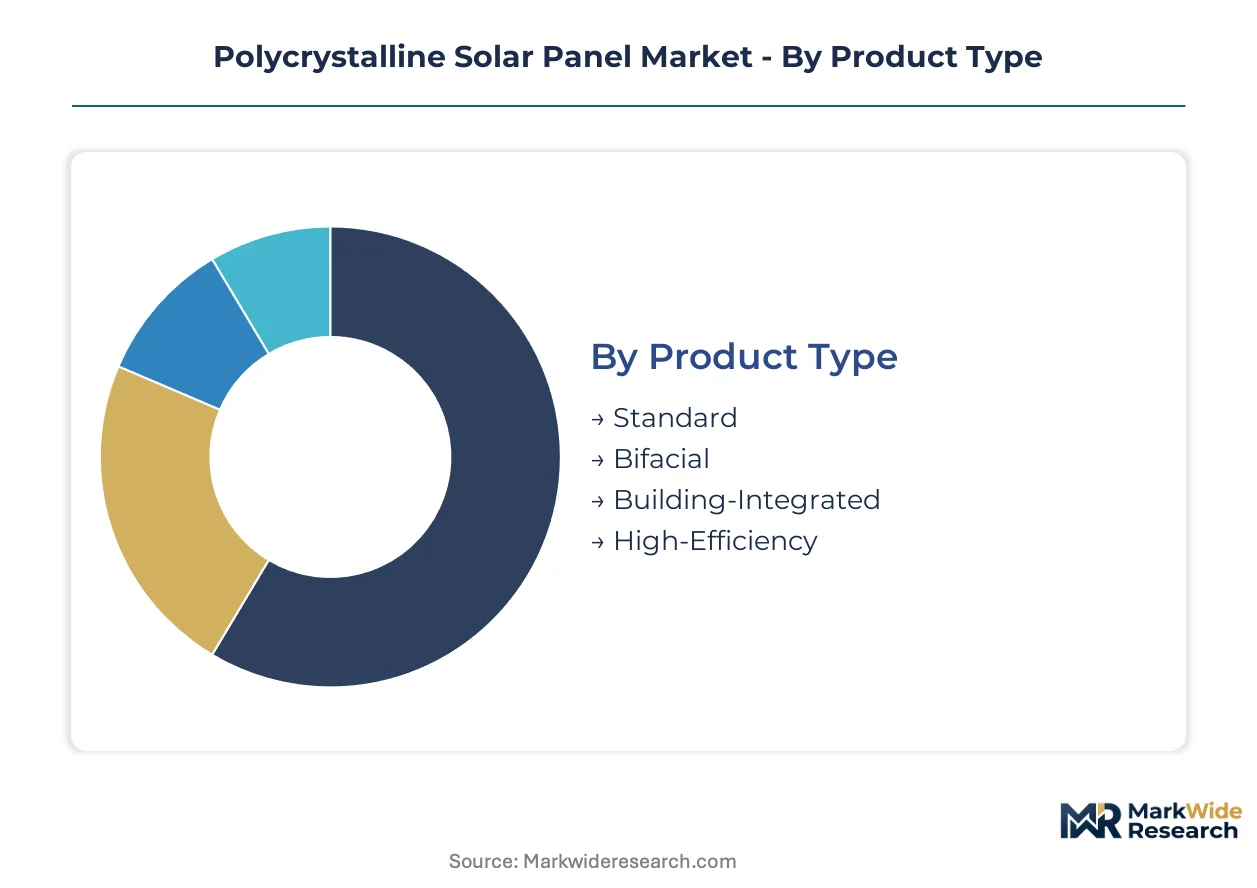
Polycrystalline panel procurement splits across product architectures, installation contexts, and channel structures that each carry distinct margin profiles and regulatory exposure. Understanding these fault lines clarifies where efficiency mandates bite hardest and where cost-driven demand persists.
Product Type:
MIIT's GB/T 9535 standards and the EU Green Deal's carbon border mechanism create divergent compliance burdens across product tiers, reshaping which variants can access protected procurement pools.
- Standard:Conventional aluminum-framed modules with 15-17% conversion efficiency dominate procurement in India's CEA-mandated government projects where domestic content requirements override efficiency premiums. These panels absorb the bulk of volume in Rajasthan and Gujarat solar parks where land abundance minimizes yield-per-watt sensitivity.
- Bifacial:Dual-glass constructions capture rear-side albedo reflection from desert and snowy surfaces, extending polycrystalline competitiveness in high-irradiance installations without abandoning cost structures. Demand concentrates in Southeast Asian utility tenders where Vietnam's EVN and Thailand's EGAT specify bifacial configurations for floating and agrivoltaic deployments.
- Building-Integrated:Frameless and aesthetic-weighted variants serve commercial rooftop retrofits where planning permissions favor visual integration over peak output.
- High-Efficiency:Passivated emitter and rear contact upgrades push polycrystalline cells toward 18%+ conversion rates for markets with tighter rooftop space constraints.
Standard panels handle the majority of throughput; bifacial variants are gaining share fastest as albedo capture economics improve.
End User:
Procurement scale and capital intensity separate customer tiers, with utility-scale offtakers commanding pricing leverage that residential channels cannot replicate.
- Utility:Multi-hundred-megawatt solar farm developers in India, Vietnam, and Thailand aggregate demand through engineering-procurement-construction master supply agreements, compressing distributor margins and privileging integrated manufacturers with captive polysilicon supply.
- Residential:Distributed rooftop installations in Japan and South Korea favor smaller module formats where installer relationships and local certification speed matter more than per-watt manufacturing cost.
- Commercial:Corporate power purchase agreement offtakers balance space constraints against sustainability commitments, often accepting efficiency premiums for faster project completion.
- Industrial:Captive consumption models at manufacturing facilities in China and India prioritize levelized cost minimization for self-generation against grid tariffs.
Utility procurement commands absolute volume leadership; residential channels are expanding most quickly as net-metering frameworks mature in select Asian markets.
Installation Type:
Mounting configuration dictates module specifications, with structural loading and environmental exposure creating divergent durability requirements.
- Ground-Mounted:Fixed-tilt and tracking systems on open land dominate Indian solar park development, with Gujarat's Charanka and Rajasthan's Bhadla complexes specifying polycrystalline modules for 1500-volt string architectures.
- Floating:Buoyant platform installations on reservoirs and coastal waters in Japan, South Korea, and Vietnam demand corrosion-resistant framing and humidity-tolerant junction boxes that add cost but avoid land scarcity premiums.
- Rooftop:Distributed commercial and industrial systems face structural load limits and shading complexity that favor lighter, smaller-format modules.
- Solar Farms:Utility-scale aggregations above 100 MW concentrate procurement through centralized tenders with stringent domestic content and efficiency thresholds.
Ground-mounted infrastructure processes the largest module volumes; floating installations are climbing the fastest as land-constrained markets expand reservoir-based capacity.
Distribution Channel:
Channel structure determines pricing transparency and working capital requirements, with direct contracting displacing intermediary layers in large-scale procurement.
- Direct Sales:Manufacturer-to-developer contracting for multi-gigawatt Indian solar park tenders eliminates distributor markups and locks in volume commitments across pooled land parcels.
- Distributors:Regional inventory holders serve fragmented commercial and residential demand where project timing unpredictability requires local availability.
- E-commerce:Digital procurement platforms gain traction among small-scale installers in price-sensitive emerging markets where specification standardization reduces pre-purchase inspection needs.
- Retail:Hardware and electrical supply chains reach residential end-users through installer networks with embedded product recommendations.
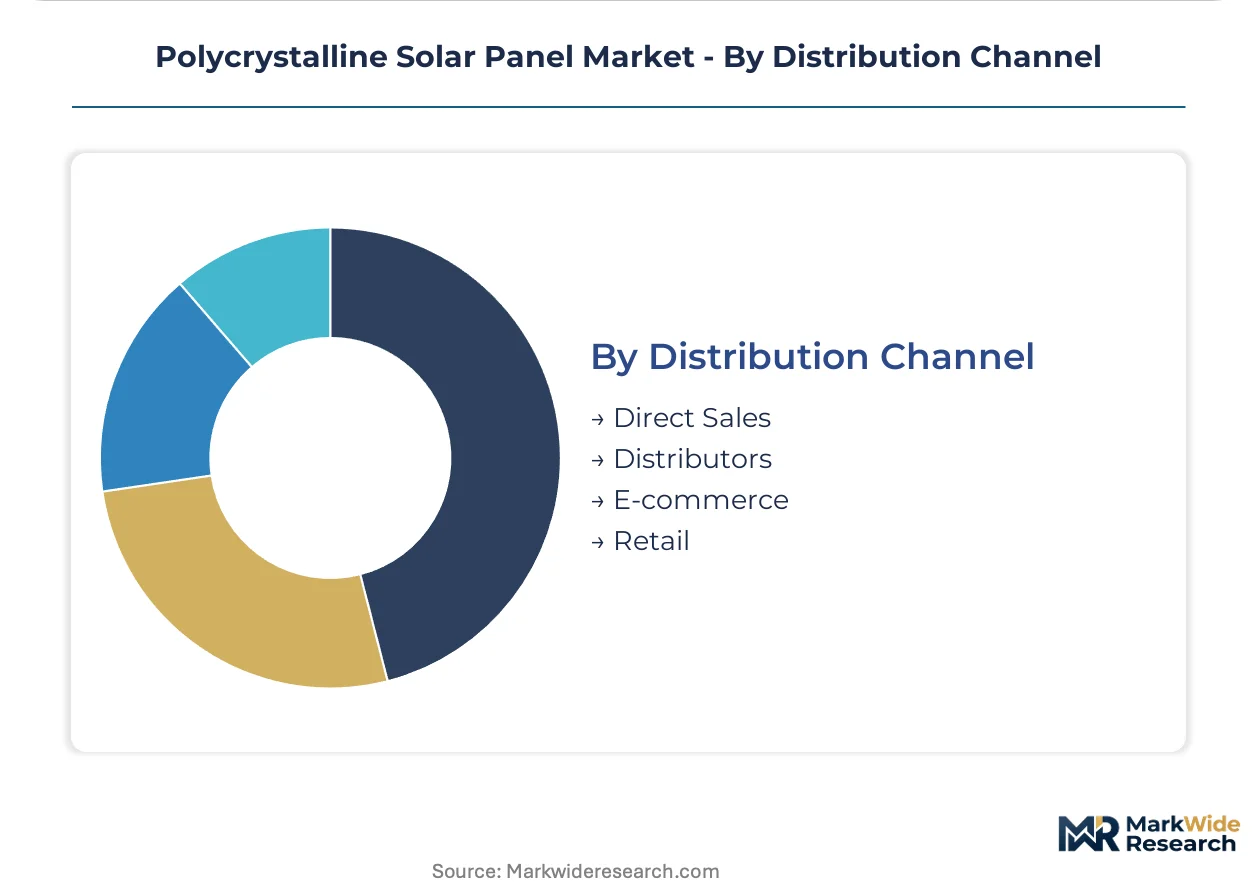
Direct sales channels capture the dominant share of megawatt-scale transactions; e-commerce routes are expanding most rapidly among smaller project developers seeking price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards and efficiency mandates from Beijing anchor polycrystalline production governance, while India's PLI scheme and the EU Green Deal's carbon border mechanism reshape demand geography across three continents.
China
Domestic module demand concentrates in western provinces where utility-scale solar parks absorb gigawatt volumes. MIIT enforces GB/T 9535 efficiency thresholds that accelerate equipment replacement in legacy ingot-to-module facilities. Xinjiang and Inner Mongolia host the dominant polysilicon-to-wafer manufacturing clusters.
India
Gujarat and Rajasthan solar parks drive polycrystalline absorption as land abundance minimizes yield-per-watt sensitivity. The Central Electricity Authority mandates domestic content requirements for government-backed projects, protecting local assembly operations. Adani Solar anchors manufacturing in Mundra Special Economic Zone.
Vietnam
EVN utility tenders specify bifacial configurations for floating and ground-mounted deployments as grid parity against coal baseload improves. The national power development plan prioritizes solar capacity additions through independent power producer frameworks. Ninh Thuan and Binh Thuan provinces concentrate project development.
Germany
Utility tenders under the EU Green Deal face carbon border adjustment pressures that raise landed costs for imported panels. The Bundesnetzagentur auction mechanisms favor lowest-cost bids, preserving polycrystalline viability in price-sensitive segments. Eastern Länder host repurposed industrial zones for module assembly.
Japan
Reservoir-based floating solar installations in land-constrained prefectures favor polycrystalline cost structures for buoyant platform economics. METI feed-in-tariff adjustments compress developer margins, intensifying procurement price sensitivity. Hyogo and Chiba prefectures lead floating capacity deployment.
Polycrystalline Solar Panel Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the polycrystalline value chain. Integrated ingot-to-module producers with captive polysilicon supply command margin protection during upstream volatility. The vendor base stratifies into three tiers: global-scale integrated manufacturers, regional specialists with protected domestic demand, and technology-focused R&D-intensive operators. Dominant competitive moves include backward integration into metallurgical-grade silicon refining and multi-gigawatt master supply agreement consolidation with engineering-procurement-construction firms.
Among China-based integrated producers, JA Solar and Trina Solar occupy positions representing scale-driven manufacturing archetypes with multi-continent production footprints. JinkoSolar exemplifies the R&D-intensive tier, anchoring competitive differentiation through passivated emitter and rear contact engineering directed at polycrystalline cell upgrades. These three entities represent the strategic archetypes—scale integration, geographic diversification, and technology intensity—that define competitive positioning in cost-sensitive solar markets.
| Leading Market Players |
|---|
| JA Solar |
| Trina Solar |
| JinkoSolar |
| Canadian Solar |
| LONGi Green Energy Technology |
| Hanwha Q CELLS |
| Risen Energy |
| Adani Solar |
| DMEGC Solar |
| Others |
Pricing and Supply Chain Analysis
Metallurgical-grade silicon substitution for electronic-grade polysilicon in wafer manufacturing is compressing input costs while simultaneously shifting supply geography toward Xinjiang and Inner Mongolia refining clusters and resetting module pricing economics for utility-scale procurement.
Pricing Analysis
Chinese-manufactured panels land in European utility tenders at 15-20% premiums over Southeast Asian equivalents after EU carbon border adjustment calculations. Three-tier pricing structure across premium efficiency, standard utility-grade, and economy residential levels separates certified bifacial products from legacy aluminum-framed configurations. Pricing pressure stems from monocrystalline passivated emitter and rear contact cells capturing cost-sensitive segments previously reserved for polycrystalline procurement. Utility-scale engineering-procurement-construction aggregators exhibit highest price sensitivity; commercial rooftop developers accepting efficiency premiums show lowest.
Supply Chain Analysis
Strategic stockpiling of metallurgical-grade silicon dominates procurement behavior among integrated manufacturers anticipating polysilicon price volatility, while project developers maintain just-in-time module inventories to minimize working capital lockup during BIS certification queues. Supply concentrates in China, Vietnam, and India for wafer and cell processing; polysilicon refining anchors in Xinjiang and Inner Mongolia. Raw material dependencies span metallurgical-grade silicon, silver paste for metallization, and aluminum framing. Single-source vulnerability concentrates in Chinese polysilicon refining exposed to EU carbon border tariffs. Distribution runs through direct manufacturer-to-developer contracting for utility-scale tenders, bypassing regional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polycrystalline module procurement is approaching a platform-economics inflection where 1500-volt system standardization and engineering-procurement-construction master supply agreement consolidation create winner-take-most dynamics for integrated producers with captive material supply.
For Market Incumbents: Fortify margin pools through backward integration into metallurgical-grade silicon refining and multi-gigawatt master supply agreement consolidation with Indian and Southeast Asian engineering-procurement-construction firms. Monocrystalline substitution threatens volume retention in cost-sensitive utility tenders; captive polysilicon supply and BIS certification pre-approval accelerate inventory turns. For New Entrants and Emerging Players: Differentiate on floating solar platform specialization and agrivoltaic dual-use configurations where shading tolerance outweighs peak efficiency metrics. White-space concentrates in Japan's reservoir-based installations and India's CEA-mandated domestic content corridors. Go-to-market leverage rests on corrosion-resistant framing engineering and humidity-tolerant junction box certification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed engineering-procurement-construction contractors holding multi-gigawatt offtake commitments in Gujarat and Rajasthan solar parks. Long-term viability hinges on regulatory convergence between MIIT efficiency mandates and EU carbon border thresholds. Watch for bifacial albedo capture economics crossing grid parity thresholds in Vietnam and Thailand as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Refining | Xinjiang and Inner Mongolia metallurgical-grade silicon clusters protect margin pools during upstream volatility. |
| Multi-Gigawatt Master Supply Agreement Consolidation | Indian state nodal agencies aggregate offtake across pooled land parcels in Gujarat and Rajasthan. |
| Bifacial Product Line Expansion | EVN and EGAT tenders specify dual-glass configurations for floating and agrivoltaic deployments. |
| CEA-Mandated Domestic Content Compliance | Adani Solar and local assemblers capture protected procurement pools in government-backed projects. |
| 1500-Volt System Architecture Certification | Half-cut cell multi-busbar designs reduce silver paste consumption while maintaining string inverter compatibility. |
Research Methodology
A spread of perspectives from utility planning officers, independent power producer project developers, engineering-procurement-construction contractors, grid operators, and polysilicon supply specialists converged on the working assumptions underlying demand and pricing trajectories. Primary fieldwork combined structured interviews with secondary validation against MIIT GB standard filings, CEA domestic content requirement circulars, EU Green Deal carbon border mechanism documentation, and engineering-procurement-construction tender databases. Bottom-up module shipment analysis triangulated against top-down solar capacity addition forecasts across the analysis window.
Segmentation dimensions modeled span product architecture (standard, bifacial, building-integrated, high-efficiency), end-user tier (utility, residential, commercial, industrial), installation type (ground-mounted, floating, rooftop), and distribution channel structure (direct sales, distributor, e-commerce, retail). CAGRs were derived from installed base evolution and replacement cycle dynamics, cross-referenced against polysilicon price elasticity assumptions and regulatory efficiency mandate compliance thresholds. Forecast inputs incorporated albedo capture economics for bifacial deployments and land scarcity premiums driving floating solar adoption.
Forecasts assume regulatory continuity in MIIT GB/T 9535 efficiency mandates, EU Green Deal carbon border adjustment mechanisms, and India's PLI scheme and CEA domestic content requirements; material policy shifts would require re-modeling supply geography and pricing tier viability. Revision becomes warranted when monocrystalline passivated emitter and rear contact cost curves intersect polycrystalline production economics or when EU carbon border tariffs exceed utility tender price elasticity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
United Kingdom Distributed Solar Power Generation Market