
 United Kingdom Distributed Solar Power Generation Market | 2026-2036
United Kingdom Distributed Solar Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Distributed Solar Power Generation Market Analytics
Aftermarket service revenue from inverter replacement and battery augmentation is rewriting margin capture across the United Kingdom distributed solar value chain. Anesco Limited leverages its asset management platform to sustain recurring income from operational portfolios. EDF Renewables UK anchors utility-scale expertise into distributed project development. Trina Solar competes on module efficiency gains and manufacturing scale.
United Kingdom distributed solar power generation encompasses photovoltaic systems below five megawatts capacity, typically interconnecting at distribution voltage levels through net metering or export arrangements. These installations deploy monocrystalline silicon panels with conversion efficiencies exceeding twenty-one percent, paired with string or hybrid inverters, to offset onsite consumption or feed surplus electricity into local networks. Residential end users dominate deployment volumes though commercial and industrial segments concentrate larger average system sizes and faster payback periods. Rooftop installation type leads in urban density zones while ground-mounted systems expand across agricultural landholdings where landowner lease structures improve project returns.
Ofgem administers the Smart Export Guarantee obligating licensed suppliers to offer export tariffs for small-scale generators. MCS certification governs installer competency and product eligibility for consumer protection schemes. Building regulations across England, Scotland, and Wales mandate structural assessments and electrical compliance for rooftop installations. Stakeholders must monitor grid connection queue reforms and distribution network operator flexibility procurement mechanisms as electrification strains local infrastructure capacity.
Market Dynamics
Grid connection queues across England and Wales now stretch beyond 24 months for distribution network upgrades, forcing developers toward battery co-location and flexibility service contracts to monetize constrained export capacity.
Growth Catalysts
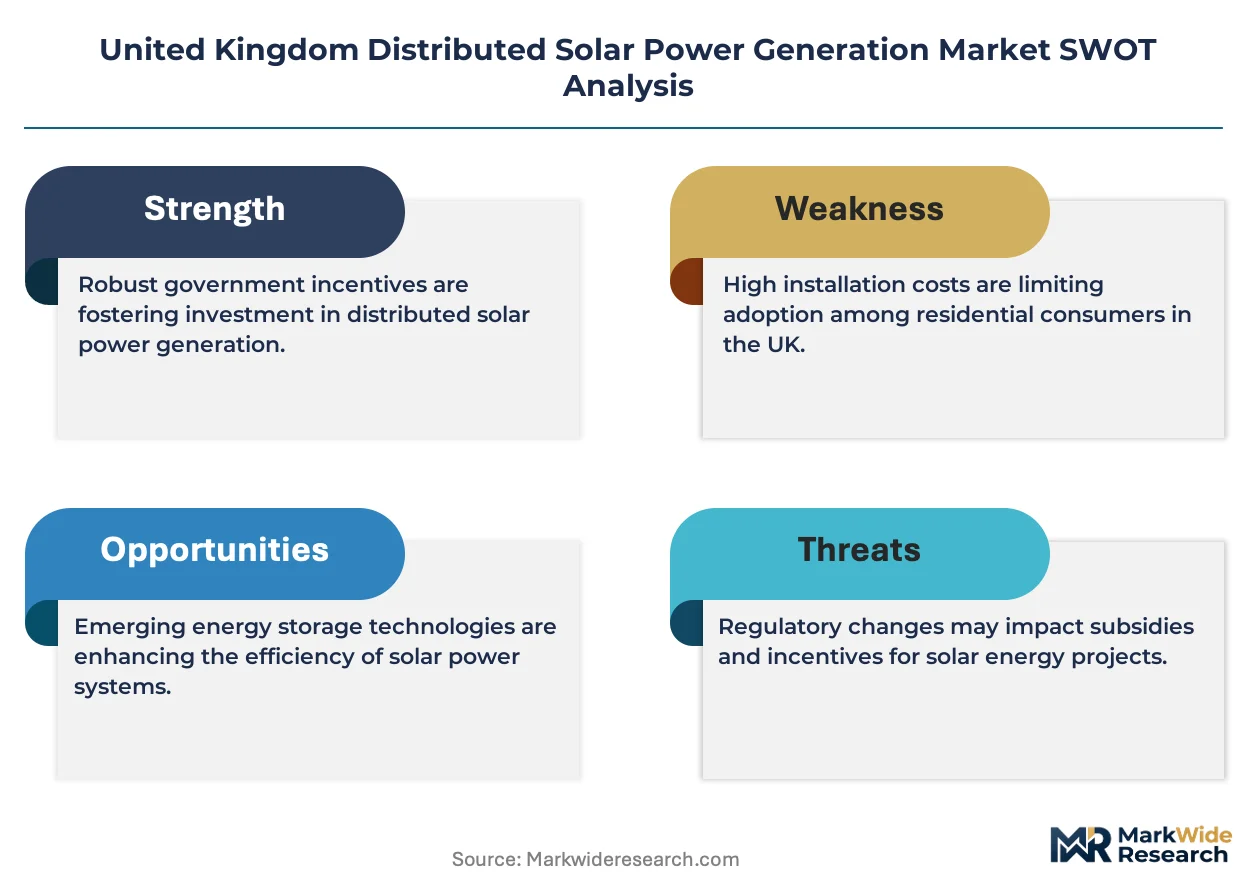
- Smart Export Guarantee:Ofgem's tariff mandate obligates licensed electricity suppliers to compensate small-scale generators for surplus exports, sustaining project economics below 5MW capacity thresholds.
- Agricultural land leasing:Farmers across East Anglia and the South West are converting marginal acreage to ground-mounted arrays under 25-year lease structures that diversify rural income streams.
- Monocrystalline PERC technology:Panel efficiencies exceeding 21 percent now dominate residential and commercial rooftops, shrinking payback periods and expanding viable roof footprints.
Market Restraints
- Distribution network capacity:Local grid infrastructure in Devon, Cornwall, and rural Wales lacks headroom for new solar export, triggering costly reinforcement delays or zero-export constraints.
- Polysilicon price volatility:Input cost swings for wafer-grade silicon transmit directly to module pricing, compressing installer margins and destabilizing project finance assumptions.
- Building regulation friction:Structural assessments mandated under England and Wales building codes add 4-8 weeks to rooftop commissioning timelines, eroding seasonal installation windows.
Strategic Opportunities
- Northern England irradiance gap closure:Yorkshire and Lancashire present underserved addressable markets where falling system costs are extending project viability beyond traditional southern concentration zones.
- Agrivoltaics integration:Dual-use solar arrays permitting continued grazing or cropping beneath elevated panels unlock planning permission pathways on agricultural landholdings previously restricted to food production.
- Distribution flexibility procurement:National Grid ESO and regional distribution network operators are tendering for battery-solar hybrid assets to manage local voltage constraints and peak demand.
Industry Challenges
- MCS installer certification bottlenecks:Microgeneration Certification Scheme competency requirements constrain qualified workforce supply, extending customer wait times and inflating labor rates.
- Hybrid inverter integration complexity:Battery-solar system commissioning demands electrical engineering skills spanning DC coupling, energy management software, and grid code compliance that legacy solar-only installers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Distributed Solar Power Generation Market |
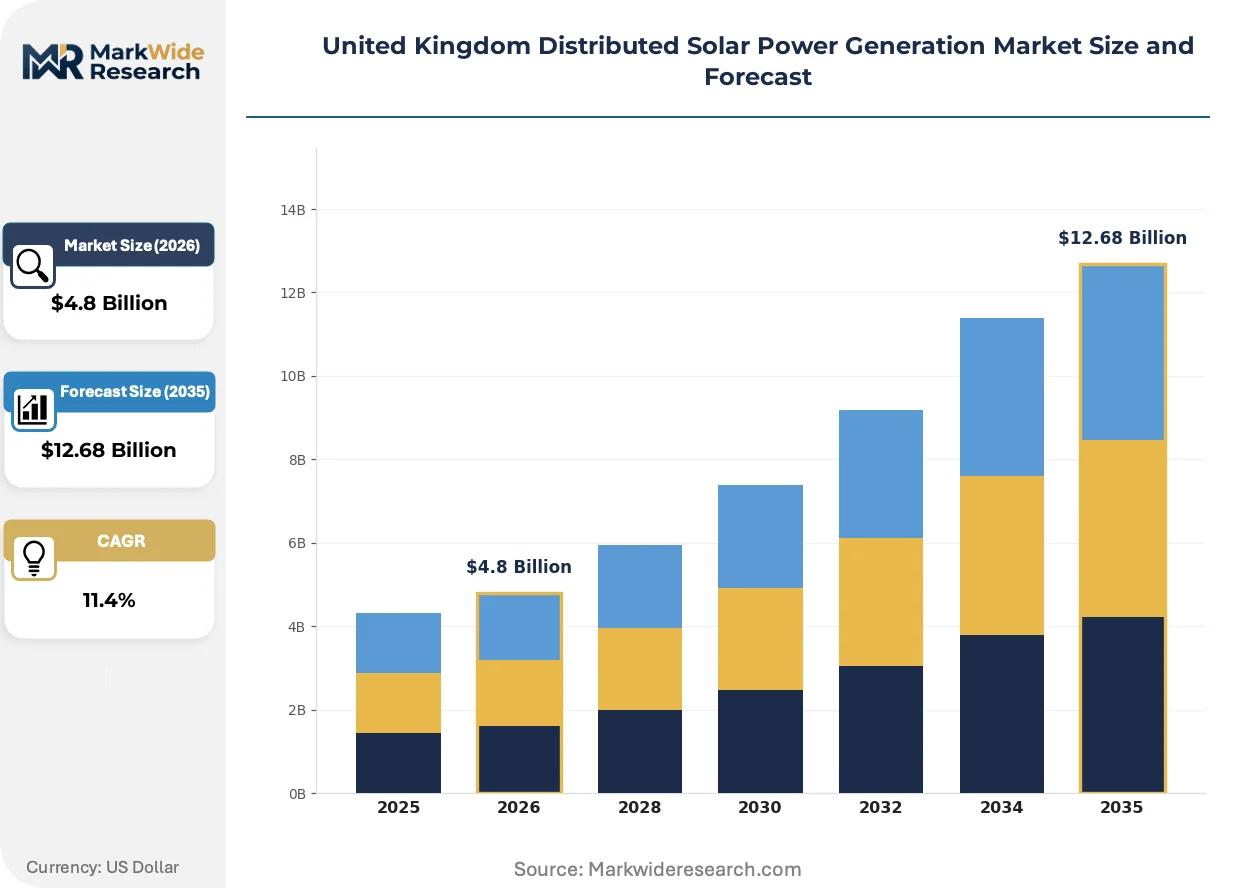
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Mounting Systems, Batteries End User: Residential, Commercial, Industrial, Agricultural Installation Type: Rooftop, Ground-mounted, BIPV, Off-grid Technology: Monocrystalline, Polycrystalline, Thin-film, Concentrated Solar Power |
| Companies Covered | Anesco Limited, EDF Renewables UK, British Solar Renewables, Trina Solar, NextEnergy Solar Fund, Quinbrook Infrastructure Partners, BayWa r.e., BElectric, Solarsense UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Distributed Solar Power Generation Market Evolving Landscape
Hardware commoditization is compressing module margins and redirecting competitive differentiation toward software-enabled asset management, predictive maintenance, and grid flexibility orchestration platforms.
String inverter architecture is migrating from centralised 50kW units toward module-level power electronics with rapid shutdown compliance and panel-level monitoring granularity. Commercial installers serving C&I rooftops are specifying these systems to reduce mismatch losses and accelerate fault isolation. The shift is compressing traditional string inverter replacement cycles and expanding recurring software subscription revenue pools.
Ofgem's ongoing review of distribution network charging frameworks is recalibrating connection cost allocation between generators and network operators. Industrial solar developers face exposure to deeper connection charges unless co-located storage qualifies for shared infrastructure treatment. The reform is accelerating battery-solar hybrid project structuring in constrained grid zones.
Aggregators are consolidating residential battery fleets into virtual power plants bidding into frequency response and wholesale arbitrage markets. This procurement model unbundles hardware ownership from energy service revenue, shifting customer value propositions from bill savings to income generation. The model is penetrating fastest in southern England where smart meter penetration and export tariff differentials create viable stacking economics.
United Kingdom Distributed Solar Power Generation Market Segmentation
Segmentation reveals how distributed solar economics shift across hardware configurations, customer profiles, and site constraints. Understanding these dimensions clarifies where technology premiums command pricing power versus where commoditization erodes margins.
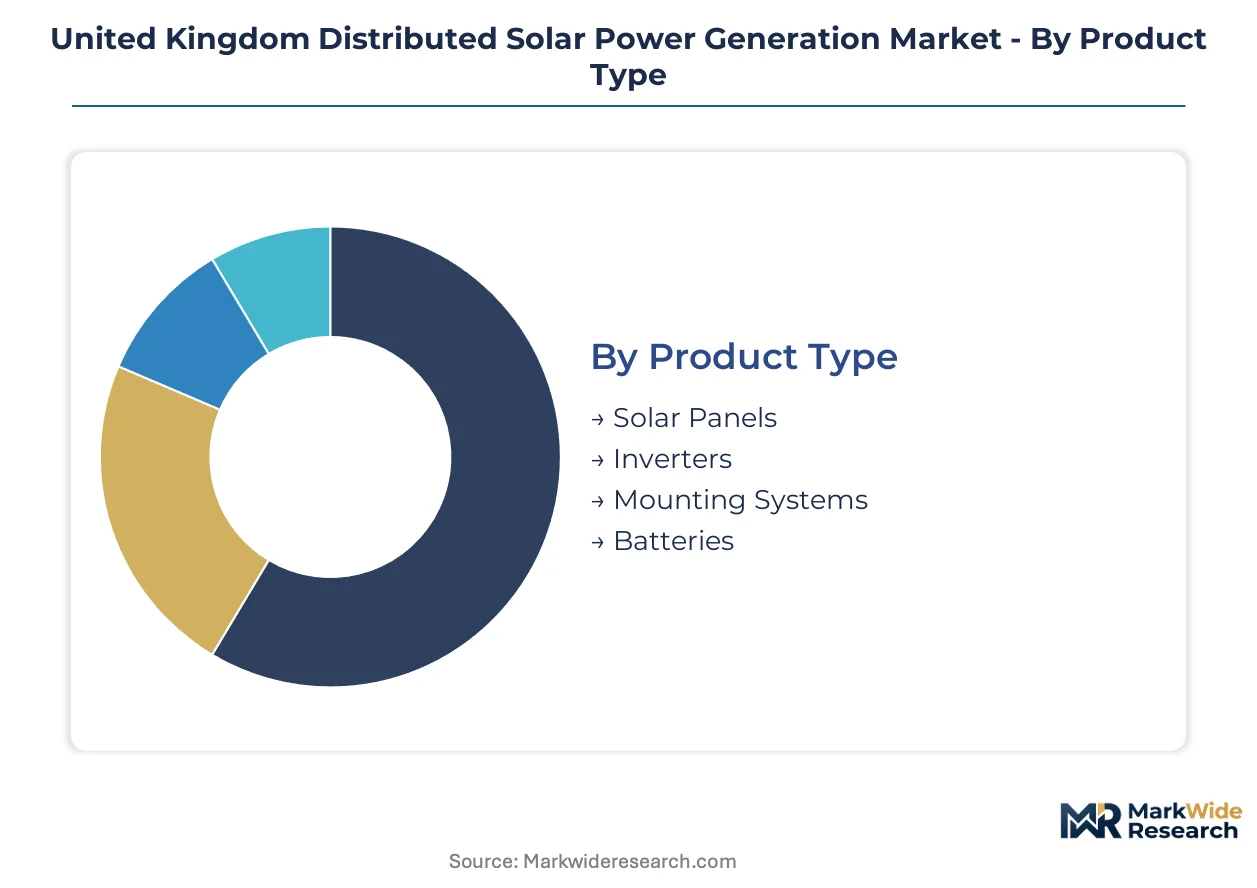
Product Type:
The hardware stack spans generation, conversion, storage, and structural integration, each tier carrying distinct margin profiles and replacement cycles.
- Solar Panels:Monocrystalline PERC and TOPCon architectures now dominate procurement, with module efficiencies above 21 percent shrinking rooftop footprint requirements. Residential installers in southern England prioritize these units for constrained urban roofscapes where every square meter counts.
- Batteries:Lithium iron phosphate chemistry underpins co-located storage systems that unlock export flexibility and grid services revenue. Agricultural ground-mounted projects in East Anglia increasingly pair solar arrays with battery containers to capture time-of-use arbitrage and capacity market payments.
- Inverters:String and hybrid architectures manage DC-to-AC conversion with varying degrees of module-level optimization and storage integration capability.
- Mounting Systems:Roof-integrated, ballasted, and pile-driven structures adapt to structural load limits and ground conditions across England and Wales.
Established volume favors Solar Panels; emerging adoption favors Batteries.
End User:
Customer archetypes range from household bill optimizers to rural income diversifiers, each segment demanding tailored financing and service models.
- Residential:Owner-occupied and social housing deployments typically size systems for self-consumption maximization rather than export revenue. MCS certification requirements and consumer protection schemes govern installer selection and product eligibility across England, Scotland, and Wales.
- Agricultural:Farmers leverage marginal land and barn rooftops under long-term lease or ownership structures that stabilize volatile commodity income. Ground-mounted arrays on East Anglian arable land and dairy farm rooftops in the South West concentrate deployment.
- Commercial:Retail, warehouse, and office installations target daytime load matching with payback periods compressed by high electricity tariffs.
- Industrial:Manufacturing and processing facilities deploy larger rooftop and brownfield ground systems with in-house engineering capabilities.
Commercial and Industrial segments concentrate larger average system sizes; Agricultural ground-mount is climbing the fastest as lease structures mature.
Installation Type:
Site topology determines planning pathway complexity, grid connection voltage level, and structural engineering requirements.
- Rooftop:Retrofit and new-build applications dominate urban and suburban density zones, constrained by structural load assessments and electrical compliance timelines. Building regulations across England and Wales mandate four-to-eight-week assessment periods that compress seasonal installation windows.
- Ground-mounted:Agricultural and brownfield deployments access lower per-watt installation costs but face planning scrutiny on greenfield sites. Devon, Cornwall, and rural Wales struggle with distribution network capacity limits that trigger zero-export constraints or costly reinforcement delays.
- BIPV:Building-integrated photovoltaic systems replace conventional cladding and roofing materials, serving new construction and deep retrofit markets.
- Off-grid:Standalone systems serve remote properties and mobile applications beyond distribution network reach.
Rooftop retains deployment volume leadership; Ground-mounted is gaining share fastest as agricultural leasing structures proliferate.
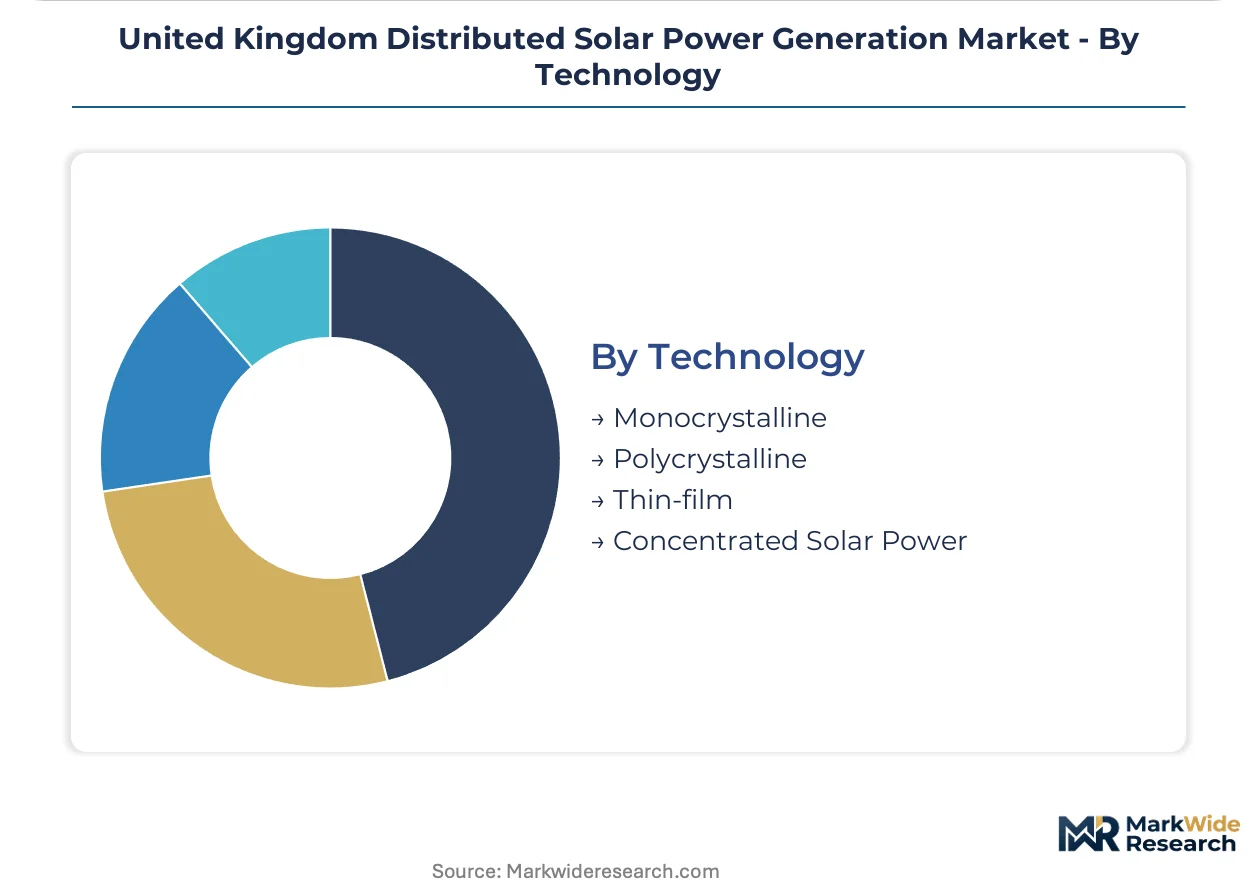
Technology:
Cell architecture and manufacturing process define efficiency ceilings, temperature coefficients, and supply chain exposure.
- Monocrystalline:Single-crystal silicon ingots yield the highest commercial efficiencies and dominate residential and commercial procurement. PERC and TOPCon variants from Tier-1 manufacturers anchor project finance assumptions.
- Polycrystalline:Multi-crystal silicon offers lower capital cost but efficiency penalties that have marginalized deployment in space-constrained applications.
- Thin-film:Cadmium telluride and amorphous silicon architectures suit specific BIPV and weight-constrained applications.
- Concentrated Solar Power:Thermal concentration systems with thermal storage capability find niche utility-scale applications but minimal distributed deployment.
Monocrystalline commands premium positioning; Polycrystalline retains residual cost-sensitive volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive agricultural buyers in East Anglia respond aggressively to module cost shifts, while premium-tolerant commercial operators in London accept efficiency premiums for constrained roof footprints.
South East England
Commercial warehouse operators and data center campuses drive rooftop demand across the M25 corridor where grid access fees and land scarcity inflate project costs. Ofgem's Smart Export Guarantee sustains export economics for sub-5MW installations clustered around Slough, Reading, and Gatwick. The Thames Valley technology corridor concentrates battery-solar hybrid deployments serving corporate renewable energy procurement targets.
South West England
Dairy farm rooftops and cider orchard ground-mount arrays dominate deployment across Devon and Cornwall where agricultural diversification incentives outweigh irradiance penalties. Distribution network capacity constraints in rural Cornwall trigger zero-export restrictions or reinforcement delays exceeding 24 months. The Exeter-Plymouth axis hosts installer training hubs addressing MCS certification bottlenecks.
East Anglia
Arable land leasing structures convert marginal acreage to ground-mounted solar across Norfolk and Suffolk where commodity price volatility drives income diversification. Natural England's biodiversity net gain requirements shape planning applications on former agricultural land. The Cambridge-Norwich corridor attracts agrivoltaic pilot projects testing dual-use grazing configurations beneath elevated arrays.
North West England
Industrial estates in Greater Manchester and Liverpool retrofit expansive warehouse rooftops where daytime load matching improves payback periods against volatile wholesale tariffs. The region's lower irradiance levels demand larger system sizes to achieve viability, favoring commercial over residential segments. Oldham and Rochdale host emerging installer networks extending MCS-certified service coverage northward.
Wales
Hill farm sheep grazing operations in Powys and Ceredigion pilot agrivoltaic arrays where dual-use planning permissions overcome agricultural land protection restrictions. SP Energy Networks and Welsh Water collaborate on constrained grid zone flexibility procurement. The Swansea Bay city region concentrates building-integrated photovoltaic demonstrations on social housing retrofit programs.
United Kingdom Distributed Solar Power Generation Market Competitive Landscape
Capability concentration sits with integrated asset managers who command recurring service revenue; scale advantage sits with module manufacturers leveraging global procurement leverage. The vendor base stratifies across three tiers: vertically integrated energy majors with balance sheet capacity, specialist distributed developers with local planning expertise, and hardware suppliers competing on conversion efficiency and manufacturing scale. Dominant competitive moves include battery-solar hybrid portfolio assembly and geographic expansion into underserved northern English markets.
Within the specialist developer tier, Anesco Limited and British Solar Renewables exemplify asset-light platforms monetizing operational portfolios through long-term service contracts. Trina Solar anchors the hardware-supplier vector as a Chinese manufacturer whose module efficiency gains reshape rooftop economics. EDF Renewables UK represents the integrated energy major archetype, deploying utility-scale development discipline into sub-5MW distributed project structuring.
| Leading Market Players |
|---|
| Anesco Limited |
| EDF Renewables UK |
| British Solar Renewables |
| Trina Solar |
| NextEnergy Solar Fund |
| Quinbrook Infrastructure Partners |
| BayWa r.e. |
| BElectric |
| Solarsense UK |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese polysilicon refining is compressing module prices across the United Kingdom distributed solar market, forcing Tier-1 manufacturers to absorb margin erosion while installers capture improved project economics. This utilization imbalance simultaneously accelerates supplier consolidation in wafer-grade silicon and expands viable deployment footprints for price-sensitive agricultural ground-mount segments.
Pricing Analysis
Aftermarket service revenue from inverter replacement cycles and battery augmentation contracts now drives lifetime value capture across installer portfolios. Three-tier pricing structure across premium, standard, and economy levels segments the hardware stack, with MCS-certified Tier-1 systems commanding installation premiums over uncertified alternatives. Cost compression in module supply is intensifying because Chinese manufacturing scale has outstripped European demand absorption, eroding manufacturer margins while expanding addressable roof footprints for residential buyers. Agricultural ground-mount developers in East Anglia exhibit highest price sensitivity, prioritizing lowest per-watt capital outlay over efficiency premiums; conversely, commercial warehouse operators in the Thames Valley accept module efficiency premiums to maximize generation density on constrained rooftops.
Supply Chain Analysis
Contract manufacturing concentration rests with Chinese integrated cell-module producers and Southeast Asian assembly facilities serving European tariff-exempt channels. Geographic supply concentration centers on China for polysilicon and wafer production, Vietnam and Thailand for module assembly under EU anti-circumvention protocols, and Germany for string inverter engineering. Raw material dependencies hinge on metallurgical-grade silicon from Xinjiang, silver paste for cell metallization, and lithium carbonate for co-located storage systems. Single-source vulnerability in polysilicon refining creates exposure to trade remedy investigations or forced labor due diligence disruptions. Distribution runs through national distributor networks serving MCS-certified installer bases, with direct procurement emerging for utility-scale developer portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among agricultural landholding aggregators and corporate energy procurement consortia, fragmenting the traditional residential-dominated demand base and compressing installer margins through volume tendering.
For Market Incumbents: Harden recurring revenue streams through captive asset management platforms that lock in operational service contracts across installed portfolios. Deepen vertical integration into battery-solar hybrid system commissioning to capture margin pools beyond hardware supply. The emerging threat of zero-export grid constraints demands investment in flexibility service orchestration software to maintain project viability in constrained zones like Devon and Cornwall. For New Entrants and Emerging Players: Northern England commercial rooftops in Greater Manchester and Liverpool represent the most penetrable entry point, where lower irradiance levels have historically suppressed incumbent presence and daytime load matching economics are improving against volatile wholesale tariffs. Yorkshire agricultural ground-mount arrays present secondary white-space opportunity where falling system costs are closing viability gaps with southern England. A contractor-certified go-to-market angle leveraging MCS accreditation partnerships accelerates market access without legacy installer network dependencies. For Investors and Strategic Acquirers: Long-term, this sits as a grid-services infrastructure play because distributed solar-battery hybrid assets are being recharacterized as flexibility providers rather than pure generation capacity. Acquisition targets should emphasize operational platforms with contracted grid services revenue and established distribution network operator relationships. The signal to watch is Ofgem's distribution charging reform implementation, which will recalibrate connection cost allocation and accelerate battery co-location economics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Solar Hybrid Portfolio Assembly | Captures flexibility service revenue streams from National Grid ESO procurement tenders. |
| MCS Certification Network Expansion | Addresses installer workforce bottlenecks constraining customer wait times across England and Wales. |
| Agrivoltaic Planning Permission Pathway | Unlocks agricultural landholdings previously restricted by Natural England biodiversity requirements. |
| Distribution Flexibility Contracting | Monetizes constrained export capacity through regional distribution network operator tenders. |
| Northern England Geographic Expansion | Extends addressable market beyond traditional southern irradiance concentration zones. |
Research Methodology
Initial hypotheses were tested against primary input from distributed solar developers, MCS-certified installation contractors, agricultural landholding managers, and distribution network operator planning officers and refined through secondary validation. Primary fieldwork encompassed structured interviews with project finance arrangers, EPC contractors, and battery system integrators active in sub-5MW deployment. Secondary sources included Ofgem regulatory filings, MCS certification databases, National Grid ESO flexibility procurement records, and distribution network operator connection queue data. Bottom-up project pipeline aggregation was cross-referenced against top-down market sizing from equipment shipment tracking.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeled across installation type, end-user archetype, technology tier, and regional grid constraint status. CAGRs were derived from equipment cost trajectory assumptions, policy stability assessments, and electrification load growth projections. Forecast inputs incorporated Smart Export Guarantee tariff evolution scenarios and distribution network reinforcement timelines by region.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, construction input costs, or sterling exchange rates would shift the trajectory of project finance viability and equipment import pricing. Forecasts reflect documented assumptions regarding regulatory continuity and technology cost curves. Quarterly review of distribution network connection queue lengths, polysilicon spot pricing, and Ofgem charging framework consultations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
Single Axis Solar PV Tracker Market