
 Polyamide 12 Market | 2026-2036
Polyamide 12 Market Size, Share, and Industry Trends Forecast 2026-2036
Polyamide 12 Market Outlook
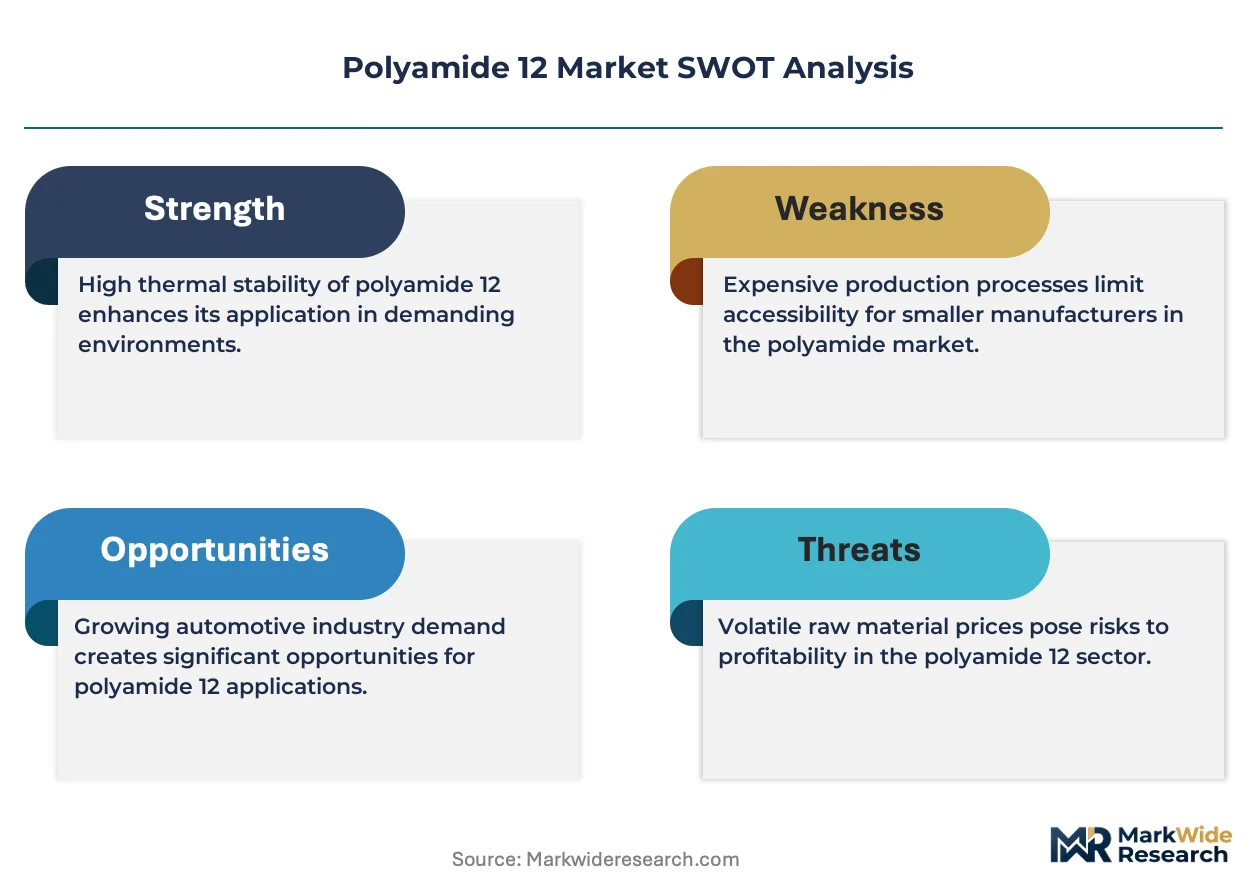
Automotive tier-one suppliers is unwinding legacy reliance on metal tubing as OEMs pursue 15-25% weight reductions in fuel and fluid handling systems. Arkema SA leverages its bio-based Rilsan PA12 platform to anchor supply contracts with European and Asian automakers. Evonik Industries AG competes through high-purity VESTAMID grades optimized for medical catheter and cable jacket applications. EMS-Chemie Holding AG dominates the Swiss and Central European specialty compounds segment with glass-filled and flame-retardant formulations.
Polyamide 12 is a long-chain aliphatic polyamide synthesized from laurolactam monomer, distinguished by low moisture absorption, exceptional chemical resistance to hydrocarbons, and a density of 1.01-1.04 g/cm³ that enables metal replacement in precision components. Granules command the largest volume share as the default feedstock for injection molding and extrusion, while powders represent the fastest-expanding product type due to laser sintering demand in 3D printing. Automotive end-use applications generate the deepest margin pools, though aerospace qualification cycles for PA12 tubing in aircraft fuel systems extend payment terms and compress working capital efficiency.
REACH registration requirements and the EU Green Deal's progressive carbon border adjustments are redirecting capital toward bio-sourced and recycled-content PA12 development pathways. The FDA maintains stringent biocompatibility protocols for medical-grade PA12 in permanent implant contact devices, while China's GB standards and NMPA oversight govern localized production for domestic healthcare markets. Stakeholders must monitor feedstock volatility in butadiene-derived C12 lactam supply chains and assess backward integration into renewable castor oil precursors before committing capacity expansion capital.
Market Dynamics
Automotive lightweighting mandates and REACH-driven bio-based feedstock requirements are compressing the competitive window for conventional petrochemical PA12, forcing producers to reconfigure supply chains around renewable castor oil precursors before carbon border adjustments take full effect.
Growth Catalysts
- EU Green Deal carbon border adjustments:The progressive implementation of CBAM mechanisms is redirecting capital expenditure toward bio-sourced PA12 development pathways, particularly for suppliers serving German precision engineering clusters.
- Laser sintering adoption:Powder-grade PA12 demand is accelerating as aerospace and medical device manufacturers qualify additive manufacturing for end-use components previously machined from metal stock.
- Fuel system redesign:OEM specifications for 15-25% weight reduction in fluid handling architectures are displacing metal tubing with extruded PA12 lines in thermal management and brake systems.
Market Restraints
- C12 lactam supply concentration:Butadiene-derived monomer production clusters in Northeast Asian petrochemical corridors, exposing European compounders to feedstock volatility and freight cost spikes.
- FDA biocompatibility protocols:Permanent implant contact device classifications impose multi-year qualification timelines that compress working capital efficiency for medical-grade resin producers.
- Polyether block amide substitution:TPE-A materials are capturing select catheter and cable jacket applications where ultra-flexibility outweighs PA12's chemical resistance advantages.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory harmonization with ISO standards is enabling import substitution for domestic catheter and surgical instrument producers seeking localized PA12 supply.
- Closed-loop powder recycling:Unfused PA12 recovery systems in selective laser sintering operations are opening circular economy service contracts with aerospace maintenance, repair, and overhaul facilities.
- Castor oil backward integration:Captive cultivation partnerships in Gujarat and Brazil are securing non-food biomass feedstocks that satisfy EU Green Deal sustainability verification requirements.
Industry Challenges
- Aerospace qualification cycles:SAE ARP4754 and DO-160 certification protocols for aircraft fuel system tubing extend payment terms beyond 180 days, straining compounder balance sheets.
- Multi-material bonding expertise:PA12-to-metal and PA12-to-elastomer adhesion chemistry requires polymer scientists with fluorination and plasma treatment process knowledge that remains scarce in emerging manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyamide 12 Market |
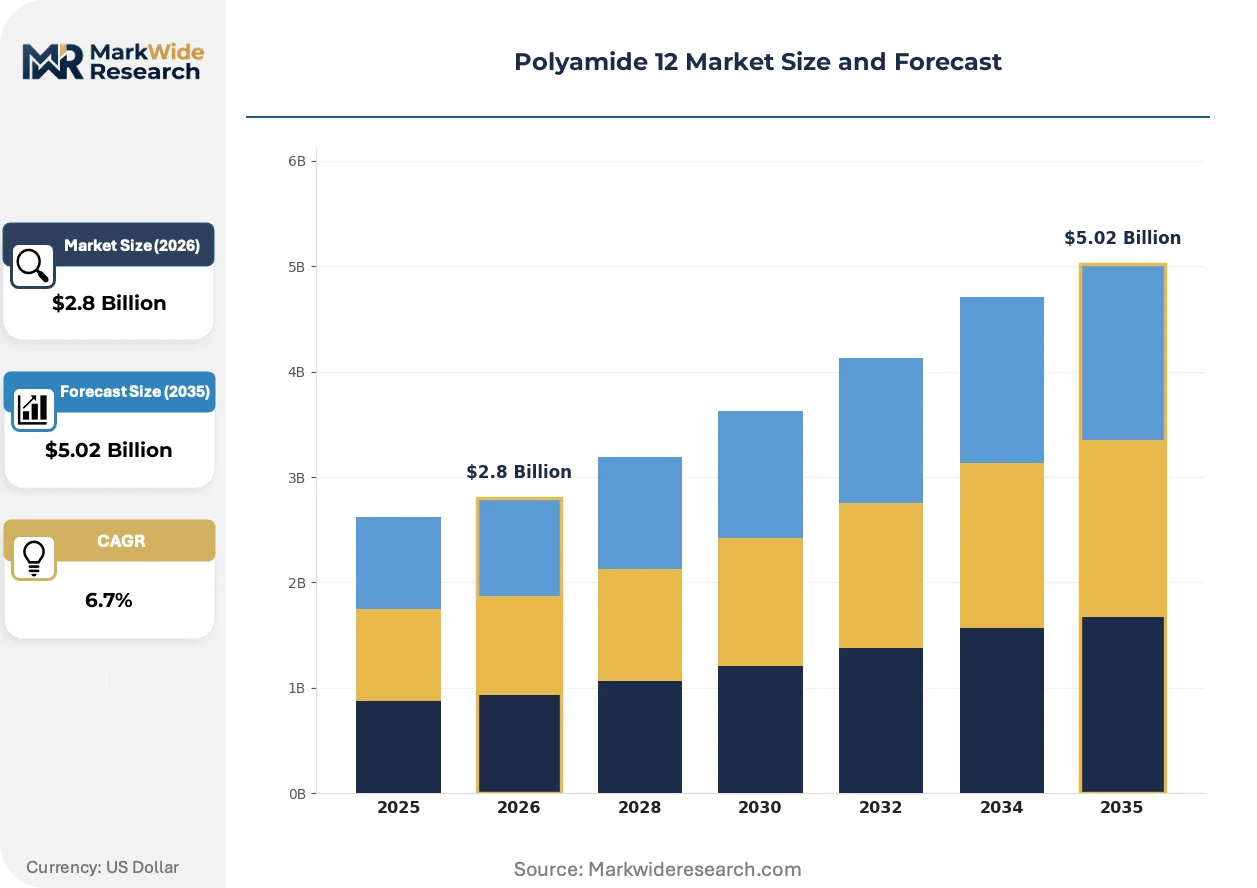
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powders, Liquid, Films End Use Industry: Automotive, Aerospace, Consumer Goods, Industrial Application: 3D Printing, Fasteners, Coatings, Gaskets Form: Sheet, Rod, Tube, Fiber |
| Companies Covered | Arkema SA, Evonik Industries AG, EMS-Chemie Holding AG, Ube Industries Ltd, Toray Industries Inc, BASF SE, Asahi Kasei Corporation, RTP Company, Kuraray Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyamide 12 Market Strategic Shifts
Material science convergence with digital manufacturing protocols is redefining PA12 value capture, as producers compete on circularity credentials and application-specific formulation services rather than commodity resin tonnage alone.
Multi-laser powder bed fusion is miniaturizing feature resolution in PA12 structural components. Medical device manufacturers are adopting these systems for patient-specific surgical guides and dental frameworks. The technology is miniaturizing minimum viable production runs below 100 units, collapsing the economic threshold for mass customization in orthopedic and maxillofacial applications.
REACH authorization list expansion is tightening control over C12 lactam impurities and processing aid residuals. ECHA substance evaluation workflows now demand extended chronic toxicity datasets for substances above one tonne annual volume. German automotive suppliers are responding by qualifying bio-based Rilsan grades that preempt regulatory restriction scenarios.
Buyers are consolidating resin procurement through direct compounder relationships, bypassing traditional distribution intermediaries. Tier-one automotive suppliers now negotiate formulation exclusivity clauses and technical service retainers rather than spot purchasing standard grades. This pattern is most pronounced in Bavaria and Baden-Württemberg, where OEM technical centers co-locate with precision molding operations.
Polyamide 12 Market Segmentation
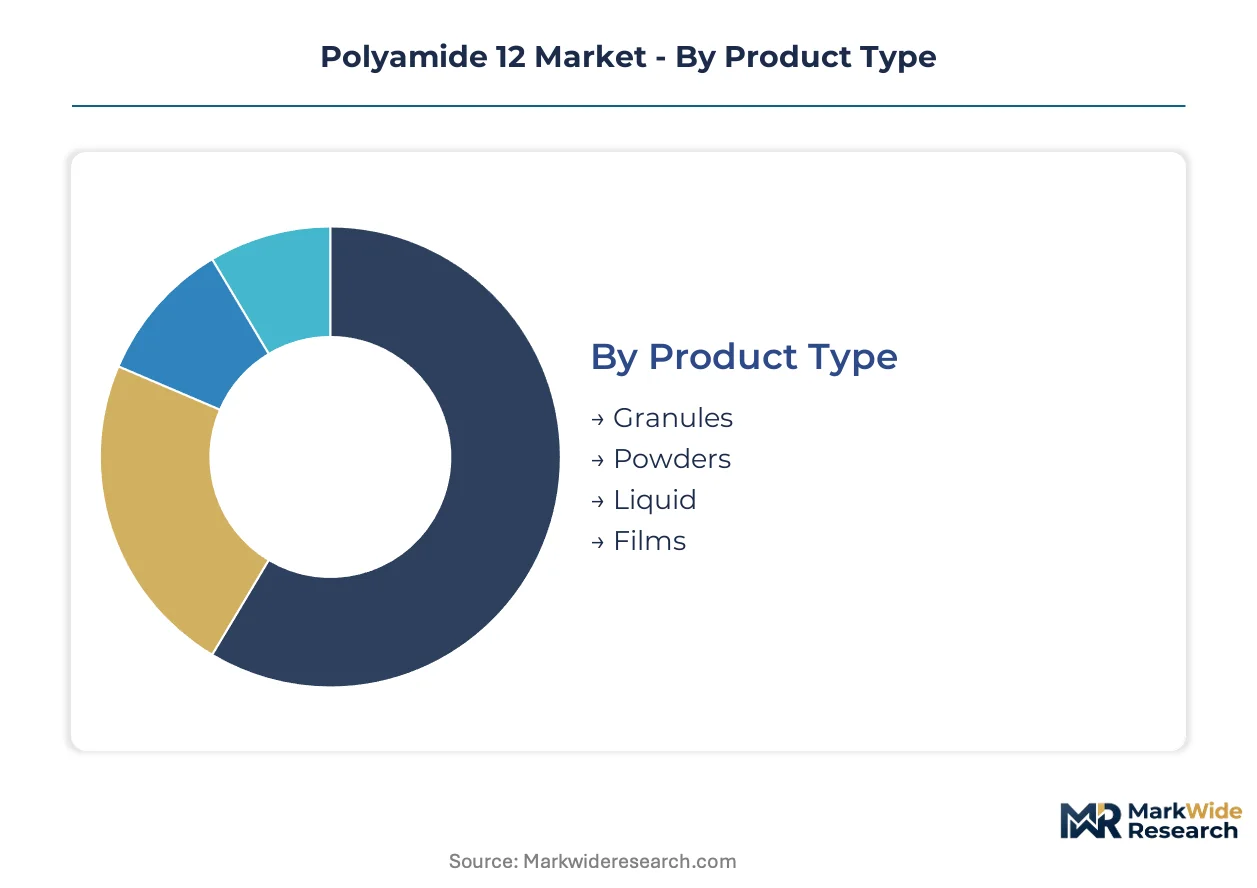
Polyamide 12 procurement channels diverge sharply by physical form. Granules and standard forms flow through distributors to injection molders, while powders and specialized geometries require direct compounder relationships with additive manufacturers and precision converters.
Product Type:
Granules dominate distributor stocking programs, while powders and liquids move through technical service channels with formulation support.
- Granules:Standard pelletized feedstock for injection molding and extrusion operations. Demand concentrates in German automotive supplier parks serving BMW and Mercedes-Benz thermal management programs, where lot-to-lot consistency requirements favor established compounder relationships.
- Powders:Finely milled resin optimized for laser sintering and rotational molding. Aerospace maintenance facilities in Toulouse and Hamburg are qualifying these grades for non-critical cabin components, compressing minimum order quantities below 500 kilograms.
- Liquid:Dispersed or solubilized formulations for coating and adhesive applications.
- Films:Cast or blown sheet structures for barrier packaging and membrane applications.
By volume, Granules leads. By growth pace, Powders is expanding most quickly.
End Use Industry:
Margin profiles separate automotive and aerospace contract structures from consumer and industrial procurement patterns.
- Automotive:Fuel line tubing, brake hose, and thermal management components. Tier-one suppliers in Stuttgart and Wolfsburg are consolidating resin procurement through direct Arkema and Evonik contracts, bypassing distributors entirely.
- Aerospace:Aircraft fuel system tubing and interior cable jacketing. SAE ARP4754 certification requirements in Toulouse and Seattle extend qualification timelines, compressing working capital for compounders serving this segment.
- Consumer Goods:Sporting equipment, eyewear frames, and personal care packaging.
- Industrial:Pneumatic tubing, conveyor components, and chemical processing equipment.
Automotive commands the deepest margin pools. Aerospace shows the steepest expansion trajectory in value per kilogram terms.
Application:
Application-specific formulation services now determine supplier selection more than commodity resin pricing.
- 3D Printing:Laser sintering and multi-jet fusion feedstocks. Medical device manufacturers in Basel and Warsaw are adopting patient-specific surgical guides, collapsing economic thresholds for production runs below 100 units.
- Fasteners:Threaded and snap-fit components for assembly systems. Automotive underhood applications in Munich are displacing metal clips with glass-filled PA12 variants rated for 150°C continuous service.
- Coatings:Protective and functional surface treatments.
- Gaskets:Static and dynamic sealing elements for fluid systems.
Fasteners generates the largest current volume. 3D Printing is gaining share fastest as qualification protocols mature.
Form:
Form factor determines conversion technology and shapes regional supply chain configuration.
- Sheet:Flat stock for thermoforming and machining. Aircraft interior panel producers in Hamburg are qualifying these grades for seat shells and tray tables under EASA CS-25 fire resistance protocols.
- Rod:Cylindrical stock for precision machining. Medical instrument manufacturers in Tuttlingen machine these into surgical tool handles requiring sterilization compatibility.
- Tube:Extruded hollow profiles for fluid transport.
- Fiber:Monofilament and multifilament structures for textiles and filtration.
Tube leads by installed conversion capacity. Sheet shows the strongest growth momentum in aerospace qualification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors Northern European polyamide 12 distribution, while the Rhine-Alpine corridor rail link funnels resin from Basel compounders to Stuttgart automotive clusters. These infrastructure assets concentrate procurement decisions in German-speaking industrial zones.
Germany
Automotive lightweighting programs at BMW and Mercedes-Benz drive resin consumption for thermal management tubing. REACH registration requirements under ECHA oversight compounders to document C12 lactam purity thresholds. Stuttgart and Wolfsburg supplier parks now procure directly from Arkema and Evonik, bypassing traditional distribution channels.
United States
FAA certification protocols for aircraft fuel system components sustain demand for aerospace-grade PA12 tubing. FDA biocompatibility standards govern medical catheter applications from Minnesota device manufacturers. The Gulf Coast petrochemical corridor supplies butadiene-derived monomer feedstock to domestic compounders.
China
NMPA oversight of medical device resin imports creates compliance barriers for European suppliers seeking domestic market access. GB standards for automotive fluid handling systems now reference PA12 specifications. Yangtze River Delta molding operations are qualifying powder grades for laser sintering applications.
Japan
PMDA pharmaceutical regulations shape medical-grade resin qualification timelines for catheter manufacturers. METI industrial policy encourages lightweight material substitution in automotive supply chains. Nagoya-area Tier-one suppliers consume extruded PA12 tubing for hybrid vehicle thermal management.
India
CDSCO regulatory harmonization with ISO standards enables import substitution for domestic catheter producers. PLI scheme incentives attract medical device manufacturing investment to Gujarat and Karnataka. Mumbai-Pune industrial corridor compounders are establishing captive castor oil processing for bio-based feedstock security.
Polyamide 12 Market Competitive Environment
Concentration sits with integrated petrochemical conglomerates and specialty compounders that control monomer synthesis and formulation expertise. The vendor base stratifies across three tiers: global resin producers with backward integration into C12 lactam, regional compounders serving automotive qualification pipelines, and niche powder specialists for additive manufacturing. Dominant competitive moves include captive cultivation partnerships for castor oil feedstock security and direct technical service contracts that displace distributor intermediaries.
Within the integrated producer tier, Arkema SA, Evonik Industries AG, and EMS-Chemie Holding AG exemplify divergent strategic positioning. Arkema represents the bio-based pathway through its castor oil-derived platform. Evonik occupies a position emphasizing high-purity grades for medical and aerospace qualification cycles. EMS-Chemie anchors specialty compounding capabilities in Central European automotive supply chains. These three entities collectively illustrate how feedstock sourcing strategy and application-specific formulation services now determine competitive differentiation more than commodity resin scale.
| Leading Market Players |
|---|
| Arkema SA |
| Evonik Industries AG |
| EMS-Chemie Holding AG |
| Ube Industries Ltd |
| Toray Industries Inc |
| BASF SE |
| Asahi Kasei Corporation |
| RTP Company |
| Kuraray Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German automotive tier-one suppliers and Arkema or Evonik lock in both C12 lactam supply access and price visibility, insulating compounders from spot volatility while committing buyers to volume minimums that strain working capital during aerospace qualification delays.
Pricing Analysis
Three-tier pricing structure across aerospace-certified, automotive-grade, and industrial-standard levels separates resin tiers by qualification burden and purity thresholds. Aerospace-certified material commands premium positioning due to SAE ARP4754 documentation requirements, while automotive-grade resin faces cost compression from metal-to-polymer substitution mandates. Medical device manufacturers show least price sensitivity given FDA biocompatibility protocol barriers, whereas industrial pneumatic tubing buyers prioritize unit economics over performance specifications.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European compounders sourcing butadiene-derived C12 lactam from Northeast Asian petrochemical corridors. Supply concentrates in China, Japan, and Germany as integrated producers with captive monomer synthesis. Raw material dependencies encompass butadiene feedstocks, castor oil bio-precursors, and high-purity processing aids. Single-source vulnerability from concentrated C12 lactam production exposes compounders to freight cost spikes. Distribution runs through direct technical service relationships with automotive OEMs, bypassing traditional distributor intermediaries in precision engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyamide 12 sits in early-cycle expansion as laser sintering adoption in aerospace and medical device manufacturing accelerates powder-grade qualification beyond prototyping into end-use component production.
For Market Incumbents: Consolidate formulation expertise in multi-material bonding chemistry to defend against polyether block amide substitution in catheter applications. Deepen backward integration into castor oil cultivation partnerships in Gujarat and Brazil before EU Green Deal carbon border adjustments take full effect. Lock in exclusive technical service retainers with Stuttgart and Wolfsburg automotive supplier parks to preempt distributor disintermediation. For New Entrants and Emerging Players: Anchor in India's CDSCO-harmonized medical device manufacturing corridor, where PLI scheme incentives attract catheter and surgical instrument producers seeking localized PA12 supply. Target powder-grade production for laser sintering applications, where aerospace MRO facilities in Toulouse and Hamburg qualify new suppliers below 500-kilogram minimum order thresholds. Pursue circular economy service contracts for unfused powder recovery systems as a differentiated entry wedge. For Investors and Strategic Acquirers: Capital is best deployed toward specialty compounders with captive bio-based feedstock pathways and established aerospace qualification pipelines, given the five-to-ten-year viability window for conventional petrochemical PA12 under REACH authorization tightening. Watch for inflection signals in multi-laser powder bed fusion system installations at medical device manufacturers, as patient-specific production run economics below 100 units validate mass customization business models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil | Captive cultivation partnerships in Gujarat and Brazil secure EU Green Deal sustainability verification. |
| Multi-Laser Powder Bed Fusion Qualification | Medical device manufacturers in Basel adopt patient-specific surgical guides below 100-unit thresholds. |
| Closed-Loop Powder Recycling | Unfused PA12 recovery systems open circular economy contracts with aerospace MRO facilities. |
| Direct Technical Service Retainers | Bavarian and Baden-Württemberg OEM technical centers bypass distribution intermediaries entirely. |
| Aerospace Fuel System Tubing Certification | SAE ARP4754 and DO-160 protocols extend payment terms beyond 180 days for compounders. |
Study Parameters
Operator-level perspectives from polymer scientists at compounders, procurement leads at German automotive tier-one suppliers, biomedical engineers at catheter manufacturers, and plant managers at C12 lactam synthesis facilities anchored the qualitative base. These primary inputs combined with secondary validation from ECHA substance evaluation workflows, FDA 510(k) filings for medical-grade resins, customs trade data on butadiene derivative flows, and SEC filings from integrated petrochemical conglomerates. Bottom-up resin consumption modeling triangulated against top-down macroeconomic drivers.
Sensitivity analysis tested forecast robustness across varying adoption scenarios for laser sintering in aerospace and medical applications. Segmentation dimensions encompassed physical form, end-use industry, application type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating substitution dynamics between PA12 and polyether block amides. Industry-specific inputs included aerospace qualification pipeline data, automotive lightweighting program timelines, and REACH authorization list revision schedules.
Material uncertainties — feedstock volatility in butadiene markets, ECHA chronic toxicity dataset requirements, and FAA certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization progress and bio-based feedstock cost parity achievement. Recalibration cycles align with material shifts in carbon border adjustment implementation and multi-laser powder bed fusion system penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Global Bio Polyols Market