
 Polymethacrylimide Foam Market | 2026-2036
Polymethacrylimide Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Polymethacrylimide Foam Market Intelligence
Polyvinyl chloride foam is shifting out of high-performance aerospace sandwich panels as polymethacrylimide foam delivers superior heat resistance and mechanical stability at elevated temperatures. Evonik Industries AG leverages captive Rohacell production capacity to dominate aerospace-qualified foam supply across Europe. DIAB Group sustains competitive positioning through broad density-grade portfolios that span wind energy, marine, and rail applications. Zotefoams PLC differentiates via nitrogen-expanded cellular structures that reduce resin absorption during infusion processes.
Polymethacrylimide foam constitutes a closed-cell thermoplastic foam synthesized through free-radical polymerization of methacrylimide monomers, yielding rigid cellular structures with service temperatures exceeding 180°C and compressive strengths tunable from 0.3 to 3.5 MPa depending on density grade. Aerospace OEMs and Tier-1 suppliers specify this material for primary and secondary structure sandwich cores where epoxy prepreg co-cure compatibility and autoclave stability prove essential. Block and sheet formats currently anchor volume demand from wind blade manufacturers executing resin-infusion of spar caps and shear webs. Fabricated parts represent the fastest-expanding product category as automated machining centers convert near-net blocks into complex core kits that reduce layup labor and scrap rates.
FAA airworthiness directives and EASA CS-25 certification standards govern foam core qualification for commercial aircraft interiors and primary structures, compelling suppliers to maintain exhaustive test data packages for flammability, smoke toxicity, and fatigue performance. REACH registration requirements and evolving EU Green Deal carbon-footprint disclosure rules are reshaping raw material sourcing decisions and end-of-life recyclability investments across European supply chains. Stakeholders must monitor evolving battery enclosure standards in automotive applications, where thermal runaway containment specifications could either accelerate PMI foam substitution for metal housings or redirect development budgets toward alternative intumescent materials depending on test protocol outcomes.
Market Dynamics
Wind turbine blade manufacturers are compressing core material selection cycles as rotor diameters exceed 120 meters, forcing immediate qualification of PMI foam grades that withstand longer resin infusion times without thermal degradation.
Growth Catalysts
- REACH compliance mandates:European aerospace OEMs now require certified low-toxicity foam cores for cabin interiors, eliminating PVC alternatives from primary structure bidding.
- Resin infusion process adoption:Wind blade fabricators specify nitrogen-expanded cellular structures that reduce resin absorption rates during vacuum-assisted infusion of spar caps.
- German aerospace cluster concentration:Hamburg and Munich metropolitan areas host bonded sandwich structure specialists sourcing qualified PMI foam for next-generation narrowbody programs.
Market Restraints
- Methacrylimide monomer cost volatility:Acrylic acid feedstock price swings compress foam producer margins during contract renegotiations with Tier-1 suppliers.
- European supply concentration:Captive production capacity at a single German chemical group creates single-source risk for EASA-certified aerospace grades.
- Epoxy prepreg incompatibility:Certain low-density foam grades exhibit dimensional instability above 160°C, limiting co-cure applications in autoclave-cured primary structures.
Strategic Opportunities
- Automotive battery enclosures:Thermal runaway containment specifications under development by German and US safety regulators could open volume demand for intumescent foam core assemblies.
- EU Green Deal carbon-footprint disclosure:Mandatory Scope 3 reporting creates first-mover advantage for foam suppliers with verified recycled content and end-of-life recyclability pathways.
- Marine superyacht segment:Lloyd's Register and RINA certification protocols for lightweight deck cores remain underpenetrated by thermoplastic foam suppliers relative to balsa and PVC.
Industry Challenges
- CNC machining talent scarcity:Automated conversion of near-net blocks into complex core kits requires operators skilled in five-axis programming for aerodynamic profiles.
- FAA airworthiness certification timelines:Exhaustive flammability and smoke toxicity test data packages extend qualification cycles to 18-24 months for new density grades.
- Legacy bonding surface preparation:Adhesion promotion protocols for thermoplastic foam cores vary across epoxy, bismaleimide, and phenolic resin systems, complicating supplier technical service.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymethacrylimide Foam Market |
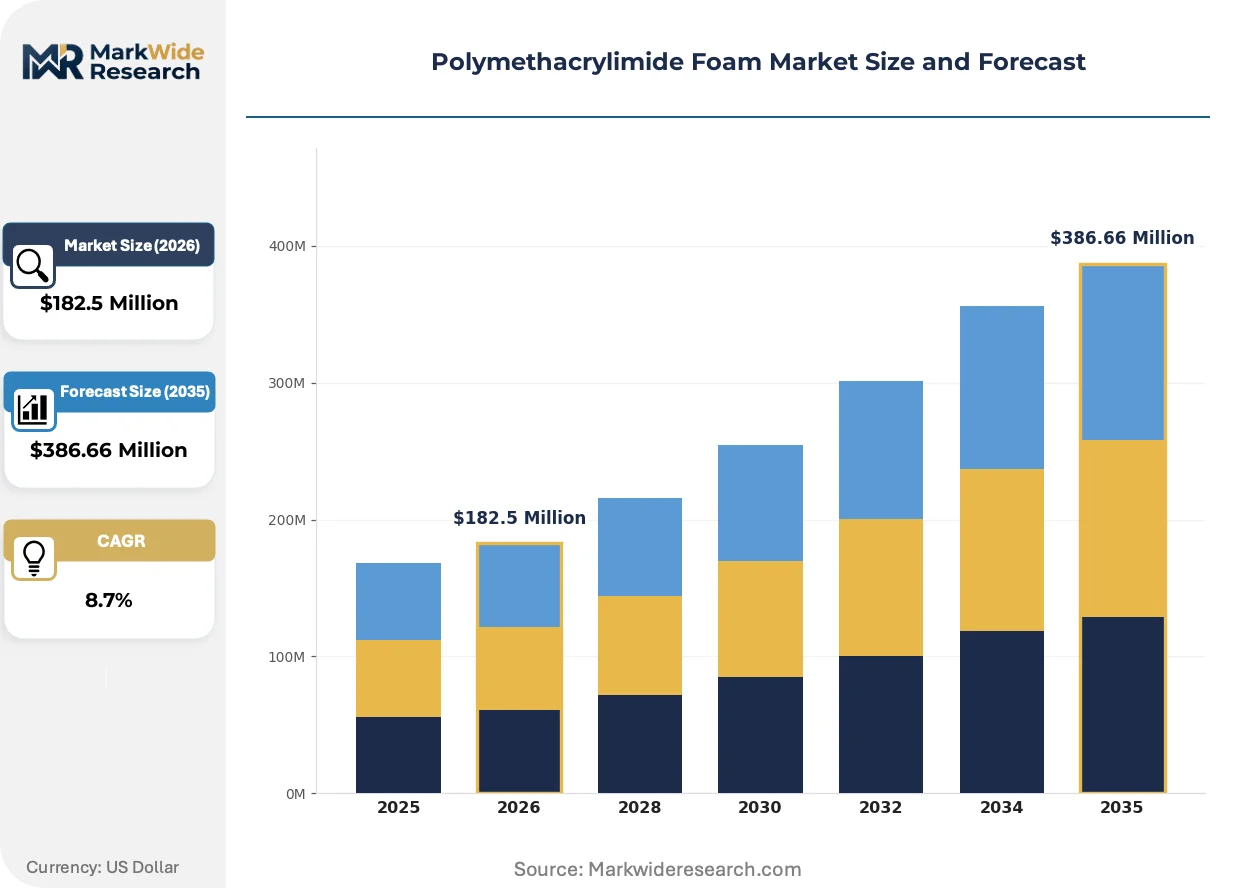
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $386.66 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block, Sheet, Core, Fabricated Parts Application: Aerospace, Automotive, Building & Construction, Thermal Insulation End User: OEMs, Tier-1 Suppliers, Contractors, Distributors Density: Low Density, Medium Density, High Density, Ultra High Density |
| Companies Covered | 3A Composites, Zotefoams PLC, Evonik Industries AG, Hunan Rifeng Composite Co., Ltd., Cashem Advanced Materials Hi-Tech Co., Ltd., DIAB Group, BASF SE, Jiaxing Sky Composites Co., Ltd., SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymethacrylimide Foam Market Strategic Shifts & Innovations
Material qualification protocols and manufacturing process automation are compressing the interval between foam grade development and commercial deployment across aerospace and renewable energy supply chains.
Nitrogen-expanded cellular structures are overtaking conventional foaming agent methods in wind blade core applications. These foams reduce resin absorption during vacuum-assisted infusion by 15-25 percent relative to chemically blown alternatives. Vestas and Siemens Gamesa blade engineering teams specify these grades for spar cap and shear web components exceeding 80 meters in length.
EU Green Deal carbon-footprint disclosure rules are reshaping raw material sourcing decisions across European aerospace supply chains. The Corporate Sustainability Reporting Directive now mandates Scope 3 emissions documentation from foam core suppliers to Tier-1 fabricators. German and French OEM procurement teams are prioritizing suppliers with verified recycled content pathways and end-of-life recyclability investments.
Automated core kit delivery models are disrupting traditional block-and-sheet distribution channels. Wind blade manufacturers now contract machined near-net-shape kits directly from foam suppliers equipped with five-axis CNC centers. This pattern is most visible in Denmark and northern Germany, where blade fabricators have consolidated layup operations and eliminated in-house core shaping capacity.
Polymethacrylimide Foam Market Segmentation
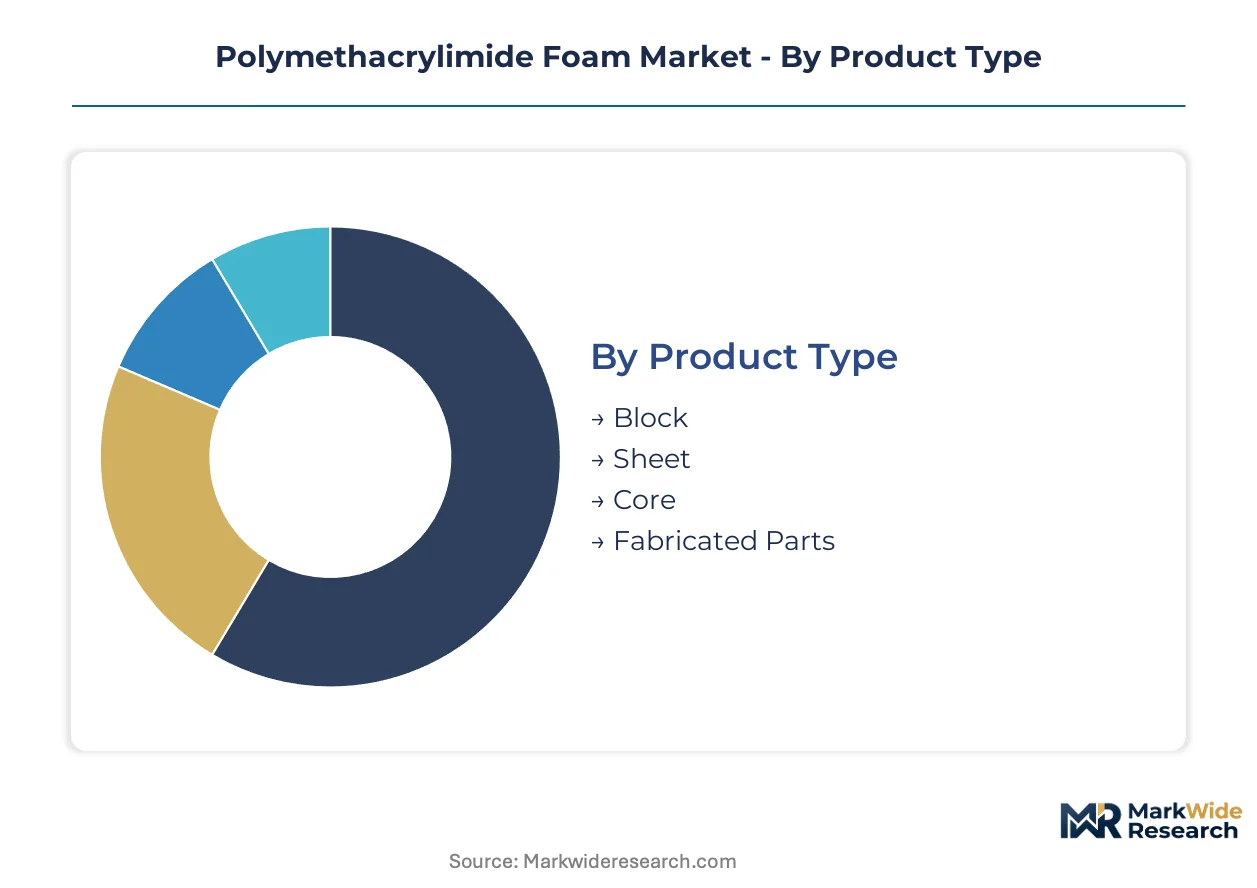
PMI foam procurement patterns diverge sharply between standardized bulk formats and precision-engineered kits. Aerospace OEMs demand certified fabricated components, while wind blade manufacturers optimize resin-infusion economics through density-graded sheet selection.
Product Type:
Standardization dominates block and sheet supply, while fabricated parts command premium positioning through CNC machining value-add.
- Block:Near-net cellular billets serve as feedstock for automated machining centers. Wind turbine blade fabricators in Denmark and northern Germany source high-volume block supply for spar cap conversion.
- Sheet:Planar formats with calibrated thickness tolerance enable rapid layup in sandwich panel production. Aerospace Tier-1 suppliers specify sheet grades for secondary structure cores where dimensional consistency reduces bondline variability.
- Core:Pre-shaped cellular inserts for specific structural locations. Marine deck manufacturers specify core segments for superyacht hull stiffening.
- Fabricated Parts:Complex geometries machined from near-net blocks into kit-ready components. Automated five-axis conversion reduces scrap rates and layup labor for rotor blade shear webs.
Leading the category by volume: Block. Growing fastest: Fabricated Parts.
Application:
Performance requirements stratify across thermal stability thresholds and flammability certification tiers.
- Aerospace:Primary and secondary sandwich structures where epoxy prepreg co-cure compatibility and autoclave stability above 180°C prove essential. FAA airworthiness directives and EASA CS-25 standards govern foam core qualification for commercial aircraft interiors.
- Automotive:Battery enclosure prototypes under evaluation for thermal runaway containment specifications. German and US safety regulators are developing test protocols that could accelerate PMI foam substitution for metal housings.
- Building & Construction:Structural insulated panels and facade systems requiring moisture-resistant closed-cell performance. REACH compliance mandates eliminate PVC alternatives from certified building envelopes.
- Thermal Insulation:High-temperature process equipment and industrial piping applications. Service temperature thresholds exceed 180°C for chemical processing infrastructure.
Highest certification barrier: Aerospace. Steepest expansion trajectory: Automotive.
End User:
Procurement authority concentrates with design-responsible entities rather than material distributors.
- OEMs:Original equipment manufacturers specify qualified foam grades for bonded sandwich structures. Hamburg and Munich metropolitan aerospace clusters source certified PMI foam for next-generation narrowbody programs.
- Tier-1 Suppliers:Subcontracted fabricators execute resin-infusion and autoclave curing under OEM technical authority. These suppliers maintain exhaustive test data packages for flammability and smoke toxicity compliance.
- Contractors:Installation specialists for building envelope and industrial insulation applications. Scope 3 emissions documentation requirements now extend to construction procurement teams.
- Distributors:Inventory holders for standard block and sheet formats. Automated core kit delivery models are displacing traditional distribution channels in wind energy supply chains.
Technical authority rests with: OEMs. Fastest-growing procurement channel: Tier-1 Suppliers.
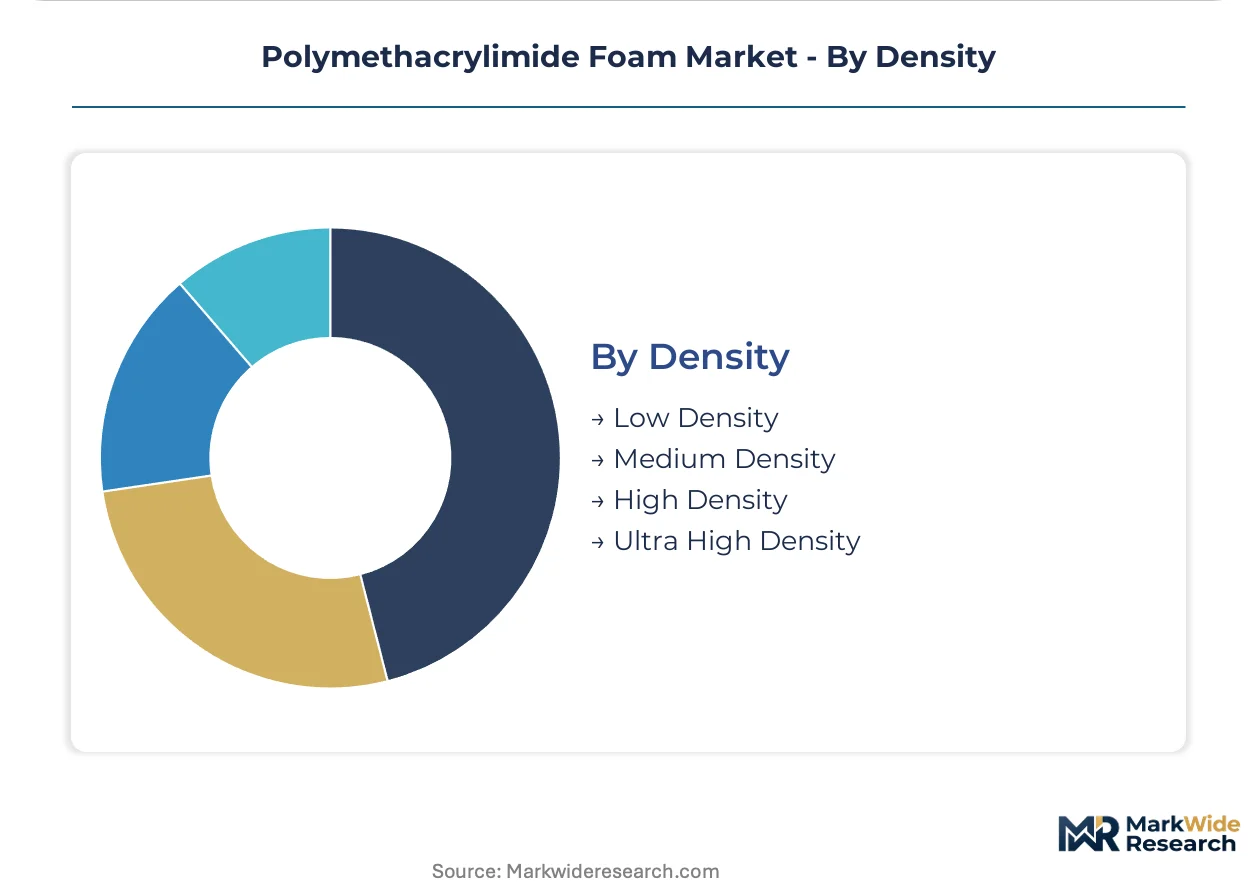
Density:
Mechanical property targets and resin absorption rates determine density grade selection.
- Low Density:Cellular structures with compressive strengths from 0.3 to 0.8 MPa. Certain grades exhibit dimensional instability above 160°C, limiting co-cure applications in autoclave-cured primary structures.
- Medium Density:Balanced stiffness-to-weight ratios for wind blade spar caps and shear webs. Nitrogen-expanded cellular structures in this range reduce resin absorption during vacuum-assisted infusion.
- High Density:Enhanced compressive strength for primary load-bearing aerospace applications. Epoxy prepreg compatibility and fatigue performance certification require exhaustive test protocols.
- Ultra High Density:Maximum mechanical stability for critical structural nodes. Limited adoption due to methacrylimide monomer cost volatility compressing margins during contract renegotiations.
Volume concentration: Medium Density. Gaining share fastest: High Density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for polymethacrylimide foam concentrates in Germany, where aerospace OEMs and wind blade fabricators source certified material for bonded sandwich structures. Hamburg and Munich metropolitan clusters anchor procurement authority for next-generation narrowbody programs and rotor blade spar caps exceeding 80 meters.
Germany
Aerospace OEMs in Hamburg and Munich drive qualification of EASA-certified foam grades for primary structures. REACH compliance mandates eliminate PVC alternatives from cabin interior bidding. The Hamburg metropolitan cluster hosts bonded sandwich structure specialists sourcing PMI foam for next-generation narrowbody programs.
United States
FAA airworthiness directives govern foam core qualification for commercial aircraft interiors and primary structures. NHTSA battery enclosure standards under development could accelerate PMI foam substitution for metal housings in electric vehicles. The Pacific Northwest wind energy corridor sources nitrogen-expanded cellular structures for blade spar caps.
China
Wind turbine blade manufacturers execute resin-infusion of spar caps using medium-density sheet formats. GB standards and MIIT industrial policy shape certification protocols for composite materials. The Yangtze River Delta hosts blade fabricators consolidating layup operations and eliminating in-house core shaping capacity.
Denmark
Wind blade manufacturers contract machined near-net-shape kits directly from foam suppliers equipped with five-axis CNC centers. EU Green Deal carbon-footprint disclosure rules mandate Scope 3 emissions documentation from core suppliers. The Jutland Peninsula anchors automated core kit delivery models displacing traditional distribution channels.
France
Aerospace Tier-1 suppliers maintain exhaustive test data packages for flammability and smoke toxicity compliance under EASA CS-25 standards. ANSM and CNIL oversight extends to material traceability in defense applications. The Toulouse metropolitan cluster sources certified foam for secondary structure cores where dimensional consistency reduces bondline variability.
Polymethacrylimide Foam Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with aerospace-qualified supply concentrating around captive production capacity and wind energy procurement fragmenting across density-grade portfolios. Three strategic archetypes dominate: German chemical groups with backward integration into methacrylimide monomer supply, Anglo-Saxon foam fabricators with nitrogen-expansion process differentiation, and Chinese composite material houses with cost-optimized sheet formats. Competitive moves center on automated machining center investments for core kit delivery and EASA certification maintenance for aerospace grades.
Within the premium-tier vector, Evonik Industries AG exemplifies the captive-production archetype through Rohacell-branded supply chains. Zotefoams PLC occupies a position among nitrogen-expansion specialists with cellular structures that reduce resin absorption. DIAB Group anchors the broad-portfolio segment spanning wind energy, marine, and rail density grades. These three represent the structural fault lines between monomer-integrated, process-differentiated, and application-diversified competitive positions.
| Leading Market Players |
|---|
| 3A Composites |
| Zotefoams PLC |
| Evonik Industries AG |
| Hunan Rifeng Composite Co., Ltd. |
| Cashem Advanced Materials Hi-Tech Co., Ltd. |
| DIAB Group |
| BASF SE |
| Jiaxing Sky Composites Co., Ltd. |
| SABIC |
| Others |
Cost & Logistics Intelligence
Wind blade fabricators in Denmark and northern Germany now specify nitrogen-expanded cellular structures that reduce resin absorption, forcing foam suppliers to absorb methacrylimide monomer cost volatility while maintaining contract pricing for multi-year blade programs.
Pricing Analysis
Volume concentration in medium-density sheet formats for wind energy runs on thinner margins than aerospace-qualified fabricated parts. Three-tier pricing structure separates EASA-certified grades from industrial-specification block and economy-grade sheet. Cost compression in wind energy procurement is intensifying because blade manufacturers have consolidated layup operations and eliminated in-house core shaping. Tier-1 aerospace suppliers exhibit lowest price sensitivity due to qualification timelines and test data package investments, while construction contractors face highest sensitivity under Scope 3 emissions documentation mandates.
Supply Chain Analysis
CNC machining talent scarcity in Hamburg, Munich, and Toulouse metropolitan clusters constrains automated conversion capacity for complex core kits. Supply concentrates in Germany, China, and Denmark, with captive methacrylimide monomer production anchoring European aerospace grades. Raw material sourcing draws from acrylic acid feedstock, nitrogen expansion equipment, and epoxy prepreg compatibility testing protocols. Single-source vulnerability persists for EASA-certified aerospace grades tied to one German chemical group's captive capacity. Distribution runs through direct contracting for fabricated kits, displacing traditional block-and-sheet inventory holders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance and FAA airworthiness certification function as cost-of-compliance moats, with exhaustive flammability and smoke toxicity test data packages extending qualification cycles to 18-24 months for new density grades.
For Market Incumbents: Extend EASA certification maintenance investments to defend against nitrogen-expansion process specialists encroaching on wind energy share. Deepen backward integration into methacrylimide monomer supply to buffer acrylic acid feedstock price swings during Tier-1 contract renegotiations. Anchor capacity expansion in Jutland Peninsula clusters where automated core kit delivery models are displacing traditional distribution. For New Entrants and Emerging Players: Launch via automated five-axis CNC machining service contracts targeting marine superyacht deck core specifications under Lloyd's Register and RINA protocols. White-space availability concentrates in thermal insulation for chemical processing infrastructure and automotive battery enclosure prototypes under German and US safety regulator evaluation. Penetrate through density-graded sheet formats for Chinese wind blade fabricators executing resin-infusion of spar caps. For Investors and Strategic Acquirers: The window for entry favors nitrogen-expansion process specialists with verified EU Green Deal carbon-footprint disclosure pathways. Long-term viability hinges on recyclability investments and end-of-life pathway verification as Scope 3 mandates harden. Monitor NHTSA battery enclosure standard finalization as inflection indicator for automotive volume demand acceleration or redirection toward alternative intumescent materials.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive methacrylimide production buffers German suppliers against acrylic acid feedstock volatility. |
| Automated CNC Machining Center Deployment | Five-axis conversion capacity in Denmark reduces scrap rates for wind blade shear web kits. |
| EASA Certification Maintenance Investment | Exhaustive test data packages for CS-25 compliance protect aerospace-grade pricing premiums. |
| Nitrogen Expansion Process Scale-Up | Cellular structures reducing resin absorption by 15-25 percent attract Vestas and Siemens Gamesa specifications. |
| EU Green Deal Recyclability Pathway Development | Verified end-of-life documentation meets Corporate Sustainability Reporting Directive Scope 3 mandates from French and German OEM procurement teams. |
Research Approach
Independent corroboration across foam core procurement managers at wind blade fabricators, technical directors at aerospace Tier-1 suppliers, and plant managers at nitrogen-expansion facilities underwrites the qualitative findings. Primary interviews with EASA certification specialists, REACH compliance officers, and five-axis CNC programming operators combined with secondary validation from customs trade data, SEC 10-K filings of listed chemical groups, and EASA CS-25 certification databases. Bottom-up demand modeling from end-use application volumes and top-down supply-side capacity triangulation anchored market size estimates.
Rate-of-change decomposition across density grade, application thermal stability threshold, and regional regulatory cluster shaped the analytical framework. Segmentation dimensions modeled include product format, end-use industry certification tier, and geographic production hub concentration. CAGRs derived from slope-intercept fitting against normalized adoption curves, with wind turbine rotor diameter expansion and battery enclosure thermal runaway protocol development as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for intumescent foam core assemblies in automotive battery enclosures would alter the outlook. Forecasts reflect assumptions about REACH compliance timeline adherence and FAA airworthiness directive evolution without specific regulatory date commitments. Material deviation in methacrylimide monomer cost volatility or EASA certification timeline extension warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
Bismaleimide Monomer Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Chelating Resins Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
PVDF Resin Market