
 Bio-Sourced Nylon Market | 2026-2036
Bio-Sourced Nylon Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Sourced Nylon Market Analytics
REACH is broadening the cost-of-entry calculus for petrochemical-derived nylon by tightening registration requirements and driving substitution toward certified bio-based alternatives. BASF SE leverages its integrated biotechnology platform to control upstream fermentation of renewable feedstocks for PA 11 production. Genomatica anchors its position through proprietary bio-based hexamethylenediamine process technology that sustains R&D intensity across multiple polymer grades.
Bio-sourced nylon denotes polyamide resins synthesized from renewable biomass feedstocks—castor oil-derived sebacic acid for PA 11, sugarcane-derived bio-benzene for PA 66, or microbially fermented lactams for PA 6—typically achieving 40-70% biobased carbon content per ASTM D6866 testing. These engineered thermoplastics serve demanding mechanical and thermal applications previously reserved for petroleum-based counterparts, particularly where OEMs mandate verified lifecycle emissions reductions. PA 11 dominates current production volumes due to established castor oil supply chains and decades of formulation optimization, while PA 66 from bio-aramatic pathways represents the fastest-expanding segment as sugarcane-to-benzene technologies achieve industrial scale. Textiles applications capture concentrated margin pools through premium fiber certifications, whereas automotive parts demand is structurally volume-led with thinner spreads.
The EU Green Deal and ECHA REACH framework mandate mass-balance chain-of-custody documentation for bio-content claims, while the US EPA biopreferred program shapes federal procurement specifications. Japan's METI has established bioplastic content targets for automotive and electronics sectors that directly translate to qualified supplier status requirements. Stakeholders must monitor feedstock certification interoperability between ISCC PLUS and RSB standards, as divergence in accepted methodologies will determine which production assets retain market access across major importing jurisdictions.
Market Dynamics
Integrated biorefinery-to-polymer complexes in China's Yangtze River Delta are compressing cost structures and forcing incumbent petrochemical producers to accelerate feedstock certification timelines or surrender volume in automotive and textile grades.
Growth Catalysts
- EU Green Deal industrial emissions benchmarks:Tightening feedstock qualification requirements are disqualifying uncertified conventional PA 6 and PA 66 from automotive supplier lists in Germany and France.
- Castor oil supply chain maturation:Decades of agronomic optimization across Gujarat and Brazil's Northeast region are stabilizing sebacic acid input costs for PA 11 producers.
- Japan METI bioplastic content mandates:Automotive and electronics sector targets are converting qualified supplier status into procurement volume guarantees for certified bio-nylon producers.
Market Restraints
- Castor oil crop concentration:Over 80% of global supply originates from drought-exposed regions of India, creating recurrent input volatility for PA 11 resin pricing.
- Fermentation scale-up capex:Microbial lactam production requires billion-dollar bioreactor investments that exceed mid-cap chemical producers' balance sheet capacity.
- Petrochemical feedstock lock-in:Existing adipic acid and caprolactam infrastructure in the US Gulf Coast and Rotterdam-Antwerp corridor generates 30-40% cost advantages for conventional PA 66.
Strategic Opportunities
- US EPA BioPreferred federal procurement:Mandatory biobased content specifications for textile and automotive applications are opening qualified supplier channels for certified PA 11 and PA 66 grades.
- Sugarcane-to-benzene technology convergence:Industrial-scale bio-aromatic pathways are enabling PA 66 production with verified lifecycle emissions reductions for premium automotive tiers.
- Underpenetrated technical textiles in South Korea:MFDS medical device regulations and industrial safety standards are creating specification pull for high-tenacity bio-polyamide fibers in protective equipment.
Industry Challenges
- ISCC PLUS and RSB certification interoperability:Divergent mass-balance methodologies across EU and North American audit regimes are forcing producers to maintain dual documentation systems for cross-border shipments.
- Bioprocess engineering talent scarcity:Fermentation scale-up and downstream purification expertise concentrates in Basel, Boston, and Singapore, constraining greenfield project execution timelines.
- Legacy polymer compounding integration:Bio-nylon moisture sensitivity and crystallization kinetics differ from petroleum-based grades, requiring reformulation of tool designs and processing parameters at Tier 1 automotive molders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Sourced Nylon Market |
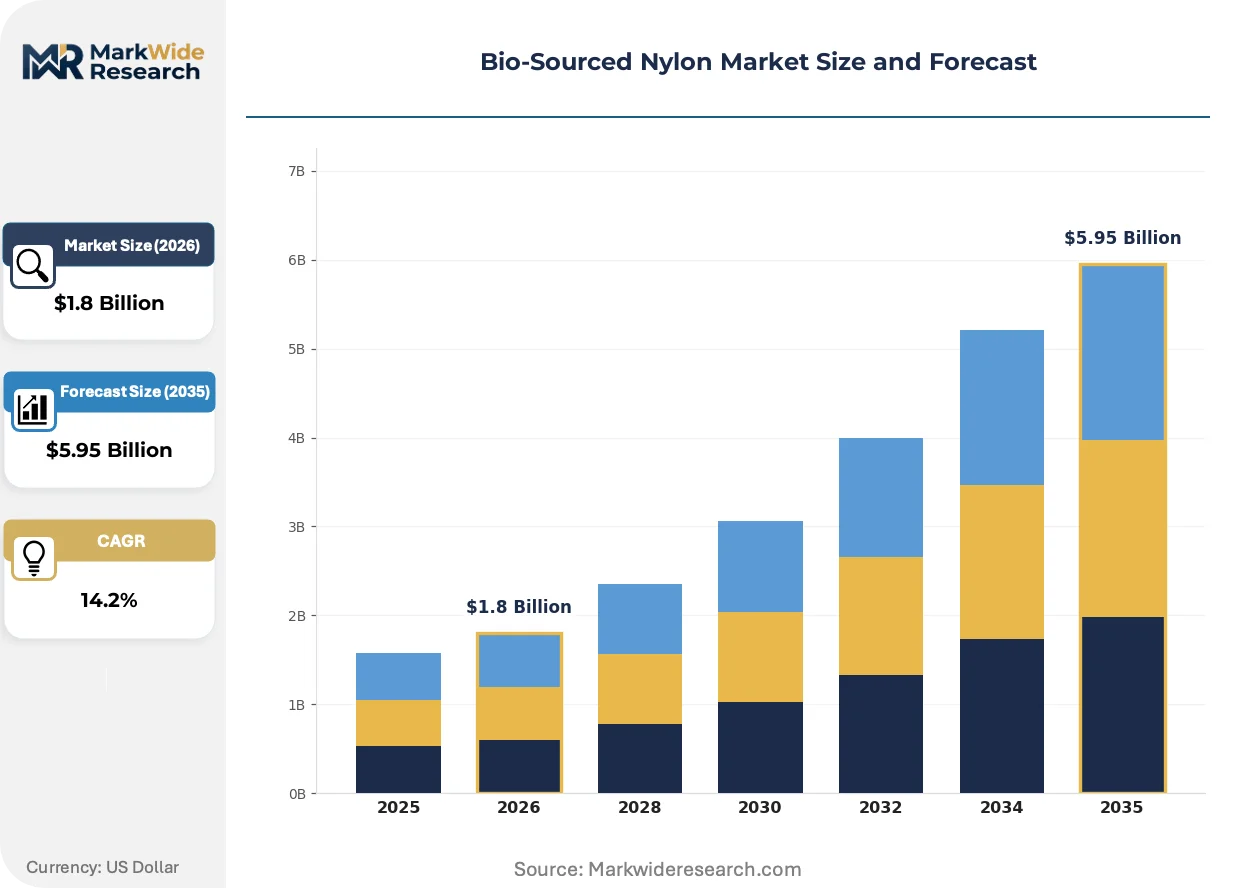
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA 6, PA 66, PA 11, PA 12 Application: Textiles, Automotive Parts, Packaging, Consumer Goods End User: Fashion Industry, Automotive Manufacturers, Electronics, Home Goods Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Arkema S.A., BASF SE, DSM Engineering Materials, Aquafil Group, Radici Group, Cathay Biotech Inc., Genomatica, Evonik Industries AG, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Sourced Nylon Market Evolving Landscape
Microbial fermentation pathways for bio-based hexamethylenediamine are compressing the technology gap between laboratory yield targets and industrial-scale PA 66 production economics.
Enzymatic conversion of lignocellulosic sugars to bio-benzene precursors is overtaking thermochemical routes as the dominant pathway for aromatic bio-nylon feedstocks. Automotive seating and airbag fabric suppliers in Germany and Japan are qualifying these grades for 2027 model year platforms. This transition is overtaking first-generation sugarcane ethanol derivatives in cost-competitiveness at commercial fermentation volumes above 50,000 tonnes annually.
REACH mass-balance chain-of-custody documentation requirements are mandating blockchain-traceable feedstock verification for all bio-content claims above 20% threshold. ECHA's enforcement arm is conducting unannounced audits of polymer distributors in the Port of Rotterdam and Antwerp hub. Textile spinners serving EU luxury apparel brands are absorbing 8-12% certification cost premiums to maintain market access.
Automotive OEMs are consolidating resin procurement under lifecycle emissions accounting protocols that weight Scope 3 upstream emissions at 60-70% of total polymer carbon footprint. Tier 1 suppliers in Stuttgart and Toyota City are disintermediating commodity distributors to contract directly with certified bio-nylon producers holding ISCC PLUS documentation. This concentration is most visible in under-the-hood applications where thermal performance specifications previously protected conventional PA 66 incumbents.
Bio-Sourced Nylon Market Segmentation
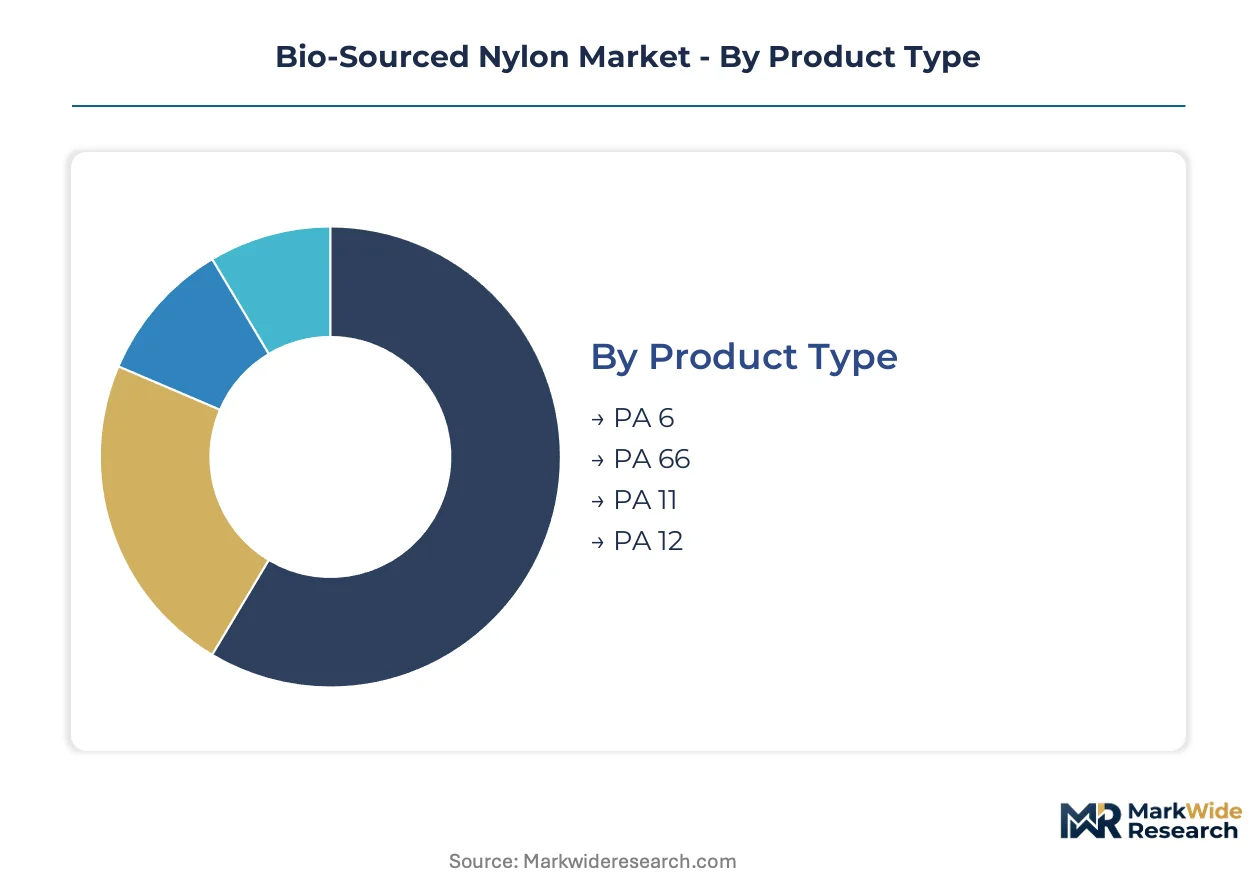
Bio-sourced nylon procurement decisions hinge on certification grade, thermal performance thresholds, and feedstock traceability requirements that vary sharply across end-use industries. Segment boundaries are blurring as automotive OEMs impose lifecycle emissions accounting that reclassifies supplier tiers based on verified biobased carbon content rather than conventional polymer grade alone.
Product Type:
Cost tier determines procurement channel selection, with premium fermentation-derived grades commanding direct mill relationships while commodity bio-PA competes through distributor networks.
- PA 11:Castor oil-derived sebacic acid polymerizes into a long-chain polyamide with exceptional dimensional stability and hydrocarbon resistance. Demand concentrates in German automotive under-the-hood components where BASF SE and Arkema SA hold qualified supplier status under EU Green Deal emissions benchmarks.
- PA 66:Bio-aromatic pathways from sugarcane-derived benzene are achieving industrial scale, yielding petroleum-matching thermal performance with 40-60% biobased carbon per ASTM D6866. China's Yangtze River Delta integrated complexes are compressing cost structures against conventional adipic acid routes.
- PA 6:Microbial lactam fermentation remains capex-intensive, locking production to venture-backed biotechnology platforms in Basel and Boston.
- PA 12:Lauryllactam bio-routes from palm kernel or castor oil feedstocks serve medical tubing and pneumatic hose specifications requiring low moisture absorption.
PA 11 leads on scale; PA 66 leads on momentum.
Application:
Application selection follows margin architecture—textiles capture certification premiums while automotive volumes thin spreads across long-term supply agreements.
- Textiles:High-tenacity fiber grades for luxury apparel and technical protective equipment command 15-25% price premiums contingent on ISCC PLUS or RSB mass-balance documentation. EU spinners serving Milan and Paris fashion houses absorb certification costs to maintain market access under ECHA REACH chain-of-custody mandates.
- Automotive Parts:Interior trim, airbag fabrics, and under-the-hood components represent volume concentration, with Toyota City and Stuttgart Tier 1 suppliers consolidating procurement under Scope 3 emissions protocols weighting upstream feedstocks at 60-70% of polymer carbon footprint.
- Packaging:Film and barrier layer applications remain underpenetrated due to moisture sensitivity and crystallization kinetics requiring tool redesign.
- Consumer Goods:Eyewear frames, sporting equipment, and kitchen utensils drive small-batch demand through specialty compounders.
Automotive Parts dominates procurement volume; Textiles dominates value capture.
End User:
Customer type dictates specification stringency, with automotive and electronics sectors imposing qualified supplier status requirements that exclude uncertified producers.
- Fashion Industry:Luxury apparel brands in France and Italy mandate blockchain-traceable feedstock verification above 20% biobased content threshold, with ECHA conducting unannounced audits of Rotterdam and Antwerp distributors.
- Automotive Manufacturers:Germany's KBA and Japan's METI frameworks convert bioplastic content targets into procurement volume guarantees for certified bio-nylon producers holding documented mass-balance credentials.
- Electronics:Connector housings and cable management systems in South Korea and Japan require halogen-free flame retardancy matching conventional PA 66 performance.
- Home Goods:Furniture components and appliance housings represent price-sensitive demand served through distributor channels with thinner certification requirements.
Automotive Manufacturers anchor contract security; Fashion Industry anchors margin expansion.
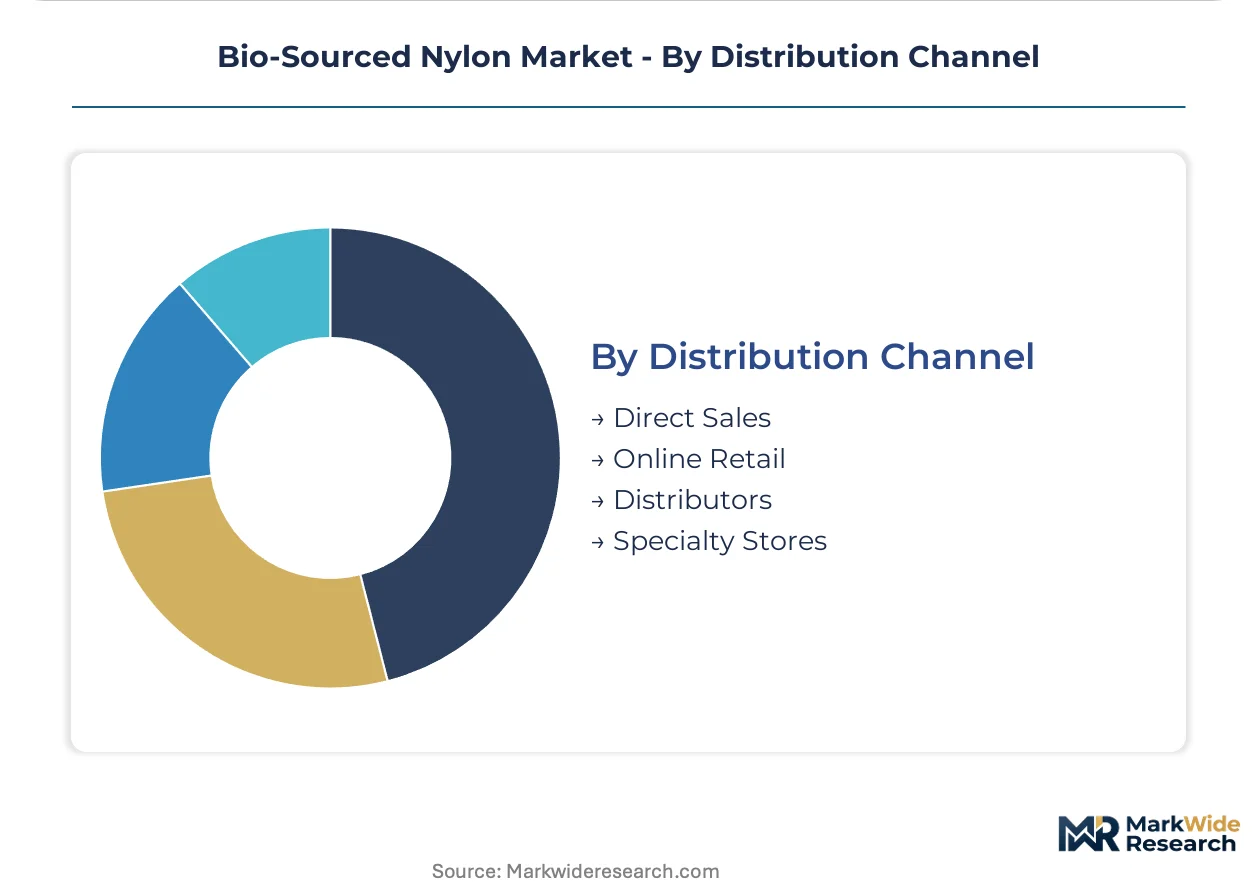
Distribution Channel:
Channel selection reflects order scale and technical service intensity, with direct relationships consolidating around automotive emissions-accounting protocols.
- Direct Sales:Tier 1 automotive suppliers in Stuttgart and Toyota City are disintermediating commodity distributors to contract directly with certified bio-nylon producers, eliminating margin stacking and ensuring documentation integrity for EU Green Deal compliance.
- Distributors:Polymer distributors in the Port of Rotterdam and Antwerp hub maintain inventory positions for mid-volume textile spinners and compounders, though ECHA enforcement audits are raising compliance costs.
- Online Retail:Specialty grades for consumer goods prototyping and small-batch industrial applications flow through digital platforms with limited technical support.
- Specialty Stores:Regional compounders serving molders in China's Yangtze River Delta offer localized formulation support and just-in-time delivery.
Direct Sales captures contract value; Distributors retains geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioprocess engineering talent concentrates in Basel, Boston, and Singapore, anchoring production capacity decisions and greenfield project execution timelines across major manufacturing zones.
China
Integrated biorefinery-to-polymer complexes in the Yangtze River Delta are compressing cost structures and achieving parity with conventional PA 6 and PA 66. MIIT's dual carbon goals are tightening industrial emissions benchmarks for chemical producers. Shanghai and Jiangsu Province host the densest concentration of certified bio-nylon fermentation capacity outside Europe.
Germany
Automotive manufacturers in Stuttgart and Wolfsburg are accelerating procurement of bio-based polyamide components for interior and under-the-hood applications. KBA emissions protocols and EU Green Deal industrial benchmarks are disqualifying uncertified conventional nylon from supplier lists. The Rhine-Main chemical corridor maintains Europe's largest installed base of mass-balance certified polymer production.
United States
Federal procurement specifications under the EPA BioPreferred program are opening qualified supplier channels for certified PA 11 and PA 66 grades. Textile and automotive applications face mandatory biobased content thresholds for government contracts. The Gulf Coast petrochemical corridor retains cost advantages in conventional adipic acid routes, pressuring bio-nylon producers to differentiate through certification premiums.
Japan
METI bioplastic content targets for automotive and electronics sectors are converting qualified supplier status into procurement volume guarantees. Toyota City and Nagoya-based Tier 1 suppliers are consolidating resin procurement under lifecycle emissions accounting protocols. Chubu region molders are reformulating tool designs to accommodate bio-nylon moisture sensitivity and crystallization kinetics.
India
Castor oil agronomic optimization across Gujarat is stabilizing sebacic acid input costs for PA 11 producers serving export markets. BIS standards for biobased content verification are aligning with ISCC PLUS methodologies to maintain EU market access. The Gujarat chemical cluster supplies over 80% of global castor oil derivatives, exposing pricing to monsoon-driven harvest volatility.
Bio-Sourced Nylon Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers, with integrated petrochemical incumbents leveraging existing adipic acid infrastructure against venture-backed biotechnology platforms. Market structure tilts toward consolidation in automotive supply chains, where qualified supplier status requirements are disintermediating commodity distributors. Three archetypes dominate: integrated chemical majors with biotechnology platforms, specialty polymer compounders with regional formulation expertise, and fermentation technology licensors with proprietary bio-aromatic pathways. Competitive moves center on backward integration into renewable feedstock supply and strategic partnerships with automotive OEMs for lifecycle emissions documentation.
Among European integrated chemical majors, BASF SE and Arkema S.A. occupy positions anchoring qualified supplier status under EU Green Deal emissions benchmarks. DSM Engineering Materials represents the specialty compounder archetype with regional formulation capabilities. Within the biotechnology platform tier, Genomatica exemplifies proprietary process technology development for bio-based hexamethylenediamine production. Cathay Biotech Inc. sits within the Asia-Pacific fermentation specialist group serving cost-optimized industrial grades.
| Leading Market Players |
|---|
| Arkema S.A. |
| BASF SE |
| DSM Engineering Materials |
| Aquafil Group |
| Radici Group |
| Cathay Biotech Inc. |
| Genomatica |
| Evonik Industries AG |
| DuPont de Nemours Inc. |
| Others |
Value Network & Pricing Analysis
Backward integration into castor oil agronomy and sugarcane biorefineries anchors both supply security and margin control for bio-nylon producers competing against Gulf Coast petrochemical incumbents. This upstream positioning determines which certified grades can absorb ECHA compliance costs while maintaining contract competitiveness against conventional PA 66.
Pricing Analysis
Bundled certification-plus-feedstock contracts dominate premium grades while unbundled spot purchasing persists in commodity bio-PA tiers. Pricing stratifies across ISCC PLUS-certified, mass-balance-documented, and uncertified economy levels with textile spinners absorbing 8-12% documentation premiums. Cost compression in fermentation-derived PA 6 is intensifying because Yangtze River Delta integrated complexes achieve petroleum parity. Automotive OEMs show lowest price sensitivity due to Scope 3 emissions mandates, while packaging converters remain most exposed to conventional nylon substitution.
Supply Chain Analysis
ISCC PLUS and RSB certification gating forces dual documentation systems for cross-border shipments between EU and North American audit regimes. Feedstock supply concentrates in India, Brazil, and China's Yangtze River Delta with sebacic acid, bio-benzene, and microbial lactams as critical inputs. Single-source vulnerability runs through Gujarat's monsoon-exposed castor harvests. Distribution runs through Rotterdam-Antwerp polymer hubs and direct mill relationships with Stuttgart Tier 1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-sourced nylon market compounds steadily as EU Green Deal emissions benchmarks hardwire bio-content requirements into automotive supplier qualification. This regulatory ratchet sustains demand displacement from conventional polyamides regardless of petrochemical feedstock price cycles.
For Market Incumbents: Extend qualified supplier status into under-the-hood thermal applications previously protected by conventional PA 66 performance specifications. Deepen captive control over castor oil supply through Gujarat processing partnerships to buffer monsoon-driven input volatility. BASF SE and Arkema SA anchor positions through integrated biotechnology platforms that compound certification premiums across multiple polymer grades. For New Entrants and Emerging Players: Begin with South Korean technical textiles where MFDS medical device regulations and industrial safety standards create specification pull for high-tenacity bio-polyamide fibers in protective equipment. Target fermentation technology licensing to mid-cap compounders lacking in-house bioprocess engineering capabilities. A certification-first go-to-market angle opens channels before capacity scale demands billion-dollar bioreactor investments. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with ISCC PLUS credentials because automotive OEM procurement consolidation under lifecycle emissions protocols is disintermediating commodity distributors. Five-to-ten year viability hinges on feedstock certification interoperability rather than fermentation yield breakthroughs. Watch for divergence between EU and North American mass-balance audit methodologies as the inflection signal determining which production assets retain cross-border market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil Supply | Gujarat processing partnerships stabilize sebacic acid input costs against monsoon volatility. |
| ISCC PLUS Certification Investment | Mass-balance documentation unlocks EU automotive supplier lists under KBA emissions protocols. |
| Fermentation Scale-Up Partnership | Joint ventures with Basel or Boston biotech platforms share billion-dollar bioreactor capex burdens. |
| Direct Mill Relationship Development | Tier 1 automotive molders in Stuttgart and Toyota City eliminate distributor margin stacking. |
| Bio-Aromatic Pathway Licensing | Sugarcane-to-benzene technology transfers enable PA 66 production with verified lifecycle emissions reductions. |
Research Methodology
Direct dialogue with fermentation technology directors, automotive Tier 1 procurement leads, textile spinner technical managers, and ECHA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from customs trade databases, SEC 10-K filings of listed chemical producers, ISCC PLUS certification registries, and EU Green Deal implementation guidance documents. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the projection horizon.
Segment-level outputs across product type, application, end user, and distribution channel dimensions were generated through the analytical framework with CAGRs derived from elasticity-adjusted substitution curves against conventional polyamide pricing. Forecast inputs incorporated MIIT dual carbon goal implementation timelines, METI bioplastic content mandate phase-ins, and EPA BioPreferred federal procurement specification updates without assigning specific effective dates.
Several conditions sit outside the modeled scope, including unforeseen breakthroughs in enzymatic lignocellulosic conversion economics, abrupt castor oil crop failures exceeding historical monsoon volatility bands, and petrochemical feedstock price collapses that temporarily invert bio-nylon cost competitiveness. A model refresh is warranted upon material change in EU-NA certification methodology interoperability or automotive OEM lifecycle emissions accounting protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East and Africa Polyurethane Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
Global UV Curable Resins Market
Polymers & Resins
Nylon Resins Market
Polymers & Resins
Smart Polymers Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Sustainable Polymers Market