
 Global Bio Polyols Market | 2026-2036
Global Bio Polyols Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio Polyols Market Foresight
Specialty chemical distribution is fragmenting as bio-based feedstock suppliers bypass traditional distributors to secure direct relationships with polyurethane formulators. BASF SE leverages its backward integration into renewable feedstocks to control raw material quality and cost. Covestro AG anchors its position through dedicated production lines for castor oil-derived polyols at its European sites. Cargill, Incorporated competes by converting its agricultural commodity base into consistent glycerol feedstock for polyol manufacturing.
Bio polyols are polyether or polyester polyols synthesized from renewable biomass feedstocks such as sucrose, glycerol, or castor oil, typically containing 30-70% bio-based carbon content and used primarily as reactive intermediates in polyurethane synthesis. Vegetable oil-based formulations dominate current production volumes due to established supply chains and cost parity with petroleum alternatives. Castor oil-based grades command premium positioning in coatings and elastomers where hydrolytic stability and low moisture sensitivity define performance requirements. Foam production absorbs the majority of output, though adhesives and sealants represent faster-growing application pockets as VOC regulations tighten.
EPA bio-preferred procurement standards in the United States, REACH authorization requirements in Europe, and China's GB standards for green building materials collectively elevate compliance costs for petroleum-based alternatives while creating preferential market access for certified bio polyols. ECHA substance evaluation under REACH specifically targets isocyanate precursors, indirectly accelerating formulator migration toward bio-based polyol systems with lower hazardous substance profiles. Stakeholders must monitor feedstock crop yield volatility and evolving lifecycle assessment methodologies as these determine both cost competitiveness and regulatory eligibility.
Market Dynamics
Polyurethane formulators are decoupling from petroleum feedstocks as EU Green Deal mandates and EPA bio-preferred standards harden compliance baselines, forcing raw material sourcing decisions toward certified bio-based carbon content verification systems.
Growth Catalysts
- REACH authorization tightening:ECHA substance evaluation targets isocyanate precursors, accelerating formulator migration toward bio-based polyol systems with lower hazardous substance profiles.
- Construction sector rigid foam demand:Residential and commercial building codes in Germany and the United States mandate higher thermal performance, pulling bio polyols into insulation formulations.
- Castor oil supply chain maturation:India and Brazil expand cultivated acreage, reducing feedstock price volatility and improving cost parity with petroleum polyols.
Market Restraints
- Oilseed crop yield volatility:Drought cycles in Argentina and flooding in Southeast Asia disrupt castor and soybean supply, transmitting price spikes to polyol converters.
- Technical performance ceilings:Bio-based polyesters exhibit inferior hydrolytic stability versus petrochemical equivalents, limiting penetration in marine coatings and outdoor elastomers.
- Certification cost burden:USDA BioPreferred and EU Ecolabel lifecycle assessment documentation requirements add compliance overhead that disadvantages small-batch formulators.
Strategic Opportunities
- Adhesives and sealants vertical:VOC regulations in California and China's GB standards create preferential market access for low-emission bio polyol systems in furniture and automotive assembly.
- Direct supplier-formulator relationships:Agricultural commodity processors bypass traditional chemical distributors, capturing margin and securing volume commitments from polyurethane manufacturers.
- China green building acceleration:Dual carbon goals and MIIT industrial policy incentivize bio-based content in construction materials, opening dedicated supply channels for certified producers.
Industry Challenges
- Biomass pretreatment expertise scarcity:Glycerol purification and vegetable oil epoxidation require specialized chemical engineering talent concentrated in legacy petrochemical regions.
- Legacy equipment retrofit costs:Polyol reactors and continuous foam lines engineered for petroleum feedstocks demand capital-intensive reconfiguration to handle variable bio-based viscosity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio Polyols Market |
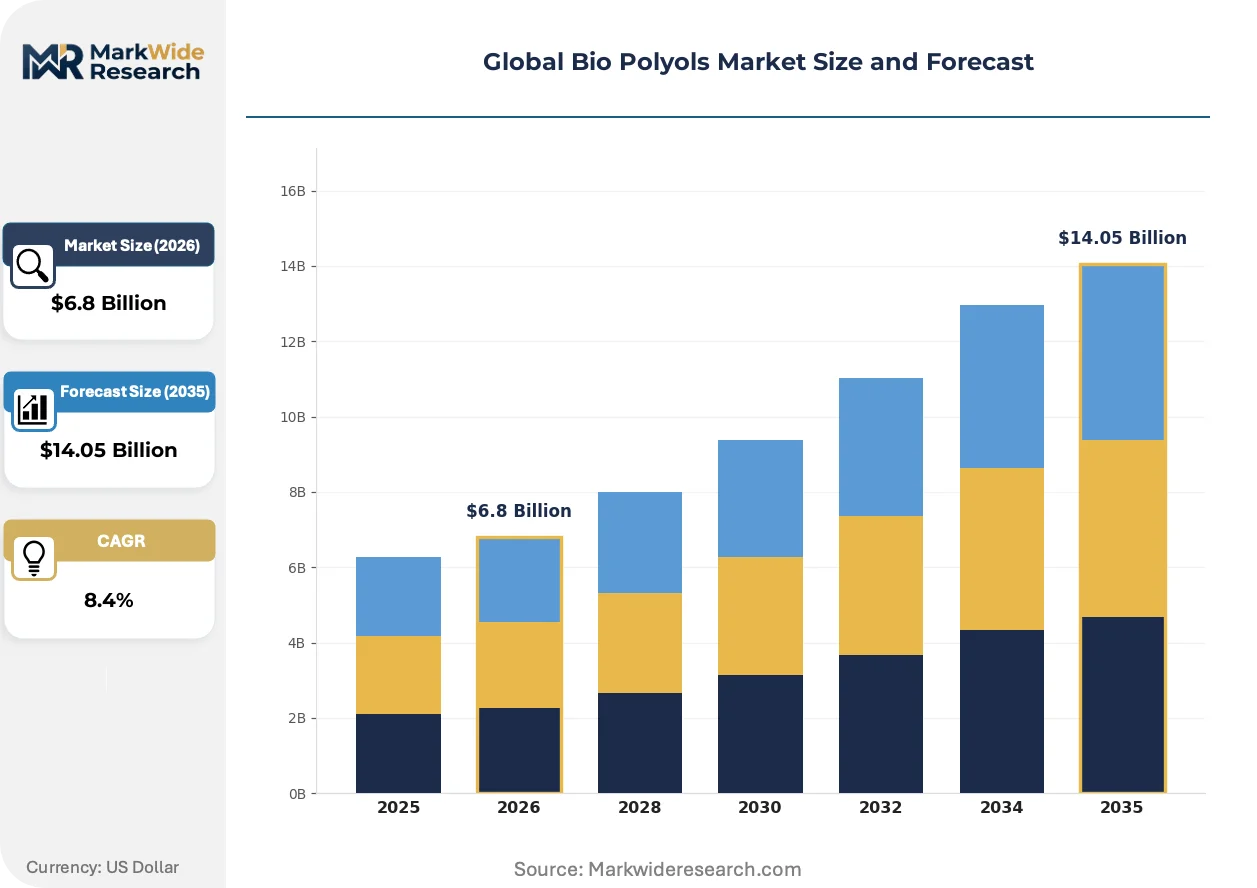
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose-Based, Glycerol-Based, Castor Oil-Based, Vegetable Oil-Based, Others Application: Foam Production, Adhesives, Coatings, Sealants, Elastomers End Use Industry: Construction, Furniture, Footwear, Marine, Packaging Form: Liquid, Solid, Semi-Solid, Powder |
| Companies Covered | BASF SE, Covestro AG, Dow Inc., Cargill, Incorporated, Emery Oleochemicals, Huntsman Corporation, Stepan Company, Mitsui Chemicals, Inc., Arkema SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio Polyols Market Shifts & Advancements
Feedstock diversification and process intensification are compressing the traditional petroleum-to-polyol value chain, collapsing established margin structures and opening entry points for non-traditional chemical suppliers.
Second-generation bio polyol production is collapsing the cost premium historically attached to renewable feedstocks. Algae-derived and waste-glycerol pathways achieve carbon content thresholds matching vegetable oil routes at lower land-use intensity. Coatings manufacturers in the Netherlands and automotive tier suppliers in Michigan accelerate qualification timelines for these grades. The technology is collapsing the historical 15-20 percent price gap that restricted bio polyols to premium positioning.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon displacement in rigid foam blowing agents, indirectly elevating bio polyol demand as formulators redesign insulation systems for lower-global-warming-potential alternatives. German appliance manufacturers and French construction material producers face 2027 compliance deadlines requiring reformulation. The regulation is compressing qualification cycles and forcing closer technical collaboration between polyol suppliers and isocyanate producers.
Buyer concentration among large polyurethane formulators is consolidating procurement leverage, squeezing mid-tier bio polyol suppliers into specialty niches or captive supply arrangements. Direct long-term offtake agreements now dominate volume planning, displacing spot-market transactions that historically balanced supply fluctuations. This pattern is most visible in the United States, where three major construction chemical groups account for a disproportionate share of certified bio-based polyol contracting.
Global Bio Polyols Market Segmentation
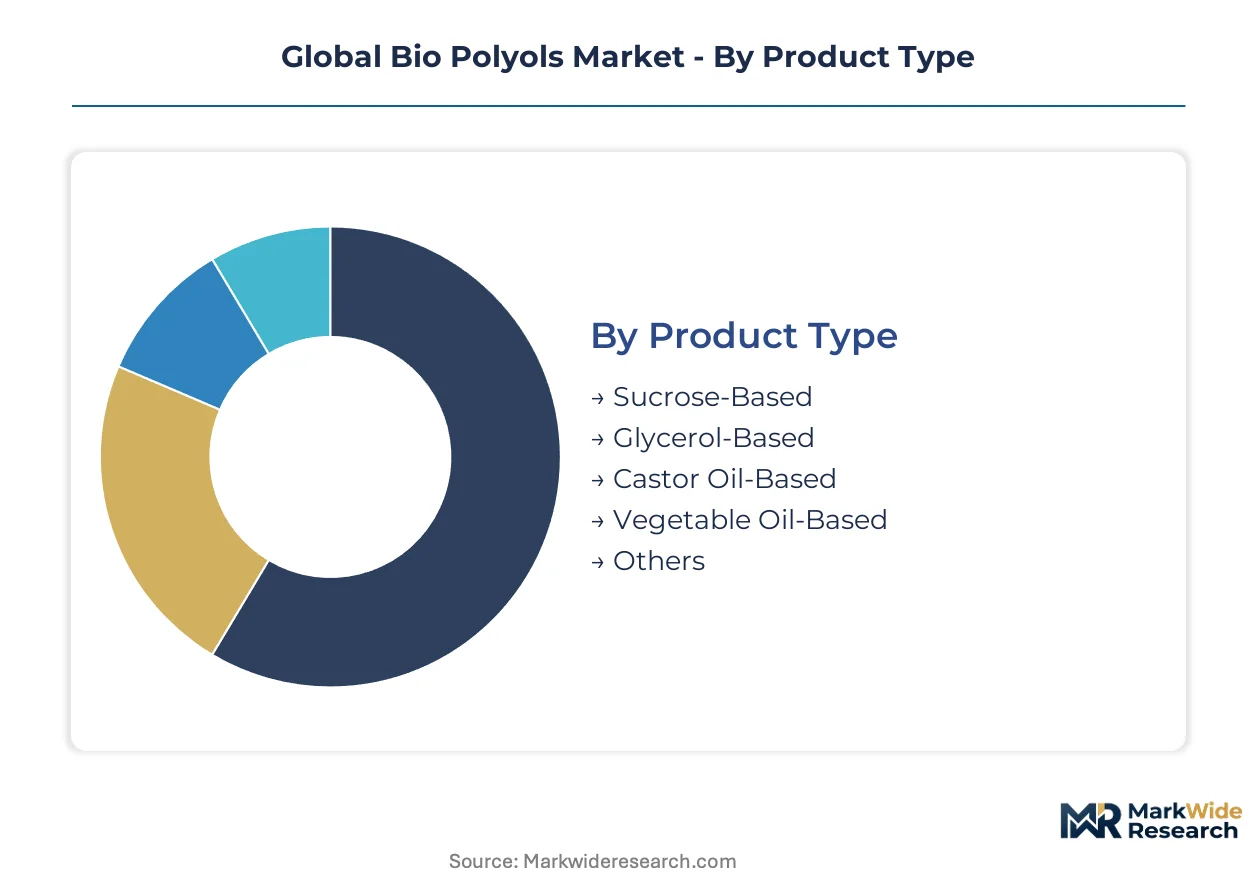
Bio polyol segmentation reveals how feedstock chemistry, application performance requirements, and end-use compliance standards create distinct commercial battlegrounds. Each dimension carries different margin profiles and qualification timelines that reshape supplier priorities.
Product Type:
Cycle times vary dramatically across feedstock platforms, with vegetable oil routes offering the shortest path from crop to qualified polyol while algae and waste-stream alternatives demand extended development horizons.
- Vegetable Oil-Based:Established epoxidation and transesterification processes deliver consistent hydroxyl functionality for flexible foam applications. Demand concentrates in Germany and the United States where construction chemical formulators prioritize supply security and REACH-compliant carbon verification.
- Castor Oil-Based:Ricinoleic acid content provides inherent hydrolytic stability and low moisture sensitivity without additional chemical modification. Premium positioning in marine coatings and outdoor elastomers in France and Italy reflects performance requirements that justify 20-30% price premiums over petroleum alternatives.
- Glycerol-Based:Biodiesel byproduct streams create cost-competitive feedstock for rigid foam polyols in China and Brazil.
- Sucrose-Based:Sugar industry integration enables high-functionality polyethers for appliance insulation in India's growing manufacturing corridor.
- Others:Algae-derived and lignin-based routes occupy pilot-scale production with qualification timelines extending 18-24 months.
Vegetable oil-based grades dominate installed base. Castor oil-based formulations are where expansion concentrates in performance-critical segments.
Application:
Margin structures diverge sharply between commodity foam markets and specialty adhesive segments, with certification requirements and technical service intensity determining supplier economics.
- Foam Production:Rigid polyurethane insulation for residential and commercial construction absorbs the majority of bio polyol volume, with German building codes and California Title 24 standards mandating thermal performance improvements that pull renewable content into formulations. Spot pricing volatility and buyer concentration among three major construction chemical groups compress margins.
- Adhesives:VOC regulations in China's GB standards and California's SCAQMD rules create preferential market access for low-emission bio polyol systems. Furniture and automotive assembly applications in Michigan and Guangdong province drive fastest volume expansion as formulators redesign hot-melt and reactive systems.
- Coatings:Hydrolytic stability requirements limit bio-based penetration to castor oil grades in marine and industrial maintenance segments.
- Sealants:Construction joint and automotive seam applications in Japan and South Korea favor low-viscosity liquid polyols with consistent cure profiles.
- Elastomers:Castor oil-derived polyols command positioning in footwear soles and industrial rollers where dynamic fatigue resistance defines performance.
Foam production anchors volume scale. Adhesives represent the steepest expansion trajectory as regulatory compliance deadlines compress qualification cycles.
End Use Industry:
Customer concentration and procurement sophistication vary enormously, with construction sector buyers wielding consolidated leverage while marine and footwear segments tolerate higher service costs for technical partnership.
- Construction:Residential and commercial rigid foam insulation mandates in Germany, the United States, and China create the largest addressable demand pool. Direct long-term offtake agreements now dominate volume planning, displacing spot-market transactions.
- Furniture:Upholstery and bedding flexible foam applications in North Carolina and Zhejiang province prioritize cost parity with petroleum alternatives over bio-based content certification.
- Footwear:Athletic and casual shoe midsole producers in Vietnam and Portugal specify castor oil-based polyols for rebound resilience and hydrolytic stability.
- Marine:Coatings and sealant applications for shipbuilding in South Korea and Norway demand extended weathering performance that limits bio-based options.
- Packaging:Insulated shipping containers and protective foam inserts in the Netherlands and California face emerging extended producer responsibility regulations.
Construction commands the dominant share of procurement volume. Footwear is where premium positioning and technical collaboration create defensible supplier margins.
Form:
Physical state determines handling infrastructure requirements and geographic service radius, with liquid formulations enabling broad distribution while solid and powder grades demand localized processing partnerships.
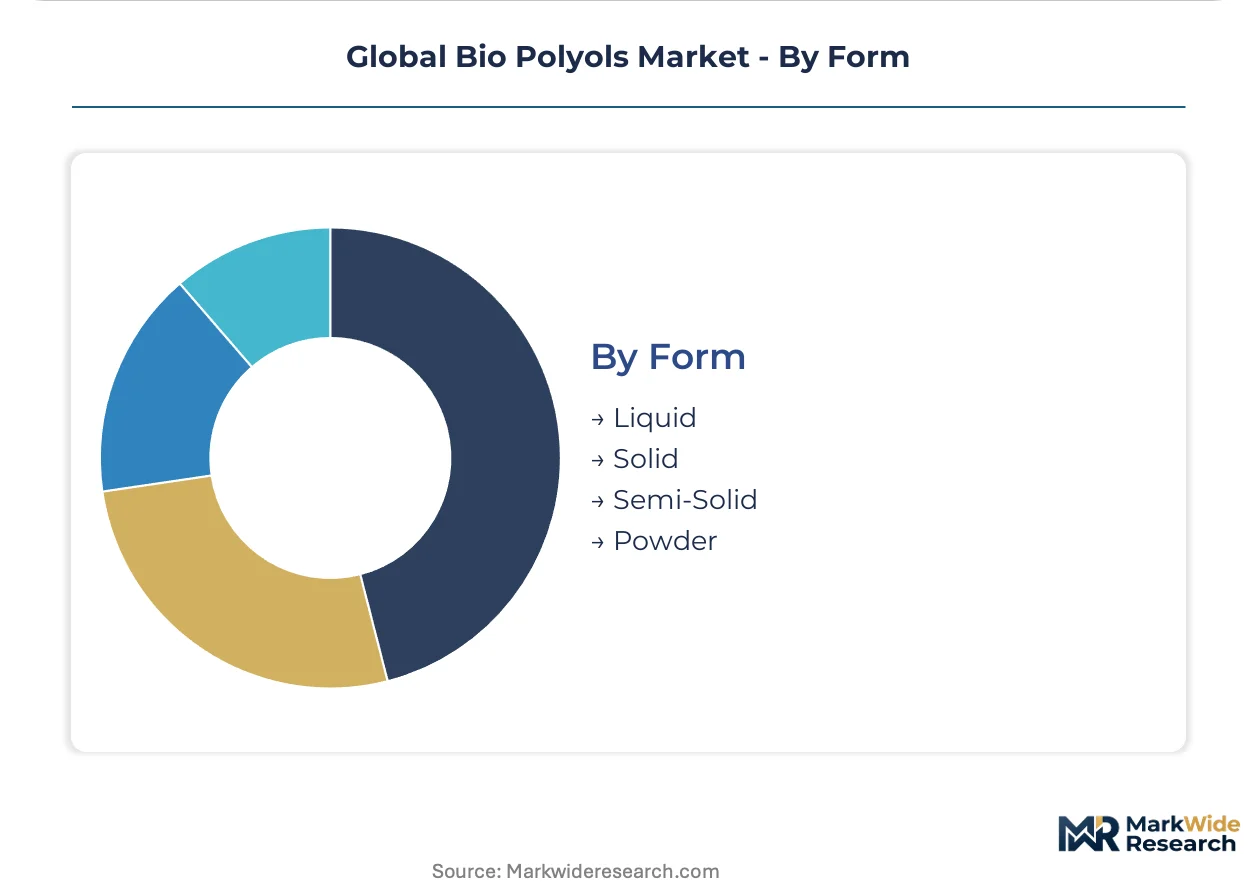
- Liquid:Pumpable viscosity profiles compatible with existing polyurethane reactor infrastructure and continuous foam lines. Standard drum and bulk tanker logistics support global supply chains serving construction and furniture manufacturers.
- Solid:Hot-melt adhesive and reactive injection molding applications in automotive assembly require pellet or flake form with controlled melting point specifications.
- Semi-Solid:Paste consistency for manual application in sealant and coating repair segments with limited automation.
- Powder:Spray-applied insulation and powder coating crosslinkers occupy niche applications with specialized handling equipment requirements.
Liquid formulations dominate installed processing equipment. Solid grades are where adhesive and automotive application growth concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical storage and distribution infrastructure anchors European bio polyol trade flows, connecting Indian castor oil shipments to German polyurethane formulators and enabling bulk liquid handling that reduces per-unit logistics costs.
United States
Construction chemical procurement concentrates among three major formulator groups in the Midwest and Southeast. EPA bio-preferred procurement standards mandate renewable content verification for federal infrastructure projects. Michigan automotive tier suppliers accelerate qualification timelines for low-VOC adhesive systems.
Germany
Rigid foam insulation demand from residential building codes in Bavaria and North Rhine-Westphalia pulls bio polyols into construction supply chains. EU F-Gas Regulation phase-down schedules force appliance manufacturers toward reformulated blowing agent systems. Covestro AG operates dedicated castor oil-derived polyol production lines at Leverkusen.
China
Dual carbon goals and MIIT industrial policy incentivize bio-based content in construction materials across the Yangtze River Delta. GB standards for green building materials create preferential market access for certified producers. Guangdong province furniture manufacturers drive fastest volume expansion in adhesive applications.
India
Castor cultivation expansion in Gujarat and Rajasthan reduces feedstock price volatility for export-oriented polyol production. Biodiesel byproduct glycerol streams create cost-competitive feedstock for rigid foam applications. Maharashtra chemical clusters integrate sugar industry sucrose into high-functionality polyethers.
Brazil
Soybean oil supply chains in Mato Grosso and Paraná underpin vegetable oil-based polyol cost parity with petroleum alternatives. Biodiesel production growth generates glycerol byproduct streams for local conversion. São Paulo state construction chemical formulators localize supply chains to avoid import duty exposure.
Global Bio Polyols Market Competitive Landscape
On the supply side, the industry is consolidating around backward-integrated agricultural processors and diversified chemical conglomerates with captive renewable feedstock positions. Three strategic archetypes dominate: petrochemical majors with bio-based product lines, agricultural commodity processors converting crop outputs into chemical intermediates, and specialty oleochemical houses with dedicated epoxidation capabilities. Capacity expansion and direct supplier-formulator offtake agreements represent the dominant competitive moves, displacing traditional distributor relationships.
Among diversified chemical conglomerates, BASF SE and Covestro AG exemplify the integrated archetype, combining renewable feedstock sourcing with polyurethane formulation expertise. Cargill, Incorporated occupies the agricultural processor position, leveraging commodity conversion capabilities into consistent glycerol feedstock supply. These three anchors illustrate how control over upstream biomass inputs increasingly determines downstream market access in certified bio-based systems.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Dow Inc. |
| Cargill, Incorporated |
| Emery Oleochemicals |
| Huntsman Corporation |
| Stepan Company |
| Mitsui Chemicals, Inc. |
| Arkema SA |
| Others |
Supply & Pricing Matrix
Undercapacity in European castor oil processing facilities tightens feedstock availability and amplifies supplier pricing power against polyurethane formulators negotiating annual contracts. This utilization squeeze transmits directly into tiered contract structures that reward volume commitment with preferential terms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates castor oil-based grades from vegetable oil alternatives from glycerol feedstock options. Price differentiation hinges on bio-based carbon certification tier and geographic delivery cost to manufacturing clusters. Cost compression in standard vegetable oil grades is intensifying because India and Brazil expand cultivated acreage. Furniture manufacturers in North Carolina exhibit highest price sensitivity, while marine coatings formulators in Norway tolerate premiums for hydrolytic stability.
Supply Chain Analysis
Extended payment terms from German construction chemical groups now stretch to 90 days, forcing mid-tier bio polyol suppliers into supply-chain finance facilities. Geographic supply concentration centers on India for castor oil, Brazil for soybean feedstock, and China for glycerol streams. Raw material dependencies draw from agricultural crop yields, biodiesel byproduct availability, and epoxidation catalyst supply. Single-source vulnerability in Indian castor seed processing creates structural risk. Distribution runs through bulk liquid tanker networks anchored at Rotterdam chemical storage terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to construction sector capital expenditure cycles as residential and commercial building codes tighten thermal performance mandates.
For Market Incumbents: Pre-empt margin erosion from agricultural commodity processors by securing captive castor oil supply through equity stakes in Gujarat processing facilities. Accelerate REACH-compliant carbon verification certification to defend position against emerging glycerol-based entrants targeting rigid foam substitution.
For New Entrants and Emerging Players: Underpenetration in China's Yangtze River Delta adhesive applications offers fastest qualification pathways as Guangdong furniture manufacturers redesign hot-melt systems for GB standard compliance. Target direct supplier-formulator relationships bypassing legacy chemical distributors to capture margin and secure volume commitments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across second-generation algae-derived production routes, compressing breakeven thresholds for novel feedstock platforms. Long-term viability favors agricultural processors with backward integration into crop cultivation rather than standalone conversion facilities. Watch EPA bio-preferred procurement standard expansion as inflection signal for US federal infrastructure demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstocks | BASF SE's captive supply of castor oil secures raw material quality and cost control against volatile spot markets. |
| Dedicated Production Line Investment | Covestro AG's castor oil-derived polyol lines at Leverkusen anchor European supply for premium coatings applications. |
| Long-term Supply Agreement | Direct offtake contracts with German construction chemical groups displace spot-market transactions and balance supply fluctuations. |
| Green Manufacturing Transition | Algae-derived and waste-glycerol pathways achieve carbon content thresholds at lower land-use intensity than virgin vegetable oils. |
| Joint Venture with Agricultural Processor | Cargill's commodity conversion capabilities create consistent glycerol feedstock supply for biodiesel byproduct utilization. |
Research Methodology
The analysis maps vegetable oil-based, castor oil-based, glycerol-based, and sucrose-based feedstock platforms, each validated through polyurethane formulators, agricultural commodity processors, chemical plant managers, and distribution channel partners. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings enable bottom-up and top-down triangulation across the analysis window.
Assumptions held fixed include current EU F-Gas Regulation phase-down schedules and existing EPA bio-preferred procurement standards, while feedstock crop yield volatility and lifecycle assessment methodology evolution were treated as variable inputs. The analytical framework models grade tier, end-use industry, packaging format, and regional production hub segmentation throughout the forecast period. CAGRs derive from production capacity expansion announcements, offtake agreement volumes, and regulatory compliance deadline clustering.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by agricultural commodity processors would shift outcomes. Macroeconomic construction sector contraction, regulatory relaxation of bio-based content mandates, or breakthrough petroleum polyol cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Polymer Seals Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Southeast Asia Modified Polypropylene Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Polymer Binders Market