
 Vinyl Acetate Emulsion Polymers Market | 2026-2036
Vinyl Acetate Emulsion Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Acetate Emulsion Polymers Market Analytics
Modular adhesive systems for prefabricated building components is shifting how construction contractors evaluate vinyl acetate emulsion polymer suppliers. Wacker Chemie AG leverages its integrated silicones-emulsions technology platform to anchor premium positioning in European construction adhesives. BASF competes through its backward integration into acetic acid and ethylene feedstocks, sustaining cost advantages across emulsion adhesive grades. Dow Inc. dominates North American supply chains for packaging adhesives, extending its reach through direct mill relationships with corrugated board manufacturers.
Vinyl acetate emulsion polymers comprise colloidal dispersions of polyvinyl acetate or vinyl acetate copolymers in water, typically stabilized with polyvinyl alcohol protective colloids at solids contents of 50-60 percent by weight. These emulsions function primarily as film-forming binders that impart adhesion, flexibility, and water resistance to applied coatings and bonded substrates. Emulsion adhesives represents the most mature revenue pool, though margin compression from commoditized wood glue formulations is pushing producers toward higher-performance vinyl acetate-ethylene copolymers for flexible packaging laminates. Paints and coatings segments are capturing accelerated specification gains as architectural reformulation toward waterborne systems displaces solvent alkyd binders in decorative and protective applications.
EPA VOC emissions standards for architectural coatings and adhesives constrain product formulation choices in the United States, while REACH registration requirements and the EU Green Deal chemical sustainability targets impose disclosure and substitution obligations across European supply chains. China's MEE environmental inspections and GB standards for indoor air quality in buildings are tightening permissible formaldehyde and VOC content in construction materials, redirecting demand toward certified low-emission emulsion systems. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and certification timelines that will determine competitive access across major demand centers.
Market Dynamics
Construction sector specification of low-VOC adhesive systems is compressing reformulation timelines and forcing emulsion polymer producers to requalify products across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Mandatory disclosure obligations under REACH are redirecting European construction materials procurement toward certified low-emission emulsion binders for interior applications.
- China infrastructure investment:State-funded building programs in tier-one cities are consuming vinyl acetate-ethylene copolymers for moisture-resistant flooring adhesives and tile bonding systems.
- Waterborne coating reformulation:Architectural paint manufacturers are displacing solvent alkyd binders with vinyl acetate emulsion polymers to meet indoor air quality specifications.
Market Restraints
- Acetic acid feedstock volatility:Backward-integrated producers with captive ethylene supply command structural cost advantages that independent emulsion manufacturers cannot replicate.
- Commoditized wood glue margin compression:Standard polyvinyl acetate homopolymer formulations face price erosion from Asian imports with minimal differentiation beyond solids content.
- Formaldehyde emission scrutiny:China's GB standards for indoor air quality are disqualifying uncertified emulsion systems from government-procured construction projects.
Strategic Opportunities
- Flexible packaging laminate adhesives:Vinyl acetate-ethylene copolymers with enhanced heat seal performance are penetrating food-grade pouch and lidding applications previously served by solvent systems.
- Prefabricated building component bonding:Modular construction contractors are specifying custom-formulated emulsion adhesives for engineered wood panel assembly with accelerated cure profiles.
- MEE environmental inspection compliance:Producers with certified low-VOC product portfolios are securing preferred supplier status with state-owned Chinese construction enterprises.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA VOC compliance, REACH registration, and China GB standard testing extends product launch cycles by 18-24 months.
- Protective colloid formulation expertise:Polyvinyl alcohol stabilization chemistry requires specialized polymer science talent that competes with broader materials science sectors for limited graduate pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Acetate Emulsion Polymers Market |
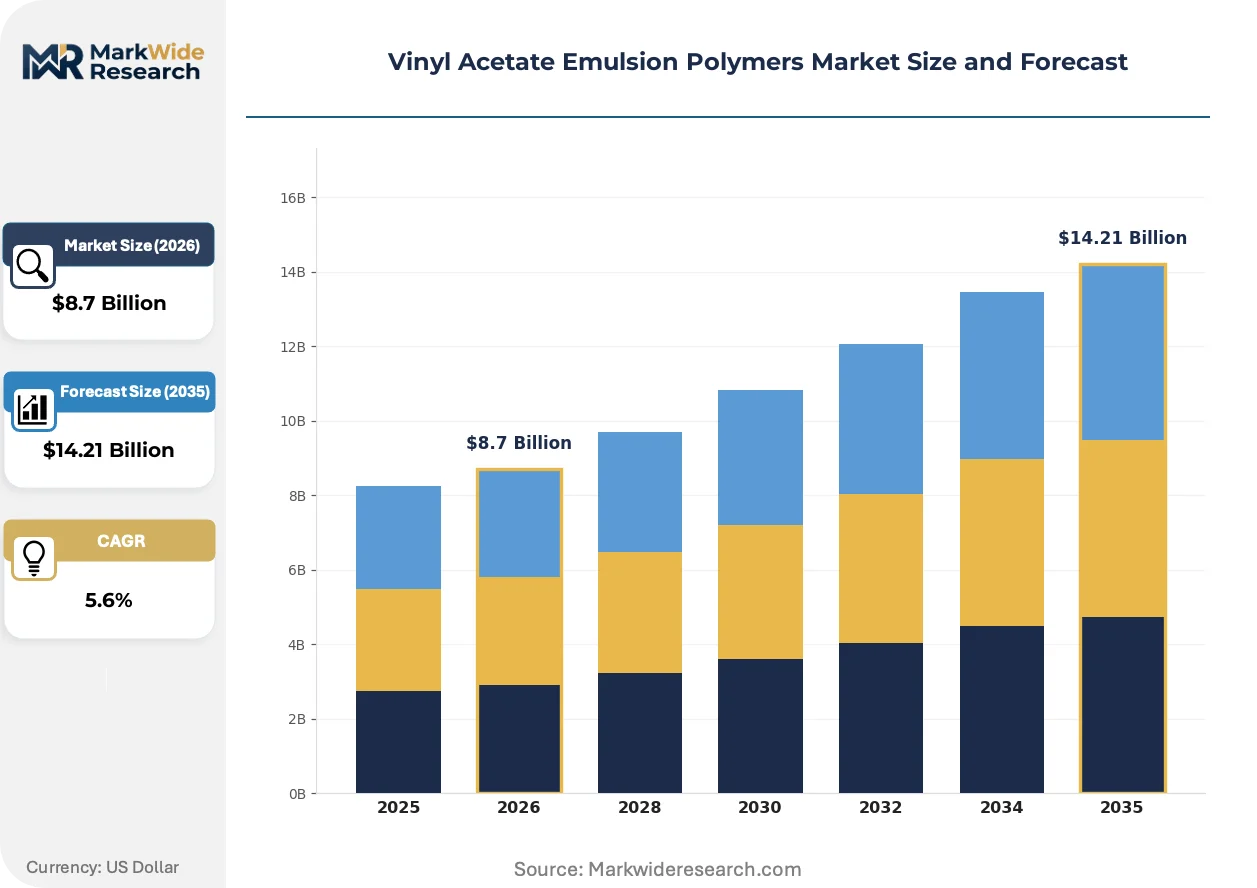
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion Adhesives, Paints, Coatings, Sealants Application: Construction, Automotive, Packaging, Textiles End User: Manufacturers, Contractors, Distributors, Retailers Distribution Channel: Direct Sales, Online Retail, Wholesale, Others |
| Companies Covered | BASF, Wacker Chemie AG, Celanese Corporation, Dow Inc., Arkema, Clariant, Synthomer, DIC Corporation, Trinseo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Acetate Emulsion Polymers Market Evolving Landscape
Waterborne system performance parity with solvent-based alternatives is unlocking specification gains in protective coatings and high-performance laminates previously resistant to emulsion chemistry.
Vinyl acetate-ethylene copolymer technology is expanding into food-contact flexible packaging applications where heat seal strength and organoleptic neutrality rival polyurethane and solvent acrylic systems. Multinational packaging converters in Germany and Japan are qualifying these emulsions for retort pouch and lidding structures. This migration is expanding into premium segments that command formulation premiums over standard packaging adhesives.
REACH registration requirements and the EU Green Deal chemical sustainability targets are forcing disclosure of full substance inventories across European construction supply chains. Emulsion polymer producers must now document protective colloid sources, residual monomer levels, and biodegradation profiles to maintain specification status. Architectural coatings and interior adhesives segments are absorbing the largest compliance burden as building certification schemes incorporate these disclosures into scoring methodologies.
Building materials distributors are consolidating adhesive procurement through direct mill relationships with corrugated board and engineered wood manufacturers. This channel compression is displacing traditional chemical distributor networks in North American packaging and construction segments. Specification authority is concentrating with national account managers at large building product retailers who demand volume-tiered pricing and just-in-time delivery guarantees.
Vinyl Acetate Emulsion Polymers Market Segmentation
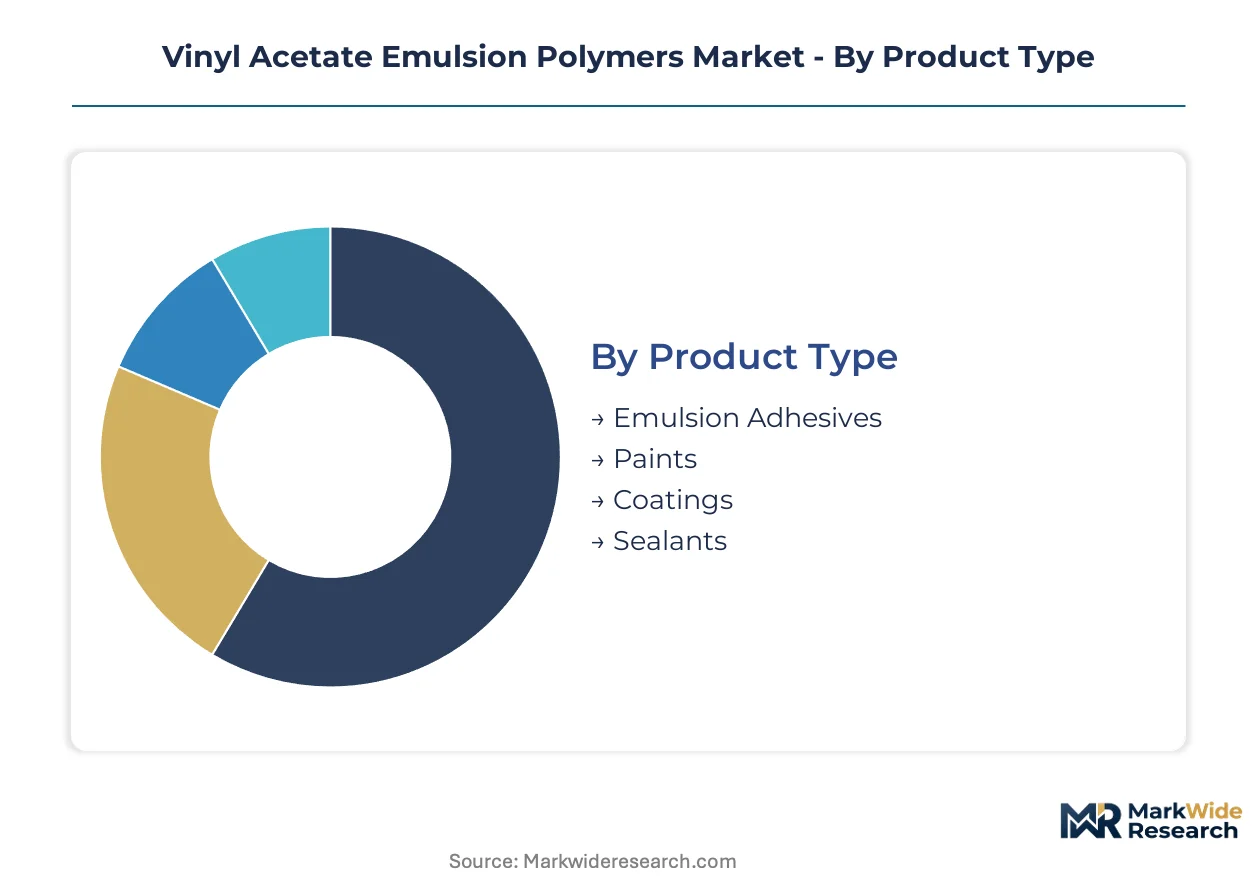
Vinyl acetate emulsion polymers serve divergent performance requirements across adhesives, coatings, and sealants. Segmentation reveals how formulation specifications, procurement patterns, and regulatory exposure fragment addressable markets.
Product Type:
Buyers differentiate primarily by film-forming requirements and VOC compliance thresholds rather than base chemistry alone.
- Emulsion Adhesives:Polyvinyl acetate homopolymers and vinyl acetate-ethylene copolymers formulated with polyvinyl alcohol protective colloids deliver bond strength for porous substrates. Construction contractors in China are specifying certified low-emission grades for government-procured flooring and panel assembly under MEE environmental inspection protocols.
- Paints:Waterborne architectural systems displace solvent alkyd binders in decorative and protective applications. German and French coatings manufacturers are reformulating interior wall systems to satisfy REACH disclosure obligations and EU Green Deal chemical sustainability scoring methodologies.
- Coatings:Industrial finishes for metal and wood substrates demand enhanced water resistance and UV stability. Protective applications in automotive refinishing and machinery are absorbing specification gains as performance parity with solvent systems improves.
- Sealants:Flexible joint compounds and gap-fillers for building envelopes require elongation recovery and weathering resistance. Caulk and construction sealant producers blend vinyl acetate copolymers with plasticizers to meet movement accommodation specifications.
Emulsion adhesives lead volumes today; paints are gaining share fastest as architectural waterborne reformulation accelerates.
Application:
Volume concentration tracks construction intensity and packaging conversion rates in major manufacturing economies.
- Construction:Flooring adhesives, tile bonding systems, and engineered wood panel lamination consume vinyl acetate-ethylene copolymers for moisture resistance. State-funded infrastructure programs in Chinese tier-one cities are driving specification of certified low-VOC systems for interior air quality compliance.
- Packaging:Flexible food-grade laminates and corrugated board bonding represent the fastest-expanding specification frontier. Japanese and German converters are qualifying vinyl acetate-ethylene copolymers for retort pouches and lidding structures previously served by solvent polyurethane systems.
- Automotive:Interior trim bonding and lightweight composite assembly use heat-resistant copolymer grades. OEM pressure to reduce cabin VOC emissions is redirecting adhesive procurement toward waterborne emulsion systems.
- Textiles:Nonwoven fabric binders and fabric finishing applications require soft hand and wash durability. Technical textile manufacturers in South Korea and Italy specify emulsion polymers for geotextiles and filtration media.
Construction anchors current demand; packaging climbs the fastest as food-contact specifications expand.
End User:
Procurement authority concentrates with volume-scale buyers who command formulation customization and just-in-time delivery guarantees.
- Manufacturers:Building product companies and packaging converters purchase bulk emulsions for in-house adhesive compounding and coating operations. Direct mill relationships with corrugated board and engineered wood producers are displacing traditional chemical distributor networks.
- Contractors:Large construction firms and modular building specialists specify certified low-emission systems for government and commercial projects. National account managers at retailers now hold specification authority for volume-tiered procurement.
- Distributors:Regional chemical distributors serve mid-scale adhesive formulators and coatings manufacturers with blended product portfolios. Margin compression in commoditized wood glue segments is forcing portfolio shifts toward specialty copolymers.
- Retailers:Home improvement chains and building materials retailers stock consumer-grade wood adhesives and architectural coatings. Private-label sourcing decisions increasingly weight environmental certification and supply chain transparency.
Manufacturers dominate procurement volumes; contractors are expanding specification influence fastest through direct mill relationships.
Distribution Channel:
Channel selection reflects order scale, formulation complexity, and technical service requirements.
- Direct Sales:Large-volume adhesive and coatings manufacturers negotiate directly with emulsion polymer producers for custom formulations and dedicated supply agreements. BASF and Wacker Chemie AG anchor premium positioning through technical collaboration with European construction adhesives customers.
- Wholesale:Regional distributors aggregate demand from mid-scale formulators and provide inventory management services. This channel retains relevance where formulation expertise and local technical support differentiate supplier relationships.
- Online Retail:E-commerce platforms serve small-batch purchasers and specialized applications requiring rapid sourcing. Digital procurement is penetrating standard-grade wood adhesives and architectural coatings segments with transparent pricing.
- Others:Agent networks and cooperative purchasing arrangements serve fragmented geographies and niche applications. These channels persist where logistics infrastructure or credit terms require localized intermediation.
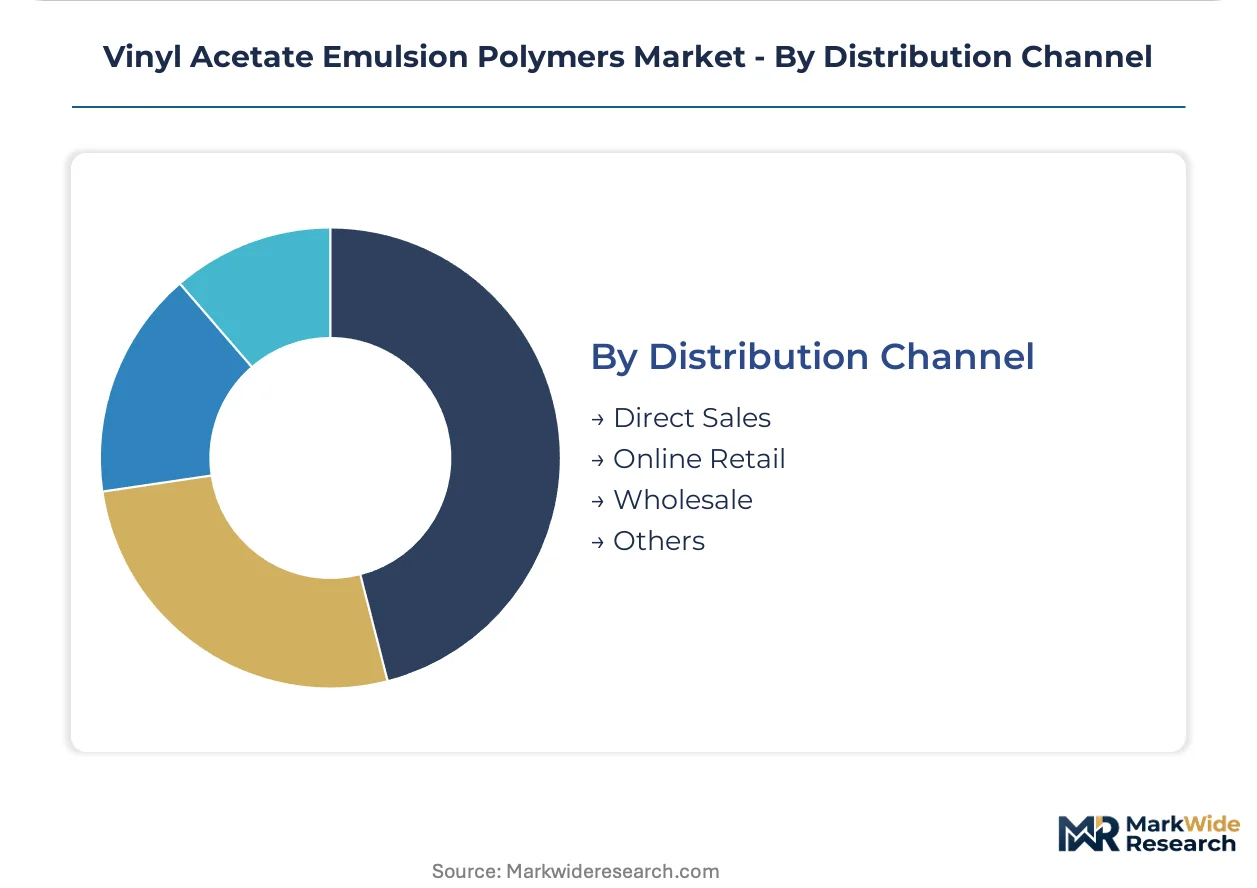
Direct sales capture the largest volume flows; online retail is expanding most quickly in standardized product segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale vinyl acetate emulsion polymer production during the mid-20th century, establishing the technical foundation that now diffuses across construction and packaging applications worldwide.
China
State-funded infrastructure programs in Shanghai, Beijing, and Shenzhen are consuming vinyl acetate-ethylene copolymers for moisture-resistant flooring adhesives and tile bonding systems. The Ministry of Ecology and Environment (MEE) environmental inspections and GB standards for indoor air quality are disqualifying uncertified emulsion systems from government-procured construction projects. The Yangtze River Delta concentration of building materials manufacturers is driving specification of certified low-VOC grades for interior applications.
Germany
REACH registration requirements and the EU Green Deal chemical sustainability targets are redirecting construction materials procurement toward certified low-emission emulsion binders for interior applications. The German coatings cluster around Leverkusen and Ludwigshafen is reformulating architectural wall systems to satisfy disclosure obligations and sustainability scoring methodologies. Bavaria and North Rhine-Westphalia anchor European emulsion polymer specification authority for premium construction adhesives.
United States
EPA VOC emissions standards for architectural coatings and adhesives are constraining product formulation choices across state-level regulatory variations. The Southeast concentration of engineered wood and corrugated board manufacturers is absorbing specification gains for packaging adhesives through direct mill relationships. Texas and Georgia building product clusters are driving procurement consolidation toward volume-tiered supply agreements with national retailers.
Japan
METI industrial standards and JIS certification requirements are qualifying vinyl acetate-ethylene copolymers for food-contact flexible packaging applications including retort pouches and lidding structures. The Kansai region around Osaka hosts multinational packaging converters penetrating premium segments previously served by solvent polyurethane systems. Tokyo-based coatings manufacturers are displacing solvent alkyd binders with waterborne emulsion systems for automotive and industrial finishes.
India
Bureau of Indian Standards (BIS) certification and state-level building code adoption are tightening permissible formaldehyde and VOC content in construction materials across Maharashtra and Gujarat. The Delhi-Mumbai Industrial Corridor infrastructure investment is redirecting demand toward certified low-emission emulsion systems for commercial and residential building applications. Tamil Nadu textile manufacturers are specifying emulsion polymers for nonwoven fabric binders and technical textile finishing.
Vinyl Acetate Emulsion Polymers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification depth, with backward-integrated feedstock control separating cost structures. The vendor base concentrates among diversified chemical conglomerates with captive acetic acid supply and specialized emulsion polymer houses with protective colloid expertise. Three archetypes dominate: integrated petrochemical majors with ethylene-acetic acid chains, European specialty chemical players with silicones-emulsions technology platforms, and regional formulators serving construction distributor networks. Competitive moves center on multi-jurisdiction product requalification for EPA, REACH, and China GB compliance, plus direct mill relationship cultivation with corrugated board and engineered wood manufacturers.
Within the integrated petrochemical tier, BASF and Dow Inc. exemplify scale-driven positioning anchored by upstream control over acetic acid and ethylene feedstocks. Wacker Chemie AG occupies a distinctive premium-tier position through its integrated silicones-emulsions technology platform, representing the European specialty chemical archetype that competes on formulation collaboration rather than feedstock scale. These three companies illustrate how competitive positioning fragments across cost leadership, technical differentiation, and geographic supply chain concentration.
| Leading Market Players |
|---|
| BASF |
| Wacker Chemie AG |
| Celanese Corporation |
| Dow Inc. |
| Arkema |
| Clariant |
| Synthomer |
| DIC Corporation |
| Trinseo |
| Others |
Value Network & Pricing Analysis
Acetic acid feedstock index volatility cascades through vinyl acetate emulsion polymer supply chains into three distinct pricing tiers anchored by backward integration depth, certification grade, and volume scale. Producers with captive ethylene supply command structural cost advantages that independent manufacturers cannot replicate, compressing margins at the economy tier while premium grades sustain formulation premiums through REACH compliance and low-VOC certification.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects divergence in protective colloid quality, regulatory certification depth, and technical service bundling. Premium grades carrying EU Green Deal compliance and China GB standard certification command sustained premiums from construction contractors and packaging converters. Cost compression in standard wood glue formulations intensifies due to Asian import competition with minimal solids content differentiation. Large building product retailers exhibit highest price sensitivity through volume-tiered procurement negotiations, while specialty packaging converters prioritize heat seal performance over unit cost.
Supply Chain Analysis
Acetic acid supply rests on integrated petrochemical complexes in Germany, the United States, and China with varying ethylene feedstock access. Vinyl acetate monomer production draws from coal-based acetylene chemistry in China and ethylene-based routes in Western markets. Single-source vulnerability concentrates in polyvinyl alcohol protective colloids manufactured by specialized chemical houses. Distribution runs through direct mill relationships with corrugated board and engineered wood manufacturers, displacing traditional chemical distributor networks in North American packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vinyl acetate emulsion polymers function as a stable compounder anchored by construction sector specification of low-VOC systems that resists cyclical demand collapse. Regulatory tightening across EPA, REACH, and China GB standards creates durable pricing power for certified producers.
For Market Incumbents: To counter margin compression from commoditized wood glue imports, deepen protective colloid formulation expertise and secure multi-jurisdiction certification for EPA VOC compliance, REACH registration, and China GB standard testing. Anchor premium positioning through direct mill relationships with engineered wood and corrugated board manufacturers that consolidate procurement authority.
For New Entrants and Emerging Players: The price-point gap between solvent-based flexible packaging laminates and certified emulsion alternatives creates white-space opportunity in food-contact retouch pouch and lidding applications. Penetrate Japanese and German converter qualification pipelines by demonstrating organoleptic neutrality and heat seal strength parity with polyurethane systems. Pursue partnership routes with regional building materials distributors serving mid-scale adhesive formulators outside direct mill networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where independent emulsion manufacturers lack backward integration into acetic acid and face 18-24 month requalification timelines for multi-jurisdiction compliance. Target specialty chemical houses with captive protective colloid technology and established REACH disclosure documentation. Watch MEE environmental inspection enforcement intensity in Chinese tier-one cities as inflection indicator for certified low-VOC grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Captive ethylene supply locks in cost advantages against Asian import competition. |
| Multi-Jurisdiction Certification Investment | REACH, EPA VOC, and China GB compliance extends product launch cycles but secures specification status. |
| Direct Mill Relationship Cultivation | Building product retailers and corrugated manufacturers consolidate procurement through national account managers. |
| Flexible Packaging Laminate Qualification | Japanese and German converters seek heat seal performance rivaling solvent polyurethane systems. |
| Protective Colloid Formulation Collaboration | Wacker Chemie AG leverages integrated silicones-emulsions platforms for premium construction adhesives positioning. |
Research Methodology
Direct dialogue with emulsion polymer plant managers, procurement leads at downstream adhesive formulators, technical R&D directors, and distribution channel partners grounds qualitative assessment in operational reality. Secondary validation draws from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings, and regulatory agency disclosure databases. Bottom-up demand modeling across adhesives, paints, coatings, and sealants segments triangulates against top-down macroeconomic indicators.
Segmented volume and value outputs emerge from modeling grade tier, end-use industry, packaging format, and regional production hub dimensions across the projection horizon. CAGRs derive from regression analysis against construction spending indices, packaging conversion rates, and regulatory compliance cost absorption curves. Industry-specific inputs include vinyl acetate-ethylene copolymer penetration rates in flexible food packaging and MEE environmental inspection enforcement intensity in Chinese tier-one cities.
Caveats apply where acetic acid feedstock volatility, regulatory divergence between EPA VOC and REACH timelines, or formaldehyde emission standard tightening could materially shift the outlook. A small set of triggers including China infrastructure program funding levels, EU Green Deal chemical sustainability scoring adoption, and protective colloid supply concentration warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Propylene Terpolymer Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Latent Curing Agents for Epoxy Resin Market
Polymers & Resins
Global Chromatography Resin Market