
 Anti-Fog Lens Market | 2026-2036
Anti-Fog Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Fog Lens Market Outlook
Capital-intensity divergence between integrated coating developers and assembly-only manufacturers is unwinding competitive stability in the anti-fog lens supply base. ZEISS International leverages captive optical coating technology to sustain premium positioning across medical and industrial channels. EssilorLuxottica anchors volume scale through global retail networks while competing on brand breadth rather than coating chemistry leadership.
An anti-fog lens incorporates hydrophilic surface treatments—typically nano-scale surfactant layers or permanent polymer coatings—that reduce water droplet contact angles below 15 degrees to maintain optical clarity across temperature differentials. Polycarbonate substrates dominate material selection due to impact resistance and coating adhesion properties, though acrylic alternatives occupy cost-sensitive recreational segments. Medical eyewear represents the fastest-growing application category as hospital infection-control protocols expand eye-protection mandates, while industrial safety retains the largest installed base with mature replacement cycles. Distribution runs through specialty safety distributors for bulk corporate procurement, though online retail channels are capturing smaller healthcare and sports end-users.
FDA device classification for medical eyewear and OSHA eye-protection standards jointly determine product certification requirements in the United States, creating compliance barriers for uncoated or substandard imports. The EU's REACH regulation and CE marking under the Personal Protective Equipment Regulation shape coating formulation and testing protocols for European market access. Stakeholders must monitor evolving healthcare procurement centralization and polymer feedstock volatility as dual determinants of margin sustainability.
Market Dynamics
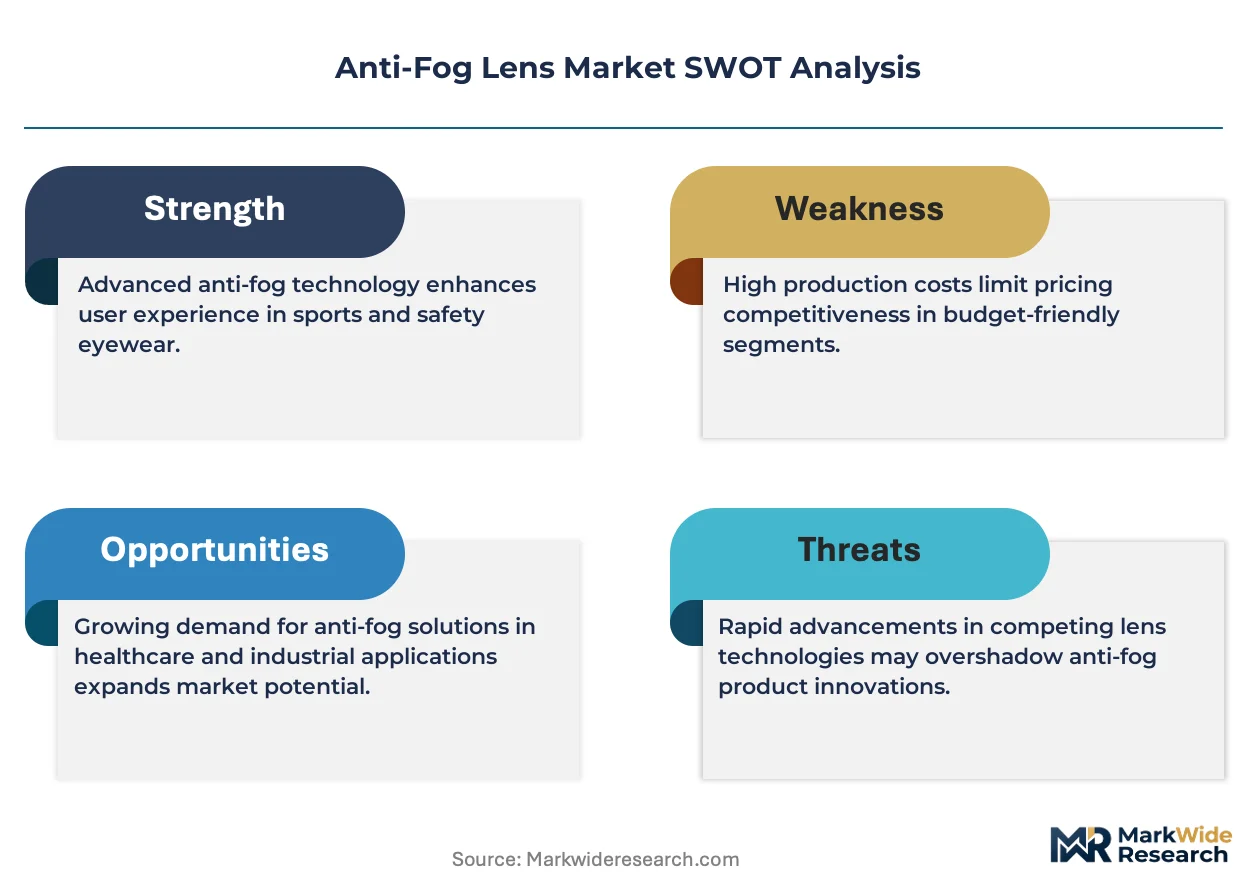
Coating chemistry differentiation is fragmenting the anti-fog lens supply base as hydrophilic nano-surfactant layers displace conventional polymer treatments across medical and industrial channels. Manufacturers with captive optical coating capabilities now command pricing premiums against assembly-only competitors.
Growth Catalysts
- Hospital infection-control mandates:United States healthcare facilities are expanding procurement of medical eyewear with anti-fog coatings to meet Joint Commission eye-protection protocols in surgical and emergency departments.
- REACH chemical reformulation:The European Union's REACH regulation on chemical substances in coatings is pushing manufacturers toward permanent polymer alternatives that eliminate perfluorinated compounds.
- Germany's industrial safety cluster:Demand concentrates around Munich and Stuttgart where automotive and precision manufacturing facilities require certified anti-fog protection for high-humidity assembly environments.
Market Restraints
- Polycarbonate feedstock volatility:Bisphenol A price swings and benzene derivative supply constraints compress margin predictability for substrate-dependent manufacturers.
- Coating equipment concentration:Vacuum deposition and plasma treatment system suppliers cluster in Japan and Germany, creating capex bottlenecks for mid-scale entrants.
- Acrylic substitution in recreation:Cost-sensitive sports eyewear buyers accept inferior coating durability to achieve unit price reductions below medical-grade thresholds.
Strategic Opportunities
- India's healthcare infrastructure expansion:Central government hospital procurement programs under Ayushman Bharat create first-mover advantages for anti-fog medical eyewear suppliers establishing CDSCO certification pathways.
- Augmented reality convergence:Smart glasses integration with heads-up displays requires anti-fog coatings compatible with waveguide optics and sensor arrays.
- Direct-to-clinic distribution:Online platforms bypass specialty safety distributors to capture smaller healthcare practices and dental clinics with lower minimum order quantities.
Industry Challenges
- Multi-jurisdiction certification timelines:FDA 510(k) clearance for medical eyewear and CE marking under EU MDR create sequential approval bottlenecks stretching 18-24 months.
- Coating-to-substrate adhesion expertise:Thin-film deposition physics and surface energy matching require specialized process engineers scarce outside established optical hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Fog Lens Market |
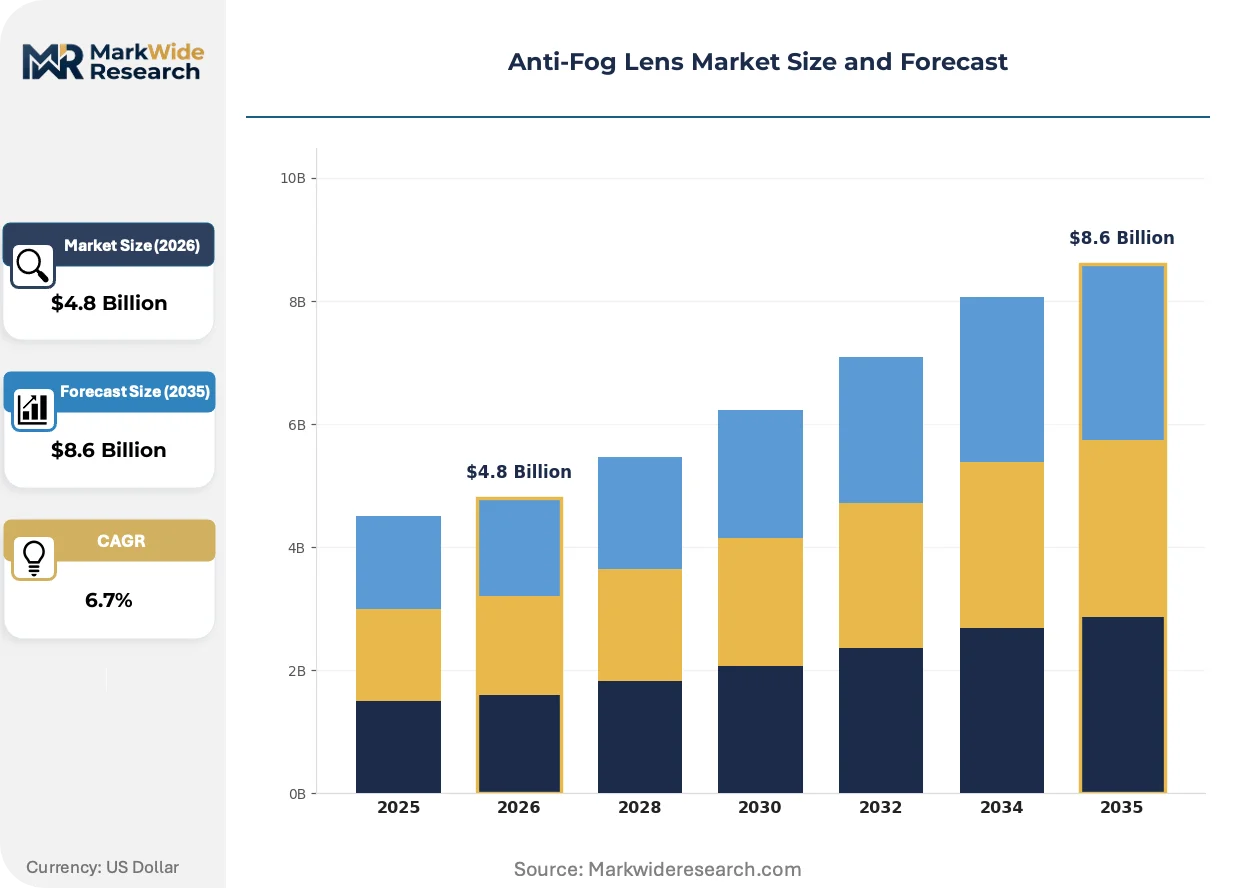
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Goggles, Face Shields, Sports Glasses, Medical Eyewear Material: Polycarbonate, Acrylic, Glass, PVC Application: Industrial Safety, Sports, Healthcare, Recreational Use Distribution Channel: Online Retail, Distributors, Specialty Stores, Wholesale |
| Companies Covered | ZEISS International, Bolle Safety, EssilorLuxottica, Pyramex Safety Products, Uvex Safety Group, 3M Company, Hoya Corporation, MSA Safety, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Fog Lens Market Strategic Shifts
Surface engineering advances are compressing the performance gap between permanent and reapply anti-fog treatments while regulatory chemical restrictions force formulation pivots. These shifts are redrawing competitive boundaries between integrated coating developers and component assemblers.
Plasma-enhanced chemical vapor deposition is decomposing the traditional trade-off between coating durability and optical clarity. Medical device manufacturers in the United States and Germany are adopting this process for surgical loupes and protective eyewear at accelerating rates. The technology is decomposing incumbent wet-coating equipment installed bases and raising capital barriers for new market entrants.
REACH Annex XVII restrictions on perfluorinated substances are compelling coating reformulations across European supply chains. Manufacturers must validate alternative hydrophilic chemistries through ECHA notification procedures before commercial placement. Medical eyewear exports to the European Union face the most acute compliance pressure, with several suppliers accelerating in-house toxicology testing investments.
Corporate safety procurement consolidation is compressing distributor margins and favoring direct manufacturer relationships. Large industrial employers in Germany and the United States are unbundling eyewear from broad personal protective equipment contracts to negotiate anti-fog specifications separately. This pattern is most visible in automotive final assembly and food processing verticals where fogging incidents carry specific liability exposure.
Anti-Fog Lens Market Segmentation
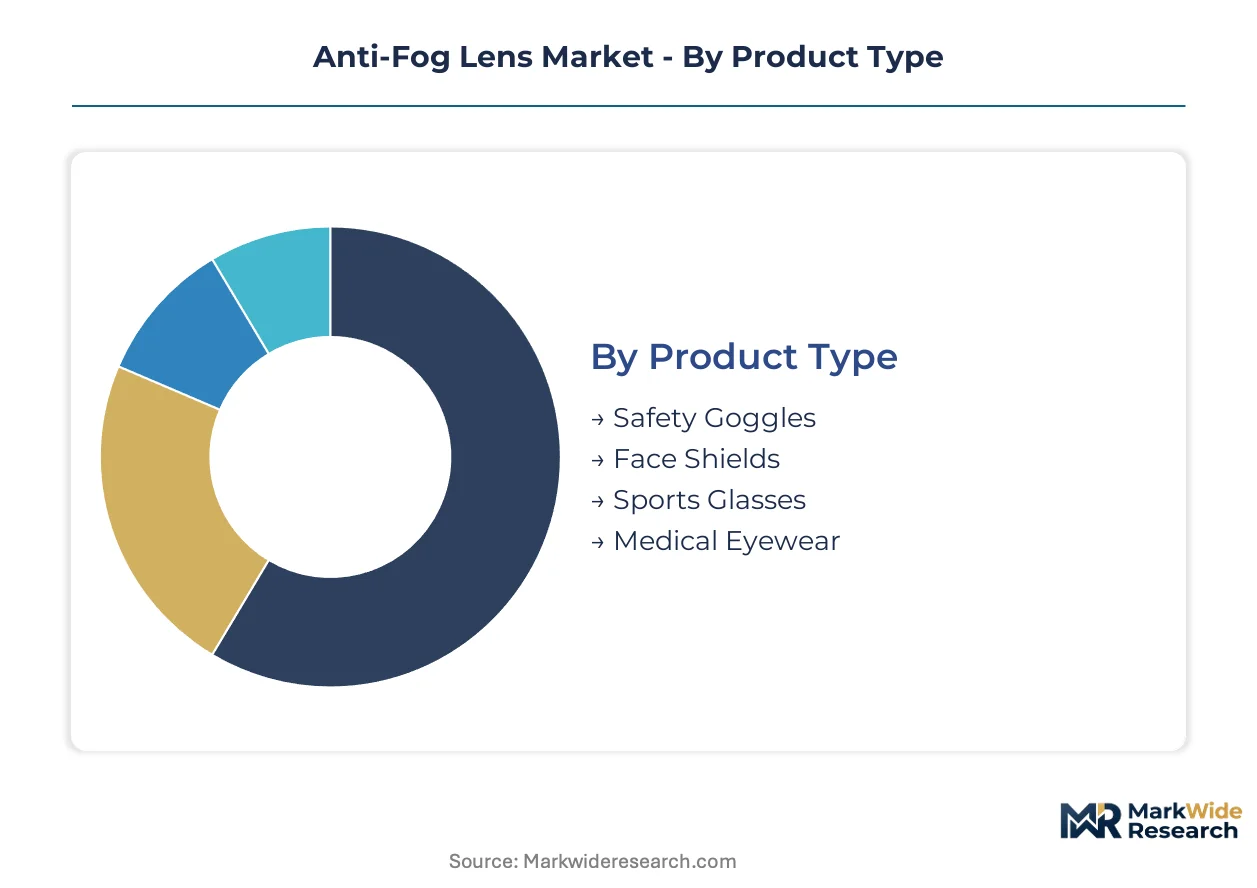
Anti-fog lens manufacturers navigate divergent margin structures across product categories, with coating chemistry sophistication and certification requirements determining profitability tiers. Segmentation clarity exposes where integrated coating capabilities yield pricing power versus assembly-only commoditization.
Product Type:
Premium margin pools concentrate in medical-grade and industrial-certified eyewear where coating durability and regulatory compliance create defendable positions.
- Safety Goggles:Enclosed designs with indirect ventilation rely on permanent hydrophilic polymer coatings to prevent fogging in high-humidity industrial environments. Demand clusters in Germany's automotive assembly plants around Stuttgart, where OSHA-equivalent workplace standards mandate certified eye protection for chemical handling and grinding operations.
- Medical Eyewear:Surgical loupes, protective goggles, and face shields incorporate nano-scale surfactant layers compatible with hospital sterilization protocols. United States healthcare facilities under Joint Commission oversight are expanding procurement to meet expanded eye-protection mandates in emergency and surgical departments, driving coating chemistry investments.
- Face Shields:Full-face coverage with anti-fog films serves dental and laboratory settings where splash protection intersects with clarity requirements.
- Sports Glasses:Cycling and skiing eyewear prioritizes impact resistance over coating longevity, accepting shorter functional lifespans for weight reduction.
The dominant share belongs to Safety Goggles, while Medical Eyewear is closing the gap fastest.
Material:
Substrate selection traces cost-performance trade-offs, with high-performance polymers commanding technical premiums against commodity alternatives.
- Polycarbonate:Impact-resistant thermoplastic with superior coating adhesion properties dominates medical and industrial channels. Bisphenol A feedstock volatility from benzene derivative supply constraints compresses margin predictability for manufacturers without backward integration into polymer supply.
- Acrylic:Lower-cost alternative with inferior coating durability occupies recreational sports segments where unit price sensitivity outweighs functional longevity requirements.
- Glass:Optical clarity leader in precision applications remains niche due to weight and fragility limitations.
- PVC:Cost-minimized option for disposable face shields in high-turnover healthcare settings.
Polycarbonate holds the volume base, though Acrylic substitution is accelerating in price-sensitive recreational channels.
Application:
End-use concentration shapes coating specification requirements, with regulated environments demanding validated performance against consumer discretionary tolerances.
- Industrial Safety:Mature replacement cycles in manufacturing, construction, and chemical processing sustain baseline demand. Germany's precision manufacturing cluster around Munich generates concentrated procurement from automotive and electronics assembly facilities requiring CE-marked protection under EU PPE Regulation.
- Healthcare:Hospital infection-control protocol expansion and surgical eye-protection mandates drive specification upgrades. FDA 510(k) clearance requirements for medical devices create compliance barriers that favor established coating developers with toxicology testing infrastructure.
- Sports:Performance and recreational cycling, skiing, and motorcycling segments prioritize aesthetics and weight over coating permanence.
- Recreational Use:General-purpose eyewear for hunting, fishing, and outdoor activities accepts lower-grade treatments.
Industrial Safety retains the largest installed base, while Healthcare posts the steepest expansion trajectory.
Distribution Channel:
Channel economics separate bulk corporate procurement from fragmented small-lot purchasing, with digital platforms disrupting traditional distributor relationships.
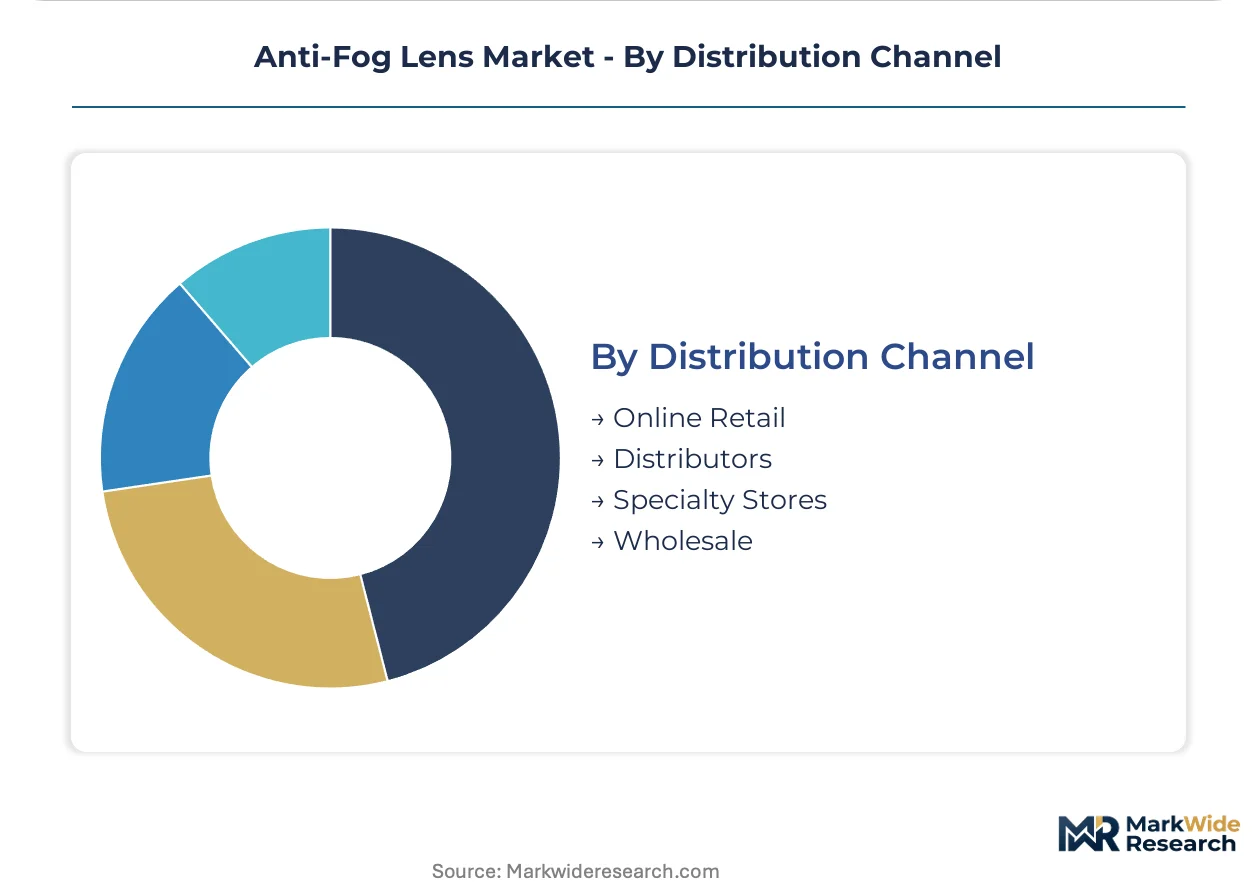
- Distributors:Specialty safety distributors dominate bulk corporate procurement for industrial and healthcare facilities, though margin compression from procurement consolidation is forcing unbundling of eyewear from broad PPE contracts.
- Online Retail:Direct-to-clinic and direct-to-consumer platforms capture smaller healthcare practices, dental offices, and sports end-users with lower minimum order quantities and faster fulfillment.
- Specialty Stores:Optical retailers and safety equipment dealers provide fitting services and prescription integration for medical and industrial buyers.
- Wholesale:Volume aggregation for retail chains and institutional procurement programs.
Distributors still command the revenue majority, yet Online Retail is gaining share fastest among smaller healthcare and sports purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward deficit in coating equipment-dependent markets while surplus regions concentrate captive optical manufacturing. Anti-fog lens trade flows track industrial safety procurement cycles and medical device certification timelines across major economies.
United States
Hospital infection-control mandates from the Joint Commission drive medical eyewear procurement expansion. FDA 510(k) clearance requirements for medical devices create compliance barriers favoring established coating developers. Industrial safety demand clusters around Detroit automotive assembly and Houston petrochemical corridors where OSHA eye-protection standards enforce certified anti-fog specifications.
Germany
REACH Annex XVII restrictions on perfluorinated substances compel coating reformulation across European supply chains. CE marking under the EU PPE Regulation shapes testing protocols for industrial safety market access. Munich and Stuttgart anchor precision manufacturing demand from automotive and electronics assembly facilities requiring certified protection in high-humidity environments.
China
Domestic healthcare infrastructure expansion under hospital procurement centralization programs accelerates medical eyewear specification upgrades. NMPA medical device registration creates parallel approval pathways for imported coating technologies. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou concentrate vacuum deposition equipment suppliers serving regional lens fabricators.
India
Ayushman Bharat hospital procurement programs generate first-mover opportunities for anti-fog medical eyewear establishing CDSCO certification pathways. BIS standards for personal protective equipment intersect with state-level industrial safety enforcement. Maharashtra and Gujarat pharmaceutical manufacturing corridors drive concentrated demand for surgical loupes and protective eyewear in sterile processing environments.
Japan
METI industrial safety guidelines and PMDA medical device oversight create dual regulatory frameworks for anti-fog lens market entry. JIS standards for eye protection influence specification requirements across manufacturing verticals. Kanto region precision optics clusters around Tokyo and Yokohama maintain coating technology leadership serving domestic medical device manufacturers.
Anti-Fog Lens Market Competitive Environment
Concentration sits with integrated coating developers possessing captive optical technology and established certification infrastructure. Assembly-only manufacturers face margin compression from feedstock volatility and equipment supplier bottlenecks. Two strategic archetypes dominate: premium-positioned optical specialists leveraging proprietary surface engineering, and scale-driven safety conglomerates competing through distribution breadth. Competitive moves center on coating chemistry licensing partnerships and direct-to-clinic distribution bypassing traditional safety distributors.
Within the integrated optical specialist tier, ZEISS International and Hoya Corporation exemplify technology-led positioning through captive coating capabilities. EssilorLuxottica anchors volume scale through global retail network presence. Among diversified safety conglomerates, 3M Company and Honeywell International Inc. occupy positions spanning industrial PPE portfolios where eyewear represents one component of bundled procurement relationships. MSA Safety and Uvex Safety Group sit within the pure-play safety equipment archetype, competing on certification breadth and corporate account penetration rather than coating chemistry differentiation.
| Leading Market Players |
|---|
| ZEISS International |
| Bolle Safety |
| EssilorLuxottica |
| Pyramex Safety Products |
| Uvex Safety Group |
| 3M Company |
| Hoya Corporation |
| MSA Safety |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between polycarbonate resin suppliers and integrated coating developers lock in both substrate access and margin visibility across medical and industrial channels. These arrangements insulate ZEISS International and Hoya Corporation from benzene derivative volatility while forcing assembly-only competitors into spot-market exposure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA 510(k) certification tier and volume scale, with hospital procurement consolidation compressing distributor markups. Cost compression in the acrylic recreational tier is intensifying because Asian manufacturers are flooding sports eyewear channels with disposable alternatives. Dental clinics and small healthcare practices exhibit the highest price sensitivity, while surgical loupe manufacturers accept premium positioning for sterilization-compatible coatings.
Supply Chain Analysis
Japan and Germany anchor vacuum deposition equipment manufacturing, feeding coating systems to polycarbonate substrate fabricators in China and the United States. Raw material flows draw from bisphenol A producers in the US Gulf Coast and benzene derivative complexes in Northeast Asia. Single-source vulnerability concentrates in plasma treatment system suppliers clustered around Tokyo and Yokohama. Distribution runs through specialty safety distributors for bulk corporate procurement, though direct-to-clinic platforms are fragmenting smaller-lot channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-fog lens market functions as a regulatory-moat arena where FDA 510(k) clearance and REACH-compliant coating chemistry create switching costs that entrench established developers against commodity assemblers.
For Market Incumbents: Shield market position by deepening captive coating capabilities through backward integration into polymer substrate supply, particularly around bisphenol A procurement hedges. Accelerate toxicology testing infrastructure investments to preempt REACH Annex XVII expansion into additional fluorinated chemistries. Channel control through direct-to-clinic platforms offers defensive leverage against distributor margin compression. For New Entrants and Emerging Players: CDSCO fast-track certification for Ayushman Bharat hospital procurement programs in Maharashtra and Gujarat offers the most penetrable entry vector. Target India's pharmaceutical manufacturing corridors with surgical loupe specifications tailored to sterile processing environments. A go-to-market angle anchored on plasma-enhanced chemical vapor deposition compatibility with waveguide optics for augmented reality eyewear bypasses incumbent wet-coating equipment lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward integrated optical specialists with captive coating technology and established FDA/ECHA toxicology validation infrastructure. Long-term viability over a multi-year horizon favors developers with in-house plasma deposition physics expertise rather than assembly-only manufacturers exposed to feedstock volatility. The signal to watch is consolidation among vacuum equipment suppliers in Japan and Germany, which would tighten capex bottlenecks and accelerate margin compression for non-integrated competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Deposition Capacity Expansion | PE-CVD systems from Tokyo and Yokohama suppliers enable permanent coating durability for surgical loupes. |
| REACH-Compliant Chemistry Reformulation | ECHA notification procedures for perfluorinated alternatives secure European medical eyewear market access. |
| Direct-to-Clinic Distribution Launch | Online platforms bypass specialty safety distributors to capture dental and small-practice procurement. |
| CDSCO Certification Fast-Track | Ayushman Bharat hospital programs in Maharashtra create first-mover positioning in India's healthcare expansion. |
| Polycarbonate Backward Integration | Upstream control over bisphenol A supply insulates margin predictability from benzene derivative volatility. |
Study Parameters
Operator-level perspectives from coating process engineers, hospital purchasing committee members, biomedical equipment specialists, and GPO contracts managers anchored the qualitative base. These primary inputs combined with secondary validation from FDA 510(k) filings, ECHA REACH registration databases, hospital procurement contract disclosures, and SEC filings from listed optical manufacturers. Bottom-up volume estimates across product categories triangulated against top-down market sizing from trade flow analysis.
Sensitivity analysis tested forecast outputs across the projection horizon against polycarbonate feedstock price scenarios and regulatory timeline variations. Segmentation dimensions modeled include coating chemistry type, substrate material grade, application end-use, certification tier, and regional procurement cluster. CAGRs derived from historical shipment trajectories and capacity expansion announcements, with medical eyewear specification upgrades and industrial safety replacement cycles as primary demand drivers.
Underlying assumptions cover REACH Annex XVII enforcement continuity and Joint Commission eye-protection mandate expansion, with deviation risk concentrated in polymer feedstock supply disruptions and multi-jurisdiction certification timeline extensions. Recalibration cycles align with material shifts in regulatory chemical restrictions and healthcare procurement centralization patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Goggles Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Luxury Sunglass Market
Eyewear
Reading Glasses Market
Eyewear
Sunglasses Pouch Market
Eyewear
Latin America Eyewear Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Face and Ear Bow Market
Eyewear
Wooden Eyewear Market
Eyewear
Smart Eyewear Market
Eyewear
Luxury Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
Smart Sunglasses Market
Eyewear
Blue Light Glasses Market
Eyewear
Spectacles Market