
 Asia-Pacific Eyewear Market | 2026-2036
Asia-Pacific Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Eyewear Market Insights
A shift from single-source acetate suppliers toward multi-source resin partnerships is recalibrating procurement risk across the Asia-Pacific eyewear supply base. Essilor leverages its captive lens-finishing network in Thailand to sustain margin control across Southeast Asian optical chains. Lenskart competes through vertically integrated home-try-on logistics, while HOYA Corporation anchors premium progressive lens output from its Philippine manufacturing hub.
Asia-Pacific eyewear encompasses vision-correction devices, solar-protection lenses, and occupational safety frames fabricated from cellulose acetate, polycarbonate, and titanium alloys through precision injection molding and free-form surfacing processes, serving refractive correction, UV attenuation, and impact-protection functions. Prescription glasses dominate value generation due to recurring lens replacement cycles among aging populations, while contact lenses capture faster volume growth from younger consumers seeking aesthetic alternatives. Online retail channels are displacing traditional optical store traffic in India and South Korea, though specialty stores retain premium fitting margins across Japan's mature market.
Japan's PMDA and METI enforce medical-device classification and manufacturing quality standards for corrective lenses, while China's NMPA and SAMR regulate contact lens distribution through licensed optical practitioner requirements, tightening market access for unapproved imports. India's CDSCO and BIS mandate ISI marking on prescription lenses sold through domestic channels, elevating compliance costs for regional distributors. Stakeholders must monitor evolving digital health integrations as smart glasses blur boundaries between consumer electronics and regulated medical devices across Asia-Pacific enforcement regimes.
Market Dynamics
Japan's METI energy-efficiency mandates for manufacturing facilities are compressing lens production timelines while forcing capital retooling across precision molding operations in Jiangsu and Zhejiang provinces.
Growth Catalysts
- Blue-light filtering prescription lenses:Young adults in urban India and China are driving adoption of these specialized lenses as screen-time exposure intensifies across knowledge-work sectors.
- Thailand's captive lens-finishing networks:Southeast Asian optical chains benefit from integrated regional manufacturing that reduces import dependency and shortens fulfillment cycles.
- India's PLI scheme for manufacturing:Domestic production incentives are attracting resin processing and frame assembly investments away from traditional coastal export zones.
Market Restraints
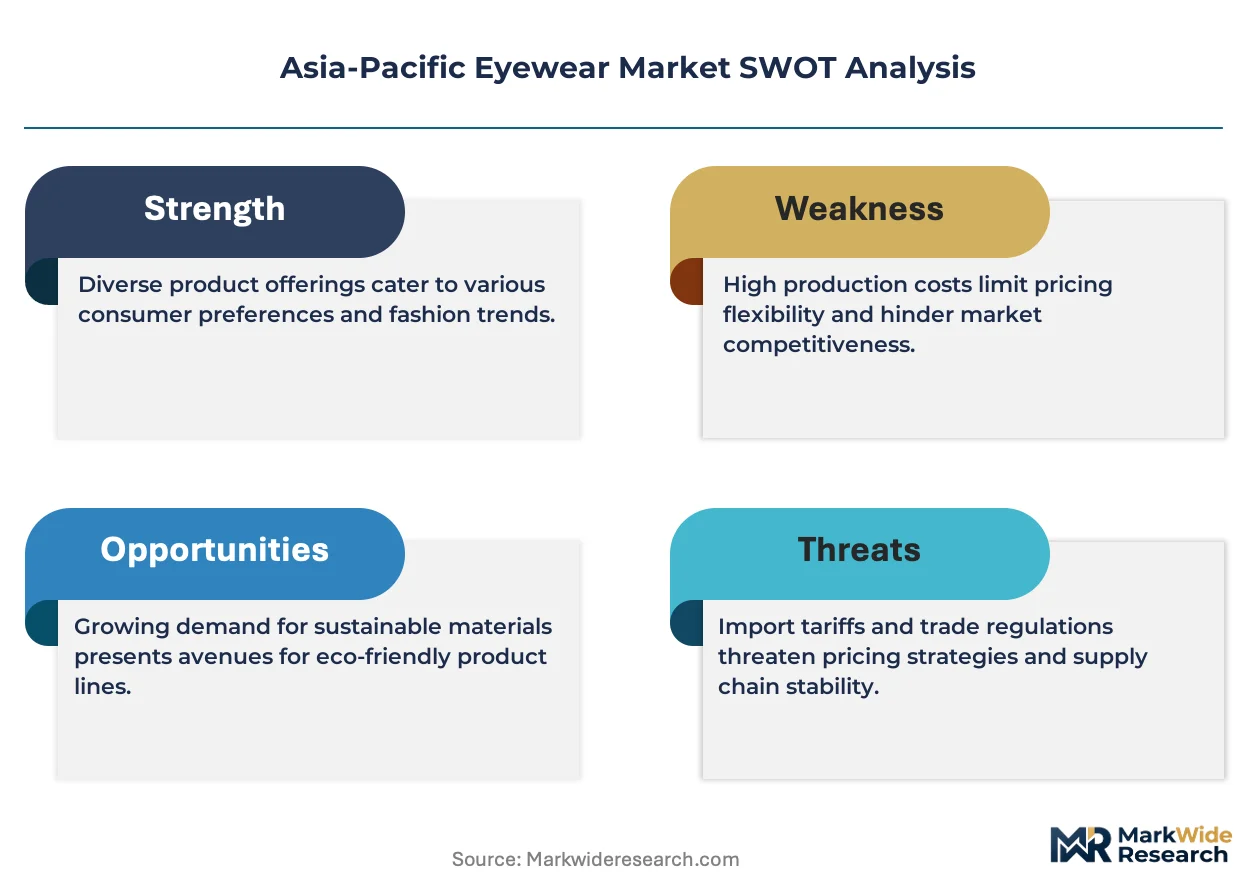
- Acetate supply concentration:Heavy reliance on single-source cellulose acetate suppliers creates vulnerability to petrochemical feedstock volatility and force majeure disruptions.
- Polycarbonate input cost volatility:Bisphenol-A price swings directly compress margin structures for impact-resistant lens producers serving safety eyewear segments.
- China's NMPA licensing requirements:Contact lens distribution restrictions through licensed optical practitioners block direct-to-consumer channels for imported brands.
Strategic Opportunities
- Free-form surfacing technology convergence:Integration of digital scanning with CNC lens fabrication enables mass customization of progressive lenses at mid-market price points.
- Smart glasses regulatory ambiguity:Asia-Pacific enforcement regimes have not finalized medical-device classifications for augmented-reality eyewear, creating first-mover windows.
- South Korea's online optical retail:Virtual try-on platforms and tele-optometry are displacing traditional store traffic among digital-native consumers.
Industry Challenges
- Free-form surfacing technician scarcity:Precision lens fabrication requires specialized CNC programming skills that outpace vocational training output in Philippine and Thai manufacturing hubs.
- CDSCO ISI marking timelines:India's domestic lens certification process extends product launch cycles by four to six months for regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Eyewear Market |
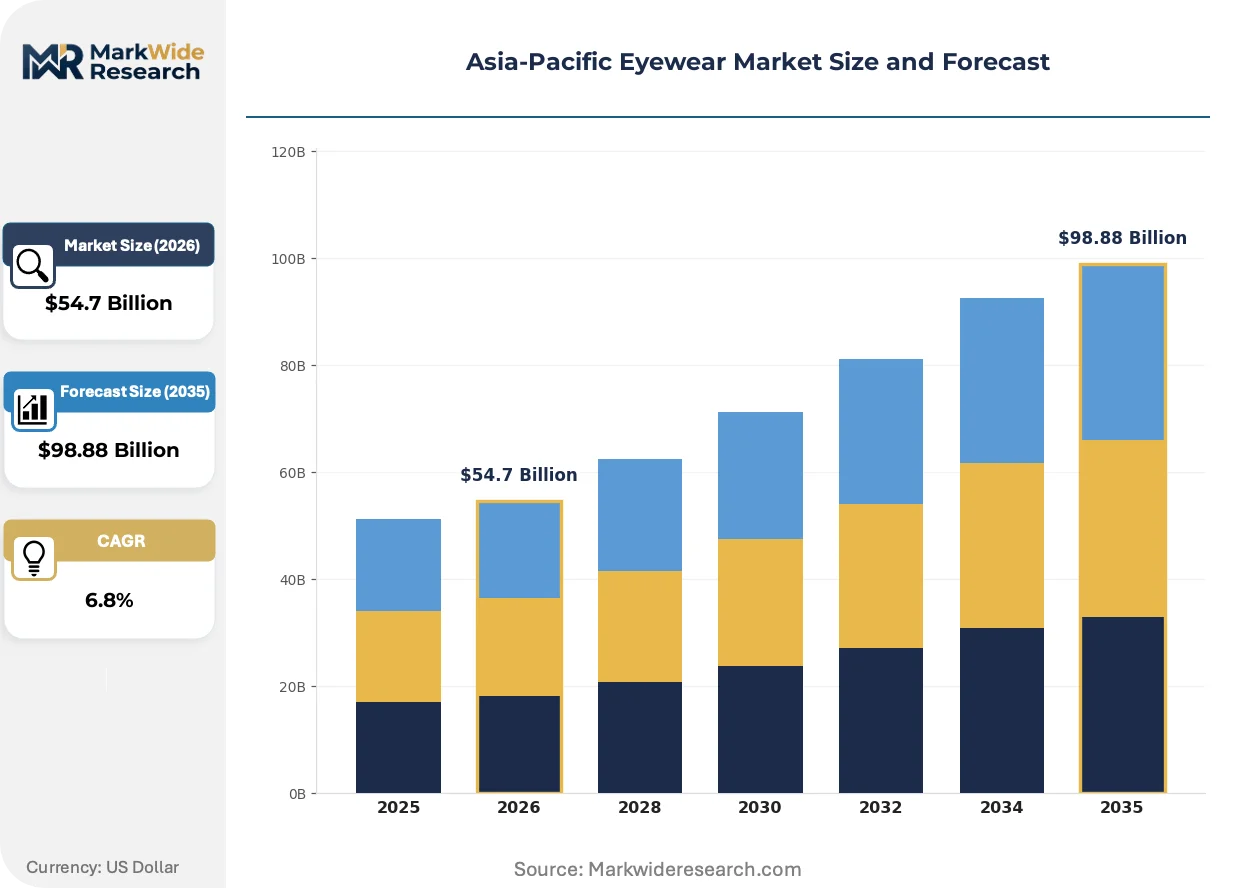
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $98.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Glasses, Sunglasses, Contact Lenses, Safety Glasses Material: Plastic, Metal, Glass, Nylon End User: Children, Adults, Seniors, Athletes Distribution Channel: Online Retail, Optical Stores, Supermarkets, Specialty Stores |
| Companies Covered | Seiko Optical Products, Lenskart, Essilor, SAFILO GROUP, Bolon, HOYA Corporation, PRADA, Reliance Retail, JINS Eyewear, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Eyewear Market Trends and Innovations
Digital health integration is dissolving boundaries between consumer electronics and regulated medical devices across Asia-Pacific eyewear value chains.
Free-form digital surfacing is absorbing conventional semi-finished lens grinding across progressive and high-astigmatism prescriptions. Urban optical chains in Japan and South Korea are adopting these systems at replacement-cycle pace. The technology is absorbing technician labor from downstream finishing labs into upstream digital design centers.
China's NMPA and SAMR are tightening contact lens distribution enforcement through licensed practitioner mandates. Unapproved import channels face escalating compliance penalties and customs scrutiny. Direct-to-consumer brands are responding by acquiring domestic optical retail licenses or partnering with hospital-affiliated chains.
Home-try-on logistics networks are compressing purchase cycles for prescription eyewear in India and South Korea. Young consumers now expect frame delivery within 48 hours of digital prescription upload. Specialty stores in Japan's mature market resist this shift by anchoring premium fitting margins through in-person optometric services.
Asia-Pacific Eyewear Market Segmentation
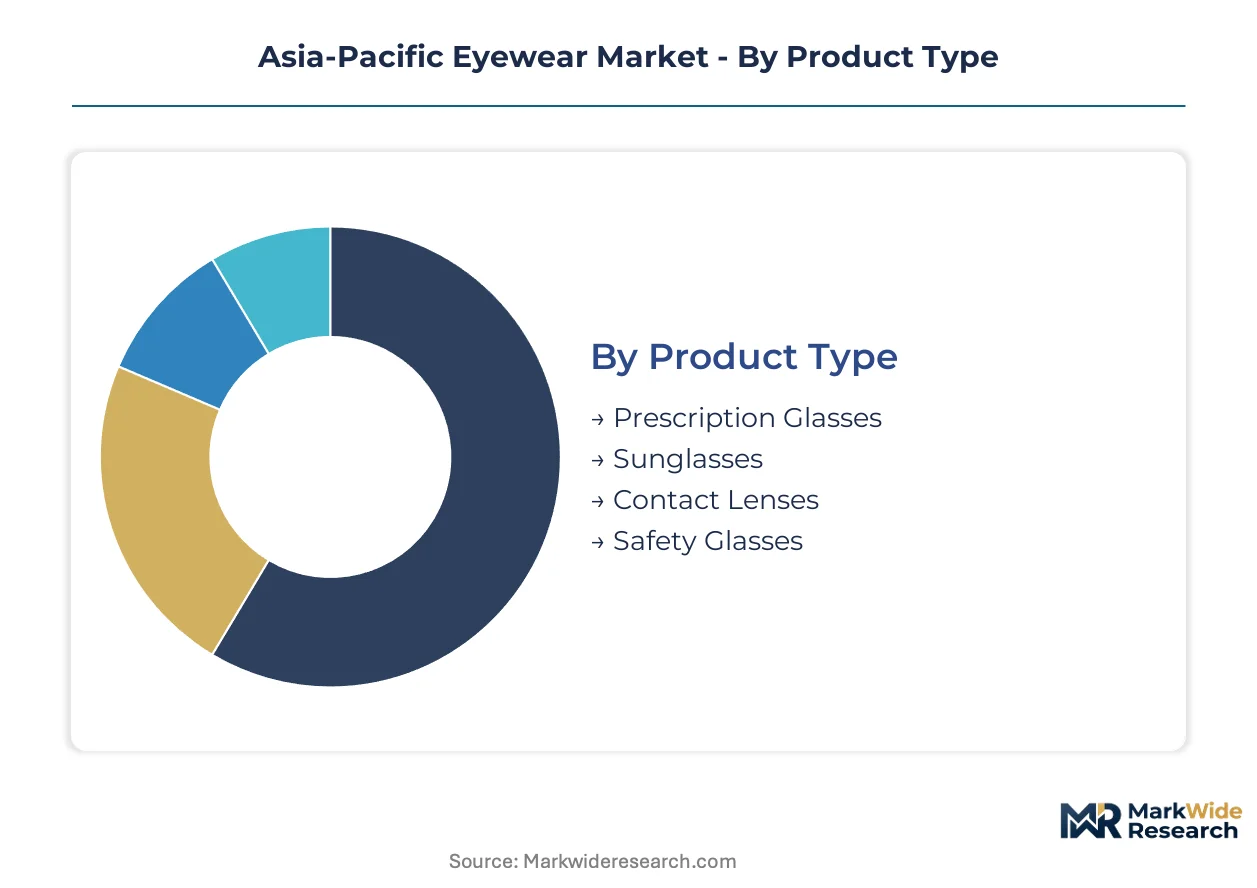
Asia-Pacific eyewear purchasing patterns diverge sharply across age cohorts and channel preferences, with prescription replacement cycles, aesthetic priorities, and occupational safety mandates creating distinct demand profiles that reward targeted portfolio positioning.
Product Type:
Purchase frequency and margin structure vary dramatically by vision-correction modality versus discretionary accessory use.
- Prescription Glasses:Fabricated through free-form surfacing of polycarbonate, high-index resin, or Trivex substrates to correct refractive errors. Recurring lens replacement among Japan's aging population and China's myopic youth sustains volume leadership across Jiangsu and Zhejiang manufacturing clusters.
- Contact Lenses:Silicone hydrogel and daily-disposable formats dominate, with South Korean and Indian consumers driving aesthetic adoption for cosmetic color variants. China's NMPA licensing restrictions force imported brands into hospital-affiliated retail partnerships, constraining direct-to-consumer expansion.
- Sunglasses:UV400-rated polycarbonate and glass lenses serve solar protection across Australia's high-UV environments and Southeast Asian tourism corridors.
- Safety Glasses:Impact-resistant polycarbonate frames meet occupational standards for manufacturing and construction sectors in Thailand and Vietnam.
Leading the category by volume: Prescription Glasses. Expanding most quickly: Contact Lenses.
Material:
Cost-positioning and durability requirements segment procurement decisions across premium titanium alloys versus mass-market acetate alternatives.
- Plastic:Cellulose acetate and injection-molded propionate dominate mid-market frame production with color versatility and moldability. Zhejiang processors face feedstock volatility from single-source petrochemical dependencies.
- Metal:Beta-titanium and stainless steel alloys enable thin, flexible temples for premium Japanese and South Korean optical chains. Higher material costs limit penetration in India's price-sensitive urban markets.
- Glass:Crown glass and photochromic substrates persist in high-clarity prescription segments despite weight penalties.
- Nylon:TR-90 and Grilamid polymers serve sports eyewear with flexibility and chemical resistance for Australian and Southeast Asian athletic applications.
Highest volume concentration: Plastic. Steepest premium trajectory: Metal.
End User:
Life-stage vision requirements and activity-specific performance demands create four distinct customer journeys through Asia-Pacific distribution channels.
- Adults:Knowledge workers in urban India and China propel blue-light filtering prescriptions as screen-time exposure intensifies across software and financial services sectors.
- Seniors:Progressive lens adoption accelerates with presbyopia onset, with Japanese consumers demanding precision-fitted multifocal corrections through in-person optometric services.
- Children:Myopia control lenses and orthokeratology fittings expand across South Korea and Taiwan as juvenile refractive error rates climb.
- Athletes:Prescription-compatible sports frames and photochromic cycling lenses gain traction in Australia's outdoor recreation market and Southeast Asian endurance sports communities.
Dominant revenue contributor: Adults. Gaining share fastest: Seniors.
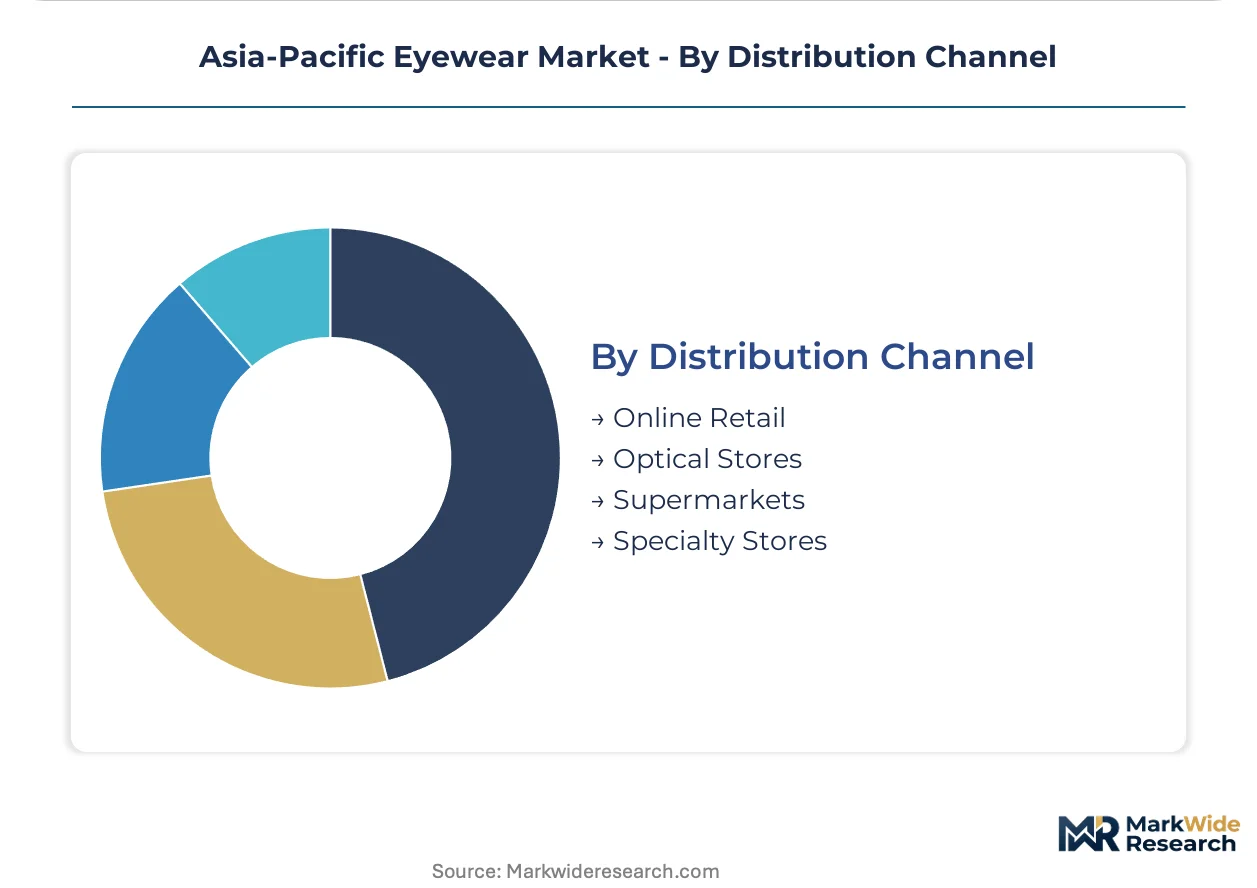
Distribution Channel:
Channel selection determines margin capture, with digital-native consumers accepting remote fitting while premium segments insist on in-person optometric validation.
- Optical Stores:Licensed practitioners in Japan and South Korea anchor progressive lens fitting and after-sales adjustment services, defending premium pricing against online encroachment.
- Online Retail:Home-try-on logistics and tele-optometry compress purchase cycles to 48-hour fulfillment for Indian and South Korean digital-native consumers.
- Specialty Stores:Curated designer frame collections and personalized styling consultations serve affluent segments in Singapore and Hong Kong.
- Supermarkets:Mass-market reading glasses and basic sunglasses drive impulse purchases across China's tier-two and tier-three cities.
Capturing the largest transaction volume: Optical Stores. Channel climbing fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cellulose acetate feedstock from Zhejiang province anchors Asia-Pacific frame production, while precision lens fabrication clusters concentrate in Jiangsu manufacturing corridors and Thai finishing networks.
China
Knowledge workers in Shanghai and Shenzhen propel blue-light filtering prescriptions as screen-time exposure intensifies across software and financial services sectors. NMPA and SAMR tighten contact lens distribution through licensed practitioner mandates, blocking direct-to-consumer channels for imported brands. Jiangsu and Zhejiang provinces host coastal manufacturing clusters where precision molding operations face METI-aligned energy-efficiency retooling pressures.
Japan
Presbyopic seniors in Tokyo and Osaka demand progressive lens precision through in-person optometric services, defending premium fitting margins against online encroachment. PMDA enforces medical-device classification and manufacturing quality standards for corrective lenses. Kanto and Kansai regions concentrate free-form surfacing adoption at replacement-cycle pace, absorbing technician labor into upstream digital design centers.
India
Young adults in urban centers drive home-try-on logistics adoption, expecting frame delivery within 48 hours of digital prescription upload. CDSCO and BIS mandate ISI marking on prescription lenses sold through domestic channels, extending product launch cycles by four to six months. Maharashtra and Karnataka attract resin processing and frame assembly investments under PLI scheme incentives, shifting capacity from traditional coastal export zones.
South Korea
Digital-native consumers displace traditional optical store traffic through virtual try-on platforms and tele-optometry services. MFDS regulates contact lens distribution with practitioner licensing requirements comparable to regional standards. Seoul Capital Area anchors online optical retail innovation, while Busan-Ulsan corridor maintains specialty store presence for premium progressive fittings.
Thailand
Southeast Asian optical chains benefit from captive lens-finishing networks that reduce import dependency and shorten fulfillment cycles. National pharmaceutical regulator enforces medical-device standards for corrective lens imports. Bangkok metropolitan area and Eastern Economic Corridor concentrate Essilor-affiliated finishing operations serving regional distribution.
Asia-Pacific Eyewear Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers respond to energy-efficiency mandates and feedstock volatility. The vendor base organizes around three strategic archetypes: integrated optical chains controlling home-try-on logistics, captive lens-finishing networks preserving margin control, and premium progressive specialists anchoring multifocal output. M&A activity and geographic licensing partnerships represent the dominant competitive moves, particularly as direct-to-consumer brands acquire domestic optical retail licenses to circumvent distribution restrictions.
Among Japanese fabricators, Seiko Optical Products and JINS Eyewear exemplify precision-manufacturing archetypes with domestic market anchoring. HOYA Corporation occupies a position within the premium progressive lens tier, while Lenskart represents the vertically integrated logistics model compressing purchase cycles in South Asian markets. Essilor and SAFILO GROUP sit within the multinational network archetype, leveraging regional finishing infrastructure across Southeast Asian supply corridors.
| Leading Market Players |
|---|
| Seiko Optical Products |
| Lenskart |
| Essilor |
| SAFILO GROUP |
| Bolon |
| HOYA Corporation |
| PRADA |
| Reliance Retail |
| JINS Eyewear |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ISI-marked domestic lenses and unmarked import alternatives bifurcates procurement economics across Indian distribution channels while compressing margin structures for regional distributors facing four-to-six-month compliance timelines. This tiered quality architecture simultaneously shapes supplier selection in Jiangsu and Zhejiang manufacturing clusters, where energy-efficiency retooling costs propagate differentially across premium progressive and commodity single-vision output.
Pricing Analysis
Warranty-bundled after-sales service separates Japanese optical chains commanding premium fitting margins from unbundled online competitors in South Korea and India. Three-tier pricing structure across premium, standard, and economy levels reflects free-form surfacing capability, brand heritage, and practitioner certification tier. Cost compression in mid-market acetate frames intensifies because Zhejiang feedstock volatility transmits directly through single-source petrochemical dependencies. Price-sensitive buyers concentrate in India's tier-two cities, while least-sensitive segments occupy Tokyo's presbyopic progressive lens market.
Supply Chain Analysis
Cellulose acetate feedstock rests on Zhejiang province petrochemical processors, polycarbonate lens blanks draw from Thai finishing networks, and titanium alloy temples hinge on Japanese precision metalworking. Raw material dependencies span bisphenol-A for impact-resistant lenses, silicone hydrogel polymers for daily disposables, and Grilamid polymers for sports applications. Single-source vulnerability in cellulose acetate supply creates force majeure exposure for mid-market frame assemblers. Distribution runs through licensed optical practitioners in Japan and China, direct-to-consumer logistics in India and South Korea, and hospital-affiliated chains for contact lens fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Free-form surfacing technician scarcity across Philippine and Thai manufacturing hubs constrains precision lens output, propping pricing for qualified fabrication capacity and creating supply-constrained conditions for progressive lens fulfillment.
For Market Incumbents: Anchor progressive lens margins through captive finishing network expansion in Thailand and the Philippines, defending against home-try-on logistics specialists compressing purchase cycles in South Asian markets. Certification investment in India's ISI marking process preserves channel access against four-to-six-month launch delays threatening import-dependent competitors. Backward integration into resin processing under Maharashtra and Karnataka PLI incentives reduces Zhejiang feedstock exposure. For New Entrants and Emerging Players: China's NMPA licensing requirements for contact lens distribution open a window for hospital-affiliated retail partnerships, bypassing direct-to-consumer restrictions blocking unapproved import channels. Target South Korea's virtual try-on platform segment as the most penetrable geography, where tele-optometry acceptance among digital-native consumers outpaces regulatory adaptation. Acquire domestic optical retail licenses as the essential go-to-market angle for contact lens market entry. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated logistics operators given home-try-on fulfillment compression driving 48-hour delivery expectations across Indian urban markets. Long-term viability favors archetypes controlling both digital prescription upload platforms and captive lens-finishing infrastructure. Watch free-form surfacing technician training output in Southeast Asian manufacturing hubs as the signal indicating capacity constraint resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Lens-Finishing Network Expansion | Essilor's Thai operations demonstrate margin preservation against import-dependent Southeast Asian optical chains. |
| Domestic Optical Retail License Acquisition | Direct-to-consumer brands circumvent China's NMPA practitioner mandates through hospital-affiliated chain partnerships. |
| Free-Form Surfacing Technician Training Programs | Philippine and Thai vocational output gaps constrain precision progressive lens fabrication capacity expansion. |
| Home-Try-On Logistics Infrastructure Buildout | Lenskart's vertically integrated fulfillment compresses Indian purchase cycles to 48-hour frame delivery benchmarks. |
| Resin Processing Investment Under PLI Incentives | Maharashtra and Karnataka attract acetate and polycarbonate capacity shifting from traditional coastal export zones. |
Research Methodology
Multi-period observation of prescription replacement cycles, blue-light filtering adoption rates, and contact lens licensing enforcement anchored the trend analysis, supplemented by interviews with optical chain procurement directors, lens fabrication plant managers, regulatory affairs specialists at NMPA and CDSCO, and tele-optometry platform engineers. Secondary validation drew from customs trade databases, BIS certification registries, SEC filings of listed eyewear manufacturers, and hospital procurement contract disclosures. Bottom-up demand modeling across age cohorts and vision-correction modalities triangulated against top-down manufacturing capacity assessments.
Segment-weighting approaches distributed value estimates across prescription glasses, contact lenses, sunglasses, and safety eyewear by material substrate, distribution channel, and end-user life stage. CAGRs were derived from fitted growth curves across the analysis window, incorporating myopia progression epidemiology, presbyopia demographic shifts, and screen-time exposure intensification in knowledge-work sectors. Industry-specific inputs included free-form surfacing equipment installation rates, PLI scheme uptake in Indian states, and METI energy-efficiency compliance timelines.
Caveats apply where NMPA enforcement intensity, acetate feedstock volatility, or smart glasses medical-device reclassification could materially shift the outlook. Forecasts incorporate assumptions regarding licensed practitioner availability, vocational training output pacing, and cross-border e-commerce regulatory tolerance. A small set of named triggers—technician scarcity resolution, ISI marking timeline compression, and augmented-reality eyewear classification clarity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Latin America Eyewear Market
Eyewear
Eyewear Market
Eyewear
Europe Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Blue Light Glasses Market
Eyewear
Goggles Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Spectacles Market
Eyewear
Sunglasses Pouch Market
Eyewear
Eyeglass Market
Eyewear
North America Eyewear Market
Eyewear
Face and Ear Bow Market
Eyewear
Plano Sunglasses Market
Eyewear
Wooden Eyewear Market