
 Global Sailing Dinghy Masts Market | 2026-2036
Global Sailing Dinghy Masts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sailing Dinghy Masts Market Foresight
Aftermarket service revenue is tilting toward mast inspection, repair, and recertification as fleet owners extend asset life. Selden Mast AB leverages its Nordic service network to capture recurring revenue from yacht clubs. Z Spars International Ltd. anchors its position through backward integration into extrusion and CNC machining of aluminum sections. Pauger Carbon Composites specializes in autoclave-cured carbon fiber rigs for Olympic-class dinghies.
A sailing dinghy mast is a vertical spar that supports sails and rigging, typically fabricated from aluminum extrusions, carbon fiber prepregs, or hybrid composites with wall thicknesses calibrated to bending moment profiles along the length. Its primary purpose is to translate aerodynamic force into hull propulsion while maintaining controlled flex characteristics for sail shape optimization. Carbon fiber racing masts command premium positioning due to stiffness-to-weight ratios that aluminum cannot match, whereas training masts in fiberglass and wood retain stable volume from sailing schools. Composite material development now occupies the fastest-growing segment as builders layer dissimilar fibers to tune bend and twist behavior.
ISO 12217 small-craft stability standards, EU REACH chemical restrictions on resin systems, and US Coast Guard recreational boat safety regulations collectively elevate compliance costs for mast builders seeking multi-territory sales. REACH in particular forces reformulation of epoxy matrices and gelcoat finishes, redirecting R&D budgets toward bio-derived thermoset alternatives. Stakeholders must monitor evolving class-rule amendments from World Sailing and national federations that can overnight obsolete existing mast profiles.
Market Dynamics
Carbon fiber prepreg technology is compressing the performance gap between recreational and racing-grade masts, forcing aluminum extruders to defend volume in the training segment while composite specialists capture margin in competitive fleets.
Growth Catalysts
- EU REACH compliance mandates:Chemical restrictions on styrene-based resins are accelerating bio-epoxy formulation adoption among European mast builders, creating first-mover certification advantages for compliant suppliers.
- Lake Garda sailing cluster concentration:Italy's dense racing fleet infrastructure generates concentrated demand for Olympic-class carbon fiber rigs, supporting specialized autoclave curing operations at local facilities.
- Prepreg automation:Automated fiber placement systems are reducing labor content in carbon mast production, enabling cost structures that penetrate club racing segments previously served by aluminum.
Market Restraints
- Toray carbon fiber supply concentration:Japanese and Korean precursor manufacturers control high-modulus fiber supply, exposing mast builders to allocation risk during aerospace demand surges.
- Aluminum billet price volatility:LME aluminum price swings directly compress margin on training mast production lines where composite substitution remains uneconomical.
- Class rule rigidity:World Sailing equipment regulations freeze mast section dimensions for Olympic classes, preventing geometric innovation that could differentiate incumbent suppliers.
Strategic Opportunities
- Australian coastal sailing expansion:TGA-aligned recreational boat safety standards and expanding youth academy networks in Sydney and Melbourne create import substitution potential for regional mast fabrication.
- Digital twin rig tuning:Convergence of strain-gauge instrumentation and cloud-based bend characterization software enables remote mast optimization services for distance racing programs.
- US Inflation Reduction Act clean manufacturing credits:Domestic production incentives for composite components support reshoring of mast fabrication serving North American one-design fleets.
Industry Challenges
- Autoclave operator scarcity:Specialized thermoset curing technicians are concentrated in aerospace supply chains, constraining capacity expansion for premium carbon mast production.
- Multi-territory certification timelines:Simultaneous ISO 12217, US Coast Guard, and CE marking approvals extend product launch cycles by eight to fourteen months for new mast profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sailing Dinghy Masts Market |
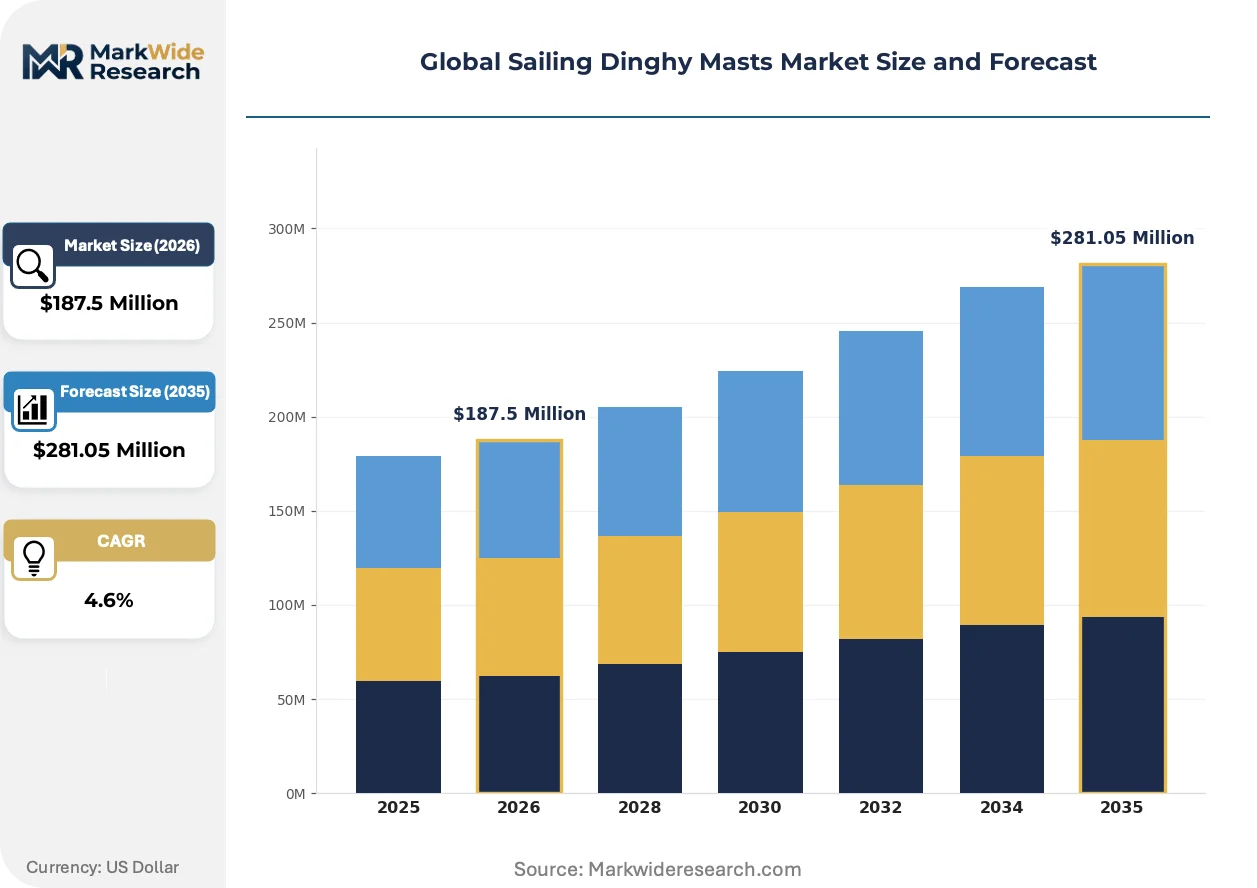
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $281.05 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Carbon Fiber, Wood, Fiberglass, Composite Product Type: Standard Mast, Racing Mast, Telescopic Mast, Adjustable Mast, Training Mast Application: Recreational Sailing, Competitive Racing, Training & Education, Charter Services, Event Hosting End User: Private Owners, Sailing Schools, Yacht Clubs, Rental Operators, Boat Builders |
| Companies Covered | Selden Mast AB, Z Spars International Ltd., AG Plus SPARS, Allspars Ltd., Chinook Sailing Products, Pauger Carbon Composites, Heol Composites, New Zealand Rigging Ltd., Pinnell and Bax Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sailing Dinghy Masts Market Shifts & Advancements
Material science advances and regulatory chemistry mandates are restructuring competitive advantage away from pure manufacturing scale toward formulation IP and inspection service integration.
Modular carbon fiber mast sections with tunable bend characteristics are rendering obsolete fixed-geometry aluminum extrusions in high-performance dinghy classes. Olympic development squads and national sailing federations are adopting these systems for rapid rig tuning across varying wind conditions. The technology is compressing replacement cycles as clubs upgrade from legacy aluminum inventories to configurable composite platforms.
REACH Annex XVII restrictions on bisphenol-A in marine coatings are forcing reformulation of mast finishing systems throughout European supply chains. German and French builders are redirecting R&D expenditure toward bio-derived gelcoat alternatives certified by ECHA. Racing segment suppliers face accelerated compliance timelines as class associations prioritize environmental credentials in equipment selection criteria.
Aftermarket inspection and recertification services are unbundling from original equipment sales as fleet owners extend asset life through non-destructive testing protocols. Yacht clubs in the Netherlands and Denmark are contracting specialized technicians for annual mast certification rather than purchasing replacement spars. Nordic sailing infrastructure exhibits the most advanced adoption of condition-based maintenance contracts for carbon fiber rigging.
Global Sailing Dinghy Masts Market Segmentation
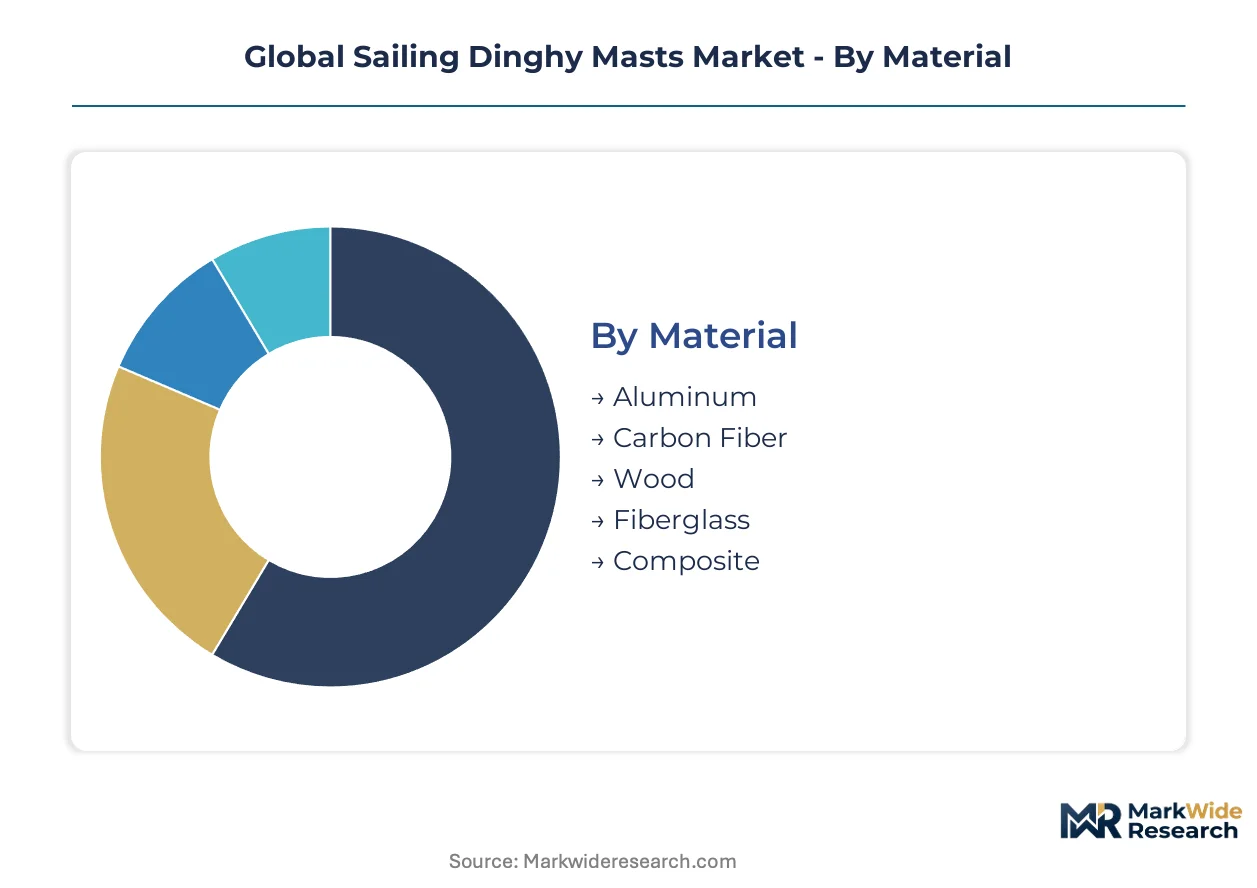
Segmentation in sailing dinghy masts reveals how performance requirements, cost thresholds, and regulatory compliance reshape procurement patterns across fleet types. Material selection and product configuration directly determine competitive positioning for builders serving distinct sailing communities.
Material:
Use-case spectrum spans Olympic medal campaigns to municipal sailing programs, with material choice locking in performance ceiling and replacement cycle economics.
- Carbon Fiber:Autoclave-cured prepregs deliver unmatched stiffness-to-weight ratios for bend-tuned racing rigs. Demand concentrates at Italy's Lake Garda cluster and Sydney's Olympic development squads, where World Sailing class rules permit geometric optimization.
- Aluminum:Extruded 6061-T6 and 7075-T6 sections dominate training fleets through impact tolerance and field repairability. Sailing schools in the Netherlands and Denmark specify aluminum for cost-controlled fleet standardization amid volatile LME pricing.
- Wood:Traditional spruce and Douglas fir spars persist in classic dinghy restoration and heritage regatta circuits.
- Fiberglass:E-glass and S-glass layups serve entry-level recreational sailors seeking durability over performance tuning.
- Composite:Hybrid fiber layering combines carbon modulus with fiberglass toughness for club racing price points.
The dominant share belongs to aluminum, while carbon fiber is closing the gap fastest through automated prepreg placement cost reduction.
Product Type:
Cost tier stratification separates premium racing technology from volume training equipment, with adjustable geometries capturing margin in between.
- Racing Mast:Bend-characterized carbon sections with calibrated wall thickness profiles optimize sail shape across wind bands. National federations in Australia and the United States procure these for Olympic pathway programs.
- Standard Mast:Fixed-geometry aluminum extrusions serve one-design class fleets where class rules prohibit equipment variation. Yacht clubs in Germany standardize on these for fleet parity.
- Telescopic Mast:Nested aluminum or composite sections enable transportable rigs for trailer-sailer dinghy classes.
- Adjustable Mast:Rake and bend-tuning systems allow rapid reconfiguration between light and heavy air conditions.
- Training Mast:Reinforced wall sections and simplified rigging attachment points withstand repeated groundings and student errors.
Racing mast revenue leads product type value capture, though adjustable configurations are expanding most quickly through club fleet upgrade cycles.
Application:
Customer maturity and performance requirements segment demand from casual weekend sailing to medal-grade athletic preparation.
- Competitive Racing:Olympic-class and national championship campaigns require ISO 12217 stability compliance and REACH-certified resin systems. Fleet owners in Italy and France prioritize autoclave-cured rigs with ECHA-compliant gelcoats.
- Training & Education:Sailing academies specify standardized aluminum spars with extended service intervals. Municipal programs in Melbourne and Copenhagen favor replaceable sections over repairable composites.
- Recreational Sailing:Weekend sailors select fiberglass or hybrid masts for durability in uncontrolled storage conditions.
- Charter Services:Rental operators demand rapid rigging and derigging protocols for high-turnover beach operations.
- Event Hosting:Temporary regatta infrastructure requires modular mast systems for rapid fleet assembly.
Competitive racing commands premium positioning, while training and education applications deliver steadiest replacement volume.
End User:
Procurement authority and fleet scale differentiate individual owners from institutional buyers with structured maintenance protocols.
- Sailing Schools:Structured curriculum programs in the United States, Australia, and the Netherlands operate standardized fleets with scheduled replacement cycles. These institutions negotiate volume contracts for aluminum training masts.
- Yacht Clubs:Racing committees balance one-design parity requirements against member demands for performance equipment. Clubs on Lake Garda and Sydney Harbour lead carbon fiber adoption.
- Private Owners:Individual racers and cruisers select masts based on class association rules and personal performance priorities.
- Rental Operators:Beach concession businesses prioritize rapid repair and minimal downtime over weight optimization.
- Boat Builders:OEM mast specification locks in supplier relationships for production dinghy lines.
Sailing schools anchor volume demand, yet yacht clubs are gaining procurement sophistication fastest through condition-based maintenance contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian autoclave-curing operations and Nordic service networks concentrate high-value mast fabrication, while Australian and North American markets expand import substitution capacity. REACH compliance costs and TGA-aligned safety standards reshape territorial procurement patterns. Fleet density at specific sailing clusters drives localized demand spikes for carbon fiber and aluminum spars.
Italy
Lake Garda's dense Olympic-class racing infrastructure generates concentrated demand for autoclave-cured carbon fiber rigs. ECHA REACH Annex XVII restrictions on bisphenol-A gelcoats force reformulation timelines at Lombardy-based facilities. The Garda sailing cluster supports specialized curing operations serving national federation development squads.
United States
US Coast Guard recreational boat safety regulations and expanding youth academy networks in Florida and California drive fleet standardization. The Inflation Reduction Act's clean manufacturing credits support domestic composite component reshoring. One-design fleets in Newport and Annapolis anchor procurement volume for aluminum training masts.
Australia
TGA-aligned recreational boat safety standards and Sydney's Olympic development pathways create import substitution potential. Melbourne's municipal sailing programs specify replaceable aluminum sections over repairable composites. The national youth academy network standardizes fleet procurement across New South Wales and Victoria.
Netherlands
Sailing schools in Amsterdam and Rotterdam operate standardized aluminum fleets with scheduled replacement cycles. Condition-based maintenance contracts for carbon fiber rigging exhibit advanced adoption at Dutch yacht clubs. Municipal programs negotiate volume contracts prioritizing extended service intervals over performance optimization.
Denmark
Copenhagen's sailing infrastructure leads Nordic adoption of mast inspection and recertification services. Yacht clubs contract specialized technicians for annual carbon fiber certification rather than replacement purchases. The Danish sailing federation's maintenance protocols extend asset life across municipal training programs.
Global Sailing Dinghy Masts Market Competitive Landscape
Integrated composite specialists and aluminum extrusion houses split the market between premium racing rigs and volume training equipment. Consolidation pressure intensifies as automated prepreg placement compresses cost structures into club racing segments. Three archetypes dominate: autoclave-cured carbon fiber specialists, backward-integrated aluminum extruders, and Nordic-centric service network operators. Capacity expansion and geographic licensing agreements represent the dominant competitive moves as builders seek REACH compliance advantages and regional certification footholds.
Among Nordic-based fabricators, Selden Mast AB anchors the service-network archetype through its regional maintenance infrastructure. Z Spars International Ltd. exemplifies backward-integrated aluminum production with captive extrusion and CNC machining capabilities. Pauger Carbon Composites occupies the autoclave-specialist tier, serving Olympic-class demand from European racing clusters. These three entities represent distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Selden Mast AB |
| Z Spars International Ltd. |
| AG Plus SPARS |
| Allspars Ltd. |
| Chinook Sailing Products |
| Pauger Carbon Composites |
| Heol Composites |
| New Zealand Rigging Ltd. |
| Pinnell and Bax Ltd. |
| Others |
Supply & Pricing Matrix
Lombardy's autoclave-curing cluster concentrates capacity for carbon fiber racing masts, translating aerospace-grade composite expertise into premium pricing power over club racing segments. REACH compliance costs at Italian facilities propagate downstream through tiered pricing structures that separate Olympic-class rigs from training equipment.
Pricing Analysis
Aftermarket inspection and recertification services now drive lifetime value capture as fleet owners extend asset life through condition-based maintenance contracts. Three-tier pricing structure across premium racing, standard club, and economy training levels reflects certification grade and geometric customization depth. Pricing pressure stems from automated prepreg placement compressing cost structures into segments previously served by aluminum. Sailing schools exhibit highest price sensitivity due to municipal budget constraints, while Olympic development squads prioritize performance over cost.
Supply Chain Analysis
Supplier-financing facilities from Japanese precursor manufacturers stabilize fiber allocation for European mast builders during aerospace demand surges. High-modulus carbon fiber supply concentrates in Japan and South Korea, while aluminum billet sourcing draws from Norwegian and Russian smelters. Epoxy resin systems hinge on German and Dutch chemical suppliers navigating REACH reformulation mandates. Single-source vulnerability runs through Toray's high-modulus fiber allocation. Distribution runs through yacht club procurement committees and national federation tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated prepreg placement technology is accelerating composite adoption into club racing segments previously price-locked to aluminum, expanding addressable market penetration for carbon fiber specialists.
For Market Incumbents: Harden autoclave-curing capacity in Lombardy against emerging automated fiber placement competitors by securing REACH-compliant resin formulation IP. Anchor position through backward integration into carbon fiber precursor supply agreements with Japanese suppliers. Defend margin structure by bundling inspection and recertification services that lock fleet owners into multi-year maintenance contracts. For New Entrants and Emerging Players: Pursue Australian coastal sailing expansion where TGA-aligned safety standards and youth academy network growth create import substitution openings. Target municipal sailing programs in Melbourne and Sydney seeking replaceable aluminum sections over repairable composites. Enter through OEM partnerships with regional boat builders lacking captive mast fabrication. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automated prepreg placement is compressing viable independent fabricator count to integrated specialists with formulation IP and service network density. Acquisition targets should combine autoclave capacity with established yacht club maintenance contracts. Watch REACH Annex XVII amendment timelines as inflection signals for bio-derived gelcoat certification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Investment | ECHA-certified bio-epoxy systems secure first-mover certification advantages in European racing segments. |
| Automated Fiber Placement Scale-Up | Reduced labor content enables carbon fiber cost structures to penetrate club racing previously served by aluminum. |
| Condition-Based Maintenance Contracting | Annual mast certification services at Dutch and Danish yacht clubs extend asset life and lock recurring revenue. |
| Australian Manufacturing Footprint | TGA-aligned production serving Sydney and Melbourne youth academies reduces import dependency and logistics exposure. |
| Backward Integration into Precursor Supply | Direct relationships with Toray and Korean fiber suppliers mitigate allocation risk during aerospace demand surges. |
Research Methodology
A standing panel of mast fabrication plant managers, yacht club fleet procurement officers, national sailing federation technical directors, and composite materials R&D leads provided ongoing calibration across primary interview cycles. Secondary validation drew from World Sailing equipment regulations, ECHA REACH substance databases, ISO 12217 small-craft stability standards, and customs trade data for carbon fiber prepregs. Bottom-up triangulation across builder capacity and fleet replacement cycles converged with top-down expenditure analysis from national academy budgets.
Scenario-bracketing framed volume projections across material, product type, application, and end-user segmentation dimensions. CAGRs derived from replacement cycle modeling for aluminum training fleets and upgrade penetration rates for carbon fiber racing rigs. Industry-specific inputs included LME aluminum price volatility assumptions and REACH compliance cost trajectories for epoxy matrix reformulation.
Macroeconomic conditions sit as an overlay; deviation in marine leisure discretionary spending or aerospace carbon fiber demand absorption would shift the trajectory. Forecasts reflect documented assumptions on class rule stability and automation adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Global Slingshot Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Mexico Fishing Reels Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Swimming Pool and Spa Market
Outdoor & Sports
Skateboard Ramp Market
Outdoor & Sports
Golf Stand Bag Market