
 Middle East Eyewear Market | 2026-2036
Middle East Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Eyewear Market Outlook
Buyer concentration across the Middle East Eyewear Market is decoupling from legacy family-owned optical chains toward digitally native consumers and hospital-affiliated vision centers. EssilorLuxottica leverages its integrated lens-manufacturing and retail footprint to dominate premium distribution across Saudi Arabia and the UAE. Magrabi-Rivoli Enterprise anchors its position through deep vertical control of eye-care clinics, optical retail, and wholesale import channels. Lenskart competes aggressively on price-transparent online refraction and home trial services, extending its India-born model into Gulf urban centers.
Eyewear comprises vision-correction and eye-protection devices constructed from engineered plastics, mineral glass, or impact-resistant polycarbonate, with frame geometries precision-milled to individual pupillary distance and diopter specifications. The primary commercial purpose spans refractive error correction, ultraviolet blocking, occupational hazard shielding, and aesthetic identity expression. Sunglasses and prescription glasses together occupy the largest value share, though contact lenses command higher per-user lifetime margins due to recurring replacement schedules. Online retail is accelerating fastest among distribution channels, while optical stores retain the dominant share of complex prescription fulfillment where fitting accuracy determines outcomes.
Saudi Food and Drug Authority registration protocols, UAE Ministry of Health and Prevention product standards, and Gulf Standardization Organization conformity marks collectively govern import access and clinical claims across the region. These frameworks elevate compliance costs for new entrants but protect incumbent suppliers with established certification infrastructure. Stakeholders must monitor evolving telehealth refraction permissions and e-commerce licensing rules, as regulatory clarity on remote prescription issuance will reshape channel economics and customer acquisition strategies.
Market Dynamics
Young adult demand for fashion-forward prescription frames is decoupling from traditional clinical purchasing patterns across Gulf Cooperation Council markets, forcing suppliers to bifurcate their distribution strategies between medical-grade fulfillment and style-driven retail experiences.
Growth Catalysts
- SFDA Registration Harmonization:Saudi Food and Drug Authority's tightened contact lens registration requirements, while raising barriers, are consolidating compliant suppliers and accelerating professional channel upgrade investments.
- Dubai Retail Corridor Concentration:Mall-based optical boutiques and e-commerce fulfillment centers co-locating in Dubai capture both tourist and resident spending, creating density economies for inventory and logistics.
- Polycarbonate Lens Adoption:Impact-resistant polycarbonate materials displace mineral glass in active-lifestyle segments, reducing breakage returns and expanding pediatric and sports prescription markets.
Market Restraints
- Import Compliance Burden:Gulf Standardization Organization conformity marks and MOHAP product standards elevate fixed costs for international suppliers without regional certification infrastructure.
- Input Cost Volatility:Engineered plastics and specialized coatings face petrochemical feedstock price swings that compress margin stability for mid-tier frame manufacturers.
- Clinical Channel Concentration:Hospital-affiliated vision centers and established optical chains control complex prescription fulfillment, limiting direct-to-consumer penetration for pure-play online entrants.
Strategic Opportunities
- Telehealth Refraction Expansion:Regulatory clarity on remote prescription issuance in Saudi Arabia and UAE would unlock customer acquisition cost advantages for digitally native platforms.
- Home Trial Services:Price-transparent online refraction combined with frame home-trial logistics, proven in Gulf urban centers, addresses fit-risk aversion among first-time online buyers.
- Tourist Duty-Free Capture:Dubai International Airport and Abu Dhabi duty-free zones represent underexploited high-margin sunglasses volume for premium brand portfolios.
Industry Challenges
- Optometrist Talent Scarcity:Licensed refraction professionals remain concentrated in Riyadh, Jeddah, and Dubai, constraining clinic expansion into secondary Saudi and UAE cities.
- Multi-Channel Inventory Synchronization:Optical retailers must reconcile real-time stock visibility across mall boutiques, e-commerce warehouses, and clinic dispensaries without fragmenting customer experience.
- Certification Timeline Compression:SFDA and MOHAP approval cycles for new contact lens formulations delay product launches by 12-18 months against competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Eyewear Market |
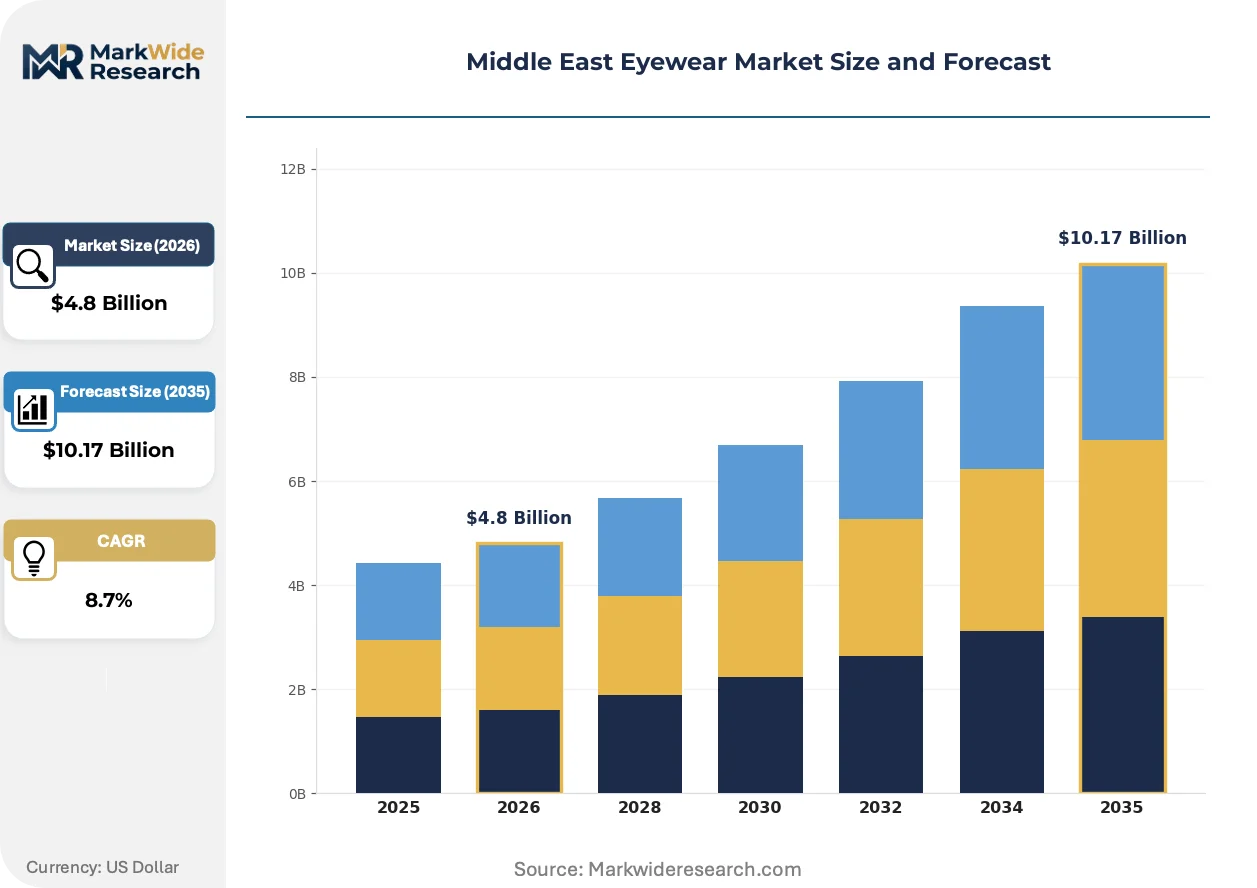
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glasses, Sunglasses, Contact Lenses, Safety Eyewear Material: Plastic, Glass, Polycarbonate, Acrylic Use Case: Vision Correction, Fashion Accessory, Sports Performance, Occupational Safety Distribution Channel: Online Retail, Optical Stores, Department Stores, Pharmacies |
| Companies Covered | Eyewa, EssilorLuxottica, Magrabi-Rivoli Enterprise, Bausch Health Companies, Safilo Group, Yateem Optician, Lenskart, Zeiss Group, Al Jaber Optical, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Eyewear Market Strategic Shifts
Digital refraction technologies and AI-powered frame recommendation engines are compressing the traditional optical purchase journey from clinical consultation to self-directed online configuration.
Blue-light-filtering lens coatings with embedded photochromic activation are electrifying workplace eyewear segments across UAE and Saudi corporate campuses. Young professionals in finance and technology sectors adopt these dual-function lenses at triple the rate of conventional single-vision prescriptions. The technology is electrifying mid-tier price positioning by collapsing the separate sunglasses purchase into a single transaction.
MOHAP's expanded product standards for decorative contact lenses, including cosmetic and colored varieties, are redirecting import flows through formal medical device channels rather than informal retail. The regulation eliminates unregistered Asian suppliers from UAE shelves while creating compliance advantages for established pharmaceutical distributors. Beauty-focused consumers now encounter these products primarily through licensed optometry clinics rather than cosmetic retailers.
Subscription replacement models for daily disposable contact lenses are displacing episodic bulk purchasing among Saudi millennials and Gen Z consumers. E-commerce platforms capture recurring revenue streams that optical stores struggle to replicate without inventory management system upgrades. This behavioral shift concentrates most visibly in Riyadh and Jeddah, where delivery infrastructure and digital payment penetration support automated replenishment cycles.
Middle East Eyewear Market Segmentation
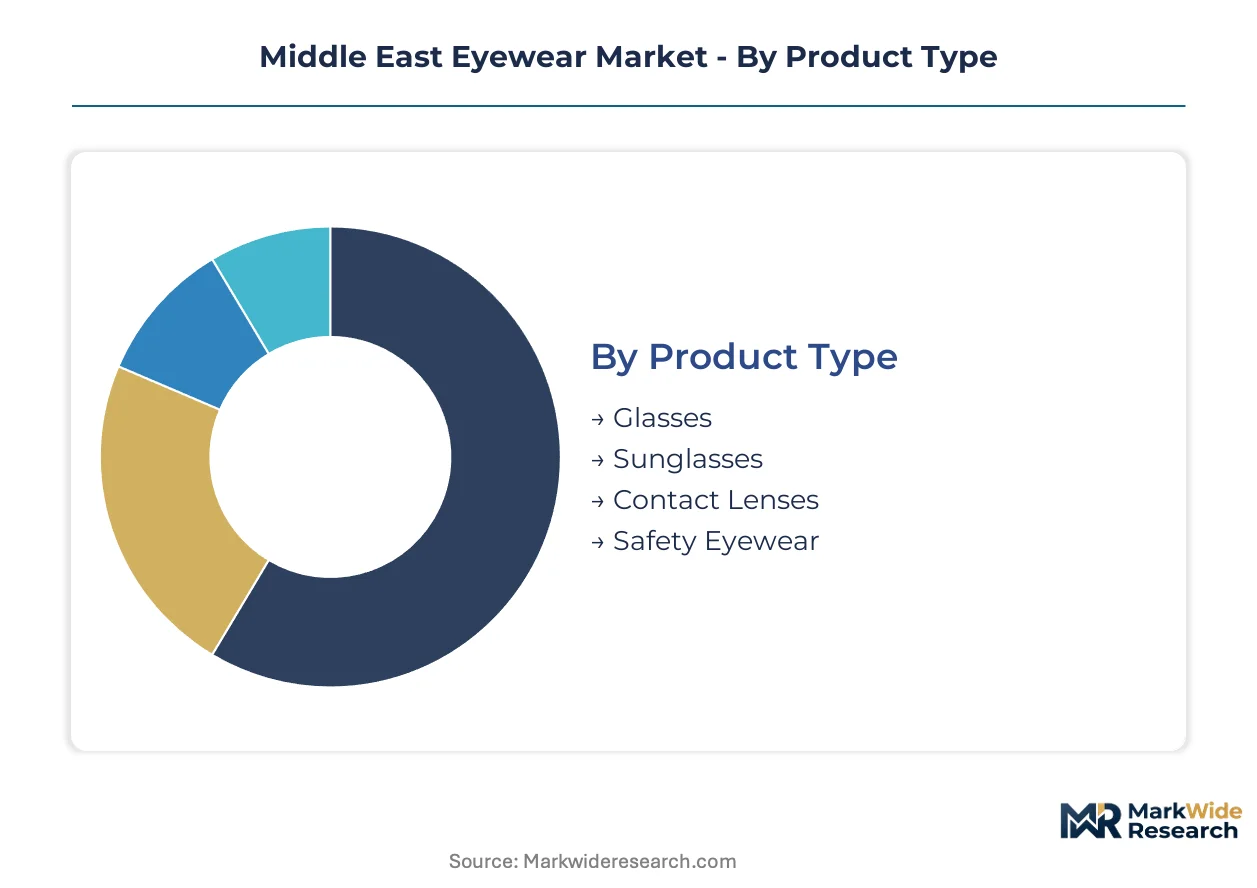
Supplier positioning across the Middle East Eyewear Market fragments sharply across product and channel dimensions, with margin structures and certification requirements varying dramatically by segment. Understanding these fault lines enables targeted resource allocation between high-touch clinical fulfillment and scalable digital distribution.
Product Type:
Supply concentration in lens manufacturing tilts heavily toward integrated producers with captive prescription laboratory networks across Saudi Arabia and the UAE.
- Glasses:Precision-milled frames engineered to individual pupillary distance specifications dominate prescription fulfillment in hospital-affiliated vision centers. Demand clusters in Dubai's mall corridor where optical boutiques co-locate with e-commerce fulfillment centers to capture resident and tourist spending simultaneously.
- Sunglasses:UV-blocking lenses with polarized and photochromic coatings command premium positioning in duty-free zones at Dubai International Airport and Abu Dhabi terminals. The segment attracts fashion-forward young adults decoupling from traditional clinical purchasing patterns across Gulf Cooperation Council markets.
- Contact Lenses:Daily disposable silicone hydrogel formulations face tightened SFDA registration requirements that reshape import compliance burdens for international suppliers.
- Safety Eyewear:Impact-resistant polycarbonate occupational shields serve construction and petrochemical sectors under Gulf Standardization Organization conformity protocols.
Today's leader: Glasses. Tomorrow's challenger: Contact Lenses.
Material:
Cost tier differentiation separates premium mineral substrates from mass-market engineered polymers, with polycarbonate displacing legacy materials fastest in pediatric and sports applications.
- Polycarbonate:Impact-resistant thermoplastic with inherent UV blocking properties reduces breakage returns and expands active-lifestyle prescription markets. Demand concentrates in Riyadh and Jeddah where sports participation rates among young professionals drive replacement cycles.
- Plastic:Cellulose acetate and injection-molded propionate enable fashion-forward frame geometries at accessible price points. The material anchors mid-tier positioning across Saudi Arabia's growing optical retail chains.
- Glass:Mineral crown glass with superior optical clarity retains niche positioning in high-prescription applications despite weight penalties.
- Acrylic:Lightweight PMMA substrates serve decorative and entry-level sunglass segments with limited durability expectations.
Polycarbonate is gaining share fastest; glass holds residual clinical loyalty.
Use Case:
Customer type fragmentation splits the market between medically refracted correction and self-directed aesthetic acquisition, requiring divergent distribution architectures.
- Vision Correction:Medically supervised refraction for myopia, hyperopia, and astigmatism requires licensed optometrist concentration in Riyadh, Jeddah, and Dubai. Clinical channel control limits pure-play online penetration for complex prescriptions.
- Fashion Accessory:Non-prescription frames and cosmetic contact lenses attract beauty-focused consumers through licensed clinics following MOHAP's expanded decorative lens standards. The segment redirects formerly informal retail flows through formal medical device channels.
- Sports Performance:Wraparound geometries with anti-fog coatings serve cycling, running, and water sports enthusiasts across UAE's active lifestyle corridor.
- Occupational Safety:ANSI-rated and GSO-compliant protective eyewear serves oilfield, construction, and laboratory environments under mandated employer provision rules.
Fashion Accessory is expanding most quickly; Vision Correction retains volume dominance.
Distribution Channel:
Geography of fulfillment determines customer acquisition economics, with Dubai's retail density enabling hybrid models unavailable in secondary Saudi cities.
- Online Retail:Price-transparent refraction platforms with home trial logistics address fit-risk aversion among first-time digital buyers. Subscription replacement models for daily disposables concentrate recurring revenue in Riyadh and Jeddah where delivery infrastructure supports automated replenishment.
- Optical Stores:Mall-based boutiques with in-house optometrists retain dominant share of complex prescription fulfillment where fitting accuracy determines outcomes. Inventory synchronization challenges mount across multi-location chains.
- Department Stores:Sunglass counters in luxury retail formats capture tourist spending with limited clinical service attachment.
- Pharmacies:Reading glasses and over-the-counter blue-light filters serve convenience-driven purchase occasions with minimal professional consultation.
Online Retail climbs the fastest; Optical Stores defend the core.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed optometrists and optical retail professionals concentrate in Riyadh, Jeddah, and Dubai, anchoring prescription fulfillment capacity across the Gulf while secondary cities face talent scarcity constraints.
Saudi Arabia
Young adult demand for fashion-forward frames and subscription contact lens models drives growth in Riyadh and Jeddah. SFDA registration protocols for silicone hydrogel formulations extend approval timelines and consolidate compliant supplier networks. The Eastern Province's petrochemical corridor sustains occupational safety eyewear procurement under GSO conformity mandates.
United Arab Emirates
Dubai's mall-based optical boutiques and e-commerce fulfillment centers capture tourist and resident spending through hybrid retail density. MOHAP expanded product standards for decorative contact lenses redirect informal retail flows through licensed clinics. Abu Dhabi's duty-free zones at airport terminals represent high-margin sunglasses volume concentration.
Qatar
Expatriate professional populations and healthcare infrastructure investments support vision correction demand in Doha. The national health regulator maintains alignment with Gulf Standardization Organization protocols for imported optical devices. Lusail City's emerging retail clusters attract optical chain expansion from established UAE operators.
Kuwait
Affluent consumer segments sustain premium frame and lens positioning across Kuwait City's optical retail corridor. The national pharmaceutical and medical device authority enforces registration requirements parallel to Saudi and UAE frameworks. Mall-based vision centers in Salmiya concentrate inventory investment for fashion-accessory eyewear.
Bahrain
Financial services sector professionals generate workplace blue-light filtering lens demand in Manama's corporate districts. The national health regulator operates within Gulf Cooperation Council harmonization frameworks for optical product standards. Seef Mall and City Centre anchor optical retail presence for resident and Saudi cross-border consumers.
Middle East Eyewear Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across prescription fulfillment, lens manufacturing, and digital distribution vectors. Market structure tilts toward consolidation at the premium tier where integrated lens-retail operations dominate, while mid-tier positioning fragments across regional optical chains and emerging e-commerce platforms. Three archetypes prevail: vertically integrated lens manufacturers with captive retail networks, hospital-affiliated vision center operators controlling clinical channels, and digitally native platforms competing on price transparency and home trial logistics. Capacity expansion through clinic network growth and strategic partnerships with e-commerce fulfillment operators represent the dominant competitive moves.
Among integrated multinational operators, EssilorLuxottica and Zeiss Group exemplify lens-manufacturing-to-retail architectures with regional laboratory and distribution infrastructure. Within the Gulf-origin healthcare-retail tier, Magrabi-Rivoli Enterprise anchors hospital-affiliated vision center and optical retail positioning through clinical channel control. At the digitally native vector, Lenskart occupies a position representing India-born e-commerce expansion into Gulf urban centers with online refraction and home trial service models.
| Leading Market Players |
|---|
| Eyewa |
| EssilorLuxottica |
| Magrabi-Rivoli Enterprise |
| Bausch Health Companies |
| Safilo Group |
| Yateem Optician |
| Lenskart |
| Zeiss Group |
| Al Jaber Optical |
| Others |
Value Chain & Pricing Dynamics
Gulf Standardization Organization conformity protocols gate qualified supply access and premium-tier pricing power across Middle East eyewear markets, compressing margins for uncertified entrants while rewarding compliant manufacturers with pricing authority in hospital-affiliated channels.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across prescription fulfillment. Three-tier pricing structure across premium, standard, and economy levels reflects lens material grade and optometrist consultation inclusion. Price differentiation hinges on SFDA registration tier and captive laboratory proximity. Cost compression in mid-tier frames intensifies as petrochemical feedstock volatility squeezes injection-molded propionate margins. Tourist buyers at Dubai duty-free zones exhibit lowest price sensitivity; Saudi millennials purchasing daily disposable subscriptions online show highest.
Supply Chain Analysis
Dual-sourcing requirements from Saudi hospital chains and UAE retail conglomerates mandate multi-supplier qualification for silicone hydrogel formulations and polycarbonate substrates. Manufacturing concentrates in Italy, China, and India for finished frames; lens blanks originate from Germany, Japan, and Thailand. Raw material dependencies span petroleum-derived engineered plastics, titanium alloys, and optical coatings. Single-source vulnerability concentrates in specialized photochromic dye suppliers. Distribution runs through Dubai's co-located mall boutiques and e-commerce fulfillment centers serving GCC-wide demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in subscription contact lens models and blue-light-filtering lens tiers, where premium positioning offsets polycarbonate feedstock cost volatility through recurring revenue capture.
For Market Incumbents: Acquire optometrist talent pools in Riyadh and Jeddah to defend clinic channel control against Lenskart's digital refraction encroachment. Secure backward integration into prescription laboratory networks across Saudi Arabia's Eastern Province. SFDA registration timeline compression threatens first-mover advantage for silicone hydrogel launches. For New Entrants and Emerging Players: Launch via home trial logistics in secondary Saudi cities where optical store density remains thin and delivery infrastructure now supports frame return cycles. Target Abu Dhabi duty-free sunglasses counters as highest-margin white space with limited incumbent saturation. Exploit telehealth refraction regulatory ambiguity in UAE before clarity favors established players. For Investors and Strategic Acquirers: Roll-up economics work for regional optical chain consolidation because family-owned legacy operators lack succession planning and digital inventory systems. Five-to-ten year viability favors targets with captive SFDA certification infrastructure and clinic real estate in Dubai's mall corridor. Watch MOHAP telehealth prescription permissions as inflection signal for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Compresses approval timelines for silicone hydrogel formulations against competitive windows. |
| Telehealth Refraction Platform Launch | Captures customer acquisition cost advantages before UAE regulatory clarity favors incumbents. |
| Home Trial Logistics Expansion | Addresses fit-risk aversion among first-time online buyers in Riyadh and Jeddah. |
| Blue-Light-Filtering Lens Tier Introduction | Collapses separate sunglasses purchase into single transaction for UAE corporate professionals. |
| Optometrist Talent Acquisition | Secures licensed refraction capacity in secondary Saudi cities facing scarcity constraints. |
Study Parameters
Bottom-up vision correction demand modeling reconciled against top-down lens manufacturing capacity tracking forms the analytical core of this study. Primary interviews with licensed optometrists, optical retail chain procurement directors, SFDA regulatory affairs specialists, and e-commerce fulfillment operators combined with secondary validation from MOHAP product standard filings, Gulf Standardization Organization conformity databases, and customs import records. Triangulation across stakeholder perspectives and documentary sources ensures cross-verified segmentation outputs.
Historical trendline analysis of prescription fulfillment volumes, contact lens replacement frequencies, and sunglasses tourist purchase patterns anchored projection modeling across the analysis window. Segmentation dimensions span product type, material substrate, use case, and distribution channel with regional regulatory cluster overlays. CAGRs derive from fitted growth curves adjusted for SFDA registration pipeline visibility and polycarbonate adoption trajectory. Industry-specific inputs include optometrist concentration ratios and mall-based retail density indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under telehealth refraction permission delays or petrochemical feedstock price spikes. Deviation in SFDA contact lens approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
United States Eyewear Market
Eyewear
3D Printing in Eyewear Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Wooden Eyewear Market
Eyewear
Goggles Market
Eyewear
Anti-Fog Lens Market
Eyewear
Reading Glasses Market
Eyewear
Eyewear Market
Eyewear
Luxury Eyewear Market
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Sunglasses Market
Eyewear
Smart Sunglasses Market
Eyewear
Eyeglass Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Blue Light Glasses Market
Eyewear
Spectacles Market