
 Smart Eyewear Market | 2026-2036
Smart Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Eyewear Market Analysis
Subscription-based hardware leasing and asset-light enterprise procurement models are rewriting competitive entry barriers in smart eyewear. Vuzix leverages vertical integration across waveguide design and microdisplay assembly to sustain margin control in enterprise AR glasses. TCL RayNeo anchors its position through aggressive pricing and rapid product refresh cycles in consumer-facing smart sunglasses. Meta competes by pouring R&D intensity into spatial computing platforms that extend beyond hardware into software ecosystems.
Smart eyewear comprises optoelectronic devices integrating microdisplays, sensors, and wireless connectivity into spectacle-form factors, typically weighing 80-150 grams with field-of-view specifications ranging from 30 to 110 degrees. These devices overlay digital information onto physical environments or immerse users in synthetic worlds for industrial training, remote collaboration, and consumer entertainment. AR glasses command the dominant revenue share among product types due to enterprise penetration in logistics and field service, while wearable displays represent the fastest-growing category as medical and defense applications expand. Gesture recognition technology leads technology segments in patent filings, though mixed reality systems capture the highest average selling prices through integrated depth sensing and spatial mapping capabilities.
FDA premarket notification requirements for smart eyewear with biometric monitoring functions are lengthening approval timelines for health-focused entrants. EU MDR and REACH compliance obligations on battery materials and electromagnetic emissions are forcing redesign cycles for manufacturers targeting European commercial buyers. FCC equipment authorization rules in the United States govern radio frequency emissions from wireless-enabled frames. Stakeholders must monitor evolving ocular safety standards and spectrum allocation decisions that will determine which connectivity protocols dominate next-generation devices.
Market Dynamics
Enterprise logistics operators are consolidating procurement around AR glasses platforms that integrate waveguide optics with warehouse management systems, compressing vendor selection cycles from multi-year pilots to single-source fleet deployments.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:Expedited premarket notifications for ocular-worn diagnostic devices are accelerating health-focused smart eyewear commercialization timelines for biometric monitoring applications.
- Gesture Recognition Patents:Dense intellectual property filings around hand-tracking algorithms are reducing licensing friction for mid-tier hardware entrants seeking spatial interface capabilities.
- German Industrial Clusters:Dense concentrations of automotive and precision manufacturing facilities in Bavaria and Baden-Württemberg are generating sustained pilot demand for assisted-assembly AR systems.
Market Restraints
- Microdisplay Supply Concentration:Captive production of high-brightness OLED microdisplays by Sony and Samsung Display creates allocation bottlenecks for second-tier AR hardware vendors.
- EU MDR Compliance Burden:Extended clinical evaluation requirements for ocular-worn medical devices are extending redesign cycles by 18-24 months for biometric monitoring entrants targeting European healthcare procurement.
- Battery Energy Density Ceiling:Lithium-polymer cell chemistry limitations constrain all-day operational targets for enterprise AR glasses below 100-gram form factors.
Strategic Opportunities
- Subscription Hardware Leasing:Asset-light procurement models are opening enterprise AR deployment to mid-market logistics operators previously excluded by upfront capital requirements.
- Defense Training Simulations:Mixed reality systems for combat scenario rehearsal represent an underpenetrated vertical with concentrated procurement authority and accelerated procurement cycles.
- China NMPA Digital Health Fast-Track:Priority review pathways for AI-enabled diagnostic devices are creating regulatory arbitrage opportunities for biometric eyewear developers with domestic manufacturing partnerships.
Industry Challenges
- Optical Engineering Talent Scarcity:Waveguide design and micro-optics simulation expertise concentrates within a narrow pool of specialists trained at specific German and Swiss technical institutes.
- FCC Equipment Authorization Delays:Backlogs in radio frequency certification for wireless-enabled frames are compressing product launch windows and misaligning with seasonal enterprise procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Eyewear Market |
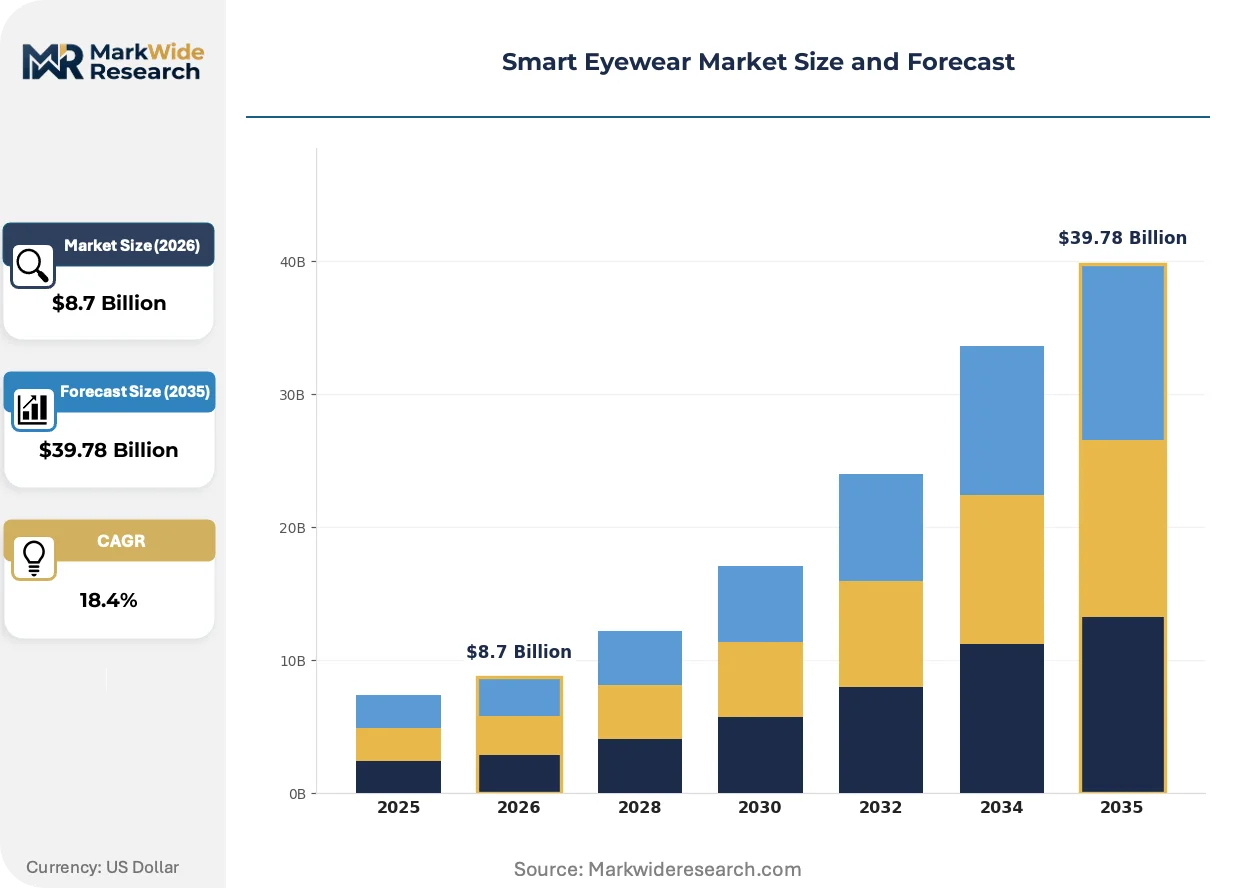
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AR Glasses, VR Headsets, Smart Sunglasses, Wearable Displays End User: Consumers, Enterprises, Healthcare Providers, Educational Institutions Technology: Augmented Reality, Virtual Reality, Mixed Reality, Gesture Recognition Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Vuzix, TCL RayNeo, Meta, Magic Leap, ASUS, XREAL, Amazon, Google, Rokid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Eyewear Market Emerging Trajectories
Spatial computing architectures are migrating from standalone headsets toward distributed processing ecosystems where eyewear functions as a lightweight display peripheral. This architectural shift is compressing hardware BOM costs while elevating software platform control as the primary competitive battleground.
Waveguide optics incorporating surface-relief gratings are digitizing how field service technicians access schematics and remote expert guidance. Energy utilities and telecommunications maintenance divisions in the United States are deploying these systems at scale, replacing tablet-based workflows. The technology is digitizing knowledge transfer protocols that previously required physical co-location of senior and junior technicians.
EU MDR ocular safety standards are tightening electromagnetic emissions thresholds for devices worn in proximity to sensitive tissue. Manufacturers targeting European commercial buyers are redesigning antenna configurations and shielding architectures to satisfy notified body expectations. Medical-grade smart eyewear with biometric monitoring functions faces the steepest compliance trajectory under these revised requirements.
Enterprise buyers are consolidating vendor relationships around integrated hardware-software-service bundles that internalize training, device management, and refresh cycles. Logistics operators in Germany and the United States are displacing fragmented procurement of point solutions with multi-year fleet agreements. This pattern concentrates purchasing authority among procurement teams with technical evaluation capabilities rather than distributed IT departments.
Smart Eyewear Market Segmentation
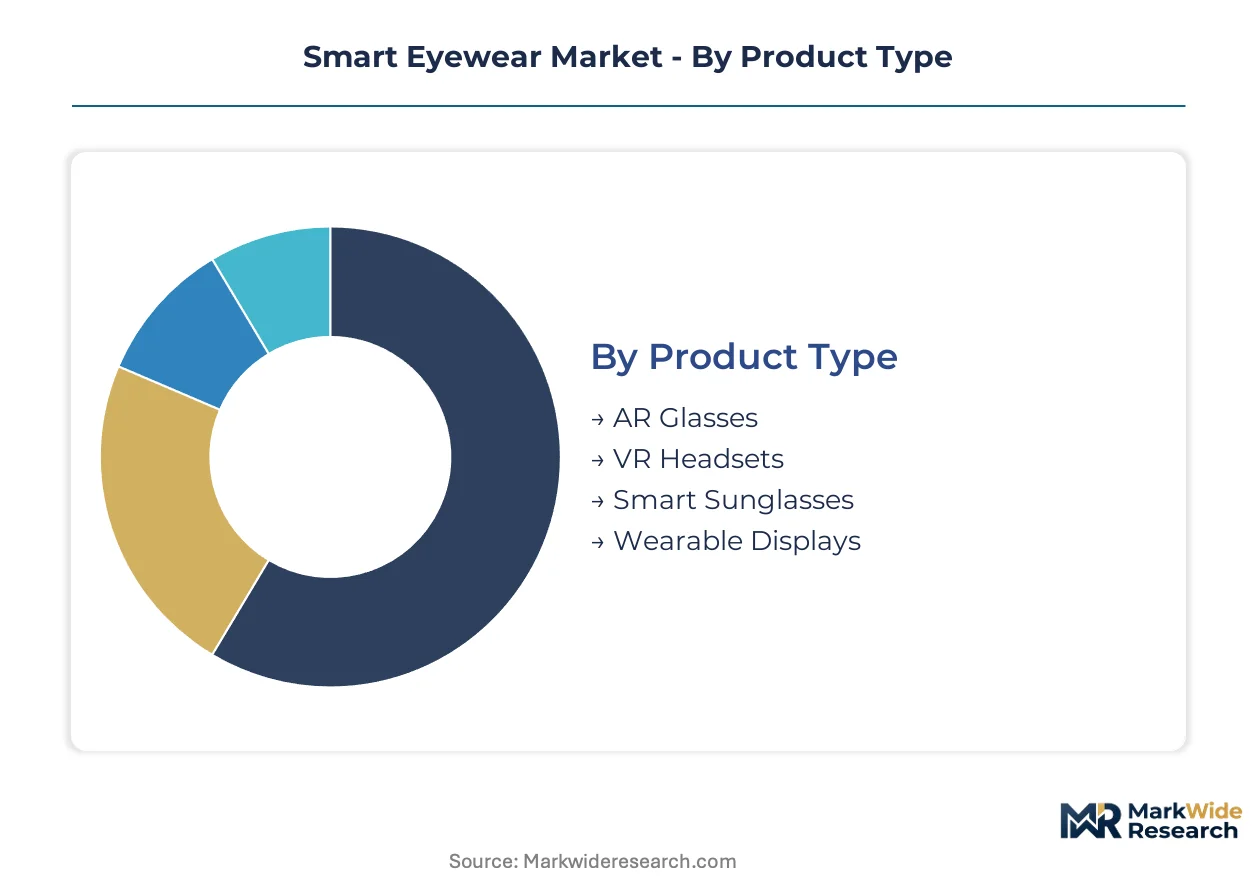
Segmentation in smart eyewear reveals how technical specifications, procurement patterns, and service requirements diverge across use cases. Enterprise buyers prioritize multi-year support contracts and fleet management capabilities that consumer channels rarely offer.
Product Type:
After-sales service intensity varies dramatically across form factors, with enterprise AR glasses requiring dedicated field engineering support while consumer smart sunglasses operate on minimal-touch replacement models.
- AR Glasses:Waveguide optics and microdisplay assemblies demand specialized calibration and repair infrastructure. Logistics operators in Germany and the United States are consolidating fleet procurement around vendors offering integrated device management platforms with guaranteed uptime clauses.
- Wearable Displays:Lightweight monocular and binocular projection systems serve medical imaging and defense training applications. Medical institutions in China are deploying these systems for surgical navigation, supported by NMPA fast-track pathways for AI-enabled diagnostic peripherals.
- VR Headsets:Fully immersive headsets with integrated tracking and haptic feedback.
- Smart Sunglasses:Audio-integrated eyewear with camera and Bluetooth connectivity for consumer lifestyle applications.
By volume, AR Glasses leads. By growth pace, Wearable Displays is expanding most quickly.
End User:
Procurement authority concentrates differently across customer types, with enterprise IT departments wielding technical evaluation capabilities that healthcare procurement teams are only now developing.
- Enterprises:Warehouse operators and field service divisions purchase through multi-year hardware-software-service bundles. German automotive clusters in Bavaria generate sustained demand for assisted-assembly systems with embedded remote expert connectivity.
- Consumers:Individual buyers respond to pricing tiers and brand ecosystem lock-in. Chinese e-commerce platforms drive volume through aggressive promotional cycles and rapid product refresh cadences.
- Healthcare Providers:Hospitals and clinics navigating FDA 510(k) and EU MDR compliance for biometric monitoring functions.
- Educational Institutions:Universities and vocational training centers deploying immersive learning laboratories.
Enterprises command the highest average contract values. Healthcare Providers face the steepest regulatory compliance trajectory.
Technology:
Patent density and licensing friction separate technology categories, with gesture recognition algorithms commanding premium royalty structures that squeeze mid-tier hardware margins.
- Mixed Reality:Integrated depth sensing and spatial mapping systems achieve the highest average selling prices through combined virtual and physical environment manipulation. Defense training simulations in the United States represent concentrated procurement with accelerated deployment cycles.
- Gesture Recognition:Hand-tracking and spatial interface algorithms reduce hardware button dependency. Dense intellectual property filings around computer vision methods are lowering licensing friction for second-tier entrants seeking spatial control capabilities.
- Augmented Reality:Optical see-through displays overlaying digital information onto physical environments.
- Virtual Reality:Fully enclosed visual systems with positional tracking for synthetic environment immersion.
Mixed Reality captures premium pricing. Gesture Recognition is gaining share fastest through cross-platform licensing expansion.
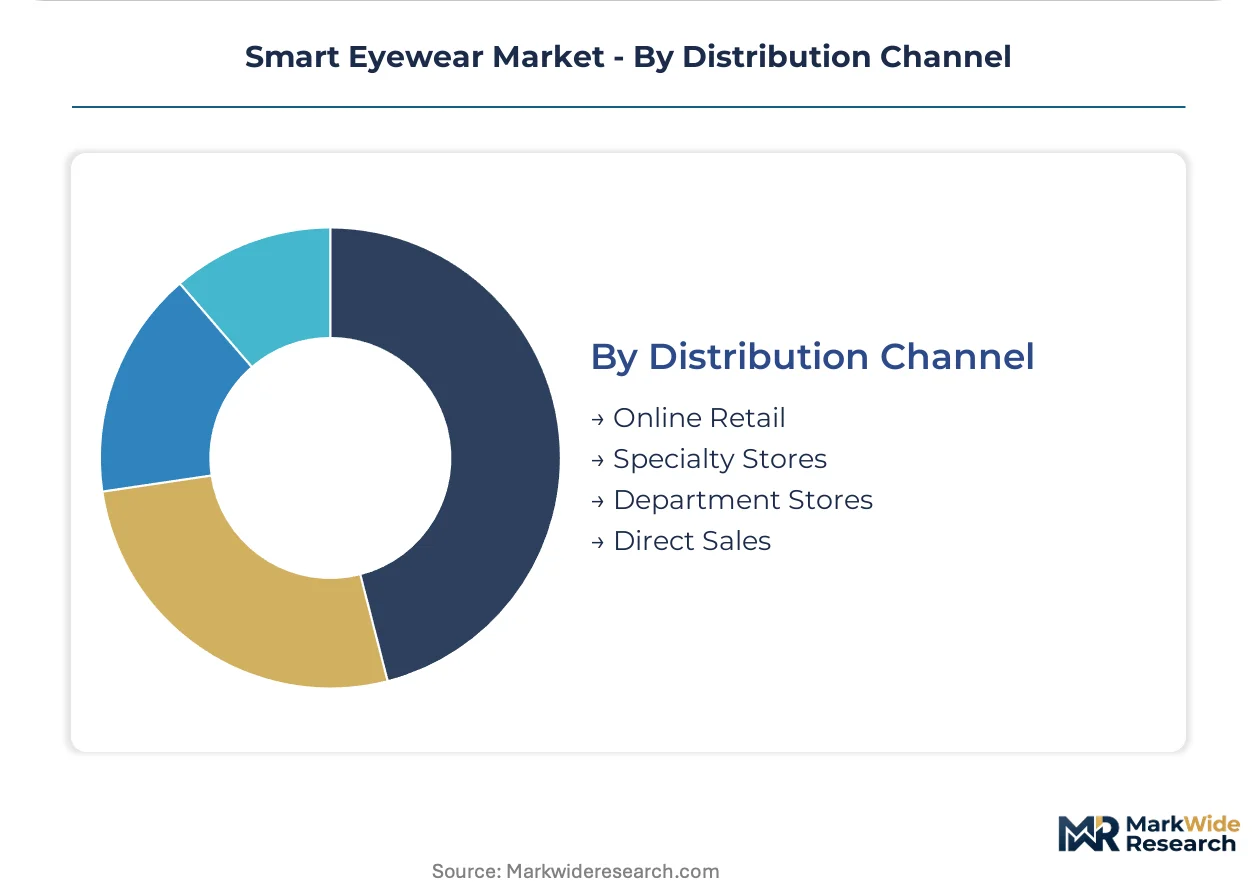
Distribution Channel:
Channel economics reflect customer acquisition costs and technical support requirements, with direct sales teams commanding enterprise relationships that online retail cannot replicate.
- Direct Sales:Vendor field organizations manage complex enterprise procurement with customized integration services. FCC equipment authorization requirements for wireless-enabled frames create technical consultation needs that direct channels address through pre-sales engineering support.
- Online Retail:E-commerce platforms aggregate consumer demand with minimal touchpoints. Chinese domestic manufacturers leverage Tmall and JD.com infrastructure for rapid market penetration without physical retail investment.
- Specialty Stores:Optical retailers and electronics boutiques offering fitting and demonstration services.
- Department Stores:Mass merchandisers with seasonal promotional calendars and limited technical expertise.
Direct Sales dominates enterprise contract value. Online Retail leads unit volume through consumer accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where enterprise procurement teams command multi-year fleet agreements, while Chinese manufacturers compete on volume through aggressive e-commerce promotional cycles.
United States
Energy utilities and telecommunications maintenance divisions deploy waveguide-equipped AR glasses at scale, replacing tablet-based field service workflows. FCC equipment authorization requirements for wireless-enabled frames create technical consultation needs that direct sales channels address through pre-sales engineering support. Boston and San Francisco host dense concentrations of spatial computing startups developing gesture recognition algorithms for industrial applications.
Germany
Automotive and precision manufacturing facilities in Bavaria and Baden-Württemberg generate sustained pilot demand for assisted-assembly AR systems with embedded remote expert connectivity. EU MDR compliance obligations on battery materials and electromagnetic emissions are forcing redesign cycles for manufacturers targeting European commercial buyers. Stuttgart's industrial cluster anchors procurement authority for multi-year hardware-software-service bundles among automotive OEMs.
China
Domestic manufacturers leverage Tmall and JD.com infrastructure for rapid consumer market penetration without physical retail investment. NMPA digital health fast-track pathways for AI-enabled diagnostic devices are creating regulatory arbitrage opportunities for biometric eyewear developers with domestic manufacturing partnerships. Shenzhen and Shanghai concentrate waveguide optics and microdisplay assembly capabilities within vertically integrated supply chains.
Japan
METI industrial technology programs support enterprise AR deployment in precision manufacturing and logistics optimization. JIS standards for wearable device electromagnetic compatibility establish baseline certification requirements for market entry. Tokyo and Osaka metropolitan areas concentrate demand from automotive electronics suppliers and semiconductor equipment manufacturers.
South Korea
Samsung Display and LG Display captive production of high-brightness OLED microdisplays creates allocation bottlenecks for second-tier AR hardware vendors seeking premium panel supply. MFDS medical device regulations govern biometric monitoring functions in health-focused smart eyewear targeting hospital procurement. Seoul Capital Area concentrates R&D investment in mixed reality systems for defense training simulations.
Smart Eyewear Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling waveguide optics and microdisplay supply. The vendor base stratifies across three tiers: multinational technology conglomerates with spatial computing ecosystems, vertically integrated optical hardware specialists, and contract assemblers serving private-label brands. Dominant competitive moves include strategic partnerships with warehouse management system providers and geographic expansion through direct sales organizations targeting German and US enterprise logistics operators.
Among platform integrators, Meta and Google exemplify the software-ecosystem archetype, pouring R&D intensity into spatial computing platforms that extend beyond hardware into developer tools and cloud services. Vuzix and XREAL occupy positions within the vertically integrated optical hardware tier, with Vuzix representing sustained margin control through captive waveguide design and microdisplay assembly capabilities. These three companies anchor the competitive structure through divergent strategic postures: ecosystem lock-in versus component specialization versus aggressive pricing with rapid refresh cycles.
| Leading Market Players |
|---|
| Vuzix |
| TCL RayNeo |
| Meta |
| Magic Leap |
| ASUS |
| XREAL |
| Amazon |
| Rokid |
| Others |
Supply Flow & Price Mechanics
Captive production of high-brightness OLED microdisplays by Sony and Samsung Display in South Korea and Japan concentrates upstream margin capture, forcing downstream AR hardware vendors into allocation queues that erode pricing autonomy and compress contract negotiation leverage against enterprise fleet buyers.
Pricing Analysis
Configured-to-order pricing for enterprise AR glasses with embedded warehouse management system integration commands substantial premiums over standard SKUs distributed through online retail channels. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade biometric eyewear with FDA 510(k) clearance from consumer smart sunglasses and mid-tier logistics hardware. Cost compression in the mid-tier logistics segment is intensifying because TCL RayNeo and domestic Chinese manufacturers are flooding e-commerce platforms with aggressive promotional cycles. Enterprise procurement teams in Germany and the United States exhibit the lowest price sensitivity due to multi-year fleet agreements that internalize total cost of ownership calculations.
Supply Chain Analysis
Export control regimes governing semiconductor lithography equipment and advanced microdisplay manufacturing technology restrict technology flows from the Netherlands, Japan, and the United States to Chinese waveguide optics foundries. Geographic supply concentration clusters in China, South Korea, and Japan for lithium-polymer battery cells, surface-relief grating waveguides, and OLED microdisplay panels. Raw material dependencies include rare-earth phosphors for display backlighting, high-purity silicon substrates, and specialized optical polymers. Single-source vulnerability around Sony and Samsung Display captive microdisplay production creates allocation bottlenecks during demand surges. Distribution runs through vertically integrated direct sales organizations for enterprise contracts and e-commerce platforms for consumer volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart eyewear incumbents face substitution pressure from smartphone-based AR platforms and tablet-based field service workflows that require lower capital deployment and minimal training overhead.
For Market Incumbents: Entrench enterprise relationships through captive waveguide design capabilities and multi-year hardware-software-service bundles that internalize refresh cycles. Deepen backward integration into microdisplay assembly to secure allocation priority during supply crunches. Defend against smartphone AR substitution by emphasizing hands-free operation and thermal compliance in industrial environments where device handling constraints eliminate phone-based alternatives. For New Entrants and Emerging Players: Mid-market logistics operators in Southeast Asia represent the most penetrable entry point, as these fleet buyers remain excluded from premium vendor direct sales coverage and lack technical evaluation capabilities for complex integration. Defense training simulation procurement in NATO-aligned countries offers concentrated authority with accelerated deployment cycles and limited incumbent saturation. Pursue regulatory arbitrage through NMPA partnerships for biometric eyewear targeting Chinese hospital procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed optical hardware specialists that consolidated waveguide design talent during the 2019-2021 AR investment peak. Long-term viability hinges on platform control migration from hardware BOM to software ecosystem recurring revenue. Watch for inflection when enterprise procurement teams begin consolidating vendor relationships around spatial computing platforms rather than point hardware solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Optics Vertical Integration | Captive surface-relief grating production secures margin control against Sony and Samsung Display allocation constraints. |
| Warehouse Management System Partnership | SAP and Oracle integration certifications compress enterprise vendor selection cycles to single-source fleet deployments. |
| FDA 510(k) Fast-Track Submission | Premarket notification streamlining accelerates biometric monitoring commercialization timelines against EU MDR delays. |
| Defense Training Simulation Development | Pentagon procurement authority concentrates demand for mixed reality combat rehearsal systems with premium pricing. |
| NMPA Digital Health Partnership | Domestic manufacturing alliances unlock priority review pathways for AI-enabled diagnostic eyewear in Chinese hospitals. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR notified body documentation, and FCC equipment authorization records preceded structured interviews with logistics procurement directors, biomedical engineers at hospital purchasing committees, waveguide optics R&D leads, and enterprise AR deployment managers. Secondary validation drew from SEC 10-K disclosures of display panel manufacturers, customs trade data for microdisplay imports, and patent filing databases tracking gesture recognition algorithms. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Assumptions held fixed include sustained lithium-polymer energy density ceilings constraining sub-100-gram form factors, continued FDA premarket notification requirements for biometric functions, and stable enterprise procurement consolidation around multi-year fleet agreements. Segmentation dimensions spanned product type, end user archetype, technology category, and regional regulatory cluster. CAGRs derived from logistic curve adoption modeling calibrated to warehouse automation deployment rates and defense procurement cycle timing.
Macroeconomic conditions sit as an overlay; deviation in enterprise capital expenditure cycles or lithium raw material pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway stability and microdisplay supply allocation continuity. Material shifts in EU MDR ocular safety standards or export control expansion to waveguide manufacturing equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Face and Ear Bow Market
Eyewear
Sunglasses Market
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Europe Eyewear Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Eyeglass Market
Eyewear
Middle East Eyewear Market
Eyewear
Eyewear Market
Eyewear
Luxury Eyewear Market
Eyewear
Blue Light Glasses Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Anti-Fog Lens Market
Eyewear
United States Eyewear Market
Eyewear
North America Eyewear Market
Eyewear
Wooden Eyewear Market