
 Face and Ear Bow Market | 2026-2036
Face and Ear Bow Market Size, Share, and Industry Trends Forecast 2026-2036
Face and Ear Bow Market Insights
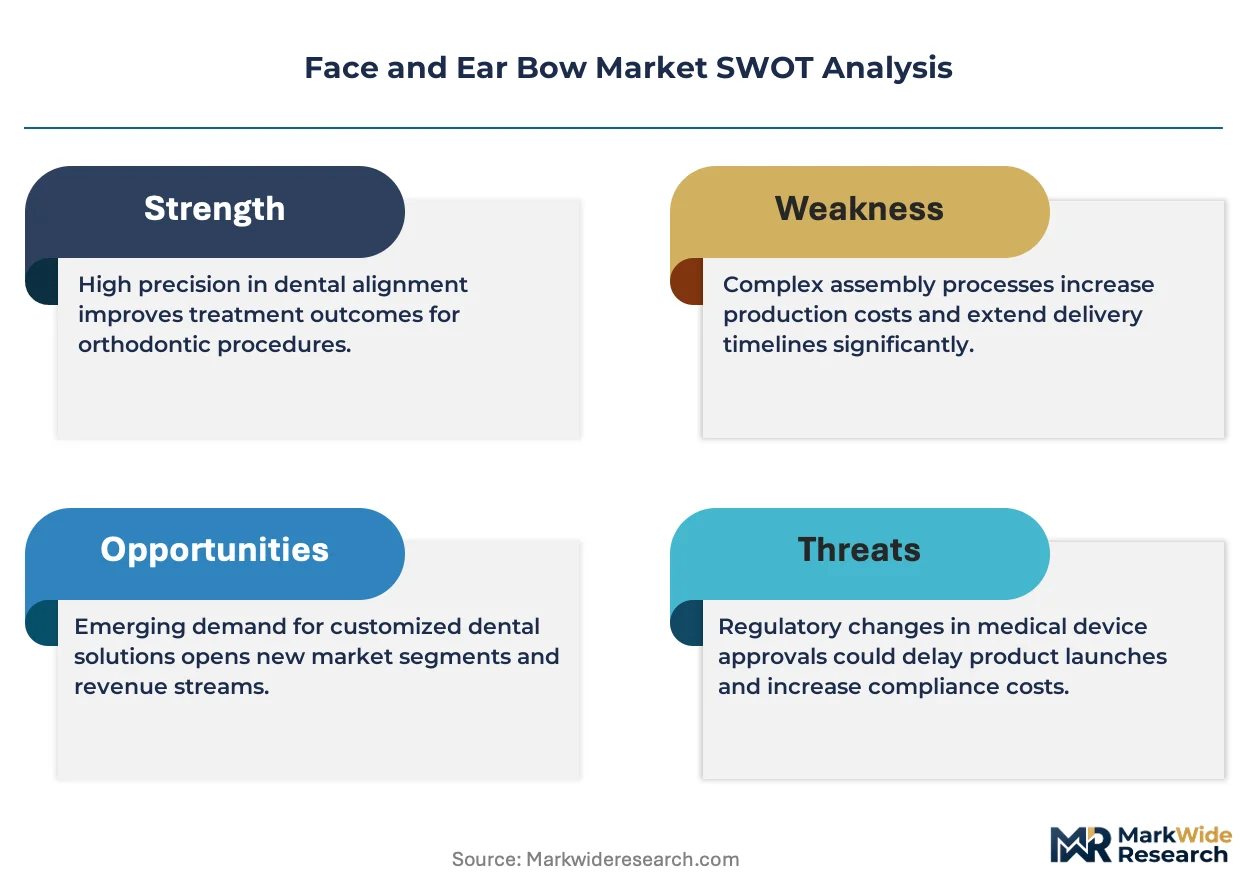
The EU Medical Device Regulation is restructuring cost-of-entry calculus for reusable dental instrumentation across European manufacturing bases. Amann Girrbach AG leverages in-house milling capabilities to sustain margin control on precision metal bows. Kavo Dental GmbH anchors its position through German engineering standards and direct clinic channel relationships. Shofu Dental Corporation differentiates via ceramic-compatible transfer system designs that serve digital restorative workflows.
Face and ear bows are mechanical transfer instruments that record the spatial relationship of the maxilla to the temporomandibular joints, typically constructed from aluminum alloys or reinforced polymers with earpiece assemblies that reference the hinge axis within 5 millimeters of true rotation. Dental face bows capture maxillomandibular orientation data for articulator mounting, while transfer bows enable prosthetic fabrication accuracy in complex restorative cases. Metal bows occupy the premium tier due to dimensional stability under repeated sterilization cycles, whereas composite and carbon fiber variants are gaining traction among orthodontic specialists seeking reduced chairside weight. Pediatric dentistry applications remain underpenetrated relative to implantology, creating asymmetric growth profiles across the application matrix.
FDA 510(k) clearance pathways govern US market entry for reusable dental instruments, while CE marking under the EU MDR imposes enhanced clinical evaluation requirements on manufacturers. ISO 13485 quality management certification has become a de facto procurement filter for dental distributors across OECD markets. Stakeholders must monitor regulatory divergence between FDA predicate device routes and MDR technical documentation demands when allocating product development resources.
Market Dynamics
Dental laboratories are abandoning conventional impression plaster for digital intraoral scanning workflows, compressing demand for mechanical transfer instruments while elevating precision requirements for remaining face bow applications in complex restorative cases.
Growth Catalysts
- EU MDR compliance deadlines:German manufacturers holding notified body certifications capture procurement preference from dental distributors seeking supply chain certainty under elevated technical documentation requirements.
- Implantology case volume:Full-arch rehabilitation protocols require articulator-mounted casts for prosthetic fabrication, sustaining instrument demand in oral surgery and prosthodontic practices.
- Aluminum-magnesium alloys:Advances in lightweight metal casting reduce chairside fatigue without sacrificing dimensional stability through repeated autoclave cycles.
Market Restraints
- Raw material concentration:Primary aluminum smelting capacity clusters in China and Russia, exposing European instrument fabricators to energy-price-driven input volatility and trade policy friction.
- Digital workflow substitution:Virtual articulator software paired with direct milled restorations eliminates physical cast mounting in select orthodontic and single-unit crown applications.
- CE marking cost inflation:EU MDR clinical evaluation requirements and notified body capacity constraints extend time-to-market for Class I reusable instrument renewals by 12-18 months.
Strategic Opportunities
- Pediatric dentistry:Downsized ear bow assemblies for mixed-dentition patients remain commercially underdeveloped relative to adult-focused implantology instrument lines.
- ISO 13485-certified contract manufacturing:Outsourced precision machining from Czech and Polish suppliers enables mid-tier brands to bypass capital-intensive in-house milling investments.
- Carbon fiber-reinforced polymers:Convergence of aerospace composite manufacturing techniques with dental instrument design creates radiolucent, thermally stable alternatives to metal bows.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for novel polymer earpiece materials delay product launches by 8-14 months.
- CAD/CAM integration complexity:Face bow data formats lack universal interoperability with third-party articulator software, forcing laboratories to maintain redundant measurement systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face and Ear Bow Market |
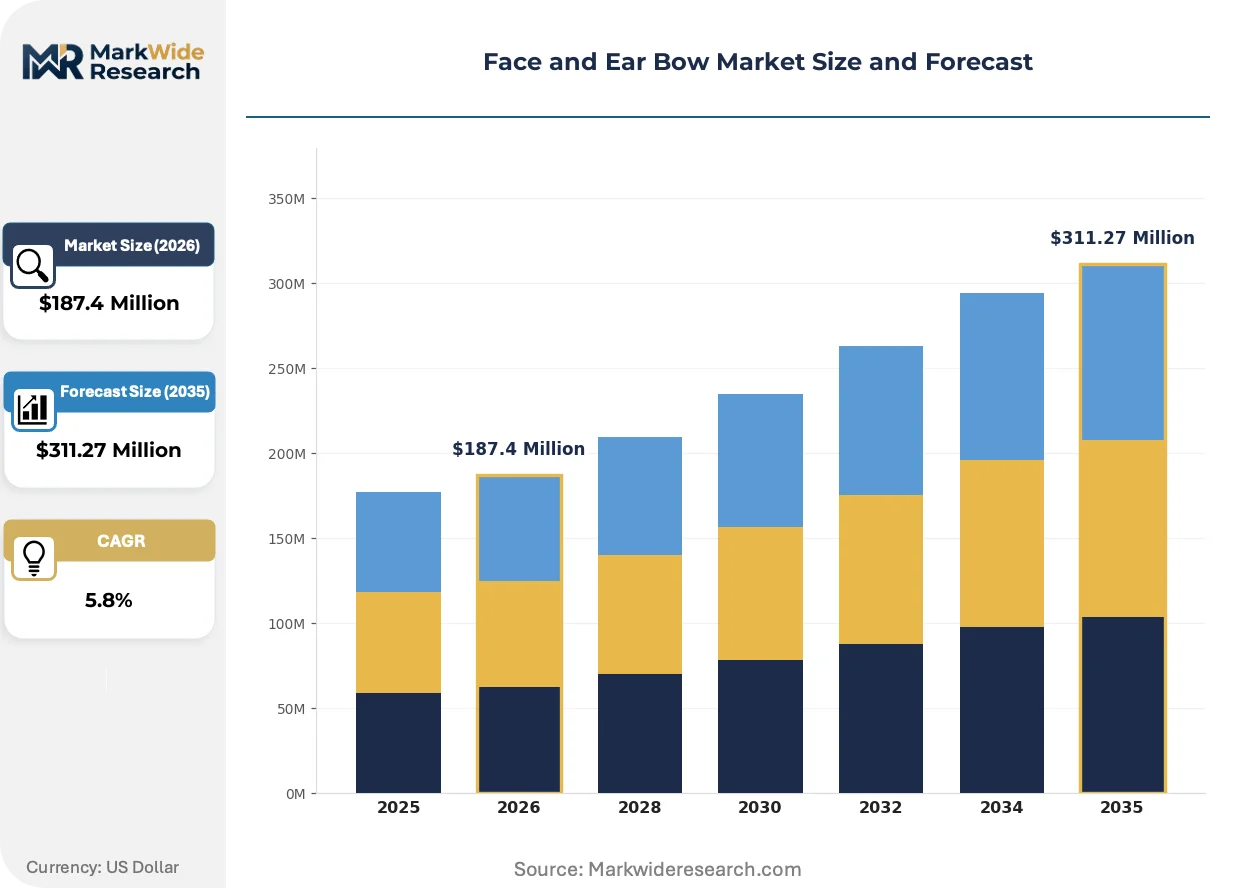
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Face Bows, Ear Bows, Transfer Bows, Other Bows Material: Plastic, Metal, Composite, Carbon Fiber End User: Dentists, Orthodontists, Dental Labs, Academic Institutions Application: Orthodontic Treatment, Dental Implants, Pediatric Dentistry, Restorative Dentistry |
| Companies Covered | Whip Mix Corporation, Amann Girrbach AG, Dentatus USA Ltd., Bio-Art Equipamentos Odontológicos Ltda., Kavo Dental GmbH, Great Lakes Dental Technologies, SAM Präzisionstechnik GmbH, Shofu Dental Corporation, Zirkonzahn GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face and Ear Bow Market Trends and Innovations
Workflow digitization is bifurcating the face bow market between premium precision instruments for complex cases and commoditized alternatives for routine applications, while materials science and regulatory architecture reshape competitive requirements.
Optical scanning face bows is integrating electromagnetic tracking sensors to capture hinge axis position without mechanical earpiece contact. German dental technology institutes are piloting these systems for patients with external auditory canal sensitivity or post-surgical anatomy. The technology is integrating maxillomandibular relationship capture directly into digital treatment planning software, compressing the traditional plaster cast intermediary.
EU MDR technical documentation mandates now require clinical evaluation reports for reusable dental instruments previously exempt under the Medical Device Directive. German notified bodies are prioritizing review capacity for high-risk device categories, creating queuing delays for Class I instrument renewals. Bavarian manufacturers with legacy CE certificates under the MDD transition timeline are accelerating technical file updates to avoid market withdrawal.
After-sales calibration services are unbundling from instrument purchase contracts as dental laboratories internalize metrology competency. Independent service technicians in Baden-Württemberg now offer third-party verification of face bow accuracy against ISO 12836 reference standards. This shift concentrates maintenance revenue with specialized calibration providers while compressing manufacturer service margins.
Face and Ear Bow Market Segmentation
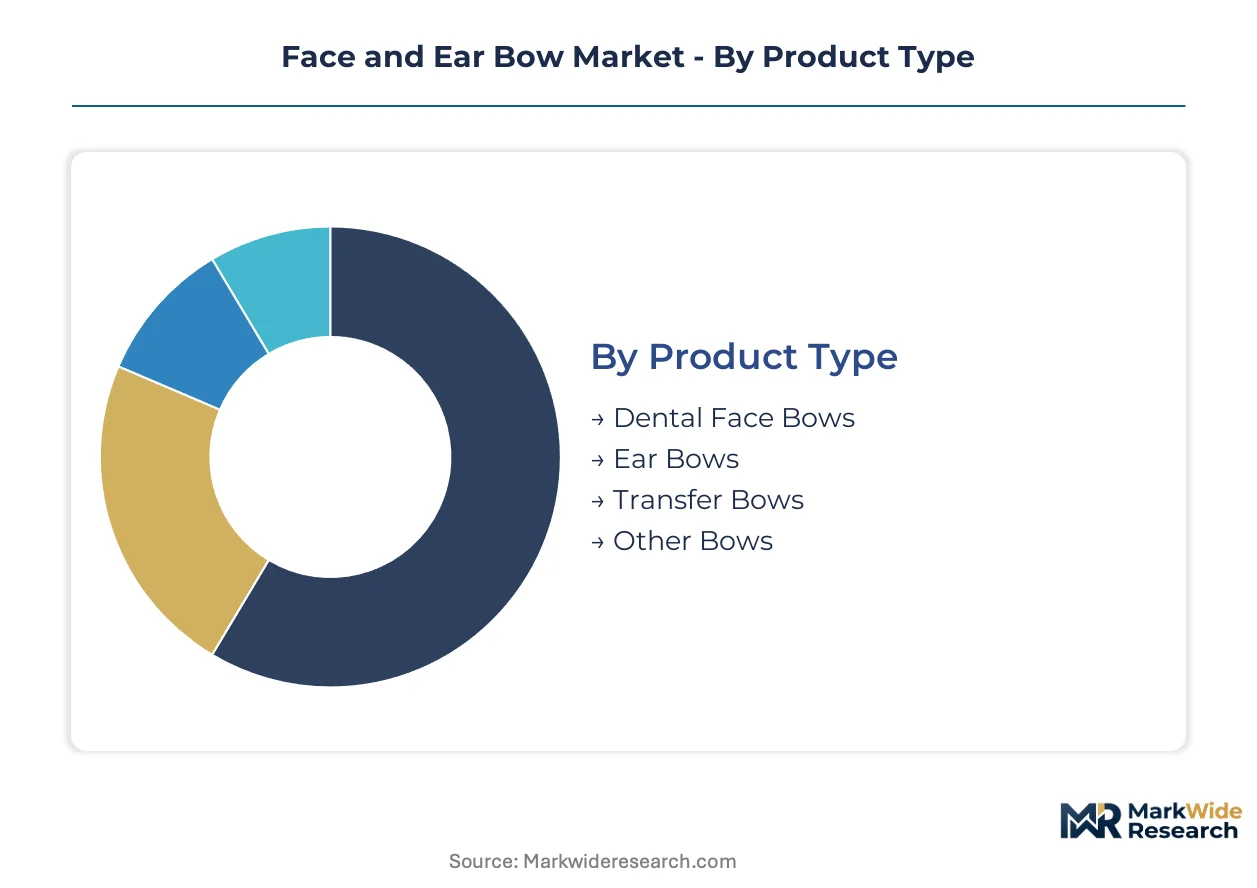
Face and ear bow segmentation reveals how precision requirements, sterilization durability, and digital workflow compatibility fragment demand across dental specialties. Each dimension carries distinct procurement criteria that reshape vendor positioning and R&D allocation.
Product Type:
Dental face bows operate as standalone diagnostic instruments, while transfer bows embed into laboratory fabrication chains and ear bows serve as orientation reference subsystems.
- Dental Face Bows:Aluminum-alloy or carbon-fiber instruments capturing maxillary orientation relative to the temporomandibular hinge axis. German prosthodontic clinics in Bavaria drive replacement demand as EU MDR elevates documentation requirements for reusable Class I devices.
- Transfer Bows:Precision-machined components enabling cast mounting on semi-adjustable articulators. Dental laboratories in Baden-Württemberg source these for full-arch implant cases where virtual articulators remain insufficient.
- Ear Bows:Compact reference assemblies for pediatric and post-surgical applications where external auditory canal sensitivity limits conventional earpiece contact.
- Other Bows:Specialized kinematic face bows and optical tracking variants piloted at German dental technology institutes for electromagnetic hinge axis capture.
Dental face bows lead volumes today; transfer bows are gaining share fastest.
Material:
Material selection trades thermal stability against chairside weight and radiolucency requirements across orthodontic and implantology workflows.
- Metal:Aluminum-magnesium alloys and stainless steel deliver dimensional stability through repeated autoclave cycles. European fabricators in Stuttgart and Munich favor these for premium instrument lines serving complex restorative protocols.
- Carbon Fiber:Aerospace-derived composites offering radiolucency and thermal neutrality. Orthodontic specialists in academic institutions adopt these for reduced patient fatigue during extended chairside procedures.
- Composite:Reinforced polymer blends balancing cost and sterilization resistance for mid-tier dental laboratories.
- Plastic:Single-use or limited-cycle polymers for pediatric applications and emerging markets where capital equipment constraints dominate.
Metal dominates revenue concentration; carbon fiber shows the steepest expansion trajectory.
End User:
Procurement authority concentrates with practitioners who control articulator selection and laboratory referral networks.
- Dental Labs:Volume purchasers of transfer bows and calibration services, with Baden-Württemberg facilities internalizing ISO 12836 metrology competency.
- Dentists:General practitioners selecting face bows for single-unit crown and bridge work, influenced by distributor inventory availability.
- Orthodontists:Early adopters of lightweight composite and carbon fiber variants for adolescent patient compliance.
- Academic Institutions:Pilot sites for optical scanning face bows and electromagnetic tracking validation studies.
Dental labs command procurement volumes; orthodontists are expanding their share fastest.
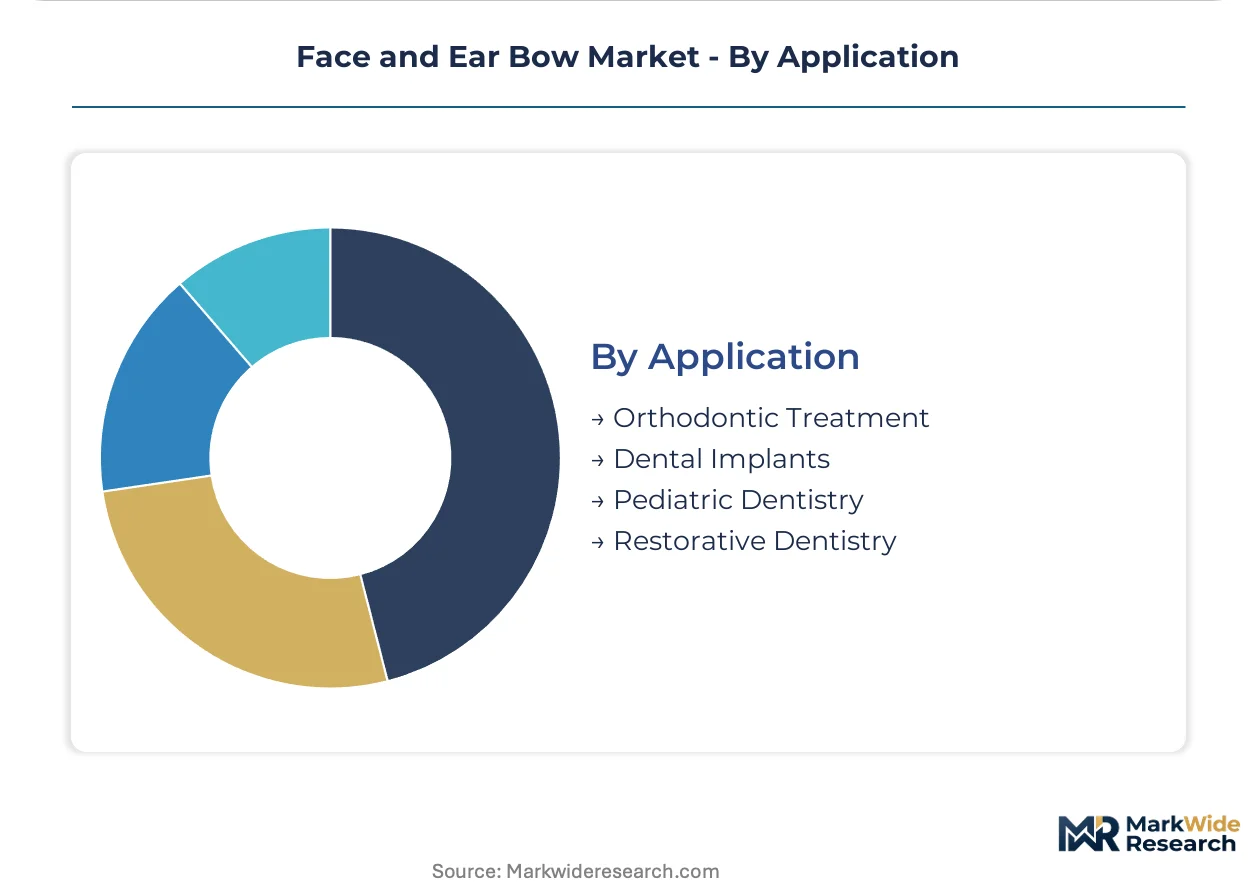
Application:
Application segmentation maps directly to reimbursement intensity and case complexity tiers.
- Dental Implants:Full-arch rehabilitation protocols require articulator-mounted casts for prosthetic fabrication accuracy. Oral surgery practices in Germany sustain instrument demand despite digital workflow penetration.
- Restorative Dentistry:Single and multi-unit crown cases where face bow transfer ensures occlusal precision in semi-adjustable articulator mounting.
- Orthodontic Treatment:Functional appliance fabrication and diagnostic mounting for skeletal discrepancy assessment.
- Pediatric Dentistry:Downsized ear bow assemblies for mixed-dentition patients, currently underdeveloped relative to adult-focused instrument lines.
Dental implants anchor revenue today; pediatric dentistry offers the most asymmetric growth profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The face and ear bow industry traces its precision manufacturing heritage to German dental technology clusters established in the early twentieth century, with Stuttgart and Munich retaining dominant positions in articulator-compatible instrument fabrication.
Germany
Baden-Württemberg dental laboratories command procurement volumes for transfer bows used in full-arch implant protocols. EU MDR notified body certifications under TÜV SÜD and BSI Group create queuing delays for Class I instrument renewals. Bavarian manufacturers in the Munich-Stuttgart corridor accelerate technical file updates to avoid market withdrawal under MDD transition deadlines.
United States
Oral surgery practices in the Northeast and California sustain demand for aluminum-magnesium alloy face bows despite digital workflow penetration. FDA 510(k) clearance pathways govern reusable instrument entry, with predicate device routes favoring established manufacturers. Louisville-based dental distributors maintain inventory concentration for general practitioner crown and bridge applications.
Japan
Academic institutions in Tokyo and Osaka pilot optical scanning face bows with electromagnetic tracking sensors for temporomandibular joint research. PMDA regulatory alignment with ISO 13485 quality management streamlines import approval for European precision instruments. Nagoya-area dental technology suppliers specialize in ceramic-compatible transfer system components.
China
Domestic dental laboratory expansion in Shanghai and Guangzhou drives mid-tier instrument procurement for single-unit restorative cases. NMPA medical device registration requirements impose clinical evaluation documentation on reusable Class I instruments. Yangtze River Delta manufacturing clusters produce aluminum alloy castings for export-oriented precision bow fabricators.
Brazil
Prosthodontic practices in São Paulo and Rio de Janeiro anchor South American demand for semi-adjustable articulator mounting systems. ANVISA medical device regulations align with Mercosur technical standards for reusable dental instrumentation. São Paulo-state dental technology distributors consolidate procurement relationships with German and US instrument suppliers.
Face and Ear Bow Market Competitive Landscape
The competitive structure tilts toward vertically integrated precision manufacturers with in-house milling capabilities. Bavarian and Baden-Württemberg fabricators hold procurement preference from EU distributors seeking supply chain certainty under MDR documentation requirements. Three archetypes dominate: German engineering-standard precision houses, Japanese ceramic-specialist instrument designers, and North American dental distributor-aligned brands. Consolidation pressure concentrates through ISO 13485 certification barriers and notified body capacity constraints, while technology licensing agreements bridge CAD/CAM interoperability gaps.
Among German precision fabricators, Amann Girrbach AG and Kavo Dental GmbH exemplify the engineering-standard archetype with direct clinic channel relationships. Shofu Dental Corporation occupies a position within the ceramic-compatible specialization tier, serving digital restorative workflows. These three entities represent distinct competitive vectors: in-house milling control, distributor network anchoring, and material-science differentiation.
| Leading Market Players |
|---|
| Whip Mix Corporation |
| Amann Girrbach AG |
| Dentatus USA Ltd. |
| Bio-Art Equipamentos Odontológicos Ltda. |
| Kavo Dental GmbH |
| Great Lakes Dental Technologies |
| SAM Präzisionstechnik GmbH |
| Shofu Dental Corporation |
| Zirkonzahn GmbH |
| Others |
Pricing and Supply Chain Analysis
Baden-Württemberg dental laboratories concentrate procurement authority for transfer bows, anchoring a contract-based pricing model where volume commitments secure preferential terms from German precision fabricators. This buyer concentration compresses margins for mid-tier suppliers while rewarding notified body-certified manufacturers with pricing power under EU MDR compliance deadlines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aluminum-magnesium alloy instruments from carbon fiber-reinforced variants and entry-level polymer assemblies. Price differentiation hinges on ISO 13485 certification grade and after-sales calibration bundling. Pricing pressure stems from Czech and Polish contract manufacturers undercutting in-house milling investments. Dental laboratories exhibit highest price sensitivity, while oral surgery practices absorb premium tiers for full-arch implant protocols.
Supply Chain Analysis
Domestic-content mandates under EU MDR technical documentation requirements reshape sourcing toward German notified body-certified fabricators in Bavaria and Baden-Württemberg. Primary aluminum smelting capacity draws from China and Russia, exposing European instrument fabricators to energy-price-driven input volatility. Single-source vulnerability concentrates in Yangtze River Delta casting clusters. Distribution runs through Stuttgart and Munich-based dental technology distributors serving laboratory procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German engineering-standard precision houses exploit regulatory arbitrage against CE marking cost inflation in Southern European markets, capturing margin expansion from notified body capacity constraints that delay competitor renewals.
For Market Incumbents: Deepen backward integration into aluminum-magnesium alloy casting to defend against energy-price volatility from Russian and Chinese smelting concentration. Secure TÜV SÜD notified body queue priority for Class I instrument renewals before MDD transition deadlines force market withdrawal. Channel control through direct clinic relationships in Bavaria anchors pricing power against distributor consolidation. For New Entrants and Emerging Players: Enter via ISO 13485-certified contract manufacturing partnerships with Czech and Polish precision machinists to bypass capital-intensive in-house milling. Pediatric dentistry applications present the most penetrable white space, with downsized ear bow assemblies for mixed-dentition patients commercially underdeveloped relative to adult-focused implantology lines. Target academic institutions in Tokyo and Osaka piloting optical scanning face bows for electromagnetic tracking validation studies. For Investors and Strategic Acquirers: Dental technology distributors with GPO contracts management capability are the most active acquirer in this space, consolidating procurement relationships under EU MDR supply chain certainty demands. Long-term viability centers on CAD/CAM interoperability licensing positions bridging face bow data format gaps with third-party articulator software. Watch for inflection when independent calibration providers in Baden-Württemberg achieve ISO 12836 verification scale sufficient to compress manufacturer service margins.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDD-to-MDR technical file updates under TÜV SÜD review prevent market withdrawal for Bavarian manufacturers. |
| Backward Integration into Alloy Casting | In-house aluminum-magnesium production insulates Amann Girrbach and Kavo from Chinese smelting price volatility. |
| ISO 13485 Contract Manufacturing Partnership | Czech and Polish suppliers enable mid-tier brands to bypass Stuttgart and Munich capital intensity barriers. |
| Optical Scanning Face Bow Development | Electromagnetic tracking sensors at German dental institutes eliminate mechanical earpiece contact for sensitive patients. |
| Independent Calibration Service Scaling | Third-party ISO 12836 verification in Baden-Württemberg concentrates maintenance revenue away from manufacturers. |
Research Methodology
Coverage spans Germany, United States, Japan, China, and Brazil, with primary inputs from each combining interviews with prosthodontic clinicians, dental laboratory procurement managers, biomedical engineers at academic institutions, GPO contracts managers, and aftermarket service heads with secondary validation. FDA 510(k) filings, EU MDR technical documentation databases, ISO 13485 certification registries, and hospital procurement databases anchored source triangulation. Bottom-up instrument shipment data and top-down dental laboratory spending estimates were reconciled.
Rate-of-change decomposition across the analysis window modeled product type splits, material grade tiers, end-user procurement authority concentration, and application complexity tiers. CAGRs derived from segment-level growth rate reconciliation against macro dental expenditure patterns. Forecast inputs incorporated EU MDR notified body queue dynamics, digital intraoral scanning penetration curves, and aluminum alloy price volatility indices.
Inputs from German dental technology institutes and Bavarian manufacturer technical files were available through the study window; gaps in pediatric dentistry application data introduce uncertainty bands around that segment trajectory. Forecasts reflect documented assumptions regarding MDR transition timeline adherence and digital workflow substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Spectacles Market
Eyewear
Blue Light Glasses Market
Eyewear
Wooden Eyewear Market
Eyewear
Latin America Eyewear Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Eyewear Market
Eyewear
Eyeglass Market
Eyewear
North America Eyewear Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Glasses Frame Market
Eyewear
Plano Sunglasses Market
Eyewear
Middle East Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
Goggles Market
Eyewear
Reading Glasses Market