
 Eyeglass Market | 2026-2036
Eyeglass Market Size, Share, and Industry Trends Forecast 2026-2036
Eyeglass Market Insights
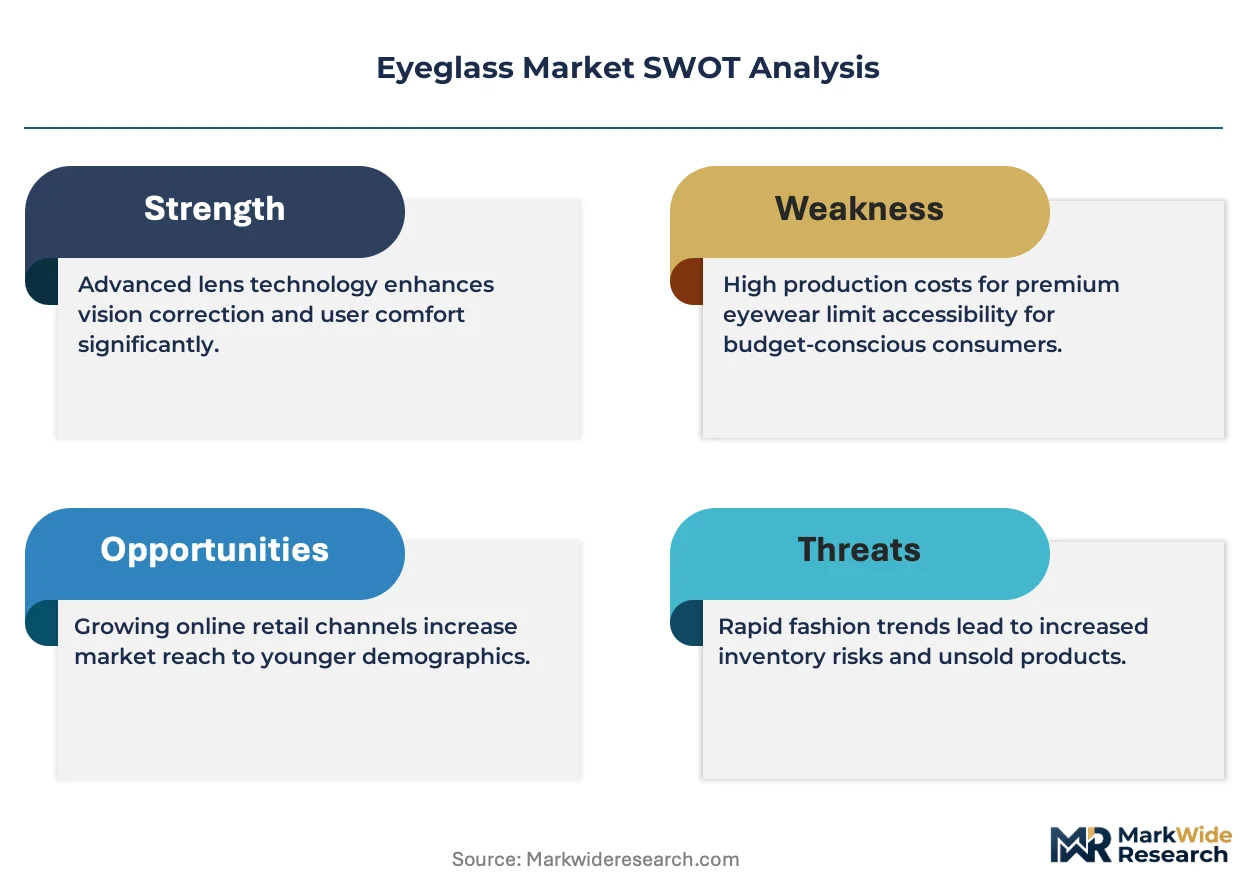
Digital-native consumers are redrawing how eyewear is discovered, fitted, and purchased, shifting share from traditional optical shops to hybrid online-offline journeys. EssilorLuxottica leverages its vertically integrated supply chain to control both lens technology and retail access across continents. Hoya sustains leadership in high-index and photochromic lens innovations through intensive R&D spending. Warby Parker competes by anchoring its brand in direct-to-consumer digital distribution, forcing incumbents to accelerate their own channel modernization.
An eyeglass is a vision-correcting or protective optical device consisting of mounted lenses held in a frame, typically engineered with refractive indices ranging from 1.50 to 1.74 and surface treatments including anti-reflective, scratch-resistant, and hydrophobic coatings, designed to compensate for ametropia, presbyopia, or environmental hazards while conforming to wearer-specific pupillary distance and vertex measurements. Prescription glasses dominate value generation due to recurring replacement cycles tied to prescription changes and fashion turnover, while polycarbonate lenses capture share in safety and pediatric applications owing to impact resistance that meets ANSI Z87.1 standards. Online retail channels are expanding fastest among distribution modes, though optical stores retain margin concentration through high-margin lens add-ons and personalized fitting services.
The U.S. Food and Drug Administration regulates prescription eyeglasses as Class I medical devices, mandating impact resistance and labeling standards that shape manufacturer compliance costs. The European Union's Medical Device Regulation and CE marking requirements govern optical products sold across member states, creating a harmonized but stringent market access framework. China's National Medical Products Administration enforces GB standards for ophthalmic lenses that influence both domestic production and import eligibility. Stakeholders must monitor how evolving digital health integrations and personalized lens algorithms will reshape regulatory boundaries and competitive requirements.
Market Dynamics
Digital-native consumers are forcing a channel restructuring that compresses traditional optical retail margins while expanding direct-to-consumer capture. This behavioral shift is redrawing competitive requirements across prescription fulfillment, virtual try-on deployment, and lens customization workflows.
Growth Catalysts
- Anti-reflective coating mandates:China's NMPA has tightened GB standards for ophthalmic lens surface treatments, accelerating manufacturer compliance investments and premium lens penetration.
- Blue-light filtering technology:Screen-time exposure among knowledge workers and students is driving specification upgrades across polycarbonate and high-index lens categories.
- Aging demographics:Presbyopia prevalence in India and the United States is expanding the recurring replacement base for progressive and bifocal prescriptions.
Market Restraints
- Crude oil derivative volatility:Polycarbonate and high-index lens monomers depend on petrochemical feedstocks, exposing margin structures to energy price swings.
- Optical blank concentration:Lens substrate manufacturing clusters in Thailand and Germany create geographic supply vulnerability for independent labs.
- Prescription verification friction:The FDA's Class I medical device classification for corrective eyewear imposes documentation burdens that slow online fulfillment velocity.
Strategic Opportunities
- Rural India penetration:Underpenetrated vision correction in tier-3 and tier-4 cities offers volume expansion for mobile eye-care and tele-optometry platforms.
- Smart lens convergence:Integration of liquid crystal technology with prescription optics is enabling real-time focal adjustment for presbyopia management.
- EU MDR harmonization:Streamlined CE marking pathways under the Medical Device Regulation are reducing market access costs for innovative lens coatings.
Industry Challenges
- Optometrist workforce scarcity:Licensed practitioner shortages in the United States are constraining retail expansion and same-day prescription fulfillment.
- ISO 21987 certification timelines:Extended conformity assessment periods for mounted spectacle lenses are delaying new product launches in regulated markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eyeglass Market |
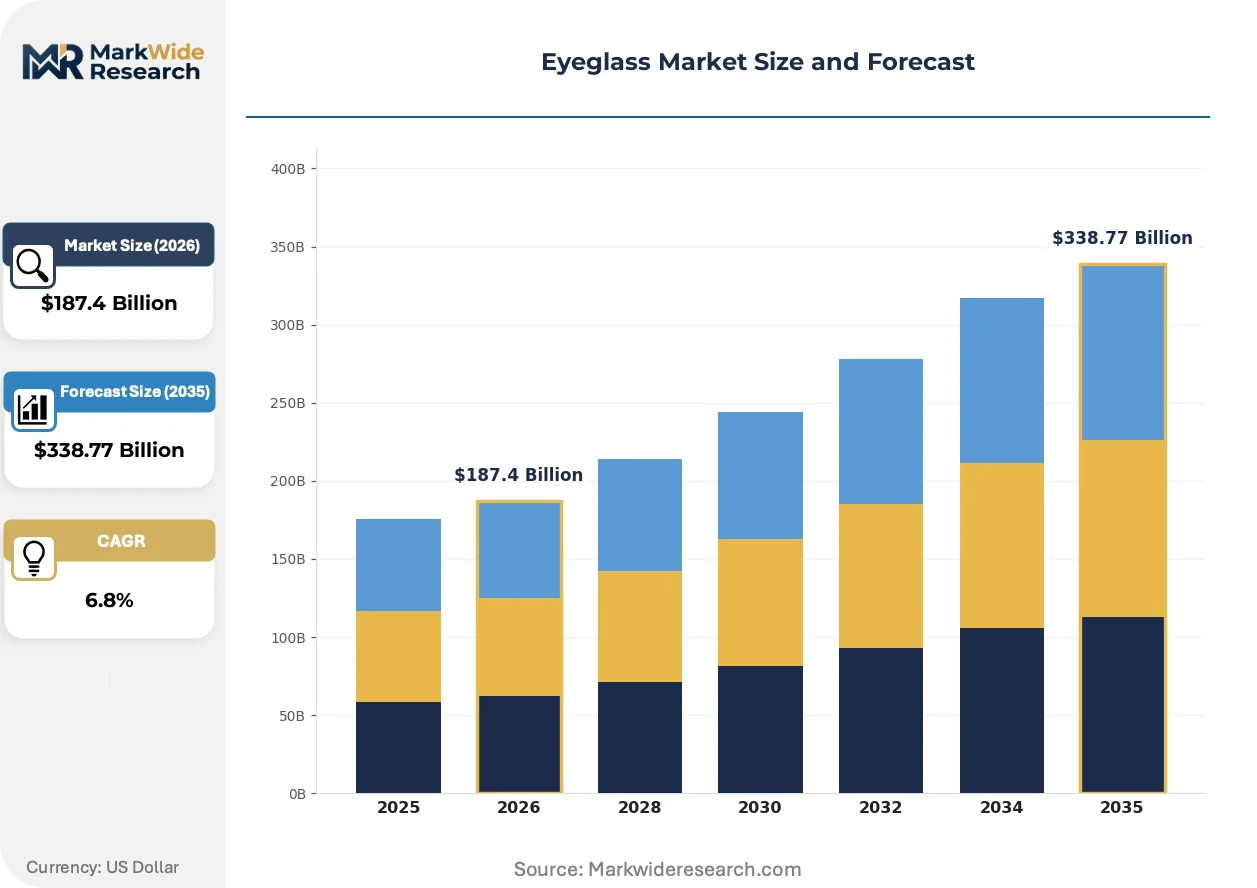
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Glasses, Reading Glasses, Sunglasses, Safety Glasses Material: Plastic, Glass, Polycarbonate, Trivex End User: Adults, Children, Seniors, Athletes Distribution Channel: Online Retail, Optical Stores, Supermarkets, Pharmacies |
| Companies Covered | EssilorLuxottica, Hoya, Cooper Companies, Bausch + Lomb, Fielmann, Warby Parker, National Vision Holdings, Safilo Group, Carl-Zeiss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eyeglass Market Trends and Innovations
Lens technology is splitting into divergent performance tiers while regulatory frameworks harden around medical device claims. These forces are compressing mid-market positioning and rewarding specialized capabilities.
Freeform digital surfacing is bifurcating the prescription lens market between mass-produced stock lenses and fully customized compensated designs. Independent optical labs and premium retail chains are adopting five-axis generators at accelerated rates. This capability split is compressing margins for semi-finished distributors while concentrating value capture with equipment-integrated manufacturers.
The EU's Medical Device Regulation is tightening post-market surveillance requirements for ophthalmic devices sold across member states. Manufacturers must now maintain clinical evidence portfolios and vigilance systems that increase compliance overhead. High-index and photochromic lens categories face the steepest documentation burdens, driving consolidation among smaller CE certificate holders.
Virtual try-on tools are displacing in-person frame selection for initial purchase consideration among millennial and Gen-Z cohorts. Optical retailers are responding by unbundling eye exams from merchandise transactions, converting stores to fulfillment nodes. This channel restructuring is most advanced in the United States, where Warby Parker's digital-native model has forced incumbents to accelerate hybrid platform investments.
Eyeglass Market Segmentation
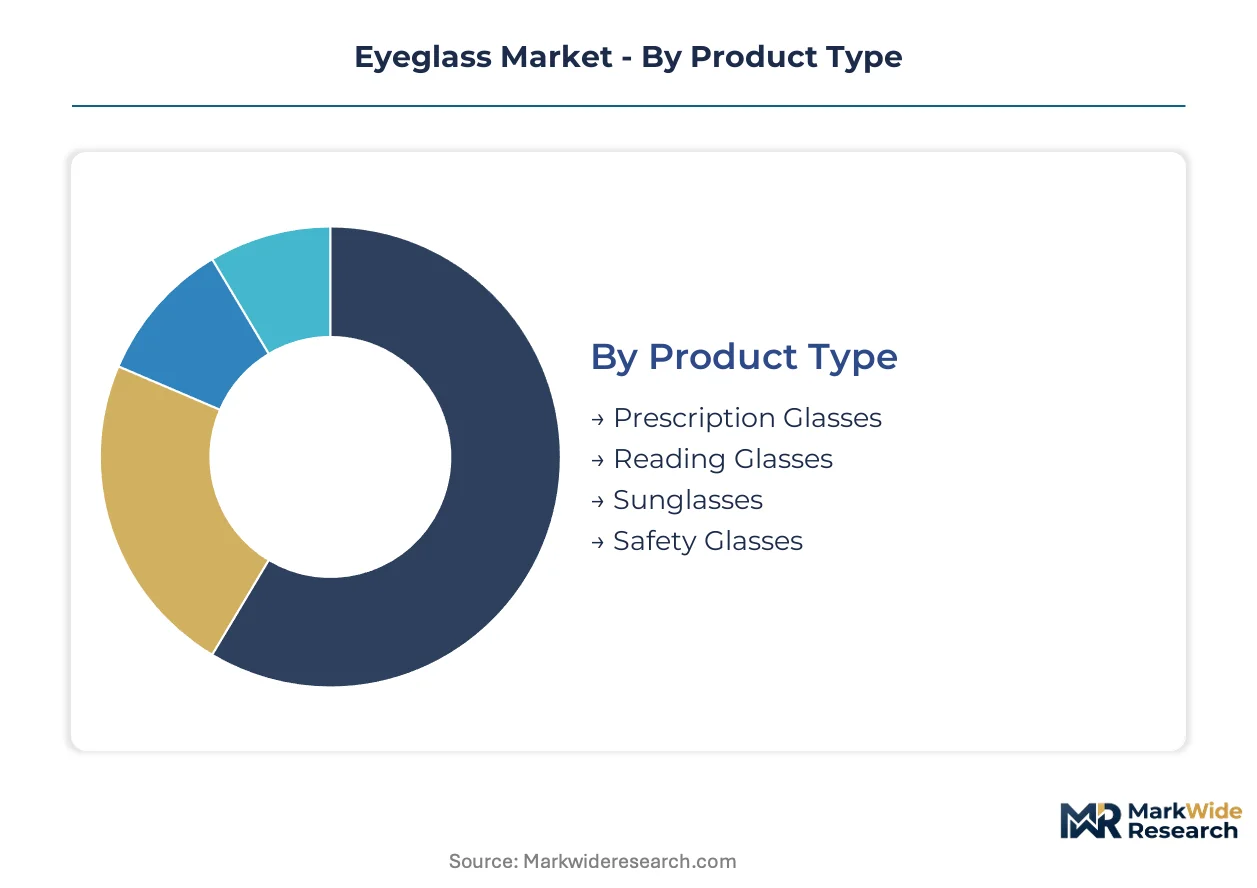
Segmentation in the eyeglass market determines pricing power, regulatory exposure, and channel strategy. Product type and material composition dictate margin structures, while end-user demographics and distribution channels shape geographic expansion priorities.
Product Type:
Domestic consumption concentrates in prescription and reading glasses across aging populations in China, India, and the United States, while sunglasses and safety glasses carry heavier export orientation toward European and Middle Eastern markets.
- Prescription Glasses:Custom-fabricated lenses with refractive indices from 1.50 to 1.74, incorporating anti-reflective and photochromic surface treatments. Demand clusters in the United States and China where presbyopia prevalence and screen-time exposure drive recurring replacement cycles tied to prescription changes.
- Reading Glasses:Pre-fabricated positive diopter lenses typically ranging +1.00 to +3.50, sold without professional fitting. Volume concentrates in India's tier-2 and tier-3 cities where mobile eye-care platforms address underpenetrated vision correction needs among aging workforces.
- Sunglasses:UV-filtering tinted or polarized lenses with fashion-driven frame aesthetics. European Union markets absorb significant export volume under CE marking requirements for ophthalmic devices.
- Safety Glasses:Impact-resistant polycarbonate or Trivex lenses meeting ANSI Z87.1 and EN 166 standards for occupational hazards. Industrial procurement in Germany and the United States sustains volume.
Prescription glasses hold installed capacity. Safety glasses is rotating up the share rankings.
Material:
Cost tiers separate premium high-index formulations from economy plastic substrates, with mid-market polycarbonate capturing volume in pediatric and safety applications.
- Plastic (CR-39):Standard-index thermoset resin with Abbe value of 58, offering optical clarity at lower cost. Mass-market prescription fulfillment in India and Brazil depends on CR-39 blanks.
- Glass:Mineral lenses with superior scratch resistance and refractive stability, though weight limits adoption. Niche demand persists in Germany and Japan for high-precision optical applications.
- Polycarbonate:Impact-resistant thermoplastic with refractive index 1.586, mandatory for pediatric prescriptions and occupational safety in the United States under FDA Class I standards.
- Trivex:Lightweight urethane-based material combining impact resistance with Abbe value 43 for reduced chromatic aberration. Premium positioning in athletic and children's eyewear segments across North American markets.
Plastic substrates dominate unit economics. Trivex is climbing the fastest among specialty materials.
End User:
Application requirements diverge sharply between correction-driven adults and protection-focused athletes, with children and seniors presenting distinct regulatory and fitting complexities.
- Adults:Working-age consumers requiring single-vision, bifocal, or progressive lenses for myopia, hyperopia, and astigmatism correction. China's knowledge-worker population drives blue-light filtering upgrades.
- Children:Pediatric patients needing impact-resistant materials and myopia management designs. India's school-based vision screening programs expand addressable base in tier-3 cities.
- Seniors:Presbyopic consumers requiring progressive addition lenses with wide near-vision corridors. United States Medicare reimbursement patterns influence purchase timing.
- Athletes:Performance-oriented users demanding wraparound frames with prescription inserts or contact lens combinations. Specialized retail channels in Australia and the United States serve this segment.
Adults command volume concentration. Seniors is expanding most quickly as demographic transitions accelerate.
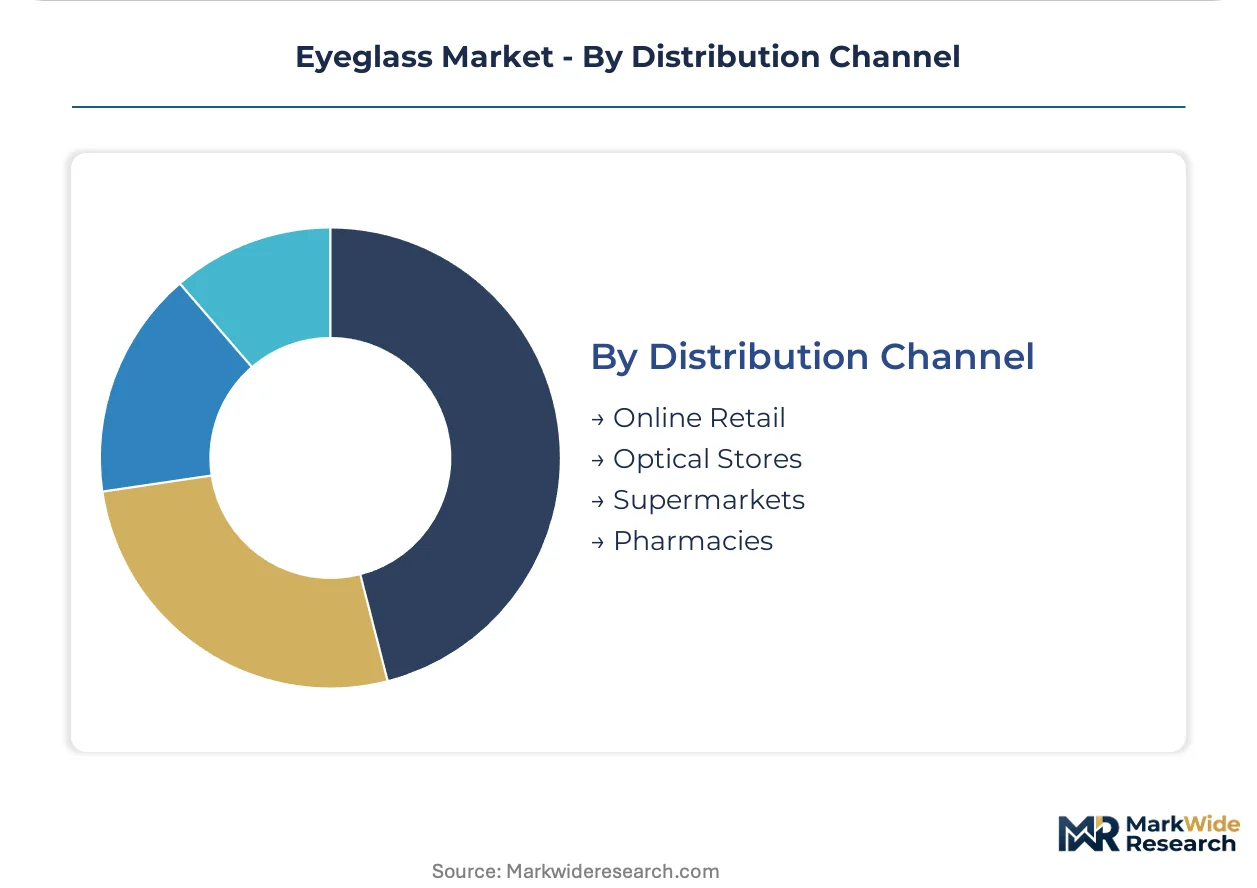
Distribution Channel:
Channel margins separate high-touch optical retail from automated online fulfillment, with supermarkets and pharmacies capturing impulse and convenience-driven purchases.
- Online Retail:Direct-to-consumer platforms with virtual try-on and home trial programs. United States digital-native consumers have shifted initial consideration online, compressing traditional optical retail foot traffic.
- Optical Stores:Professional fitting services with in-house edging labs and high-margin lens add-ons. Germany's independent optician network maintains strong positioning through personalized service.
- Supermarkets:Mass-merchandise reading glasses and basic sunglasses through self-service displays. China's Suning and JD offline formats integrate vision screening kiosks.
- Pharmacies:Over-the-counter reading glasses and blue-light filtering computer glasses. CVS and Walgreens in the United States stock pre-fabricated diopter ranges for immediate purchase.
Optical stores retain margin concentration. Online retail is gaining share fastest among fulfillment modes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific eyeglass distribution, handling lens substrate imports from Germany and Thailand while exporting finished frames to European and North American markets through integrated cold-chain logistics corridors.
United States
Medicare reimbursement patterns for presbyopia correction and employer-sponsored vision benefits sustain replacement cycles. The FDA's Class I medical device classification mandates impact resistance testing that shapes manufacturer compliance costs. Dallas-Fort Worth hosts centralized distribution hubs serving independent optical labs across the Southwest.
China
Knowledge-worker screen-time exposure and aging demographics expand demand for blue-light filtering progressives. The NMPA enforces GB standards for ophthalmic lens surface treatments including anti-reflective coatings. Danyang in Jiangsu Province concentrates domestic frame manufacturing with integrated lens edging capabilities.
Germany
Precision optics heritage and occupational safety regulations sustain demand for high-index and photochromic lenses. The EU Medical Device Regulation requires post-market surveillance systems that increase compliance overhead for CE-marked products. Munich anchors specialized retail chains serving Bavaria's industrial workforce.
India
Underpenetrated vision correction in tier-3 and tier-4 cities drives mobile eye-care platform expansion. The CDSCO regulates imported ophthalmic devices under Medical Device Rules that classify corrective eyewear by risk category. Surat in Gujarat clusters domestic frame fabrication serving price-sensitive mass markets.
Japan
Super-aging demographics and high myopia prevalence sustain premium progressive lens demand. METI promotes smart eyewear development through industrial technology grants targeting liquid crystal focal adjustment. Sabae in Fukui Prefecture retains global leadership in titanium frame manufacturing and precision metalworking.
Eyeglass Market Competitive Landscape
Listed leaders compete with private specialists across capital access and channel flexibility, producing a tiered structure where scale-driven conglomerates control lens technology while agile direct-to-consumer platforms capture digital-native demand. Vertically integrated ophthalmic giants command substrate manufacturing and retail access simultaneously. Independent optical labs and regional chains occupy mid-market positioning through personalized fitting services. Capacity consolidation and hybrid channel modernization represent the dominant competitive moves reshaping market boundaries.
Within the vertically integrated tier, EssilorLuxottica and Hoya exemplify archetypes combining lens substrate production with retail network control. Warby Parker occupies a position representing direct-to-native digital distribution that has forced incumbent channel modernization. These three anchors illustrate how competitive advantage now flows from either supply-chain captivity or consumer-platform agility rather than intermediate positioning.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Hoya |
| Cooper Companies |
| Bausch + Lomb |
| Fielmann |
| Warby Parker |
| National Vision Holdings |
| Safilo Group |
| Carl-Zeiss |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Medical Device Regulation gates both supplier qualification and price differentiation simultaneously, as manufacturers must maintain clinical evidence portfolios and vigilance systems that increase compliance overhead while creating tiered access for premium lens categories. This regulatory threshold concentrates pricing power with equipment-integrated manufacturers who can absorb documentation burdens, compressing margins for semi-finished distributors and independent labs that lack integrated surfacing capabilities.
Pricing Analysis
Volume-discount tiering structures separate EssilorLuxottica and Hoya's captive retail networks from independent optical labs competing on turnaround speed. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with high-index and photochromic lenses commanding premiums due to ISO 21987 compliance timelines. Cost compression in the mid-market is intensifying because freeform digital surfacing capabilities are concentrating with five-axis generator owners. Price-sensitive buyers cluster in India's tier-3 cities seeking basic CR-39 fulfillment, while least-sensitive purchasers in Japan and Germany prioritize progressive corridor optimization and personalized fitting services.
Supply Chain Analysis
Inventory lead times for high-index lens monomers have extended due to petrochemical feedstock volatility, forcing optical labs to hold larger safety stocks of polycarbonate and Trivex blanks. Manufacturing concentrates in Germany, Thailand, and China, with Danyang in Jiangsu Province anchoring domestic frame fabrication and integrated lens edging. Raw material dependencies rest on bisphenol-A derivatives for polycarbonate, thiourea for high-index formulations, and titanium feedstock from Fukui Prefecture. Single-source vulnerability concentrates in optical blank substrate production, where Thai and German manufacturing clusters create geographic supply risk for independent labs. Distribution runs through the Port of Shanghai for Asia-Pacific lens substrate imports, with Dallas-Fort Worth serving as the Southwest U.S. hub for independent lab fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring competitive boundaries as virtual try-on tools and tele-optometry platforms create new interoperability requirements between lens manufacturers, digital retailers, and eye-care providers. This ecosystem shift rewards either supply-chain captivity or consumer-platform agility, eliminating intermediate positioning for undifferentiated mid-market players.
For Market Incumbents: Shield high-margin progressive lens franchises by accelerating hybrid platform investments that match Warby Parker's digital-native fulfillment velocity. Prioritize backward integration into freeform surfacing equipment to maintain margin capture as five-axis generator adoption bifurcates the prescription market. Defensive consolidation should target independent optical labs in Germany and the United States facing ISO 21987 certification timeline pressures. For New Entrants and Emerging Players: Differentiate on tele-optometry-enabled rural penetration, targeting India's tier-3 and tier-4 cities where mobile eye-care platforms address underpenetrated vision correction needs. White-space opportunities concentrate in blue-light filtering specification upgrades for China's knowledge-worker population and smart lens convergence integrating liquid crystal focal adjustment technology. A direct-to-native digital distribution model with virtual try-on deployment offers the most penetrable go-to-market angle against incumbent channel modernization lags. For Investors and Strategic Acquirers: EU MDR harmonization reshapes the acquisition landscape by consolidating CE certificate holders among smaller manufacturers unable to maintain post-market surveillance systems. Long-term viability over the next decade hinges on positioning within either lens substrate manufacturing or retail network control, with mid-market independent labs facing structural compression. Target acquisition archetypes include specialized photochromic coating specialists with established clinical evidence portfolios and regional optical chains with captive edging capabilities in underserved U.S. Southwest markets. The signal to watch is FDA enforcement patterns on prescription verification friction for online fulfillment platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Freeform Digital Surfacing Investment | Five-axis generator adoption concentrates value capture with equipment-integrated manufacturers like Hoya. |
| Tele-Optometry Platform Expansion | Mobile eye-care platforms unlock India's tier-3 cities where licensed practitioner scarcity constrains retail growth. |
| Smart Lens Technology Development | Liquid crystal focal adjustment integration targets Japan's super-aging demographics through METI industrial grants. |
| Hybrid Channel Modernization | Virtual try-on deployment responds to millennial and Gen-Z cohorts displacing in-person frame selection. |
| Regulatory Certification Consolidation | EU MDR compliance overhead drives acquisition opportunities among smaller CE certificate holders in photochromic categories. |
Research Methodology
The analysis maps prescription lens substrates, frame manufacturing clusters, and retail distribution networks, each validated through optometrists, optical lab technicians, lens coating specialists, and retail chain procurement managers. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, NMPA GB standard registrations, EU MDR vigilance system disclosures, and customs trade data for ophthalmic lens blank imports. Bottom-up demand modeling across patient demographics and prescription renewal cycles triangulated with top-down value chain analysis of manufacturer revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks including hospital procurement databases for Medicare-covered vision benefits, GPO contracts for occupational safety eyewear, and independent optical lab association membership data. The analytical framework modeled product type, material composition, end-user demographics, and distribution channel segmentation across the projection horizon. CAGRs were derived from prescription renewal frequency patterns tied to aging demographics and screen-time exposure trends, with specific inputs including presbyopia prevalence curves and blue-light filtering specification upgrade rates among knowledge workers.
Material uncertainties — crude oil derivative volatility affecting polycarbonate monomer costs, optometrist workforce scarcity constraining same-day fulfillment, and regulatory enforcement shifts on online prescription verification — sit outside the modeled envelope. Forecasts reflect assumptions regarding channel modernization velocity and smart lens technology maturation without guaranteeing specific adoption timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Smart Eyewear Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
Latin America Eyewear Market
Eyewear
Europe Eyewear Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Middle East Eyewear Market
Eyewear
Anti-Fog Lens Market
Eyewear
Goggles Market
Eyewear
Eyewear Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Plano Sunglasses Market
Eyewear
North America Eyewear Market
Eyewear
Spectacles Market
Eyewear
Glasses Frame Market
Eyewear
Anti-Blue Light Glasses Market