
 Ultralight Eyeglass Frames Market | 2026-2036
Ultralight Eyeglass Frames Market Size, Share, and Industry Trends Forecast 2026-2036
Ultralight Eyeglass Frames Market Insights
Advanced CNC milling and 3D-printed titanium lattices are reshaping how ultralight frames achieve sub-8-gram weights without sacrificing structural integrity. Silhouette International leverages its Austrian manufacturing heritage to sustain premium rimless architectures. LINDBERG anchors Scandinavian design minimalism with screwless hinge engineering. Mykita competes through its in-house MYLON polyamide process, differentiating performance sport frames from conventional injection-molded alternatives.
Ultralight eyeglass frames are corrective and protective eyewear structures engineered below 15 grams total weight, typically employing beta-titanium alloys, carbon fiber composites, or high-performance polymers to distribute load across minimal surface contact. Their primary commercial purpose is reducing nasal bridge pressure and temporal fatigue during extended wear, critical for high-prescription lenses that amplify weight imbalance. Titanium material type dominates premium positioning due to its tensile strength-to-density ratio and hypoallergenic properties, while carbon fiber commands athlete targeting through vibration damping and sweat corrosion resistance. Rimless frame style occupies the fastest-growing structural slot as lens mounting hardware miniaturization advances, though full rim retains margin depth through fashion-forward acetate-titanium hybrids.
Europe's ECHA enforces REACH substance restrictions that limit cadmium and nickel leaching from metal alloys in prolonged skin contact, directly elevating certified titanium sourcing costs. The FDA in the United States classifies prescription eyewear as Class I medical devices, mandating biocompatibility testing that shapes import qualification timelines for Asian manufacturers. Japan's METI promotes JIS standards for optical product durability, creating technical barriers that domestic brands like JINS navigate with localized supply chains. Stakeholders must monitor how evolving extended producer responsibility frameworks for plastic waste alter material selection roadmaps across carbon fiber and petroleum-based polymer segments.
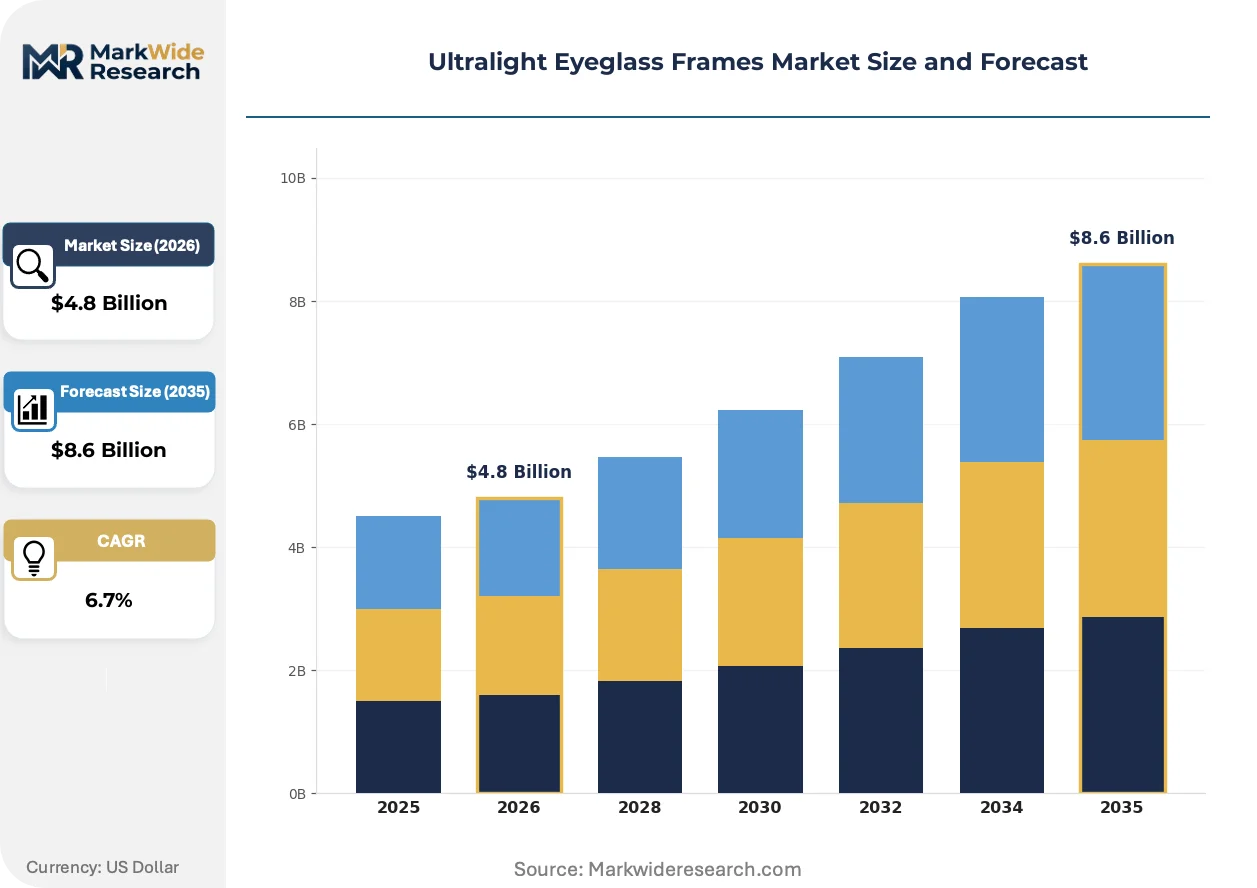
Market Dynamics
Myopia prevalence among East Asian school-age children is accelerating prescription volumes for sub-15-gram frames that reduce nasal bridge pressure during extended study hours. This demographic compression is forcing manufacturers to recalibrate material selection and regional distribution priorities.
Growth Catalysts
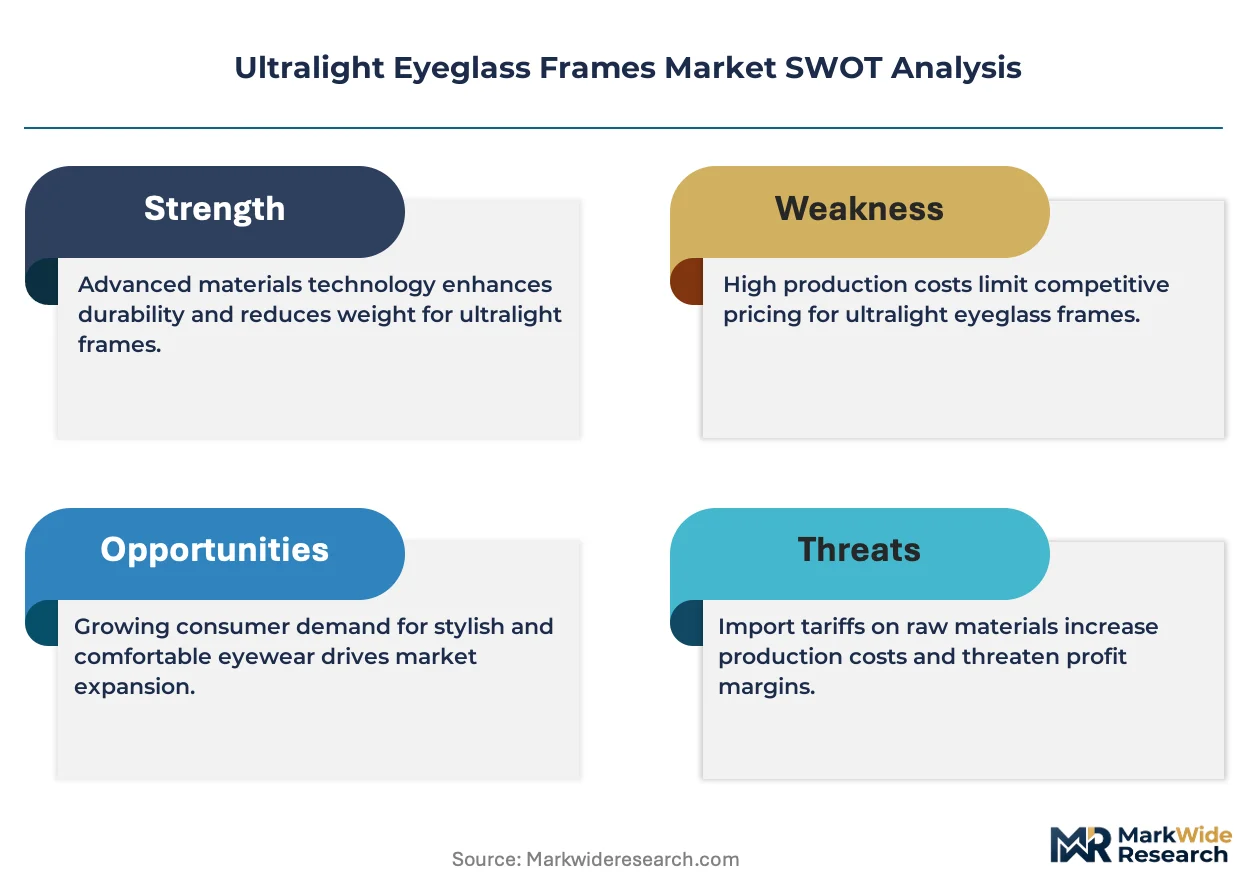
- REACH Substance Restrictions:ECHA enforcement of nickel and cadmium leaching limits in Europe is elevating certified titanium sourcing requirements, pulling premium alloy demand upward.
- Carbon Fiber Vibration Damping:Athlete-targeting frames exploit sweat corrosion resistance and load distribution properties that beta-titanium cannot replicate in high-motion environments.
- Japan's Urban Optometry Chains:METI-backed JIS durability standards and localized supply chains enable domestic brands to capture all-day comfort positioning in dense metropolitan markets.
Market Restraints
- Titanium Input Cost Volatility:Sponge titanium pricing fluctuations and certified alloy scarcity compress margin structures for mid-tier manufacturers dependent on spot-market sourcing.
- Injection-Molding Equipment Concentration:High-performance polymer frame production clusters in specialized German and Austrian machining centers, creating geographic supply vulnerability.
- Rimless Hardware Miniaturization Limits:Lens mounting component tolerances below 0.1mm require precision tooling that few Asian contract manufacturers can sustain at scale.
Strategic Opportunities
- India's Corrective Lens Penetration:BIS optical product standards and rising myopia diagnosis rates in tier-2 cities create whitespace for ultralight frame introduction.
- 3D-Printed Titanium Lattice Convergence:CNC milling integration with additive manufacturing enables patient-specific bridge geometry without mold tooling overhead.
- Direct-to-Consumer Channel Expansion:Virtual try-on platforms and prescription lens bundling bypass traditional optometry gatekeepers in North American markets.
Industry Challenges
- Biocompatibility Certification Timelines:FDA Class I medical device testing protocols for Asian manufacturers extend import qualification windows by 8-14 months.
- Extended Producer Responsibility Friction:EU plastic waste frameworks for petroleum-based polymers and carbon fiber segments force material roadmap reconfiguration without clear recycling infrastructure.
- Screwless Hinge Engineering Talent Scarcity:LINDBERG-style monoblock construction requires specialized metallurgical expertise concentrated in Scandinavian and Austrian labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultralight Eyeglass Frames Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Titanium, Aluminum, Carbon Fiber, Plastic Frame Style: Full Rim, Semi-Rimless, Rimless, Cat-Eye Target Customer: Men, Women, Children, Athletes Distribution Channel: Online Retail, Optical Stores, Specialty Shops, Supermarkets |
| Companies Covered | Silhouette International, LINDBERG, JINS, Rodenstock, Flexon, ZEISS, ZENNI OPTICAL, Skaga, Mykita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultralight Eyeglass Frames Market Trends and Innovations
Additive manufacturing is collapsing the traditional trade-off between frame weight reduction and structural load capacity. This technological inflection is redrawing competitive boundaries between heritage European manufacturers and Asian contract producers.
3D-printed titanium lattice structures is rendering obsolete the conventional stamped-sheet beta-titanium production methods that dominated rimless architecture for three decades. Japanese urban optometry chains are adopting patient-specific bridge geometries at 18-month replacement cycles. The technology is compressing batch-size economics and enabling micro-lot customization without mold tooling amortization.
ECHA REACH Annex XVII nickel release restrictions are forcing alloy reformulation across European-bound production lines. Manufacturers must recertify biocompatibility documentation for revised titanium-vanadium compositions. Full-rim acetate-titanium hybrids face elevated testing costs that rimless pure-titanium architectures avoid.
Virtual prescription verification and home try-on logistics are displacing traditional optometry channel gatekeeping in North American distribution. Direct-to-consumer platforms bundle lens edging with frame selection, capturing margin that previously flowed to independent retailers. This channel compression is most visible in California and New York metro corridors where digital-native consumers prioritize convenience over fitting-room consultation.
Ultralight Eyeglass Frames Market Segmentation
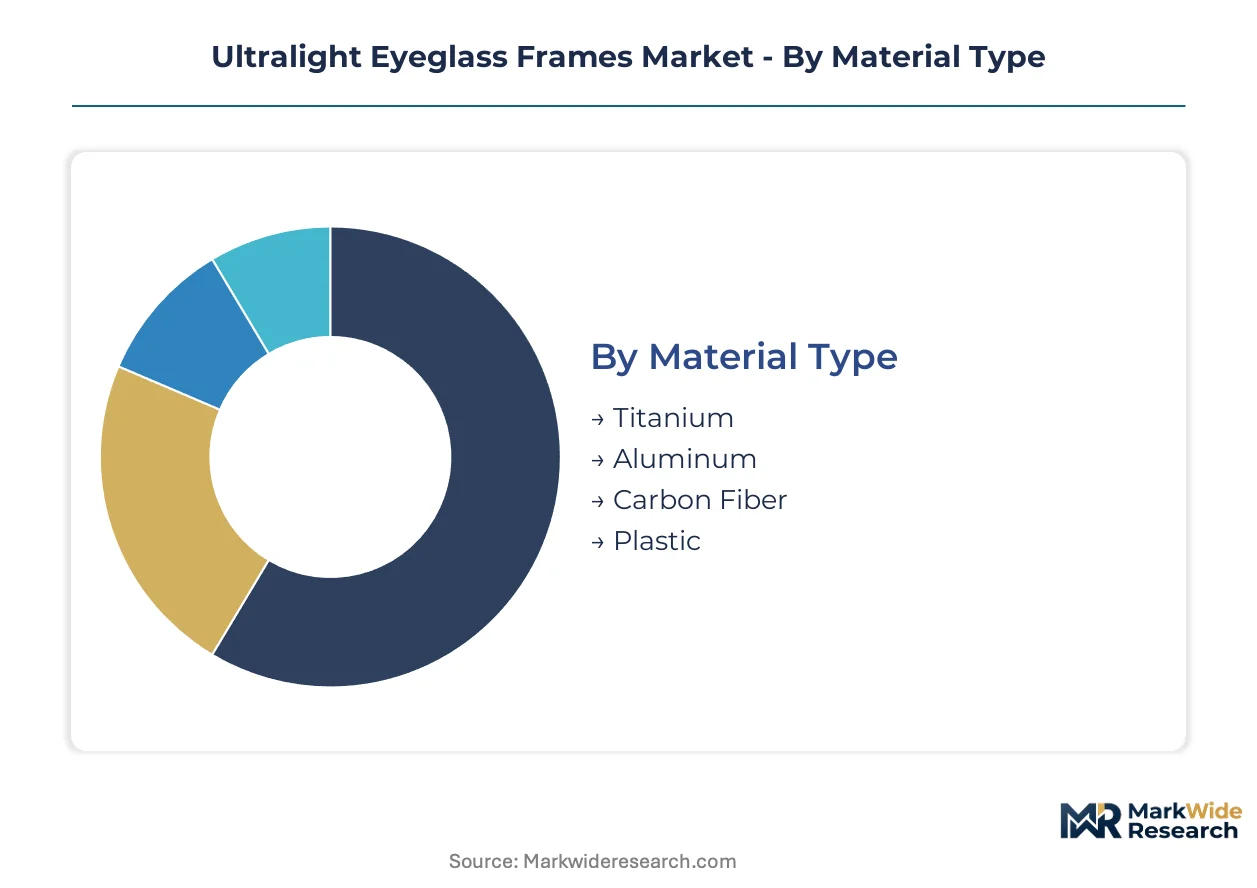
Ultralight frame manufacturers must navigate divergent material cost structures, prescription complexity thresholds, and channel margin economics simultaneously. Segmentation reveals where premium alloy sourcing concentrates versus where injection-molded polymer volumes scale.
Material Type:
Mature titanium architectures coexist with emerging carbon fiber composites as manufacturers balance tensile performance against biocompatibility certification burdens.
- Titanium:Beta-titanium alloys deliver tensile strength-to-density ratios above 800 MPa per g/cm³, enabling sub-8-gram rimless constructions. Austrian and Japanese manufacturers dominate certified sponge sourcing for European REACH compliance, absorbing elevated alloy premiums that mid-tier competitors cannot pass through.
- Carbon Fiber:Woven pre-preg laminates with thermoset epoxy matrices damp vibration frequencies that metal frames transmit to the mastoid bone. Athlete-targeting lines exploit this property in marathon and cycling segments where sweat corrosion resistance separates performance tiers.
- Aluminum:7000-series aerospace grades offer intermediate density between titanium and polymer, though anodization requirements for skin-contact biocompatibility limit European market access.
- Plastic:High-performance polyamides and acetate derivatives injection-mold at scale for price-sensitive prescription volumes, constrained by ECHA plasticizer restrictions under REACH Annex XVII.
Titanium handles the majority of throughput; carbon fiber is climbing the fastest on share as sports positioning expands beyond traditional eyewear channels.
Frame Style:
Structural load distribution requirements vary sharply across rim architectures, driving divergent tooling investments and lens mounting precision thresholds.
- Rimless:Miniaturized lens mounting hardware below 0.1mm tolerances eliminates frame perimeter weight entirely. Japanese urban optometry chains and Austrian heritage manufacturers control the precision tooling capacity that Asian contract producers struggle to replicate at volume.
- Full Rim:Acetate-titanium hybrid constructions retain fashion-forward positioning through color layering and temple sculpting, though REACH nickel-release testing adds certification overhead that pure-titanium rimless avoids.
- Semi-Rimless:Nylon cord suspension of the lower lens perimeter reduces material mass by 30-40% versus full rim while preserving structural security for moderate prescriptions.
- Cat-Eye:Retro-feminine styling with upswept temporal edges concentrates in premium Italian and French design houses, limiting volume scalability due to hand-finishing requirements.
Full Rim commands current volume leadership; Rimless shows steepest expansion trajectory as lens edging automation and hardware miniaturization advance.
Target Customer:
Demographic-specific facial anthropometry and wear-duration patterns dictate bridge width, temple pressure, and weight tolerance specifications.
- Children:East Asian myopia prevalence drives demand for sub-15-gram daily-wear frames that reduce nasal bridge pressure during extended study hours. METI-backed JIS durability standards in Japan favor domestic supply chains for this segment.
- Athletes:Sweat corrosion resistance and grip-enhancing temple coatings prioritize carbon fiber and beta-titanium over standard alloys, with distribution concentrating in specialty running and cycling retail.
- Men:Wider bridge widths and longer temple arms require adjusted moment-arm calculations for weight distribution, favoring titanium's stiffness-to-weight ratio.
- Women:Narrower facial geometry and fashion-forward color preferences drive acetate-titanium hybrid demand in full-rim configurations.
Children's frames absorb the largest prescription volume flows; Athletes represent the fastest share gain as performance eyewear crosses into mainstream fitness positioning.
Distribution Channel:
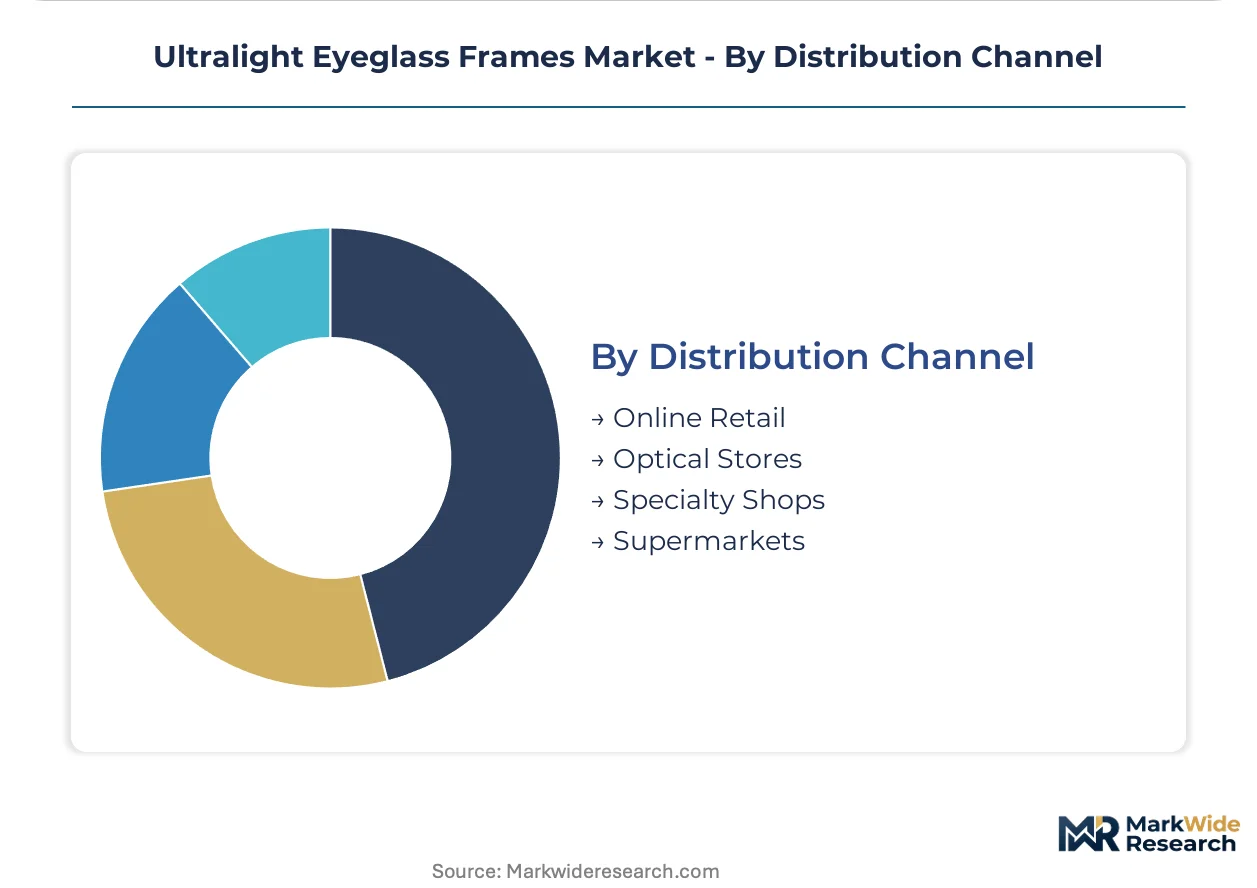
Channel selection determines margin capture, fitting service intensity, and prescription lens bundling economics.
- Optical Stores:Independent and chain optometrists control prescription verification and pupillary distance measurement, capturing bundled lens-edging margins that frame manufacturers cannot access directly.
- Online Retail:Virtual try-on platforms and home fitting kits displace traditional gatekeepers in North American metro corridors, though FDA Class I medical device compliance extends Asian manufacturer qualification timelines.
- Specialty Shops:Running, cycling, and outdoor retailers stock athlete-targeting carbon fiber lines with sport-specific temple grip technologies, bypassing prescription verification for plano sunglass configurations.
- Supermarkets:Mass-market readers and basic prescription frames at entry price points, limited by inventory depth and professional fitting absence.
Optical Stores retain volume dominance; Online Retail is gaining share fastest where virtual prescription verification and logistics infrastructure mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in ultralight eyeglass frames tilt toward European heritage manufacturers supplying Asian premium retail, while Japanese domestic brands capture localized myopia-driven volumes through METI-backed supply chain integration.
Japan
Urban optometry chains in Tokyo and Osaka drive prescription volumes for sub-15-gram daily-wear frames among school-age children facing intensive study schedules. METI enforces JIS standards for optical product durability, creating technical barriers that domestic brands navigate through captive titanium sourcing. Nagoya's precision machining cluster supplies screwless hinge components to rimless frame assemblers serving the Kanto metropolitan corridor.
Germany
Austrian-German machining centers concentrate injection-molding equipment for high-performance polymer frames, exporting rimless hardware across European markets. ECHA REACH Annex XVII restricts nickel release from metal alloys, elevating certified titanium documentation requirements for Bavarian manufacturers. Munich's design houses anchor premium acetate-titanium hybrid production for fashion-forward full-rim positioning.
United States
Direct-to-consumer platforms in California and New York metro corridors displace traditional optometry gatekeeping through virtual prescription verification and home try-on logistics. FDA Class I medical device classification mandates biocompatibility testing that extends Asian manufacturer qualification timelines. Los Angeles-based fulfillment networks bundle lens edging with frame selection, capturing margin previously flowing to independent retailers.
China
Dongguan and Shenzhen contract manufacturers supply beta-titanium stampings to European heritage brands while facing precision tolerance limits below 0.1mm for rimless hardware miniaturization. GB standards for eyewear safety shape domestic production specifications, though REACH compliance documentation gaps restrict direct European market access. Yangtze River Delta optical clusters specialize in mid-tier injection-molded polymer volumes for price-sensitive export markets.
India
Tier-2 cities including Pune and Hyderabad exhibit rising myopia diagnosis rates creating whitespace for ultralight frame introduction at corrective lens penetration points. BIS optical product standards govern import qualification, though enforcement capacity varies across state-level regulatory implementations. Mumbai's specialty retail corridors test direct-to-consumer bundling models adapted from North American virtual platforms.
Ultralight Eyeglass Frames Market Competitive Landscape
On the supply side, the industry is bifurcated between heritage European manufacturers commanding certified titanium premiums and Asian contract producers scaling polymer injection-molded volumes. Austrian and Japanese fabricators anchor the precision tooling tier for rimless hardware below 0.1mm tolerances, while Chinese and Vietnamese assemblers compete on mid-tier beta-titanium stampings. Strategic moves concentrate on additive manufacturing licensing for patient-specific bridge geometries and backward integration into certified sponge titanium sourcing.
Within the heritage premium tier, Silhouette International and LINDBERG occupy positions defined by regional manufacturing heritage and screwless hinge engineering specialization. Mykita exemplifies the performance-sport convergence through proprietary polymer processing capabilities distinct from conventional injection molding. JINS anchors the Asia-Pacific localization archetype through METI-aligned supply chain integration and rapid replacement cycle positioning in Japanese urban optometry channels.
| Leading Market Players |
|---|
| Silhouette International |
| LINDBERG |
| JINS |
| Rodenstock |
| Flexon |
| ZEISS |
| ZENNI OPTICAL |
| Skaga |
| Mykita |
| Others |
Pricing and Supply Chain Analysis
Nagoya's precision machining cluster supplies screwless hinge components that command 40-60% gross margins for rimless frame assemblers, compressing pricing power for downstream brands dependent on spot-market titanium sourcing. This geographic concentration of precision tooling capacity allows Austrian and Japanese heritage manufacturers to sustain premium positioning while Asian contract producers absorb margin pressure from sponge titanium volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with beta-titanium alloys certified for ECHA REACH nickel-release compliance commanding substantial premiums over uncertified spot-market alternatives. Price differentiation hinges on alloy certification grade and volume scale, with batch-size economics below 500 units triggering 25-35% per-unit uplifts. Cost compression in mid-tier polymer frames is intensifying because injection-molding equipment scarcity in German and Austrian machining centers limits supply expansion. Mass-market optical chains exhibit highest price sensitivity, while Japanese urban optometry chains serving myopic children show lowest sensitivity due to replacement cycle frequency and comfort-driven purchasing.
Supply Chain Analysis
Export-control restrictions on precision CNC milling equipment and additive manufacturing systems limit technology transfer to Asian contract manufacturers, constraining rimless hardware miniaturization capacity outside Austrian and Japanese production clusters. Supply concentrates in Japan, Germany, and Austria for certified titanium sponge and precision tooling, while China and Vietnam dominate mid-tier beta-titanium stampings and polymer injection molding. Raw material dependencies include sponge titanium from Japanese and Russian smelters, high-performance polyamides from German chemical producers, and carbon fiber pre-preg from Japanese and American suppliers. Single-source vulnerability concentrates in screwless hinge metallurgical expertise anchored in Scandinavian and Austrian labor pools. Distribution runs through independent optometry chains and direct-to-consumer platforms, with the latter capturing growing share in North American metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around Japanese urban optometry chains and North American direct-to-consumer platforms, compressing frame manufacturers' margin capture and forcing supply chain reconfiguration toward captive titanium sourcing and virtual fitting infrastructure.
For Market Incumbents: Pre-empt precision tooling lock-in by securing exclusive additive manufacturing licensing for patient-specific bridge geometries before Asian contract producers achieve 0.1mm tolerance replication. Defend against direct-to-consumer platform disintermediation by integrating virtual prescription verification into owned channels, while backward integration into certified sponge titanium sourcing insulates margin structures from alloy spot-market volatility. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 cities where rising myopia diagnosis rates and nascent BIS optical product enforcement create whitespace for ultralight frame introduction. Target corrective lens penetration points in Pune and Hyderabad with price-positioned beta-titanium offerings, leveraging direct-to-consumer bundling models adapted from North American virtual platforms to bypass traditional optical store gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials play because patient-specific additive manufacturing and certified alloy scarcity will concentrate value capture in precision fabrication rather than brand marketing. Acquisition targets should exhibit captive titanium sourcing, additive manufacturing licensing, or screwless hinge engineering talent. The signal to watch is FDA clearance timelines for Asian manufacturers, which would signal supply-side expansion and margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Titanium Sourcing | Captive sponge supply from Japanese or Austrian smelters insulates margin against spot-market volatility and REACH compliance documentation gaps. |
| Additive Manufacturing Licensing for Lattice Structures | 3D-printed titanium bridge geometries enable micro-lot customization without mold tooling amortization, collapsing batch-size economics. |
| Direct-to-Consumer Channel Expansion | Virtual try-on platforms with prescription lens bundling capture margin previously flowing to independent optometry retailers in California and New York corridors. |
| Scandinavian Hinge Engineering Talent Acquisition | LINDBERG-style monoblock construction expertise remains concentrated in Austrian and Scandinavian labor pools, creating competitive moat. |
| India Market Entry with BIS-Aligned Production | Tier-2 city whitespace in Pune and Hyderabad offers first-mover positioning as myopia prevalence rises and corrective lens penetration deepens. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade data, and patent databases, with optometry chain procurement directors, titanium alloy metallurgists, and precision machining equipment suppliers providing ground-truth validation. Secondary sources include ECHA REACH substance restriction updates, FDA Class I medical device classification guidance, METI JIS standard documentation, and Japanese optical product import statistics. Bottom-up demand modeling from prescription volume flows and top-down supply assessment from certified titanium production capacity were cross-referenced to establish market sizing boundaries.
Forecast inputs span material type segmentation across titanium, carbon fiber, and polymer architectures; frame style categories from rimless to full-rim configurations; and distribution channel dynamics between optical stores and direct-to-consumer platforms. CAGRs were derived from elasticity-adjusted prescription volume projections and replacement cycle compression trends, with additive manufacturing adoption curves and ECHA regulatory enforcement intensity serving as scenario variables across the projection horizon.
Stress conditions across sponge titanium price volatility, FDA clearance timeline extensions for Asian manufacturers, and EU extended producer responsibility framework implementation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding myopia prevalence trajectories and precision tooling capacity expansion. Material shifts in REACH nickel-release limit stringency or additive manufacturing equipment export control relaxation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Smart Sunglasses Market
Eyewear
Sunglasses Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Smart Eyewear Market
Eyewear
Blue Light Glasses Market
Eyewear
Spectacles Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Luxury Sunglass Market
Eyewear
Polarized Sunglasses Market
Eyewear
Middle East Eyewear Market
Eyewear
Eyewear Market
Eyewear
Latin America Eyewear Market
Eyewear
Glasses Frame Market
Eyewear
Sunglasses Pouch Market