
 Europe Eyewear Market | 2026-2036
Europe Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Eyewear Market Intelligence
The EU Green Deal is rebalancing material specifications across European eyewear supply chains, compelling manufacturers to phase out virgin petroleum-based plastics in favor of recycled and bio-derived alternatives. EssilorLuxottica leverages its integrated lens-and-frame manufacturing footprint to control material flows from polymer sourcing through finished goods. Safilo Group anchors its Italian production network with specialized acetate molding capabilities that serve premium house brands. Fielmann AG competes through vertically owned retail chains spanning Germany into Austria and Switzerland.
Eyewear comprises vision-correcting and protective devices constructed from injection-molded thermoplastics, machined acetate, stamped metal alloys, or cast glass, with optical power measured in diopters and UV protection rated by transmission percentage. Prescription glasses dominate value generation due to recurring lens replacement cycles and progressive addition lens upgrades among aging wearers. Contact lenses represent the fastest-growing product type as silicone hydrogel materials extend daily wear duration and comfort thresholds. Metal frames command premium positioning in optical stores, while plastic materials sustain volume leadership through cost-accessible fashion sunglasses.
EMA device regulations govern contact lens biocompatibility testing, while REACH restricts phthalate plasticizers in frame polymers and CE marking mandates impact resistance for sports eyewear. The EU AI Act introduces compliance layers for smart glasses incorporating facial recognition or health-monitoring sensors. Stakeholders must monitor how ECHA substance-of-very-high-concern listings reshape acetate chemistry and whether national reimbursement authorities expand myopia-control lens coverage for children.
Market Dynamics
The EU Green Deal is forcing material recalibration across European eyewear supply chains, compelling manufacturers to replace virgin petroleum-based plastics with recycled polymers and bio-derived acetates sourced within continental recycling networks.
Growth Catalysts
- REACH substance restrictions:Phasing out phthalate plasticizers in frame polymers accelerates migration toward bio-acetate formulations certified by ECHA, opening premium positioning for compliant manufacturers.
- Silicone hydrogel materials:Extended daily wear duration in contact lenses drives replacement cycle compression among working-age professionals seeking all-day comfort without removal.
- Germany's reimbursement density:Statutory health insurance frameworks covering progressive addition lenses sustain higher prescription renewal rates than neighboring markets with partial or no optical subsidies.
Market Restraints
- Acetate supply concentration:Italian and Chinese molding specialists control premium cellulose acetate sheet production, creating input bottlenecks for mid-tier frame assemblers without captive polymer sourcing.
- EMA biocompatibility testing timelines:Extended pre-market authorization protocols for silicone hydrogel contact lenses delay product launches by 18-24 months versus conventional hydrogel approvals.
- Direct-to-consumer online refraction:Tele-optometry platforms in the United Kingdom and Netherlands bypass traditional optical retail, compressing margin capture for brick-and-mortar chains dependent on exam-tied frame sales.
Strategic Opportunities
- Poland's underpenetrated optical retail:Low optician density per capita relative to Western European benchmarks creates whitespace for chains offering bundled exam-and-frame packages at mid-market price points.
- CSRD supply-chain disclosure mandates:Mandatory sustainability reporting for large EU enterprises creates certified demand for traceable bio-acetate and recycled ocean plastic frames with documented carbon footprints.
- Smart glasses convergence:Integration of prescription optics with AR displays and health-monitoring sensors opens medical-device reimbursement pathways distinct from fashion eyewear categories.
Industry Challenges
- Optical dispensing skill scarcity:Qualified optometrists and dispensing opticians face recruitment gaps in Southern European markets where vocational training pipelines have contracted over two decades.
- CE marking complexity for sports eyewear:Impact resistance testing protocols under EU Personal Protective Equipment regulations require specialized laboratory partnerships that smaller frame designers cannot access cost-effectively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Eyewear Market |
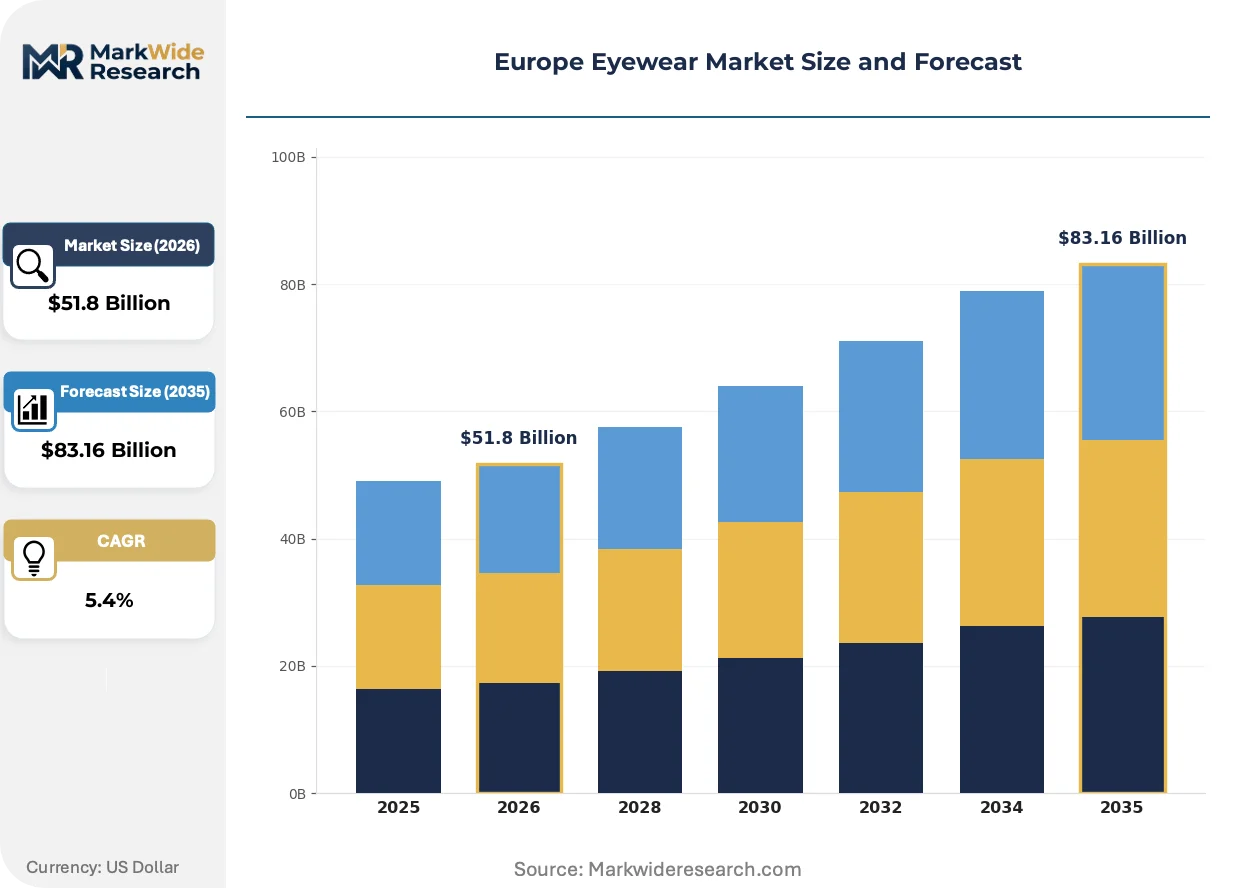
| Market Size in 2026 | $51.8 Billion |
| Market Size in 2035 | $83.16 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunglasses, Prescription Glasses, Contact Lenses, Sports Eyewear Material: Plastic, Metal, Glass, Nylon Distribution Channel: Online Retail, Optical Stores, Supermarkets, Pharmacies End User: Adults, Children, Seniors, Athletes |
| Companies Covered | De Rigo Vision, EssilorLuxottica, Luxottica Group, Johnson & Johnson Vision, Alcon, Safilo Group, Marchon Eyewear, HOYA Corporation, Fielmann AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Eyewear Market Strategic Shifts & Innovations
Digital refraction technologies and sustainable material chemistry are restructuring how European consumers access vision correction and how manufacturers qualify for public procurement contracts.
Freeform lens surfacing is overtaking traditional molded progressive addition lenses in independent optical practices across Germany and Austria. This computer-controlled diamond-point technology enables personalized corridor positioning based on individual frame fit and visual behavior. Practices investing in in-house edging equipment capture higher margin per prescription by reducing wholesale lens dependency.
REACH authorization requirements for titanium dioxide nanoparticles in UV-blocking coatings are compelling lens manufacturers to reformulate hardcoat chemistries or seek alternative UV absorbers. ECHA's 2022 classification of TiO2 as a suspected carcinogen by inhalation has triggered supply-chain audits affecting anti-reflective coating subcontractors in France and Italy. Large integrated manufacturers with internal polymer labs are accelerating transition to organic UV stabilizers ahead of sunset dates.
Subscription-based contact lens replenishment is displacing annual supply purchases in Nordic markets where postal infrastructure supports predictable home delivery cadences. Younger wearers in Sweden and Denmark prefer monthly billing aligned with salary cycles over upfront payments for 90-day lens packs. Retailers responding with auto-renewal platforms are capturing higher lifetime value per subscriber while reducing inventory carrying costs.
Europe Eyewear Market Segmentation
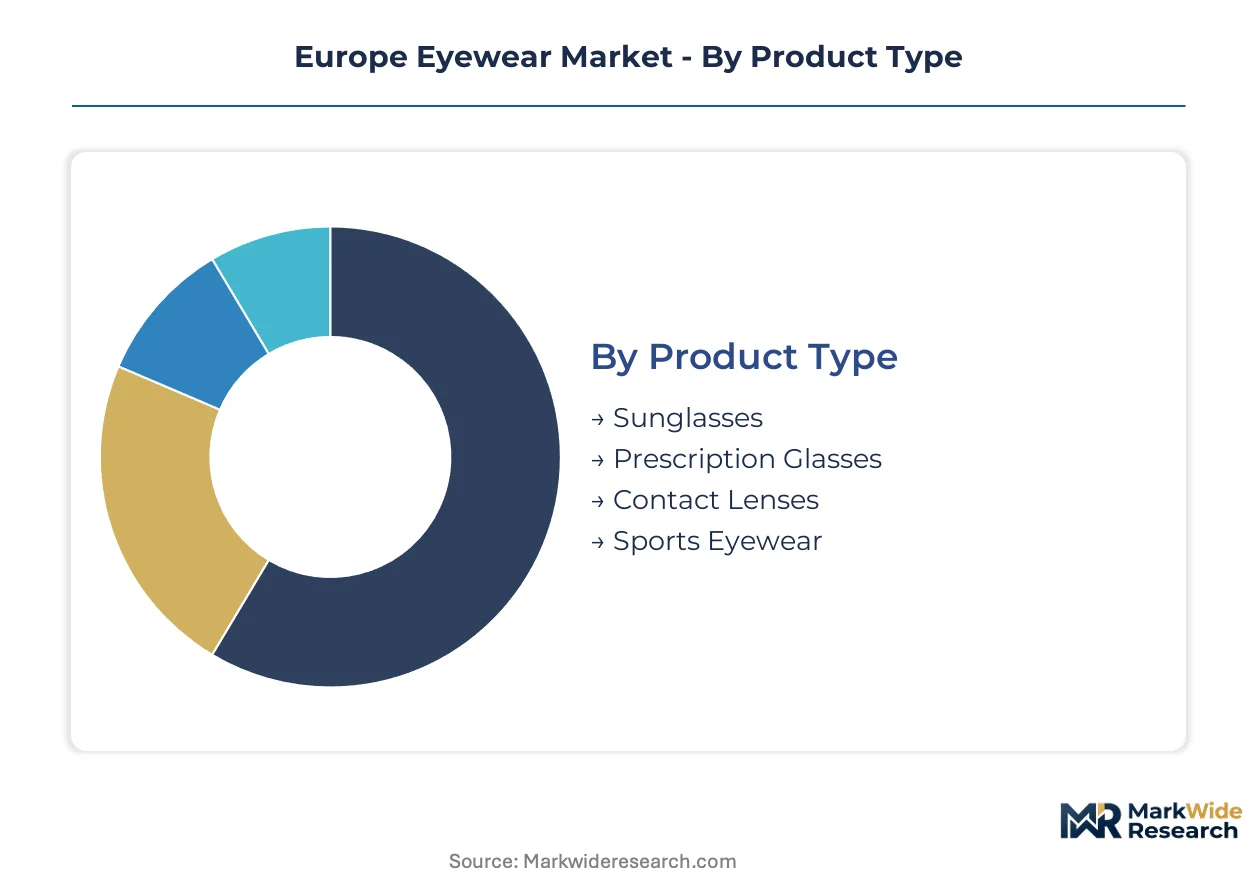
Segmentation in European eyewear reveals how replacement cycles, material regulations, and reimbursement structures concentrate value across distinct product categories. Understanding these divisions exposes where manufacturers capture recurring revenue versus one-time purchases.
Product Type:
Replacement-cycle intensity varies dramatically across vision-correction modalities, with lens upgrade frequency and frame durability creating divergent revenue profiles for manufacturers.
- Prescription Glasses:Progressive addition lens upgrades among aging populations in Germany and Austria drive recurring revenue through 24-36 month replacement cadences. Statutory reimbursement frameworks sustain higher renewal rates than self-pay markets, concentrating manufacturer investment in freeform surfacing capabilities.
- Contact Lenses:Silicone hydrogel materials extend daily wear duration to 16+ hours, compressing replacement cycles among working-age professionals seeking all-day comfort. Nordic subscription models displace annual supply purchases with monthly auto-renewal platforms.
- Sunglasses:Fashion-driven purchases concentrate in Italy and Spain with seasonal peaks tied to tourism flows.
- Sports Eyewear:CE marking mandates under EU Personal Protective Equipment regulations restrict market entry to manufacturers with certified impact-testing partnerships.
Volume placements concentrate in Prescription Glasses; the faster expansion belongs to Contact Lenses.
Material:
REACH substance restrictions and EU Green Deal procurement mandates are rebalancing material specifications toward certified sustainable alternatives with documented supply-chain footprints.
- Plastic:Injection-molded thermoplastics and cellulose acetate dominate frame production, with bio-derived acetates from Italian molding specialists commanding premium positioning. ECHA phthalate restrictions accelerate migration toward certified bio-acetate formulations.
- Metal:Titanium and stainless steel alloys anchor premium optical retail positioning in German and Swiss markets, with higher material costs offset by extended durability and hypoallergenic properties.
- Glass:Cast mineral lenses persist in specialized high-index applications despite weight penalties.
- Nylon:TR-90 and polyamide variants serve sports and children's segments requiring flexibility and impact resistance.
Cost-accessible volume flows through Plastic; Metal captures the steepest margin expansion trajectory.
Distribution Channel:
Channel selection determines margin capture, with exam-tied dispensing sustaining higher price realization than self-directed online purchases.
- Optical Stores:Vertically owned chains in Germany and independent practices in Austria leverage in-house edging equipment to reduce wholesale lens dependency. Bundled exam-and-frame packages sustain margin per transaction through professional fitting services.
- Online Retail:Tele-optometry platforms in the United Kingdom and Netherlands bypass traditional retail, compressing margins for brick-and-mortar chains dependent on exam-tied sales.
- Supermarkets:Limited to pre-assembled reading glasses and basic sunglasses with minimal service attachment.
- Pharmacies:Contact lens replenishment and lens care solutions in markets with pharmacist dispensing authority.
Transaction volume aggregates in Optical Stores; Online Retail is climbing the fastest.
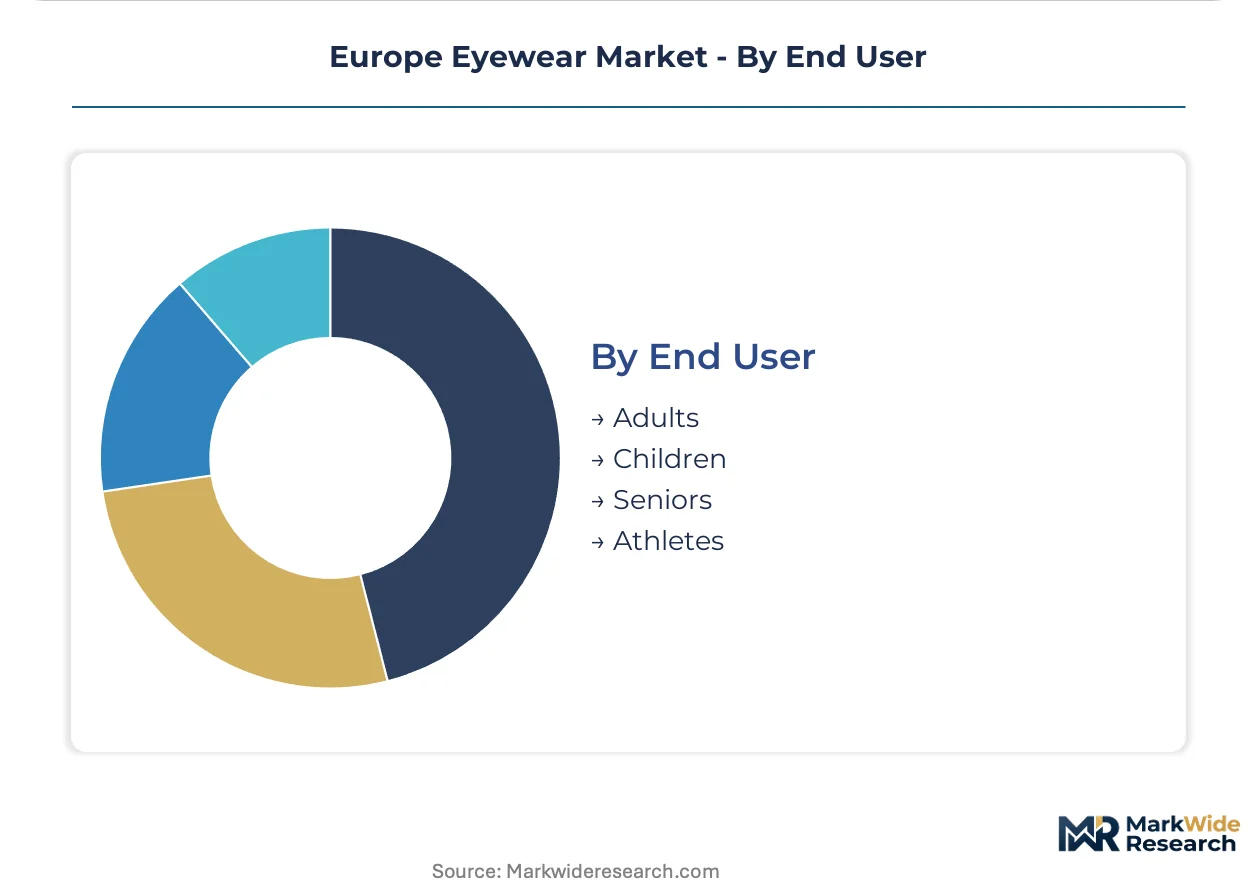
End User:
Aging demographics across the continent are expanding the senior cohort while myopia prevalence drives pediatric demand for specialized correction.
- Seniors:Progressive lens upgrades and multifocal contact lens adoption accelerate with presbyopia onset, with German statutory insurance sustaining higher penetration than Southern European self-pay markets.
- Adults:Working-age professionals balance comfort demands with occupational screen-time requirements, driving silicone hydrogel contact lens and blue-light filtering spectacle lens adoption.
- Children:Myopia-control lenses and specialized frame durability requirements create distinct product specifications.
- Athletes:Impact-rated sports eyewear with prescription inserts serves cycling and winter sports communities in Alpine regions.
Adult users anchor current volume; Seniors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agordo anchors Italian eyewear manufacturing through specialized acetate molding corridors that supply premium frame producers across the continent. German optical retail density and reimbursement frameworks concentrate value capture in Central European markets. REACH substance restrictions and CSRD disclosure mandates reshape material sourcing from Milan to Paris.
Germany
Statutory health insurance frameworks covering progressive addition lenses sustain prescription renewal rates exceeding Southern European benchmarks. The KBA monitors product safety standards for automotive-tinted prescription lenses used by professional drivers. Berlin-Brandenburg hosts tele-optometry startups challenging traditional exam-and-frame bundling.
Italy
Fashion-driven sunglasses purchases concentrate in Lombardy and Veneto with seasonal peaks tied to Milan Fashion Week and summer tourism flows. REACH phthalate restrictions accelerate bio-acetate adoption among Belluno-based frame specialists. Agordo and Cadore valleys maintain captive acetate sheet production serving luxury house brands.
France
ANSM oversees contact lens biocompatibility testing protocols that extend pre-market timelines for silicone hydrogel innovations. The Île-de-France region concentrates independent optical practices investing in freeform lens surfacing equipment. CSRD supply-chain disclosure mandates drive procurement shifts toward traceable recycled ocean plastic frames.
United Kingdom
Tele-optometry platforms in England and Wales bypass traditional optical retail, compressing margin capture for exam-dependent brick-and-mortar chains. The MHRA regulates smart glasses incorporating health-monitoring sensors under emerging medical device pathways. London anchors direct-to-consumer online refraction services displacing annual supply purchases.
Poland
Low optician density per capita relative to Western European benchmarks creates whitespace for chains offering bundled exam-and-frame packages. The country's national pharmaceutical regulator aligns contact lens distribution with pharmacist dispensing authority in urban centers. Warsaw and Krakow concentrate emerging optical retail investment targeting mid-market price positioning.
Europe Eyewear Market Key Industry Players
Premium-margin players sit above commodity-margin players across material certification and reimbursement access dimensions. The vendor base organizes around integrated lens-and-frame manufacturers, specialized acetate molders, and vertically owned retail chains. Three archetypes dominate: full-stack producers controlling polymer sourcing through finished goods, premium frame specialists leveraging Italian manufacturing heritage, and exam-tied retailers capturing recurring lens replacement revenue. Competitive moves concentrate on bio-acetate certification racing and freeform surfacing equipment deployment.
Among Italy-based fabricators, Safilo Group and De Rigo Vision exemplify premium frame specialization anchored in Veneto production networks. EssilorLuxottica occupies a position spanning integrated manufacturing and retail control. Fielmann AG represents the exam-tied retail archetype with backward integration into lens edging and frame distribution.
| Leading Market Players |
|---|
| De Rigo Vision |
| EssilorLuxottica |
| Luxottica Group |
| Johnson & Johnson Vision |
| Alcon |
| Safilo Group |
| Marchon Eyewear |
| HOYA Corporation |
| Fielmann AG |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap acetate molders in Italy's Veneto region anchor premium frame pricing through captive polymer sourcing, while German statutory reimbursement frameworks insulate prescription lens markets from direct-to-consumer price erosion.
Pricing Analysis
Reimbursement-tied pricing anchors the European eyewear market, with German statutory health insurance frameworks covering progressive addition lenses sustaining higher renewal rates than self-pay Southern European markets. Price differentiation rests on certification grade—ECHA-compliant bio-acetate formulations command premium positioning over phthalate-containing alternatives—and vertical integration depth, where in-house edging capabilities reduce wholesale lens dependency. Cost compression in mid-tier plastic frames intensifies as REACH substance restrictions accelerate material reformulation expenses. Price-sensitive buyers cluster in online retail channels bypassing exam-tied dispensing, while least-sensitive segments occupy premium optical stores bundling professional fitting services.
Supply Chain Analysis
Single-source vulnerability sits with Italian and Chinese cellulose acetate sheet specialists controlling premium molding inputs for European frame assemblers. Geographic supply concentration centers on Italy for bio-acetate formulations, Germany for freeform lens surfacing equipment, and China for injection-molded thermoplastic components. Raw material dependencies hinge on petroleum-derived polymers, titanium alloys for hypoallergenic frames, and silicone hydrogel monomers for extended-wear contact lenses. Tariff exposure on Chinese optical components threatens margin structures for mid-tier frame designers lacking captive polymer sourcing. Distribution runs through vertically owned optical chains in Germany and Austria, independent practices investing in in-house edging, and tele-optometry platforms displacing traditional exam-and-frame bundling in the United Kingdom and Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European eyewear is consolidating around integrated manufacturers controlling material certification and reimbursement access, with REACH substance restrictions and CSRD disclosure mandates forcing smaller frame assemblers toward acquisition or exit.
For Market Incumbents: Hedge against direct-to-consumer tele-optometry erosion by deepening exam-tied dispensing relationships through freeform surfacing equipment deployment in German and Austrian practices. Secure captive bio-acetate supply through backward integration into Italian molding networks before ECHA sunset dates restrict phthalate alternatives. Counter online refraction platforms with bundled professional fitting services that justify premium pricing through personalized corridor positioning. For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for traceable recycled ocean plastic frames with documented carbon footprints serving CSRD-mandated procurement at large enterprises. Poland's underpenetrated optical retail offers whitespace for mid-market exam-and-frame packages where optician density lags Western benchmarks. Enter through subscription-based contact lens replenishment platforms exploiting Nordic postal infrastructure and younger consumers' preference for monthly billing cycles. For Investors and Strategic Acquirers: Accelerating bio-acetate certification racing among Italian frame specialists is the leading indicator that material compliance capabilities are becoming the primary valuation differentiator. Target acquisition candidates with ECHA-authorized polymer formulations and established relationships with luxury house brands. Watch for inflection when national reimbursement authorities expand myopia-control lens coverage for children, signaling pediatric segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Acetate Certification Investment | ECHA compliance unlocks premium positioning in EU Green Deal procurement tenders. |
| Freeform Surfacing Equipment Deployment | In-house edging reduces wholesale lens dependency for German optical practices. |
| Subscription Platform Launch | Monthly auto-renewal captures higher lifetime value in Nordic contact lens markets. |
| Tele-Optometry Integration | Digital refraction extends reach in United Kingdom and Netherlands bypassing retail. |
| Smart Glasses Regulatory Pathway | EU AI Act compliance opens medical-device reimbursement distinct from fashion categories. |
Research Approach
Trade databases, ECHA substance registration filings, and national reimbursement authority publications formed the secondary backbone, cross-referenced with primary interviews of optical retail chain executives, acetate molding specialists, regulatory affairs leads at lens manufacturers, and dispensing opticians across Germany, Italy, and Poland. Bottom-up prescription volume estimates triangulated against top-down manufacturer shipment data.
Historical trendline analysis of replacement cycle compression and material cost trajectories informed the projection framework across product type, material certification tier, distribution channel, and end-user age cohort dimensions. CAGRs derived from segmented growth rate modeling incorporating reimbursement policy shifts and REACH regulatory phase-in schedules.
The model assumes a particular technology adoption path; alternative pathways for silicone hydrogel material penetration or smart glasses sensor integration would alter the outlook. Forecasts reflect assumptions about EMA biocompatibility timeline stability and CSRD disclosure mandate enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Smart Sunglasses Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Eyeglass Market
Eyewear
Blue Light Glasses Market
Eyewear
Goggles Market
Eyewear
United States Eyewear Market
Eyewear
Spectacles Market
Eyewear
Luxury Sunglass Market
Eyewear
Plano Sunglasses Market
Eyewear
Smart Eyewear Market
Eyewear
Anti-Fog Lens Market
Eyewear
Middle East Eyewear Market
Eyewear
Face and Ear Bow Market
Eyewear
Wooden Eyewear Market
Eyewear
Anti-Blue Light Glasses Market