
 Poland Snack Bar Market | 2026-2036
Poland Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Snack Bar Market Analytics
Food technologist talent is rotating toward functional formulation roles as manufacturers reformulate for cleaner labels. Nestle Polska leverages its confectionery R&D heritage to sustain innovation pipelines in textured protein systems. Bakalland S.A. anchors domestic sourcing through its controlled nut and dried fruit supply base. Sante Sp. competes on organic certification breadth across retail channels.
A snack bar is a shelf-stable, extruded or cold-pressed food unit typically combining cereals, nuts, binders, and functional additives such as protein isolates or fiber syrups, manufactured through continuous slab-forming or rotary molding lines for portion-controlled convenience consumption. Protein bars command premium shelf positioning as sports nutrition migrates into mainstream grocery. Granola bars occupy mature volume tiers where price elasticity constrains margin expansion. Flexible packaging dominates unit economics, though rigid formats gain traction in gift and subscription channels.
Poland's national food safety regulator enforces EU-wide additive thresholds under harmonized EFSA guidelines, while the Polish Committee for Standardization administers voluntary PN standards for gluten-free and organic claims that retailers increasingly mandate. The EU Packaging and Packaging Waste Regulation is forcing material transitions that will reshape converter relationships and unit cost structures. Stakeholders must monitor how B2B procurement policies from major retail banners redefine acceptable packaging formats before committing to capital-intensive line conversions.
Market Dynamics
EU Nutrition and Health Claims Regulation enforcement is forcing manufacturers to revalidate protein declarations and reformulate binders, compressing formulation timelines while opening premium positioning for verified functional claims.
Growth Catalysts
- Urban fitness penetration:Warsaw and Tri-City corridor consumers are normalizing protein bar consumption as meal replacements, expanding addressable demand beyond dedicated athletes into white-collar professionals.
- EFSA additive harmonization:Unified safety thresholds under EFSA guidelines are reducing cross-border formulation complexity for Polish exporters targeting German and Czech retail banners.
- Modern trade depth:Controlled expansion of discounter and convenience formats in Poznan and Wroclaw is creating dedicated shelf space for single-serve and multi-pack SKUs.
Market Restraints
- Protein isolate cost volatility:Whey and pea protein concentrate pricing fluctuates with global dairy and pulse harvests, squeezing gross margins on mid-tier formulations.
- Flexible packaging converter concentration:Domestic film extrusion capacity clusters in Silesia, creating single-source risk for brands requiring metallized or high-barrier laminates.
- Clean-label technical ceiling:Natural binding systems using date paste or tapioca syrup fail to match maltitol shelf stability, limiting texture innovation in ambient distribution.
Strategic Opportunities
- Lodz manufacturing corridor:Underutilized food processing infrastructure in central Poland offers lower opex bases for cold-pressed bar production serving Baltic states.
- Subscription channel emergence:Direct-to-consumer platforms are bypassing slotting fee structures, enabling margin recovery through personalized nutrition bundles.
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds are accelerating partnerships with domestic rPET and paperboard converters ahead of 2030 compliance deadlines.
Industry Challenges
- Food technologist scarcity:Functional formulation expertise in protein texturization and natural preservation concentrates in Warsaw and Krakow academic clusters, creating recruitment bottlenecks for regional manufacturers.
- Organic certification timelines:Polish Committee for Standardization PN-N-11000 audit cycles stretch 14-18 months, delaying organic line launches past optimal seasonal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Snack Bar Market |
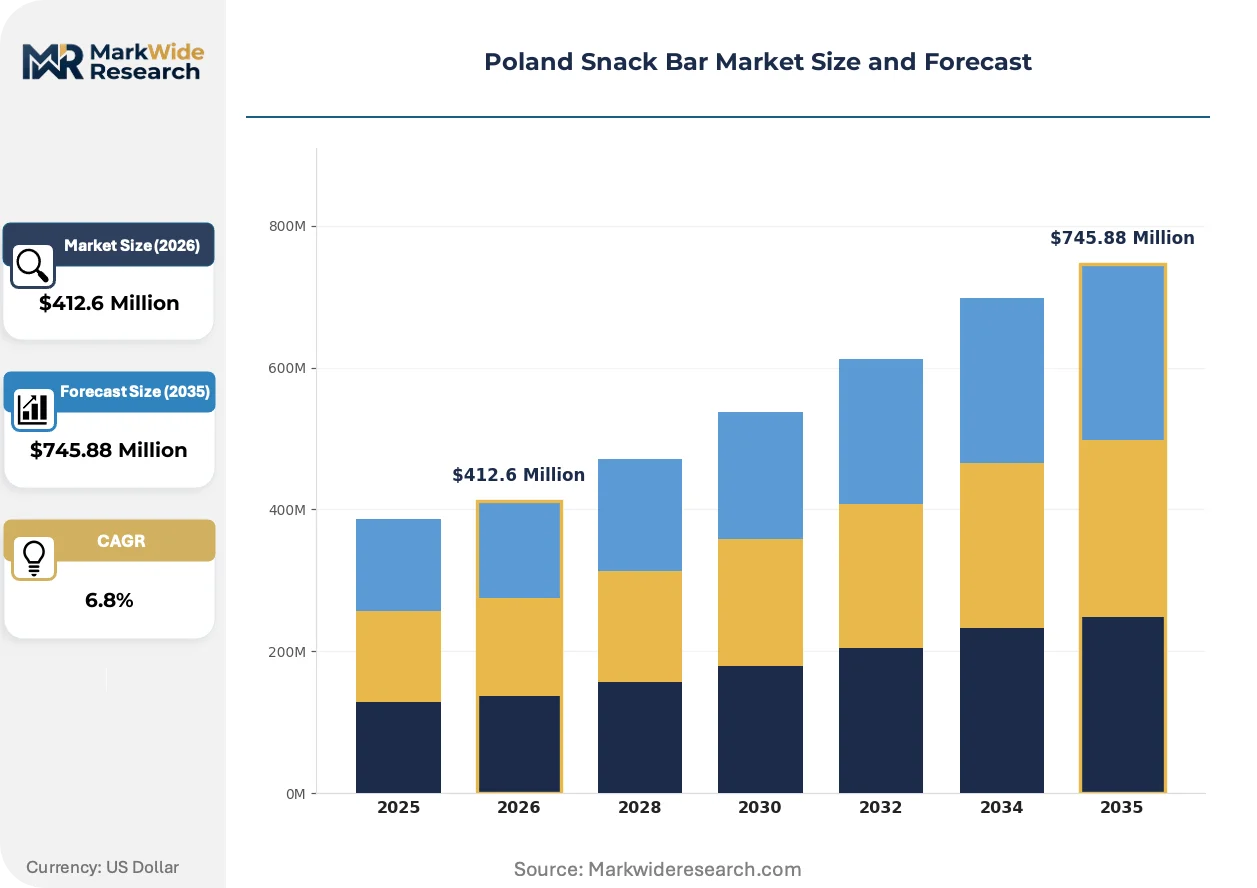
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut Bars, Energy Bars, Protein Bars, Granola Bars Packaging Type: Flexible Packaging, Rigid Packaging, Pouches, Tubs End User: Children, Teenagers, Adults, Athletes Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Shops |
| Companies Covered | Mondelez International, Nestle Polska, Bakalland S.A., Sante Sp., Melvit S.A., The Kellogg Company, General Mills Inc, Eurohansa Sp z o o, Purella Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Snack Bar Market Evolving Landscape
Extrusion and cold-pressing process lines are diverging into distinct capability tiers, with equipment choices now locking manufacturers into either mass-market efficiency or artisanal positioning.
High-moisture extrusion technology is bifurcating the protein bar texture landscape. Sports nutrition brands adopt continuous twin-screw systems for fibrous meat-analog mouthfeel, while wellness-positioned players deploy batch cold-pressing for denser, seed-forward formats. This equipment divergence is compressing mid-market players unable to fund dedicated lines for each texture platform.
The EU Packaging and Packaging Waste Regulation is mandating minimum recycled content in flexible films and rigid trays. Polish converters are retrofitting extrusion lines for rPET and chemically recycled polyolefins, though barrier performance degradation is forcing reformulation of oxygen-sensitive nut and fruit inclusions. Gift and subscription channels are absorbing rigid format premiums to meet retailer' sustainable packaging scorecards.
Consumption occasions are fragmenting across dayparts previously dominated by breakfast and post-workout. Office workers in Gdansk and Katowice are adopting mid-afternoon protein bars as blood-sugar management tools, displacing traditional confectionery. Convenience stores are responding with chilled single-serve placement near coffee counters, capturing impulse substitution from chocolate bars.
Poland Snack Bar Market Segmentation
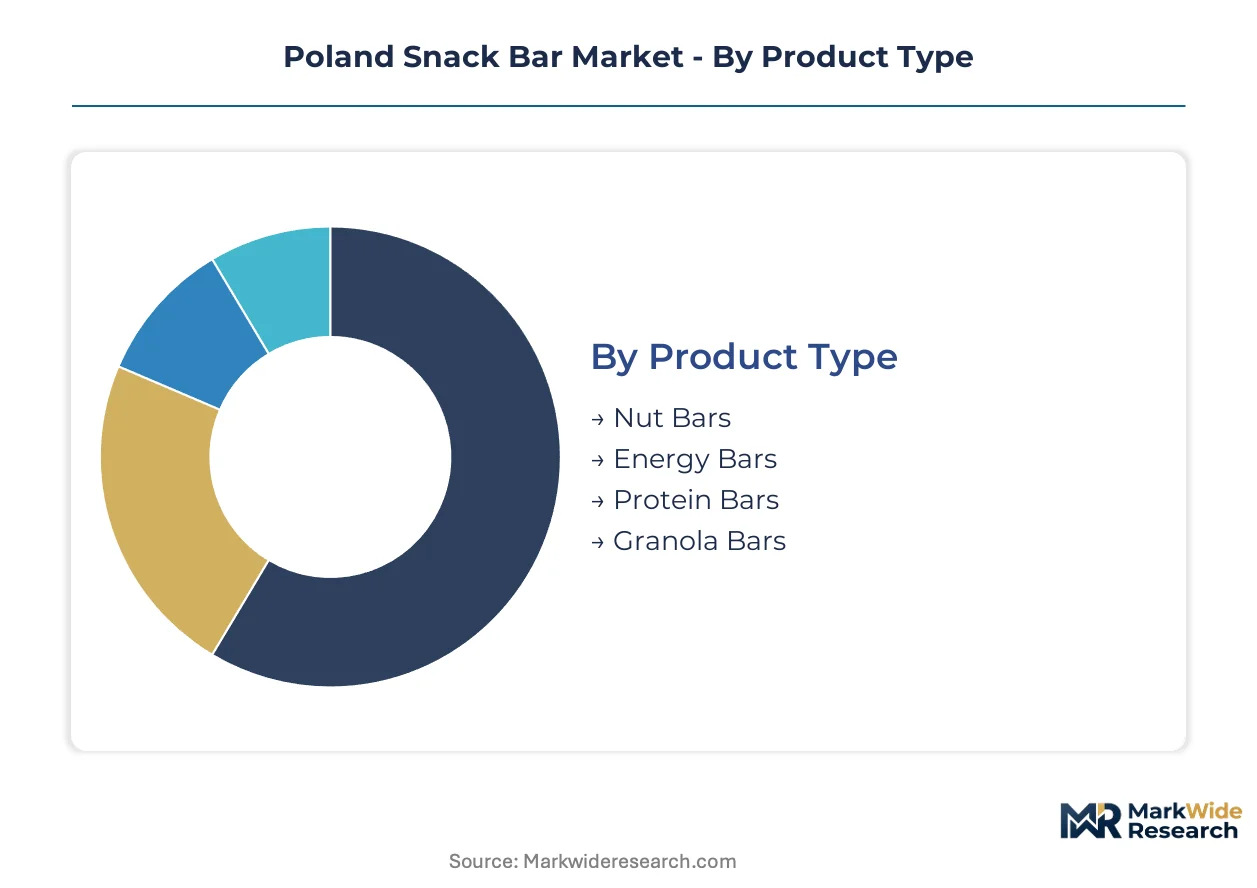
Channel dynamics in Poland's snack bar market vary sharply by segment. Protein bars command premium placement in health food shops and online subscription channels, while granola bars flow through high-volume supermarket discounters. Understanding these channel-segment pairings reveals where margin pools concentrate versus where volume scales.
Product Type:
Channel mix splits sharply across functional positioning. Protein and energy bars concentrate in health food shops and online retail where consumers self-select for performance claims. Nut and granola bars dominate supermarket and convenience store shelves where impulse and price sensitivity drive selection.
- Protein Bars:Extruded or cold-pressed formulations combining whey, pea, or soy isolates with binders and functional additives. Demand clusters in Warsaw and Tri-City fitness studios and corporate offices where white-collar professionals substitute bars for midday meals. EFSA protein declaration requirements under EU Nutrition and Health Claims Regulation compress formulation timelines but open premium positioning for verified claims.
- Granola Bars:Baked oat and cereal matrices bound with syrups and inclusions. Volume concentrates in Poznan and Wroclaw supermarket discounters where price elasticity constrains margin expansion. Modern trade depth in these urban centers creates dedicated shelf space for multi-pack SKUs targeting family breakfast occasions.
- Energy Bars:Carbohydrate-dense formulations targeting sustained release. Sante Sp. and Bakalland S.A. compete through controlled nut and dried fruit supply bases.
- Nut Bars:Minimal-processed formats emphasizing whole nut content and clean labels. Lodz manufacturing corridor infrastructure supports cold-pressed production serving Baltic export markets.
Granola bars dominate installed base. Protein bars are where expansion concentrates.
Packaging Type:
Cost tier alignment determines converter relationships and capital commitment levels. Flexible formats serve mass-market price points while rigid and pouch formats capture premium and gift-channel margins.
- Flexible Packaging:Metallized films and high-barrier laminates dominate unit economics across protein and granola bars. Domestic film extrusion capacity clusters in Silesia, creating single-source risk for brands requiring oxygen-sensitive nut and fruit protection. EU Packaging and Packaging Waste Regulation recycled content mandates are forcing partnerships with rPET converters ahead of 2030 deadlines.
- Pouches:Stand-up and flat formats with reseal features. Online retail and subscription channels absorb format premiums for portion control and shipping durability.
- Rigid Packaging:Trays and clamshells for gift and subscription channels. Barrier performance degradation with recycled content is forcing reformulation of oxygen-sensitive inclusions.
- Tubs:Multi-serve rigid formats targeting family and club-channel volumes. Modern trade penetration in Warsaw supports dedicated shelf placement.
Flexible formats capture volume leadership. Rigid and pouch formats are climbing the fastest as sustainable packaging scorecards reshape procurement.
End User:
Application occasion fragments across dayparts previously dominated by breakfast and post-workout consumption. Office workers in Gdansk and Katowice now adopt mid-afternoon protein bars as blood-sugar management tools.
- Adults:White-collar professionals in Warsaw and Tri-City corridor normalizing protein bar consumption as meal replacements. Fitness-conscious urban consumers expand addressable demand beyond dedicated athletes.
- Athletes:Dedicated sports nutrition users demanding verified protein content and texture performance. EFSA additive harmonization reduces cross-border formulation complexity for Polish exporters.
- Teenagers:Convenience-driven consumption in school and recreational settings. Chilled single-serve placement near coffee counters captures impulse substitution from confectionery.
- Children:Parent-controlled selection emphasizing clean labels and allergen management. Polish Committee for Standardization PN-N-11000 gluten-free standards increasingly mandated by retailers.
Adult users anchor revenue concentration. Athlete-targeted formulations are expanding most quickly as sports nutrition migrates into mainstream grocery.
Distribution Channel:
Geography of modern trade penetration determines segment accessibility. Warsaw and Tri-City depth supports premium format trial, while Poznan and Wroclaw discounter expansion drives volume tier scaling.
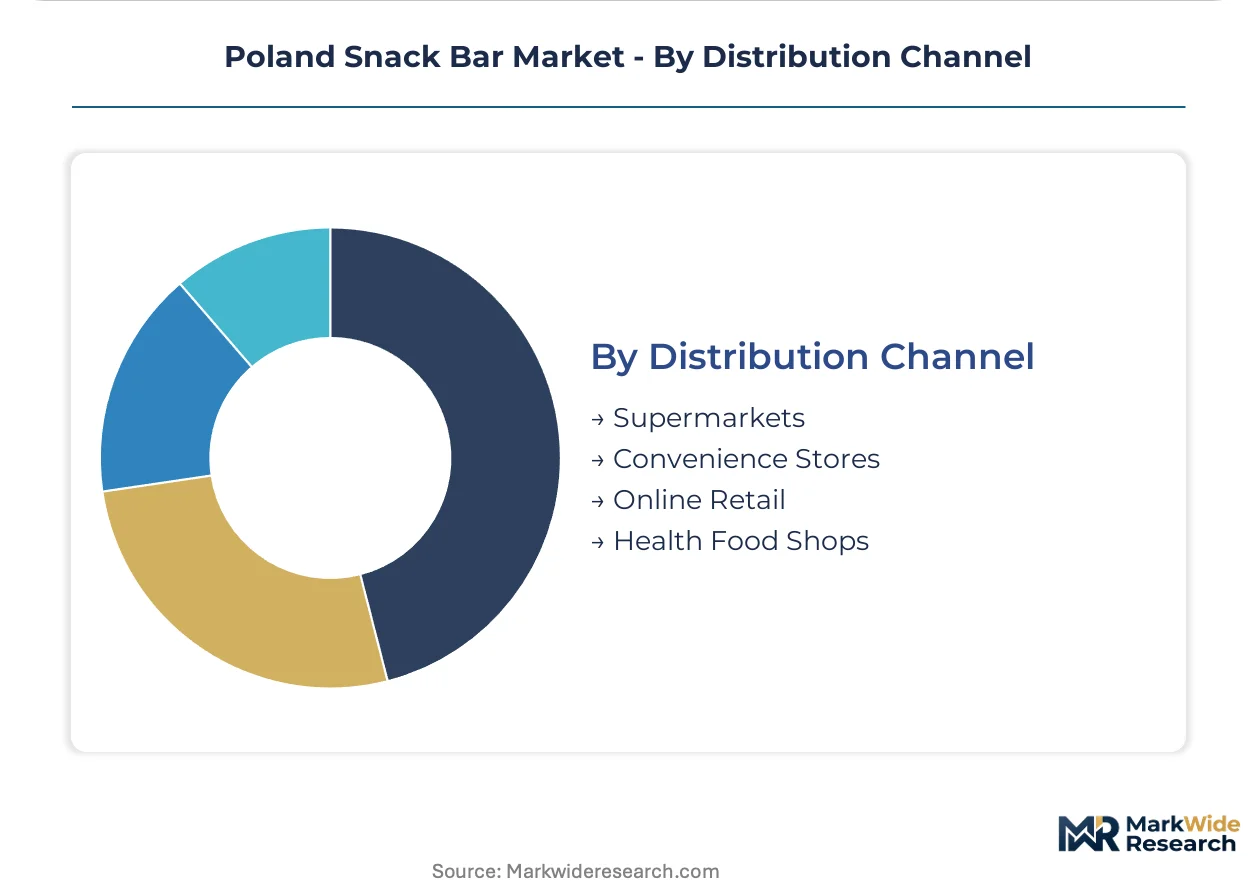
- Supermarkets:Controlled expansion of discounter and convenience formats in Poznan and Wroclaw creates dedicated shelf space for single-serve and multi-pack SKUs. Granola bars occupy mature volume tiers where price competition intensifies.
- Online Retail:Direct-to-consumer platforms bypass slotting fee structures, enabling margin recovery through personalized nutrition bundles. Subscription channel emergence supports rigid format premiums.
- Convenience Stores:Chilled single-serve placement near coffee counters captures impulse substitution from chocolate bars in Gdansk and Katowice office districts.
- Health Food Shops:Curated premium assortment targeting verified functional claims. EFSA protein declaration enforcement opens positioning for validated formulations.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw and the Tri-City corridor consume snack bars as meal replacements, while Poznan and Wroclaw treat them as breakfast commodities, creating divergent margin profiles across Poland's urban hierarchy.
Masovian Voivodeship
White-collar professionals in Warsaw normalize protein bar consumption as midday meal substitutes, expanding demand beyond fitness enthusiasts. EFSA guidelines under EU Nutrition and Health Claims Regulation enforce protein declaration standards that manufacturers must revalidate. The Warsaw academic cluster concentrates food technologist talent for functional formulation roles.
Pomeranian Voivodeship
Office workers in Gdansk adopt mid-afternoon protein bars for blood-sugar management, displacing traditional confectionery. Polish Committee for Standardization PN-N-11000 standards for gluten-free claims are increasingly mandated by Tri-City retailers. Convenience stores in Gdansk deploy chilled single-serve placement near coffee counters to capture impulse substitution.
Greater Poland Voivodeship
Supermarket discounters in Poznan drive granola bar volume through price-sensitive family breakfast occasions. EU Packaging and Packaging Waste Regulation recycled content thresholds are forcing partnerships with regional rPET converters ahead of 2030 deadlines. Modern trade expansion creates dedicated shelf space for multi-pack SKUs.
Lower Silesian Voivodeship
Flexible packaging demand from Wroclaw's retail banners concentrates converter relationships in Silesia, creating single-source risk for metallized film requirements. EFSA additive harmonization reduces cross-border formulation complexity for exporters targeting Czech and German markets. The region's film extrusion capacity clusters serve oxygen-sensitive nut and fruit inclusion protection needs.
Lodz Voivodeship
Underutilized food processing infrastructure in central Poland offers lower opex bases for cold-pressed bar production serving Baltic state export markets. Organic certification timelines through Polish Committee for Standardization stretch 14-18 months, delaying line launches past optimal seasonal windows. The Lodz manufacturing corridor supports artisanal-positioned nut bar formats.
Poland Snack Bar Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational confectionery heritage distinguishing the upper tier from domestic organic and private-label players. The market structure compresses mid-market participants unable to fund dedicated extrusion or cold-pressing lines for each texture platform. Two strategic archetypes dominate: heritage confectionery multinationals leveraging R&D infrastructure, and domestic specialists controlling nut and dried fruit supply bases. Competitive moves center on clean-label reformulation partnerships and converter relationships for recycled-content packaging compliance.
Among heritage-integrated multinationals, Nestle Polska and Mondelez International occupy positions leveraging confectionery R&D heritage for textured protein system innovation. Bakalland S.A. and Sante Sp. exemplify the domestic specialist archetype, with the former anchoring controlled supply bases and the latter competing through organic certification breadth. The Kellogg Company and General Mills Inc represent scale-driven breakfast cereal crossovers migrating granola expertise into bar formats. Eurohansa Sp z o o, Purella Foods, and Melvit S.A. sit within the emerging private-label and regional brand tier, where subscription channel emergence enables margin recovery bypassing traditional slotting fee structures.
| Leading Market Players |
|---|
| Mondelez International |
| Nestle Polska |
| Bakalland S.A. |
| Sante Sp. |
| Melvit S.A. |
| The Kellogg Company |
| General Mills Inc |
| Eurohansa Sp z o o |
| Purella Foods |
| Others |
Value Network & Pricing Analysis
Underutilized cold-pressing capacity in the Lodz manufacturing corridor compresses unit economics for artisanal-positioned nut bars while mass-market extrusion lines in Silesia enforce price floors through scale advantages. This geographic bifurcation of production technology concentrates margin pools in premium channels and squeezes mid-tier players lacking dedicated lines for each texture platform.
Pricing Analysis
Long-term offtake contracts for whey and pea protein concentrates anchor pricing structures across protein bar tiers, though spot market exposure for maltitol and natural binding syrups introduces volatility into granola formulations. Three-tier pricing structure across premium, standard, and economy levels separates verified EFSA-compliant functional claims from basic cereal matrices. Pricing pressure stems from protein isolate cost volatility tied to global dairy and pulse harvests. Discounter channels in Poznan and Wroclaw exhibit highest price sensitivity, while subscription-based direct-to-consumer platforms absorb rigid format premiums with minimal elasticity.
Supply Chain Analysis
Single-source metallized film capacity in Silesia creates chokepoint vulnerability for brands requiring oxygen-sensitive nut and fruit protection. Raw material sourcing draws from Germany for whey protein isolates, Ukraine for sunflower seeds, and Turkey for dried fruit inclusions. Tariff exposure on imported protein concentrates amplifies margin risk for mid-tier formulations. Distribution runs through modern trade banners in Warsaw and Tri-City corridors for premium SKUs, with discounter networks in Greater Poland handling volume-tier granola flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Confectionery substitution from traditional chocolate and candy categories threatens snack bar incumbents as office workers in Gdansk and Katowice displace mid-afternoon sweets with protein formats. Defense requires locking in formulation differentiation before private-label convergence erodes positioning.
For Market Incumbents: Fortify cold-pressed production capabilities in the Lodz corridor to capture Baltic export demand before regional competitors commission equivalent lines. Secure long-term converter partnerships for rPET and chemically recycled polyolefin packaging ahead of EU Packaging and Packaging Waste Regulation deadlines. EFSA protein declaration revalidation requirements compress formulation timelines, making Warsaw academic cluster recruitment a critical capability lever. For New Entrants and Emerging Players: Differentiate on organic certification breadth through Polish Committee for Standardization PN-N-11000 compliance, exploiting 14-18 month audit cycles that delay incumbent line launches. Target health food shops in the Tri-City corridor where curated premium assortment tolerates higher slotting fees. Deploy direct-to-consumer subscription channels to bypass supermarket slotting structures and recover margins through personalized nutrition bundles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic specialists with controlled nut and dried fruit supply bases over capital-intensive extrusion equipment plays. Five-to-ten year viability hinges on clean-label reformulation partnerships that resolve natural binding system shelf-stability limitations. Monitor EFSA additive harmonization enforcement as signal for cross-border export opportunity expansion into German and Czech retail banners.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | Natural binding systems using date paste resolve maltitol substitution limits for ambient distribution. |
| Recycled Content Packaging Conversion | rPET converter partnerships in Silesia meet EU Packaging and Packaging Waste Regulation thresholds before 2030. |
| Direct-to-Consumer Channel Launch | Subscription platforms bypass Poznan and Wroclaw discounter slotting fees for margin recovery. |
| Cold-Pressed Production Line Addition | Lodz corridor infrastructure serves Baltic state export markets with lower opex bases. |
| Organic Certification Investment | Polish Committee for Standardization PN-N-11000 compliance opens premium retail channel placement. |
Research Methodology
Operator-level perspectives from food technologists, retail category buyers, flexible packaging converters, and protein ingredient procurement managers anchored the qualitative base. Secondary validation drew from EU Nutrition and Health Claims Regulation filings, EFSA additive safety assessments, Polish Committee for Standardization audit records, and modern trade shelf-space allocation data. Bottom-up SKU-level volume builds triangulated against top-down voivodeship consumption intensity models.
Sensitivity analysis across protein isolate cost scenarios, recycled content compliance timelines, and subscription channel penetration rates tested forecast robustness. Segmentation dimensions modeled include product type, packaging format, end-user occasion, and distribution channel depth by urban hierarchy. CAGRs derived from trend extrapolation of fitness studio membership growth, modern trade expansion rates, and export shipment volumes. Industry-specific inputs incorporated EFSA enforcement intensity indices and organic certification queue lengths.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory harmonization and stable protein commodity markets would require recalibration. Forecasts reflect documented assumptions on urban fitness penetration trajectories and converter capacity expansion schedules. Practitioners should keep alternative scenarios live as EFSA protein declaration enforcement intensity and rPET barrier performance degradation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Southeast Asia Savory Snacks Market
Snacks
Nachos Market
Snacks
Energy Balls Market
Snacks
UK Snack Market
Snacks
Candy and Snack Food Pouches Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
Fiber Bars Market
Snacks
Edible Flakes Market
Snacks
Legume-Based Snacks Market
Snacks
South America Cereal Bar Market
Snacks
North America Savory Snacks Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Gluten Free Snacks Market
Snacks
Marshmallow Market
Snacks
Kale Chips Market
Snacks
Peanut Butter Keto Snacks Market