
 Legume-Based Snacks Market | 2026-2036
Legume-Based Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Legume-Based Snacks Market Foresight
EU F-Gas Regulation is decoupling refrigeration-dependent processing from legacy cold-chain economics, raising capital requirements for regional snack manufacturers. General Mills leverages its North American milling infrastructure to secure stable chickpea and lentil flour supply. Calbee Group anchors Asian market penetration through localized flavor development and retail partnerships.
Legume-based snacks comprise roasted, extruded, or puffed formulations derived from chickpeas, lentils, peas, or beans, typically achieving protein content of 5-8 grams per serving through densification or air-expansion processes. These products serve as shelf-stable alternatives to grain-based snacks for consumers seeking elevated fiber and plant protein intake. The baked segment leads volume due to lower oil absorption and extended shelf stability, while the spicy flavor profile captures the fastest growth as younger demographics seek bold taste experiences. Online distribution channels are expanding fastest, though supermarkets still control the largest margin pool through slotting fees and promotional scale.
FDA allergen labeling rules, EFSA novel food assessments, and USDA organic certification standards collectively shape formulation choices and market access timelines for new entrants. Compliance costs favor established players with dedicated regulatory affairs teams and existing certification portfolios. Stakeholders must monitor evolving protein content claim thresholds and front-of-pack labeling mandates that could recategorize competitive positioning.
Market Dynamics
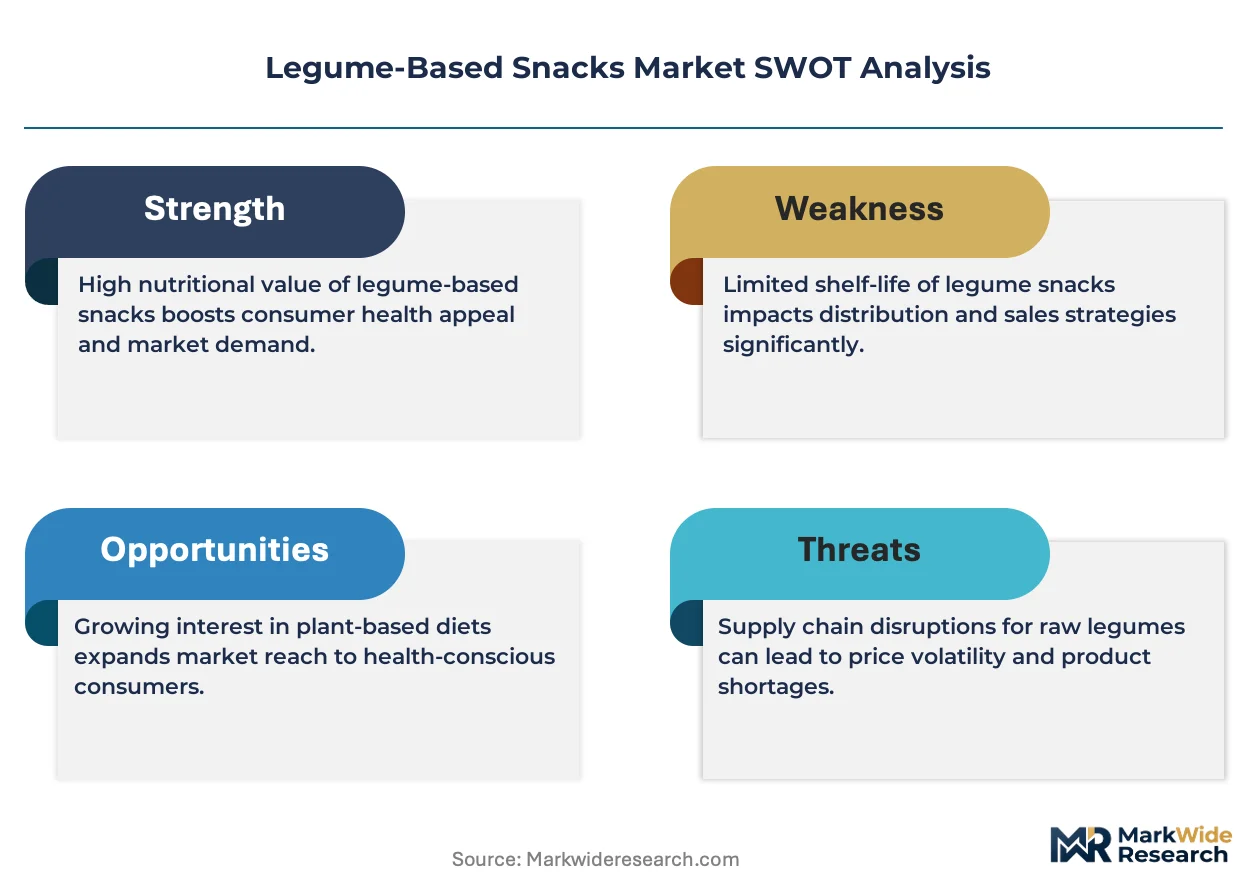
Clean-label mandates from FDA and EFSA are compressing formulation timelines while EU F-Gas Regulation forces refrigeration-dependent processors into capital-intensive equipment upgrades, reshaping competitive economics across production tiers.
Growth Catalysts
- Plant-Forward Dietary Guidelines:USDA MyPlate recommendations and EFSA protein diversification frameworks are institutionalizing legume consumption in institutional foodservice channels.
- Extrusion Technology Maturation:Twin-screw extrusion systems now achieve protein retention above 85% in chickpea flour processing, enabling cleaner ingredient decks.
- Urban Retail Density:Shelf-space allocation in United States conventional grocery channels has tripled for protein-forward snacking alternatives since 2022.
Market Restraints
- Pulse Price Volatility:Canadian lentil and Indian chickpea harvest variability creates input cost instability for flour-dependent manufacturers.
- Allergen Control Infrastructure:FDA sesame labeling requirements and cross-contamination protocols demand segregated production lines with six-figure capital outlays.
- Texture Replication Limits:Air-expansion processes struggle to match the fracture mechanics of fried potato starch, constraining mainstream palate migration.
Strategic Opportunities
- School Nutrition Programs:USDA Smart Snacks in School standards create compliant product slots for fiber-dense, reduced-sodium formulations in United States K-12 channels.
- Direct-to-Consumer Subscriptions:Curated snack boxes bypass slotting fee barriers while capturing recurring revenue from health-motivated households.
- Upcycled Ingredient Integration:Brewer's spent grain and oilseed press cakes converge with legume bases to create novel sustainability-positioned SKUs.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Fewer than 200 specialists globally possess combined expertise in FDA GRAS notifications and EFSA novel food dossiers.
- Certification Timeline Compression:USDA organic and Non-GMO Project verification cycles now exceed 14 months, delaying market entry for reformulated lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legume-Based Snacks Market |
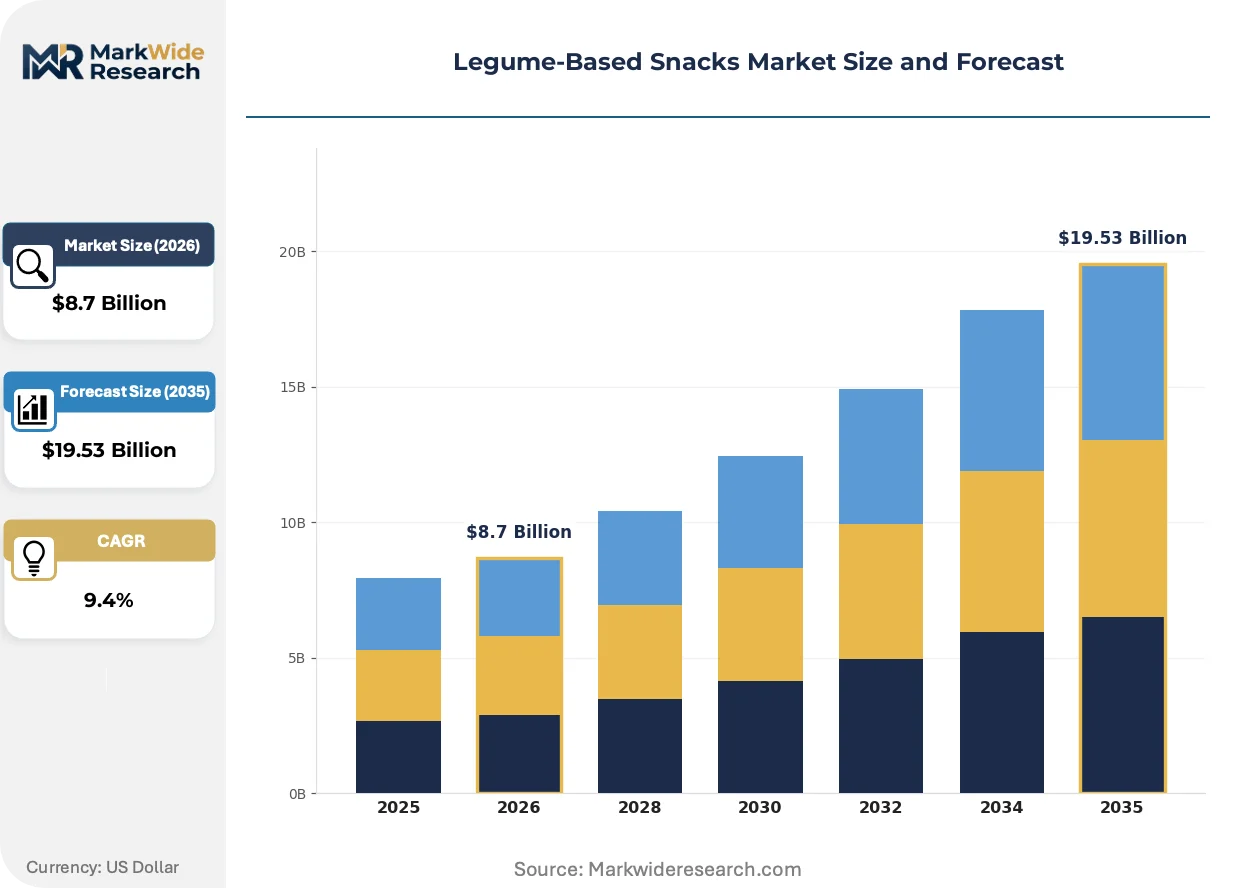
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baked, Fried, Seasoned, Coated Flavor Profile: Spicy, Sweet, Savory, Umami Distribution Channel: Supermarkets, Health Food Stores, Online, Convenience Stores Target Consumer: Health-Conscious, Vegans, Snack Enthusiasts, Athletes |
| Companies Covered | General Mills, Calbee Group, PepsiCo, The Hain Celestial Group, Conagra Brands, Nestlé, Kellogg Company, Goya Foods, Mondelez International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legume-Based Snacks Market Shifts & Advancements
Extrusion and drying technologies are converging with front-of-pack labeling mandates to redefine how legume snacks achieve shelf visibility and formulation credibility simultaneously.
High-pressure processing paired with infrared drying is expanding into roasted legume applications previously dominated by oil-frying methods. Clean-label manufacturers in the United States and Germany are adopting these systems to achieve pathogen reduction without preservative additives. The technology is expanding into premium private-label contracts that command shelf placement through sodium reduction claims rather than promotional spend.
EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in cold-chain-dependent roasting operations, forcing equipment retrofits by 2027. European processors face stranded asset risk in legacy cooling infrastructure while Asian manufacturers gain timing advantages through newer facility builds. The regulation is compressing regional production economics most severely for mid-scale operators in France and Italy lacking capital reserves for compliant equipment.
Subscription-based replenishment models are displacing impulse-driven supermarket purchases among millennial and Gen Z households. Direct-to-consumer channels now capture trial purchases that previously required slotting fee investments in conventional retail. The United States and United Kingdom show the steepest channel migration, with urban consumers prioritizing convenience and personalized nutrition bundles over in-aisle discovery.
Legume-Based Snacks Market Segmentation
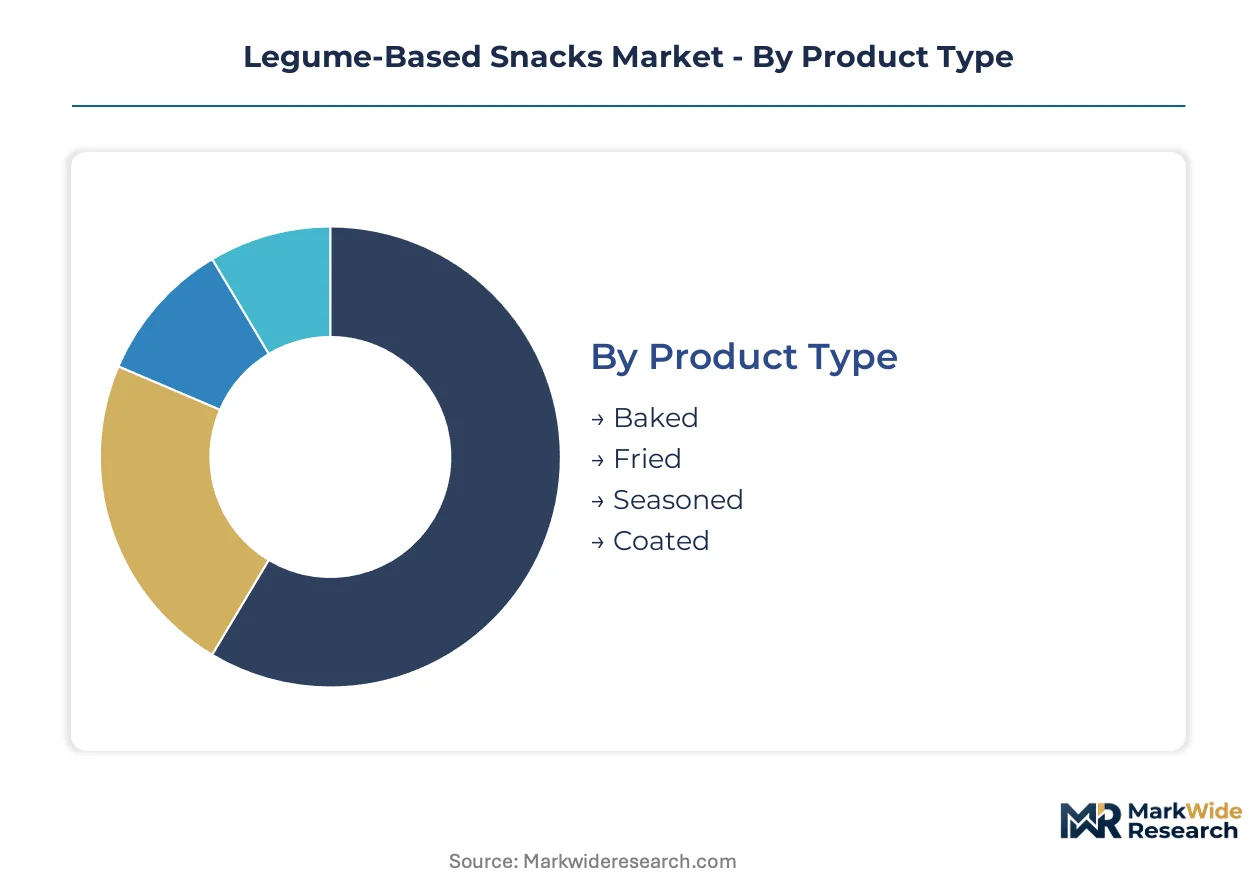
Legume-based snack manufacturers configure product portfolios across four intersecting dimensions that determine margin capture and channel access. Each segmentation axis carries distinct capital requirements, regulatory exposure, and consumer loyalty mechanics that reshape competitive economics.
Product Type:
Volume leadership sits with baked formats while premium positioning clusters around coated and specialty fried variants.
- Baked:Low-oil thermal processing achieves protein retention above 85% in chickpea flour matrices. United States conventional grocery channels allocate tripled shelf space to these formulations since 2022, driven by USDA MyPlate institutional endorsements and extended shelf stability requirements.
- Fried:Oil-immersion cooking delivers fracture mechanics that air-expansion processes struggle to replicate, constraining mainstream palate migration despite higher caloric density. European processors face stranded asset risk from EU F-Gas Regulation phase-downs in refrigeration-dependent frying lines.
- Seasoned:Post-cooking flavor adherence through oil or aqueous binding supports clean-label sodium reduction claims under FDA guidelines.
- Coated:Multi-layer batter systems command slotting fee premiums in United States supermarkets through visual differentiation and texture contrast.
Today's leader: Baked. Tomorrow's challenger: Coated.
Flavor Profile:
Consumer willingness-to-pay gradients separate bold taste experiences from conventional savory baselines.
- Spicy:Capsicum-derived heat profiles capture millennial and Gen Z trial purchases in United States urban retail. Direct-to-consumer subscription channels prioritize these SKUs for personalization algorithms and recurring revenue capture.
- Savory:Yeast extract and legume-autolyzed bases dominate volume production for institutional foodservice channels compliant with USDA protein diversification frameworks.
- Sweet:Monk fruit and allulose formulations target reduced-sugar positioning within FDA labeling thresholds.
- Umami:Mushroom and tomato-derived glutamate alternatives support clean-label positioning in German and United States premium private-label contracts.
Spicy formats are climbing the fastest among younger demographics seeking sensory differentiation.
Distribution Channel:
Margin pools concentrate where slotting fees and promotional scale create barriers for new entrants.
- Supermarkets:Control the largest absolute margin pool through centralized procurement and promotional calendar coordination. United States conventional grocery penetration for legume snacks has expanded beyond natural and specialty store boundaries.
- Online:Subscription-based replenishment models displace impulse-driven purchases among health-motivated households. The channel is expanding most quickly in United States and United Kingdom urban markets.
- Health Food Stores:Curated assortment supports premium pricing for certified organic and Non-GMO Project verified lines.
- Convenience Stores:Grab-and-go positioning targets sodium-reduced formulations compliant with USDA Smart Snacks in School standards for adjacent K-12 channel expansion.
Supermarkets retain volume dominance. Online channels are gaining share fastest through recurring revenue mechanics.
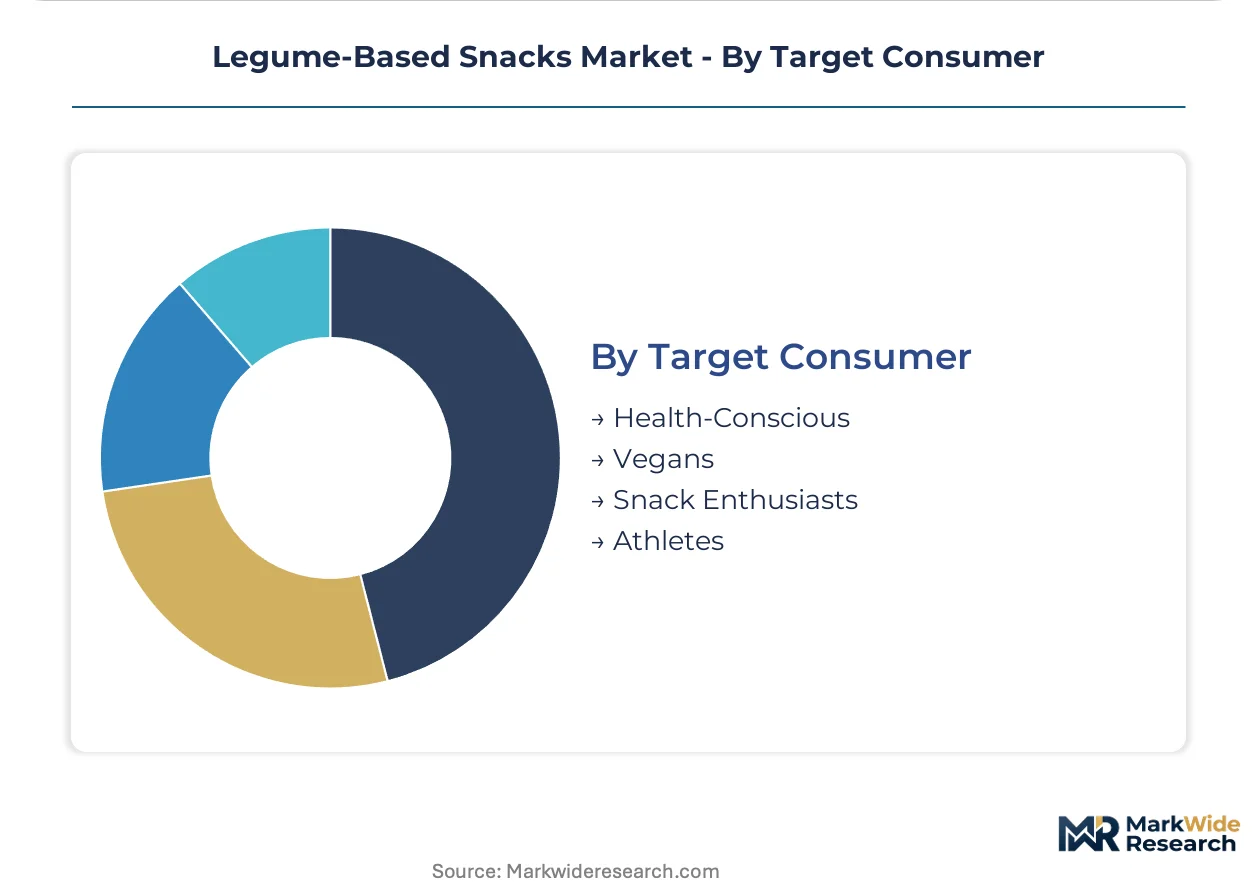
Target Consumer:
Protein claim intensity and certification requirements segment addressable markets by lifestyle commitment depth.
- Health-Conscious:Drive mainstream adoption through front-of-pack protein and fiber claims. FDA allergen labeling compliance and reduced-sodium positioning determine repeat purchase rates.
- Vegans:Require segregated production lines and dedicated certification timelines exceeding 14 months for USDA organic and Non-GMO Project verification.
- Snack Enthusiasts:Prioritize texture replication and bold flavor profiles over nutritional credentialing.
- Athletes:Demand 5-8 gram protein per serving thresholds with amino acid completeness claims supported by EFSA protein diversification frameworks.
Health-conscious consumers anchor current volume. Athletes represent the steepest expansion trajectory through sports nutrition channel integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and extrusion specialists cluster in the United States, Germany, and Japan, anchoring the industry's R&D infrastructure and pilot-scale production networks.
United States
Millennial and Gen Z households in urban centers drive plant-forward snacking adoption beyond natural food channels. FDA allergen labeling rules and USDA Smart Snacks in School standards reshape formulation requirements for K-12 and retail segments. Minneapolis-based milling operations and Chicago-area extrusion facilities concentrate chickpea flour processing capacity for national distribution.
Germany
Clean-label consumer bases in Berlin and Munich sustain premium positioning for reduced-sodium and organic-certified lines. EFSA novel food assessments and EU F-Gas Regulation phase-downs compress equipment upgrade timelines for mid-scale processors. Bavarian roasting facilities face stranded asset risk in legacy refrigeration infrastructure while adopting high-pressure processing systems.
Japan
Localized flavor development and retail partnerships anchor Asian market penetration through convenience store networks. METI guidelines on food manufacturing standards and JIS quality certifications govern production line configurations. Tokyo and Osaka metropolitan clusters host extrusion technology providers serving both domestic and export-oriented snack manufacturers.
India
Pulse processing expertise in Gujarat and Maharashtra leverages domestic chickpea and lentil harvests for cost-competitive flour supply. FSSAI labeling mandates and BIS quality standards regulate sodium content and protein claim thresholds. Mumbai-Pune industrial corridors concentrate contract manufacturing capacity for both domestic brands and export markets.
United Kingdom
Subscription-based replenishment models displace impulse purchases among London and Manchester health-motivated households. EFSA front-of-pack labeling mandates and UK post-Brexit food standards create dual compliance frameworks for manufacturers. Midlands-based co-manufacturing facilities serve direct-to-consumer brands bypassing supermarket slotting fees.
Legume-Based Snacks Market Competitive Landscape
The competitive structure tilts toward diversified food conglomerates with existing milling infrastructure and regulatory affairs capabilities. Mid-scale specialists face capital constraints from allergen-controlled production line requirements and extended certification timelines. Three archetypes dominate: legacy snack manufacturers pivoting protein-forward portfolios, pulse processors backward-integrating into consumer packaged goods, and direct-to-consumer brands bypassing retail slotting barriers through subscription mechanics. M&A activity concentrates on extrusion technology acquisitions and regional distribution network consolidation.
Among North American diversified food manufacturers, General Mills and Conagra Brands exemplify archetypes leveraging existing supply chain infrastructure for legume flour procurement and national retail placement. Calbee Group occupies a position representing Asia-Pacific market development through localized flavor adaptation and convenience store channel density. These three entities anchor the competitive spectrum spanning legacy scale advantages against emerging direct-to-consumer challengers.
| Leading Market Players |
|---|
| General Mills |
| Calbee Group |
| PepsiCo |
| The Hain Celestial Group |
| Conagra Brands |
| Nestlé |
| Kellogg Company |
| Goya Foods |
| Mondelez International |
| Others |
Supply & Pricing Matrix
Backward integration into chickpea and lentil milling operations anchors pricing power for North American manufacturers while compressing margins for flour-dependent processors in Europe and Asia. Captive supply chains in the United States and Canada insulate integrated players from Indian and Canadian pulse price volatility that destabilizes contract manufacturing economics.
Pricing Analysis
Subscription bundling versus single-SKU transactional splits separate recurring-revenue direct-to-consumer models from slotting-fee-dependent supermarket channels. Three-tier pricing structure across premium organic-certified, standard clean-label, and economy conventional tiers tracks certification grade and protein claim intensity. Pricing pressure stems from Canadian lentil harvest variability feeding into flour input costs. Institutional foodservice buyers show highest price sensitivity; sports nutrition and premium private-label channels absorb premium positioning.
Supply Chain Analysis
Domestic-content requirements under USDA Smart Snacks in School standards and Buy American provisions reshape sourcing toward United States and Canadian pulse processors. Raw material flows draw from Canadian lentil harvests, Indian chickpea production, and United States domestic pea cultivation. Single-source vulnerability concentrates in Indian monsoon-dependent chickpea output. Distribution runs through Minneapolis-Chicago milling corridors into national retail networks, with direct-to-consumer fulfillment bypassing conventional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between United States FDA fast-track GRAS pathways and EFSA novel food assessment timelines creates geographic cost differentials for new product launches. Manufacturers can compress market entry economics by staging initial launches in jurisdictions with abbreviated safety review protocols.
For Market Incumbents: Acquire extrusion technology specialists to secure proprietary protein retention capabilities above 85% thresholds. Consolidate regional distribution networks to defend against direct-to-consumer subscription erosion. Channel control through captive supermarket shelf-space agreements remains the priority defensive lever against emerging private-label threats.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier entry point for bypassing slotting fee requirements. White-space concentration sits in USDA Smart Snacks in School compliant formulations for K-12 institutional channels. Go-to-market execution should anchor on personalized nutrition bundles targeting millennial household replenishment patterns.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale extrusion specialists because certification timeline compression and capital requirements for allergen-controlled lines prevent organic scaling. Five-to-ten year viability hinges on portfolio diversification across baked, coated, and seasoned format capabilities. Monitor EFSA protein diversification framework implementation as inflection signal for European demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Extrusion Technology Acquisition | Proprietary protein retention above 85% enables clean-label positioning under FDA guidelines. |
| Direct-to-Consumer Launch | Subscription mechanics bypass supermarket slotting fees while capturing recurring revenue. |
| Backward Integration into Milling | Captive chickpea flour supply insulates against Canadian and Indian harvest volatility. |
| Sustainability Repositioning | Upcycled ingredient integration supports premium private-label contracts in German markets. |
| Distribution Channel Expansion | USDA Smart Snacks compliance opens K-12 institutional procurement beyond retail boundaries. |
Research Methodology
Bottom-up flavor profile and distribution channel modeling reconciled against top-down pulse supply and extrusion capacity tracking forms the analytical core. Primary interviews with snack brand managers, category buyers at United States conventional grocers, extrusion equipment engineers, and regulatory affairs specialists combined with secondary validation from FDA GRAS notifications, EFSA novel food registers, USDA procurement databases, and Nielsen retail audit data. Triangulation between demand-side adoption curves and supply-side input cost indices anchors volume and value estimates.
Input-output matrices map chickpea and lentil flour flows through baked, fried, seasoned, and coated processing stages across supermarkets, online, health food stores, and convenience store channels. CAGRs derive from segment-level growth rate reconciliation against macro protein diversification trends. Forecast inputs include twin-screw extrusion technology maturation curves and EU F-Gas Regulation equipment replacement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Canadian-Indian harvest variability and EFSA front-of-pack labeling mandate evolution. Analytical boundaries exclude speculative novel protein sources not yet achieving GRAS status. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Jerky Snacks Market
Snacks
Europe Snacks Food Market
Snacks
Latin America Extruded Snack Food Market
Snacks
South America Cereal Bar Market
Snacks
South America Energy Bar Market
Snacks
Crispy Fruit Chips Market
Snacks
Crackers Market
Snacks
Edible Flakes Market
Snacks
Tortilla Mix Market
Snacks
Snacks Market
Snacks
Protein Crisps Market
Snacks
Specialty Snacks Market
Snacks
Mushroom Based Jerky Market
Snacks
Roasted Corn Market
Snacks
Protein Bars Market
Snacks
Low-Fat Tortillas Market