
 Southeast Asia Savory Snacks Market | 2026-2036
Southeast Asia Savory Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Savory Snacks Market Analytics
Halal certification under MUI Indonesia and JAKIM Malaysia is reorganizing competitive access across the Southeast Asia Savory Snacks Market, determining which manufacturers qualify for shelf space in Muslim-majority markets. PT Garudafood Putra Putri Jaya Tbk leverages its integrated palm oil supply chain to control input costs across extruded snack lines. Tao Kae Noi Food & Marketing PCL anchors Thailand's seaweed snack segment through specialized coastal processing facilities. Universal Robina Corporation dominates Philippine distribution networks, extending its reach into rural sari-sari stores that competitors struggle to penetrate.
Southeast Asia savory snacks comprise processed, shelf-stable food products manufactured through frying, baking, or extrusion of starch-based, legume-based, or marine-based raw materials, typically seasoned with region-specific spice blends and packaged in moisture-barrier films for ambient retail distribution. Extruded snacks lead volume due to lower per-unit production costs and adaptable flavor application, while nuts command premium positioning in urban convenience channels. Pouches capture growing share against rigid formats because of lighter shipping weights and improved resealability for humid climates. Spicy flavor profiles outpace mild alternatives in Thailand, Vietnam, and Indonesia, where local palates favor chili-derived heat intensity.
Indonesia's BPOM enforces strict additive and labeling standards that manufacturers must satisfy before commercial release, while Thailand's FDA mandates nutritional disclosure panels that reshape product reformulation priorities. Malaysia's JAKIM halal protocols create parallel compliance tracks for export-oriented producers serving Middle Eastern markets. Stakeholders must monitor evolving ASEAN harmonization talks on prepackaged food standards, as unified regional rules would eliminate current certification redundancies but also raise baseline compliance costs for smaller domestic players.
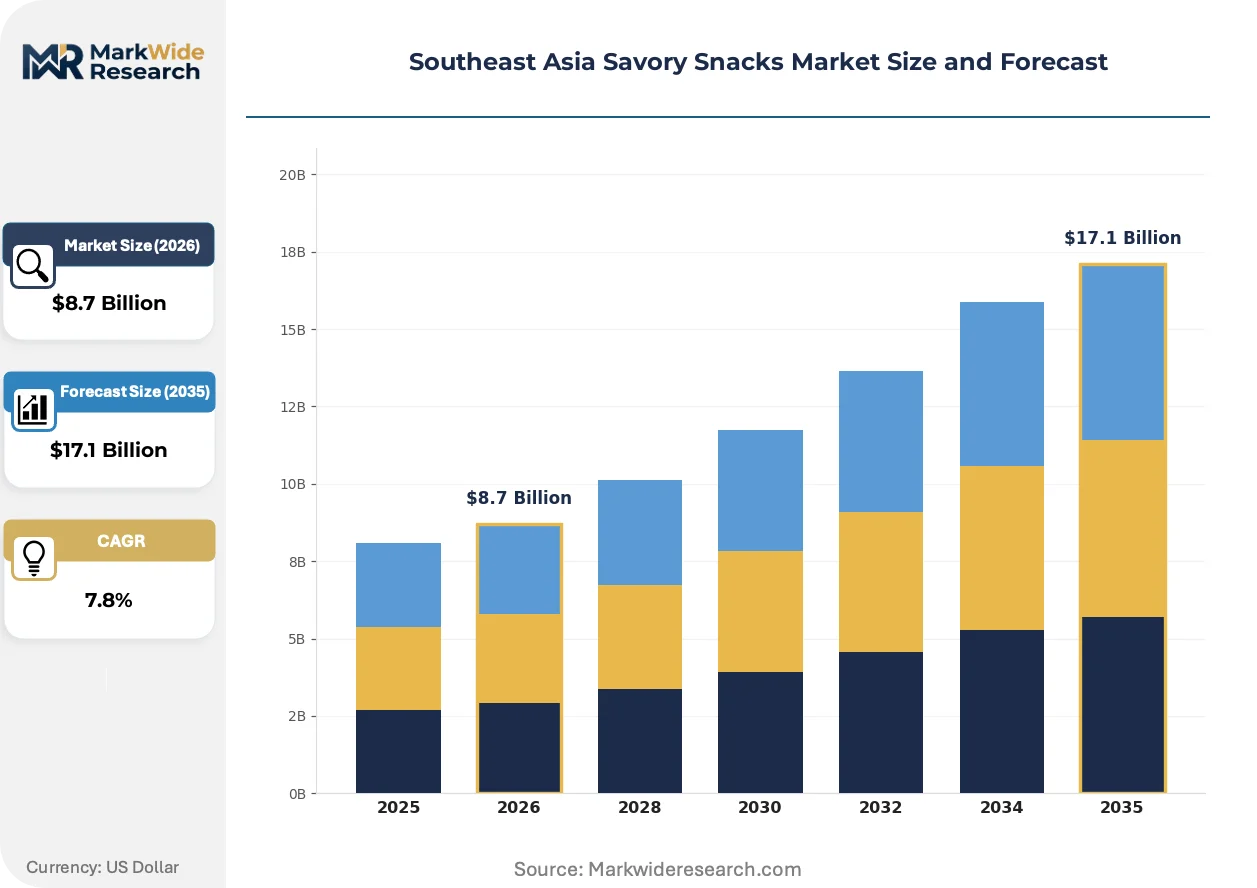
Market Dynamics
Halal certification requirements under MUI Indonesia and JAKIM Malaysia are restructuring competitive access across Muslim-majority markets, forcing manufacturers to choose between parallel compliance tracks or geographic exclusion.
Growth Catalysts
- Urban convenience demand:Young consumers in Indonesia's Greater Jakarta corridor and Vietnam's Ho Chi Minh City metro area are prioritizing shelf-stable, flavor-forward snack formats that fit compressed meal schedules.
- ASEAN harmonization momentum:Prepackaged food standardization talks are creating pressure for unified regional rules that would streamline cross-border distribution for compliant manufacturers.
- Extrusion technology maturation:Lower per-unit production costs and adaptable flavor application systems are expanding accessible price points for starch-based snack lines.
Market Restraints
- Palm oil input volatility:Integrated supply chains provide cost control for major players, but smaller manufacturers face margin compression from commodity price swings in edible oil markets.
- Regulatory fragmentation:Indonesia's BPOM additive standards, Thailand's FDA labeling mandates, and Malaysia's JAKIM halal protocols create redundant certification burdens that favor capital-rich incumbents.
- Moisture barrier material dependence:Flexible pouch adoption requires specialized film imports that concentrate supply risk with limited regional polymer processing capacity.
Strategic Opportunities
- Rural Philippine penetration:Sari-sari store networks remain underdeveloped by premium international brands, creating whitespace for localized distribution partnerships.
- Spicy flavor premiumization:Chili-derived heat intensity preferences in Thailand, Vietnam, and Indonesia support line extensions at higher price tiers than mild alternatives.
- Resealable packaging innovation:Humid climate conditions are driving pouch format share gains against rigid containers through improved ambient stability.
Industry Challenges
- Halal audit talent scarcity:Certified compliance officers familiar with both MUI and JAKIM protocols command premium compensation that strains mid-tier manufacturer staffing budgets.
- Reformulation cycle compression:Simultaneous BPOM additive reviews and FDA disclosure updates in Thailand are forcing accelerated product redevelopment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Savory Snacks Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato Chips, Extruded Snacks, Nuts, Popcorn Flavor Profile: Spicy, Sweet, Barbecue, Sour Cream Packaging Type: Bags, Pouches, Cans, Boxes Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores |
| Companies Covered | PT Garudafood Putra Putri Jaya Tbk, Tao Kae Noi Food & Marketing PCL, Mondelēz International, Calbee Inc., Monde Nissin Corp., PepsiCo Inc., Universal Robina Corporation, Want Want Holdings Ltd., Kellanov, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Savory Snacks Market Evolving Landscape
Processing technology and packaging formats are converging to address climate-specific spoilage risks while regulatory disclosure requirements reshape product development pipelines across the region.
High-barrier coextruded films are replacing metallized laminates in premium snack lines, cutting material thickness by half while maintaining oxygen transmission resistance. Urban convenience retailers in Bangkok and Singapore are specifying these formats for ambient shelf life extension. The technology is miniaturizing production equipment footprints, enabling regional co-manufacturers to serve multiple brands from shared facilities.
Thailand's FDA nutritional disclosure mandates are forcing reformulation of sodium and saturated fat levels in extruded snack categories. Manufacturers are responding with alternate seasoning technologies that preserve perceived intensity while reducing labeled content. Spicy flavor lines face the steepest adjustment requirements given traditional reliance on salt-forward taste architectures.
Direct-to-retailer procurement contracts are displacing traditional distributor intermediaries in Vietnam's modern trade channel. Convenience store chains in Ho Chi Minh City are consolidating supplier relationships to capture logistics efficiencies and private label development capabilities. This concentration is most visible in the nuts segment, where premium positioning depends on consistent quality auditing that favors vertically integrated regional processors.
Southeast Asia Savory Snacks Market Segmentation
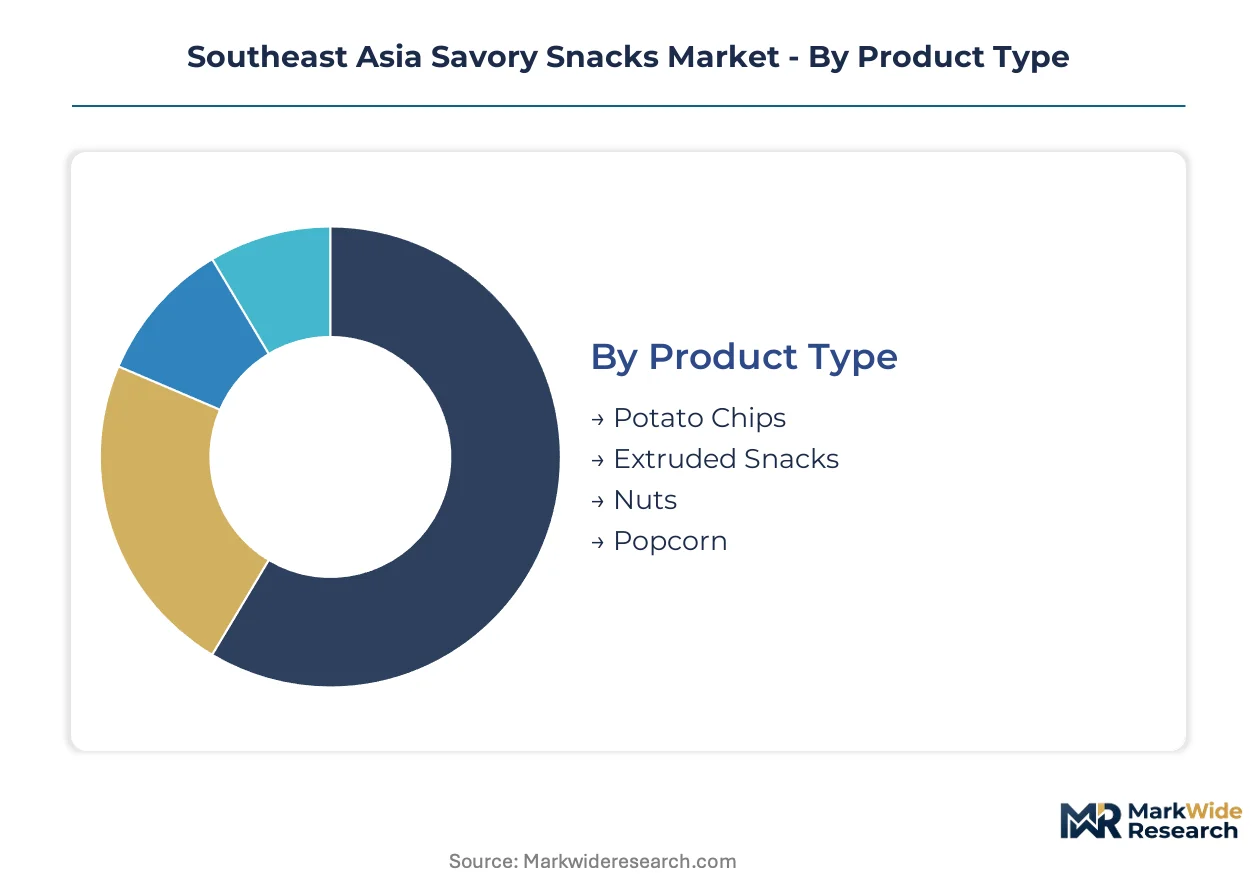
Segmentation in the Southeast Asia savory snacks market reveals how manufacturers allocate capital across competing margin pools. Product format, flavor intensity, packaging technology, and channel access each command distinct investment priorities across Indonesia, Thailand, Vietnam, and the Philippines.
Product Type:
Margin pools concentrate most heavily in extruded snacks and nuts, where input cost control and premium positioning create divergent profitability profiles.
- Extruded Snacks:Manufactured through high-pressure thermal processing of starch-based doughs into puffed or shaped formats. Demand clusters in Indonesia's Greater Jakarta corridor and Vietnam's Ho Chi Minh City metro area, where young urban consumers prioritize convenient, shelf-stable formats that fit compressed meal schedules.
- Nuts:Roasted or seasoned tree nuts and legumes requiring specialized moisture control during processing. Premium positioning dominates urban convenience channels in Bangkok and Singapore, where health-conscious positioning supports higher price tiers than starch-based alternatives.
- Potato Chips:Thin-sliced tuber products fried or baked with regional oil compositions.
- Popcorn:Expansion-popped corn kernels with butter or savory coatings, gaining traction in cinema and entertainment venues.
Extruded snacks hold installed capacity across Indonesian and Thai manufacturing bases. Nuts are rotating up the share rankings through premium channel expansion in urban Southeast Asian markets.
Flavor Profile:
Spicy formulations command the steepest price premiums in Thailand, Vietnam, and Indonesia, where chili-derived heat intensity aligns with established palate preferences.
- Spicy:Chili-derived heat systems ranging from mild paprika to intense capsaicin extracts. Thailand's FDA sodium disclosure mandates are forcing reformulation of salt-forward taste architectures while preserving perceived intensity through alternate seasoning technologies.
- Sweet:Sugar or malt-based coatings balancing savory bases with regional dessert preferences. Demand concentrates in Philippine sari-sari store networks, where localized distribution partnerships serve underpenetrated rural corridors.
- Barbecue:Smoked tomato and molasses-based seasoning profiles adapted from Western formats.
- Sour Cream:Dairy-derived tangy coatings popular in urban convenience retail across Singapore and Kuala Lumpur.
Spicy variants hold installed capacity across Thai and Indonesian flavor houses. Sweet profiles are climbing the fastest through rural Philippine distribution expansion.
Packaging Type:
Pouch adoption is accelerating fastest in humid climate conditions where resealability determines ambient shelf stability.
- Pouches:High-barrier coextruded films replacing metallized laminates in premium lines, cutting material thickness while maintaining oxygen transmission resistance. Bangkok and Singapore urban convenience retailers specify these formats for shelf life extension.
- Bags:Traditional metallized or clear film formats for standard-tier products with shorter consumption windows.
- Cans:Rigid metal containers for gift sets and premium nut assortments in Malaysian and Indonesian holiday markets.
- Boxes:Paperboard secondary packaging for multi-pack configurations in modern trade channels.
Bags hold installed capacity across legacy extruded snack lines. Pouches are gaining share fastest through climate-specific spoilage risk mitigation.
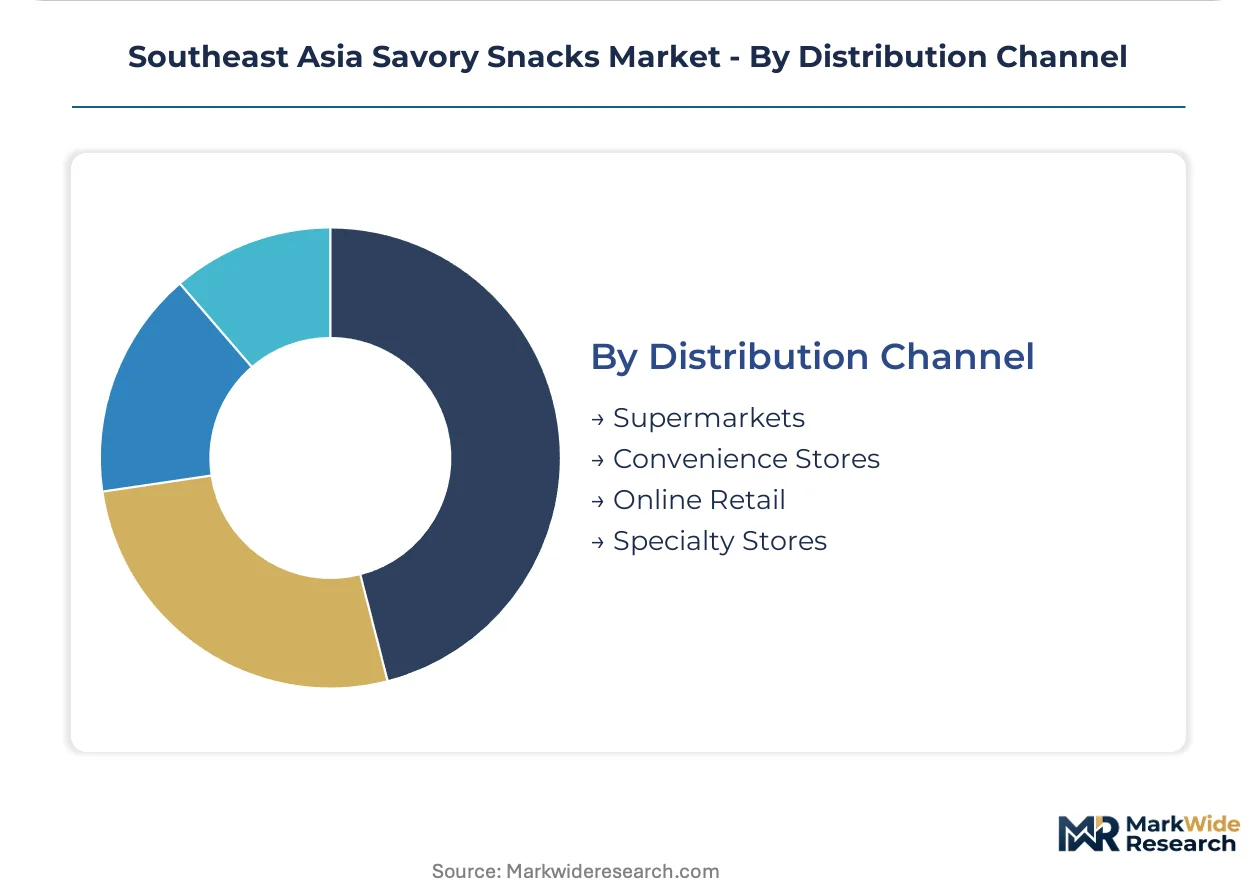
Distribution Channel:
Direct-to-retailer procurement is displacing traditional intermediaries in Vietnam's modern trade, consolidating supplier relationships around logistics efficiency.
- Convenience Stores:Ho Chi Minh City chains are consolidating supplier relationships to capture private label development capabilities, most visible in nuts where quality auditing favors vertically integrated processors.
- Supermarkets:Modern trade formats in Jakarta and Manila requiring halal certification under MUI Indonesia for shelf access in Muslim-majority catchments.
- Online Retail:E-commerce platforms serving premium snack discovery in Singapore and Kuala Lumpur urban households.
- Specialty Stores:Curated retail formats for imported or artisanal positioning in Bangkok and Jakarta premium districts.
Supermarkets hold installed capacity across established brand portfolios. Convenience stores are expanding most quickly through direct procurement consolidation in Vietnamese urban corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Halal certification harmonization talks and prepackaged food standardization initiatives are redrawing competitive boundaries across Southeast Asian snack markets. National regulators in Indonesia, Thailand, Vietnam, Malaysia, and the Philippines are tightening disclosure requirements while urban consumption clusters concentrate demand in specific metropolitan corridors.
Indonesia
Young consumers in Greater Jakarta drive demand for convenient, flavor-forward formats that fit compressed meal schedules. BPOM enforces strict additive and labeling standards that manufacturers must satisfy before commercial release. Surabaya and Bandung manufacturing bases host integrated palm oil supply chains that control input costs for extruded snack production.
Thailand
Spicy flavor preferences align with established palate preferences for chili-derived heat intensity across Bangkok urban convenience channels. FDA nutritional disclosure mandates are forcing reformulation of sodium and saturated fat levels in extruded categories. Chonburi coastal processing facilities anchor the country's seaweed snack segment through specialized marine-based raw material handling.
Vietnam
Ho Chi Minh City metro area consumers prioritize shelf-stable formats with resealable packaging for humid climate conditions. Direct-to-retailer procurement contracts are displacing traditional distributor intermediaries in modern trade channels. Da Nang and Hanoi convenience store networks are consolidating supplier relationships to capture logistics efficiencies.
Malaysia
JAKIM halal protocols create parallel compliance tracks for export-oriented producers serving Middle Eastern markets. Premium nut assortments in gift sets dominate holiday markets in Kuala Lumpur and Penang. Selangor processing facilities concentrate polymer film imports for high-barrier pouch production serving regional distribution.
Philippines
Sari-sari store networks in rural corridors remain underdeveloped by premium international brands, creating whitespace for localized distribution partnerships. Universal Robina Corporation dominates distribution networks extending into rural areas that competitors struggle to penetrate. Cebu and Davao manufacturing clusters support extruded snack capacity for archipelago-wide distribution.
Southeast Asia Savory Snacks Market Competitive Landscape
Player mix skews toward integrated domestic conglomerates with captive supply chains and multinational FMCG operators with brand portfolios. Market structure concentrates around three strategic archetypes: palm oil-integrated Indonesian manufacturers, coastal marine processors in Thailand, and Philippine distribution network owners. Dominant competitive moves include backward integration into edible oil supply and direct-to-retailer procurement consolidation in Vietnamese modern trade.
Within the integrated supply chain tier, PT Garudafood Putra Putri Jaya Tbk and Universal Robina Corporation exemplify domestic conglomerates that anchor national distribution infrastructure. Tao Kae Noi Food & Marketing PCL occupies a specialist position representing Thailand's coastal processing archetype. These three entities collectively illustrate how geographic control over raw material inputs and last-mile channel access determine competitive positioning in Muslim-majority and archipelago markets.
| Leading Market Players |
|---|
| PT Garudafood Putra Putri Jaya Tbk |
| Tao Kae Noi Food & Marketing PCL |
| Mondelēz International |
| Calbee Inc. |
| Monde Nissin Corp. |
| PepsiCo Inc. |
| Universal Robina Corporation |
| Want Want Holdings Ltd. |
| Kellanov |
| Others |
Value Network & Pricing Analysis
High-barrier coextruded film substitution for metallized laminates is redrawing input cost curves while compressing material thickness requirements, simultaneously shifting polymer sourcing toward Selangor processing clusters and eroding legacy packaging premiums in Bangkok convenience channels.
Pricing Analysis
Halal certification tier under MUI Indonesia and JAKIM Malaysia creates the primary price spread across Muslim-majority retail catchments. Pricing stratifies across MUI-certified premium, JAKIM-compliant standard, and non-certified economy tiers. Cost compression in economy extruded lines is intensifying because palm oil input volatility squeezes manufacturers lacking integrated supply chains. Sari-sari store networks in rural Philippine corridors exhibit highest price sensitivity, while Singapore convenience channels absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Port congestion at Tanjung Priok and Laem Chabang is elevating inbound logistics costs for specialty polymer film imports from Northeast Asian producers. Manufacturing gravity centers on Indonesia, Thailand, and Vietnam, where extrusion capacity clusters near palm oil refining and coastal seaweed processing. Raw material dependencies draw from edible oil markets, marine biomass harvests, and imported high-barrier film substrates. Single-source vulnerability concentrates with limited regional polymer processing capacity. Distribution runs through modern trade consolidation in Ho Chi Minh City and legacy distributor networks in Philippine archipelago markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
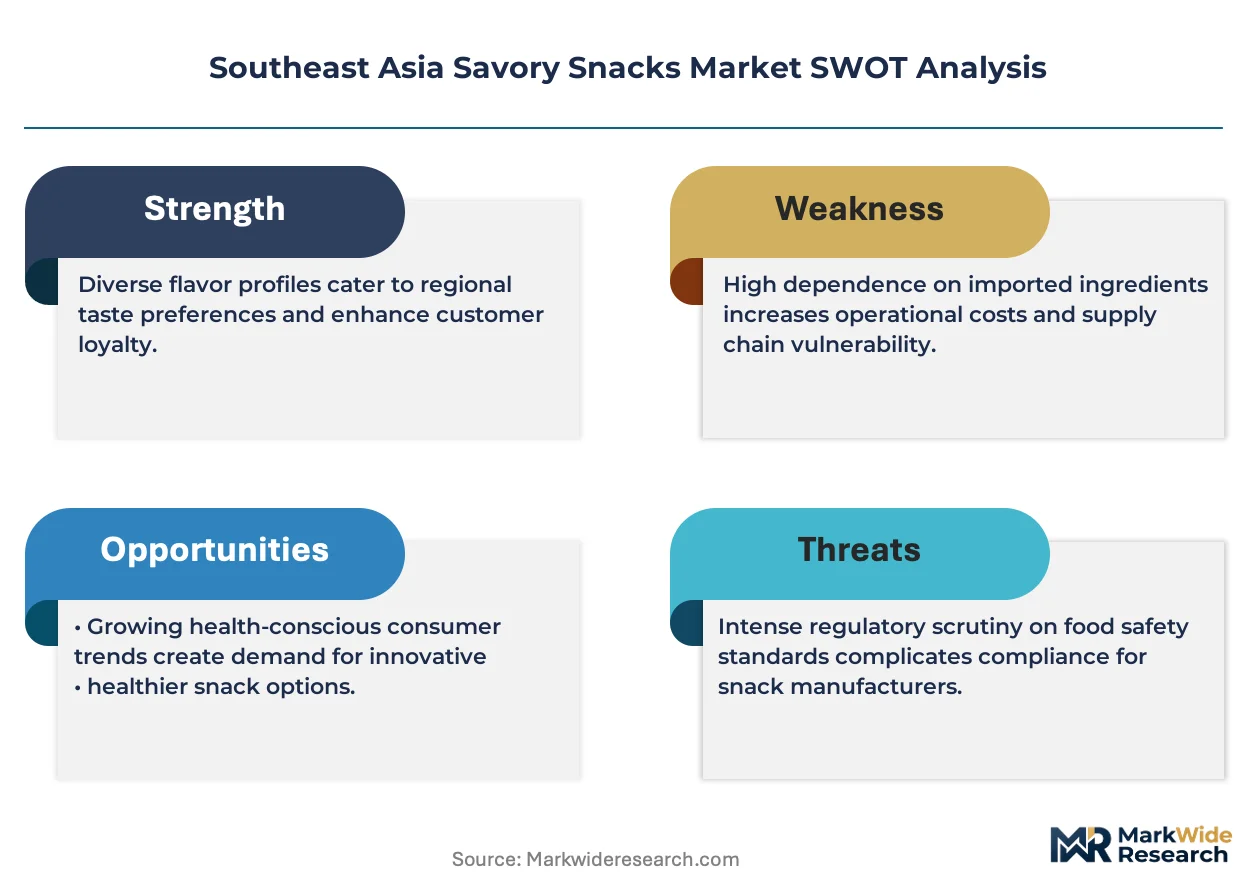
This market functions as a defensive-moat structure where regulatory entrenchment through dual halal certification requirements creates switching costs that lock in compliant incumbents and exclude capital-constrained challengers.
For Market Incumbents: Consolidate halal audit capabilities through captive certification officer training programs, reducing reliance on scarce MUI-JAKIM dual-qualified talent. Deepen backward integration into palm oil supply to defend margin position against commodity volatility. Priority lever rests on pre-emptive BPOM additive compliance investment ahead of reformulation cycle compression. For New Entrants and Emerging Players: Rural Philippine distribution service gaps present whitespace where localized sari-sari store partnerships bypass Universal Robina Corporation's entrenched network control. Spicy flavor premiumization in Vietnamese urban corridors offers penetrable positioning against legacy mild-format portfolios. Go-to-market angle centers on direct-to-retailer procurement contracts with Ho Chi Minh City convenience chains seeking private label development capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indonesian snack manufacturers holding MUI certification but lacking JAKIM compliance for Malaysian export expansion. Five-to-ten-year viability hinges on ASEAN harmonization momentum eliminating redundant certification tracks. Signal to monitor: BPOM-Thailand FDA regulatory convergence timeline as inflection indicator for compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Expansion | JAKIM compliance unlocks Malaysian retail shelf access and Middle Eastern export corridors for Indonesian manufacturers. |
| Resealable Pouch Format Conversion | High-barrier coextruded films address humid climate spoilage risks in Bangkok and Ho Chi Minh City ambient distribution. |
| Direct-to-Retailer Procurement Consolidation | Vietnamese convenience chains capture logistics efficiencies and private label development capabilities through supplier concentration. |
| Rural Philippine Distribution Partnerships | Sari-sari store network penetration bypasses entrenched Universal Robina Corporation control in archipelago markets. |
| Sodium-Reduced Reformulation Investment | Thailand FDA disclosure mandates force alternate seasoning technologies preserving perceived intensity in spicy flavor architectures. |
Research Methodology
A standing panel of category buyers at Indonesian supermarket chains, Thai FDA regulatory affairs specialists, Vietnamese convenience store procurement heads, and Philippine sari-sari store cooperative managers provided ongoing calibration across primary fieldwork. Secondary validation drew from BPOM additive disclosure filings, Thailand FDA nutritional labeling submissions, ASEAN harmonization negotiation records, and Nielsen retail audit data for Southeast Asian snack categories. Bottom-up demand modeling triangulated against top-down macro consumption indicators.
Consistency checks validated volume and value outputs against regional edible oil price indices and polymer film import trade data across the projection horizon. Segmentation dimensions modeled include product format, flavor intensity tier, packaging technology, and distribution channel access, with regulatory compliance status as an industry-specific overlay. CAGRs derived from installed capacity expansion schedules and urban consumption cluster penetration rates, cross-referenced against palm oil supply elasticity and halal certification completion timelines.
Forecasts assume regulatory continuity in Indonesia's BPOM additive standards and Thailand's FDA disclosure mandates; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Italy Snack Bar Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Thailand Snack Bar Market
Snacks
India Snack Bar Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Europe Popcorn Market
Snacks
Protein Bars Market
Snacks
China Snack Bar Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
Fat Free Snacks Market
Snacks
Spain Energy Bar Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
North America Baked Chips Market
Snacks
Low-Calorie Sweet Treats Market
Snacks
United Arab Emirates Energy Bar Market