
 UK Snack Market | 2026-2036
UK Snack Market Size, Share, and Industry Trends Forecast 2026-2036
UK Snack Market Insights
Subscription-based snack box services is broadening how brands build recurring revenue beyond impulse retail purchases. PepsiCo UK leverages its direct-to-consumer platforms to sustain repeat engagement outside supermarket aisles. Mondelēz International anchors its position through specialized gifting and personalized subscription tiers. pladis UK competes by integrating curated discovery models that extend brand reach into household pantries.
UK snacks encompass processed, ready-to-eat food items typically consumed between meals, manufactured through baking, extrusion, frying, or cold-pressing to achieve shelf-stable, portable formats with calibrated moisture content below five percent. These products serve commercial purposes ranging from convenience retail to targeted nutritional supplementation. Chips and nuts occupy mature volume positions with established margin pools, while granola bars and popcorn capture faster structural growth as protein-fortified and clean-label variants expand. Distribution through online retailers concentrates the highest growth velocity, though supermarkets still dominate absolute value capture.
The Food Standards Agency enforces HFSS placement restrictions that reshape where high-fat, high-sugar products appear in retail environments. BSI standards and evolving DEFRA sustainability requirements further govern packaging recyclability and ingredient provenance claims. Stakeholders must monitor how regulatory tightening on formulation thresholds interacts with shifting consumer willingness to pay for permissible indulgence formats.
Market Dynamics
HFSS placement restrictions are compressing retail visibility for traditional snack formats while simultaneously accelerating investment in reformulation pipelines and alternative channel strategies.
Growth Catalysts
- Protein fortification technology:Extrusion and cold-pressing advances enable 15-20 gram protein loads in shelf-stable bars without texture degradation, opening sports nutrition adjacent demand.
- DEFRA packaging mandates:Extended producer responsibility schemes accelerate shift to mono-material flexible films and home-compostable laminates, creating first-mover advantages for compliant suppliers.
- England urban corridor density:London and Manchester commuter rail networks sustain grab-and-go consumption velocity unmatched by suburban or rural catchments.
Market Restraints
- Input cost volatility:Sunflower oil and whey protein concentrate prices swing with Black Sea supply disruptions and dairy commodity cycles, squeezing margin predictability.
- Retail placement compression:Food Standards Agency HFSS end-cap and checkout prohibitions force reliance on less productive mid-aisle positions for non-reformulated lines.
- Clean-label technical ceiling:Natural preservation systems struggle to match sorbate-benzoate shelf life above nine months, constraining distribution radius for artisan-positioned entrants.
Strategic Opportunities
- Scottish and Welsh market penetration:Edinburgh, Glasgow, and Cardiff retail and foodservice channels show lower protein-bar saturation than English equivalents, offering whitespace for format introduction.
- Direct-to-consumer subscription mechanics:Curated discovery boxes bypass supermarket gatekeeping entirely, capturing household pantry access with recurring revenue models.
- BSI PAS 2050 carbon labeling:Early adoption of standardized footprint disclosure creates differentiation as Scope 3 reporting pressure intensifies across UK grocery retail.
Industry Challenges
- Reformulation R&D timelines:HFSS threshold compliance requires 18-24 month sensory and stability testing cycles, delaying revenue recapture from delisted legacy SKUs.
- Legacy ERP integration:Batch-level traceability for DEFRA packaging return schemes conflicts with decades-old manufacturing execution systems, demanding costly middleware deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Snack Market |
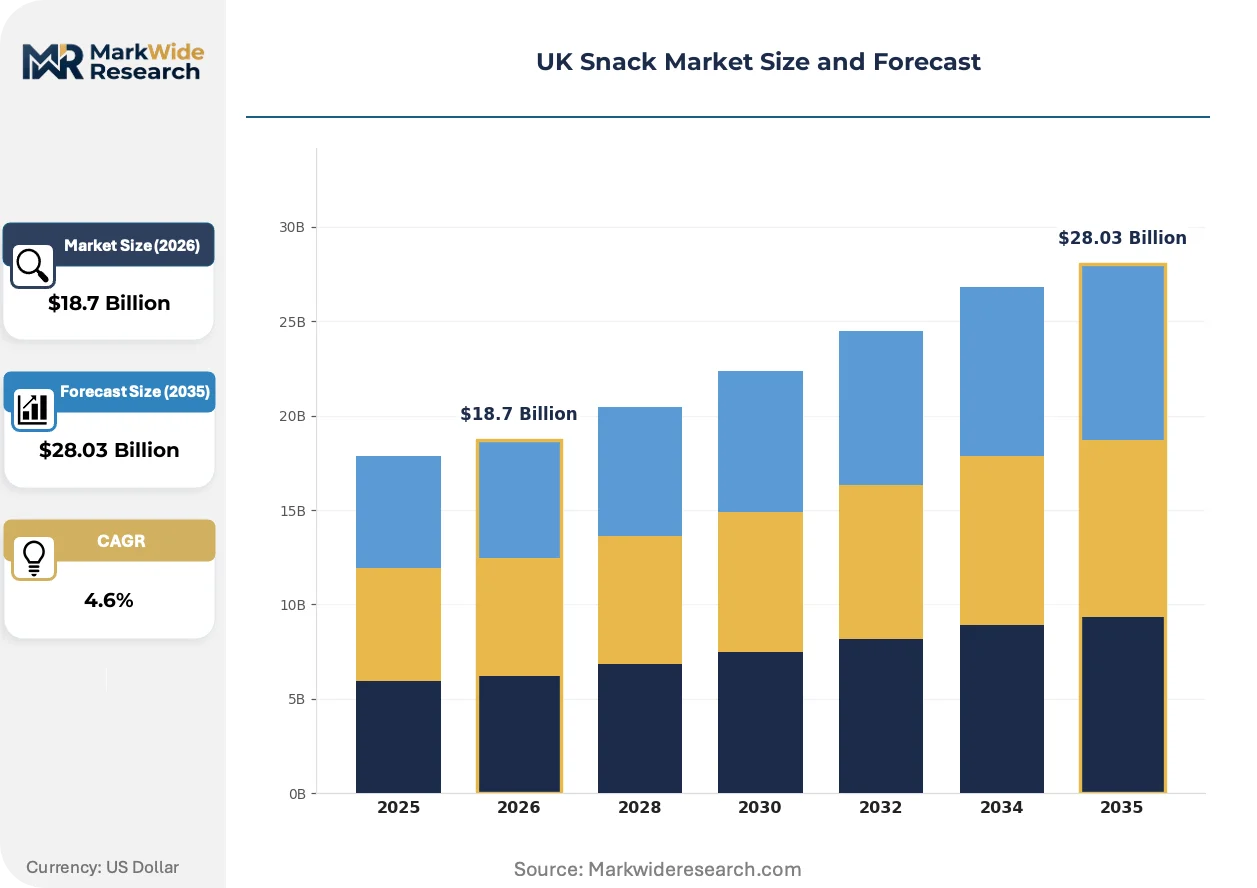
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Nuts, Granola Bars, Popcorn Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Vending Machines Customer Type: Children, Adults, Health-Conscious Consumers, Millennials Flavor Profile: Sweet, Savory, Spicy, Chocolate |
| Companies Covered | PepsiCo UK, Mondelēz International, pladis UK, Kellanova, Nestlé UK, Mars Incorporated, Associated British Foods, Burton's Biscuit Company, Tyrrells Potato Crisps, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Snack Market Trends and Innovations
Reformulation science and distribution architecture are diverging sharply from legacy snack manufacturing paradigms, creating bifurcation between permissible indulgence formats and conventional portfolio decline.
Precision fermentation-derived proteins are converging with traditional extrusion infrastructure to enable cost-parity dairy and egg replacements in baked and puffed applications. Mid-tier manufacturers in the Midlands and Yorkshire are piloting these inputs at 10-15% inclusion rates. The technology is converging with established capital equipment, avoiding greenfield facility requirements while accelerating clean-label claim viability.
The Food Standards Agency's 2022 location restrictions and pending volume-based HFSS thresholds are forcing portfolio rationalization toward sub-200 calorie single-serve formats. Retailers including Tesco and Sainsbury's are delisting non-compliant lines ahead of statutory deadlines. Confectionery and savory snack segments bear the heaviest reformulation burden, with sugar reduction targets technically more achievable than fat restructuring in fried applications.
Subscription-based household replenishment is displacing impulse-driven supermarket purchasing among metropolitan professionals aged 25-40. Curated monthly boxes from specialized operators capture pantry shelf space through algorithmic preference matching and exclusive flavor drops. This pattern concentrates in Greater London and Greater Manchester, where delivery density supports economically viable last-mile economics absent in smaller urban centers.
UK Snack Market Segmentation
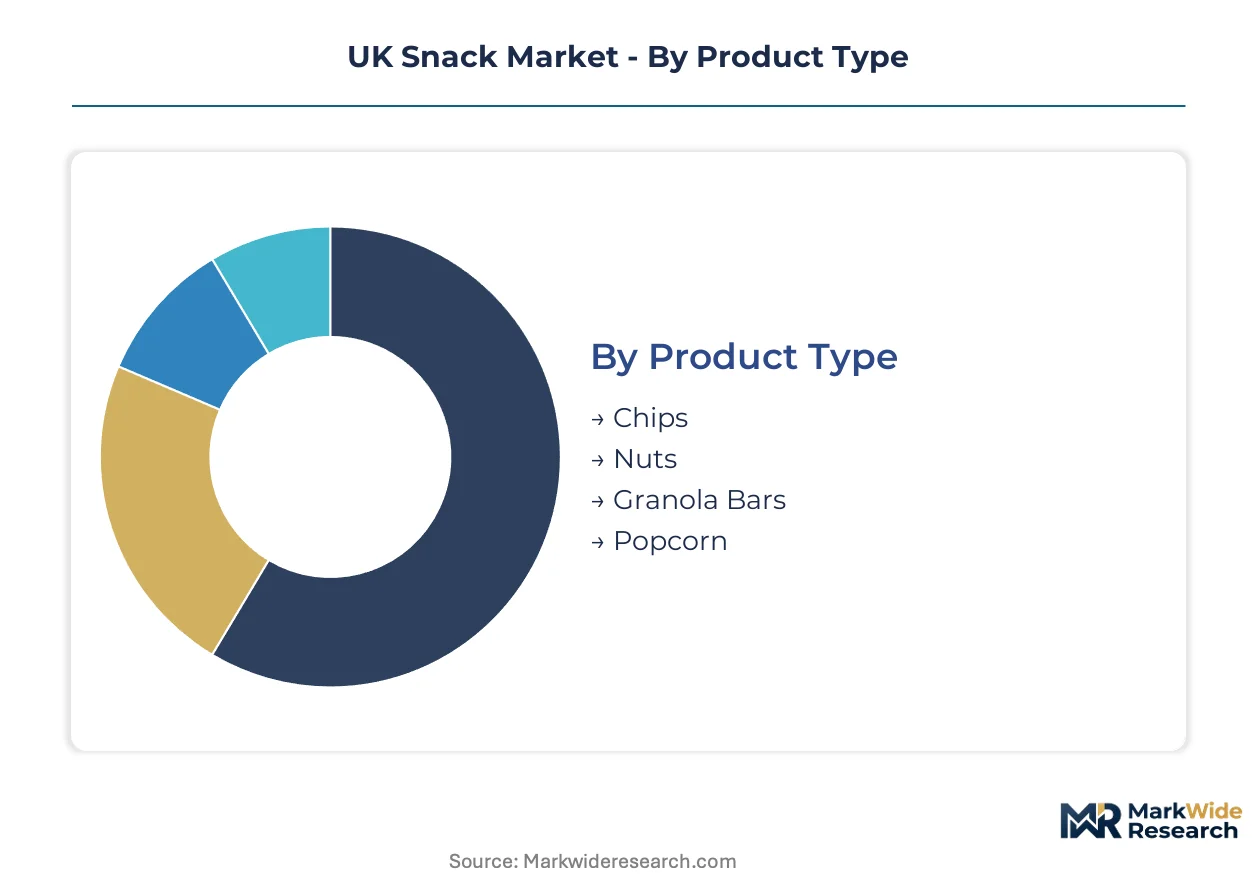
Segmentation in the UK snack market reveals how reformulation pressures and channel fragmentation create divergent growth trajectories across product formats. Understanding these splits enables targeted resource allocation toward compliant, high-velocity categories.
Product Type:
Extrusion and cold-pressing capabilities differentiate shelf-stable formats by protein load capacity and moisture retention thresholds.
- Chips:Fried or baked potato and vegetable slices with sub-five-percent moisture content dominate absolute volume through established manufacturing infrastructure in the Midlands. England's urban corridors sustain impulse purchase velocity despite HFSS placement restrictions compressing checkout visibility.
- Nuts:Roasted, salted, or flavored tree nuts and legumes carry premium positioning through protein density and clean-label compatibility. Demand concentrates in London and Manchester where commuter rail networks support grab-and-go consumption patterns unmatched by smaller catchments.
- Granola Bars:Cold-pressed or extruded oat and nut clusters with binding syrups enable 15-20 gram protein fortification without texture degradation.
- Popcorn:Air-popped or oil-popped maize kernels offer low-calorie bases for flavor innovation with shorter ingredient decks than fried alternatives.
Chips leads on scale; granola bars leads on momentum.
Distribution Channel:
Channel economics vary sharply by inventory turnover requirements and last-mile delivery density.
- Supermarkets:Tesco, Sainsbury's, and Asda dominate absolute value capture through centralized distribution and promotional scale. HFSS end-cap and checkout prohibitions force non-reformulated lines into less productive mid-aisle positions, eroding impulse conversion rates.
- Online Retailers:Amazon UK, Ocado, and direct-to-consumer platforms concentrate the steepest expansion trajectory through subscription mechanics and algorithmic personalization. Greater London and Greater Manchester delivery density supports economically viable last-mile economics absent in smaller urban centers.
- Convenience Stores:Co-op and independent forecourt operators sustain emergency replenishment occasions with limited SKU breadth.
- Vending Machines:Rail station and workplace automated retail captures captive audience moments with restricted permissible product ranges under Food Standards Agency guidelines.
Supermarkets anchor current revenue; online retailers capture future share.
Customer Type:
Demographic targeting aligns with occasion specificity and nutritional claim receptivity.
- Health-Conscious Consumers:Protein-seeking, label-reading shoppers aged 25-45 drive reformulation investment and premium price acceptance. Subscription box adoption concentrates among this cohort in metropolitan England where discovery-oriented purchasing displaces supermarket loyalty.
- Millennials:Urban professionals prioritize convenience, ethical sourcing claims, and social media-compatible packaging aesthetics.
- Adults:Broad working-age population sustains baseline volume through habitual brand selection.
- Children:School-age consumption faces strictest HFSS advertising and placement constraints, compressing permissible format innovation.
Adults provide volume foundation; health-conscious consumers command margin expansion.
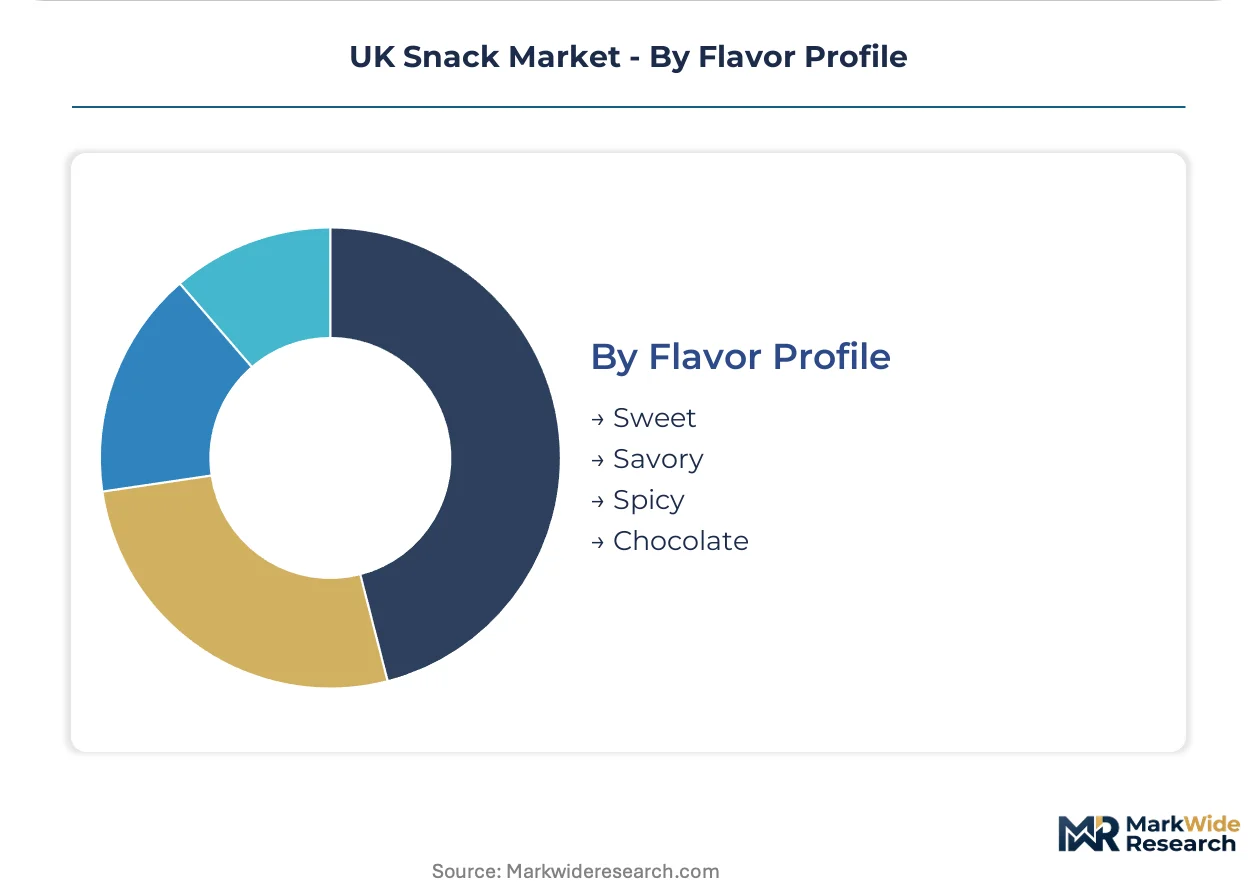
Flavor Profile:
Taste architecture interacts directly with reformulation feasibility and regional preference variation.
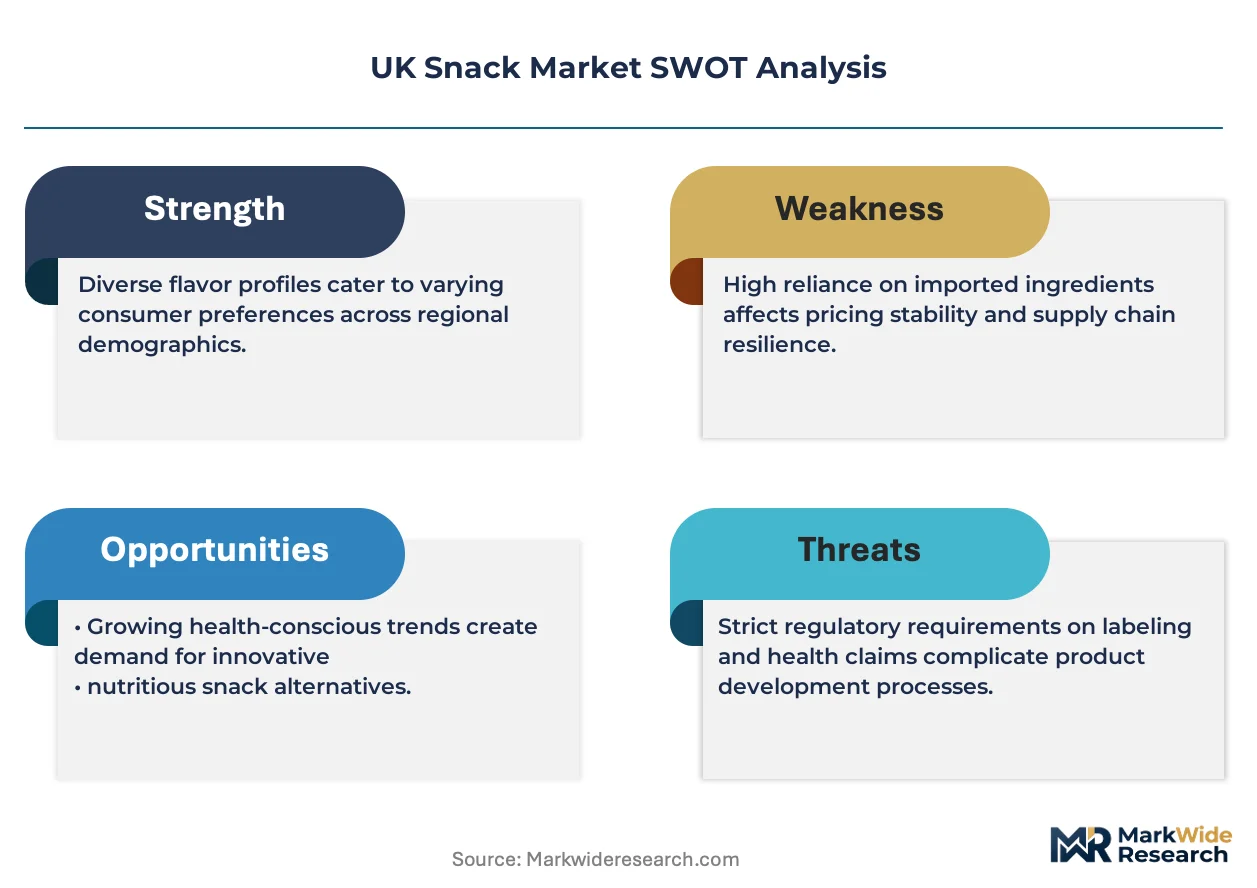
- Savory:Salt, cheese, and umami seasonings dominate mature chip and nut applications with established supplier ecosystems. Scotland and Wales show distinct preference profiles versus English equivalents, offering whitespace for localized format introduction.
- Sweet:Sugar and alternative sweetener systems face steepest technical challenge under HFSS threshold compliance, demanding 18-24 month R&D cycles.
- Spicy:Chili, wasabi, and pepper variants attract experimental younger demographics with higher trial willingness.
- Chocolate:Coated and enrobed applications carry highest fat and sugar loads, bearing heaviest delisting risk from retailer compliance programs.
Savory maintains stable share; spicy gains trial frequency fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England commands disproportionate snack consumption velocity compared to Scotland and Wales, driven by commuter rail density and urban corridor purchasing patterns. The Food Standards Agency enforces uniform HFSS placement restrictions across all four UK nations, yet enforcement intensity and retailer compliance timelines vary by local authority. Regional differentiation emerges through distribution infrastructure maturity rather than regulatory divergence.
England
London and Manchester commuter networks sustain the highest grab-and-go consumption velocity in the UK, with rail station vending and convenience retail capturing captive audience moments. The Food Standards Agency's HFSS end-cap and checkout prohibitions force reformulated products into premium aisle positions while delisting non-compliant legacy lines ahead of statutory deadlines. PepsiCo UK and Mondelēz International anchor manufacturing and distribution infrastructure in the Midlands and Greater London corridors.
Scotland
Edinburgh and Glasgow retail channels show lower protein-bar category saturation than English equivalents, offering whitespace for format introduction by specialist operators. Scotland's devolved health policy under NHS Scotland guidelines maintains stricter nutritional profiling for public sector procurement than England's equivalent standards. Burton's Biscuit Company maintains production facilities in the Scottish Central Belt serving domestic and export demand.
Wales
Cardiff and Swansea metropolitan areas present underpenetrated subscription box delivery economics compared to English urban centers, with lower last-mile density constraining curated service viability. The Welsh Government's Well-being of Future Generations Act imposes sustainability reporting requirements on suppliers to public institutions that exceed baseline UK packaging regulations. Local convenience retail chains compete with English-based operators for shelf space in the South Wales corridor.
Northern Ireland
Belfast and Derry retail markets operate with distinct distribution logistics due to Irish Sea border arrangements, creating inventory management complexity for GB-based manufacturers. The Northern Ireland Protocol maintains alignment with EU food safety standards through EFSA oversight, generating dual compliance obligations for cross-border product flows. Tyrrells Potato Crisps sources raw materials from established supplier relationships spanning the island of Ireland.
UK Snack Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational FMCG conglomerates commanding supermarket shelf space while regional craft operators capture subscription channel growth. The market structure concentrates around three strategic archetypes: diversified global snack portfolios, single-category premium specialists, and private-label contract manufacturers serving retailer own-brands. Competitive moves center on reformulation R&D pipelines for HFSS compliance and direct-to-consumer platform builds that bypass traditional retail gatekeeping. Geographic expansion into Scottish and Welsh whitespace markets represents a secondary vector for volume growth.
Within the diversified multinational tier, PepsiCo UK and Mondelēz International exemplify scale-driven portfolio breadth spanning savory, sweet, and better-for-you formats. These operators occupy positions defined by centralized procurement leverage and promotional scale economics. Pladis UK represents a distinct archetype as a UK-headquartered specialist with concentrated biscuit and snacking expertise, sitting within a structure that prioritizes regional market responsiveness over global harmonization. The competitive dynamic between these three anchors shapes shelf space allocation, reformulation investment pacing, and subscription service launch timing across English urban corridors and adjacent UK markets.
| Leading Market Players |
|---|
| PepsiCo UK |
| Mondelēz International |
| pladis UK |
| Kellanova |
| Nestlé UK |
| Mars Incorporated |
| Associated British Foods |
| Burton's Biscuit Company |
| Tyrrells Potato Crisps |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap snack manufacturers anchor supply discipline across the Midlands and Yorkshire, translating generational capital structures into patient pricing power that resists commodity-driven margin erosion. Their ownership model sustains long-term supplier relationships and defensible shelf positions against private-equity-rolled competitors chasing quarterly yield.
Pricing Analysis
Capacity additions in the Midlands are reshaping price floors for extruded and cold-pressed formats as regional manufacturers expand protein-fortification lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein load and HFSS compliance status, with reformulated variants commanding shelf-space premiums. Pricing pressure stems from sunflower oil and whey protein concentrate volatility, squeezing margin predictability for non-integrated operators. Value-oriented buyers in convenience retail show highest price sensitivity, while subscription-channel health-conscious consumers accept premium positioning for clean-label claims.
Supply Chain Analysis
Single-source vulnerability sits with Black Sea sunflower oil suppliers, exposing UK manufacturers to geopolitical disruption cascades. Raw material flows draw from Ukraine, Argentina, and domestic rapeseed processors for oil inputs, with whey protein concentrate sourcing anchored in Irish and Dutch dairy processing infrastructure. Supply chain risk centers on tariff exposure under post-Brexit rules-of-origin complexity for cross-border ingredient movements. Distribution runs through centralized Midlands manufacturing hubs into Tesco, Sainsbury's, and Asda networks, with direct-to-consumer platforms bypassing traditional wholesaler tiers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK snack market operates as a regulatory compounder where Food Standards Agency HFSS placement restrictions and pending volume-based thresholds continuously reshape permissible demand. Compliance-driven reformulation creates recurring investment cycles that favor operators with R&D scale and patient capital.
For Market Incumbents: Acquire cold-pressing and extrusion technology assets to secure protein-fortification capabilities ahead of capacity constraints. Consolidate Scottish and Welsh distribution infrastructure to capture whitespace in lower-saturation corridors. Defend against subscription-native entrants by building direct-to-consumer algorithmic personalization platforms that replicate curated discovery mechanics. For New Entrants and Emerging Players: Direct-to-consumer subscription routes offer the lowest barrier to pantry access, bypassing supermarket gatekeeping entirely. Target Edinburgh, Glasgow, and Cardiff retail channels where protein-bar category saturation trails English equivalents by meaningful margins. Enter through BSI PAS 2050 carbon-labeled positioning that differentiates against legacy portfolios facing Scope 3 reporting pressure. For Investors and Strategic Acquirers: Valuations sit cheapest among Midlands contract manufacturers with reformulation R&D capabilities and DEFRA packaging compliance infrastructure. Long-term viability favors operators with integrated extrusion assets and subscription-channel revenue mix above threshold levels. Watch for Food Standards Agency volume-based HFSS threshold announcements as the signal for accelerated portfolio rationalization and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| HFSS Reformulation Pipeline | Enables shelf retention under Food Standards Agency placement restrictions while capturing permissible indulgence premium positioning. |
| Direct-to-Consumer Platform Build | Bypasses Tesco and Sainsbury's gatekeeping to capture recurring revenue through algorithmic personalization and exclusive flavor drops. |
| Scottish and Welsh Market Entry | Exploits lower protein-bar saturation in Edinburgh, Glasgow, and Cardiff relative to London and Manchester corridors. |
| BSI PAS 2050 Carbon Labeling Adoption | Creates differentiation as Scope 3 reporting pressure intensifies across UK grocery retail procurement criteria. |
| Mono-Material Packaging Transition | Secures first-mover advantage under DEFRA extended producer responsibility schemes ahead of statutory deadlines. |
Research Methodology
Direct dialogue with brand managers, category buyers at Tesco and Sainsbury's, channel sales heads, and supply planners grounded qualitative findings in operational reality. Secondary validation drew from Nielsen retail audit data, Food Standards Agency enforcement disclosures, DEFRA packaging regulation filings, and customs import records for sunflower oil and whey protein concentrate. Bottom-up SKU-level modeling triangulated against top-down category expenditure estimates to constrain variance bands.
Bottom-up volume builds aggregated individual product lines across chips, nuts, granola bars, and popcorn by protein load tier, HFSS compliance status, and distribution channel velocity. Top-down expenditure flows calibrated against UK household food consumption surveys and commuter rail network passenger density as demand proxies. CAGRs derived from segment-level growth rate distributions weighted by reformulation pipeline visibility and subscription-channel penetration curves. Forecast inputs incorporated extrusion capacity expansion timelines and Black Sea supply disruption probability scenarios.
The model assumes a particular technology adoption path for precision fermentation-derived proteins; alternative pathways for dairy and egg replacement would alter the outlook for clean-label claim viability and cost-parity timing. Forecasts reflect assumptions about Food Standards Agency enforcement intensity, DEFRA packaging mandate phase-in schedules, and sunflower oil supply normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Saudi Arabia Snack Bar Market
Snacks
United States Popcorn Market
Snacks
US Potato Chips Market
Snacks
Thailand Snack Bar Market
Snacks
Qatar Potato Chips Market
Snacks
UAE Cereal Bar Market
Snacks
Trail Mix Market
Snacks
Nachos Market
Snacks
Edible Flakes Market
Snacks
Allergy-Free Snacks Market
Snacks
Latin America Extruded Snack Food Market
Snacks
Low Sodium Snacks Market
Snacks
South America Snack Bar Market
Snacks
Sweet Potato Fries Market
Snacks
Fat Free Snacks Market
Snacks
On-The-Go Healthy Snacks Market