
 High-Fat Low-Protein Snacks Market | 2026-2036
High-Fat Low-Protein Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
High-Fat Low-Protein Snacks Market Analytics
The specialty snack aisle is narrowing as health-conscious consumers consolidate purchases around fat-forward, protein-minimal options. Nestlé S.A. leverages its global R&D infrastructure to sustain formulation leadership across European and North American retail networks. PepsiCo Inc. anchors its position through direct-store-delivery systems that dominate convenience channel placement. Mondelez International differentiates via premium packaging formats targeting on-the-go consumption occasions.
High-fat low-protein snacks are formulated products where lipid content exceeds protein by a ratio of at least three to one, typically achieved through nut butters, aged cheese matrices, or desiccated coconut substrates processed below 120 degrees Celsius to preserve fatty acid integrity. Their commercial purpose centers on sustaining ketone body production for consumers adhering to carbohydrate-restricted metabolic protocols. The nuts and seeds category leads volume contribution due to established supply chains and minimal processing requirements, while coconut chips represent the fastest-expanding margin pool as tropical sourcing contracts stabilize. Resealable pouches capture disproportionate shelf space growth in health food shops, reflecting retailer preference for portion-control merchandising that reduces spoilage-driven returns.
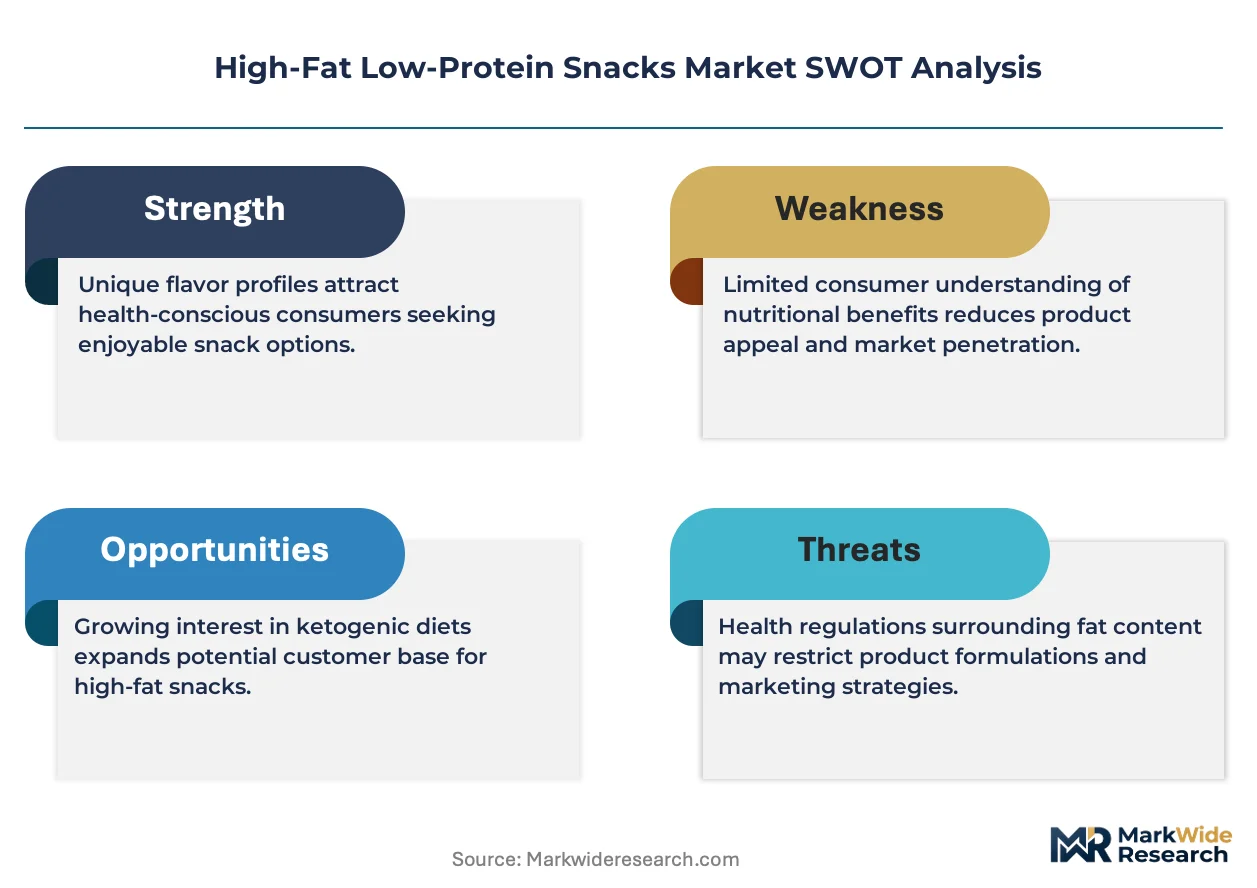
The FDA governs nutrition fact panel disclosures and health claim substantiation for products sold through U.S. supermarkets and online retail portals. EFSA evaluates novel food applications for coconut-derived ingredients entering European Union distribution channels, creating a dual-track compliance burden for multinational suppliers. FSSAI's stringent fat-content labeling mandates in India add complexity for brands seeking emerging market entry. Stakeholders must monitor evolving definitions of "healthy" across jurisdictions, as regulatory reinterpretation of dietary fat recommendations could abruptly reshape permissible marketing claims and reformulation timelines.
Market Dynamics
Clean-label reformulations are compressing formulation timelines as brands race to meet fat-adapted nutrition protocols while preserving shelf stability. The shift toward ketogenic dietary compliance is forcing simultaneous investments in low-temperature processing infrastructure and transparent supply chain documentation.
Growth Catalysts
- FSSAI Fat-Content Labeling Mandates:India's stringent disclosure requirements are accelerating clean-label innovation across export-oriented manufacturing facilities.
- Direct-to-Consumer Subscription Models:Specialty snack brands bypass traditional retail slotting fees through curated delivery platforms targeting metabolic health enthusiasts.
- Desiccated Coconut Substrates:Tropical sourcing contract stabilization enables margin expansion in coconut chip categories previously constrained by supply volatility.
Market Restraints
- Input Cost Volatility:Macadamia and pecan nut butter formulations face margin pressure from drought-induced harvest variability in Australian and Mexican growing regions.
- Supply Concentration Risk:Aged cheese matrix suppliers cluster in Wisconsin and Netherlands dairy cooperatives, creating geographic vulnerability to climate-driven feed grain shortages.
- EFSA Novel Food Application Burden:Coconut-derived ingredient approvals for EU distribution require eighteen-to-twenty-four month evaluation cycles that delay product launches.
Strategic Opportunities
- Brazilian Functional Food Aisle Expansion:ANVISA's streamlined health claim pathways for lipid-focused products open retail penetration in São Paulo and Rio de Janeiro metropolitan markets.
- Precision Fermentation Convergence:Microbial lipid production technologies intersect with traditional nut processing to create hybrid fat matrices with extended oxidative stability.
- Convenience Channel Placement:Direct-store-delivery systems dominate impulse purchase locations where ketogenic snack visibility was previously minimal.
Industry Challenges
- Refrigerated Supply Chain Reconfiguration:Aged cheese-based snacks require cold-chain infrastructure incompatible with ambient snack distribution networks.
- Ketone Body Efficacy Certification:Third-party metabolic testing protocols lack standardization, forcing brands to fund proprietary clinical validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Fat Low-Protein Snacks Market |
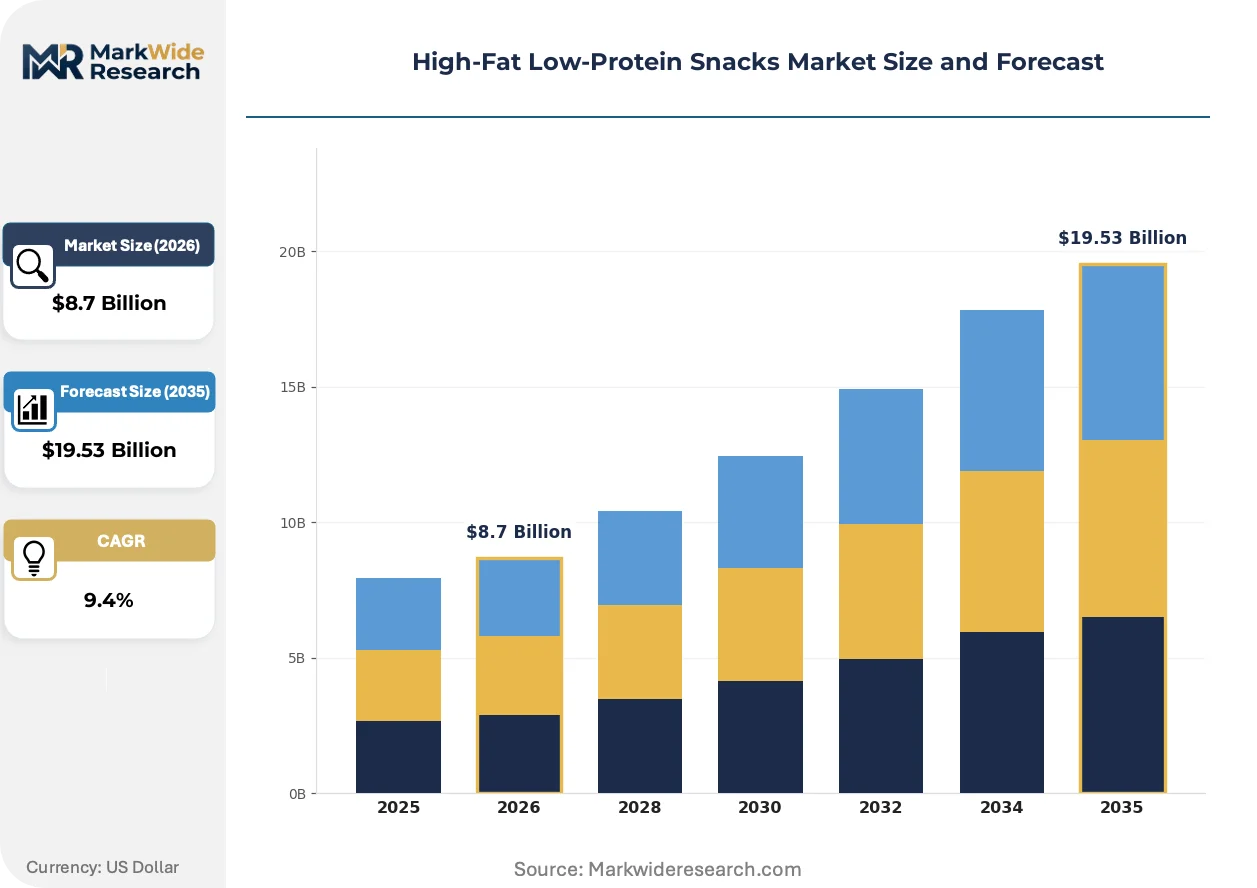
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nuts, Seeds, Cheese, Coconut Chips Flavor Profile: Spicy, Sweet, Savory, Tangy Packaging Type: Resealable Bags, Tubs, Pouches, Boxes Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops |
| Companies Covered | Nestlé S.A., PepsiCo Inc., General Mills Inc., Mondelez International, Kellanova, Unilever, Hormel Foods Corporation, Kind LLC, B&G Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Fat Low-Protein Snacks Market Evolving Landscape
Formulation science is pivoting toward lipid preservation technologies that maintain fatty acid integrity through distribution. These shifts are compressing product development cycles while expanding permissible marketing claims.
Cold-pressed oil infusion technology preserves omega-3 and omega-6 ratios in nut butter matrices without thermal degradation. Ketogenic diet adherents in United States specialty retail channels are adopting these products at accelerated purchase frequencies. The technology is migrating from artisanal production facilities to scaled manufacturing lines, enabling national distribution without reformulation.
EFSA's evolving interpretation of "healthy" dietary fat thresholds is reshaping permissible label claims across European Union member states. Manufacturers must maintain dual formulation specifications to satisfy both EFSA guidance and national enforcement variations. Coconut-derived snack categories face the steepest compliance burden as tropical fat sources remain under novel food scrutiny.
Subscription-based replenishment models are displacing conventional grocery aisle discovery for metabolic protocol adherents. Health food shops in United States coastal cities are ceding volume to algorithm-curated delivery platforms. This channel rotation concentrates buyer data with direct-to-consumer operators, compressing traditional retail negotiation leverage.
High-Fat Low-Protein Snacks Market Segmentation
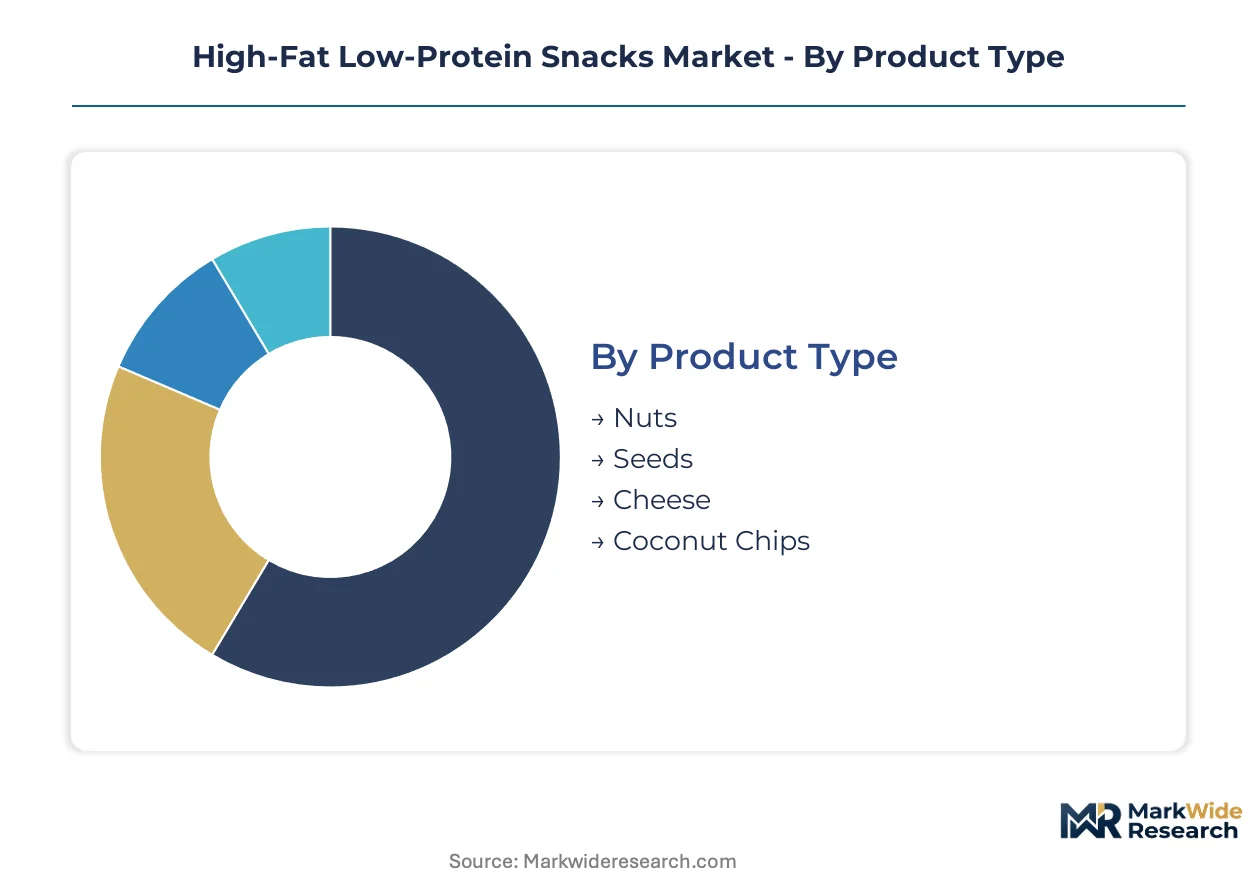
Segmentation in the high-fat low-protein snacks market reveals distinct velocity patterns across product categories. Cycle times vary dramatically from ambient-stable nut formats to refrigerated cheese matrices with compressed shelf lives.
Product Type:
Nuts and seeds turn inventory fastest through established commodity supply chains, while aged cheese substrates require extended curing cycles that slow production velocity.
- Nuts:Almond, macadamia, and pecan butters processed below 120 degrees Celsius preserve fatty acid integrity. United States specialty retail channels concentrate demand for single-origin nut butters as ketogenic diet adherence expands.
- Seeds:Pumpkin, sunflower, and hemp seed formulations achieve fat-to-protein ratios through cold-pressed oil concentration. Fitness-oriented consumers in coastal metropolitan markets drive repeat purchase frequency for portable seed-based formats.
- Cheese:Aged cheese matrices from Wisconsin and Netherlands cooperatives deliver concentrated lipid content through extended fermentation protocols.
- Coconut Chips:Desiccated coconut substrates sourced through stabilized tropical contracts now support scaled manufacturing without reformulation delays.
Nuts anchor the volume base while coconut chips gain share at the steepest rate.
Flavor Profile:
Cost tier differentiation separates commodity flavor applications from premium positioning through ingredient provenance and complexity layering.
- Spicy:Chili-infused nut butters and cayenne-dusted coconut chips command premium shelf placement through capsaicin-forward formulation science.
- Sweet:Monk fruit and erythritol-sweetened formats target carbohydrate-restricted metabolic protocols without glycemic impact.
- Savory:Nutritional yeast and herb-crusted cheese crisps dominate on-the-go consumption occasions through umami concentration.
- Tangy:Fermented flavor profiles from aged cheese matrices and cultured coconut products appeal to gut-health positioning trends.
Savory formulations anchor the volume base while spicy variants expand most quickly through premium channel penetration.
Packaging Type:
Application requirements dictate format selection, with portability needs driving flexible packaging innovation against stability demands favoring rigid containers.
- Resealable Bags:Multi-layer barrier films with zip-lock closures dominate health food shop merchandising, reducing spoilage-driven returns through portion control functionality.
- Tubs:Rigid polypropylene containers preserve nut butter consistency through temperature fluctuations in direct-to-consumer shipping.
- Pouches:Stand-up flexible formats with spouted closures enable single-serve consumption without utensil requirements.
- Boxes:Subscription-optimized corrugated formats with internal partitioning protect fragile coconut chip integrity through last-mile distribution.
Resealable bags anchor the volume base while pouches climb the fastest through convenience channel placement.
Distribution Channel:
Customer type concentration varies sharply, with metabolic protocol adherents clustering in curated channels while mainstream adoption flows through mass retail.
- Supermarkets:Specialty aisle expansion in United States retail networks creates visibility for fat-forward formulations previously confined to niche positioning.
- Online Retail:Algorithm-curated subscription platforms concentrate buyer data and displace conventional grocery discovery for ketogenic diet adherents.
- Convenience Stores:Direct-store-delivery systems from PepsiCo Inc. and comparable operators secure impulse purchase locations for single-serve formats.
- Health Food Shops:Coastal United States metropolitan clusters remain critical for new product introduction and clean-label validation.
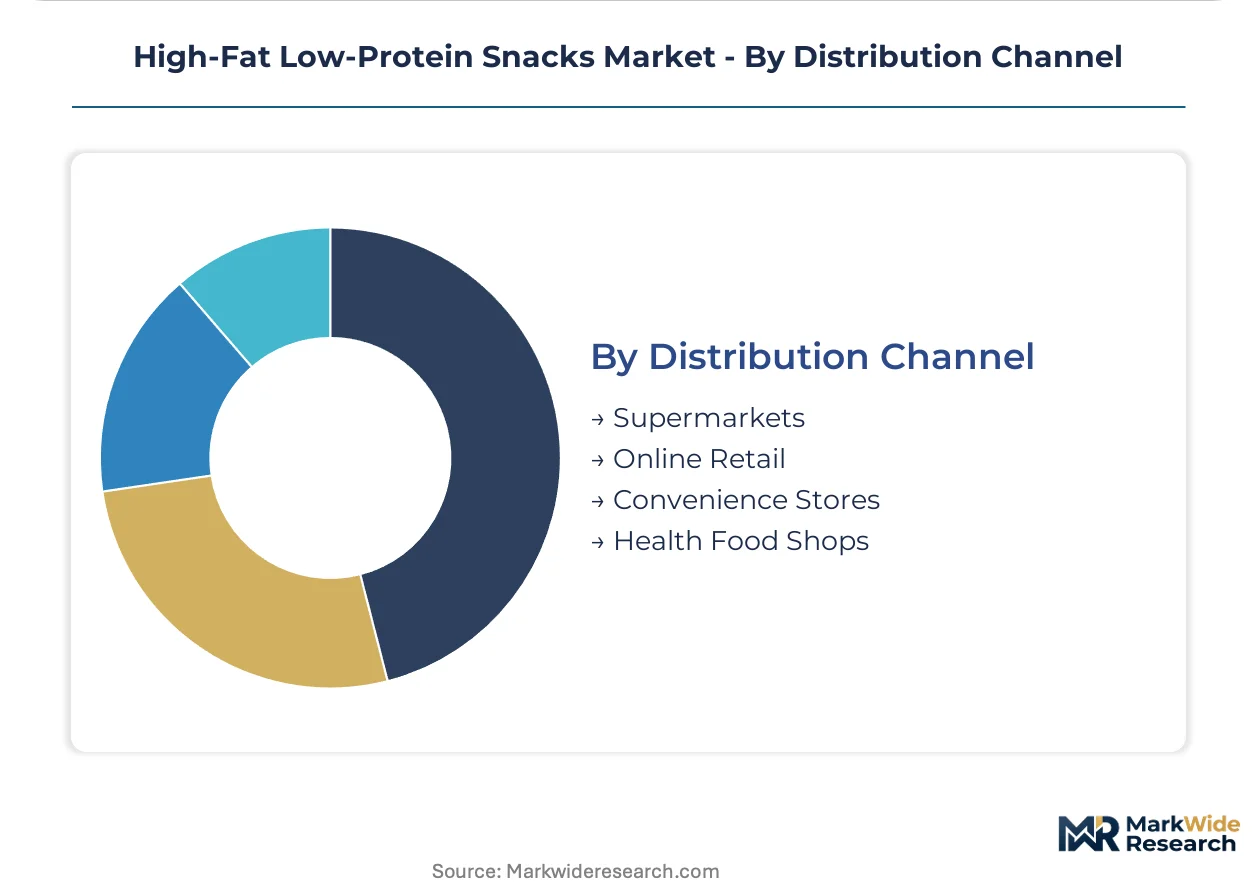
Supermarkets anchor the volume base while online retail demonstrates the steepest expansion trajectory through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition fact panel disclosures anchor commercial strategy in the United States, where specialty snack aisle expansion and direct-to-consumer subscription models concentrate metabolic protocol demand. EFSA novel food evaluations and FSSAI fat-content mandates create parallel compliance tracks across European and Indian distribution channels.
United States
Ketogenic diet adherence drives specialty retail channel expansion in coastal metropolitan clusters. FDA health claim substantiation requirements govern permissible marketing for fat-forward formulations. Greater Los Angeles and New York Metro health food shops anchor clean-label validation and new product introduction velocity.
Germany
EFSA novel food application pathways for coconut-derived ingredients shape product launch timelines for EU market entry. REACH compliance documentation requirements add formulation disclosure burdens for tropical fat sourcing. Bavaria and North Rhine-Westphalia retail networks concentrate demand for aged cheese matrix snacks through established dairy cooperative supply chains.
India
FSSAI stringent fat-content labeling mandates accelerate clean-label innovation in export-oriented manufacturing facilities. PLI scheme incentives for food processing infrastructure support domestic production scaling. Maharashtra and Gujarat industrial corridors host contract manufacturing facilities serving both domestic and international distribution.
Brazil
ANVISA streamlined health claim pathways for lipid-focused products enable retail penetration in São Paulo and Rio de Janeiro metropolitan markets. Functional food aisle expansion in premium supermarket channels creates visibility for imported ketogenic snack formats. Southeast regional distribution networks consolidate import logistics for tropical fat substrate supply.
Netherlands
EFSA regulatory interpretation of healthy dietary fat thresholds influences permissible label claims across EU member states. Dairy cooperative concentration in Friesland and Gelderland provinces supplies aged cheese matrices for high-fat snack formulations. Rotterdam and Amsterdam logistics hubs facilitate re-export distribution to broader European retail networks.
High-Fat Low-Protein Snacks Market Competitive Landscape
Multinational packaged food conglomerates and specialty health-focused brands split the market across mass retail and curated metabolic protocol channels. Tiered competitive positioning separates scale-driven distribution leverage from clean-label formulation credibility. Three archetypes dominate: global snack conglomerates with direct-store-delivery infrastructure, dairy-forward processed food specialists, and emerging direct-to-consumer subscription operators. Dominant competitive moves include portfolio diversification into ketogenic-compliant formats and strategic partnerships with tropical fat substrate suppliers.
Within the global conglomerate tier, Nestlé S.A. and PepsiCo Inc. exemplify scale-driven distribution anchoring through European and North American retail network penetration. Mondelez International occupies a position emphasizing premium packaging formats and on-the-go consumption occasion targeting. Among these, the Swiss-based Nestlé S.A. and U.S.-based PepsiCo Inc. represent contrasting geographic origins within the same strategic archetype, while Mondelez International exemplifies portfolio diversification into specialty snack positioning.
| Leading Market Players |
|---|
| Nestlé S.A. |
| PepsiCo Inc. |
| General Mills Inc. |
| Mondelez International |
| Kellanova |
| Unilever |
| Hormel Foods Corporation |
| Kind LLC |
| B&G Foods Inc. |
| Others |
Value Network & Pricing Analysis
Australian and Mexican macadamia and pecan growing regions anchor upstream nut butter supply, concentrating margin capture with processors who locked multi-year contracts before drought-induced harvest variability intensified. This geographic input concentration translates directly into pricing power asymmetries between commodity nut formats and premium single-origin derivatives.
Pricing Analysis
Geographic price spreads between United States coastal metropolitan retail and inland mass-market channels exceed thirty percent for identical SKUs. Three-tier pricing structure across premium, standard, and economy levels separates single-origin nut butters from blended formulations and private-label alternatives. Cost compression in standard-tier nut butters is intensifying because drought-induced macadamia harvest variability has compressed processor margins. Fitness-oriented consumers in coastal markets demonstrate lowest price sensitivity, while convenience channel purchasers in secondary metropolitan areas drive volume through promotional responsiveness.
Supply Chain Analysis
Contract manufacturing concentration sits with Maharashtra and Gujarat industrial corridor processors serving both domestic Indian distribution and export-oriented brands seeking FSSAI-compliant production. Raw material sourcing draws from stabilized tropical coconut contracts in Southeast Asia, aged cheese matrices from Wisconsin and Netherlands dairy cooperatives, and cold-pressed oil inputs from South American seed processors. Single-source vulnerability concentrates in Australian macadamia orchards exposed to extended drought cycles. Distribution runs through direct-store-delivery systems for impulse formats and algorithm-curated subscription platforms for metabolic protocol adherents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of low-temperature processing infrastructure compatible with fatty acid preservation protocols constrains formulation innovation velocity. Brands that secure captive capacity or exclusive co-manufacturing agreements will extract disproportionate margin from ketogenic-compliant product lines.
For Market Incumbents: Pre-empt emerging direct-to-consumer subscription operators by acquiring algorithm-curated platform capabilities before buyer data concentration shifts negotiation leverage. Secure exclusive multi-year contracts with stabilized tropical coconut suppliers to defend margin position against supply volatility. Invest in cold-pressed oil infusion technology scale-up to maintain formulation leadership as artisanal production methods migrate to industrial lines. For New Entrants and Emerging Players: Establish a beachhead in Brazilian functional food aisles where ANVISA streamlined health claim pathways reduce regulatory barriers for lipid-focused entrants. Target São Paulo and Rio de Janeiro metropolitan markets through premium supermarket channel placement before multinational conglomerates consolidate shelf space. Deploy precision fermentation-derived microbial lipid technologies as differentiation anchor against commodity nut butter incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer subscription operators possessing concentrated buyer data and algorithm-curated replenishment platforms. Five-to-ten year viability hinges on regulatory stability across FDA, EFSA, and FSSAI fat-content labeling interpretations. Watch for EFSA novel food application backlog clearance as inflection signal for coconut-derived ingredient category expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FSSAI fat-content mandates accelerate transparent supply chain documentation investments across export-oriented manufacturing. |
| Direct-to-Consumer Platform Launch | Algorithm-curated subscription models displace health food shop discovery and concentrate metabolic protocol buyer data. |
| Tropical Sourcing Contract Stabilization | Multi-year coconut substrate agreements enable margin expansion in fastest-growing chip categories. |
| Low-Temperature Processing Scale-Up | Cold-pressed oil infusion technology migration from artisanal to industrial lines preserves fatty acid integrity at volume. |
| Precision Fermentation Partnership | Microbial lipid production convergence with traditional nut processing creates hybrid matrices with extended oxidative stability. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at multinational snack conglomerates, category buyers at United States specialty retailers, supply planners at tropical ingredient processors, and regulatory affairs leads navigating EFSA novel food pathways, then refined through secondary validation against FDA nutrition fact panel disclosure databases, FSSAI fat-content labeling mandate filings, ANVISA health claim pathway documentation, and Nielsen retail audit data. Bottom-up SKU-level demand modeling and top-down metabolic protocol adherence estimates were triangulated to anchor volume projections.
Demand-supply-balance framing structured analytical approach across the analysis window, with segmentation dimensions spanning product type, flavor profile, packaging format, distribution channel, and ketogenic diet adherence intensity. CAGRs were derived through cohort-based adoption curve analysis and price elasticity modeling. Forecast inputs incorporated direct-to-consumer subscription penetration rates and cold-pressed processing capacity expansion timelines.
Stress conditions across drought-induced macadamia harvest variability, EFSA novel food evaluation cycle extensions, and refrigerated supply chain infrastructure investment gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory interpretation stability and tropical sourcing contract renewal rates. Quarterly review of FDA healthy claim reinterpretation signals, EFSA novel food backlog clearance rates, and FSSAI enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Fiber Bars Market
Snacks
Protein Crisps Market
Snacks
Snack Subscription Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
South Africa Snack Bar Market
Snacks
Jerky Snacks Market
Snacks
Fruit and Vegetable Chips Market
Snacks
Energy Balls Market
Snacks
Corn Chips Market
Snacks
UAE Snack Bar Market
Snacks
North America Extruded Snack Food Market
Snacks
Southeast Asia Savory Snacks Market
Snacks
Legume-Based Snacks Market
Snacks
Low-Calorie Sweet Treats Market
Snacks
UAE Cereal Bar Market
Snacks
Low Calorie Snack Foods Market