
 On-The-Go Healthy Snacks Market | 2026-2036
On-The-Go Healthy Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
On-The-Go Healthy Snacks Market Intelligence
Plant-based protein isolates is consolidating share from whey concentrates in protein ball formulations, cutting per-unit ingredient costs while extending shelf stability. PepsiCo leverages its Frito-Lay distribution network to dominate convenience store placement. Nestlé sustains R&D intensity in reduced-sugar binding technologies. Mondelez International anchors its position through heritage cracker-to-nut diversification.
On-the-go healthy snacks comprise shelf-stable, portion-controlled food items engineered with elevated protein, fiber, or micronutrient density relative to conventional alternatives, manufactured through cold-press extrusion, vacuum tumbling, or enrobing processes to preserve bioactive compounds without artificial preservatives. The primary commercial purpose centers on satisfying satiety and nutritional requirements during transit or between structured meals without refrigeration dependency. Granola bars occupy the most mature margin pool as private-label saturation compresses branded premiums. Protein balls represent the fastest-growing product type as CrossFit-affiliated consumers drive trial velocity. Single-serve pack sizes command disproportionate shelf space allocation in airport and transit-hub retail formats.
The FDA governs nutrient content claims and allergen labeling under FALCPA, while the EU EFSA enforces health claim substantiation through centralized pre-market authorization. These frameworks elevate compliance costs for entrants but protect established players with in-house regulatory affairs capacity. Stakeholders must monitor evolving front-of-package warning label mandates and sugar taxation proposals that could reshape formulation priorities and channel profitability.
Market Dynamics
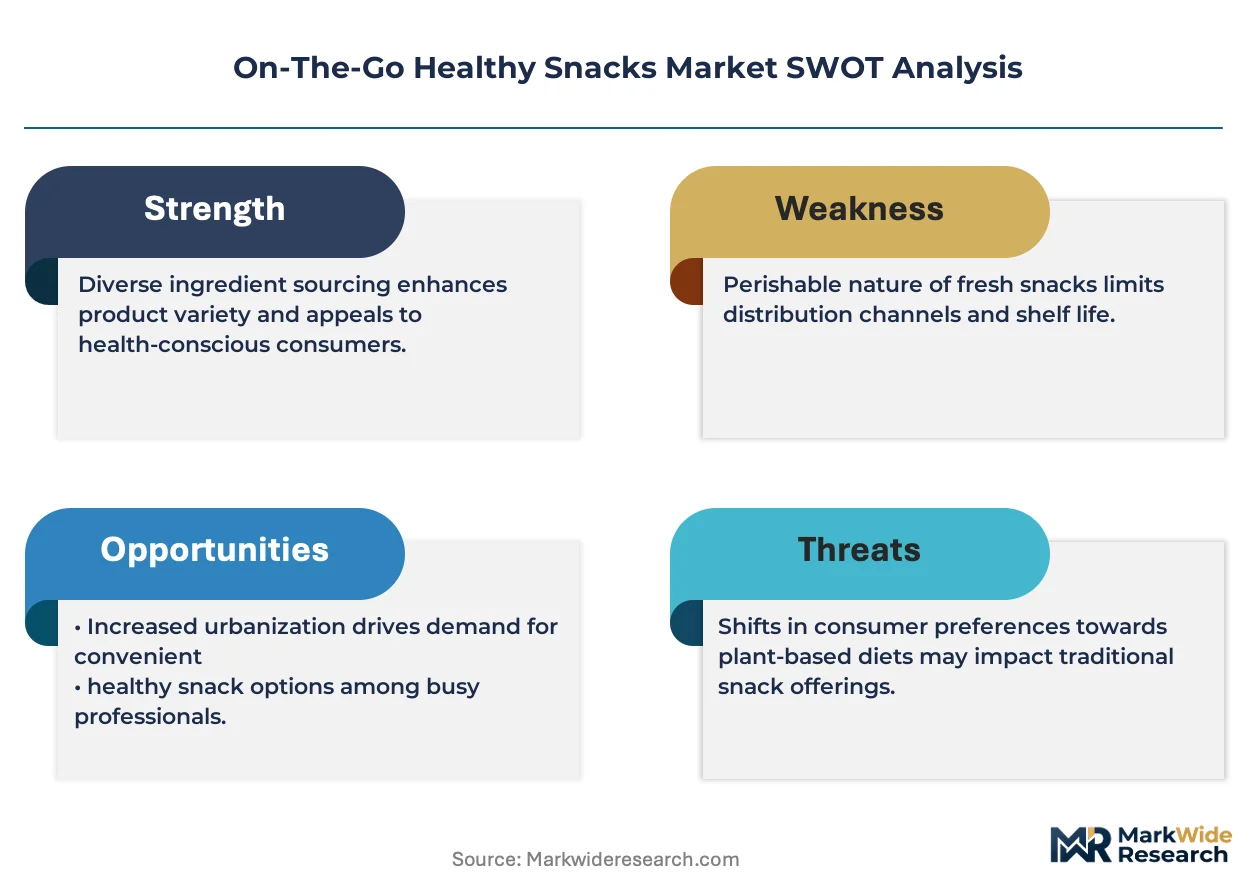
Clean-label ingredient mandates from the FDA and EU EFSA are compressing formulation flexibility while elevating compliance costs, forcing manufacturers to rebuild supply chains around certified clean-label inputs and documented traceability systems.
Growth Catalysts
- EU EFSA health claim substantiation:Pre-market authorization requirements create defensible moats for established players with in-house regulatory capacity, accelerating consolidation among compliant manufacturers.
- Cold-press extrusion technology:Equipment advances preserve heat-sensitive bioactive compounds in protein balls and fruit-based formats without artificial preservatives, unlocking extended shelf stability.
- Transit-hub retail expansion:Airport and railway station convenience formats allocate disproportionate shelf space to single-serve healthy snacks as commuter traffic rebounds.
Market Restraints
- Plant protein input volatility:Pea and rice protein isolate prices fluctuate with agricultural yield cycles and biofuel diversion pressures, compressing gross margins on protein-forward formulations.
- Allergen labeling complexity:FDA FALCPA mandates and EU 1169/2011 requirements multiply SKUs as manufacturers segregate nut-free, gluten-free, and soy-free production lines.
- Refrigeration-independent alternatives:Shelf-stable fresh fruit cups and ambient yogurt formats compete for the same convenience occasions without dry-goods margin structures.
Strategic Opportunities
- Japan's aging commuter demographic:Functional fortification with collagen, GABA, and blood-sugar-moderating fibers addresses senior mobility patterns in dense urban corridors.
- Direct-to-subscription channel:Monthly curated snack boxes bypass retail slotting fees while capturing consumer preference data for rapid SKU iteration.
- EU Green Deal packaging mandates:Compostable flexible film requirements favor early movers with validated home-compostable barrier technologies.
Industry Challenges
- Food technologist talent scarcity:Formulation chemists with dual expertise in clean-label binding systems and scaled manufacturing are concentrated among legacy baked goods and confectionery employers.
- Co-manufacturer qualification timelines:FDA-registered, allergen-segregated, and organic-certified contract manufacturing capacity requires 18-24 month onboarding cycles for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-The-Go Healthy Snacks Market |
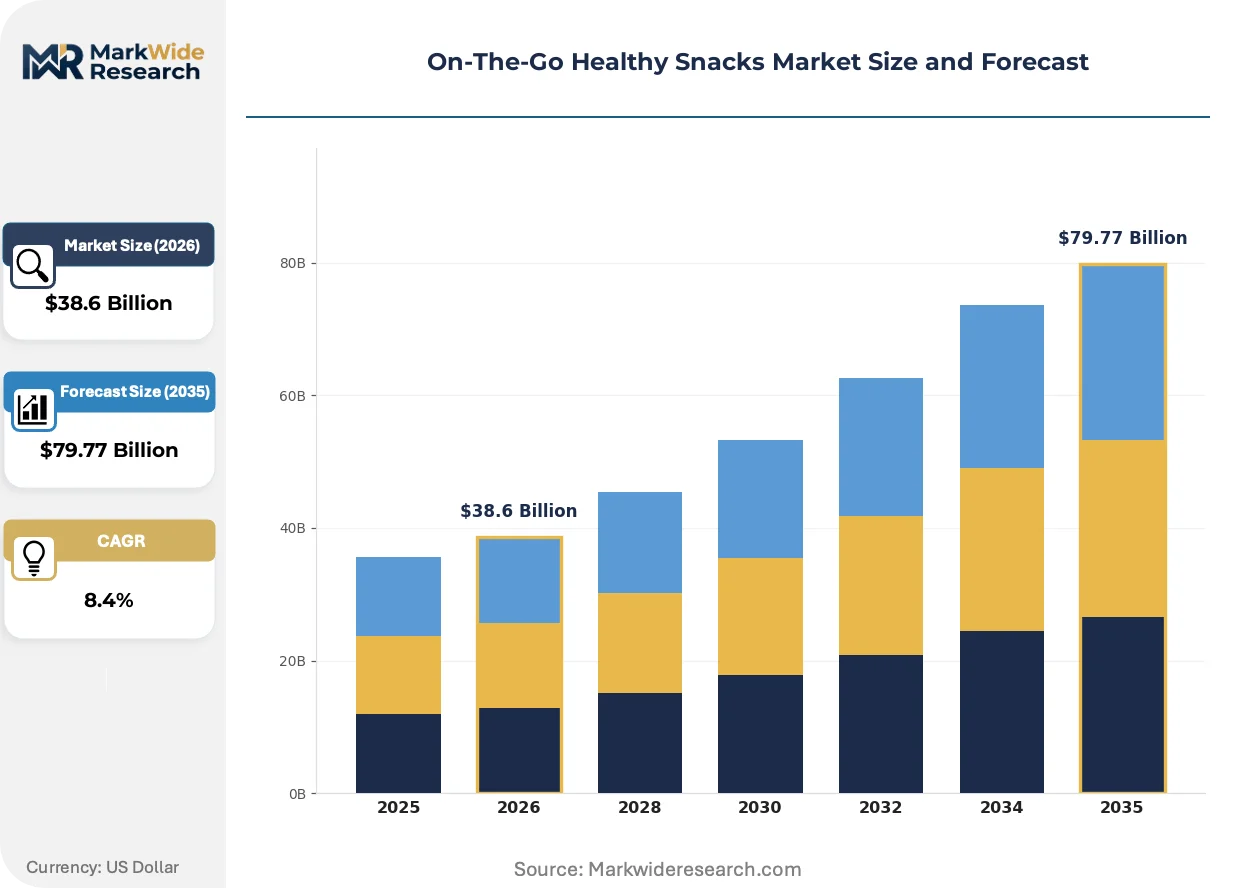
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Trail Mix, Nut Butters, Protein Balls Target Consumer: Fitness Enthusiasts, Busy Professionals, Students, Health-Conscious Families Flavor Profile: Chocolate, Fruit Medley, Peanut Butter, Savory Herb Pack Size: Single Serve, Multi-Pack, Family Size, Bulk |
| Companies Covered | PepsiCo Inc., Nestlé S.A., Mondelez International Inc., General Mills Inc., Danone S.A., Kellogg Company, Hormel Foods Corporation, The Hain Celestial Group Inc., B&G Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-The-Go Healthy Snacks Market Strategic Shifts & Innovations
Formulation science and packaging engineering are converging to eliminate the trade-off between shelf stability and clean-label positioning, with vacuum tumbling and modified atmosphere technologies now standard rather than premium-tier differentiators.
Mycelium-derived binding systems are absorbing moisture-management functions previously handled by synthetic humectants and modified starches. CrossFit-affiliated consumers and endurance athletes are driving trial velocity for protein balls incorporating these fungal matrices. The technology is absorbing cost premiums from legacy hydrocolloid suppliers while delivering label-friendly "fermented" positioning.
EU EFSA front-of-package nutrient profiling schemes are reshaping permissible health claims and reformulation targets. Manufacturers must now substantiate protein quality scores and glycemic impact data through centralized pre-market review. Reduced-sugar binding technologies face heightened scrutiny as the Nutri-Score algorithm penalizes added sweeteners regardless of source.
Urban millennials are compressing purchase decision cycles to under ninety seconds in convenience retail contexts. Transit-hub vending and grab-and-go cold cases are displacing traditional grocery aisle browsing for impulse snack acquisition. Germany's railway station retail networks demonstrate the format's highest penetration density.
On-The-Go Healthy Snacks Market Segmentation
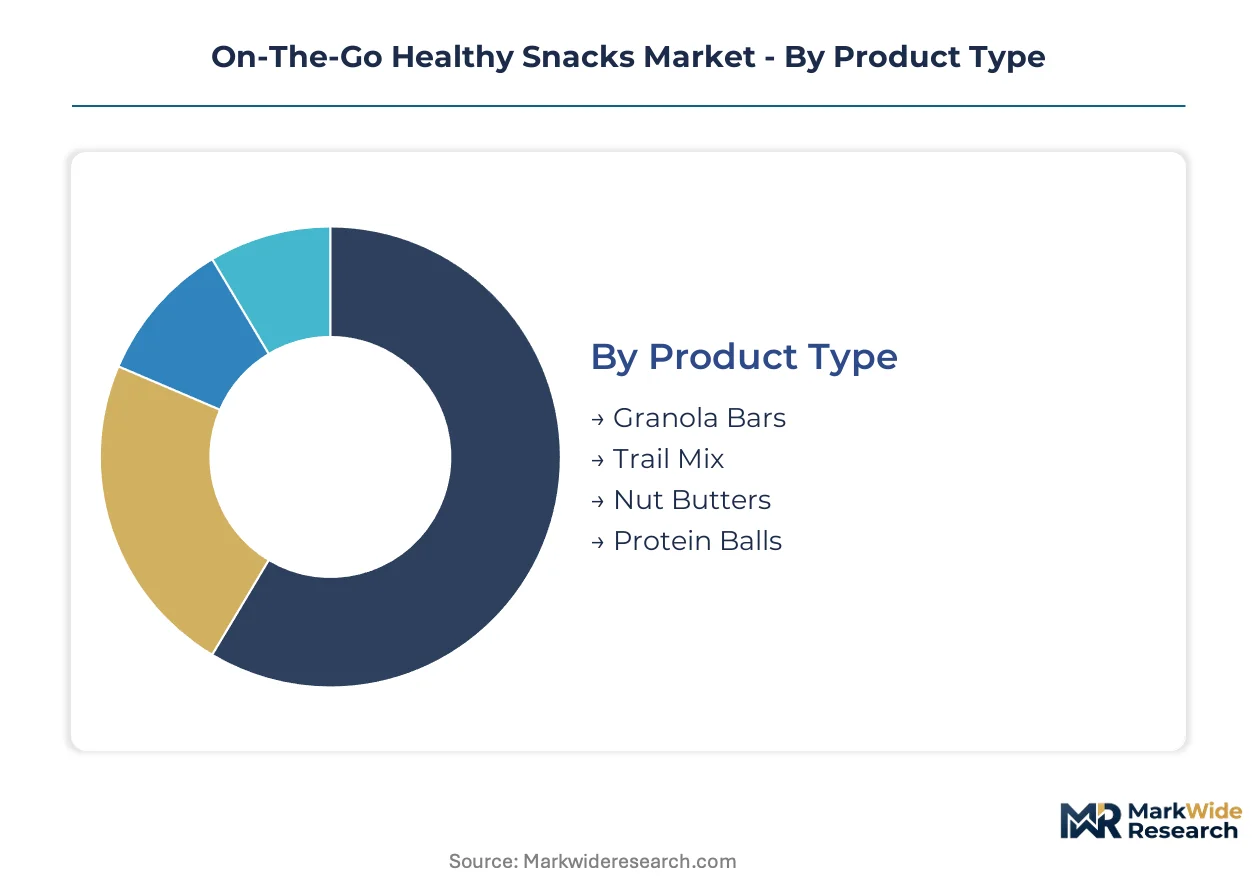
On-the-go healthy snacks segment across four intersecting dimensions that determine formulation priorities, channel strategy, and margin architecture. Product type and pack size govern manufacturing scale and shelf placement economics, while target consumer and flavor profile shape R&D resource allocation and marketing spend intensity.
Product Type:
Standalone snack formats dominate airport and transit-hub retail, while embedded meal-replacement applications concentrate in gym and corporate vending channels.
- Granola Bars:Oat and honey-based matrices bound with natural syrups and cold-pressed oils, delivering shelf-stable energy density. Demand concentrates in United States convenience retail as private-label saturation compresses branded premiums and forces ingredient differentiation.
- Protein Balls:Cold-pressed spherical formats incorporating plant protein isolates, nut butters, and binding hydrocolloids without baking. CrossFit-affiliated consumers in Germany and Japan drive trial velocity through gym-channel sampling programs and endurance event sponsorships.
- Trail Mix:Dry-blended nut, seed, and dried fruit combinations requiring no processing beyond roasting and nitrogen flushing.
- Nut Butters:Single-serve sachets and squeeze packs of almond, cashew, and peanut spreads formulated for ambient stability.
Volume placements concentrate in granola bars; the faster expansion belongs to protein balls.
Target Consumer:
Cost tier segmentation separates premium functional fortification from mass-market satiety solutions, with fitness enthusiasts commanding per-unit price premiums that subsidize student and family segments.
- Fitness Enthusiasts:Consumers prioritizing protein density, amino acid completeness, and glycemic control in pre- and post-workout windows. Protein-forward formulations in Japan incorporate collagen and GABA for recovery positioning.
- Busy Professionals:Time-constrained commuters seeking satiety without meal interruption, driving single-serve premium placement in airport and railway retail.
- Students:Price-sensitive demand concentrating in multi-pack formats with simplified ingredient lists for budget-constrained purchasing.
- Health-Conscious Families:Bulk and family-size purchasers prioritizing clean-label transparency and allergen segregation for household distribution.
Revenue per unit peaks with fitness enthusiasts; health-conscious families generate the highest absolute volume throughput.
Flavor Profile:
Application-driven segmentation distinguishes indulgence-positioned formats from functional-savory alternatives, with chocolate and peanut butter anchoring impulse purchase conversion.
- Chocolate:Cocoa powder and cacao nib inclusions requiring moisture management through modified starch or mycelium-derived binding systems. United States convenience retail allocates disproportionate shelf facings to chocolate-positioned bars.
- Peanut Butter:Roasted nut paste formulations delivering protein density with familiar taste recognition. German consumers demonstrate highest per-capita consumption of peanut butter-flavored protein balls.
- Fruit Medley:Dried berry and citrus inclusions requiring sulfur-free preservation and texture optimization.
- Savory Herb:Rosemary, thyme, and seed-based formulations targeting reduced-sugar positioning and meal-replacement occasions.
Chocolate and peanut butter combine for dominant shelf presence; savory herb claims the steepest expansion trajectory as sugar taxation pressures mount.
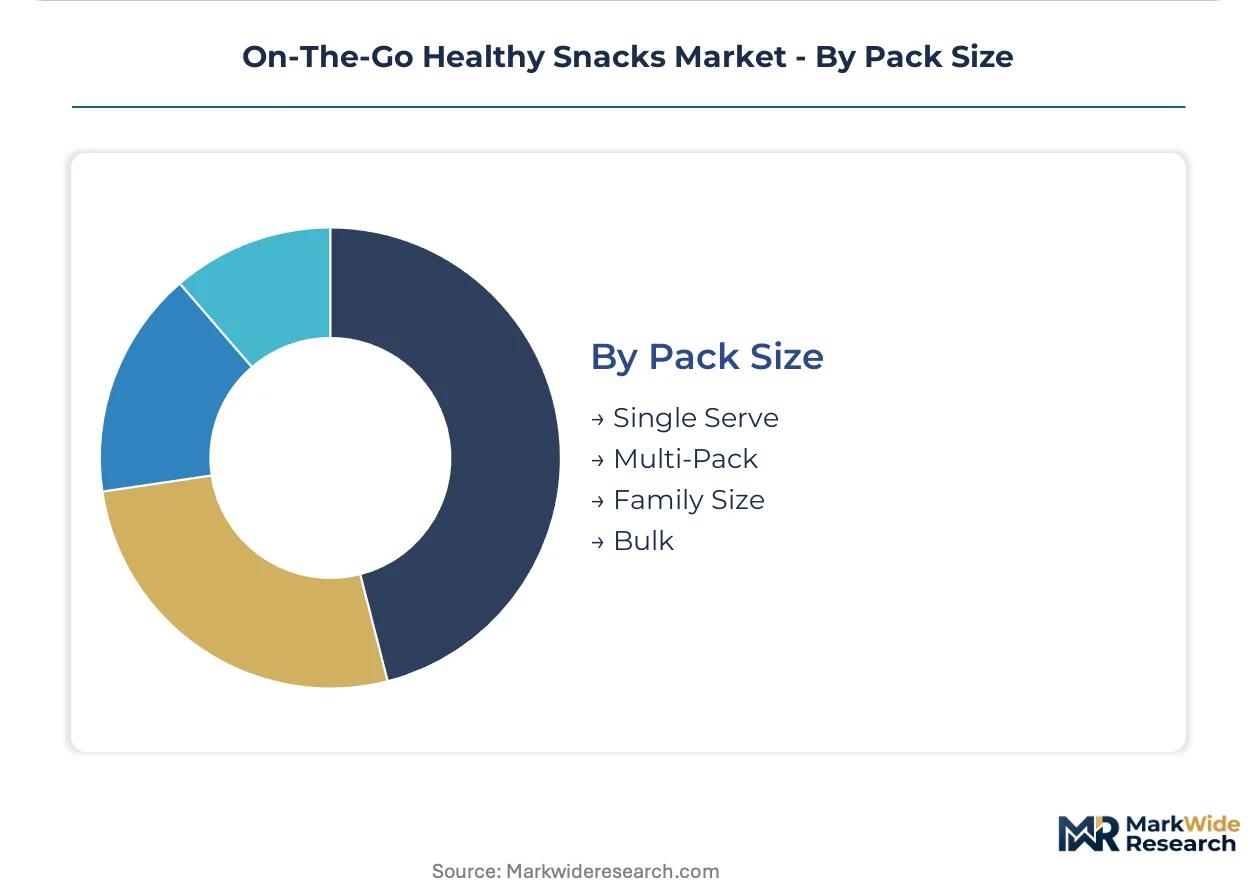
Pack Size:
Customer-type segmentation separates immediate consumption from planned pantry stocking, with single-serve formats capturing margin premiums that offset higher packaging costs.
- Single Serve:Individually wrapped portions engineered for ninety-second purchase decisions in transit-hub vending and grab-and-go cold cases. Japan's railway station networks demonstrate highest penetration density.
- Multi-Pack:Three-to-six unit bundles balancing per-unit cost reduction with portion control for weekly consumption planning.
- Family Size:Ten-to-twelve unit bags targeting household pantry stocking with resealable barrier film.
- Bulk:Unwrapped or minimally packaged formats for food service, corporate catering, and athletic team provisioning.
Unit economics favor single serve for margin; bulk formats absorb volume in institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban commuters in the United States, Germany, and Japan generate the highest per-capita consumption of single-serve healthy snacks, with transit-hub retail formats capturing disproportionate shelf space allocation.
United States
Millennial and Gen Z professionals in New York and Chicago drive protein ball trial velocity through CrossFit gym networks and airport vending placement. FDA FALCPA allergen labeling mandates elevate compliance costs for nut-free and gluten-free SKU proliferation. Los Angeles-based clean-label startups leverage direct-to-consumer subscription models to bypass traditional retail slotting fees.
Germany
Railway station retail networks in Berlin and Munich demonstrate the highest penetration density of grab-and-go healthy snack formats in Europe. EU EFSA health claim substantiation requirements create regulatory moats favoring established manufacturers with in-house compliance capacity. Bavarian contract manufacturers specialize in cold-press extrusion equipment for protein ball production.
Japan
Aging commuters in Tokyo and Osaka demand functional fortification with collagen, GABA, and blood-sugar-moderating fibers. METI guidelines on food-with-function claims shape permissible marketing language for senior-targeted products. Kanto region production clusters concentrate shelf-stable binding technology expertise.
United Kingdom
Health-conscious professionals in London's financial district compress purchase decisions to under ninety seconds in transit-hub convenience formats. EU Green Deal packaging mandates accelerate transition to home-compostable barrier films. Midlands-based co-manufacturers scale allergen-segregated production lines for private-label entrants.
Australia
Endurance athletes in Sydney and Melbourne drive premium protein ball consumption through event sponsorship channels. TGA regulations on complementary medicines influence functional ingredient positioning strategies. Queensland agricultural suppliers provide sulfur-free dried fruit inputs for trail mix formulations.
On-The-Go Healthy Snacks Market Key Industry Players
Portfolio diversification dominates the current landscape as legacy packaged food conglomerates acquire clean-label startups to offset private-label compression in mature granola bar segments. The market structure concentrates around three tiers: multinational CPG giants with Frito-Lay scale distribution networks, mid-cap specialists with certified organic and allergen-free production lines, and venture-backed direct-to-consumer brands leveraging rapid SKU iteration. Strategic archetypes include scale-driven shelf-space capturers, regulatory-compliance specialists, and subscription-channel innovators. M&A activity and cold-press extrusion capacity expansion constitute the dominant competitive moves.
Among North American CPG incumbents, PepsiCo Inc., Nestlé S.A., and Mondelez International Inc. exemplify the scale-driven archetype through heritage snack portfolio breadth and transit-hub retail penetration. These corporations occupy positions defined by distribution infrastructure rather than formulation innovation, representing the consolidation endpoint for brands seeking Frito-Lay or Mondelez shelf placement. Their market presence anchors pricing benchmarks against which mid-tier and emerging players position premium clean-label alternatives.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Nestlé S.A. |
| Mondelez International Inc. |
| General Mills Inc. |
| Danone S.A. |
| Kellogg Company |
| Hormel Foods Corporation |
| The Hain Celestial Group Inc. |
| B&G Foods Inc. |
| Others |
Cost & Logistics Intelligence
Pea protein isolate costs cascade through protein ball formulations, compressing gross margins at the premium tier while forcing mid-market brands toward rice protein alternatives and simplified binding systems. Cold-press extrusion equipment depreciation further stratifies pricing power between legacy manufacturers with captive capacity and new entrants dependent on co-manufacturer markups.
Pricing Analysis
Volume placements in granola bars absorb price erosion from private-label saturation, while protein balls capture margin premiums through CrossFit-channel positioning and functional ingredient density. Price differentiation hinges on clean-label certification tier and single-serve convenience packaging. Cost compression in the mass tier is intensifying because agricultural yield volatility feeds directly into plant protein input costs. Students exhibit highest price sensitivity, forcing multi-pack bundling; fitness enthusiasts tolerate per-unit premiums for amino acid completeness claims.
Supply Chain Analysis
Reverse-logistics flows for expired or damaged single-serve units remain underdeveloped, with most retailers absorbing shrinkage rather than returning product to manufacturers for reformulation or donation channels. Raw material sourcing concentrates in the United States for oat and honey inputs, Canada for pea protein cultivation, and Southeast Asia for sulfur-free dried fruit. Production draws from cold-press extrusion equipment clusters in Germany and Japan. Single-source vulnerability sits with mycelium-derived binding suppliers still scaling fermentation capacity. Distribution runs through Frito-Lay-scale direct-store-delivery networks for convenience penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: FDA FALCPA and EU EFSA health claim substantiation requirements erect regulatory moats that favor established players with in-house regulatory affairs capacity and documented traceability systems.
For Market Incumbents: Hedge against private-label compression in granola bars by accelerating cold-press extrusion capacity additions in Bavaria and Kanto region clusters. Acquire venture-backed direct-to-consumer brands to capture subscription-channel preference data and rapid SKU iteration capabilities. Vertical integration into certified organic oat sourcing defends margin position against agricultural input volatility. For New Entrants and Emerging Players: Mycelium-derived binding technology offers a technology-first wedge into the protein ball segment, displacing legacy hydrocolloid suppliers with label-friendly fermented positioning. White-space targets include Japan's aging commuter demographic seeking collagen and GABA fortification, and EU Green Deal-compliant compostable packaging formats. A direct-to-subscription go-to-market angle bypasses retail slotting fees while building iterative formulation feedback loops. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with certified allergen-segregated production lines and EU organic certification in Germany and the United Kingdom. Long-term viability over a multi-year window rests on regulatory compliance capacity as a scarce, non-replicable asset. Monitor EU front-of-package Nutri-Score algorithm updates as an inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Extrusion Capacity Expansion | Bavarian equipment clusters anchor protein ball production scale for CrossFit-channel supply. |
| Direct-to-Consumer Subscription Launch | Monthly curated boxes capture preference data while bypassing Frito-Lay slotting fee structures. |
| EU Green Deal Packaging Transition | Home-compostable barrier films align with railway station retail sustainability mandates in Germany. |
| Functional Ingredient Fortification | Collagen and GABA positioning addresses Tokyo commuter demographic mobility patterns. |
| Allergen-Segregated Production Line Addition | FDA-registered nut-free capacity unlocks school and family-channel distribution expansion. |
Research Approach
Independent corroboration across regulatory filing databases, retail audit data, and equipment manufacturer order books underwrites the qualitative findings. Primary interviews with brand managers, category buyers at convenience retailers, cold-press extrusion equipment specialists, and regulatory affairs directors combined with secondary validation from FDA warning letters, EU EFSA health claim registers, and customs trade records. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates.
Comparable-period anchoring to pre-pandemic transit-hub retail traffic baselines established the forecast window's demand recovery trajectory. The analytical framework segments by product type, target consumer archetype, flavor profile, and pack size across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macroeconomic consumption elasticity assumptions. Forecast inputs include plant protein spot price volatility indices and railway station retail format expansion pipelines.
Several conditions sit outside the modeled scope, including unannounced sugar taxation legislation, abrupt FDA allergen labeling reinterpretations, and mycelium fermentation capacity buildout delays. Forecasts reflect documented assumptions about commuter behavior normalization and clean-label input cost trajectories. Practitioners should monitor EU Nutri-Score algorithm revisions and Japan METI food-with-function claim guideline updates for early signals of reformulation cycle triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
North America Cereal Bar Market
Snacks
North America Baked Savory Snacks Market
Snacks
Granola Bars Market
Snacks
Global Fruit Snacks Market
Snacks
Jerky Snacks Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
Low Fat Crackers Market
Snacks
Sweet Potato Fries Market
Snacks
Qatar Potato Chips Market
Snacks
Extruded Snacks Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Latin America Extruded Snack Food Market
Snacks
Mushroom Based Jerky Market
Snacks
Middle East Snack Bar Market
Snacks
Low Calorie Snack Foods Market
Snacks
Fried Potato Chips Market