
 Middle East and Africa Protein Bar Market | 2026-2036
Middle East and Africa Protein Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Protein Bar Market Foresight
Specialty shop distribution is reconfiguring across Gulf cities as boutique nutrition retailers expand shelf space for functional snacks. Quest Nutrition leverages its whey-dominant formulation range to anchor premium positioning in Dubai and Riyadh. Nestlé S.A. sustains broad retail penetration through supermarket partnerships spanning Morocco to Kenya. General Mills Inc. competes on brand recognition, adapting its portfolio to local flavor preferences in Egypt and Nigeria.
Protein bars in the Middle East and Africa constitute shelf-stable, nutrient-dense food products manufactured through cold-extrusion or baking processes, typically delivering 10-25 grams of protein per serving with controlled carbohydrate profiles for satiety and muscle recovery applications. Whey protein bars occupy the dominant value share due to established consumer familiarity and superior amino acid completeness, while plant-based formulations register the fastest trajectory as flexitarian diets gain traction among urban millennials. The bars format commands the majority of volume, though bites and crisps expand snacking occasion relevance for busy professionals seeking portion-controlled options.
SFDA in Saudi Arabia and South Africa's Department of Health enforce protein content accuracy and allergen disclosure standards that elevate compliance costs for imported brands. Egypt's food safety authority applies parallel scrutiny on dairy-derived ingredients, shaping supplier qualification protocols for whey and casein sourcing. Stakeholders must monitor evolving halal certification requirements across Gulf Cooperation Council jurisdictions, as these standards increasingly influence procurement decisions rather than serving as passive market-entry formalities.
Market Dynamics
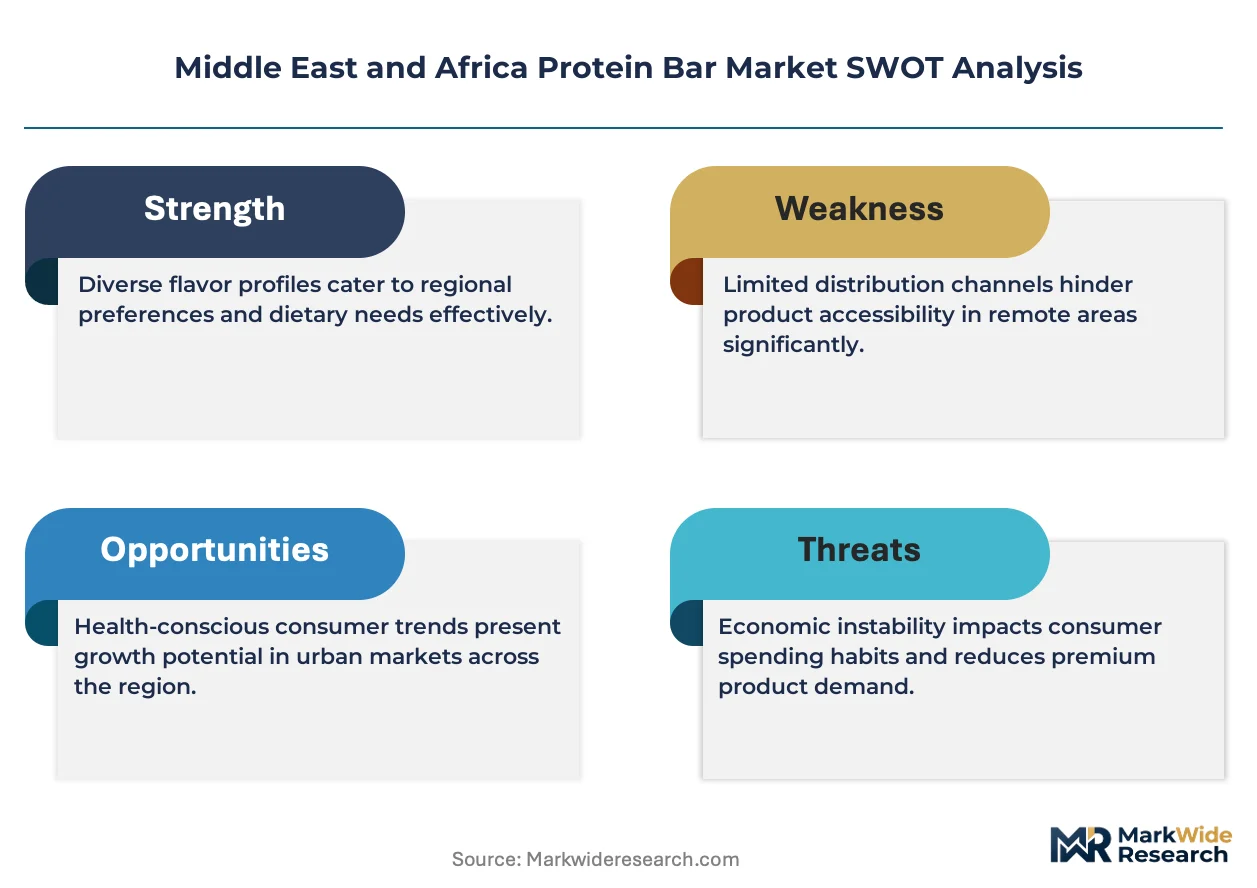
Halal certification protocols across Gulf Cooperation Council jurisdictions are tightening ingredient traceability requirements, forcing reformulations and supplier audits throughout the whey and plant-protein supply chains.
Growth Catalysts
- Fitness culture penetration:Urban gym memberships in Saudi Arabia and the UAE are expanding the core consumer base for post-workout nutrition products.
- SFDA labeling mandates:Saudi Arabia's protein content verification standards are building consumer trust through transparent nutritional claims.
- Plant protein innovation:Pea and fava bean isolates are overcoming taste barriers that previously limited adoption in North African markets.
Market Restraints
- Dairy input volatility:Whey protein concentrate prices fluctuate with EU and New Zealand milk powder auctions, compressing margin predictability for importers.
- Supply concentration risk:Over 70% of specialty hydrolyzed whey originates from a limited set of European processors, creating vulnerability to export disruptions.
- Cold chain gaps:Inland distribution networks in Nigeria and Kenya lack temperature-controlled logistics for preservative-free premium bars.
Strategic Opportunities
- Ethiopia's underpenetrated channels:Addis Ababa's emerging supermarket sector offers first-mover positioning before competitor saturation.
- Moroccan date-protein fusion:Local ingredient integration satisfies domestic content preferences while differentiating against standardized imports.
- E-commerce pharmacy integration:South Africa's Dis-Chem and Clicks platforms are expanding dedicated health-food verticals with subscription mechanics.
Industry Challenges
- Halal audit complexity:Multi-country sourcing of whey and collagen requires chain-of-custody documentation across disparate certification bodies.
- Refrigerated warehousing scarcity:Lagos and Nairobi lack sufficient cold storage capacity for temperature-sensitive plant-protein isolates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Protein Bar Market |
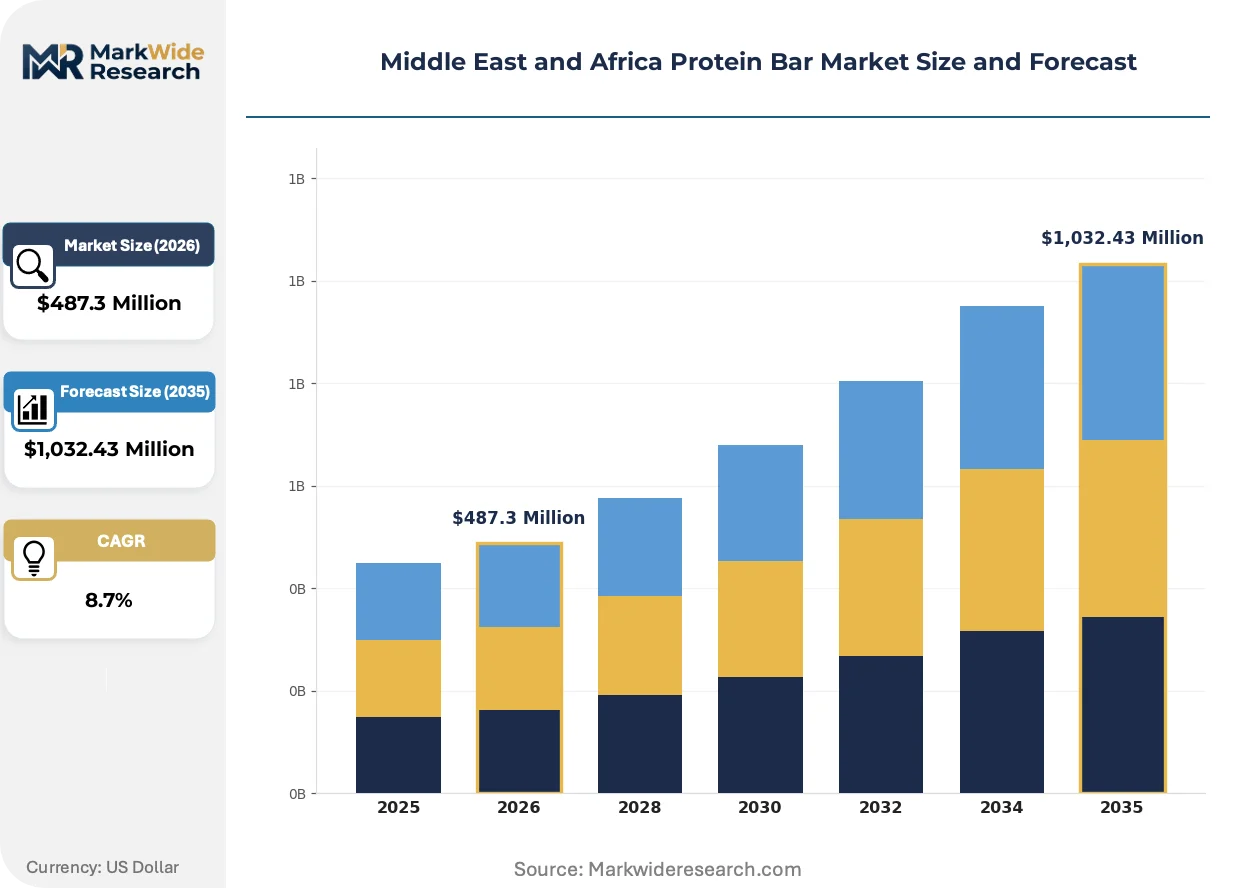
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey, Casein, Soy, Plant-Based Form: Bars, Crisps, Chews, Bites Distribution Channel: Supermarkets, Health Stores, Online Retailers, Specialty Shops End User: Athletes, Fitness Enthusiasts, Busy Professionals, Students |
| Companies Covered | The Kellogg Company, Quest Nutrition, Nestlé S.A., Clif Bar & Company, Post Holdings, General Mills Inc., Glanbia plc, Abbott Laboratories, Mondelez International Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Protein Bar Market Shifts & Advancements
Cold-extrusion processing advances and enzymatic flavor-masking technologies are compressing the quality gap between plant and dairy proteins. Manufacturers are responding with hybrid formulations that blend functional benefits across source types.
Enzymatic hydrolysis of pea and rice proteins is rendering obsolete the gritty texture profiles that previously limited consumer acceptance in premium segments. Egyptian and South African millennial buyers are switching to these reformulated bars at accelerating rates. The technology is compressing the price premium between plant-based and whey-dominant products.
South Africa's Department of Health is enforcing updated allergen disclosure standards that mandate batch-level traceability for imported dairy ingredients. Manufacturers must redesign packaging artwork and supply chain documentation to achieve compliance. Whey-based products face the steepest adaptation costs, accelerating interest in allergen-free plant alternatives.
Subscription-based replenishment models are displacing impulse purchases in metropolitan retail corridors. Cape Town and Johannesburg health-store networks are unbundling single-bar sales in favor of monthly box deliveries with personalized macro profiles. The shift is most visible among competitive amateur athletes seeking consistent nutrition timing.
Middle East and Africa Protein Bar Market Segmentation
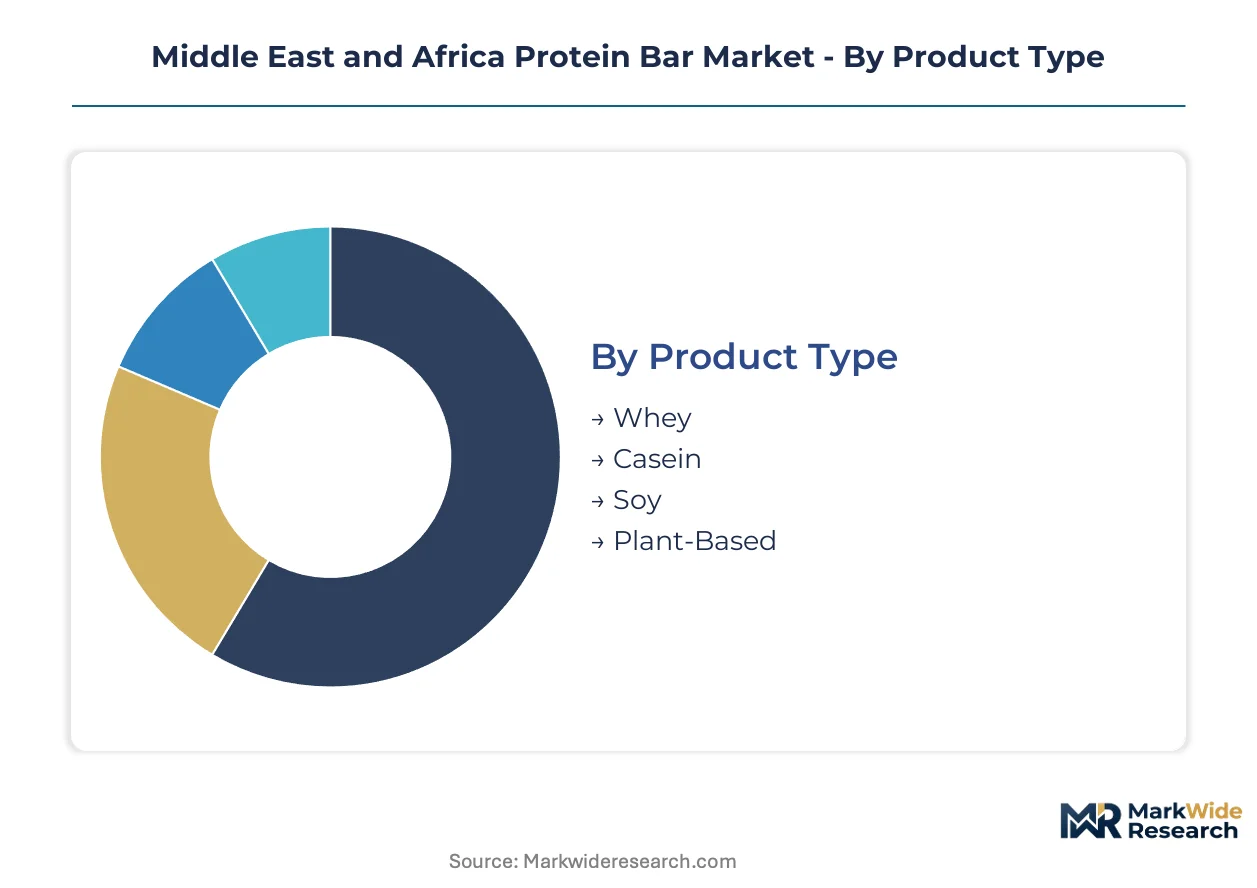
Protein bar segmentation in the Middle East and Africa reveals distinct consumption patterns across protein sources, physical formats, retail channels, and lifestyle cohorts. Manufacturers calibrate formulation and packaging strategies against these intersecting demand profiles to capture premium positioning in urban centers.
Product Type:
Mature dairy-derived categories anchor current revenue while plant-based alternatives accelerate on flexitarian adoption.
- Whey:Cold-extruded bars delivering 15-25 grams of complete amino acid profiles dominate gym-adjacent retail in Dubai and Johannesburg. Saudi Arabia's SFDA protein verification standards reinforce whey dominance through transparent labeling that builds consumer trust in dairy-derived claims.
- Plant-Based:Pea and fava bean isolates processed through enzymatic hydrolysis now achieve texture parity with dairy proteins. Urban millennials in Cairo and Casablanca are switching to these reformulated bars as allergen-free alternatives gain shelf space in health-store networks.
- Casein:Slow-release micellar formulations target overnight recovery applications among competitive amateur athletes.
- Soy:Cost-competitive isolates retain penetration in Nigeria's price-sensitive mass retail channels.
Whey retains volume leadership; plant-based holds the steepest expansion curve.
Form:
Physical format selection maps directly to consumption occasion fragmentation across professional and athletic schedules.
- Bars:Standard 50-70 gram formats remain the default for meal-replacement scenarios among busy professionals commuting through Riyadh and Lagos. The segment benefits from established manufacturing infrastructure and familiar portion expectations.
- Bites:Portion-controlled 15-20 gram clusters are displacing impulse purchases in Cape Town health-store subscription boxes. Competitive amateur athletes favor these for precise macro timing without caloric excess.
- Crisps:Baked wafer formats expand snacking relevance for mid-afternoon energy management in office corridors.
- Chews:Gummy-textured alternatives attract younger consumers in Egyptian and Moroccan supermarket aisles.
Bars dominate absolute volume; bites are climbing the fastest on subscription model adoption.
Distribution Channel:
Channel strategy determines margin capture and brand positioning altitude across the region's fragmented retail landscape.
- Health Stores:Dedicated nutrition retailers in Johannesburg and Cape Town drive premium product uptake through personalized macro consultations and subscription mechanics. These channels command highest margins but require specialized staff training.
- Specialty Shops:Boutique nutrition retailers across Gulf cities are expanding shelf space for functional snacks with halal-certified provenance documentation. The format rewards brands with transparent supply chain storytelling.
- Supermarkets:Mass retail partnerships spanning Morocco to Kenya sustain broad penetration for established brands with standardized flavor profiles.
- Online Retailers:E-commerce pharmacy integration through South Africa's Dis-Chem and Clicks platforms enables subscription-based replenishment with personalized curation.
Health stores capture premium pricing power; online retailers are gaining share fastest on convenience positioning.
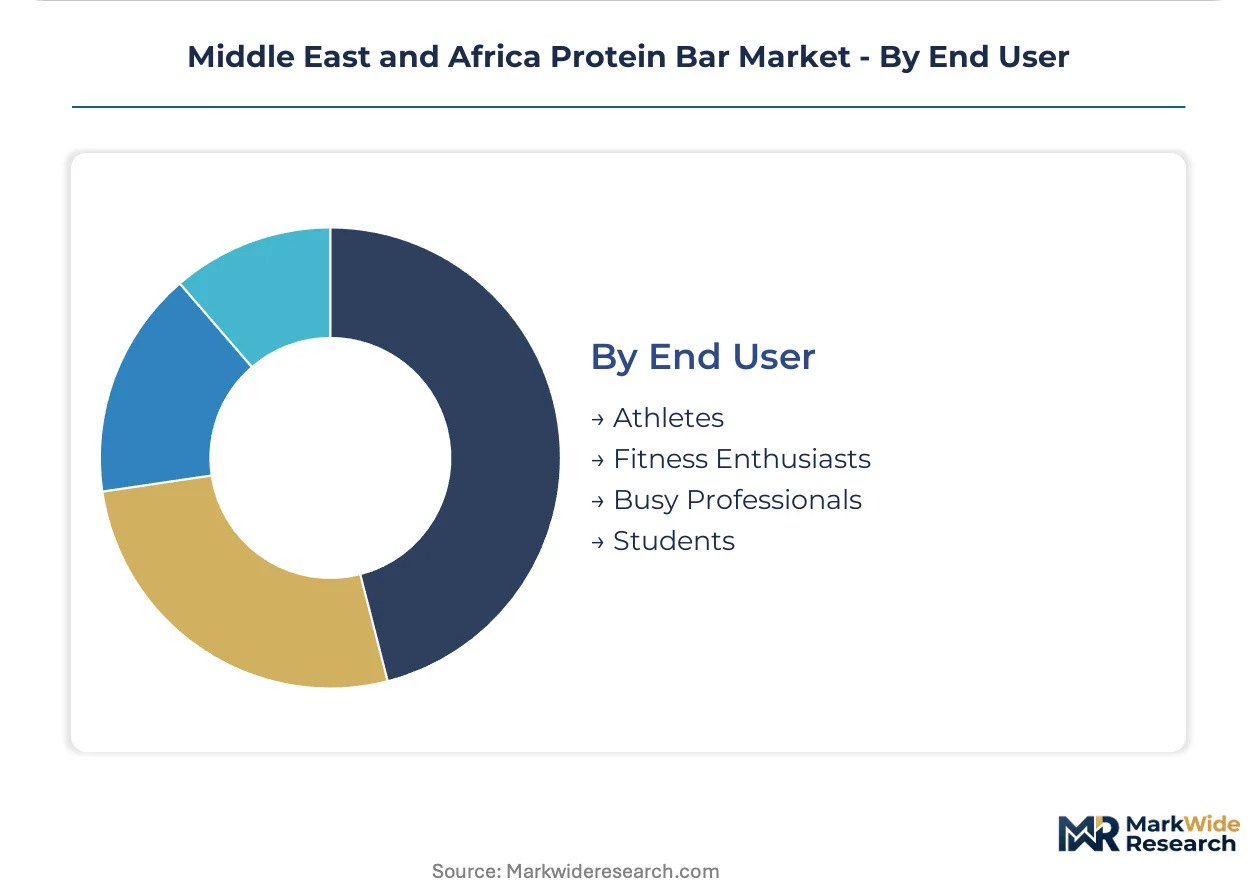
End User:
User archetypes dictate protein load requirements, flavor preferences, and price sensitivity thresholds.
- Fitness Enthusiasts:Urban gym members in Saudi Arabia and the UAE constitute the fastest-expanding cohort as post-workout nutrition becomes ritualized. This segment demands 20+ gram protein loads with minimal carbohydrate interference.
- Athletes:Competitive amateurs in South Africa's metropolitan corridors prioritize batch-tested formulations with transparent allergen documentation for competition compliance.
- Busy Professionals:Portion-controlled formats appeal to time-constrained workers in Nairobi and Lagos seeking desk-drawer nutrition solutions.
- Students:Price-optimized variants with localized flavors penetrate university-adjacent retail in Egypt and Nigeria.
Fitness enthusiasts represent the steepest growth trajectory; busy professionals anchor current volume on convenience purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port in Dubai anchors distribution capacity for protein bar imports entering Gulf markets, while South Africa's Durban-Gauteng logistics corridor sustains regional supply chain throughput for southern African retail networks.
Saudi Arabia
Fitness culture penetration in Riyadh and Jeddah is expanding the post-workout nutrition consumer base as urban gym memberships multiply. The Saudi Food and Drug Authority enforces protein content verification standards that elevate compliance costs for imported formulations. The Riyadh metropolitan corridor concentrates premium health-store networks where subscription-based replenishment models are displacing single-unit purchases.
United Arab Emirates
Boutique nutrition retailers across Dubai are expanding shelf space for functional snacks with transparent halal certification documentation. The Dubai Municipality food safety department applies stringent allergen disclosure requirements on dairy-derived imports. The Dubai Marina and Jumeirah Lakes Towers clusters host the region's densest concentration of fitness enthusiasts driving demand for 20+ gram protein formulations.
South Africa
Metropolitan retail corridors in Johannesburg and Cape Town anchor premium product uptake through health-store networks with personalized macro consultations. The Department of Health enforces updated allergen disclosure standards mandating batch-level traceability for imported dairy ingredients. The Cape Town health-store sector leads subscription model adoption among competitive amateur athletes seeking consistent nutrition timing.
Egypt
University-adjacent retail in Cairo and Alexandria sustains volume for price-optimized variants with localized flavor profiles. The country's food safety authority applies parallel scrutiny on dairy-derived ingredients, shaping supplier qualification protocols for whey and casein sourcing. The Cairo metropolitan area concentrates mass retail partnerships where established brands compete on brand recognition and adapted portfolios.
Nigeria
Price-sensitive mass retail channels in Lagos retain penetration for cost-competitive soy protein isolates amid dairy input volatility. The national food safety regulator enforces labeling standards that compress margin predictability for importers navigating cold chain gaps. The Lagos-Ibadan corridor represents the primary distribution bottleneck where inland networks lack temperature-controlled logistics for preservative-free premium bars.
Middle East and Africa Protein Bar Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base fragments across multinational conglomerates with broad retail penetration and niche nutrition specialists with formulation expertise. Three archetypes dominate: dairy-dominant whey processors, plant-protein innovators, and diversified snack conglomerates with health-food verticals. Competitive moves center on halal certification compliance investments and cold-extrusion technology licensing for texture parity across protein sources.
Within the diversified-snack tier, Nestlé S.A. and General Mills Inc. exemplify scale-driven market coverage spanning Morocco to Kenya through supermarket partnerships. Quest Nutrition occupies a position among whey-dominant specialists leveraging premium positioning in Dubai and Riyadh. These three anchors represent distinct strategic postures: broad retail saturation, brand-recognition adaptation, and formulation-led premium positioning.
| Leading Market Players |
|---|
| The Kellogg Company |
| Quest Nutrition |
| Nestlé S.A. |
| Clif Bar & Company |
| Post Holdings |
| General Mills Inc. |
| Glanbia plc |
| Abbott Laboratories |
| Mondelez International Inc. |
| Others |
Supply & Pricing Matrix
Dairy input volatility from EU and New Zealand milk powder auctions compresses margin predictability for importers while simultaneously determining tier spreads between whey-dominant premium formulations and soy-based economy alternatives. This commodity exposure forces manufacturers to balance supply chain resilience against pricing architecture that segments fitness enthusiasts from price-sensitive mass retail buyers.
Pricing Analysis
Volume-discount tiering structures separate subscription-based health-store replenishment from single-unit supermarket transactions across the Middle East and Africa. Three-tier pricing stratifies across premium enzymatically-hydrolyzed plant proteins, standard cold-extruded whey formulations, and economy soy isolates. Pricing pressure stems from SFDA compliance investments elevating import costs for dairy-derived bars. Fitness enthusiasts in Saudi Arabia and the UAE show lowest price sensitivity; students in Egypt and Nigeria anchor the economy tier.
Supply Chain Analysis
Extended payment terms from European whey processors strain working capital for importers navigating Gulf certification requirements. Supply concentrates in the Netherlands, Germany, and New Zealand for specialty hydrolyzed whey; pea and fava bean isolates draw from French and Canadian extraction facilities. Raw material dependencies center on dairy protein concentrates, enzymatically-processed legume isolates, and halal-certified collagen. Single-source vulnerability pervades hydrolyzed whey procurement. Distribution runs through Jebel Ali Port for Gulf markets and Durban-Gauteng corridors for southern Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halal certification audit capabilities represent the critical skill gap separating viable competitors from market casualties, as multi-country whey sourcing demands chain-of-custody documentation across disparate certification bodies.
For Market Incumbents: Harden halal compliance infrastructure through supplier-financed audit programs and captive certification relationships with Gulf Cooperation Council bodies. Defend premium positioning by acquiring cold-extrusion technology licenses that compress the quality gap between plant and dairy proteins. Margin pressure from enzymatic hydrolysis cost reductions demands accelerated R&D in hybrid formulation patents. For New Entrants and Emerging Players: Ethiopia's underpenetrated supermarket channels in Addis Ababa offer first-mover positioning before competitor saturation. Target Moroccan date-protein fusion formulations that satisfy domestic content preferences while differentiating against standardized imports. E-commerce pharmacy integration through South Africa's Dis-Chem and Clicks platforms provides the most penetrable go-to-market angle via subscription mechanics. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors vertically integrated specialists with captive halal audit capabilities. Long-term viability across the analysis window rests on brands that internalize supply chain documentation rather than outsourcing compliance. The signal to watch is SFDA enforcement consistency on protein content verification standards.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | SFDA and MOHAP documentation requirements now influence procurement decisions beyond passive market-entry formalities. |
| Enzymatic Hydrolysis Licensing | Pea and rice protein texture parity eliminates the quality premium historically commanded by whey formulations. |
| Cold Chain Partnership | Temperature-controlled logistics gaps in Lagos and Nairobi block preservative-free premium bar distribution. |
| Subscription Model Launch | Cape Town and Johannesburg health-store networks displace impulse purchases with monthly box deliveries. |
| Local Ingredient Integration | Moroccan date-protein fusion satisfies domestic content preferences while differentiating against standardized imports. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers, category buyers at health-store networks, halal certification auditors, and supply chain directors at importers and refined through secondary validation. Primary research drew from structured interviews with stakeholders across Dubai, Riyadh, Johannesburg, and Cairo. Secondary sources encompassed SFDA regulatory filings, South Africa's Department of Health allergen disclosure standards, customs and trade data on whey protein concentrate imports, and Nielsen retail audit data from metropolitan corridors. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to reconcile volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed protein source, physical format, distribution channel, and end-user lifestyle cohort alongside regional regulatory cluster variations. CAGRs were derived from growth rate convergence analysis applied to historical consumption patterns and projected fitness culture penetration curves. Forecast inputs incorporated gym membership expansion rates in Saudi Arabia and the UAE, plus enzymatic hydrolysis technology adoption timelines in North African manufacturing facilities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plant-protein specialists with halal-certified supply chains would shift outcomes beyond modeled ranges. Macroeconomic deviation, regulatory enforcement intensity changes, or breakthroughs in enzymatic flavor-masking would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Asia-Pacific Functional Water Market