
 Nachos Market | 2026-2036
Nachos Market Size, Share, and Industry Trends Forecast 2026-2036
Nachos Market Outlook
Mexican tortilla mill capacity is realigning toward industrial-scale masa production for snack manufacturers. Frito-Lay (PepsiCo) dominates North American corn chip supply chains through captive sourcing of proprietary hybrid corn varieties. General Mills leverages its cereal grain procurement infrastructure to secure consistent yellow corn flows for its snack division. Grupo Bimbo anchors Latin American distribution through its pan-regional bakery and snack logistics network.
Nachos consist of fried or baked tortilla chips, typically fabricated from nixtamalized corn masa, topped or paired with processed cheese sauces, salsas, and ancillary condiments for immediate consumption in commercial and retail settings. The nixtamalization process—alkaline cooking of corn in lime solution—defines the characteristic flavor profile and structural integrity of authentic tortilla chips. Classic Nachos and Cheese Nachos command the largest volume positions, while Loaded Nachos capture expanding premium positioning in cinema and stadium concessions. The Distribution Channel segment shows structural divergence: Supermarkets and Convenience Stores sustain baseline retail velocity, while Food Trucks and Online Retailers represent the fastest-expanding access points for specialty and artisanal formats.
The FDA governs cheese sauce labeling and pasteurization standards for prepared nacho toppings, while USDA grading rules apply to corn procurement specifications for federally inspected facilities. Mexico's national health regulator, COFEPRIS, enforces additive limits on flavored tortilla coatings exported to the United States, creating compliance friction for cross-border suppliers. Stakeholders must monitor evolving front-of-package warning label regimes in Latin American markets and assess whether reformulation investments or portfolio pruning better protects margin structures.
Market Dynamics
Nachos supply chains pivot on nixtamalized corn masa availability and FDA cheese sauce pasteurization mandates, with cinema concession operators now demanding extended hold-time formulations that reshape ingredient sourcing priorities.
Growth Catalysts
- Stadium concession expansion:Sports venue operators are expanding nacho menu placements across premium seating tiers, driving volume commitments from industrial masa suppliers.
- COFEPRIS additive harmonization:Mexico's national health regulator is streamlining cross-border coating approvals, reducing compliance friction for tortilla chip exporters targeting US distribution.
- Nixtamalization automation:Industrial-scale alkaline cooking systems are reducing per-batch labor costs and improving masa consistency for high-volume chip fabrication.
Market Restraints
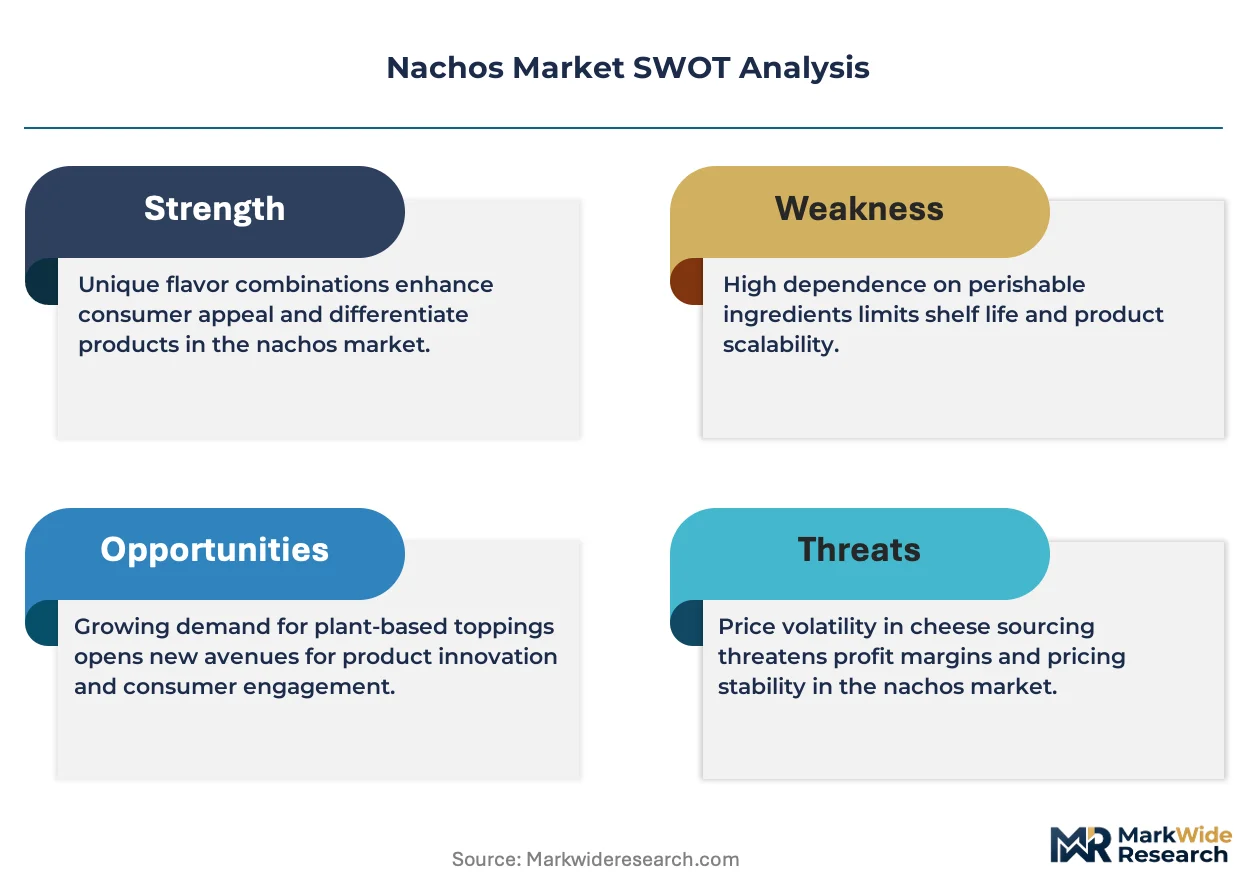
- Yellow corn price volatility:Input cost swings tied to drought cycles in US Midwest growing regions compress margin predictability for snack manufacturers.
- Proprietary hybrid concentration:Captive corn seed development by dominant processors creates supply access barriers for mid-tier tortilla mill operators.
- Front-of-package warning regimes:Latin American regulators are mandating sodium and saturated fat disclosure labels that force reformulation investments or SKU rationalization.
Strategic Opportunities
- Food truck channel penetration:Mobile foodservice operators represent underdeveloped distribution for artisanal nacho formats with premium topping configurations.
- Online retail velocity:Direct-to-consumer snack platforms are capturing specialty and small-batch tortilla chip demand outside traditional supermarket placement.
- USDA BioPreferred procurement:Federal facility concession contracts increasingly specify biobased packaging and ingredient sourcing, creating compliance-driven preference premiums.
Industry Challenges
- Nixtamalization specialist scarcity:Industrial food science programs produce limited graduates with hands-on alkaline cooking process expertise.
- Legacy equipment retrofit costs:Existing tortilla lines require capital-intensive modifications to achieve FDA-compliant cheese sauce temperature control integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nachos Market |
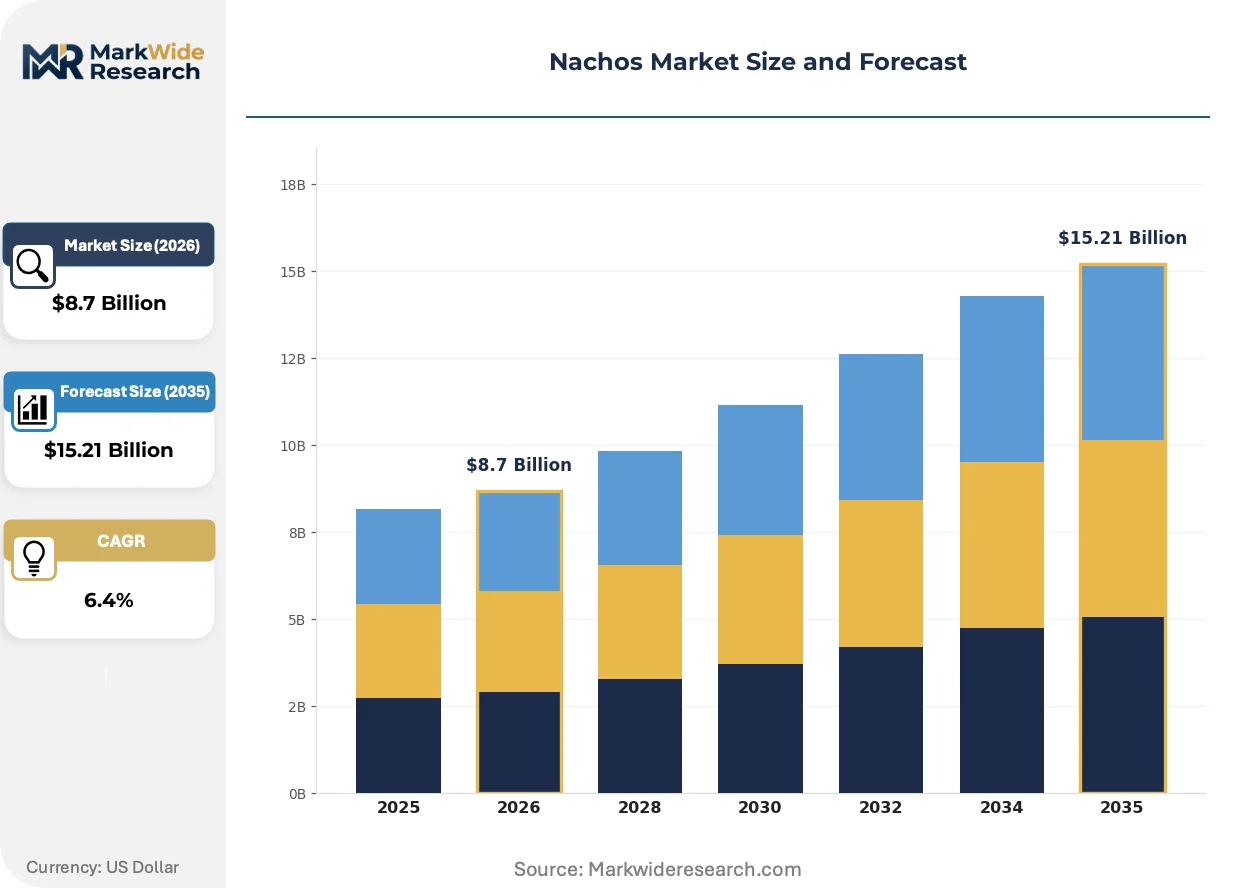
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Nachos, Cheese Nachos, Spicy Nachos, Loaded Nachos Ingredient Type: Organic Corn, Gluten-Free Tortilla, Cheddar Cheese, Salsa Serving Style: Tray, Bag, Bowl, Platter Distribution Channel: Supermarkets, Food Trucks, Online Retailers, Convenience Stores |
| Companies Covered | General Mills, Mondelēz International, Frito-Lay (PepsiCo), Intersnack Group, Kellogg Company, Pringles, Grupo Bimbo, Nacho King, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nachos Market Strategic Shifts
Automation in masa production and regulatory pressure on prepared food labeling are compressing operational timelines while fragmenting distribution channels across mobile and digital access points.
Continuous nixtamalization systems are modularizing production architecture for mid-scale tortilla mills. Regional chip fabricators in Mexico and the southwestern United States are adopting skid-mounted alkaline cooking units to bypass centralized masa supply dependence. This technology is modularizing capital deployment, allowing processors to scale output in 500kg increments rather than committing to greenfield facility construction.
FDA updated nutrition labeling requirements for prepared foods are forcing cheese sauce reformulation across cinema and stadium concessionaires. Manufacturers must now disclose added sugars and revise serving-size declarations on pump-dispensed toppings. Prepared topping suppliers serving federally inspected facilities face the steepest compliance timelines and are accelerating clean-label ingredient transitions.
Concession procurement is consolidating around extended-hold cheese sauce specifications that maintain viscosity beyond four hours. Cinema chains are displacing traditional topping pumps with insulated reservoir systems that reduce waste and labor intervention. This specification shift is most visible in US multiplex operations where labor cost pressures intersect with extended operating schedules.
Nachos Market Segmentation
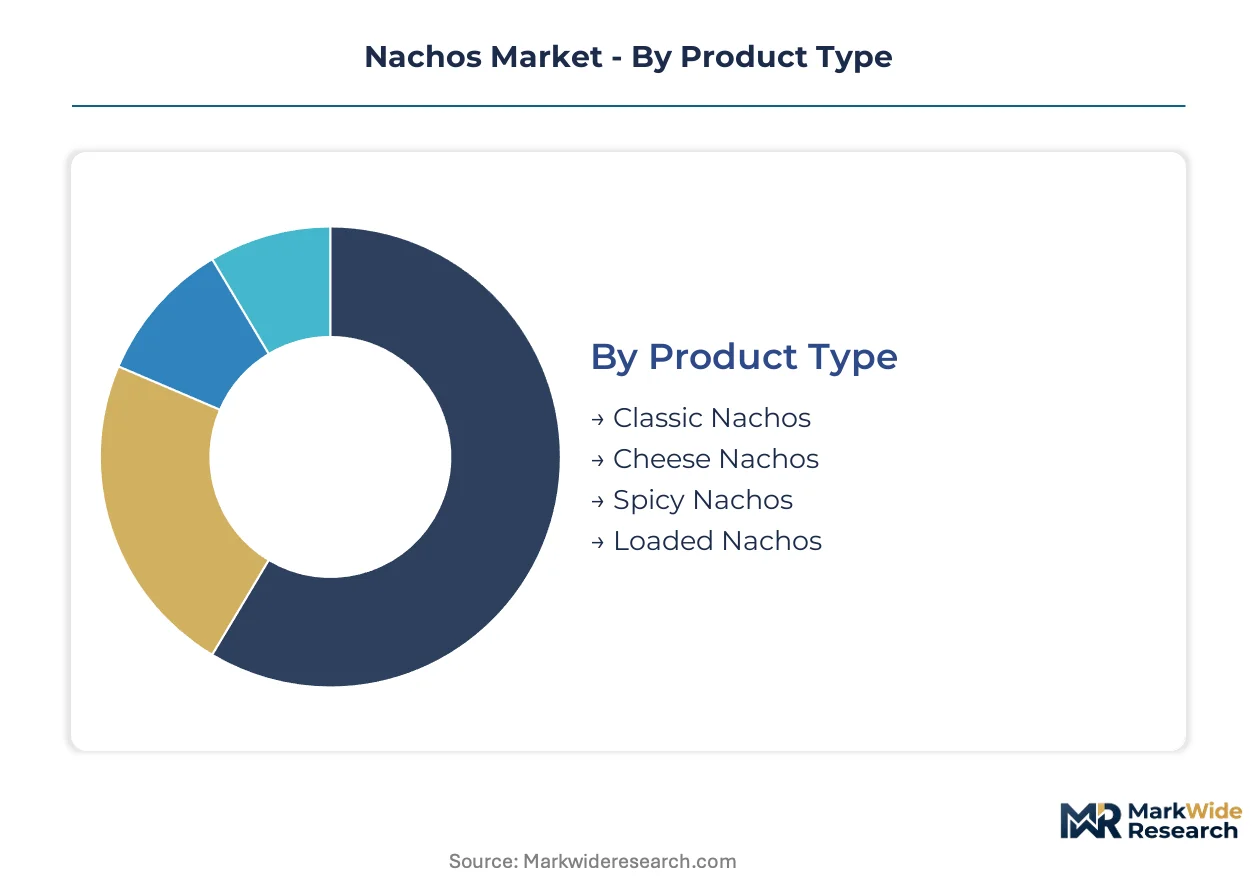
Segmentation in the nachos market reveals how supply chain concentration and consumption context reshape competitive positioning. Product formats, ingredient specifications, serving configurations, and channel access each create distinct margin profiles and sourcing requirements for masa suppliers and topping manufacturers.
Product Type:
Supply concentration in industrial masa production favors high-volume formats that amortize nixtamalization equipment costs across predictable batch sizes.
- Classic Nachos:Unadorned tortilla chips with minimal topping specifications dominate cinema and stadium concession procurement. Demand concentrates in US multiplex chains where extended-hold cheese sauce compatibility determines supplier selection.
- Cheese Nachos:Standard cheese sauce coverage represents the baseline formulation for foodservice operators. US Southwestern regional chains and Mexican cinema circuits anchor volume, with FDA pasteurization compliance filtering supplier pools.
- Spicy Nachos:Chile-infused coatings requiring COFEPRIS additive clearance for cross-border distribution.
- Loaded Nachos:Multi-component configurations with premium proteins and specialty salsas.
Today's leader: Classic Nachos. Tomorrow's challenger: Loaded Nachos.
Ingredient Type:
Cost tier differentiation separates commodity procurement from certified ingredient premiums that command placement in specialty retail.
- Organic Corn:Non-GMO yellow corn varieties sourced through contracted Midwestern US growers carry USDA Organic certification premiums. Natural grocery chains and direct-to-consumer platforms in California and Texas concentrate demand.
- Gluten-Free Tortilla:Dedicated processing lines eliminate cross-contamination for celiac-safe certification. US health-focused retailers and Canadian cinema chains with dietary accommodation mandates drive specification adoption.
- Cheddar Cheese:Commodity dairy sourcing through Wisconsin and California cooperatives.
- Salsa:Tomato and pepper-based condiments with regional recipe variation.
Volume concentrates in Cheddar Cheese. Premium expansion centers on Organic Corn.
Serving Style:
Application context dictates packaging specifications that determine shelf-life engineering and portion control economics.
- Tray:Open-faced disposable containers designed for immediate consumption in seated venues. US sports stadium premium seating tiers and Mexican cinema chains standardize this format for labor efficiency.
- Bag:Flexible packaging for retail portability and foodservice pre-portioning. Convenience store chains across the US Southwest and grab-and-go operators in Mexican transit hubs drive format specification.
- Bowl:Contained vessels for loaded configurations with multiple components.
- Platter:Shareable presentations for group consumption occasions.
Tray dominates foodservice throughput. Bag captures retail velocity expansion.
Distribution Channel:
Customer type fragmentation between institutional procurement and individual purchase occasions creates divergent margin structures and service requirements.
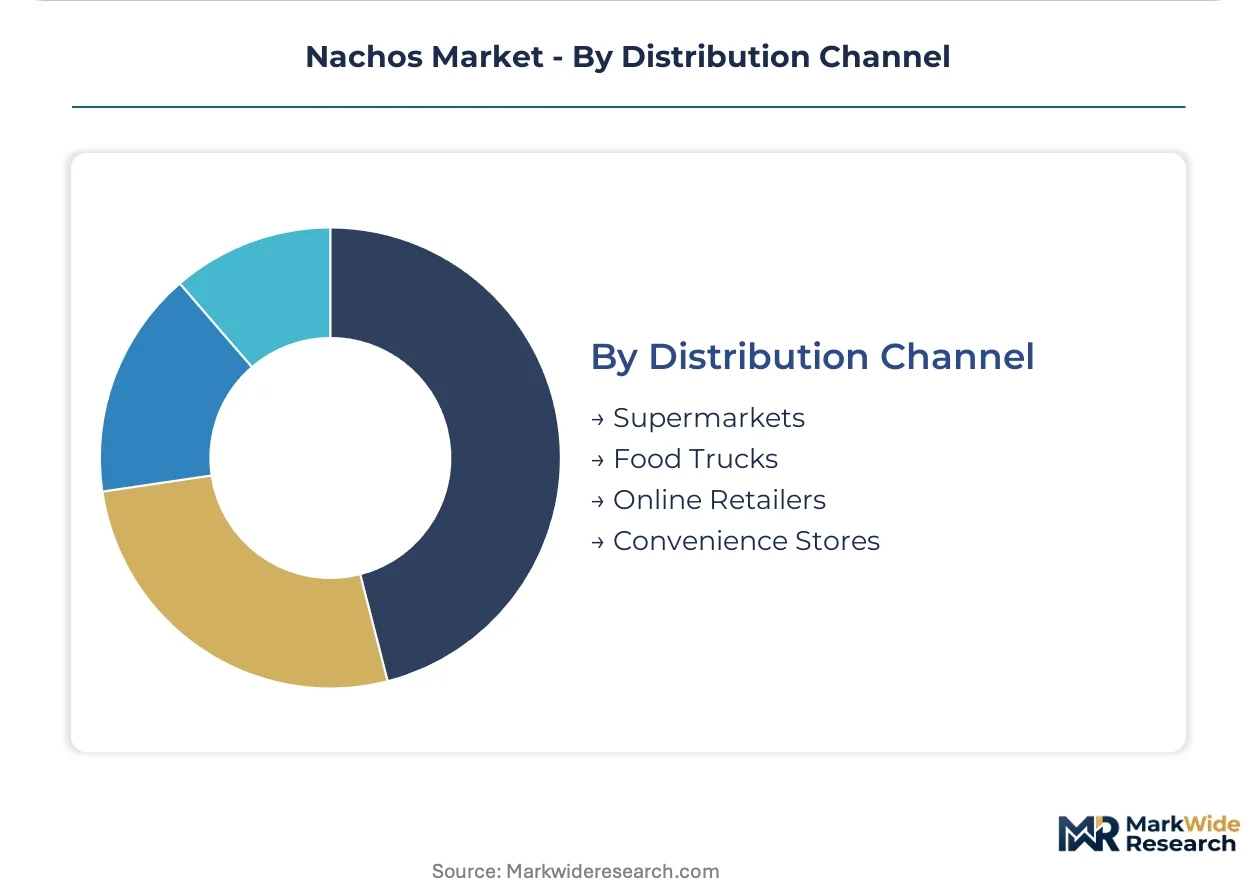
- Supermarkets:Center-store and perimeter placements for retail tortilla chip velocity. US national chains and Mexican regional banners anchor baseline volume with promotional calendar dependence.
- Food Trucks:Mobile operators requiring compact equipment footprints and rapid throughput capability. Austin, Los Angeles, and Mexico City street food clusters concentrate artisanal format experimentation.
- Online Retailers:Direct-to-consumer platforms capturing specialty and subscription formats outside traditional placement constraints.
- Convenience Stores:Immediate consumption occasions with grab-and-go packaging specifications.
Supermarkets sustain volume foundation. Online Retailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping tortilla chip production geography as Mexico's COFEPRIS streamlines cross-border coating approvals while US FDA pasteurization mandates elevate compliance costs for cheese sauce suppliers. Masa producers are relocating alkaline cooking capacity toward border-adjacent industrial zones to capture duty-efficient export positioning without sacrificing US market access.
United States
Cinema chains and sports stadium concessionaires anchor tortilla chip procurement volume, with multiplex operators demanding extended-hold cheese sauce specifications. FDA updated nutrition labeling requirements for prepared foods are forcing reformulation investments across pump-dispensed topping suppliers. Texas and California industrial clusters concentrate masa fabrication capacity serving Southwestern regional chains.
Mexico
Nixtamalization heritage and captive yellow corn sourcing sustain tortilla chip export competitiveness into US distribution. COFEPRIS additive harmonization for cross-border coating approvals is reducing compliance friction for Jalisco and Nuevo León fabricators. Mexico City metro area anchors artisanal format experimentation while Bajío Region mills automate industrial-scale alkaline cooking systems.
Canada
Health-focused retailers and cinema chains with dietary accommodation mandates drive gluten-free tortilla certification adoption. Health Canada pasteurization standards for prepared cheese toppings align with US FDA requirements, simplifying cross-border supplier qualification. Ontario and Quebec distribution hubs concentrate import velocity for specialty and organic corn varieties.
Germany
Snack manufacturers leverage cereal grain procurement infrastructure to secure consistent ingredient flows for European tortilla chip production. EFSA food additive regulations and EU front-of-pack nutrition labeling schemes are shaping clean-label reformulation priorities. Bavaria and North Rhine-Westphalia host industrial baking and snack processing equipment clusters serving continental distribution.
United Kingdom
Supermarket private-label programs and convenience store chains sustain baseline retail velocity for bagged tortilla chip formats. UK Food Standards Agency enforcement of allergen labeling and novel food regulations filters supplier pools for imported masa-based products. London-Southeast distribution corridors concentrate specialty and artisanal format access through direct-to-consumer platforms.
Nachos Market Competitive Environment
US-based producers anchor one tier; Mexican specialists hold cost-advantaged nixtamalization expertise. The vendor base concentrates around diversified snack conglomerates with captive corn procurement infrastructure and regional tortilla mill operators with alkaline cooking process specialization. Three archetypes dominate: vertically integrated grain-to-chip processors, contract masa suppliers serving private-label programs, and artisanal fabricators targeting specialty retail. Competitive moves center on automation capital deployment for nixtamalization consistency and strategic partnerships with cinema concession procurement consortia.
Within the diversified-snack conglomerate tier, Frito-Lay and General Mills exemplify scale-driven procurement leverage over yellow corn supply chains. Grupo Bimbo occupies a position bridging Latin American distribution density with US market penetration through pan-regional logistics infrastructure. These three companies represent distinct strategic postures: captive hybrid corn development, cereal grain infrastructure repurposing, and bakery-snack network integration.
| Leading Market Players |
|---|
| General Mills |
| Mondelēz International |
| Frito-Lay (PepsiCo) |
| Intersnack Group |
| Kellogg Company |
| Pringles |
| Grupo Bimbo |
| Nacho King |
| Conagra Brands |
| Others |
Value Chain & Pricing Dynamics
USDA BioPreferred procurement specifications for federal facility concession contracts gate both qualified supply access and premium-tier pricing eligibility, forcing suppliers to certify biobased packaging and ingredient sourcing before capturing compliance-driven preference premiums in institutional nacho procurement channels.
Pricing Analysis
Distributor margin compression in cinema and stadium concession supply chains is intensifying as extended-hold cheese sauce specifications require specialized formulation investments. Three-tier pricing structure across premium organic corn, standard yellow corn, and economy-grade masa separates certified biobased suppliers from commodity processors. Price differentiation hinges on USDA Organic certification and FDA pasteurization compliance tier. Foodservice operators show highest price sensitivity due to volume procurement leverage, while direct-to-consumer specialty retail exhibits lowest sensitivity.
Supply Chain Analysis
COFEPRIS additive clearance certification gates cross-border supply access for Mexican tortilla fabricators targeting US distribution. Geographic concentration centers on Mexico, the United States, and Canada for nixtamalized corn masa production. Raw material dependencies include proprietary hybrid yellow corn varieties, food-grade lime for alkaline cooking, and pasteurized cheese sauce formulations. Single-source vulnerability persists in captive corn seed development controlled by dominant processors. Distribution runs through pan-regional bakery and snack logistics networks anchored by Grupo Bimbo infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nachos procurement is becoming a margin-expansion story as automation in nixtamalization systems drives per-batch labor cost reduction while premium loaded formats capture pricing premiums in cinema premium seating tiers.
For Market Incumbents: Acquire skid-mounted alkaline cooking unit manufacturers to secure modular production architecture for mid-scale tortilla mills. Consolidate backward integration into proprietary hybrid corn breeding programs to defend against input cost volatility from drought cycles in US Midwest growing regions. Lock in extended-hold cheese sauce formulation patents before FDA compliance timelines accelerate.
For New Entrants and Emerging Players: Launch via food truck channel partnerships in Austin, Los Angeles, and Mexico City street food clusters where artisanal format experimentation concentrates. Target online retail velocity through direct-to-consumer specialty platforms capturing subscription formats outside supermarket placement constraints. Penetrate gluten-free certification white space in Canadian cinema chains with dietary accommodation mandates.
For Investors and Strategic Acquirers: Roll-up economics work for regional tortilla mill operators with nixtamalization process specialization because industrial food science programs produce limited graduates with hands-on alkaline cooking expertise. Target mid-cap fabricators with COFEPRIS clearance and USDA Organic dual certification. Watch COFEPRIS additive harmonization progress as inflection signal for cross-border supply consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Nixtamalization Automation Investment | Reduces labor costs and improves masa consistency for high-volume chip fabrication. |
| Extended-Hold Cheese Sauce Development | Meets cinema chain specifications for viscosity maintenance beyond four hours. |
| Biobased Packaging Certification | Unlocks USDA BioPreferred procurement preference in federal facility contracts. |
| COFEPRIS Additive Harmonization | Streamlines cross-border coating approvals for Jalisco and Nuevo León fabricators. |
| Food Truck Channel Partnership | Captures underdeveloped distribution for artisanal nacho formats with premium toppings. |
Study Parameters
Direct dialogue with cinema concession procurement directors, industrial masa suppliers, COFEPRIS regulatory affairs specialists, and food truck operators grounded the qualitative foundation. Secondary validation drew from FDA cheese sauce pasteurization guidance documents, USDA corn grading standards, COFEPRIS additive clearance registries, and Nielsen retail audit data for tortilla chip velocity. Bottom-up volume modeling triangulated against top-down category spend estimates across the analysis window.
Top-down macroeconomic drivers filtered through bottom-up segment granularity across product type, ingredient certification tier, serving style application, and distribution channel access. Segmentation dimensions modeled include classic versus loaded format positioning, organic versus conventional corn sourcing, tray versus bag packaging specifications, and supermarket versus online retail velocity. CAGRs derived from historical trajectory analysis and forward-looking regulatory compliance cost absorption rates. Forecast inputs incorporated nixtamalization automation capital deployment cycles and front-of-package warning label regime expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under yellow corn price volatility from drought cycles and accelerated FDA nutrition labeling compliance deadlines. Model assumptions reflect documented stakeholder input and secondary source triangulation. A model refresh is warranted upon material change in COFEPRIS-USDA regulatory harmonization progress or cinema chain consolidation in extended-hold cheese sauce specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Sodium Snacks Market
Snacks
United Kingdom Energy Bar Market
Snacks
Qatar Potato Chips Market
Snacks
Germany Energy Bar Market
Snacks
North America Snack Bar Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
Europe Snack Bar Market
Snacks
North America Baked Savory Snacks Market
Snacks
Asia Pacific Tortilla Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Europe Frozen Snacks Market
Snacks
Protein Crisps Market
Snacks
Dried Fruit Snacks Market
Snacks
North America Snack Pellets Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Tortilla Mix Market