
 Poland Rail Freight Transport Market | 2026-2036
Poland Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Rail Freight Transport Market Analytics
The EU Green Deal's modal shift targets for freight transport is broadening investment horizons across Polish rail corridors. PKP Cargo leverages its extensive domestic network to sustain volume leadership in bulk commodities. CTL Logistics anchors intermodal operations through strategic terminal positions in Łódź and Małaszewicze. DB Cargo Polska competes on cross-border efficiency into Germany and the Czech Republic.
Poland rail freight transport encompasses the movement of goods via railway infrastructure using diesel and electric locomotives across standard-gauge networks, typically operating at axle loads up to 22.5 tonnes and train lengths exceeding 700 meters. This system serves industrial supply chains by offering land-based cargo movement with lower carbon intensity per tonne-kilometer than road alternatives. Intermodal transport represents the fastest-expanding service category as manufacturers seek integrated sea-rail-road solutions. Bulk transport retains the largest volume share but faces margin pressure from energy commodity fluctuations. Container transport commands premium pricing through refrigerated and specialized equipment offerings.
Poland's Office of Rail Transport and the European Union Agency for Railways enforce safety standards and interoperability mandates that shape fleet modernization requirements. EU F-Gas Regulation and national emission frameworks limit diesel locomotive deployments in urban corridors and terminal zones. Stakeholders must monitor TEN-T corridor completion timelines and cross-border capacity auctions to secure strategic positioning.
Market Dynamics
The EU Green Deal's modal shift mandates are restructuring Poland's rail freight economics, forcing infrastructure owners to accelerate electrification timelines while chemical and automotive shippers rewrite logistics contracts to meet Scope 3 targets.
Growth Catalysts
- TEN-T Corridor Completion:The Baltic-Adriatic corridor upgrades are unlocking dedicated freight capacity through Silesia and Małopolska, reducing transit times to Adriatic ports.
- Chemical Sector Contract Expansion:Hazardous material shippers in the Oświęcim industrial cluster are locking in multi-year rail commitments to replace road tanker movements.
- EU F-Gas Regulation:Terminal operators in Warsaw and Łódź are retiring diesel switchers ahead of urban emission deadlines, creating fleet replacement demand.
Market Restraints
- Cross-Border Capacity Auctions:DB Netz and Správa železnic control priority slots into Germany and Czechia, squeezing Polish operator margins on international routes.
- Legacy Signaling Infrastructure:ETCS Level 2 deployment gaps on the CMK central trunk line limit train frequency below theoretical capacity.
- Steel Price Volatility:Rail and sleeper input costs from ArcelorMittal Poland and imported Ukrainian steel fluctuate with energy market instability.
Strategic Opportunities
- Podlaskie-Volhynia Cross-Border Links:Gauge conversion terminals at Hrubieszów and Dorohusk can capture Ukrainian grain and ore flows displaced from Black Sea routes.
- Battery-Electric Shunting:Lithium-titanate traction systems are converging with solar-powered terminal microgrids to eliminate diesel dependency in urban yards.
- Refrigerated Intermodal:Pharma cold chains from Warsaw and Poznań are migrating to temperature-controlled rail containers for EU distribution.
Industry Challenges
- Locomotive Engineer Shortage:PKP Cargo and private operators compete for certified drivers trained on both ETCS and legacy signaling systems.
- Intermodal Terminal Integration:Legacy warehouse management systems at Łódź and Małaszewicze require middleware upgrades to sync with rail operating platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Rail Freight Transport Market |
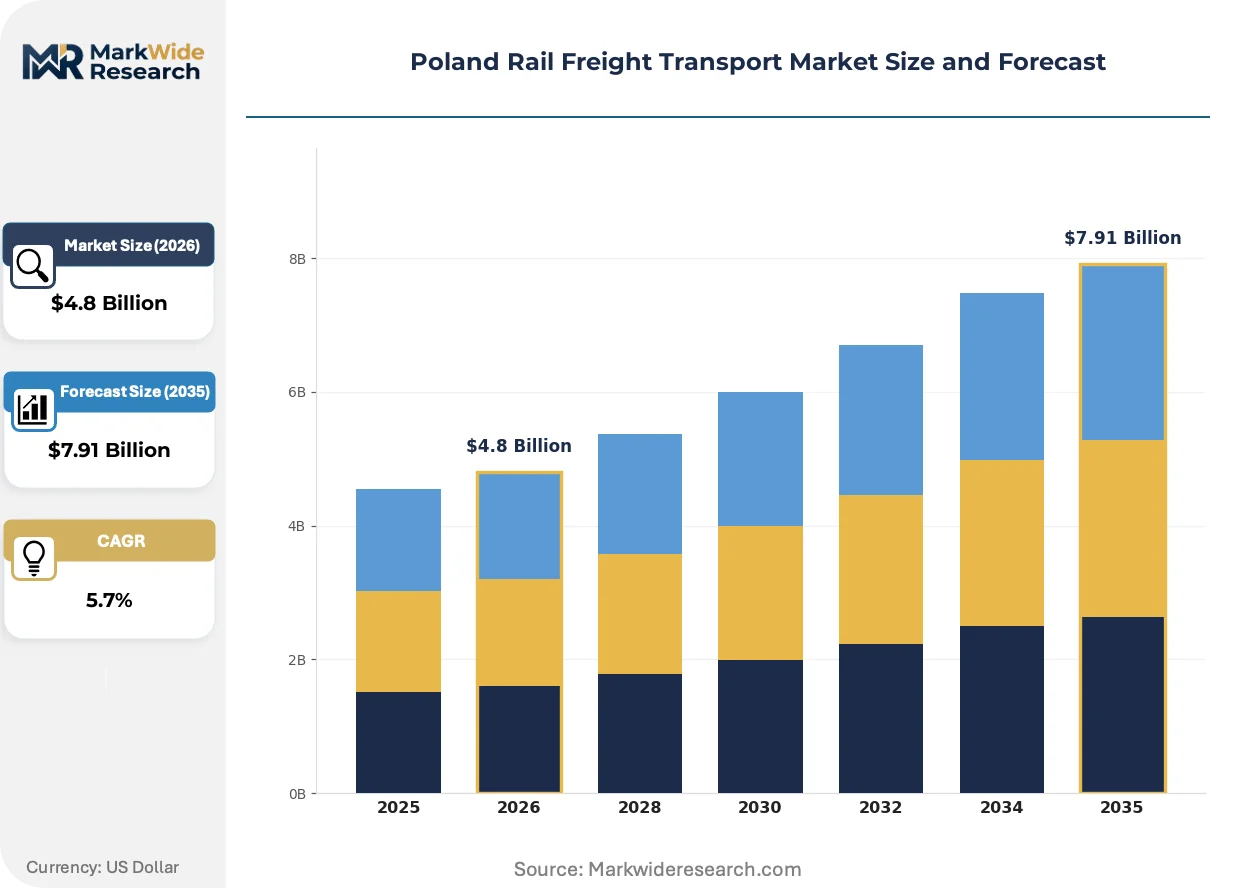
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Shunting, Container Transport, Bulk Transport, Intermodal Transport Delivery Mode: Direct Delivery, Scheduled Delivery, Same-Day Delivery, Scheduled Freight Transport Customer Type: Manufacturers, Distributors, Retailers, Importers Container Type: Flat Rack, Bulk Tank, Refrigerated, Open Top |
| Companies Covered | CTL Logistics, Orlen KolTrans, PKP Cargo, PCC Intermodal, Inter Cargo, DB Cargo Polska, Freightliner, CD Cargo Poland, Lotos Kolej, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Rail Freight Transport Market Evolving Landscape
Digital automation and alternative traction technologies are compressing operating cost structures while EU environmental compliance deadlines force capital reallocation away from diesel assets.
Automated train operation is converging with predictive maintenance analytics to reshape crew scheduling and asset utilization. CTL Logistics and PKP Cargo are piloting ATO-GoA2 systems on the Łódź-Warsaw corridor. This convergence is enabling 24-hour terminal throughput without shift-change delays, compressing turnaround times at Małaszewicze.
The EU Green Deal's modal shift targets are mandating 30% freight volume transfer from road to rail by 2030. Poland's Office of Rail Transport is accelerating infrastructure access fee reforms to reward electric traction. Bulk commodity shippers in Silesia are responding by renegotiating long-term contracts to secure guaranteed slot allocations.
Shippers are unbundling transport procurement from warehousing contracts, forcing 3PLs to compete on rail-specific KPIs rather than bundled pricing. Automotive manufacturers in Bielsko-Biała and Tychy are issuing separate RFPs for rail legs versus terminal handling. This pattern is most visible in the Katowice logistics cluster where OEMs are qualifying multiple rail operators per corridor.
Poland Rail Freight Transport Market Segmentation
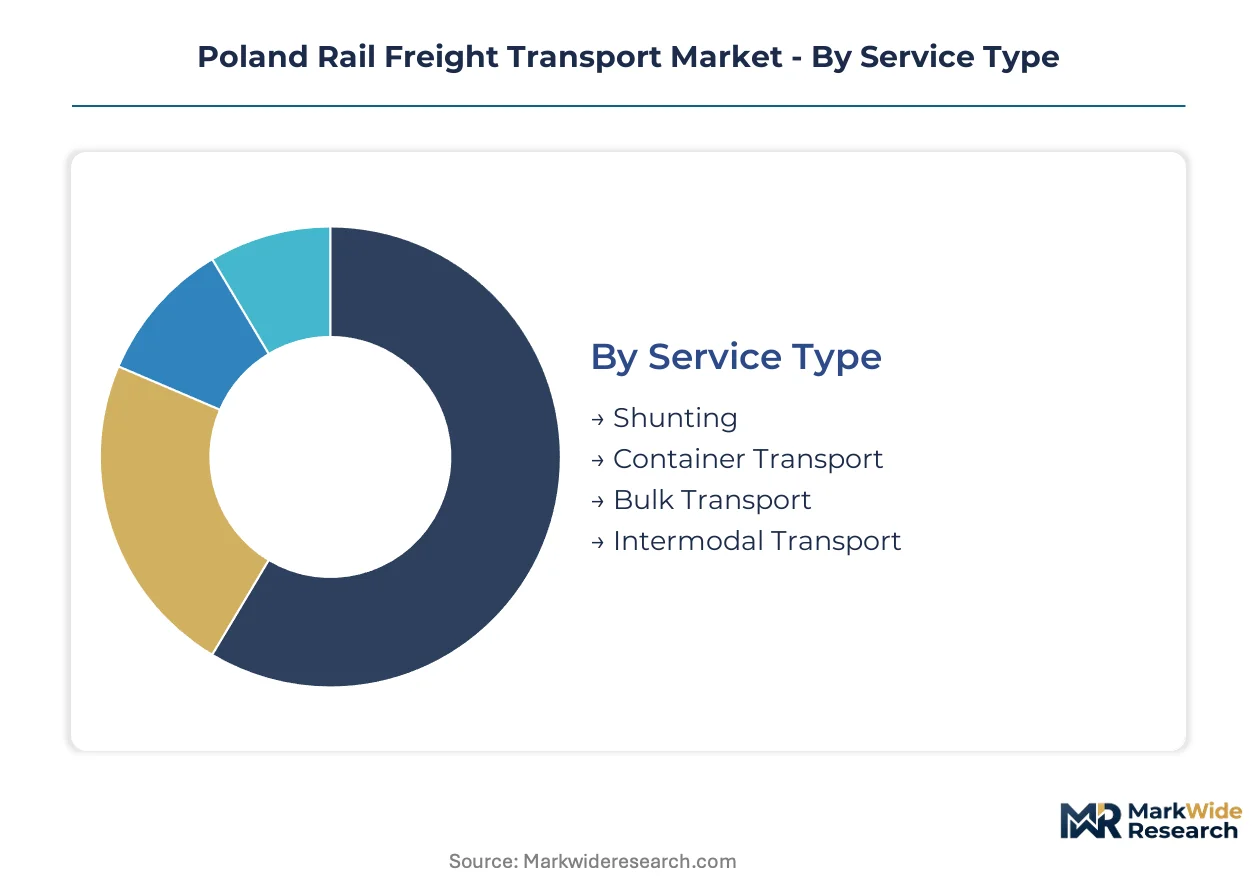
Poland's rail freight market segments along operational, customer, and equipment dimensions that determine pricing power and asset utilization. Shippers select service configurations based on cargo characteristics, delivery urgency, and integration requirements with broader supply chains.
Service Type:
Operational complexity and cargo handling requirements drive buyer selection between specialized and integrated service modes.
- Intermodal Transport:Seamless integration of rail legs with sea and road connections through standardized containers and swap bodies. Pharmaceutical and automotive manufacturers in Warsaw and Poznań are locking in multi-year contracts to secure capacity on Baltic-Adriatic corridor routes.
- Container Transport:Dedicated movement of ISO containers between terminals and inland logistics hubs, typically operating at fixed schedules with guaranteed slot allocations. Małaszewicze and Łódź terminals are capturing concentrated demand from Central European freight forwarders seeking China-Europe rail bridge alternatives.
- Bulk Transport:Movement of unpackaged commodities including coal, ore, and aggregates in open wagons or specialized hoppers.
- Shunting:Yard-based locomotive operations for train assembly, disassembly, and terminal positioning.
Bulk transport leads on scale; intermodal transport leads on momentum.
Delivery Mode:
Speed premiums and reliability guarantees separate pricing tiers across urgency-sensitive cargo categories.
- Scheduled Freight Transport:Fixed-timetable operations with published departure windows and guaranteed transit windows. Chemical manufacturers in the Oświęcim cluster are negotiating scheduled blocks to replace road tanker movements for hazardous materials.
- Direct Delivery:Non-stop train operations between origin and destination without intermediate classification or terminal processing.
- Scheduled Delivery:Day-definite arrival commitments with flexible routing through the Polish network.
- Same-Day Delivery:Express rail services compressing transit times through priority pathing and dedicated locomotive assignment.
Scheduled freight transport dominates volume throughput; same-day delivery commands the steepest expansion trajectory.
Customer Type:
Contract structure and volume commitment levels vary systematically across buyer categories with different inventory strategies.
- Manufacturers:Industrial producers with captive logistics functions or direct rail siding access. Steel and chemical producers in Upper Silesia are anchoring long-term volume commitments to secure favorable infrastructure access fees.
- Distributors:Third-party logistics operators consolidating cargo from multiple shippers into block trains.
- Retailers:Large-format and e-commerce operators with seasonal demand spikes requiring flexible capacity.
- Importers:Trading companies moving containerized goods from Baltic ports to inland distribution centers.
Manufacturers lead on scale; importers lead on momentum.
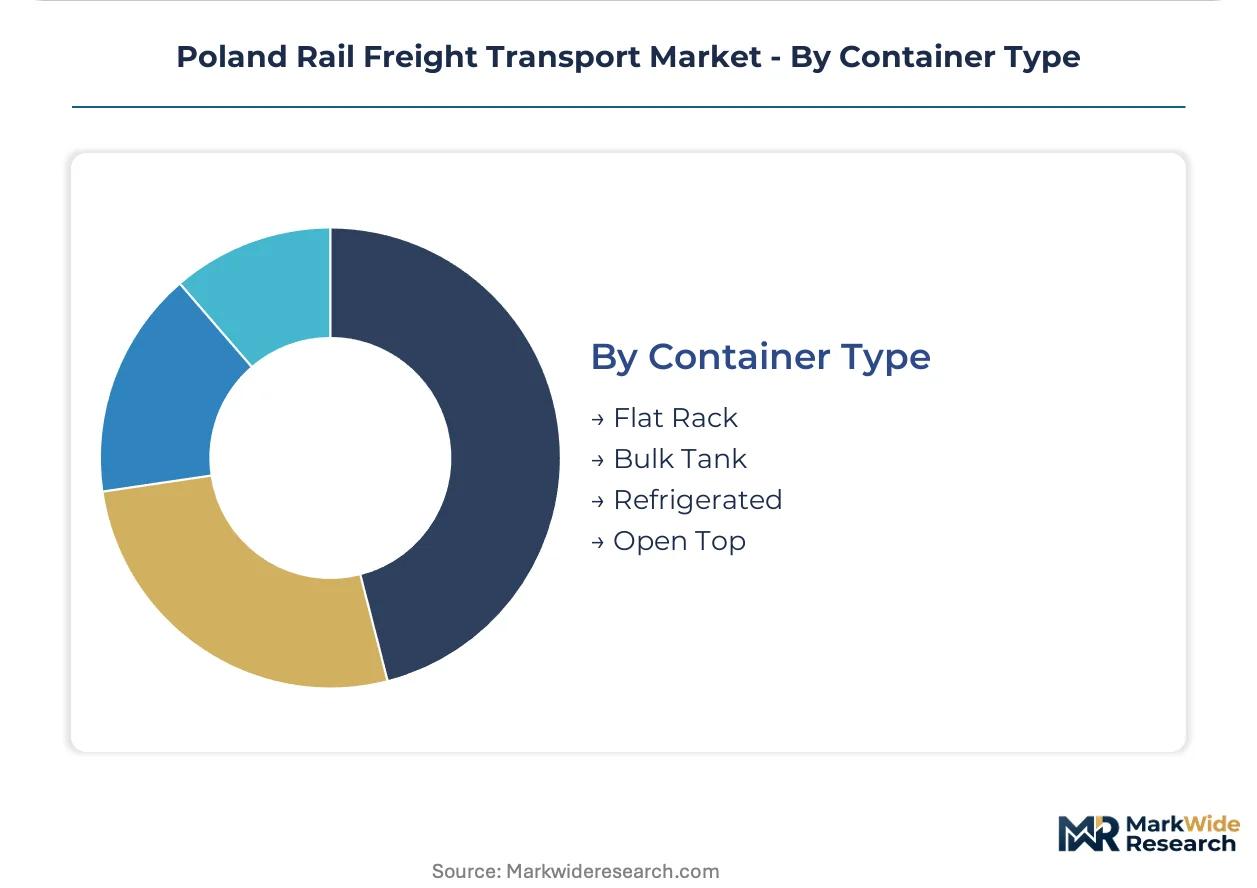
Container Type:
Equipment specialization determines cargo eligibility and tariff structures across temperature-sensitive and oversized freight categories.
- Refrigerated:Temperature-controlled units with integrated cooling systems for pharma and food cold chains. Warsaw-based pharmaceutical distributors are migrating temperature-sensitive products from road to rail for EU distribution networks.
- Flat Rack:Collapsible-sided platforms for heavy machinery and project cargo exceeding standard container dimensions.
- Bulk Tank:Specialized liquid and gas containment systems for chemical and petroleum product movements.
- Open Top:Removable-roof containers for top-loading of bulk materials and tall cargo items.
Flat rack leads on scale; refrigerated leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers and certified locomotive drivers cluster around Silesia's coal belt and Warsaw's intermodal terminals, anchoring Poland's rail freight workforce density. This talent concentration shapes infrastructure investment patterns and operator expansion decisions across the country's freight corridors.
Upper Silesia
Coal and steel producers in Katowice and Gliwice generate sustained bulk transport demand through dedicated siding networks. The EU Green Deal's modal shift mandates are pressuring industrial shippers to convert road haulage contracts to rail. ArcelorMittal Poland's integrated steelworks anchor high-volume ore and coke movements along the CMK central trunk line.
Masovia
Pharmaceutical distributors in Warsaw and automotive suppliers in Bielsko-Biała are migrating temperature-controlled cargo to scheduled rail services. Poland's Office of Rail Transport enforces ETCS interoperability deadlines that accelerate fleet modernization across terminal operators. Małaszewicze's container terminal captures China-Europe rail bridge traffic seeking Baltic port alternatives.
Łódź Voivodeship
Third-party logistics operators consolidate garment and electronics cargo into block trains for Adriatic corridor destinations. EU F-Gas Regulation compliance deadlines are forcing diesel switcher retirement at urban terminals. CTL Logistics anchors intermodal operations through strategic terminal positions connecting manufacturers to Baltic and North Sea ports.
Podlaskie
Grain and ore flows from Ukraine are rerouting through Hrubieszów and Dorohusk gauge conversion terminals displaced from Black Sea shipping lanes. National emission frameworks limit diesel locomotive deployments in terminal zones near Białystok. Cross-border infrastructure investments are capturing agricultural commodity movements from Volhynia and Lviv oblasts.
Lesser Poland
Chemical manufacturers in the Oświęcim industrial cluster are locking in multi-year rail commitments for hazardous material movements. TEN-T corridor upgrades are unlocking dedicated freight capacity through Silesia and Małaszewicze reducing transit times to Adriatic ports. Grupa Azoty's fertilizer production anchors specialized tank wagon demand along the Kraków-Rzeszów axis.
Poland Rail Freight Transport Market Competitive Landscape
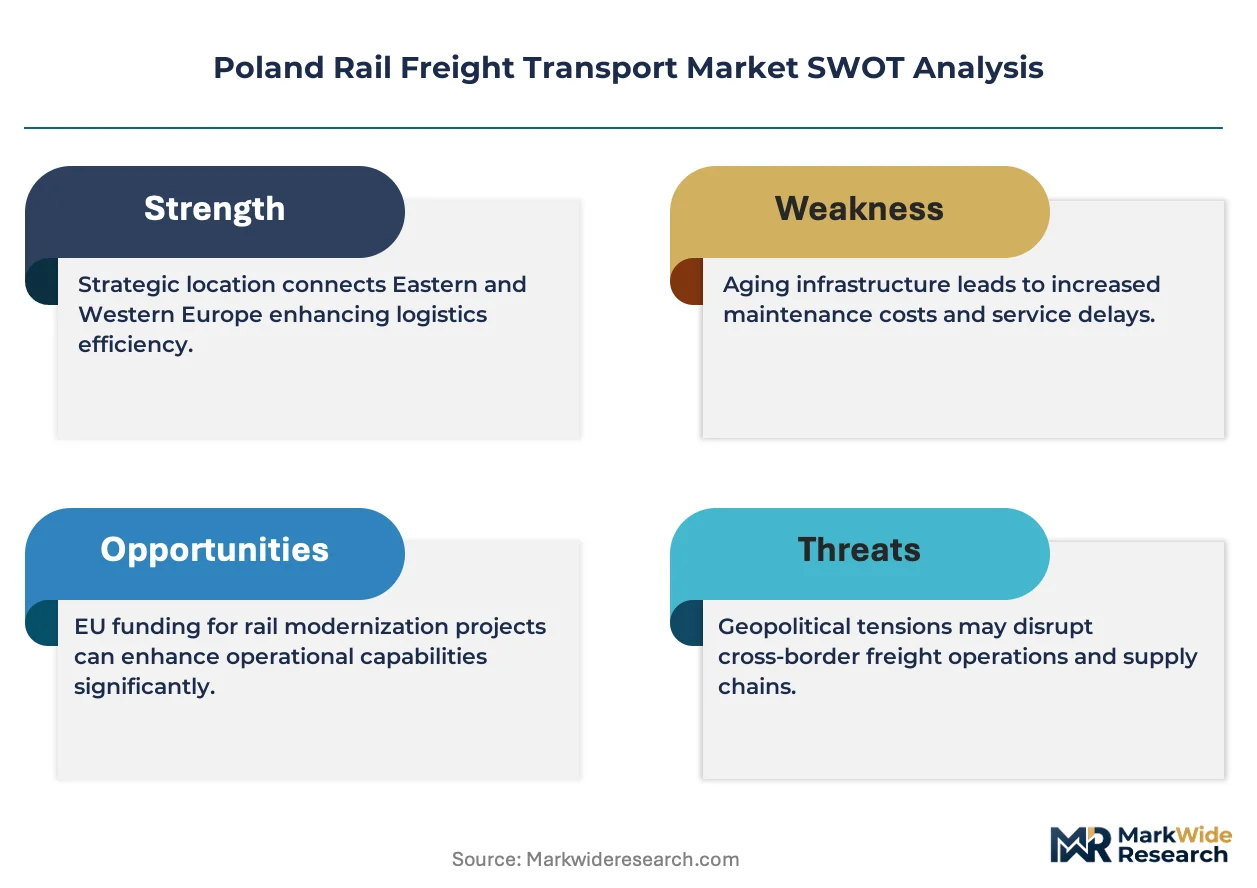
Capital-heavy infrastructure owners compete with asset-light operators leasing traction and path capacity. The market structure concentrates around three tiers: state-affiliated incumbents with terminal real estate, private intermodal specialists with corridor expertise, and international subsidiaries leveraging cross-border networks. Dominant competitive moves include terminal capacity expansion along Baltic-Adriatic corridors and strategic partnerships with chemical and automotive shippers seeking Scope 3 emissions reductions.
Among Poland-based operators, PKP Cargo and CTL Logistics occupy positions as volume leaders in bulk and intermodal segments respectively. DB Cargo Polska represents the international subsidiary archetype competing on cross-border efficiency into Germany and the Czech Republic. These three anchors exemplify the strategic archetypes shaping contract negotiations and infrastructure access fee structures across Polish rail corridors.
| Leading Market Players |
|---|
| CTL Logistics |
| Orlen KolTrans |
| PKP Cargo |
| PCC Intermodal |
| Inter Cargo |
| DB Cargo Polska |
| Freightliner |
| CD Cargo Poland |
| Lotos Kolej |
| Others |
Value Network & Pricing Analysis
Captive terminal ownership by PKP Cargo and CTL Logistics anchors pricing power through infrastructure access control, while EU Green Deal compliance deadlines force capital reallocation into electrified traction fleets that reshape cost structures across Polish rail corridors.
Pricing Analysis
Contract-based long-term offtake agreements dominate chemical and automotive shipper relationships, with price differentiation hinging on volume scale and ETCS interoperability certification. Premium-mid-economy pricing differentiation separates scheduled block trains from ad-hoc spot movements. Cost compression in intermodal services is intensifying because shippers unbundle transport from warehousing procurement. Small importers exhibit highest price sensitivity; bulk commodity manufacturers with captive sidings show lowest.
Supply Chain Analysis
Direct-to-manufacturer channels handle high-volume contract demand from ArcelorMittal Poland and Grupa Azoty, while distribution runs through third-party logistics consolidators for fragmented retail and importer segments. Locomotive manufacturing concentrates in Poland, Germany, and the Czech Republic. Steel rail and concrete sleeper inputs draw from ArcelorMittal Poland and Ukrainian suppliers. Single-source vulnerability in cross-border path auctions with DB Netz and Správa železnic threatens margin stability on international routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's rail freight market operates as a regulatory compounder where EU F-Gas Regulation compliance deadlines and TEN-T corridor investments continuously reshape infrastructure access economics and fleet modernization requirements.
For Market Incumbents: Acquire battery-electric shunting locomotive fleets to preempt urban emission zone restrictions in Warsaw and Łódź terminal zones. Secure long-term path capacity reservations on Baltic-Adriatic corridor segments before DB Cargo Polska and CD Cargo Poland capture priority slots. Backward integration into solar-powered terminal microgrids reduces diesel dependency exposure.
For New Entrants and Emerging Players: Ukrainian grain and ore traders displaced from Black Sea routes represent an underserved buyer archetype seeking gauge-converted capacity through Podlaskie border terminals. Target Hrubieszów and Dorohusk cross-border infrastructure with specialized bulk handling equipment. Partner with Polish forwarding agents for customs-clearance bundled pricing.
For Investors and Strategic Acquirers: Roll-up economics work for regional intermodal terminal operators because ETCS modernization requirements create capital barriers that fragment smaller competitors. Five-to-ten year viability hinges on corridor positioning relative to Adriatic port access. Monitor TEN-T completion timelines at Małaszewicze as inflection indicator for China-Europe rail bridge volume capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Electrification | EU F-Gas Regulation deadlines force diesel switcher retirement in Warsaw and Łódź urban zones. |
| Cross-Border Path Auctions | Priority slot acquisition with DB Netz secures German corridor access for chemical shippers. |
| Battery-Electric Fleet Procurement | Lithium-titanate traction systems eliminate diesel dependency in terminal shunting operations. |
| Refrigerated Container Investment | Pharma cold chains from Warsaw migrate to temperature-controlled rail for EU distribution. |
| Intermodal Middleware Integration | Legacy WMS upgrades at Łódź terminals sync warehouse operations with rail platforms. |
Research Methodology
Coverage spans Upper Silesia, Masovia, Łódź Voivodeship, Podlaskie, and Lesser Poland, with primary inputs from each region combining interviews with terminal operations managers, locomotive fleet directors, chemical shipper logistics leads, intermodal forwarding agents, and infrastructure access planners. Secondary validation draws from Poland's Office of Rail Transport filings, EU Agency for Railways interoperability directives, TEN-T corridor development databases, and customs trade flow records. Bottom-up terminal throughput estimates and top-down modal shift projections undergo triangulation.
Granularity-level framing models service type, delivery mode, customer category, and container specialization at segment-specific resolution across the projection horizon. CAGRs derive from volume trajectory analysis against infrastructure capacity expansion schedules. Forecast inputs incorporate ETCS deployment timelines and EU Green Deal modal shift enforcement mechanisms.
Inputs from PKP Cargo and CTL Logistics operational disclosures were available through the study window; gaps in private operator financials introduce uncertainty bands around margin estimates. Forecasts reflect assumptions on corridor completion pacing and cross-border capacity auction outcomes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Railway Fishplate Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Rail Pads Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Rail Switch Point Heating System Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Global Autonomous Trains Market