
 Rail Pads Market | 2026-2036
Rail Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Pads Market Analytics
European elastomer compounders is consolidating production of rail pads as freight operators demand longer-lasting track components. Pandrol leverages its integrated rail fastening systems to control supply chains across Western Europe. Getzner Werkstoffe GmbH sustains competitive positioning through specialized polyurethane formulations engineered for heavy-haul damping. Nantong Zhentong Railway Parts Co. Ltd. anchors cost-efficient manufacturing capacity serving Asia-Pacific infrastructure buildouts.
Rail pads are elastomeric or composite cushioning elements installed between steel rails and concrete or timber sleepers, typically manufactured from rubber, polyurethane, or resin-based compounds through compression molding or injection processes, designed to absorb dynamic loads, attenuate vibration, and prevent rail seat abrasion in track superstructures. Their primary industrial purpose is to distribute wheel loads across the sleeper surface while reducing structure-borne noise transmission to surrounding environments. Polyurethane rail pads command premium positioning due to superior fatigue resistance and extended service life in heavy rail applications, whereas rubber formulations retain volume share in cost-sensitive freight corridors where replacement cycles are shorter. Composite material segments are gaining traction in light rail and passenger networks where regulatory noise limits are most stringent and total cost-of-ownership calculations favor extended maintenance intervals.
Europe's TSI noise standards, Germany's KBA rail vehicle certification requirements, and China's GB/T railway material specifications collectively elevate product compliance barriers and filter subscale suppliers from tender participation. The EU Green Deal's embodied-carbon tracking for infrastructure procurement is beginning to favor rail pad manufacturers with verified recycled-content supply chains and lifecycle-assessed production footprints. Stakeholders must monitor evolving interoperability mandates and material traceability rules to align R&D roadmaps with the compliance architectures taking shape across major rail networks.
Market Dynamics
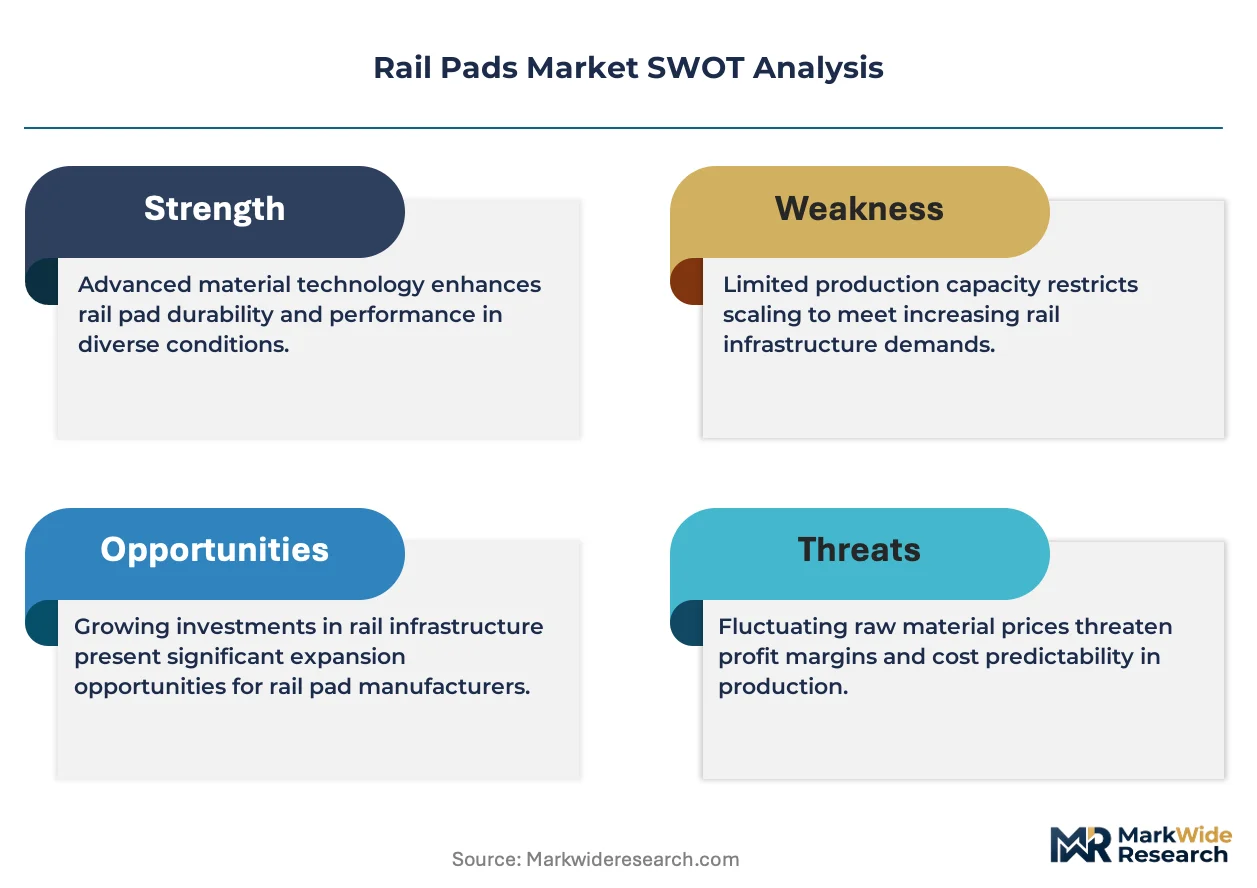
Polyurethane formulation advances are compressing replacement cycles for heavy-haul operators while EU embodied-carbon tracking is filtering supplier participation in public tenders. Rail networks now prioritize lifecycle-assessed pad systems that reconcile fatigue performance with environmental compliance.
Growth Catalysts
- TSI Noise Standards:EU rolling stock interoperability mandates compel freight and passenger operators toward certified composite damping systems that attenuate structure-borne vibration below threshold limits.
- China's High-Speed Corridor Expansion:National rail infrastructure buildouts generate concentrated demand for premium fatigue-resistant pads engineered for continuous welded rail applications.
- India's Dedicated Freight Corridors:Heavy-haul axle load increases on new freight routes accelerate consumption of high-durometer polyurethane formulations with extended service intervals.
Market Restraints
- Isocyanate Price Volatility:Polyurethane raw material costs fluctuate with petrochemical feedstock markets, squeezing margin structures for compounders without backward integration into chemical precursors.
- German KBA Certification Bottlenecks:Extended approval timelines for rail vehicle component testing delay product launches and freeze working capital in compliance pipelines.
- Rubber Substitution in Cost-Sensitive Corridors:Lower-grade elastomer pads retain volume in emerging market freight applications where replacement labor costs remain below polyurethane premium amortization.
Strategic Opportunities
- Recycled-Content Supply Chains:EU Green Deal procurement preferences favor manufacturers with verified post-industrial rubber reprocessing capabilities and ISO-compliant carbon footprint documentation.
- Light Rail Electrification Projects:Urban transit authorities in France and Spain specify low-profile composite pads that reduce trackform height while meeting stringent noise emission ceilings.
- Digital Twin Integration:Predictive maintenance platforms from rolling stock OEMs create data-sharing partnerships with pad suppliers to optimize replacement scheduling based on real-time load monitoring.
Industry Challenges
- Polyurethane Formulation Chemistry Expertise:Compounders struggle to recruit polymer scientists capable of balancing dynamic mechanical properties with flame-retardant additives for tunnel applications.
- Legacy Timber Sleeper Compatibility:Operators with mixed track inventories require pad geometries that perform across concrete and timber substrates without inventory proliferation.
- Multi-Jurisdiction Certification Overlap:Suppliers face redundant testing costs when China's GB/T specifications diverge from EN railway material standards for equivalent performance claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Pads Market |
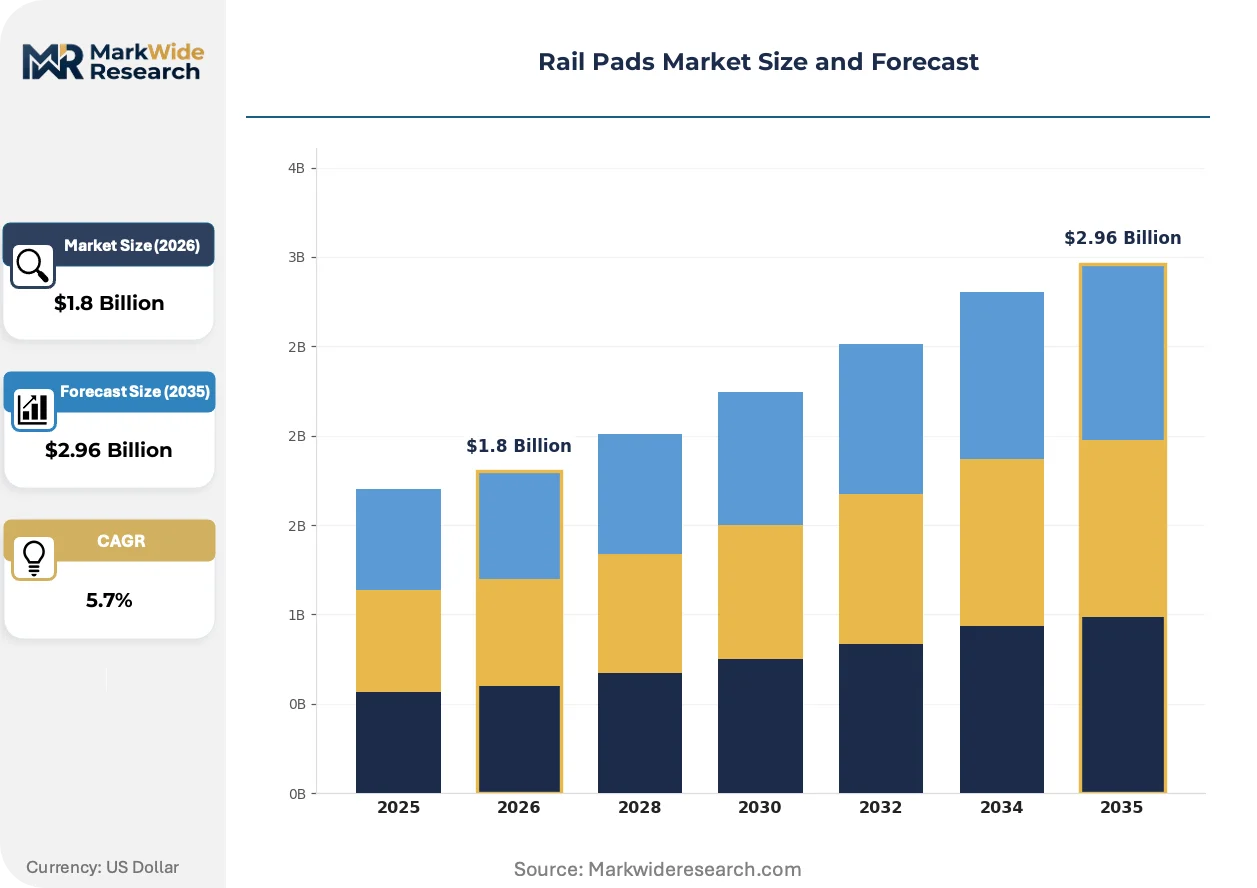
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber, Polyurethane, Resin, Composite Application: Freight, Passenger, Light Rail, Heavy Rail End User: Railway Operators, OEMs, Maintenance Providers, Infrastructure Companies Installation Type: Trackside, Depot, Workshop, Onboard |
| Companies Covered | Pandrol, Tiflex Ltd., Jekay International Track Pvt. Ltd., Anyang General International Co. Ltd., Getzner Werkstoffe GmbH, Nantong Zhentong Railway Parts Co. Ltd., Molytex A/S, Iron Horse Engineering Company, Delkor Rail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Pads Market Evolving Landscape
Material science convergence with digital infrastructure is redefining how rail pads are specified, monitored, and replaced across network maintenance cycles. Three developments dominate competitive positioning.
Microcellular polyurethane formulations with tunable density gradients are electrifying specification standards for heavy-haul damping. North American Class I railroads are accelerating adoption of these engineered foams to extend track service intervals beyond conventional solid elastomer limits. The technology is electrifying procurement criteria by compressing total cost-of-ownership calculations toward lifecycle performance rather than unit price.
REACH chemical registration requirements are tightening disclosure obligations for isocyanate-based formulations imported into EU member states. Compounders must now document full substance inventories through the European Chemicals Agency database to maintain tender eligibility. Western European freight operators are responding by consolidating supplier relationships toward vertically integrated manufacturers with captive REACH compliance teams.
Condition-based maintenance contracts are displacing scheduled replacement programs among infrastructure managers with dense sensor networks. German and Swiss network operators now source pads bundled with wear-monitoring telemetry that triggers replacement only upon measured performance degradation. This behavioral shift concentrates most visibly in alpine corridor operators where tunnel access costs amplify the value of predictive intervention timing.
Rail Pads Market Segmentation
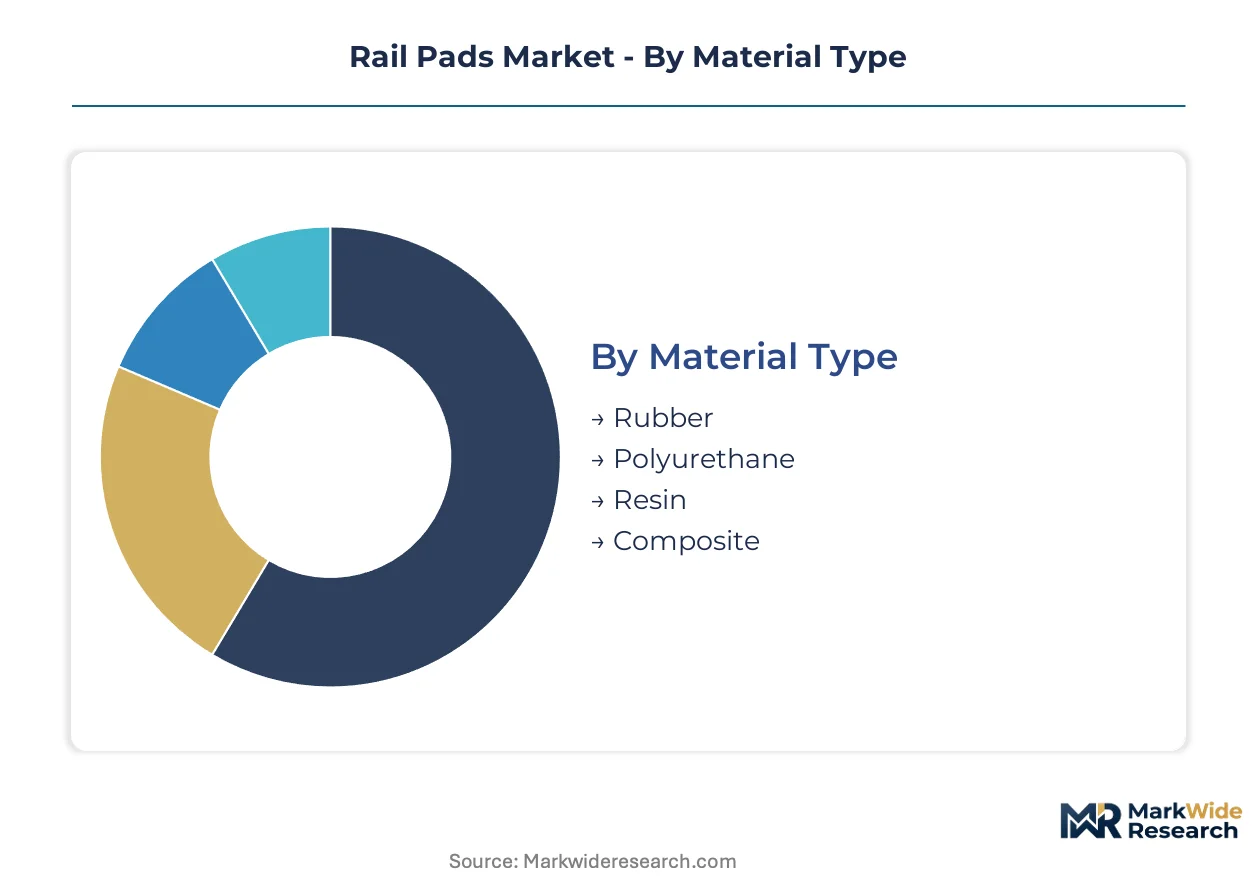
Rail pad procurement patterns diverge sharply across material grades and operational contexts. Specification engineers balance fatigue performance against replacement labor economics while regulatory pressure reshapes material preferences in noise-sensitive corridors.
Material Type:
Cost tolerance and service interval requirements separate buyers across elastomer chemistry tiers.
- Polyurethane:Microcellular foam structures with tunable density gradients deliver superior dynamic load distribution and extended fatigue life. North American Class I railroads specify these formulations for heavy-haul routes where tunnel access costs amplify replacement economics. REACH chemical registration requirements from ECHA filter supplier participation toward compounders with captive compliance infrastructure.
- Rubber:Natural and synthetic elastomer compounds dominate volume through lower unit costs and established supply chains. India's Dedicated Freight Corridor projects source rubber pads for cost-sensitive track sections where replacement labor remains inexpensive. Price volatility in petrochemical feedstocks squeezes margin structures for non-integrated compounders.
- Resin:Thermoset polymer formulations serve specialized damping applications requiring chemical resistance.
- Composite:Multi-layer constructions combining elastomeric cores with reinforcing substrates meet stringent EU noise emission thresholds.
Volume sits with rubber formulations; growth tilts toward polyurethane as lifecycle cost calculations displace unit price procurement.
Application:
Axle loading and operating frequency dictate pad specification intensity across rail modes.
- Heavy Rail:Continuous welded rail networks with 25-tonne axle loads demand high-durometer pads engineered for million-cycle fatigue resistance. China's high-speed corridor expansion concentrates demand for premium formulations with verified dynamic mechanical properties. TSI interoperability mandates compel specification of certified composite systems.
- Freight:Bulk commodity corridors prioritize cost efficiency over extended service intervals. Brazilian and Australian iron ore railways accept shorter replacement cycles to minimize upfront capital deployment. Mixed traffic operations require pad geometries compatible with varying load spectra.
- Passenger:Urban and intercity networks balance ride quality with noise attenuation requirements.
- Light Rail:Low-profile trackform installations in French and Spanish cities specify reduced-height composite pads.
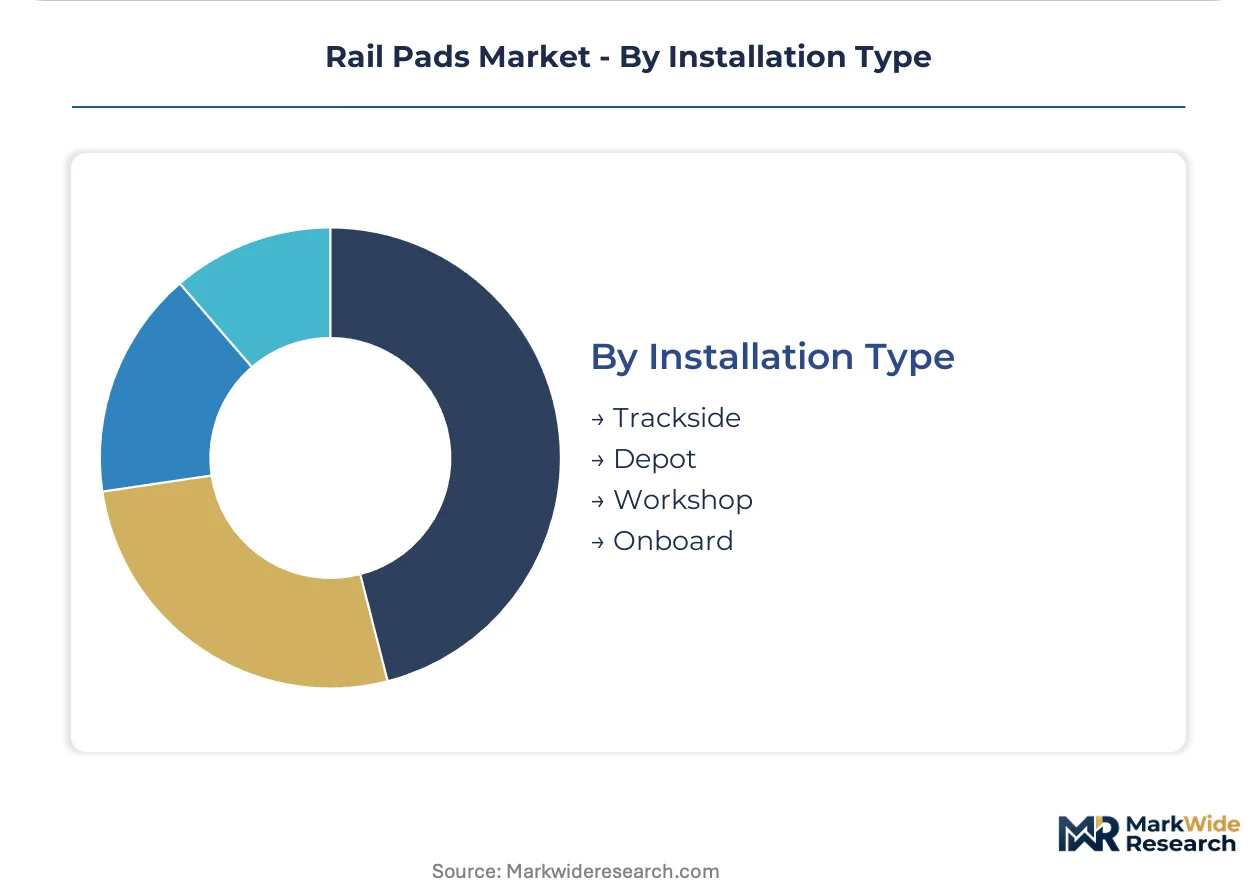
Freight corridors generate the heaviest unit volume; heavy rail applications are climbing the fastest on infrastructure investment cycles.
End User:
Procurement authority and technical specification control vary across the value chain.
- Railway Operators:Deutsche Bahn and SNCF maintain direct supplier relationships for critical track components. Infrastructure managers with dense sensor networks are displacing scheduled replacement with condition-based maintenance contracts. Predictive maintenance platforms create data-sharing partnerships with pad manufacturers.
- OEMs:Rolling stock builders bundle pad systems with turnkey trackform solutions. Pandrol and Vossloh specify captive pad formulations within integrated fastening system portfolios. OEM procurement concentrates volume toward qualified supplier lists with multi-jurisdiction certification coverage.
- Maintenance Providers:Third-party track contractors serve fragmented regional operators with standardized inventory.
- Infrastructure Companies:Project developers on greenfield corridors specify pads within design-build contracts.
Direct operator procurement dominates premium segments; OEM channel share is expanding fastest on bundled system sales.
Installation Type:
Site accessibility and labor mobilization costs structure replacement economics.
- Trackside:In-situ pad replacement on revenue-generating lines demands rapid installation protocols. Swiss and Austrian alpine operators prioritize extended-service formulations to minimize tunnel possession windows. Night-shift labor premiums in German corridors amplify lifecycle cost advantages of premium materials.
- Depot:Controlled-environment installations on maintenance-of-way equipment enable standardized procedures.
- Workshop:Component-level refurbishment serves legacy rolling stock with specialized fastening geometries.
- Onboard:Vehicle-mounted damping elements require flame-retardant formulations for tunnel compliance.
Trackside installation represents the dominant volume channel; depot-based replacement is gaining share fastest on fleet modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast and North Sea basin shapes regional manufacturing economics for polyurethane rail pad compounders. Infrastructure investment cycles and noise regulation stringency create divergent demand profiles across national markets.
Germany
KBA rail vehicle certification requirements compel freight operators toward certified composite damping systems with extended fatigue validation. The EU Green Deal's embodied-carbon tracking filters tender participation toward manufacturers with ISO-compliant lifecycle documentation. Bavaria's industrial corridor hosts compounders supplying alpine corridor operators where tunnel access costs amplify premium material economics.
China
GB/T railway material specifications govern procurement for high-speed corridor expansion generating concentrated demand for fatigue-resistant formulations. MIIT industrial policy prioritizes domestic supply chain security for critical track components. The Yangtze River Delta cluster anchors manufacturing capacity serving continuous welded rail applications across national network buildouts.
United States
Class I railroads specify microcellular polyurethane formulations to compress replacement cycles on heavy-haul routes with 25-tonne axle loads. FRA safety regulations shape material qualification protocols for track superstructure components. Chicago's rail hub concentration drives specification influence for North American freight network procurement.
India
Dedicated Freight Corridor projects accelerate consumption of high-durometer pads engineered for heavy-haul axle load increases. BIS standards compliance requirements structure tender eligibility for track component suppliers. Gujarat's industrial belt hosts fabrication capacity serving cost-sensitive corridor segments where replacement labor economics favor rubber formulations.
France
Urban transit authorities in Paris and Lyon specify low-profile composite pads reducing trackform height while meeting stringent noise emission ceilings. ANSM chemical registration obligations compound REACH compliance burdens for imported polyurethane formulations. The Île-de-France region concentrates specification engineering for light rail electrification projects.
Rail Pads Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry tiers and certification infrastructure. The vendor base stratifies between vertically integrated fastening system suppliers and specialized elastomer compounders. Three archetypes dominate: integrated rail infrastructure providers, dedicated polyurethane formulators, and cost-optimized Asian fabricators. Competitive moves concentrate on strategic partnerships with rolling stock OEMs and capacity expansion into high-growth corridor markets.
Among European specialists, Getzner Werkstoffe GmbH and Pandrol exemplify contrasting strategic positions. The former occupies a formulation-focused niche anchored in Austrian material science capabilities. The latter represents integrated system architecture through its captive fastening portfolio. Nantong Zhentong Railway Parts Co. Ltd. anchors the Asia-Pacific manufacturing tier, exemplifying cost-efficient capacity serving infrastructure buildouts across China's high-speed network expansion and India's freight corridor development.
| Leading Market Players |
|---|
| Pandrol |
| Tiflex Ltd. |
| Jekay International Track Pvt. Ltd. |
| Anyang General International Co. Ltd. |
| Getzner Werkstoffe GmbH |
| Nantong Zhentong Railway Parts Co. Ltd. |
| Molytex A/S |
| Iron Horse Engineering Company |
| Delkor Rail |
| Others |
Value Network & Pricing Analysis
North American Class I railroads and European infrastructure managers concentrate procurement authority for rail pads, locking suppliers into lifecycle-contracting models where polyurethane formulations command premiums based on fatigue-performance guarantees rather than unit cost. This buyer consolidation compresses margin structures for compounders lacking backward integration into isocyanate feedstocks or REACH-compliant certification infrastructure.
Pricing Analysis
Warranty-bundled service contracts now dominate heavy-haul procurement, with extended-fatigue guarantees replacing transactional spot purchasing. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified microcellular polyurethane from conventional rubber and unvalidated imports. Cost compression in rubber formulations is intensifying because Indian and Brazilian freight corridors prioritize replacement labor economics over material longevity. Freight operators in emerging markets exhibit highest price sensitivity; alpine corridor managers in Switzerland and Austria show lowest sensitivity due to tunnel access cost premiums.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke fulfillment patterns for rail pad compounders. Manufacturing gravity centers on Germany's chemical corridor, China's Yangtze River Delta, and India's Gujarat industrial belt. Formulation chemistry draws from petrochemical isocyanates, post-industrial rubber reprocessing streams, and flame-retardant additive packages. Single-source vulnerability concentrates in MDI precursor supply from limited European and Asian chemical producers. Distribution runs through OEM-integrated fastening system providers and direct rail operator contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rail pads market is transitioning from scheduled replacement to predictive maintenance architectures, with microcellular polyurethane formulations displacing conventional elastomers in heavy-haul applications. This technology shift rewards compounders with materials science capabilities and digital integration partnerships.
For Market Incumbents: Hedge against isocyanate price volatility through captive supply agreements or backward integration into chemical precursors. Consolidate certification infrastructure to defend against REACH compliance bottlenecks filtering subscale competitors from EU tenders. Prioritize sensor-embedded pad development to capture condition-based maintenance contract growth. For New Entrants and Emerging Players: Regional maintenance contractors serving fragmented Latin American and Southeast Asian freight networks represent an underserved buyer archetype with limited incumbent penetration. Target cost-optimized rubber formulations for these price-sensitive corridors. Pursue white-label supply partnerships with established fastening system OEMs to bypass multi-jurisdiction certification barriers. For Investors and Strategic Acquirers: The window for entry favors specialized polyurethane formulators with verified recycled-content supply chains and ISO-compliant carbon footprint documentation. Focus on compounders positioned for EU Green Deal procurement preferences. Monitor ECHA regulatory enforcement intensity as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Feedstocks | Captive MDI supply insulates margins from petrochemical volatility affecting European compounders. |
| Recycled-Content Supply Chain Certification | Post-industrial rubber reprocessing capabilities unlock EU Green Deal tender preferences in Germany and France. |
| Digital Twin Integration Partnership | Data-sharing agreements with rolling stock OEMs enable predictive replacement scheduling for alpine operators. |
| Multi-Jurisdiction Certification Expansion | Simultaneous KBA, REACH, and GB/T compliance broadens addressable market across EU, China, and India corridors. |
| Light Rail Low-Profile Pad Development | Reduced-height composite formulations capture urban electrification projects in Paris and Lyon transit authorities. |
Research Methodology
Document review covered customs and trade data, railway infrastructure procurement databases, and chemical industry association reports, complemented by interviews with track maintenance directors, OEM procurement leads, elastomer compounder R&D heads, and regulatory compliance officers. Secondary validation drew from KBA certification filings, ECHA REACH registrations, Chinese GB/T standards documentation, and infrastructure investment disclosures from national rail operators. Bottom-up segment sizing and top-down market triangulation reconciled volume estimates across material grades and regional demand clusters.
Output modeling produced segment-level value and volume trajectories across the projection horizon, with analytical frameworks incorporating material type, application intensity, end-user procurement channel, and installation context dimensions. CAGRs were derived from infrastructure investment pipeline analysis, replacement cycle compression rates, and regulatory adoption curve modeling. Forecast inputs included axle load escalation schedules, tunnel access cost inflation, and interoperability mandate implementation timelines.
Revisions become necessary when isocyanate supply disruptions, regulatory enforcement intensity shifts, or infrastructure investment pauses materialize outside modeled scenarios. Forecasts reflect assumptions regarding REACH compliance cost trajectories, recycled-content verification standardization, and predictive maintenance platform adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Track Fittings Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Railway Fishplate Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Global Railcar Leasing Market
Railway Transportation
Rail Fasteners Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Global Railway Wiring Harness Market