
 Railway Sliding Bearing Market | 2026-2036
Railway Sliding Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Sliding Bearing Market Analytics
Composite material substitution in rail bearing assemblies is reconfiguring supplier technical requirements across OEM and aftermarket channels. AB SKF leverages its European R&D footprint to anchor development of self-lubricating polymer-metal hybrids for high-speed applications. Schaeffler AG sustains manufacturing scale across German and Chinese plants, competing on volume for freight car retrofits. NTN Corporation specializes in tapered sleeve designs that dominate Japanese Shinkansen maintenance cycles.
Railway sliding bearings are cylindrical or flanged components, typically manufactured from bronze-brass alloys or PTFE-impregnated composites, that permit axial or radial motion between rotating and stationary rail subsystems while managing friction coefficients below 0.15 under load. Sleeve bearings fabricated from sintered bronze-polyamide composites serve primary suspension linkages where vibration damping and maintenance intervals determine lifecycle economics. Roller bearings occupy the mature locomotive traction motor segment where steel cage designs face margin compression from remanufacturing competition. Composite bearings represent the fastest-expanding material category as railway operators in Europe and Asia prioritize weight reduction and extended service periods.
The EU F-Gas Regulation and REACH chemical standards constrain traditional lubricant formulations, redirecting R&D investment toward dry-running bearing surfaces that eliminate sealed grease systems. China's SAMR enforces GB standards for rail component fatigue testing that filter out uncertified suppliers from CRRC procurement lists. India's BIS certification mandates for rolling stock subsystems create comparable barriers for imported bearing assemblies on Dedicated Freight Corridor contracts. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving national content rules redistribute competitive advantage between regional manufacturing bases and global component suppliers.
Market Dynamics
Composite material substitution is collapsing the traditional bronze-brass supply base as railway operators prioritize dry-running bearings that eliminate sealed grease systems and extend maintenance intervals.
Growth Catalysts
- EU F-Gas Regulation:The framework bans fluorinated greenhouse gases in rail applications, forcing operators toward PTFE-impregnated composites that function without lubricant reservoirs.
- High-speed rail expansion:China's CRRC and India's Dedicated Freight Corridor are expanding procurement of bronze-polyamide composite bearings for primary suspension linkages.
- Dual carbon goals:China's MEE enforcement of carbon intensity targets accelerates material substitution toward lightweight polymer-metal hybrids in bogie assemblies.
Market Restraints
- Copper alloy cost volatility:Bronze feedstock prices fluctuate with mining output constraints in Chile and Peru, compressing margins for traditional bearing fabricators.
- Supplier concentration:Certified composite formulation expertise concentrates among European and Japanese specialty compounders, creating single-source risk for tier-two rail OEMs.
- REACH chemical compliance:ECHA restrictions on certain polymer additives extend R&D timelines for new composite bearing certifications.
Strategic Opportunities
- Indian aftermarket expansion:The Dedicated Freight Corridor's rolling stock fleet creates demand for tapered sleeve bearing retrofits in maintenance depots across Haryana and Gujarat.
- Digital condition monitoring integration:Sensor-embedded composite bearings that transmit wear data via IoT networks open recurring revenue streams for component suppliers.
- Remanufacturing regulatory tailwind:EU circular economy directives incentivize bearing refurbishment programs that extend service life beyond OEM specifications.
Industry Challenges
- Polymer tribology expertise gap:Rail maintenance crews trained on steel bearing lubrication protocols require reskilling for dry-running composite inspection and replacement.
- Multi-standard certification burden:Suppliers must simultaneously satisfy China's GB standards, India's BIS mandates, and EU EN specifications for cross-border contracts.
- Legacy fleet incompatibility:Axle housing designs from Soviet-era rolling stock resist retrofit with modern composite sleeve geometries without machining modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Sliding Bearing Market |
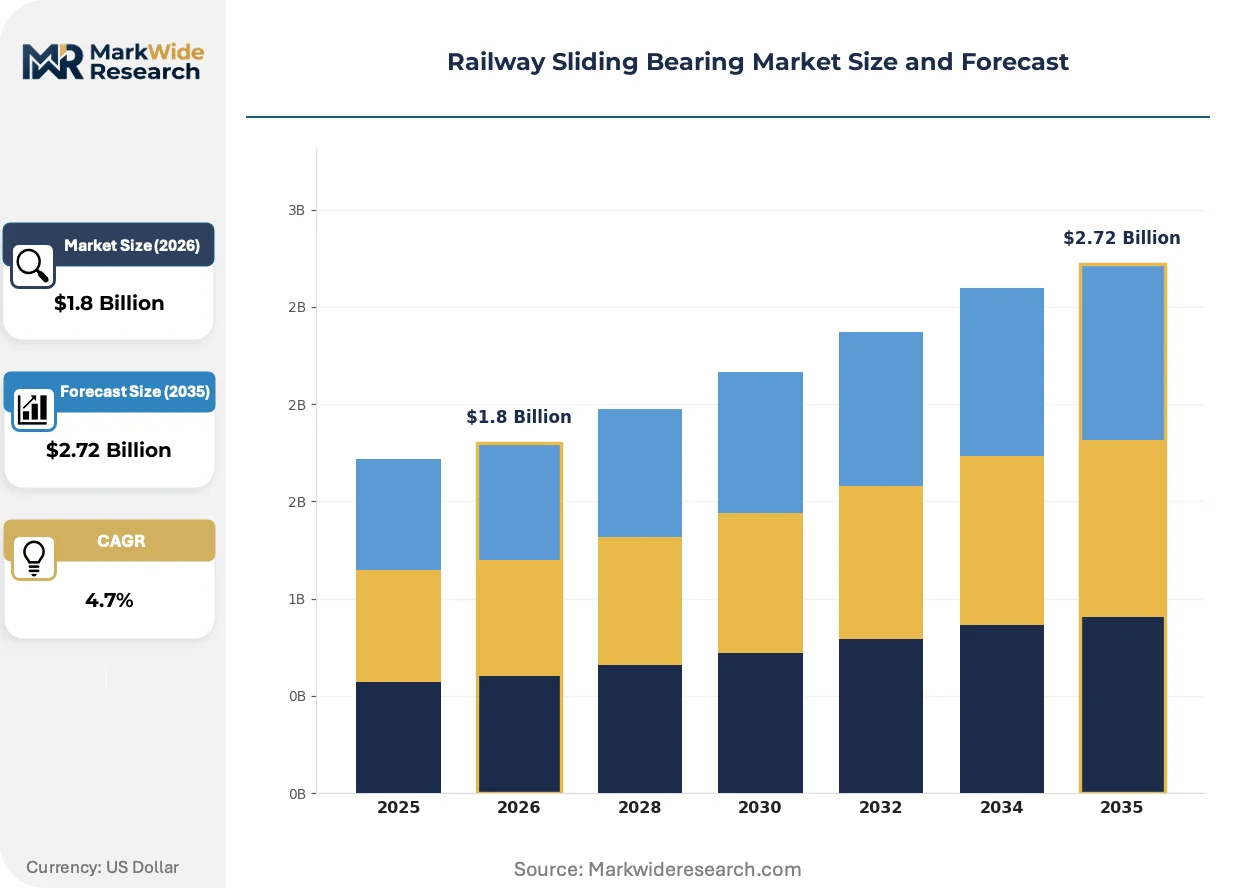
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sleeve Bearings, Ball Bearings, Roller Bearings, Composite Bearings Material: Brass, Steel, Polyamide, Bronze Application: Locomotives, Freight Cars, Passenger Coaches, High-Speed Trains End User: Railway Operators, OEMs, Maintenance Providers, Infrastructure Companies |
| Companies Covered | AB SKF, Schaeffler AG, NTN Corporation, The Timken Company, GGB, NSK Ltd., RBC Bearings Incorporated, MinebeaMitsumi Inc., Fujian Longxi Bearing Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Sliding Bearing Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to reconfigure bearing procurement specifications across high-speed and freight rail segments.
Sintered bronze-polyamide composites are collapsing the performance gap between traditional lubricated metal bearings and fully polymer designs. CRRC's high-speed train procurement teams specify these materials for primary suspension linkages where vibration damping and 800,000-kilometer maintenance intervals determine lifecycle economics. The technology is collapsing aftermarket service revenue models built around scheduled lubrication and premature replacement cycles.
REACH chemical standards constrain traditional PTFE formulations containing perfluorinated compounds, redirecting formulation R&D toward bio-based polyamide matrices and graphene-enhanced lubricant layers. ECHA's 2023 restriction proposals on long-chain fluorinated substances force compounders to requalify bearing grades for EU rail certification. German and French OEMs respond fastest, locking in supply agreements with compliant material suppliers before certification bottlenecks widen.
Condition-based maintenance contracts are displacing time-based replacement schedules for critical bearing positions. Indian Railways and European freight operators unbundle component supply from installation service, awarding separate contracts to bearing fabricators and regional maintenance providers. This pattern concentrates most visibly in China's CRRC supply chain, where state rail procurement mandates separate pricing for hardware, installation, and predictive monitoring subscriptions.
Railway Sliding Bearing Market Segmentation
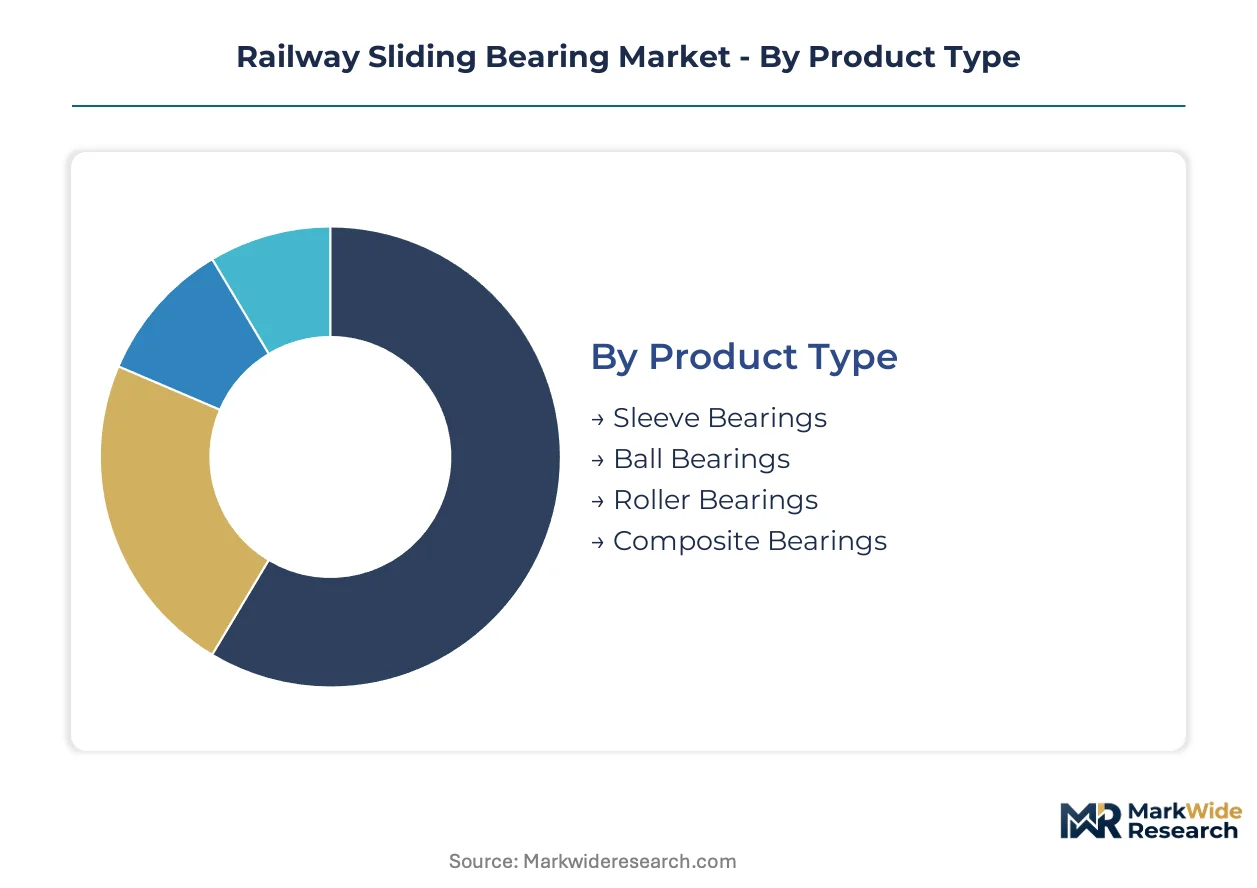
Railway sliding bearing procurement splits across four distinct dimensions, each carrying different margin profiles and certification burdens. Material composition and application environment determine replacement cycles, with high-speed applications demanding accelerated inspection protocols compared to freight rolling stock.
Product Type:
Sleeve bearings turn over slowest in depot maintenance cycles while composite designs refresh fastest as operators validate dry-running performance in revenue service.
- Sleeve Bearings:Cylindrical bronze or steel shells that support radial loads in axle boxes and suspension linkages. Indian Railways' Dedicated Freight Corridor specifies these for primary suspension positions where 800,000-kilometer service intervals reduce lifecycle costs.
- Composite Bearings:Sintered bronze-polyamide or PTFE-impregnated polymer-metal hybrids engineered for dry-running operation. China's CRRC procurement mandates these for high-speed bogie assemblies to satisfy dual carbon goals and eliminate grease maintenance.
- Ball Bearings:Steel raceway designs with cage-retained rolling elements for precision positioning in auxiliary systems.
- Roller Bearings:Cylindrical or tapered configurations dominating locomotive traction motor mounts where load distribution requirements exceed sleeve capacity.
Sleeve bearings anchor the volume base while composite bearings gain share at the steepest rate.
Material:
Cost tiering separates commodity metals from engineered polymers, with feedstock volatility compressing margins differently across each bracket.
- Bronze:Copper-tin alloys sintered with lubricant reservoirs form the traditional bearing substrate. German KBA certification requirements and EU F-Gas Regulation compliance pressures are redirecting procurement toward polymer alternatives in European fleets.
- Polyamide:Engineering thermoplastics reinforced with glass fiber or PTFE for wear resistance in dry-running applications. India's BIS certification framework now includes polyamide composite grades for Dedicated Freight Corridor rolling stock.
- Brass:Copper-zinc alloys serving lower-load auxiliary positions where material cost sensitivity outweighs weight reduction targets.
- Steel:Through-hardened or case-hardened alloys for roller bearing raceways and heavy-load sleeve configurations in legacy freight car retrofits.
Bronze retains the installed base while polyamide climbs the fastest as operators prioritize maintenance interval extension.
Application:
Operating speed and duty cycle intensity create divergent technical specifications across rolling stock categories.
- High-Speed Trains:Bogie and suspension systems subject to continuous dynamic loading above 250 km/h. China's SAMR enforces GB fatigue testing standards that filter bearing suppliers for CRRC procurement lists.
- Freight Cars:Axle boxes and coupler systems with intermittent heavy loading and extended stationary periods. Indian Railways' infrastructure expansion concentrates demand in Haryana and Gujarat maintenance depots.
- Locomotives:Traction motor mounts and auxiliary drives requiring steel roller bearings for torque transmission capacity.
- Passenger Coaches:HVAC blower mounts and door mechanism positions with moderate load requirements and standardized replacement protocols.
Freight cars anchor the volume base while high-speed trains gain share at the steepest rate.
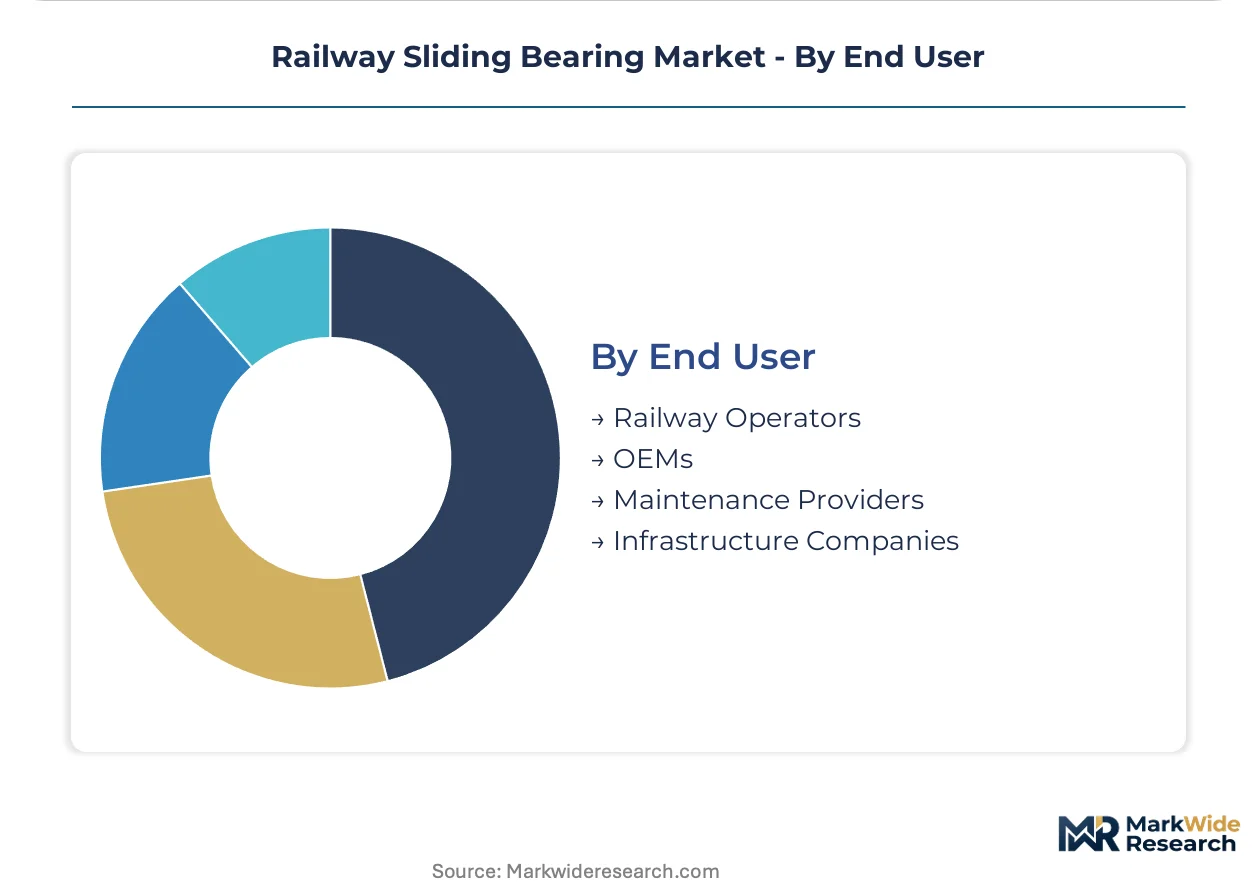
End User:
Procurement authority fragmentation splits between fleet owners, original manufacturers, and outsourced maintenance networks.
- Railway Operators:State-owned or privatized fleet managers specifying bearings for new procurement and scheduled replacement. European operators unbundle component supply from installation under condition-based maintenance contracts.
- OEMs:Rolling stock manufacturers integrating bearings into bogie and suspension system assemblies. CRRC's vertical supply chain control extends to certified bearing supplier qualification.
- Maintenance Providers:Regional depot operators executing retrofits and unplanned replacements. India's Dedicated Freight Corridor creation spurs aftermarket service provider expansion.
- Infrastructure Companies:Track and station system contractors sourcing bearings for switch mechanisms and platform equipment with non-rolling stock specifications.
OEMs anchor the volume base while maintenance providers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Railway sliding bearing procurement concentrates among state-owned fleet operators and vertically integrated rolling stock manufacturers. Chinese and Indian infrastructure expansion programs anchor volume demand. European regulatory chemistry constraints redirect material specifications toward dry-running composites.
China
CRRC procurement teams specify bronze-polyamide composite bearings for high-speed bogie assemblies across expanding intercity networks. SAMR enforces GB fatigue testing standards that filter uncertified suppliers from state rail procurement lists. Manufacturing clusters in Changzhou and Qingdao concentrate composite bearing fabrication capacity for domestic and export contracts.
Germany
KBA certification requirements and EU F-Gas Regulation compliance pressures redirect Deutsche Bahn procurement toward self-lubricating polymer-metal hybrids. ECHA restrictions on fluorinated compounds accelerate formulation R&D among specialty compounders. Industrial concentrations in Stuttgart and Munich anchor SKF and Schaeffler development facilities for high-speed applications.
India
Dedicated Freight Corridor expansion generates demand for tapered sleeve bearing retrofits across Haryana and Gujarat maintenance depots. BIS certification mandates for rolling stock subsystems create barriers for imported assemblies on infrastructure contracts. Manufacturing activity clusters in Faridabad and Ahmedabad serve regional aftermarket service networks.
Japan
Shinkansen maintenance cycles sustain demand for precision-tapered sleeve designs in traction motor and suspension applications. METI standards for rail component durability influence procurement specifications across JR Group operators. Industrial concentrations in Osaka and Nagoya anchor NTN Corporation specialty bearing production for domestic high-speed fleets.
United States
Freight railroads prioritize bearing refurbishment programs under circular economy directives that extend service life beyond OEM specifications. FRA safety standards govern axle bearing inspection protocols for Class I operators. Maintenance provider networks concentrate in Chicago and Omaha to serve transcontinental freight corridors.
Railway Sliding Bearing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement structures. Consolidation concentrates among European and Japanese fabricators with certified composite formulation expertise, while regional specialists serve aftermarket retrofit demand. Three archetypes dominate: vertically integrated rolling stock suppliers, specialty compounders with material science IP, and maintenance-focused service providers. Competitive moves center on geographic expansion into Indian and Southeast Asian infrastructure markets and technology licensing agreements for dry-running composite formulations.
Among European-based fabricators, AB SKF and Schaeffler AG exemplify the integrated development archetype with cross-border manufacturing footprints. NTN Corporation occupies a position within the precision-specialist tier serving high-speed maintenance cycles. These three names represent distinct competitive positioning vectors: SKF anchors polymer-metal hybrid R&D, Schaeffler sustains volume scale across German and Chinese plants, and NTN dominates Japanese Shinkansen technical specifications.
| Leading Market Players |
|---|
| AB SKF |
| Schaeffler AG |
| NTN Corporation |
| The Timken Company |
| GGB |
| NSK Ltd. |
| RBC Bearings Incorporated |
| MinebeaMitsumi Inc. |
| Fujian Longxi Bearing Group |
| Others |
Value Network & Pricing Analysis
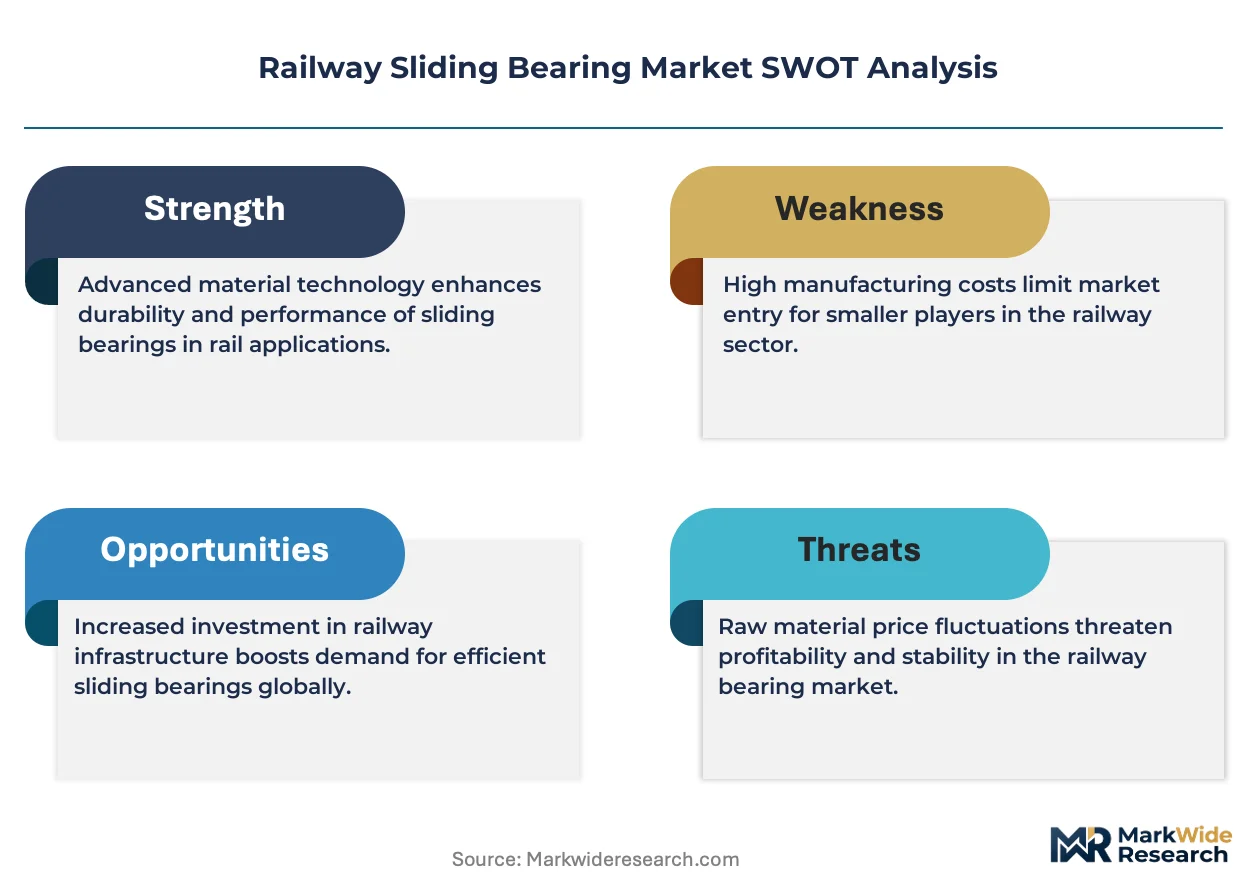
Chilean and Peruvian mining output constraints for copper-tin feedstock anchor margin compression for bronze-bearing fabricators, while polymer-metal hybrid suppliers capture value pools through certified dry-running formulations that command premium positioning in CRRC and Deutsche Bahn procurement channels.
Pricing Analysis
Cost-plus contracts indexed to LME copper and tin benchmarks dominate procurement for bronze alloy bearings, with three-tier pricing structure across premium, standard, and economy levels separating certified composite grades from commodity metal sleeves. Price differentiation hinges on GB standard certification tier and volume scale, with pricing pressure intensifying as Indian BIS mandates accelerate domestic fabrication capacity. Freight car operators exhibit highest price sensitivity, while high-speed rail OEMs prioritize maintenance interval extension over unit cost.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk planning for tier-one bearing fabricators. Manufacturing concentrates in Changzhou, Stuttgart, and Osaka, with sintered bronze feedstock, polyamide resin, and PTFE lubricant layers as critical inputs. Single-source vulnerability concentrates among European and Japanese specialty compounders holding REACH-compliant formulation IP. Distribution runs through vertically integrated OEM supply chains and regional maintenance depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a platform-economics inflection where condition-based maintenance contracts and IoT-embedded bearing subscriptions reconfigure hardware monetization toward recurring service revenue models.
For Market Incumbents: Entrench polymer-metal hybrid formulation leadership through backward integration into certified polyamide compounding, defending against specialty compounder disintermediation. Lock in multi-year supply agreements with CRRC and Deutsche Bahn before REACH requalification bottlenecks widen. Prioritize GB standard pre-certification for dual carbon procurement mandates. For New Entrants and Emerging Players: Indian Dedicated Freight Corridor maintenance depots in Haryana and Gujarat represent the most penetrable entry point, with tapered sleeve retrofit demand outpacing certified supplier capacity. Target aftermarket service provider partnerships as the fastest go-to-market channel, bypassing OEM qualification timelines through regional depot relationships. For Investors and Strategic Acquirers: Capital is best deployed toward specialty compounders with REACH-compliant dry-running formulations and established rail certification portfolios. Long-term viability rests on material science IP moats rather than volume scale. Watch for SAMR enforcement patterns on GB standard fatigue testing as the signal for supplier list consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide Compounding | Captures margin pools from specialty chemical suppliers while securing REACH-compliant formulation control for EU rail contracts. |
| GB Standard Pre-Certification Investment | Filters competitors from CRRC procurement lists as SAMR tightens fatigue testing enforcement for high-speed bogie assemblies. |
| Condition-Based Maintenance Platform Launch | Converts hardware sales into recurring revenue through sensor-embedded bearings transmitting wear data via IoT networks. |
| Regional Manufacturing Footprint in India | Positions suppliers to serve Dedicated Freight Corridor demand while satisfying BIS certification mandates for domestic content. |
| Joint Venture with Specialty Compounders | Accelerates dry-running composite R&D timelines while distributing REACH compliance investment across shared development costs. |
Research Methodology
The analysis maps sleeve bearing, composite bearing, ball bearing, and roller bearing sub-sectors, each validated through procurement managers at state rail operators, OEM platform engineers, aftermarket depot supervisors, and specialty compounder R&D directors. Primary interview findings triangulate against customs trade data for copper alloy imports, CRRC supplier disclosure filings, ECHA restriction proposal documentation, and BIS certification registry records. Bottom-up volume estimates from maintenance cycle frequencies reconcile with top-down market sizing from rolling stock procurement databases.
Assumptions hold EU F-Gas Regulation enforcement trajectory, China's dual carbon goal implementation pace, and Indian Dedicated Freight Corridor completion schedule as fixed baseline conditions across the projection horizon. Segmentation dimensions modeled include product type, material composition, application environment, and end-user procurement authority. CAGRs derive from regression analysis of historical procurement volumes against fleet expansion schedules and replacement cycle intensification. Industry-specific inputs incorporate SAMR GB standard adoption curves and REACH chemical restriction timelines.
Macroeconomic conditions sit as an overlay; deviation in copper-tin commodity price volatility, rail infrastructure investment fiscal commitments, or carbon-border adjustment mechanism implementation would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Railroad Tank Car Market
Railway Transportation
Railcar Spill Containment Materials Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Point Machine Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Global Railcar Leasing Market
Railway Transportation
Rail Pads Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
Digital Railway Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Brazil Rail Freight Transport Market