
 Freight Transport Market | 2026-2036
Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Freight Transport Market Intelligence
Modular service bundling is expanding across freight transport procurement, as shippers seek integrated road-rail-air combinations rather than discrete mode contracts. DHL Global Forwarding leverages its intermodal platform to anchor transcontinental contract logistics. Kuehne + Nagel sustains refrigerated cargo dominance through specialized pharmaceutical cold-chain infrastructure. Maersk Logistics competes by extending ocean-to-door service architectures that compress transit variability.
Freight transport encompasses the commercial movement of goods via multiple conveyance modes, governed by payload limits, container specifications such as ISO 668 dimensional standards, and route optimization algorithms that minimize fuel consumption per ton-mile. Its primary purpose is connecting production nodes with consumption markets through time-definite delivery commitments. Road freight leads service-type revenue pools due to last-mile indispensability, while air cargo commands premium margins for temperature-sensitive and high-velocity shipments. Intermodal freight forwarding represents the fastest-growing structural segment, as shippers prioritize carbon-adjusted transit cost over single-mode economics.
The International Maritime Organization enforces carbon intensity indicators that mandate vessel efficiency improvements, compelling fleet operators to retrofit or retire older tonnage. The EPA's heavy-duty vehicle emissions standards in the United States and the EU Green Deal's Fit for 55 framework collectively reshape powertrain procurement across road and water modes. China's MIIT implements dual carbon goals that accelerate electric heavy-truck deployment through GB standard compliance mandates. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance cost asymmetries will determine which operators retain cross-border route profitability.
Market Dynamics
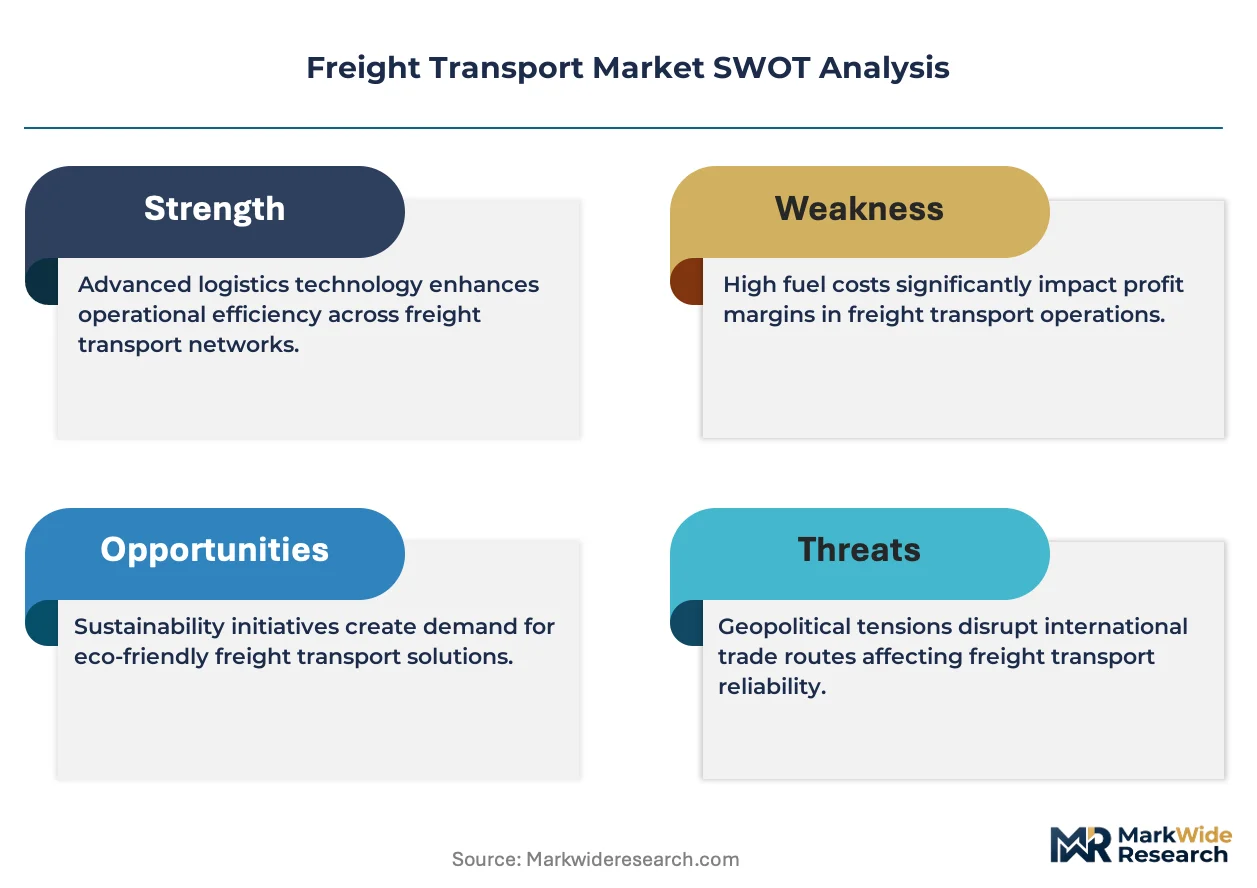
Carbon intensity regulations from the International Maritime Organization and the EU Green Deal's Fit for 55 framework are forcing fleet operators to reconfigure powertrain procurement and retire inefficient tonnage ahead of schedule.
Growth Catalysts
- E-commerce fulfillment density:Parcel volume concentration in urban corridors is pulling dedicated intermodal corridors into service. Mumbai and São Paulo logistics clusters exemplify this infrastructure response.
- EU Green Deal Fit for 55:The framework mandates heavy-duty vehicle emission cuts that accelerate electric truck deployment across European road freight networks.
- Refrigerated pharmaceutical corridors:Cold-chain infrastructure investment is expanding temperature-controlled container fleets to serve vaccine and biologics distribution.
Market Restraints
- Marine fuel cost volatility:Low-sulfur fuel oil and LNG price swings compress margins for ocean freight operators committed to IMO 2020 compliance.
- Semiconductor supply concentration:Taiwan and South Korea fabrication dominance creates vulnerability in telematics and autonomous navigation system procurement.
- Battery energy density limits:Lithium-ion cell gravimetric performance caps electric heavy-truck range below diesel equivalents for long-haul routes.
Strategic Opportunities
- India manufacturing logistics:PLI scheme incentives and dedicated freight corridors create greenfield contract logistics demand around Gujarat and Tamil Nadu industrial zones.
- Rail-road bimodal terminals:Automated gantry crane systems and digital waybilling convergence enable seamless container handoff without chassis repositioning.
- China MIIT dual carbon mandates:GB standard compliance deadlines for NEV commercial vehicles generate fleet replacement cycles favoring battery-electric and hydrogen fuel cell powertrains.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems resist API connectivity with blockchain-based cargo documentation platforms.
- Driver qualification gaps:Commercial license holders with hazardous materials and refrigerated cargo certifications remain scarce relative to expanding pharmaceutical logistics demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Transport Market |
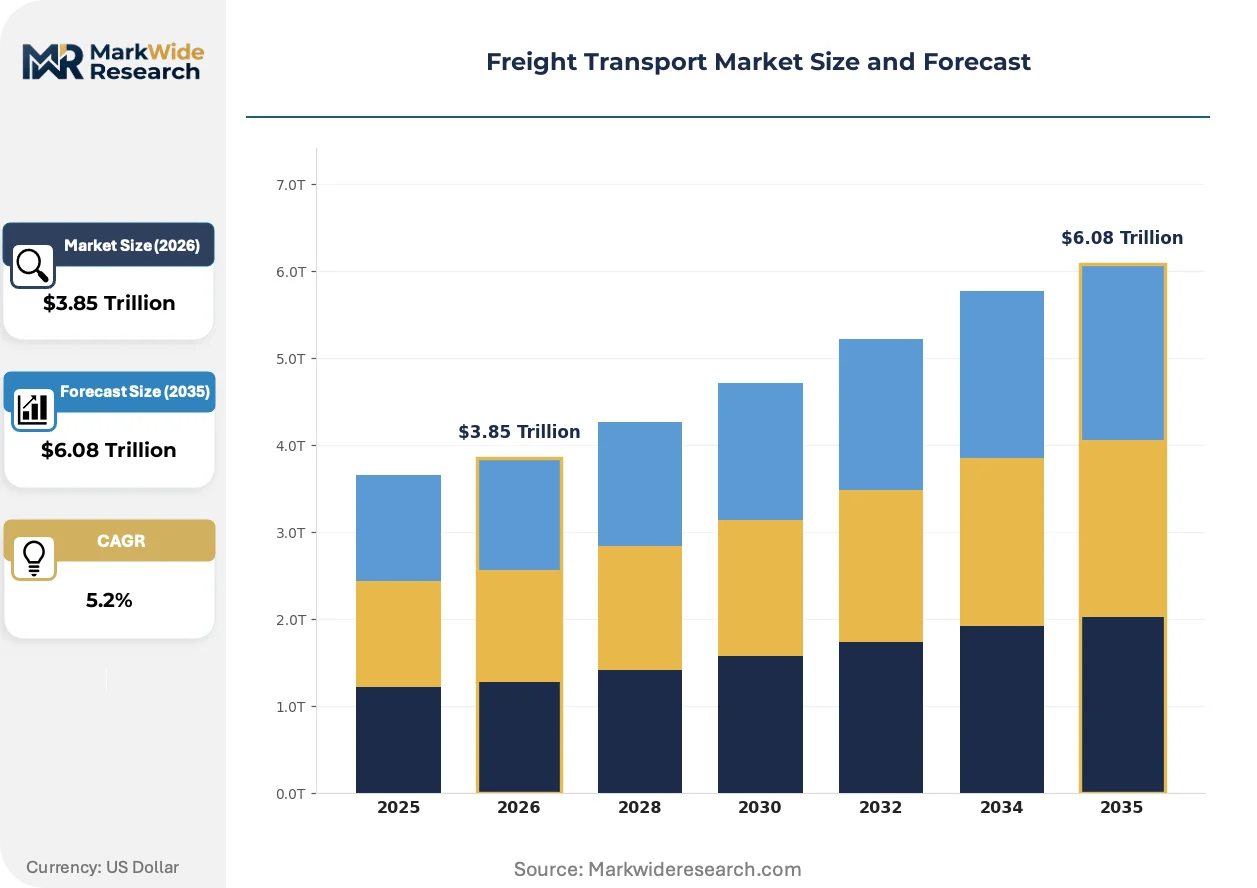
| Market Size in 2026 | $3.85 Trillion |
| Market Size in 2035 | $6.08 Trillion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Mode: Road, Rail, Air, Water Cargo Type: Containerized, Bulk, Refrigerated, Breakbulk Service Type: Full Truck Load, Less Than Truck Load, Intermodal, Freight Forwarding End User: Manufacturers, Retailers, Distributors, E-commerce |
| Companies Covered | Kuehne + Nagel, DHL Global Forwarding, DSV, DB Schenker, Expeditors International, C.H. Robinson, Nippon Express, Sinotrans, Maersk Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Transport Market Strategic Shifts & Innovations
Digital freight matching platforms and autonomous yard operations are compressing dispatch latency and eliminating manual gate processing at distribution centers.
Blockchain-enabled smart bills of lading are decentralizing document custody from carrier hierarchies to distributed ledger networks. Pharmaceutical shippers and automotive parts distributors are adopting these instruments fastest. This architecture is decentralizing trade finance access for mid-tier freight forwarders previously excluded from letter-of-credit facilities.
The EPA's heavy-duty vehicle emissions standards are tightening NOx and particulate limits for 2027 model-year engines. Engine manufacturers face redesign cycles compressing development timelines. California's CARB waivers are accelerating zero-emission truck deployment ahead of federal compliance dates.
Shippers are unbundling long-term dedicated fleet contracts in favor of spot-market capacity aggregation through digital brokerage platforms. Food and beverage distributors lead this migration from committed routing to dynamic procurement. Germany and the Netherlands show the highest platform penetration among European road freight buyers.
Freight Transport Market Segmentation
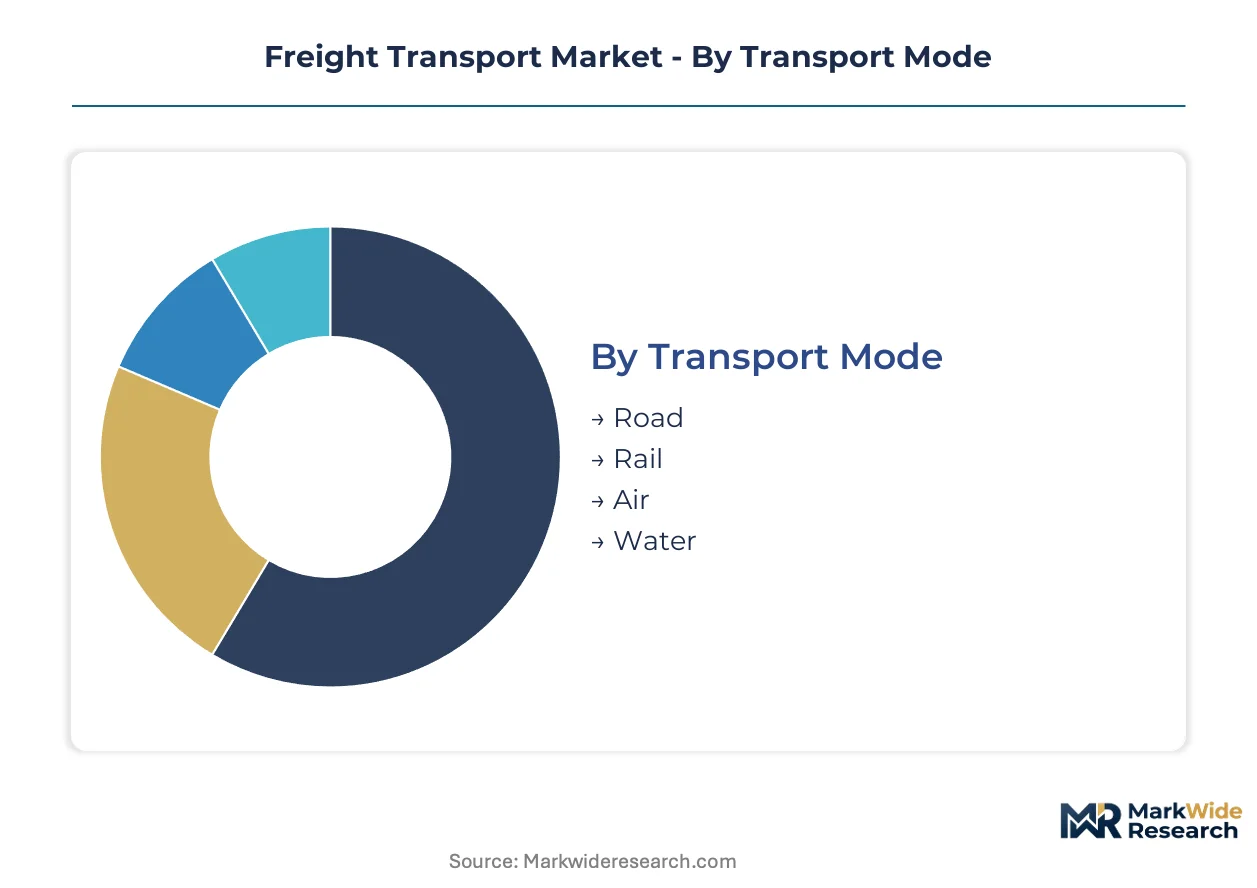
Transport mode selection determines regulatory exposure and capital intensity for freight operators. Cargo characteristics dictate container specifications and temperature compliance requirements. Service type configurations shape contract structures and margin profiles across customer segments.
Transport Mode:
ISO 668 container certification applies universally across rail and water modes, while road freight faces EPA heavy-duty emissions standards and EU Green Deal Fit for 55 mandates. Air cargo operators navigate FAA hazardous materials protocols alongside IATA temperature-controlled carriage regulations.
- Road:Diesel and electric powertrains move palletized and containerized loads across dedicated highway corridors and urban last-mile networks. Demand concentrates in India where dedicated freight corridors and PLI scheme manufacturing expansion accelerate fleet modernization around Gujarat industrial zones.
- Water:Deep-sea and coastal vessels handle bulk commodities and ISO containers under IMO carbon intensity indicator mandates. Fleet operators in Rotterdam and Singapore retrofit tonnage to comply with low-sulfur fuel oil requirements and energy efficiency design indices.
- Rail:Intermodal flatcars and hopper wagons connect inland terminals to maritime ports under national safety authority oversight. Automated gantry crane systems at Hamburg and Chicago bimodal facilities compress container handoff times without chassis repositioning.
- Air:Wide-body freighters and belly-hold capacity transport high-velocity pharmaceuticals and electronics under temperature-controlled protocols. Cold-chain infrastructure investment expands reefer container fleets serving vaccine distribution through Dubai and Brussels cargo hubs.
Road sits at the top of the volume ranking, with intermodal rail-water combinations climbing the fastest.
Cargo Type:
Container specifications and handling protocols segment procurement priorities across shipper categories. Refrigerated cargo commands specialized fleet investment and driver certification requirements.
- Containerized:Standardized box units conform to ISO 668 dimensional standards for seamless intermodal transfer. E-commerce fulfillment density in Mumbai and São Paulo logistics clusters pulls dedicated intermodal corridors into service.
- Refrigerated:Temperature-controlled units maintain pharmaceutical and perishable product integrity across extended transit lanes. Biologics distribution expansion drives reefer fleet investment around cold-chain infrastructure in Germany and the Netherlands.
- Bulk:Unpacked commodities including grain, ore, and petroleum move via specialized hopper and tank configurations. Water mode dominance in dry bulk reflects fuel efficiency per ton-mile for low-value, high-volume commodities.
- Breakbulk:Individual heavy-lift items and non-containerized project cargo require customized stowage and lifting equipment. Industrial manufacturing clusters in Tamil Nadu generate specialized breakbulk demand for capital equipment imports.
Containerized cargo dominates current volume, with refrigerated segments expanding most quickly on pharmaceutical logistics demand.
Service Type:
Contract structures range from dedicated fleet commitments to dynamic spot-market procurement through digital brokerage platforms.
- Intermodal:Integrated road-rail-air combinations optimize carbon-adjusted transit cost through single-contract procurement. DHL Global Forwarding anchors transcontinental contract logistics through platform-based service bundling.
- Full Truck Load:Dedicated vehicle capacity serves high-volume shippers with predictable routing requirements. Food and beverage distributors migrate from committed routing to dynamic procurement through digital freight matching platforms.
- Freight Forwarding:Third-party coordination of multi-leg movements consolidates documentation and customs clearance. Blockchain-enabled smart bills of lading decentralize custody from carrier hierarchies to distributed ledger networks.
- Less Than Truck Load:Consolidated partial shipments aggregate demand from multiple shippers through hub-and-spoke terminal networks. Urban parcel volume concentration drives dedicated corridor investment in last-mile delivery optimization.
Full Truck Load retains the largest volume position, while intermodal service configurations gain share fastest on carbon accounting priorities.
End User:
Customer procurement sophistication varies from integrated supply chain control to outsourced logistics management.
- E-commerce:Parcel networks demand time-definite delivery commitments with real-time visibility infrastructure. Amazon and Alibaba fulfillment networks intensify demand for automated yard operations and digital waybilling convergence.
- Manufacturers:Production nodes require inbound component synchronization and outbound finished goods distribution. China's MIIT dual carbon mandates accelerate electric heavy-truck deployment through GB standard compliance deadlines.
- Retailers:Seasonal demand fluctuations drive flexible capacity procurement and cross-docking terminal utilization. Germany and the Netherlands show highest platform penetration among European road freight buyers.
- Distributors:Inventory positioning across regional warehouses balances service levels against carrying cost optimization. Pharmaceutical shippers adopt blockchain documentation fastest for temperature-controlled cargo custody verification.
Manufacturers represent the largest current volume segment, with e-commerce end users climbing fastest on fulfillment network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern freight transport industry traces its commercial lineage to 19th-century rail expansion across the United Kingdom and Germany, where standardized gauge networks first enabled scheduled cargo movement between industrial centers. Containerization protocols developed at American ports in the mid-20th century subsequently unified global shipping standards. Today, regulatory divergence and infrastructure investment patterns create distinct operational environments across national markets.
United States
E-commerce fulfillment density and automotive manufacturing reshoring drive intermodal demand along Chicago-Memphis and Los Angeles-Dallas corridors. EPA heavy-duty vehicle emissions standards and California CARB waivers accelerate zero-emission truck deployment ahead of federal compliance dates. The Inland Empire logistics cluster east of Los Angeles anchors trans-Pacific container distribution through automated yard operations.
Germany
Automotive component supply chains and chemical exports sustain high-value freight volumes through Rhine-Ruhr and Bavarian industrial zones. EU Green Deal Fit for 55 mandates heavy-duty emission cuts that reshape fleet procurement across European road networks. Hamburg's bimodal terminals deploy automated gantry crane systems that compress container handoff times without chassis repositioning.
China
Manufacturing expansion along the Yangtze River Delta and Pearl River Delta generates massive container throughput for export-oriented production. MIIT dual carbon goals and GB standard compliance mandates accelerate electric heavy-truck deployment through NEV commercial vehicle deadlines. Ningbo-Zhoushan port infrastructure handles bulk commodity flows under national safety authority oversight.
India
PLI scheme incentives and electronics manufacturing expansion create greenfield logistics demand around Gujarat and Tamil Nadu industrial corridors. Dedicated freight corridor investment and infrastructure spending accelerate fleet modernization under national logistics policy frameworks. The Mumbai logistics cluster exemplifies urban parcel concentration pulling intermodal infrastructure into service.
Singapore
Trans-shipment hub status and refined petroleum product trade sustain maritime freight services across Southeast Asian trade lanes. IMO carbon intensity indicators compel fleet operators to retrofit tonnage for low-sulfur fuel oil compliance and energy efficiency design indices. The Tuas mega-port development integrates automated terminal operations with digital waybilling convergence.
Freight Transport Market Key Industry Players
Premium-margin players sit above commodity-margin players across service integration depth, with full-service logistics platforms commanding superior contract terms over single-mode operators. The vendor base stratifies into three tiers: integrated intermodal providers, specialized cold-chain operators, and digital freight matching platforms. Strategic archetypes include asset-heavy ocean carriers extending door-to-door service architectures, asset-light forwarders consolidating multi-leg documentation, and technology-native brokers aggregating spot-market capacity. Competitive moves concentrate on M&A-driven network expansion and proprietary digital platform development that compresses dispatch latency.
Among European-integrated logistics providers, Kuehne + Nagel and DHL Global Forwarding occupy positions representing specialized pharmaceutical infrastructure and transcontinental intermodal platforms respectively. Maersk Logistics exemplifies the ocean-to-door service archetype through extended maritime-land integration. These entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| DHL Global Forwarding |
| DSV |
| DB Schenker |
| Expeditors International |
| C.H. Robinson |
| Nippon Express |
| Sinotrans |
| Maersk Logistics |
| Others |
Cost & Logistics Intelligence
EU Green Deal Fit for 55 mandates gate qualified supply and premium-tier pricing access, as carriers with compliant fleets command rate premiums while non-compliant operators face margin compression from carbon offset purchases and retrofit capital calls. Carbon-adjusted transit cost calculations now separate contract winners from commodity bidders across European road freight procurement.
Pricing Analysis
Contract-based long-term offtake with carbon-indexed rate adjustment clauses dominates large-shipper procurement, while spot-market digital brokerage platforms serve fragmented demand. Price differentiation rests on ISO 14001 environmental certification tier and dedicated fleet availability guarantees. Cost compression in standard-tier road freight is intensifying because electric truck capital premiums amortize slowly against diesel operating economics. Food and beverage distributors exhibit highest price sensitivity, while pharmaceutical shippers prioritize temperature integrity over rate minimization.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's MIIT dual carbon goals are reshaping sourcing, compelling multinational logistics providers to localize fleet procurement and maintenance infrastructure. Manufacturing concentration draws from China, Germany, and the United States for commercial vehicle powertrains, lithium-ion battery cells, and telematics control units. Single-source vulnerability in Taiwan and South Korea semiconductor fabrication feeds from concentrated wafer supply. Distribution runs through hub-and-spoke terminal networks with automated gantry crane systems at bimodal facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freight transport functions as a regulatory compounder, with IMO carbon intensity indicators and EPA heavy-duty emissions standards creating sustained compliance-driven fleet replacement demand across maritime and road modes.
For Market Incumbents: Deploy intermodal platform consolidation to anchor transcontinental contract logistics against digital freight matching disruption. DHL Global Forwarding and Maersk Logistics exemplify this architecture. Acquire refrigerated cargo specialists to defend pharmaceutical cold-chain margins as biologics distribution expands. Retrofit legacy fleet management systems for API connectivity with blockchain documentation platforms to neutralize telematics integration complexity threats. For New Entrants and Emerging Players: Enter via India manufacturing logistics corridors around Gujarat and Tamil Nadu industrial zones, where PLI scheme incentives and dedicated freight corridor investment create greenfield contract demand with limited incumbent saturation. Target automated yard operations and digital waybilling convergence as the most penetrable technology layer, given legacy system resistance at established terminals. Pursue asset-light freight forwarding with blockchain-enabled smart bills of lading to bypass capital-intensive fleet ownership. For Investors and Strategic Acquirers: Roll-up economics work for specialized cold-chain operators because pharmaceutical logistics demand outpaces certified driver and refrigerated container supply, creating scarcity premiums for qualified assets. Five-to-ten year viability favors asset-heavy ocean carriers extending door-to-door service architectures over pure digital brokers exposed to spot-market volatility. Monitor EU Green Deal enforcement consistency as the inflection signal—accelerated emission standard tightening would compress non-compliant fleet valuations and create distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Intermodal Platform Integration | DHL Global Forwarding leverages combined road-rail-air contracts to reduce shipper procurement fragmentation. |
| Electric Fleet Deployment | China's MIIT GB standard compliance deadlines accelerate battery-electric heavy-truck replacement cycles. |
| Cold-Chain Infrastructure Expansion | Kuehne + Nagel sustains pharmaceutical margins through specialized reefer container fleet investment. |
| Blockchain Documentation Adoption | Smart bills of lading decentralize custody from carrier hierarchies to distributed ledger networks. |
| Automated Terminal Operations | Hamburg and Chicago bimodal facilities deploy gantry crane systems to eliminate chassis repositioning delays. |
Research Approach
Direct dialogue with fleet operations directors, logistics procurement managers at manufacturing and retail enterprises, intermodal terminal engineers, and regulatory compliance officers grounded qualitative findings. Secondary validation drew from IMO vessel efficiency filings, EPA heavy-duty vehicle certification records, EU ETS transaction registries, and national freight corridor investment disclosures. Bottom-up fleet capacity modeling and top-down trade flow analysis enabled cross-verification.
Bottom-up modeling aggregated operator-level capacity deployment across transport modes, while top-down analysis tracked trade lane volume concentration and infrastructure investment patterns. Segmentation dimensions included transport mode, cargo type, service configuration, and end-user procurement sophistication. CAGRs derived from regression-adjusted deployment trajectories, with carbon intensity compliance cost curves and e-commerce fulfillment density indices as freight-specific forecast inputs across the projection horizon.
Inputs from vessel efficiency filings and national logistics policy frameworks were available through the study window; gaps in real-time telematics penetration rates and autonomous vehicle deployment timelines introduce uncertainty bands around fleet modernization speed assumptions. Forecasts reflect documented regulatory milestone schedules and infrastructure investment commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Refrigerated Road Transportation Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
China Road Freight Transport Market