
 Railway Couplers Market | 2026-2036
Railway Couplers Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Couplers Market Analysis
Modular coupler-dampener bundling is consolidating buyer choice around integrated train connection systems rather than standalone components. Dellner Couplers AB leverages its Nordic engineering base to dominate premium automatic coupler niches for high-speed corridors. Wabtec Corp. sustains North American freight market presence through captive manufacturing scale and backward integration into cast steel foundry operations. Jiangsu Tedrail Industrial Co. Ltd. anchors Asia-Pacific supply with cost-competitive manual and semi-automatic variants for regional rail networks.
A railway coupler is a mechanical device engineered to join rolling stock, typically forged from high-grade steel or aluminum alloys with tensile ratings exceeding 1,000 kN, enabling safe transmission of longitudinal forces during train movement and separation. Automatic coupler variants command the steepest technology premium due to integrated pneumatic and electrical interconnection capabilities that eliminate manual linking procedures. Steel material grades retain volume leadership across freight applications where impact loading dominates duty cycles, while aluminum and composite formulations gain share in passenger segments governed by weight-reduction mandates. Freight trains represent the most mature application category with replacement-driven demand patterns, whereas maintenance-of-way specialty couplers exhibit the fastest growth trajectory tied to mechanized track renewal programs.
The US Federal Railroad Administration enforces coupler strength and fatigue testing protocols under 49 CFR Part 232, while the EU F-Gas Regulation and MDR framework shape material composition and supplier certification requirements for European deployments. China's NMPA-aligned rail equipment approval system and GB standards mandate domestic testing for imported coupler assemblies, creating structured market access barriers. India's BIS certification and PLI scheme for rail component manufacturing are redirecting procurement toward local fabrication capacity. Stakeholders must monitor evolving interoperability standards between automatic coupler generations as Europe's Shift2Rail initiative and North American precision scheduled railroading investments redefine connection system specifications.
Market Dynamics
Fleet modernization mandates across freight corridors are compressing replacement cycles for mechanical coupler assemblies, while interoperability requirements for high-speed passenger networks are accelerating automatic coupler procurement beyond historical norms.
Growth Catalysts
- Crashworthiness mandates:The US Federal Railroad Administration's 49 CFR Part 232 protocols compel Class I railroads to upgrade legacy coupler assemblies, creating sustained replacement demand across North American freight networks.
- High-speed rail expansion:China's GB standards for automatic coupler certification are driving procurement volumes as provincial rail authorities extend intercity corridors.
- Track renewal mechanization:Maintenance-of-way equipment manufacturers are specifying specialty coupler variants for automated tamping and ballast regulation fleets.
Market Restraints
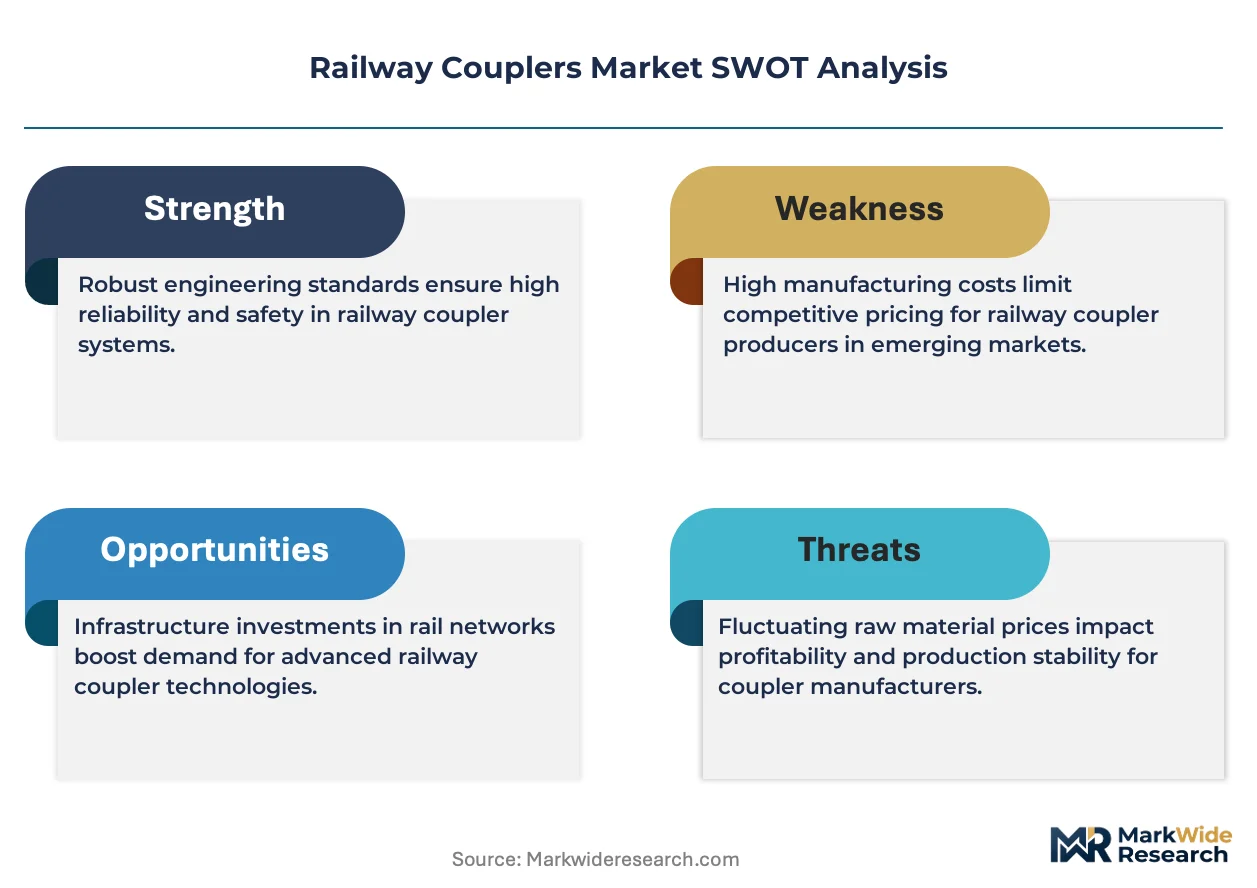
- Foundry capacity concentration:Premium-grade steel casting for knuckle couplers depends on a limited supplier base concentrated in industrial clusters, exposing buyers to input volatility.
- Certification timeline friction:India's BIS rail component approval process extends qualification cycles for imported assemblies, delaying deployment schedules.
- Aluminum substitution ceiling:Impact loading requirements in heavy-haul freight applications constrain material substitution away from forged steel grades.
Strategic Opportunities
- Digital twin integration:Coupler OEMs combining sensor-embedded hardware with predictive maintenance platforms can capture recurring revenue streams from condition-based service contracts.
- Shift2Rail standardization:Europe's interoperability initiative creates specification windows for next-generation automatic coupler designs compatible with cross-border rolling stock.
- India PLI localization:The country's production-linked incentive scheme for rail components redirects procurement toward domestic fabrication capacity, opening partnership avenues for technology licensors.
Industry Challenges
- Intergenerational compatibility:Mixed-fleet operators face integration complexity when coupling legacy manual designs with automatic variants on shared consists.
- Metallurgical expertise scarcity:Specialized fatigue testing and fracture mechanics capabilities required for coupler certification are concentrated among a narrow technical workforce pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Couplers Market |
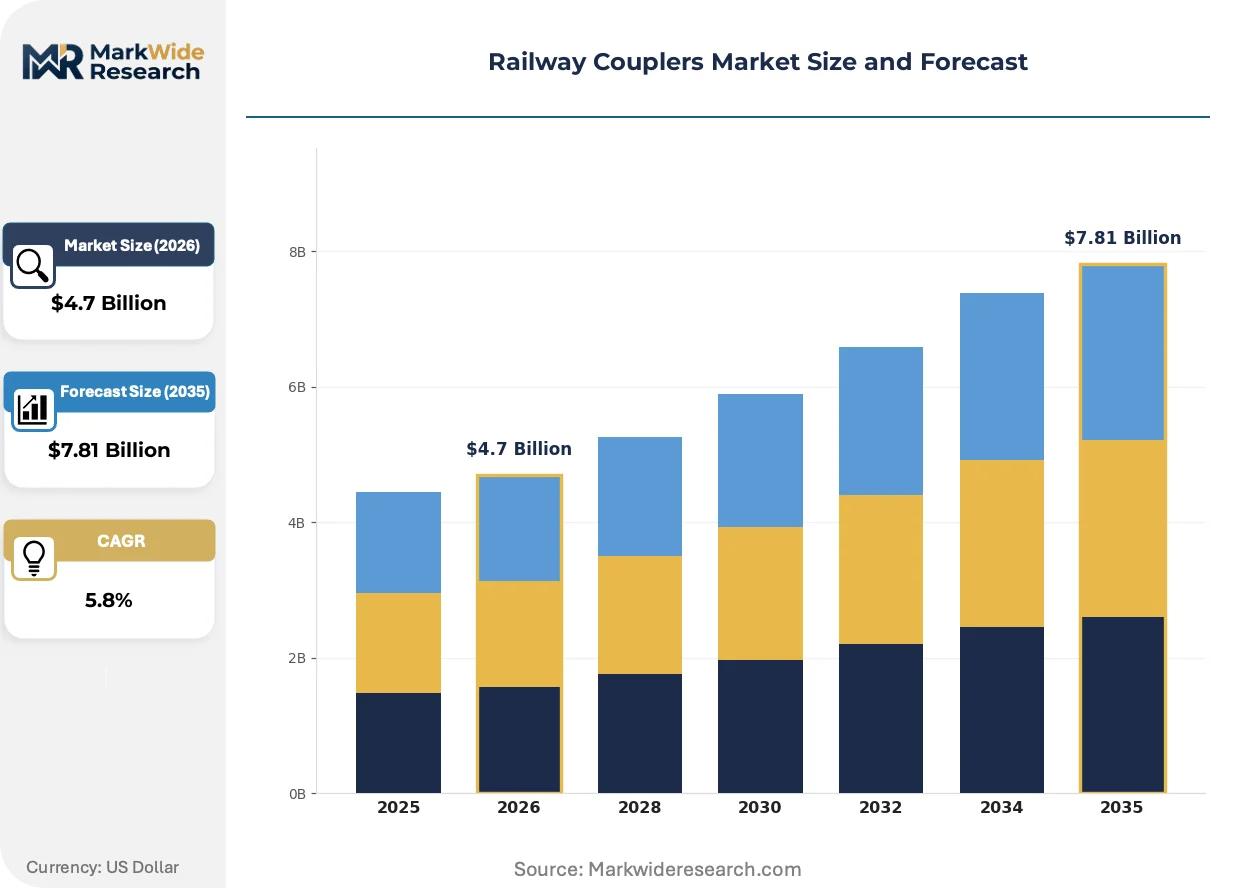
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
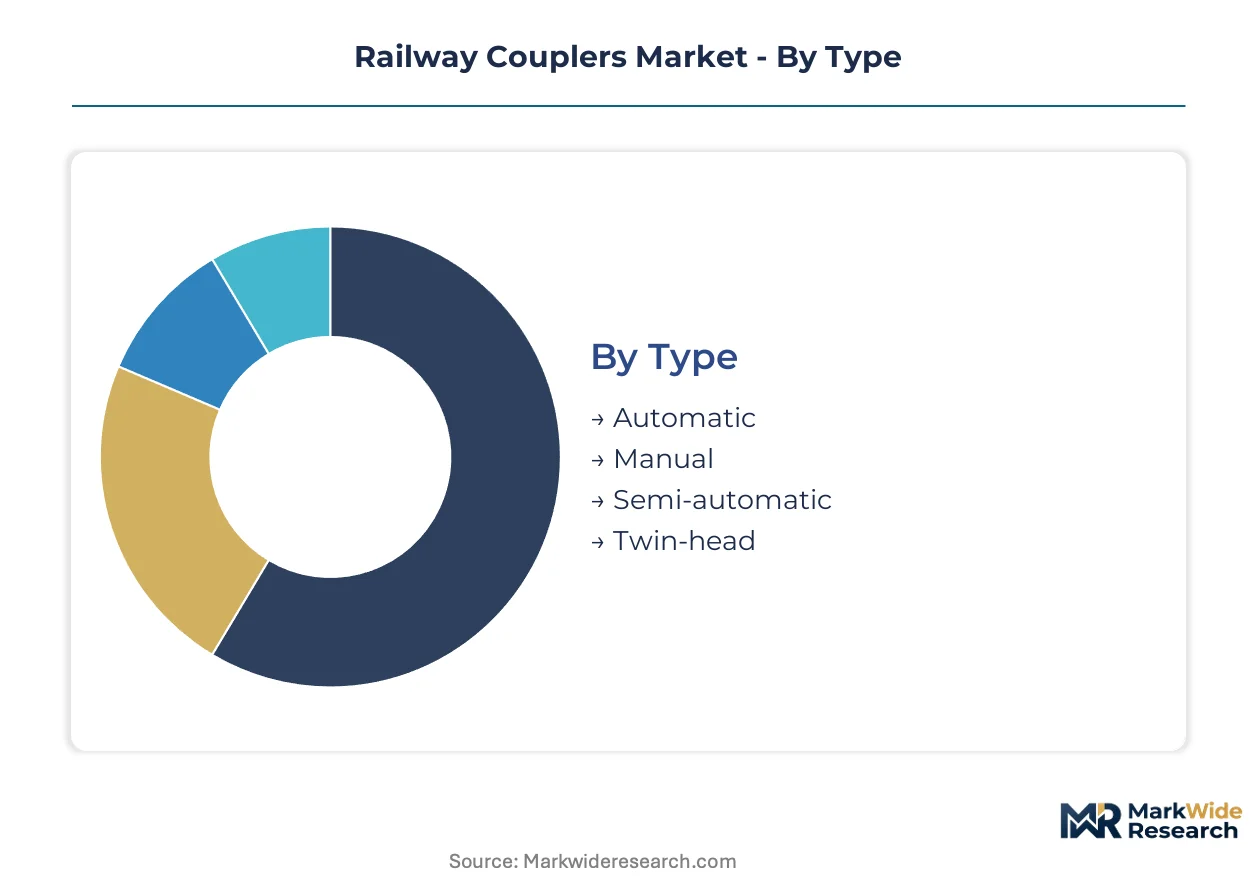
| Segmentation | Type: Automatic, Manual, Semi-automatic, Twin-head Material: Steel, Aluminum, Composite, Brass Application: Freight Trains, Passenger Trains, Maintenance-of-Way, Specialty End User: Railroad Operators, OEMs, Maintenance Providers, Logistics Companies |
| Companies Covered | Nippon Steel Corp., Irwin Car and Equipment, Dellner Couplers AB, Knorr Bremse AG, Jiangsu Tedrail Industrial Co. Ltd., Voith GmbH and Co. KGaA, Amsted Rail Company Inc., Titagarh Rail Systems Ltd., Wabtec Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Couplers Market Emerging Trajectories
Connection system architecture is fragmenting from monolithic mechanical designs toward configurable subassemblies, enabling buyers to specify dampener, pneumatic, and electrical modules independently rather than accepting bundled configurations.
Composite-reinforced coupler housings are modularizing freight car connection systems. Heavy-haul operators in Australian iron ore corridors are piloting hybrid steel-composite knuckles to reduce unsprung mass while maintaining impact ratings. This material convergence is modularizing procurement patterns, allowing railcar lessors to specify performance tiers without accepting full subsystem bundles.
Europe's F-Gas Regulation is reshaping pneumatic coupler specifications by restricting fluorinated gas use in braking interconnection systems. Manufacturers are reformulating seal compounds and valve architectures to maintain pressure integrity under compressed air alternatives. Passenger operators in Germany and France are accelerating qualification timelines for compliant variants ahead of enforcement deadlines.
Specification authority is migrating from mechanical engineering departments to procurement centers with total-cost-of-ownership models. North American freight railroads are unbundling coupler-dampener assemblies from rolling stock purchase agreements, sourcing connection systems through separate competitive tenders. This purchasing decentralization is most pronounced among precision-scheduled railroading adopters seeking component-level lifecycle accountability.
Railway Couplers Market Segmentation
Railway coupler procurement patterns diverge sharply across technical specifications and end-use contexts. Certification requirements from FRA, ECHA, and China's NMPA create tiered market access barriers that reshape competitive positioning within each segment cluster.
Type:
FRA's 49 CFR Part 232 crashworthiness protocols impose divergent testing burdens across coupler automation levels, with automatic variants facing the most exhaustive qualification cycles.
- Automatic:Integrated pneumatic and electrical interconnection systems eliminate manual linking procedures entirely. China's GB standards for high-speed rail corridors drive procurement concentration here, with provincial rail authorities mandating these variants for new intercity extensions.
- Manual:Forged steel knuckle designs predominate in legacy freight fleets where replacement cycles follow FRA-mandated fatigue testing schedules. North American Class I railroads source these through unbundled tenders separate from rolling stock agreements.
- Semi-automatic:Hybrid configurations bridge mechanical reliability with partial automation for regional networks.
- Twin-head:Dual-connection architectures serve specialized maintenance-of-way equipment requiring rapid consist reconfiguration.
Automatic sits at the top of the volume ranking, with Twin-head climbing the fastest.
Material:
Raw material selection traces directly to duty cycle intensity, with impact loading specifications from heavy-haul operators constraining substitution away from forged grades.
- Steel:High-grade forged alloys with tensile ratings exceeding 1,000 kN dominate freight applications. Australian iron ore corridors specify these for extreme impact loading, though foundry capacity concentration in industrial clusters exposes buyers to input volatility.
- Aluminum:Weight-reduction mandates from European passenger operators accelerate procurement here. Germany's F-Gas Regulation compliance timelines pressure rapid qualification of lightweight variants for high-speed rolling stock.
- Composite:Hybrid steel-composite knuckles reduce unsprung mass while maintaining impact ratings.
- Brass:Corrosion-resistant formulations serve coastal and humid climate deployments.
Steel commands the largest installed base, while Composite gains share fastest among material substitutions.
Application:
End-use context determines specification authority, with precision-scheduled railroading adopters driving purchasing decentralization toward component-level lifecycle accountability.
- Freight Trains:Replacement-driven demand patterns characterize this mature category. US Class I operators unbundle coupler-dampener assemblies from rolling stock purchase agreements, sourcing through separate competitive tenders.
- Passenger Trains:Automatic coupler procurement accelerates beyond historical norms as interoperability requirements tighten for high-speed networks. China's NMPA-aligned approval system mandates domestic testing for imported assemblies.
- Maintenance-of-Way:Mechanized track renewal programs specify specialty variants for automated tamping and ballast regulation fleets.
- Specialty:Custom configurations serve museum railways and industrial switching operations.
Freight Trains maintains volume leadership, with Maintenance-of-Way expanding most quickly.
End User:
Procurement authority migration from mechanical engineering departments to total-cost-of-ownership centers reshapes vendor engagement strategies across buyer categories.
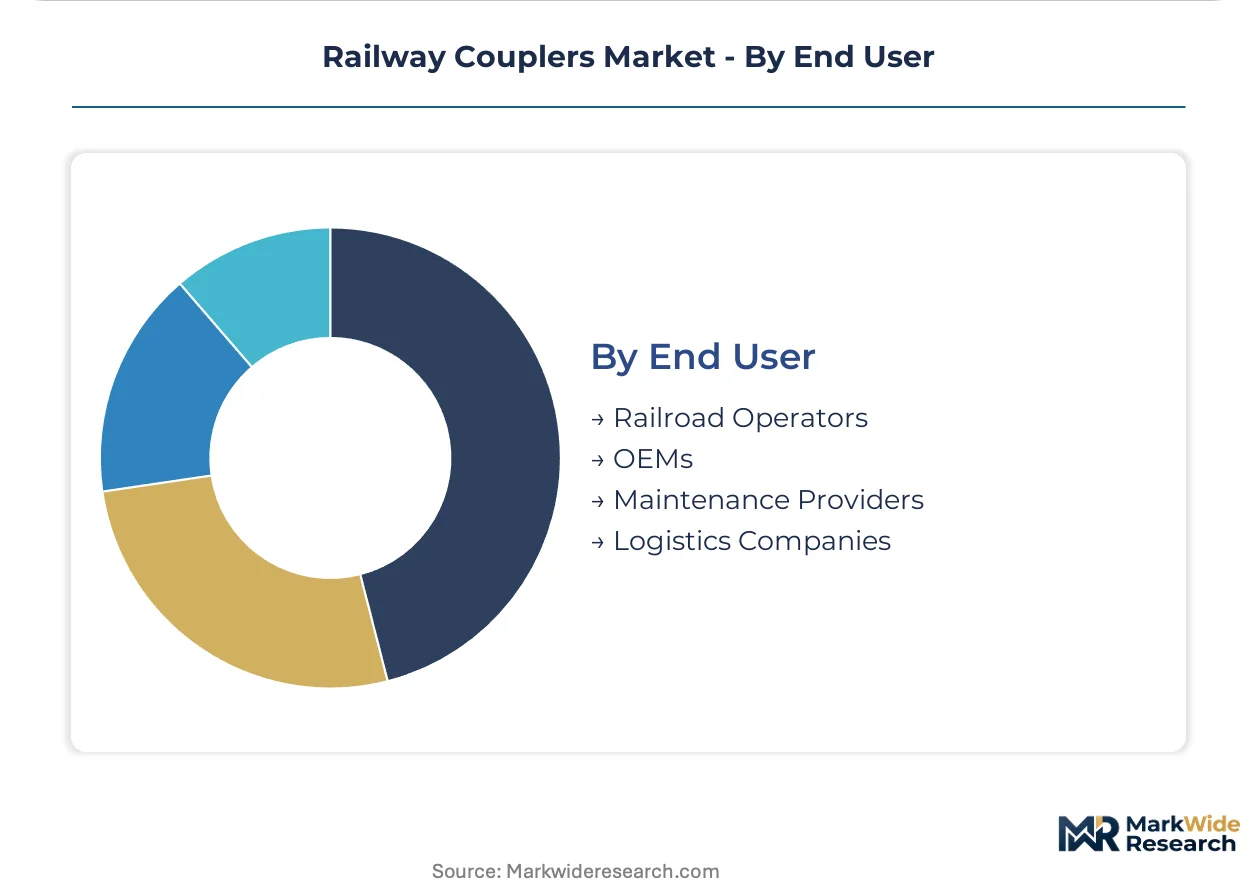
- Railroad Operators:Fleet modernization mandates compress replacement cycles for mechanical assemblies. India's BIS certification and PLI scheme redirect procurement toward domestic fabrication capacity.
- OEMs:Rolling stock manufacturers specify integrated connection systems for new-build contracts. Europe's Shift2Rail interoperability initiative creates specification windows for next-generation automatic designs.
- Maintenance Providers:Condition-based service contracts favor sensor-embedded hardware with predictive maintenance platforms.
- Logistics Companies:Railcar lessors specify performance tiers through modular procurement patterns without accepting full subsystem bundles.
Railroad Operators anchor procurement volume, with Maintenance Providers gaining influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Railway coupler manufacturing traces its industrial lineage to 19th-century American foundries that standardized the knuckle coupler design still dominant in freight applications today. Production scale later migrated toward German and Swedish engineering centers as automatic coupling systems emerged for passenger rail. Contemporary demand clusters reflect this bifurcated heritage: forged steel capacity concentrates in legacy industrial zones while precision automatic coupler assembly gravitates toward high-speed rail corridors.
United States
Class I railroads operate under FRA-mandated replacement schedules that compress procurement cycles for mechanical coupler assemblies. The 49 CFR Part 232 crashworthiness protocols require fatigue testing documentation that favors established domestic foundry relationships. Pittsburgh's Monongahela Valley retains concentrated steel casting capacity serving Norfolk Southern and CSX fleet modernization programs.
Germany
Deutsche Bahn's interoperability requirements for cross-border rolling stock accelerate automatic coupler qualification timelines. The EU F-Gas Regulation restricts seal compounds in pneumatic interconnection systems, forcing reformulation of valve architectures. Siemens Mobility anchors supplier relationships from its Erlangen engineering campus near Nuremberg's rail component cluster.
China
Provincial rail authorities extend intercity high-speed corridors under GB standards mandating automatic coupler certification for new rolling stock. The NMPA-aligned approval system requires domestic testing for imported assemblies, creating structured market access barriers. CRRC Qingdao Sifang and subsidiary suppliers dominate procurement from Shandong Peninsula manufacturing zones.
India
Indian Railways' fleet expansion and Dedicated Freight Corridor projects drive procurement volume for semi-automatic variants. The BIS certification process and PLI scheme for rail components redirect sourcing toward domestic fabrication capacity. Titagarh Rail Systems and emerging suppliers cluster around West Bengal's Kharagpur-Howrah industrial corridor.
Japan
Shinkansen network maintenance sustains demand for precision automatic couplers with integrated electrical interconnection. METI's industrial standards and JIS certification requirements shape supplier qualification protocols. Kawasaki Heavy Industries and Nippon Steel maintain engineering relationships from Kobe-Osaka manufacturing centers.
Railway Couplers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and metallurgical complexity. The vendor base stratifies into three concentration levels: integrated rolling stock suppliers with captive coupler divisions, specialized connection system manufacturers with foundry backward integration, and regional fabricators serving replacement markets. Three archetypes dominate competitive positioning: European precision engineering specialists, North American freight-focused foundry operators, and Asia-Pacific cost-optimized volume producers. Dominant competitive moves include capacity consolidation through foundry acquisition and technology licensing partnerships for automatic coupler intellectual property.
Among European precision specialists, Dellner Couplers AB and Voith GmbH occupy positions defined by automatic coupler engineering heritage and high-speed rail certification depth. Wabtec Corp. exemplifies the North American archetype through its Pittsburgh-rooted foundry integration and Class I railroad supply relationships. Jiangsu Tedrail Industrial Co. Ltd. anchors the Asia-Pacific tier with cost-competitive manual and semi-automatic variants for regional network procurement. These three representations illustrate how geographic origin and metallurgical capability stratify competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Nippon Steel Corp. |
| Irwin Car and Equipment |
| Dellner Couplers AB |
| Knorr Bremse AG |
| Jiangsu Tedrail Industrial Co. Ltd. |
| Voith GmbH and Co. KGaA |
| Amsted Rail Company Inc. |
| Titagarh Rail Systems Ltd. |
| Wabtec Corp. |
| Others |
Supply Flow & Price Mechanics
Composite-reinforced knuckle production methods are displacing conventional steel-forging economics while concentrating premium-grade foundry capacity in legacy industrial clusters. This dual shift simultaneously elevates cost barriers for automatic coupler variants and compresses margins for commodity manual assemblies as buyers unbundle component procurement.
Pricing Analysis
Three-tier pricing structure across automatic, semi-automatic, and manual levels dominates procurement contracts. Price differentiation rests on FRA certification grade and foundry backward integration depth. Cost compression in manual variants is intensifying because North American Class I railroads are decoupling coupler-dampener assemblies from rolling stock agreements. Railroad operators exhibit highest price sensitivity, whereas high-speed rail authorities in China accept steep technology premiums for GB-compliant automatic systems.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from CRRC and Siemens Mobility, while aftermarket distributors serve replacement cycles for Class I operators. Geographic supply concentrates in the United States, Germany, and China. Raw material flows draw from high-grade steel foundries, aluminum extrusion facilities, and composite resin suppliers. Single-source vulnerability pervades knuckle forging capacity concentrated in Pittsburgh's Monongahela Valley and Germany's Ruhr industrial zone. Distribution runs through captive supplier networks for new-build contracts and independent distributors for maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's PLI-subsidized fabrication costs and China's NMPA testing requirements that delay imported assembly deployment.
For Market Incumbents: Extend foundry backward integration into captive steel casting operations to defend against aluminum substitution threats in passenger segments. Deepen certification investment in FRA and ECHA compliance to maintain tiered access barriers against emerging Asian competitors. Lock long-term supply agreements with Australian iron ore corridor operators before hybrid composite variants achieve scale qualification. For New Entrants and Emerging Players: Sensor-embedded predictive maintenance platforms offer a technology-first wedge into the maintenance provider segment where condition-based service contracts are displacing transactional hardware sales. Target India's Dedicated Freight Corridor procurement where BIS certification redirects demand toward domestic fabrication partnerships. Pursue technology licensing arrangements with established European automatic coupler IP holders rather than greenfield certification investment. For Investors and Strategic Acquirers: Roll-up economics work for regional foundry operators with FRA-approved testing facilities because certification timeline friction creates defensive moats against imported competition. Acquisition targets should exhibit captive steel casting capacity and established Class I railroad relationships. Watch for India's PLI scheme disbursement acceleration as an inflection signal for domestic procurement redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Backward Integration | Captive steel casting insulates against input volatility from concentrated supplier clusters. |
| Digital Twin Platform Development | Sensor-embedded hardware enables recurring revenue from predictive maintenance contracts with Class I operators. |
| Shift2Rail Standardization Investment | Next-generation automatic coupler designs capture cross-border rolling stock specifications in Germany and France. |
| India PLI Localization Partnership | Domestic fabrication qualification redirects procurement from Titagarh Rail Systems and emerging West Bengal suppliers. |
| Composite Material Qualification | Hybrid steel-composite knuckles reduce unsprung mass for Australian heavy-haul iron ore corridors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged rolling stock procurement directors at Deutsche Bahn and Norfolk Southern, foundry operations managers in Pittsburgh and Kobe, and maintenance-of-way equipment specification leads at Harsco Rail. Secondary validation drew from FRA 49 CFR Part 232 enforcement records, EU F-Gas Regulation compliance disclosures, China's GB standards documentation, and SEC filings from Wabtec and Knorr Bremse. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches distributed volume and value across automatic, semi-automatic, manual, and twin-head coupler types, further stratified by steel, aluminum, composite, and brass material grades. Application-level modeling incorporated freight train replacement cycles, passenger train interoperability mandates, and maintenance-of-way mechanization trajectories. CAGRs derived from regression analysis against rail infrastructure investment flows and fleet modernization program announcements.
The model holds under stable regulatory certification timelines and continued high-speed rail expansion; deviation in foundry capacity constraints or aluminum alloy supply disruptions would shift volume projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Connectors Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Autonomous Train Technology Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Railcar Spill Containment Materials Market
Railway Transportation
Train Transformer Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Overhead Catenary System Market