
 Poland Household Electric Grills Market | 2026-2036
Poland Household Electric Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Household Electric Grills Market Analytics
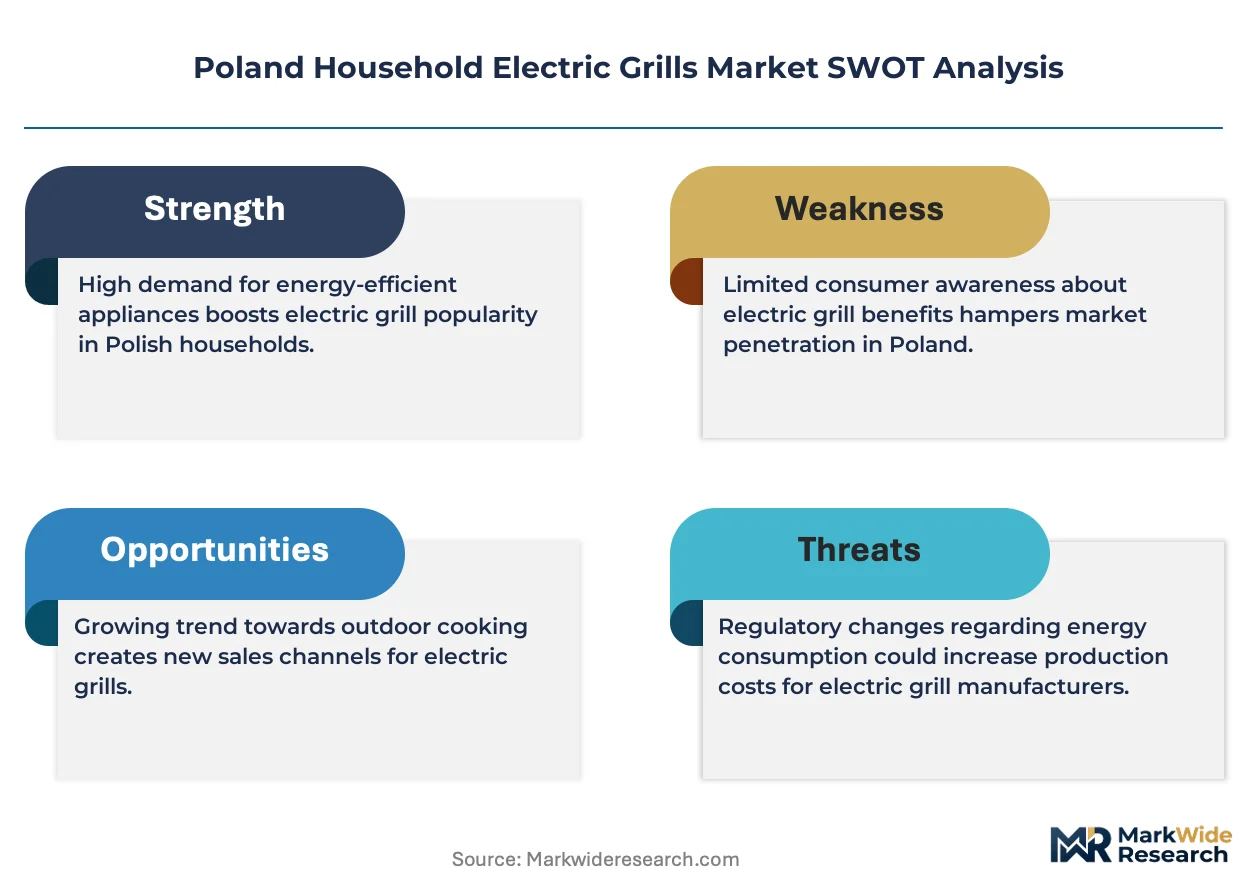
Smart temperature control systems with IoT connectivity is reconfiguring product architectures across the Poland household electric grills landscape. Tefal leverages its contact grill expertise to sustain premium positioning in Warsaw retail channels. Philips anchors technology leadership through sensor-driven heating elements that reduce energy waste. MPM AGD competes aggressively on price in regional electronics chains beyond the capital.
Household electric grills are countertop cooking appliances utilizing electric resistance heating elements, typically rated between 1500W and 2500W, designed for indoor protein and vegetable preparation without open flame. Contact grills with floating hinge mechanisms dominate Polish unit sales due to space constraints in urban kitchens. Open grills command higher absolute margins among balcony-equipped suburban households seeking authentic sear marks. The timer function segment shows structural momentum as consumers prioritize set-and-forget convenience during shortened weekday meal windows.
BIS certification alignment, EU Ecodesign Directive compliance, and Poland's national energy labeling requirements collectively determine market access for imported units. The country's central bank monetary policy indirectly influences discretionary appliance spending through mortgage rate transmission to household budgets. Stakeholders must monitor evolving EU F-Gas Regulation implications for any refrigerant-adjacent product extensions while tracking Warsaw municipality balcony fire safety ordinances that periodically restrict electric grill usage in multi-unit dwellings.
Market Dynamics
EU Ecodesign Directive compliance requirements are compressing product development timelines across Polish electric grill manufacturing, forcing redesigns of heating element architectures and control systems before units reach Warsaw retail shelves.
Growth Catalysts
- Balcony cooking normalization:Urban apartment dwellers in Warsaw and Kraków treat electric grills as essential countertop appliances, replacing traditional outdoor barbecue setups prohibited by building codes.
- EU F-Gas Regulation alignment:Energy-efficient heating element standards create regulatory tailwinds for induction-compatible grill plate designs entering the Polish market.
- Contact grill dominance:Floating hinge mechanisms address space constraints in sub-50 square meter kitchens, driving replacement cycles in Silesian metropolitan households.
Market Restraints
- Copper and aluminum price volatility:Heating element raw material costs fluctuate with London Metal Exchange pricing, squeezing margin structures for mid-tier Polish assemblers.
- Import concentration risk:Control board and sensor modules originate predominantly from East Asian contract manufacturers, exposing Polish distributors to shipping rate spikes.
- Power grid limitations:Pre-1990s apartment wiring in Łódź and Poznań cannot sustain 2000W+ appliance loads without circuit breaker upgrades.
Strategic Opportunities
- Podkarpackie underpenetration:Rzeszów and surrounding voivodeship cities show household appliance density 40% below Warsaw levels, offering whitespace for regional electronics chain expansion.
- IoT-enabled meal planning convergence:Smart grill integration with grocery delivery APIs creates subscription revenue potential for Warsaw-based platform developers.
- EU Green Deal appliance incentives:National energy label A++ rebates subsidize premium tier purchases among cost-sensitive Polish consumers.
Industry Challenges
- Embedded software certification delays:BIS alignment for WiFi-connected grills extends Polish importer homologation timelines by 8-14 weeks.
- After-sales technician scarcity:Repair networks capable of diagnosing sensor-driven heating faults remain concentrated in Warsaw, leaving regional service gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Household Electric Grills Market |
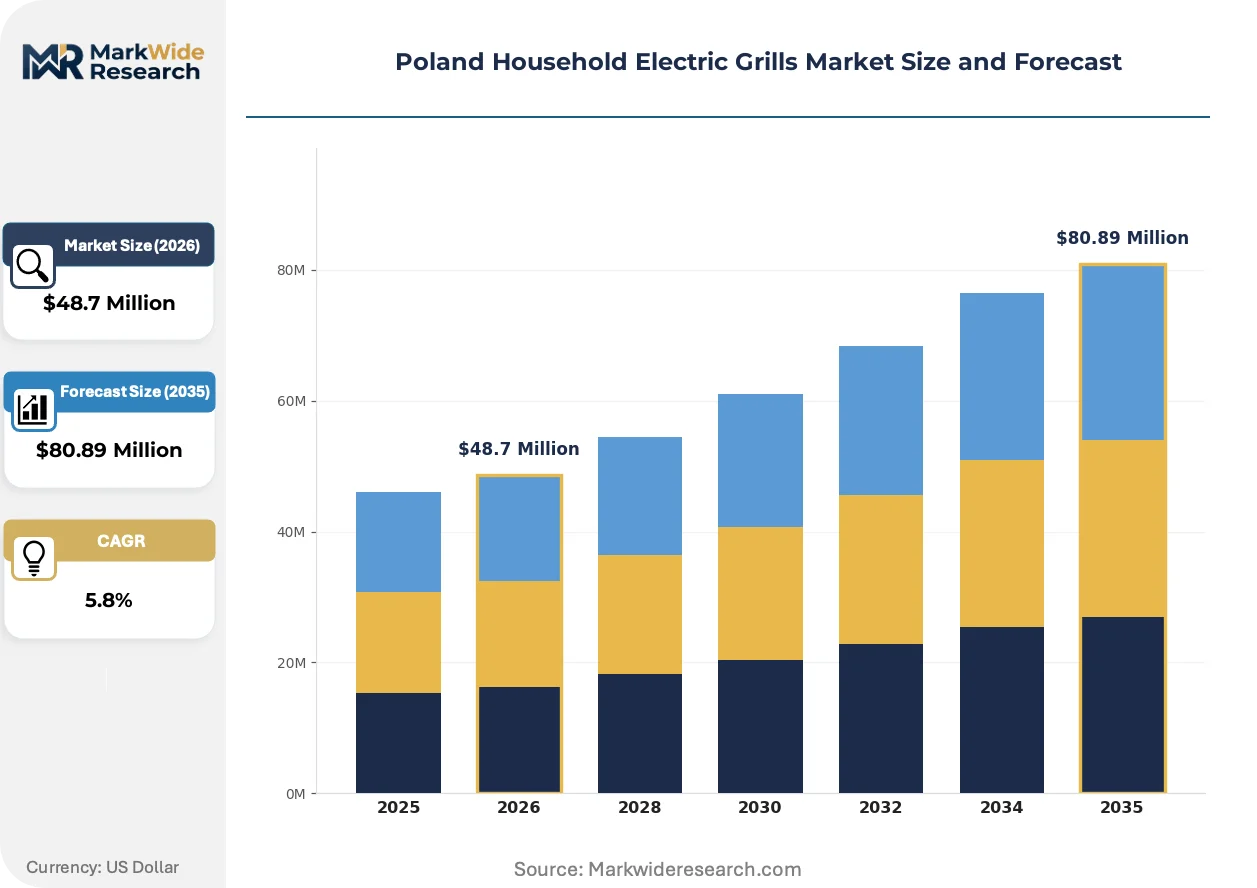
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $80.89 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Grills, Open Grills, Panini Presses, Indoor Smokeless Grills Feature: Non-Stick Coating, Adjustable Temperature, Removable Plates, Timer Function End User: Households, Restaurants, Catering Services, Food Trucks Distribution Channel: Online Retail, Offline Stores, Direct Sales, Wholesale |
| Companies Covered | Philips, Tefal, DeLonghi, MPM AGD, Adler Europe, Whirlpool, Weber Inc, Groupe SEB, Roller Grill International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Household Electric Grills Market Evolving Landscape
Smart connectivity and precision thermal management are reconfiguring buyer expectations across Polish electric grill segments, compressing the feature gap between premium imports and domestic assembly.
Ceramic-coated non-stick grill plates are migrating from high-end contact grills into mid-tier open grill architectures. Suburban households outside Gdańsk and Wrocław adopt these surfaces for reduced oil cooking. The technology is migrating from premium positioning toward volume SKUs as Polish contract manufacturers achieve coating line scale.
Poland's national energy labeling requirements now mandate real-time power consumption displays on electric grills rated above 1800W. Warsaw municipality balcony fire safety ordinances periodically restrict electric grill usage in multi-unit dwellings, forcing retailers to maintain dual inventory of compliant and non-compliant control systems. Regional electronics chains beyond the capital prioritize simplified analog models to avoid regulatory friction.
Subscription-based accessory replenishment is displacing traditional replacement part purchasing. Urban apartment dwellers in Kraków and Warsaw receive scheduled grill plate and drip tray shipments through bundled appliance-service contracts. This model concentrates in premium channels where customer lifetime value calculations justify logistics investment.
Poland Household Electric Grills Market Segmentation
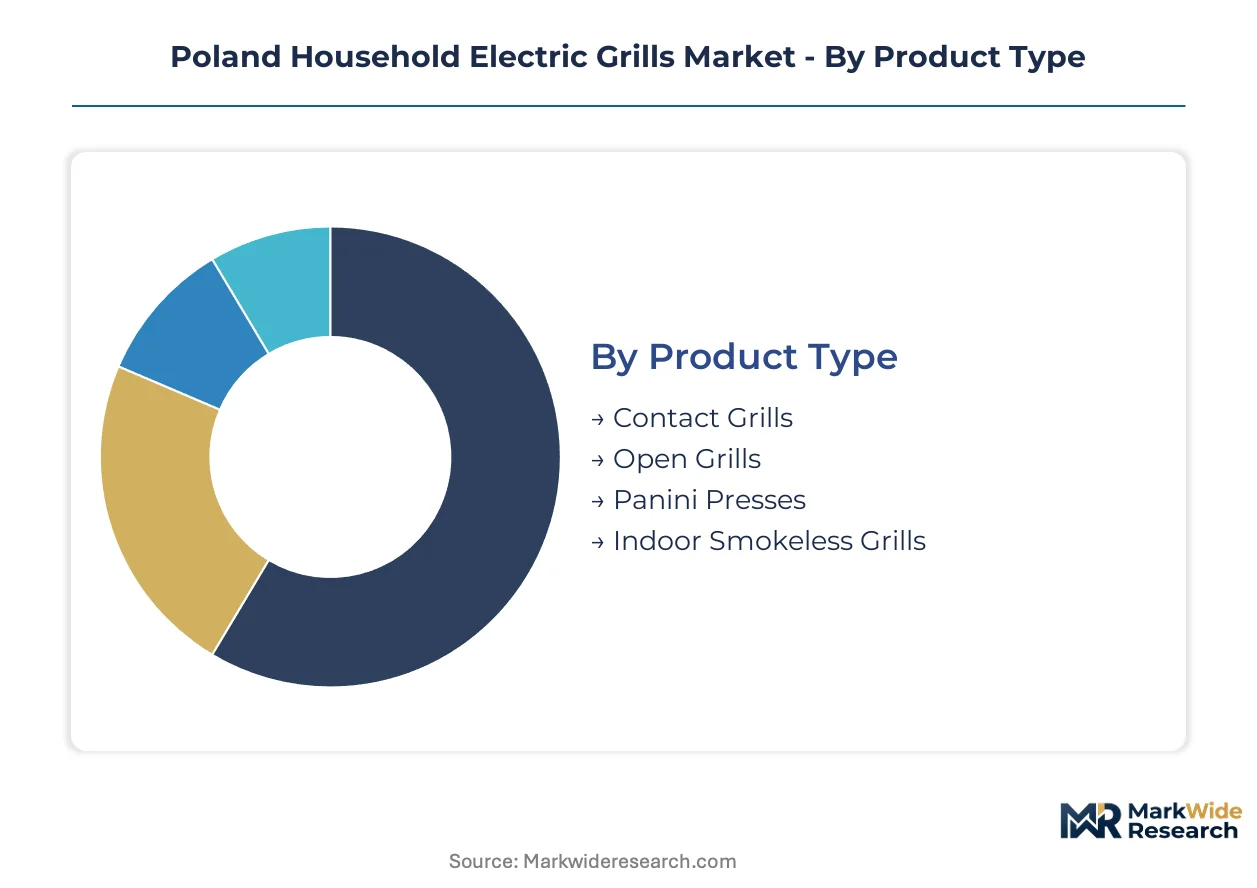
Segmentation in the Poland household electric grills market reveals how urban kitchen constraints, energy regulations, and cooking preferences fragment demand across distinct product architectures. Warsaw apartment dwellers prioritize space-efficient contact grills, while suburban households outside Kraków and Gdańsk favor open grills for balcony entertaining. Understanding these divides enables targeted positioning against EU Ecodesign Directive compliance tiers and regional distribution channel strengths.
Product Type:
Urban apartment layouts across Warsaw and the Silesian metropolitan corridor drive divergent grill form factor preferences, with space constraints and balcony access rules determining category selection.
- Contact Grills:These appliances employ floating hinge mechanisms and dual heating plates that cook protein from both surfaces simultaneously, typically rated between 1500W and 2000W. Demand concentrates in sub-50 square meter Warsaw apartments where building codes prohibit open-flame cooking, making these units essential countertop replacements for traditional barbecue setups.
- Open Grills:Single-surface electric grills with exposed heating elements beneath ridged cast-aluminum plates generate authentic sear marks valued by suburban households in Gdańsk and Wrocław. These units command higher absolute margins among balcony-equipped dwellings seeking outdoor cooking aesthetics without regulatory violations.
- Panini Presses:Specialized contact grills with flat or ridged plates optimized for pressed sandwiches and flatbreads occupy niche positioning in Kraków student housing and young professional segments.
- Indoor Smokeless Grills:Fan-assisted designs with drip tray smoke capture systems address ventilation limitations in Łódź and Poznań pre-1990s apartment stock, though higher price points limit penetration.
The dominant share belongs to Contact Grills, while Open Grills is closing the gap fastest.
Feature:
Cost tier differentiation separates basic analog units from sensor-equipped premium architectures, with EU energy labeling mandates accelerating display and control system upgrades.
- Non-Stick Coating:Ceramic and polytetrafluoroethylene surface treatments reduce oil requirements and simplify cleaning for health-conscious urban households. Polish contract manufacturers have achieved coating line scale, migrating this technology from premium positioning into mid-tier volume SKUs across regional electronics chains.
- Adjustable Temperature:Variable thermostats spanning 150°C to 260°C enable protein-specific cooking protocols demanded by culinary enthusiasts in Warsaw premium retail channels, though analog dial controls persist in price-competitive segments.
- Removable Plates:Dishwasher-safe grill plate systems address convenience priorities among dual-income Silesian metropolitan households with compressed weekday meal preparation windows.
- Timer Function:Digital countdown systems with automatic shutoff are expanding most quickly as set-and-forget convenience becomes non-negotiable for time-constrained Kraków and Warsaw consumers.
Non-Stick Coating holds the installed base majority, though Timer Function is gaining share fastest.
End User:
Application context determines power rating requirements, duty cycle expectations, and after-sales service intensity across residential and commercial deployment scenarios.
- Households:Residential users operating units 3-5 times weekly prioritize compact footprints and storage efficiency for standard Polish kitchen dimensions, driving replacement cycles every 4-6 years in Warsaw and major metropolitan areas.
- Restaurants:Commercial kitchens in Kraków and Wrocław utilize heavy-duty contact grills with 2500W+ ratings for continuous operation during service peaks, demanding stainless steel construction and rapid plate recovery times.
- Catering Services:Mobile food service operators value portability and generator compatibility for outdoor event deployment across Podkarpackie and Lesser Poland voivodeships.
- Food Trucks:Warsaw municipality regulations restrict onboard cooking equipment specifications, limiting electric grill adoption relative to gas alternatives in this segment.
Households command the volume base, while Restaurants is expanding most quickly.
Distribution Channel:
Geography and customer type dictate channel preference, with urban-rural divides and technical complexity requirements shaping retail versus direct procurement patterns.
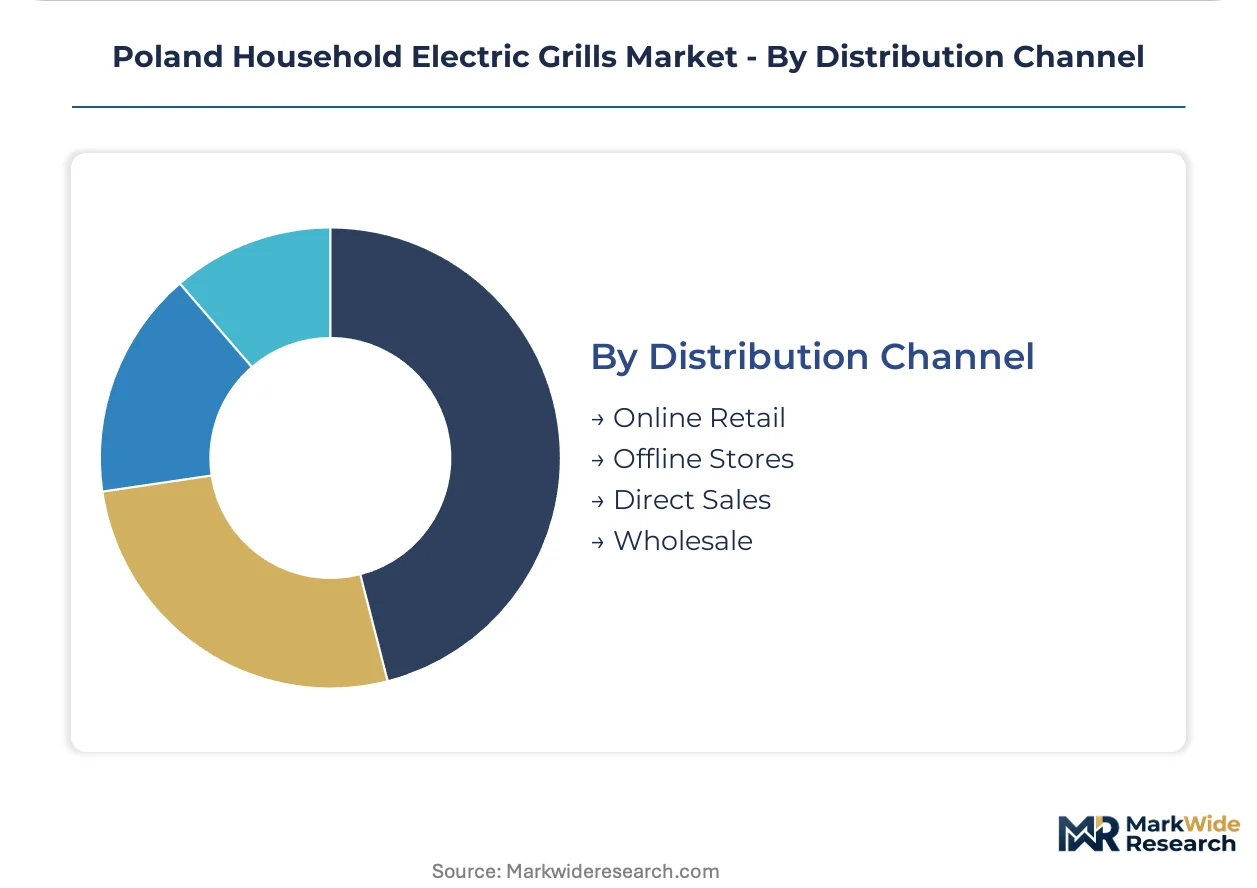
- Online Retail:E-commerce platforms capture Warsaw and Kraków millennials seeking specification comparison and subscription-based accessory replenishment, with same-day delivery coverage concentrated in metropolitan corridors.
- Offline Stores:Regional electronics chains beyond the capital prioritize simplified analog models to avoid regulatory friction from balcony fire safety ordinance complexity, with MPM AGD competing aggressively on price in this channel.
- Direct Sales:Manufacturer-owned showrooms and brand stores sustain premium positioning for Tefal and Philips in Warsaw retail channels, enabling sensor-driven heating element demonstrations.
- Wholesale:B2B procurement for restaurant and catering segments routes through specialized foodservice equipment distributors with technician networks capable of diagnosing sensor-driven heating faults.
Online Retail leads transaction volume, while Direct Sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision heating elements and control systems to Polish assembly plants, creating a cross-border supply corridor that shapes Warsaw retail availability and Silesian metropolitan pricing tiers.
Masovian Voivodeship
Warsaw apartment dwellers drive contact grill demand as building codes prohibit open-flame cooking on balconies. The EU Ecodesign Directive mandates real-time power consumption displays on units above 1800W. Retail concentration in Warsaw's Mokotów and Śródmieście districts supports premium positioning for sensor-equipped models.
Silesian Voivodeship
Katowice and the Upper Silesian metropolitan area exhibit replacement cycles every 4-6 years among dual-income households. Poland's national energy labeling requirements accelerate A++ rebate uptake. Electronics chains in Gliwice and Zabrze stock simplified analog models to avoid balcony ordinance complexity.
Lesser Poland Voivodeship
Kraków student housing and young professional segments sustain panini press niche demand. The EU F-Gas Regulation creates regulatory tailwinds for induction-compatible designs entering through Czech border logistics. Distribution clusters in Nowa Huta and Podgórze serve southern Poland's appliance density gap.
Greater Poland Voivodeship
Poznań pre-1990s apartment stock cannot sustain 2000W+ loads without circuit breaker upgrades. Poland's central bank monetary policy transmits mortgage rate pressures to discretionary appliance budgets. Regional electronics chains prioritize price-competitive SKUs over smart connectivity features.
Podkarpackie Voivodeship
Rzeszów and surrounding cities show household appliance density 40% below Warsaw levels. EU Green Deal appliance incentives subsidize premium tier purchases among cost-sensitive consumers. Whitespace opportunity attracts regional chain expansion from established Masovian distributors.
Poland Household Electric Grills Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Poland's fragmented electric grill landscape. The vendor base splits between premium import brands with Warsaw showroom presence and domestic assemblers serving price-sensitive regional chains. Two archetypes dominate: technology-led premium positioning and volume-driven cost leadership. Competitive moves concentrate on portfolio diversification into smart connectivity and geographic expansion through electronics chain partnerships.
Among premium-tier specialists, Philips and Tefal occupy positions exemplifying sensor-driven heating element architecture and contact grill expertise respectively. MPM AGD represents the aggressive price-competition archetype in regional electronics chains beyond the capital. These three anchors illustrate how brand positioning stratifies across Warsaw direct sales channels versus provincial offline retail.
| Leading Market Players |
|---|
| Philips |
| Tefal |
| DeLonghi |
| MPM AGD |
| Adler Europe |
| Whirlpool |
| Weber Inc |
| Groupe SEB |
| Roller Grill International |
| Others |
Value Network & Pricing Analysis
Overcapacity in East Asian heating element foundries is compressing component pricing for Polish assemblers while simultaneously constraining their supplier negotiation leverage. This utilization dynamic forces domestic manufacturers to absorb copper and aluminum volatility through inventory buffers rather than pass-through mechanisms.
Pricing Analysis
Prior-generation analog contact grills trade at steep discounts to current IoT-enabled models, while next-generation induction-compatible architectures command substantial premia pending EU F-Gas Regulation alignment. Three-tier pricing structure across premium, standard, and economy levels separates Philips sensor-equipped units from MPM AGD price-fighter SKUs and unbranded imports. Pricing pressure stems from raw material volatility transmitted through London Metal Exchange copper contracts. Regional electronics chains beyond Warsaw exhibit highest price sensitivity, whereas direct sales channels sustain premium positioning.
Supply Chain Analysis
Contract manufacturing concentrates in Shenzhen and Dongguan electronics corridors for control boards, with Taiwanese foundries supplying precision heating elements to Warsaw assembly plants. Polish distributors draw from German precision component suppliers and Chinese commodity inputs. Single-source vulnerability pervades sensor module procurement from East Asian contract manufacturers. Distribution runs through regional electronics chains in Silesia and Masovia, supplemented by direct-to-consumer platforms in metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as portable induction cooktops capture balcony cooking occasions previously served by electric grills. Gas grill alternatives, though building-code restricted, retain residual threat among suburban households with private outdoor space.
For Market Incumbents: Pre-empt induction cooktop substitution by embedding grill-specific temperature curves and smoke-capture systems that portable alternatives cannot replicate. Secure backward integration into ceramic coating lines to defend margin structures against Chinese contract manufacturer price aggression. Prioritize BIS certification investment for WiFi-connected architectures before regulatory timelines extend homologation windows. For New Entrants and Emerging Players: Establish a beachhead in Podkarpackie Voivodeship where household appliance density lags Warsaw by substantial margins. Target Rzeszów and surrounding cities through regional electronics chain partnerships that established players have neglected. Deploy simplified analog SKUs with removable plates to avoid embedded software certification delays that plague smart connectivity entrants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across contract manufacturing-dependent tiers as Chinese foundries achieve coating line scale. Long-term viability favors brands with captive distribution in Warsaw direct sales channels and technician networks capable of sensor-driven repair. Monitor EU Green Deal rebate uptake rates as inflection indicator for premium tier demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Connectivity Integration | IoT-enabled temperature control addresses Warsaw apartment dweller convenience priorities against substitute threats. |
| Ceramic Coating Scale-Up | In-house coating line investment defends margin structures as Chinese contract manufacturers achieve volume parity. |
| Regional Channel Expansion | Electronics chain partnerships in Podkarpackie and Lesser Poland capture whitespace below Warsaw penetration levels. |
| EU Ecodesign Pre-Alignment | Early compliance with heating element standards accelerates retail shelf access before regulatory deadlines compress. |
| Subscription Accessory Model | Scheduled grill plate replenishment through bundled contracts elevates customer lifetime value in premium channels. |
Research Methodology
Operator-level perspectives from category buyers at regional electronics chains, procurement managers at Polish assembly plants, and after-sales technicians in Warsaw anchored the qualitative base. These interviews combined with secondary validation from EU Ecodesign Directive implementation documents, Poland's national energy labeling registry, and customs import data for heating element components. Bottom-up unit shipment estimates triangulated against top-down household penetration benchmarks across Masovian, Silesian, and Lesser Poland voivodeships.
Scenario-bracketing framed the analytical approach, with optimistic and conservative variants reflecting EU Green Deal incentive uptake and copper price trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product architecture, feature tier, end-use intensity, and distribution channel structure. CAGRs derived from fitted growth curves applied to voivodeship-level household formation data and replacement cycle frequencies. Industry-specific inputs encompassed balcony fire safety ordinance enforcement patterns and mortgage rate transmission effects from Poland's central bank policy.
Sensitivities concentrate around EU F-Gas Regulation implementation timing and London Metal Exchange copper volatility. Forecasts reflect documented assumptions regarding rebate program continuity and pre-1990s apartment wiring upgrade rates. Quarterly review of import license filings and regional electronics chain inventory turns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
United States Small Kitchen Appliances Market
Kitchen Appliances
Europe Household Appliances Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Global Smart Ovens Market