
 Cookware Accessories Market | 2026-2036
Cookware Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Cookware Accessories Market Outlook
E-commerce platforms and direct-to-consumer channels are reshaping how cookware accessories reach buyers. Groupe SEB leverages its multi-brand portfolio to control shelf space across premium and mass-market tiers. ZWILLING J.A. Henckels anchors its position through German-engineered stainless steel craftsmanship and specialized retail partnerships. OXO competes on ergonomic design patents that differentiate its kitchen tools in crowded digital marketplaces.
Cookware accessories encompass specialized implements—spatulas, tongs, measuring cups, and cooking utensils—fabricated from stainless steel, silicone, wood, or food-grade plastic, with heat resistance thresholds typically spanning 200°C to 260°C for polymer-based variants, serving both food preparation efficiency and surface protection for coated cookware. Silicone-based utensils lead in growth velocity due to non-scratch compatibility with ceramic and PTFE-coated pans, while stainless steel dominates margin pools in professional segments where durability standards exceed 10,000 cycle tests. Wood and plastic categories occupy mature positions in emerging markets where cost sensitivity structures purchasing decisions.
FDA food-contact substance regulations and EU REACH chemical restrictions govern silicone curing agents and plasticizer content, compelling manufacturers to reformulate compounds or sacrifice market access. ISO 8442 cutlery and flatware standards, alongside Germany's LFGB food-contact testing protocols, create layered compliance burdens that favor vertically integrated producers with in-house laboratory certification. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these chemicals intersect with non-stick cookware accessory compatibility claims and consumer safety perceptions.
Market Dynamics
REACH chemical restrictions in Europe and FDA food-contact substance regulations in the United States are forcing manufacturers to reformulate silicone curing agents and plasticizer compounds, restructuring raw material sourcing across the cookware accessories supply chain.
Growth Catalysts
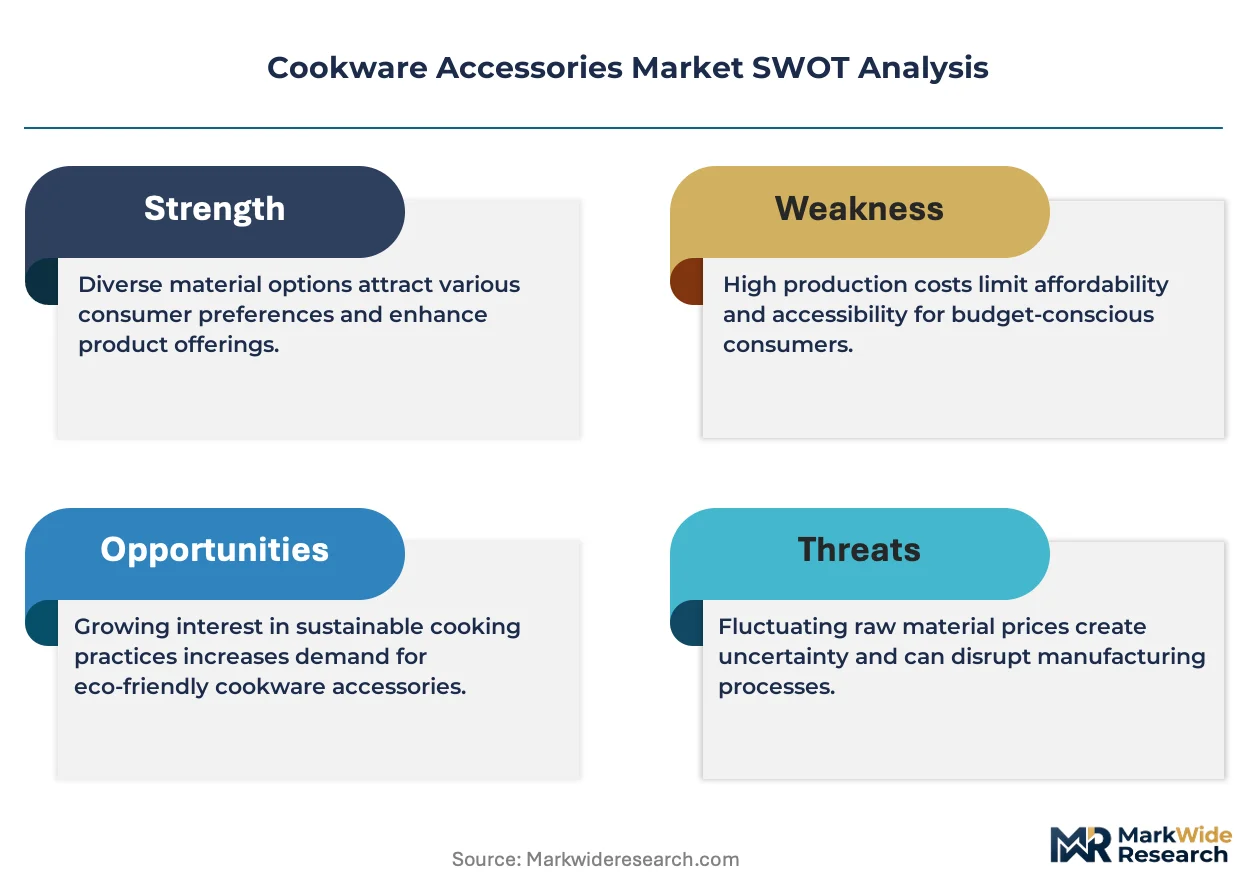
- EU REACH compliance mandates:Chemical safety testing protocols compel manufacturers to upgrade material specifications, creating demand for certified food-grade silicone and stainless steel utensil sets in professional and home kitchen segments.
- Non-scratch compatibility requirements:Ceramic and PTFE-coated pan proliferation drives replacement cycles for polymer-based utensils with heat resistance thresholds above 200°C.
- Manufacturing cluster concentration in China and India:Integrated production ecosystems reduce unit costs for export-oriented cookware accessory suppliers serving European and North American retail channels.
Market Restraints
- Petrochemical feedstock volatility:Silicone polymer precursors and food-grade plastics face input cost swings tied to crude oil derivatives, compressing margin stability for mid-tier producers.
- Single-source dependency on German LFGB certification laboratories:Limited accredited testing capacity creates bottlenecks for market entry validation, extending product launch timelines.
- Wood and bamboo substitution ceiling:Natural fiber utensils face durability limitations below 10,000 cycle tests, restricting penetration in commercial foodservice procurement specifications.
Strategic Opportunities
- Underpenetrated Indian urban households:Rising home cooking participation among metro-area consumers creates pull for ergonomic silicone utensil sets positioned between mass-market plastic and premium stainless steel tiers.
- Direct-to-consumer channel expansion:E-commerce platforms enable bypass of traditional retail slotting fees, allowing specialized manufacturers to capture margin previously allocated to distributor networks.
- Per- and polyfluoroalkyl substance restriction tailwinds:Evolving EPA and state-level chemical bans in the United States accelerate demand for PFAS-free silicone formulations compatible with non-stick cookware accessory claims.
Industry Challenges
- ISO 8442 and layered certification complexity:Manufacturers must sequence cutlery standards, LFGB food-contact protocols, and REACH chemical registrations, stretching quality assurance team capacity.
- Supply chain reconfiguration friction:Relocating silicone molding operations to alternative geographies requires rebuilding FDA-compliant compound formulation capabilities and revalidating heat resistance thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cookware Accessories Market |
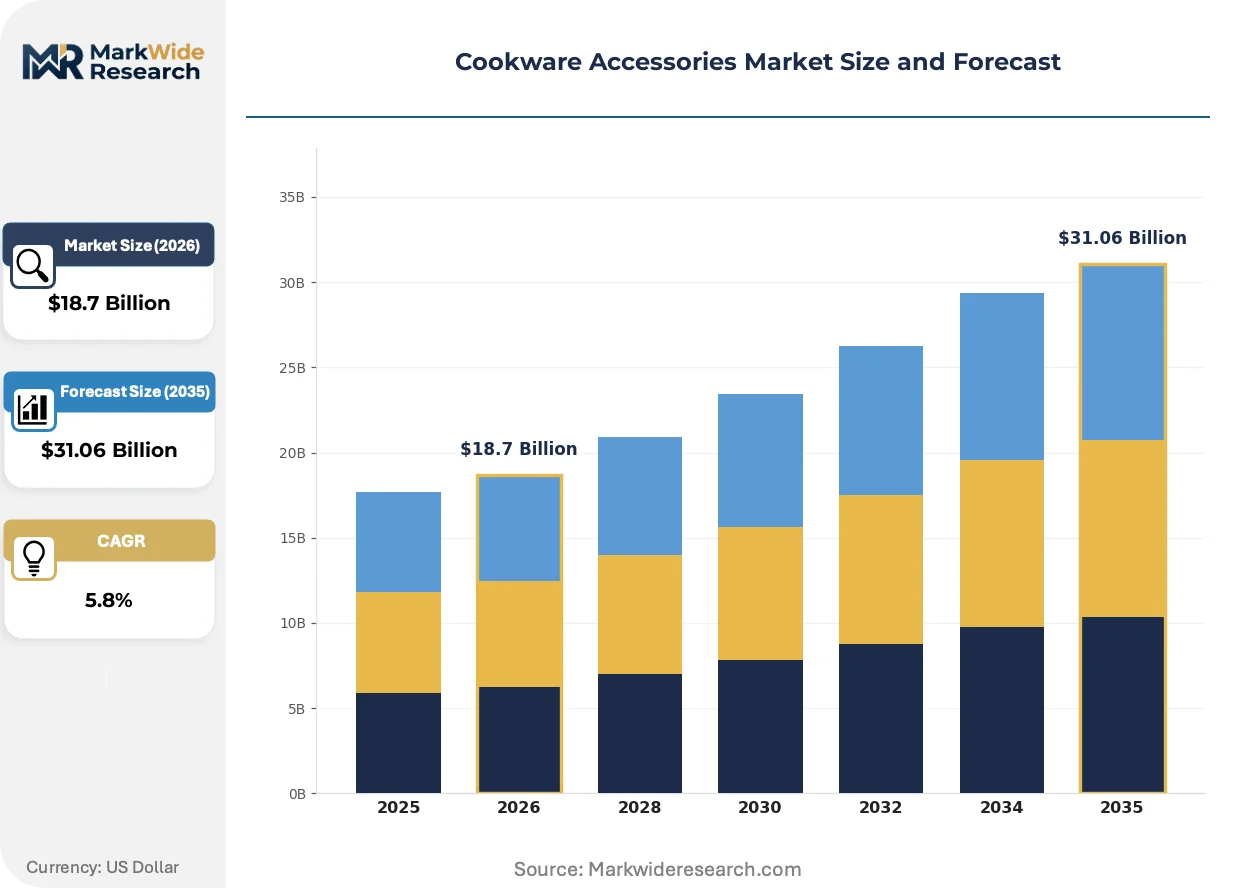
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spatulas, Tongs, Measuring Cups, Cooking Utensils Material: Stainless Steel, Silicone, Plastic, Wood Usage: Baking, Grilling, Frying, Mixing Brand: Cuisinart, OXO, Tupperware, Pampered Chef |
| Companies Covered | Groupe SEB, Meyer Corporation, Le Creuset, ZWILLING J.A. Henckels, All-Clad Metalcrafters, Williams-Sonoma, Lifetime Brands, OXO, Cuisinart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cookware Accessories Market Strategic Shifts
Material science advances and regulatory chemical restrictions are compressing traditional product lifecycles while opening premium positioning for certified-safe formulations. Three developments dominate current competitive maneuvering.
Platinum-cured silicone formulations is migrating from medical device applications into food-contact utensil production. High-end cookware brands specify these compounds for spatulas and tongs targeting consumers with ceramic and PTFE-coated pan investments. The shift enables manufacturers to command price premiums while satisfying dual FDA and REACH compliance requirements.
EU F-Gas Regulation phase-down schedules are indirectly pressuring ancillary product categories through supply chain spillover effects. Fluoropolymer component restrictions complicate non-stick coating compatibility claims for accessory suppliers, forcing reformulation of silicone surface treatments. German retailers now require third-party LFGB documentation for all polymer-based kitchen tools, elevating certification costs for export-dependent producers.
Home cooking enthusiasts now research heat resistance specifications and chemical safety certifications before purchase, displacing impulse buying at brick-and-mortar housewares aisles. Specialty kitchenware e-commerce platforms capture this traffic through detailed technical content and video demonstrations. China and Germany exhibit the strongest correlation between certification transparency and conversion rates.
Cookware Accessories Market Segmentation
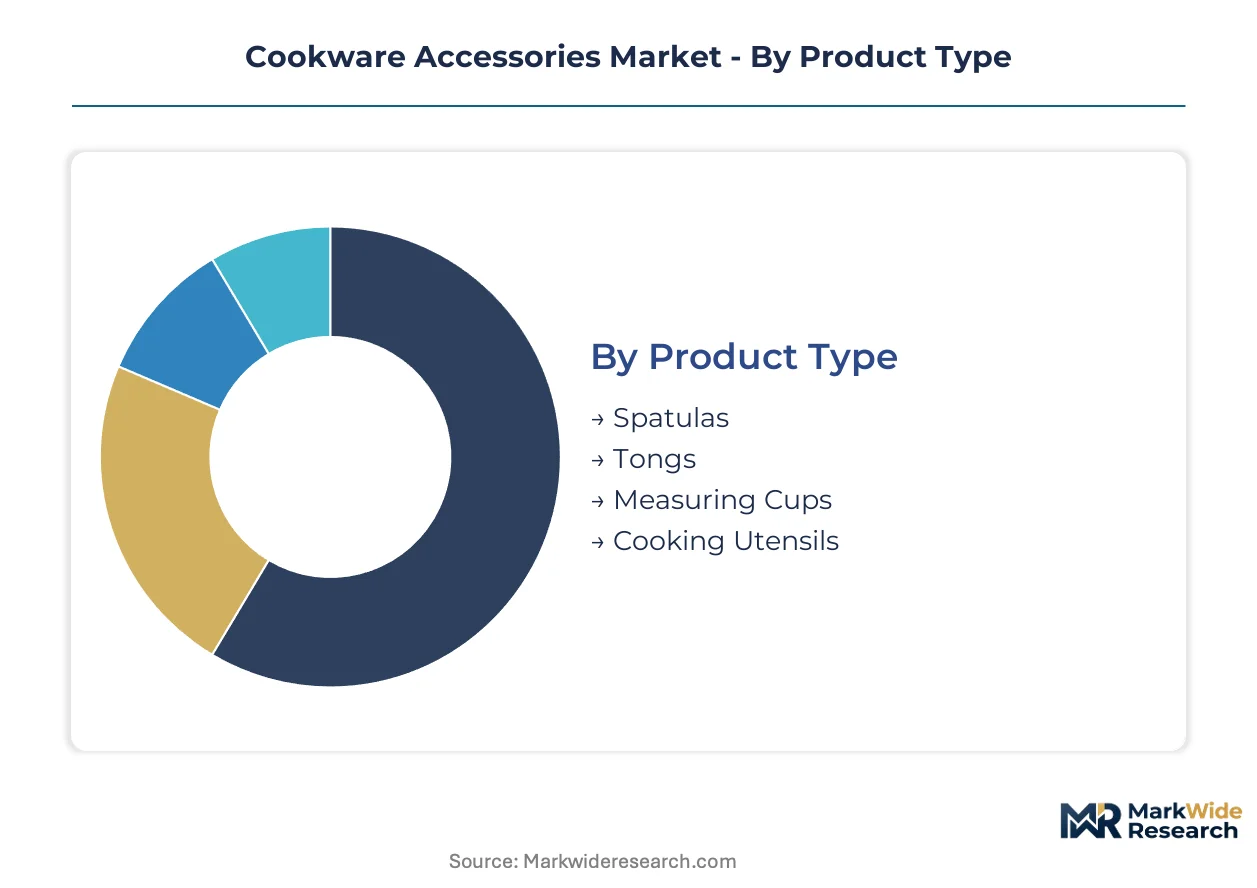
Cookware accessories fragment across functional roles, material specifications, and heat resistance thresholds that determine compatibility with coated cookware surfaces. Understanding these divides reveals where procurement budgets concentrate and where formulation investments yield competitive differentiation.
Product Type:
Home cooking enthusiasts and professional kitchens select implements based on task specificity and surface protection requirements.
- Spatulas:Polymer-based variants with heat resistance above 200°C dominate replacement cycles for ceramic and PTFE-coated pan owners. Demand clusters in Germany and China where non-scratch compatibility drives premium positioning.
- Tongs:Stainless steel constructions with silicone-coated tips capture professional foodservice procurement specifications requiring durability beyond 10,000 cycle tests. Commercial kitchens in India specify these for high-volume frying operations.
- Measuring Cups:Nested sets in food-grade plastic or stainless steel serve precision baking workflows. Cost-sensitive emerging markets favor single-material plastic sets.
- Cooking Utensils:Broad category encompassing ladles, whisks, and turners with material mix determined by cookware surface type. E-commerce platforms drive visibility for specialized ergonomic designs.
Established volume favors cooking utensils; emerging adoption favors spatulas.
Material:
Raw material selection determines regulatory compliance burden and heat performance ceiling.
- Stainless Steel:Austenitic grades meeting ISO 8442 standards anchor professional segment margins. German LFGB certification requirements favor producers with in-house metallurgical testing.
- Silicone:Platinum-cured formulations migrating from medical device applications command price premiums while satisfying FDA and REACH dual compliance. This segment climbs the fastest as ceramic pan proliferation accelerates replacement demand.
- Plastic:Food-grade polypropylene and nylon occupy mass-market tiers where cost sensitivity structures purchasing decisions in India and China.
- Wood:Bamboo and hardwood variants face durability limitations below commercial cycle test thresholds, restricting penetration in foodservice procurement.
Margin concentration favors stainless steel; formulation innovation favors silicone.
Usage:
Cooking method determines heat exposure severity and material performance requirements.
- Baking:Precision-oriented tasks favor measuring accuracy and non-reactive surfaces. Silicone spatulas and measuring cups dominate this segment.
- Grilling:High-heat exposure above 260°C necessitates stainless steel constructions with extended reach handles. Outdoor cooking enthusiasts in the United States drive replacement cycles.
- Frying:Sustained oil contact requires FDA-compliant materials with thermal stability. Commercial kitchens specify stainless steel-silicone hybrid tongs.
- Mixing:Mechanical stress tolerance determines material selection; wooden spoons retain share in home segments despite durability constraints.
Procurement scale favors frying; specialized premium positioning favors grilling.
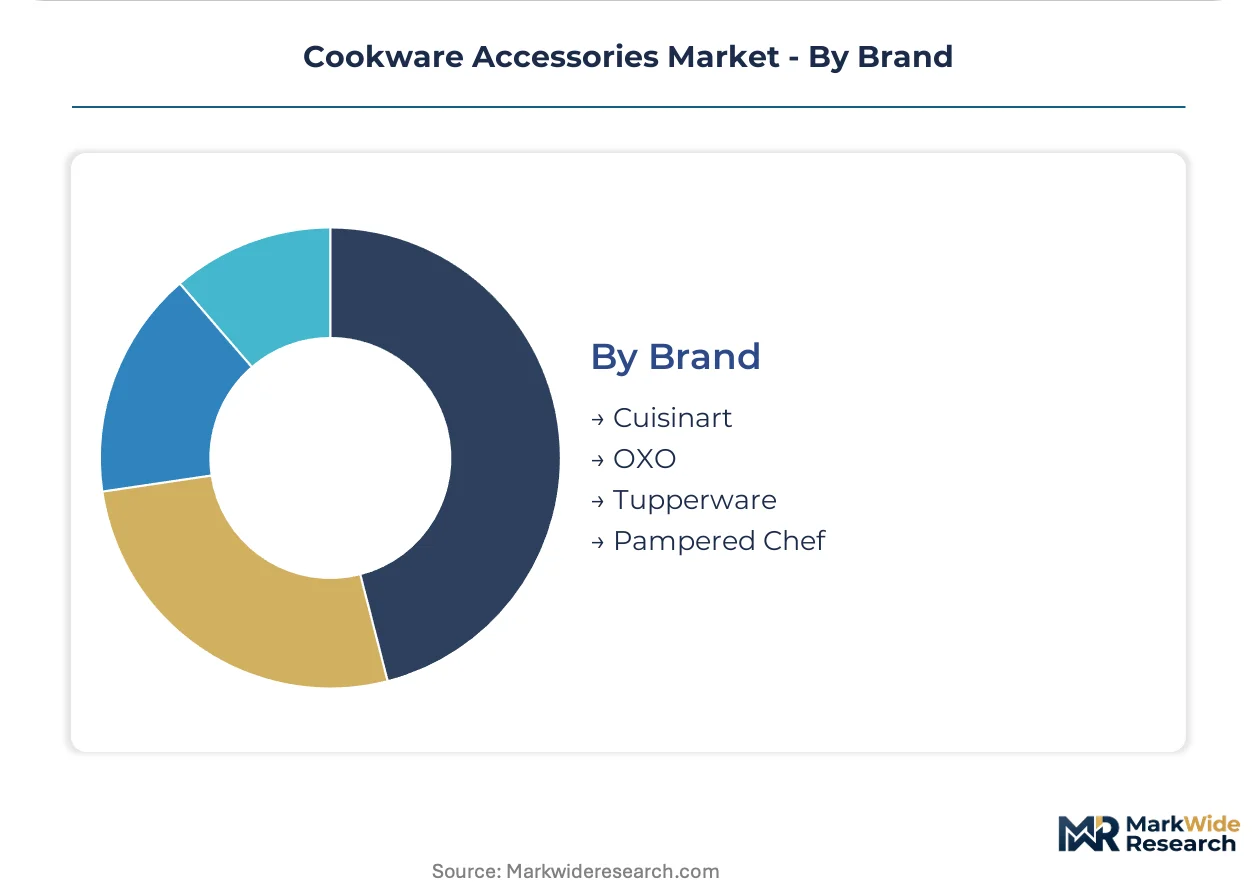
Brand:
Brand architecture spans direct-to-consumer channels and traditional retail slotting strategies.
- Cuisinart:Multi-product kitchen ecosystem leveraging appliance brand recognition into accessory attachment sales.
- OXO:Ergonomic design patents differentiate digital marketplace positioning with detailed technical content.
- Tupperware:Direct sales network targets home cooking enthusiasts through demonstration-based conversion.
- Pampered Chef:Consultant-driven model captures premium kitchen tool budgets through personalized recommendation.
Digital channel penetration favors OXO; consultant network depth favors Pampered Chef.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German LFGB certification requirements and REACH chemical restrictions are restructuring procurement specifications across major consumer markets. Manufacturing clusters in China and India leverage integrated production ecosystems to serve export demand, while regulatory divergence between jurisdictions creates layered compliance burdens for suppliers.
United States
Home cooking enthusiasts and professional kitchens drive replacement cycles for silicone utensil sets compatible with ceramic and PTFE-coated pans. FDA food-contact substance regulations govern silicone curing agents and plasticizer content, compelling manufacturers to reformulate compounds. E-commerce platforms in California and Texas capture consumer traffic through detailed technical content and certification transparency.
Germany
Specialized retail partnerships and German-engineered stainless steel craftsmanship anchor premium positioning for professional foodservice procurement. EU REACH mandates and F-Gas Regulation spillover effects reshape material specifications for polymer-based kitchen tools. Manufacturing and testing facilities concentrate in North Rhine-Westphalia and Bavaria, where LFGB-accredited laboratories validate market entry.
China
Export-oriented suppliers serving European and North American channels benefit from integrated silicone molding and stainless steel fabrication ecosystems. SAMR food-contact standards and GB technical regulations align with FDA and REACH protocols for dual-market producers. Yangtze River Delta manufacturing clusters dominate volume production for spatulas, tongs, and utensil sets.
India
Rising home cooking participation in metro-area households creates demand for ergonomic utensil sets between mass-market plastic and premium stainless steel tiers. FSSAI food safety regulations and BIS standards govern material specifications for domestic and export production. Tamil Nadu and Maharashtra host manufacturing facilities targeting cost-sensitive emerging market segments.
France
Multi-brand portfolio strategies control shelf space across premium and mass-market retail tiers through specialized kitchenware distribution. EU chemical restrictions and ECHA guidance documents influence silicone formulation requirements for food-contact applications. Paris-region design houses and Lyon-area manufacturing coordinate product development for ceramic-compatible utensil lines.
Cookware Accessories Market Competitive Environment
On the supply side, the industry is moderately consolidated around multi-brand conglomerates, specialized German-engineered manufacturers, and ergonomic design-focused specialists. Three strategic archetypes dominate: vertically integrated producers with in-house laboratory certification, design-patent holders competing through digital channels, and multi-product kitchen ecosystem builders leveraging appliance brand recognition. Competitive maneuvering centers on portfolio diversification into adjacent kitchen categories and direct-to-consumer channel expansion bypassing traditional retail slotting fees.
Among European-headquartered conglomerates, Groupe SEB and ZWILLING J.A. Henckels exemplify the vertically integrated and German-engineered archetypes respectively, while OXO occupies a position within the ergonomic design-specialist tier. These three entities represent contrasting pathways to market access: multi-brand portfolio breadth, craftsmanship-associated premium positioning, and patent-protected digital marketplace differentiation. Each anchors a distinct competitive vector without overlapping strategic territory.
| Leading Market Players |
|---|
| Groupe SEB |
| Meyer Corporation |
| Le Creuset |
| ZWILLING J.A. Henckels |
| All-Clad Metalcrafters |
| Williams-Sonoma |
| Lifetime Brands |
| OXO |
| Cuisinart |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility determines both pricing tier spreads and supply chain shape in cookware accessories, as silicone polymer precursor costs swing with crude oil derivatives and force mid-tier producers into certification-driven premium migration or margin sacrifice.
Pricing Analysis
Certification level creates the primary spread across cookware accessory tiers, with LFGB-accredited and FDA food-contact-grade silicone formulations commanding substantial premiums over uncertified alternatives. Pricing stratifies across platinum-cured medical-grade silicone, standard food-grade compounds, and mass-market polypropylene, with cost compression in the middle tier intensifying because of REACH reformulation mandates. Professional foodservice buyers in Germany exhibit lowest price sensitivity, while emerging market household segments in India drive volume at economy tiers.
Supply Chain Analysis
Silicone polymer precursors and stainless steel feedstock anchor upstream dependencies, with specialty chemical production concentrating in Germany and China while austenitic steel sourcing draws from Indian and German metallurgical facilities. Manufacturing clusters in Yangtze River Delta and Tamil Nadu host integrated molding and fabrication ecosystems for export markets. Single-source vulnerability on German LFGB certification laboratories creates regulatory chokepoints extending product launch timelines. Distribution runs through specialized kitchenware retailers, direct-to-consumer e-commerce platforms, and mass-market big-box channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cookware accessories market sits in a post-pandemic home cooking cyclical recovery, with sustained enthusiast engagement and ceramic cookware adoption extending replacement cycles beyond historical patterns.
For Market Incumbents: Build certification moats through captive LFGB and FDA laboratory accreditation, insulating margin pools from compliance cost inflation. Incumbent leaders should deepen backward integration into platinum-cured silicone compound formulation and secure dedicated capacity in Yangtze River Delta manufacturing clusters to preempt emerging entrant cost advantages. For New Entrants and Emerging Players: Pursue ergonomic design patent filings targeting underpenetrated Indian metro-area households seeking mid-tier silicone utensil sets between mass-market plastic and premium stainless steel. New entrants should leverage direct-to-consumer channel infrastructure to bypass traditional retail slotting fees and capture margin through certification-transparent technical content marketing. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated producers with in-house laboratory certification over brand-dependent assemblers. Long-term viability hinges on regulatory compliance scalability across REACH, FDA, and emerging PFAS restriction jurisdictions. Acquisition targets should demonstrate dual-market certification capabilities spanning European and North American protocols. The signal to watch is LFGB laboratory capacity expansion announcements as inflection indicator for supply chain bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Platinum-Cured Silicone Formulation Migration | Medical-grade compound transfer enables FDA-REACH dual compliance and premium pricing capture. |
| Direct-to-Consumer Channel Expansion | E-commerce bypass eliminates distributor margin extraction and enables certification-transparent conversion. |
| LFGB Laboratory Accreditation Investment | In-house testing capacity shortens product launch timelines and creates regulatory entry barriers. |
| Ergonomic Design Patent Portfolio Build | OXO-style differentiation protects digital marketplace positioning against commodity competition. |
| PFAS-Free Formulation Pre-positioning | EPA and state-level chemical ban anticipation secures future compatibility claims for non-stick cookware accessories. |
Study Parameters
The analysis maps silicone formulation tiers, stainless steel grade specifications, and certification requirement clusters, each validated through procurement managers at commercial foodservice operators, category buyers at specialty kitchenware retailers, quality assurance directors at manufacturing facilities, and regulatory affairs specialists at compound suppliers. Primary interview findings triangulate against customs trade records, SAMR and FDA food-contact substance filings, LFGB laboratory accreditation databases, and SEC 10-K disclosures from listed conglomerates. Bottom-up unit economics and top-down market sizing converge through iterative reconciliation.
Assumptions held fixed include REACH chemical restriction enforcement timelines and ceramic cookware replacement cycle patterns, while petrochemical feedstock cost trajectories and e-commerce penetration rates varied across sensitivity scenarios. The projection horizon spans product type, material specification, usage application, and geographic manufacturing cluster dimensions. CAGRs derive from regression-adjusted historical volume trends and elasticity-adjusted price evolution. Forecast inputs incorporate LFGB laboratory capacity constraints and F-Gas Regulation spillover effects on fluoropolymer compatibility claims.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and freight rate volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and supply chain reconfiguration timelines. Cross-checking against Nielsen retail audit data and customs export volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
United Kingdom Kitchen Appliances Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Electric Corkscrew Market