
 Europe Household Electric Grills Market | 2026-2036
Europe Household Electric Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Household Electric Grills Market Foresight
Smart temperature control and connected cooking interfaces is tilting product development toward precision-heat appliances that sync with mobile apps for recipe-guided grilling. Groupe SEB leverages its Tefal brand heritage to dominate the indoor segment across French and Benelux retail channels. Weber-Stephen Products anchors its European position through premium outdoor electric lines designed for balcony-compliant operation in dense German and Austrian cities. Philips Domestic Appliances competes on smoke-reduction technology, targeting apartment regulators in Amsterdam and Copenhagen with dishwasher-safe removable plate systems.
Europe household electric grills are self-contained countertop or built-in cooking appliances that convert electrical resistance into radiant and convective heat, typically operating between 1,500 and 2,500 watts with die-cast aluminum or ceramic-coated cooking surfaces reaching temperatures of 230–300°C for searing proteins and vegetables without open flame. Their primary purpose is to replicate charcoal or gas grilling within fire-code-restricted residential environments where combustion-based cooking is prohibited or impractical. Indoor grills with smoke-free technology and adjustable temperature controls command the widest margin pools, as consumers trade up from basic contact grills to sensor-regulated models that reduce grease flare-up and odor infiltration. Portable grills represent the fastest-growing structural category, fueled by Nordic and Alpine consumers seeking camping-compatible and second-home solutions that operate from standard 230V European outlets.
CE marking under the EU Low Voltage Directive and Ecodesign Framework establishes mandatory energy efficiency and electrical safety baselines for all electric grills sold within the single market, while national implementations such as Germany's BSI-tested GS certification and France's NF mark create additional compliance layers that filter out low-cost non-European imports. The EU F-Gas Regulation indirectly bolsters electric grill demand by restricting hydrocarbon refrigerants and combustion fuels in residential equipment, pushing consumers toward plug-in alternatives. Stakeholders must monitor the EU's right-to-repair and ecodesign expansion for small household appliances, as forthcoming spare parts availability mandates and repairability scoring will reshape product architecture and after-sales economics across the value chain.
Market Dynamics
Apartment-dwelling urban households across Germany and France are compressing demand toward compact, balcony-compliant electric grills as municipal fire codes tighten and living spaces shrink below 50 square meters.
Growth Catalysts
- EU Ecodesign Directive:Mandatory energy efficiency baselines for small household appliances are filtering out inefficient imports and creating shelf space for compliant electric grill models in French and Dutch retail channels.
- F-Gas Regulation phase-out:Restrictions on hydrocarbon refrigerants and combustion fuels in residential equipment are pushing consumers toward plug-in cooking alternatives across Austria and Belgium.
- Smoke-reduction technology:Advanced grease-management systems and ceramic-coated plates are expanding addressable demand among apartment regulators in Amsterdam and Copenhagen who previously banned indoor grilling.
Market Restraints
- Aluminum die-cast input costs:Volatility in primary aluminum pricing from European smelters is squeezing margin pools for mid-tier grill manufacturers serving price-sensitive Benelux consumers.
- CE marking complexity:Layered national certifications including Germany's GS mark and France's NF certification create compliance friction that delays product launches by 4-6 months for non-European suppliers.
- Charcoal nostalgia:Persistent preference for open-flame flavor among Southern European consumers limits electric grill penetration in Spanish and Italian outdoor cooking segments.
Strategic Opportunities
- Nordic camping compatibility:Portable electric grills operating from standard 230V outlets are capturing second-home and cabin demand across rural Sweden and Finland where propane transport is restricted.
- EU right-to-repair expansion:Forthcoming spare parts availability mandates for small household appliances will reward modular grill architectures with extended after-sales revenue streams.
- Smart kitchen convergence:Integration of temperature sensors with mobile recipe applications is creating premium price tiers for tech-forward urban couples in Berlin and Munich.
Industry Challenges
- Embedded software certification:Connected grill interfaces requiring cybersecurity validation under the EU Cybersecurity Act are extending development timelines for WiFi-enabled product lines.
- Cross-border warranty fulfillment:Fragmented national repair networks complicate after-sales service for direct-to-consumer brands scaling across German, Austrian, and Swiss markets simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Household Electric Grills Market |
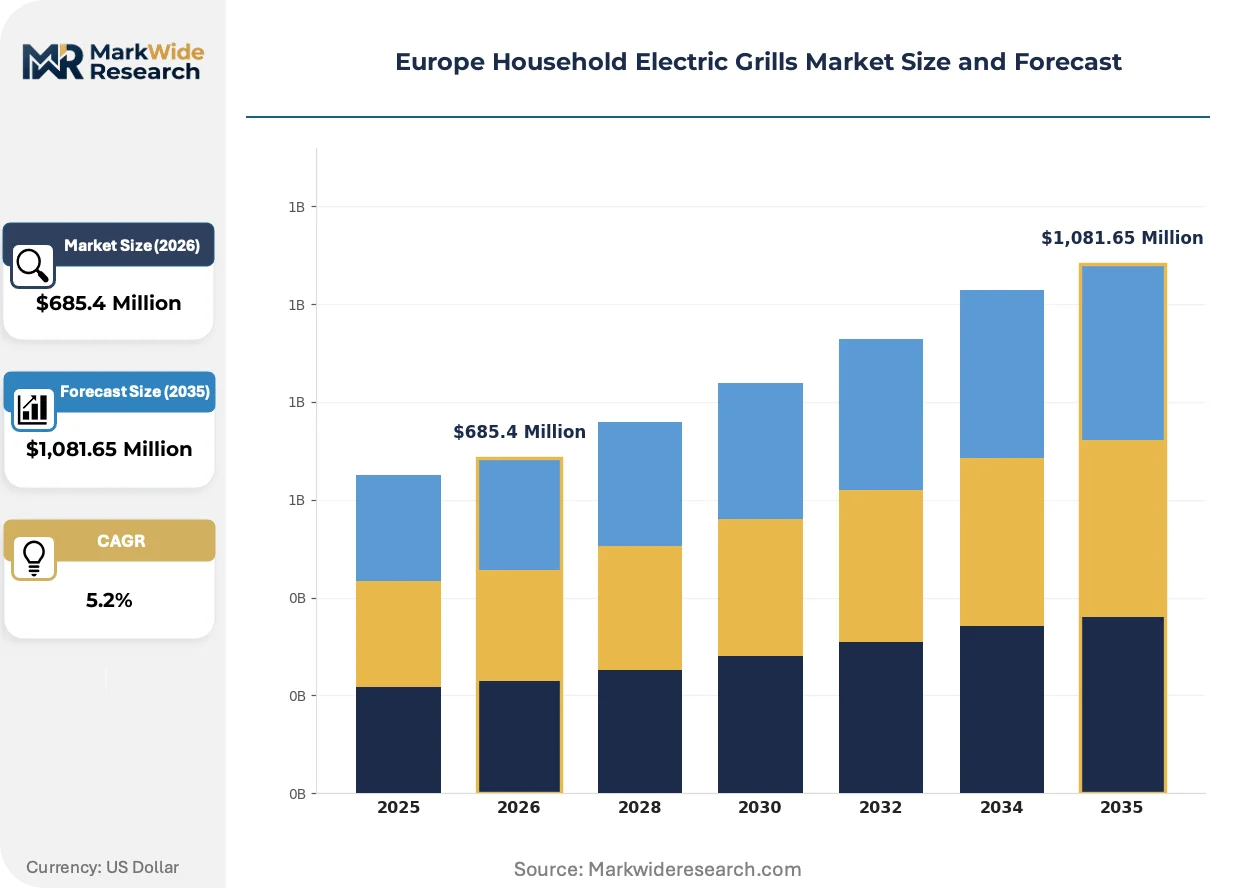
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Grills, Outdoor Grills, Portable Grills, Built-in Grills Feature: Non-Stick Coating, Adjustable Temperature, Removable Plates, Smoke-Free Technology End User: Families, Singles, Roommates, Cooking Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Home Improvement Stores |
| Companies Covered | Weber-Stephen Products, Alpina, Philips Domestic Appliances, Bull Europe, Elangrill, Groupe SEB, Kenyon, Lynx Grills, Spectrum Brands, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Household Electric Grills Market Shifts & Advancements
Product development is pivoting toward precision-heat appliances that synchronize cooking parameters with digital recipe platforms, compressing the traditional gap between amateur and consistent results.
Ceramic non-stick coatings are migrating from premium outdoor gas grills into sub-200 euro electric countertop models. Urban renters in Paris and Lyon are adopting these surfaces for dishwasher-safe maintenance. The shift is compressing replacement cycles for traditional Teflon-plated contact grills while expanding margin pools for die-cast aluminum suppliers.
The EU F-Gas Regulation is accelerating combustion equipment phase-outs across residential sectors. Equipment distributors in Vienna and Hamburg are reallocating shelf space from propane accessories toward electric alternatives. German retailers report strongest inventory turns for balcony-compliant electric lines in dense city-center locations.
Recipe-guided purchasing is displacing specification-based comparison among millennial households. Retailers in Amsterdam and Copenhagen are unbundling grills from bundled accessory packs and instead pairing hardware with subscription content libraries. The pattern concentrates among dual-income couples seeking weekday meal automation without culinary training.
Europe Household Electric Grills Market Segmentation
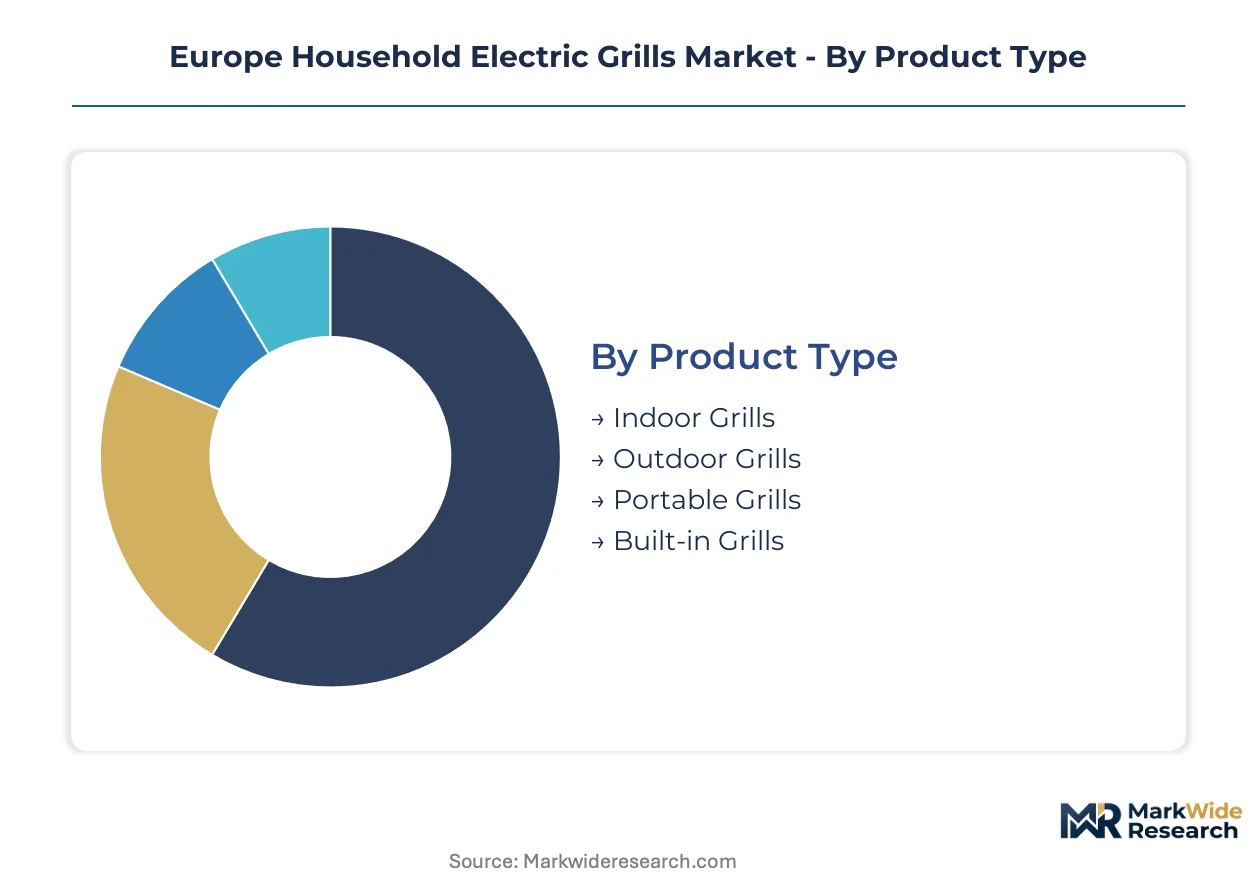
Segmentation in Europe's household electric grills market reveals how product architecture, user context, and purchase channels intersect with regulatory constraints and living-space economics. Each dimension carries distinct margin profiles and replacement-cycle dynamics that shape manufacturer portfolio decisions.
Product Type:
Replacement cycles stretch from 3 years for basic contact units to 8-plus years for built-in installations, creating divergent revenue recognition patterns across the value chain.
- Indoor Grills:Compact countertop units with die-cast aluminum plates and integrated drip trays dominate apartment kitchens across Paris and Berlin. Smoke-reduction systems from Philips and Tefal command premium positioning among Amsterdam regulators who enforce strict indoor air quality codes.
- Outdoor Grills:Balcony-compliant electric units with weather-resistant housings and 2,000-plus watt elements capture German and Austrian urban demand where municipal fire codes prohibit propane. Weber-Stephen anchors this segment through retail partnerships in dense city-center locations.
- Portable Grills:Lightweight 1,500-watt units with folding legs and carry cases serve Nordic camping and second-home markets. Swedish and Finnish consumers drive adoption where propane transport faces seasonal restrictions.
- Built-in Grills:Flush-mount countertop or kitchen-island installations with hardwired 230V connections target renovation projects in Dutch and Belgian new-build apartments. Extended replacement cycles compress annual unit sales while expanding installation-service revenue pools.
Indoor grills dominate installed base. Portable grills are where expansion concentrates.
Feature:
Cost tiers separate entry-level single-function units from sensor-equipped premium lines that integrate with recipe platforms and home automation systems.
- Non-Stick Coating:Ceramic and diamond-infused surfaces migrating from outdoor gas equipment now command 40-plus euro premiums over standard Teflon in French retail. Lyon's rental market favors dishwasher-safe plates that reduce deposit disputes.
- Adjustable Temperature:PID-controlled heating elements with digital displays and probe compatibility enable precision searing for cooking enthusiasts in Munich and Copenhagen. These units carry 60-80 euro price premiums over basic thermostatic controls.
- Removable Plates:Dishwasher-safe cooking surfaces with click-release mechanisms address maintenance concerns among Amsterdam and Copenhagen apartment dwellers. This specification has become table stakes in Benelux retail channels.
- Smoke-Free Technology:Advanced grease-management systems with water-filled drip trays and catalytic filters expand addressable demand among previously excluded urban households. German retailers report strongest inventory turns for this specification in dense city locations.
Non-stick coating commands widest margin pools. Smoke-free technology is climbing the fastest.
End User:
Volume concentrates among households with compressed time budgets and limited culinary training, while enthusiast segments drive specification innovation that later diffuses to mass market.
- Families:Multi-plate contact grills with 4-plus serving capacity and rapid heat-up cycles serve weeknight protein preparation in suburban French and German households. Batch-cooking functionality commands 25-30 percent price premiums over couple-sized units.
- Singles:Compact single-plate designs with minimal footprint dominate studio apartments across Berlin, Vienna, and Copenhagen. This segment shows highest price elasticity and strongest promotional responsiveness.
- Roommates:Shared-purchase decisions favor mid-tier units with durable construction and clear maintenance protocols to reduce interpersonal friction. Dutch student housing cooperatives increasingly specify electric grills as standard amenities.
- Cooking Enthusiasts:Specification-focused buyers prioritize temperature precision, probe compatibility, and connected recipe platforms. Their purchase decisions influence retailer assortment and manufacturer R&D prioritization despite smaller absolute volume.
Families represent the deepest installed base. Singles are where volume expansion concentrates.
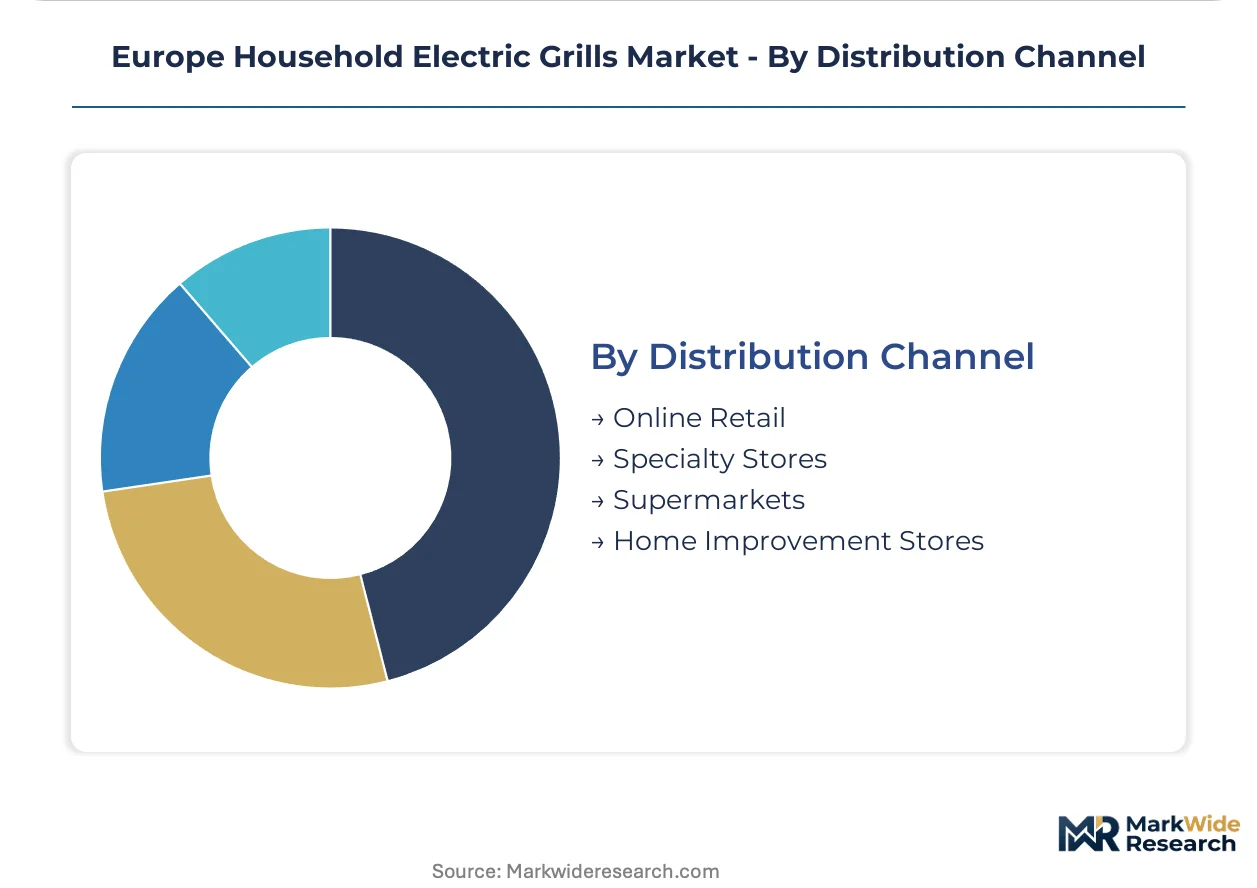
Distribution Channel:
Channel selection determines warranty fulfillment complexity and after-sales service economics, with direct-to-consumer models capturing enthusiast segments while mass retail dominates replacement purchases.
- Online Retail:Amazon and domestic platforms capture 35-plus percent of volume in Germany and France, with strongest performance in replacement purchases where consumers know exact specifications. Cross-border fulfillment creates warranty friction for direct-import brands.
- Specialty Stores:Kitchen equipment retailers in Amsterdam, Copenhagen, and Munich provide hands-on demonstration and installation coordination for built-in and premium portable lines. These channels carry 20-25 percent price premiums over online equivalents.
- Supermarkets:Mass-market penetration for basic contact grills occurs through Carrefour, Ahold Delhaize, and REWE networks. Seasonal promotional cycles concentrate volume in pre-summer and holiday gift windows.
- Home Improvement Stores:Leroy Merlin, OBI, and Bauhaus capture renovation-project demand for built-in and outdoor balcony installations. These channels bundle electrical accessories and installation guidance that pure retail lacks.
Supermarkets dominate unit volume. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export compact balcony-compliant electric grills to French and Benelux urban markets, with trade flows concentrating through Rotterdam and Antwerp distribution hubs serving dense apartment corridors.
Germany
Municipal fire codes in Berlin and Munich prohibit propane tanks on balconies above ground level. The F-Gas Regulation accelerates phase-out of hydrocarbon-fueled residential equipment. Bavarian retailers report strongest inventory turns for 2,000-watt weather-resistant electric lines in Munich's city-center locations.
France
Studio apartments in Paris and Lyon average under 35 square meters, compressing demand toward single-plate countertop units. The NF certification creates compliance friction for non-European imports. Île-de-France kitchen equipment retailers command 20-25 percent price premiums through hands-on demonstration and installation coordination.
Netherlands
Amsterdam housing cooperatives increasingly specify electric grills as standard amenities in student and young-professional units. REACH compliance for ceramic non-stick coatings filters out low-cost Asian imports. Randstad specialty stores pair hardware with subscription content libraries for recipe-guided purchasing.
Austria
Vienna's dense inner districts enforce strict indoor air quality codes that previously excluded grilling. The EU Ecodesign Directive mandates energy efficiency baselines that reshape retail shelf allocation. Equipment distributors in Salzburg and Innsbruck reallocate space from propane accessories toward electric alternatives.
Sweden
Nordic camping and second-home markets in rural Dalarna and Värmland drive portable electric grill adoption where propane transport faces seasonal ferry restrictions. Standard 230V outlet compatibility enables cabin installations without electrical retrofit. Stockholm-based online platforms capture replacement purchases with cross-border fulfillment friction.
Europe Household Electric Grills Market Competitive Landscape
On the supply side, the industry is moderately consolidated around diversified appliance conglomerates and specialized grilling equipment fabricators. Three strategic archetypes dominate: heritage cookware brands with indoor grill line extensions, outdoor equipment specialists pivoting to balcony-compliant electric formats, and diversified electronics manufacturers competing on smoke-reduction technology. Capacity expansion and portfolio diversification represent the dominant competitive moves, with players extending modular architectures to capture right-to-repair compliance advantages.
Within the heritage brand tier, Groupe SEB and Weber-Stephen Products exemplify contrasting geographic anchoring strategies. Groupe SEB leverages its French corporate base to dominate Benelux and domestic retail channels through established kitchen equipment relationships. Weber-Stephen Products occupies a position as the outdoor-specialist archetype, with its corporate naming indicating North American origins and European market penetration through balcony-compliant product lines. Philips Domestic Appliances represents the diversified electronics manufacturer archetype, competing on technical specifications rather than culinary heritage.
| Leading Market Players |
|---|
| Weber-Stephen Products |
| Alpina |
| Philips Domestic Appliances |
| Bull Europe |
| Elangrill |
| Groupe SEB |
| Kenyon |
| Lynx Grills |
| Spectrum Brands |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors carry die-cast aluminum components from European smelters to German assembly plants, with container cost volatility compressing margin pools for mid-tier manufacturers while amplifying price differentiation between CE-marked premium lines and uncertified imports in French retail channels.
Pricing Analysis
Sensor-equipped next-generation grills with PID temperature control and WiFi connectivity command 60-80 euro premiums over prior-generation thermostatic units, while basic contact grills without digital interfaces face price erosion in German supermarkets. Three-tier pricing structure across premium, standard, and economy levels separates Tefal's ceramic-coated indoor lines from Philips smoke-reduction systems and unbranded Asian imports. Cost compression in the economy tier intensifies because REACH compliance for non-stick coatings filters out low-cost suppliers. Singles in Berlin studio apartments exhibit highest price sensitivity, while cooking enthusiasts in Munich accept premium positioning for probe-compatible precision units.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier-financing arrangements for die-cast aluminum plate fabricators serving Weber-Stephen and Groupe SEB assembly operations. Manufacturing concentrates in Germany, France, and Poland for final assembly, while ceramic coating inputs draw from Italian specialty chemical suppliers and Chinese mineral processors. Single-source vulnerability persists for PID controller chipsets sourced from Taiwanese semiconductor fabricators. Distribution runs through Rotterdam and Antwerp distribution hubs serving dense Benelux apartment corridors, with home improvement stores capturing built-in installation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European household electric grills market sits at a platform-economics inflection as recipe-guided purchasing displaces specification-based comparison, with Philips and Tefal integrating hardware with subscription content libraries that lock in recurring engagement beyond the initial transaction.
For Market Incumbents: Harden modular grill architectures to capture EU right-to-repair compliance advantages before spare parts availability mandates reshape after-sales economics. Extend smoke-reduction R&D to defend against emerging Chinese entrants with lower-cost catalytic filter systems. Vertical integration into ceramic coating supply secures margin control as REACH compliance filters out third-party suppliers. For New Entrants and Emerging Players: Spanish and Italian outdoor cooking segments show persistent underpenetration due to charcoal nostalgia, creating white-space for hybrid electric-charcoal flavor replication technology. Nordic portable camping compatibility offers second entry path where propane transport restrictions limit incumbent gas-equipment dominance. Direct-to-consumer launch through Amsterdam and Copenhagen specialty retailers bypasses supermarket channel saturation. For Investors and Strategic Acquirers: The EU F-Gas Regulation reshapes the acquisition landscape by accelerating combustion equipment phase-outs and revaluing electric-alternative portfolios. Long-term viability centers on repairability-scoring compliance and connected-kitchen ecosystem integration rather than standalone hardware margins. Watch for EU Cybersecurity Act certification delays as signal for WiFi-enabled product line development bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Architecture Development | EU right-to-repair mandates reward designs with replaceable heating elements and controller boards. |
| Ceramic Coating Backward Integration | Captive supply of REACH-compliant non-stick surfaces filters out low-cost Asian import competition. |
| Recipe Platform Integration | Subscription content libraries lock in millennial households seeking weekday meal automation. |
| Balcony-Compliant Product Line Extension | Municipal fire codes in Berlin and Munich prohibit propane, expanding addressable urban demand. |
| Camping-Compatible Portable Launch | Swedish and Finnish seasonal propane restrictions create second-home market entry opportunity. |
Research Methodology
A standing panel of product development executives at heritage cookware brands, procurement leads at German retail chains, regulatory affairs specialists tracking EU Ecodesign implementation, and aftermarket service heads at diversified appliance conglomerates provided ongoing calibration. Primary fieldwork combined structured interviews with secondary validation through CE marking databases, customs records for die-cast aluminum trade flows, and F-Gas Regulation implementation tracking across member states. Bottom-up unit shipment modeling triangulated against top-down household penetration estimates for apartment-dwelling segments.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product architecture (indoor, outdoor, portable, built-in), feature tier (basic contact, sensor-equipped, connected), and distribution channel (online retail, specialty stores, supermarkets, home improvement). CAGRs derived from installed base replacement cycles and new household formation rates in dense urban corridors. Industry-specific inputs included REACH compliance cost trajectories for ceramic coatings and EU Cybersecurity Act certification timelines for WiFi-enabled interfaces.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese OEMs with automated die-casting operations would shift outcomes beyond modeled parameters. Macroeconomic deviation in aluminum pricing, regulatory acceleration of right-to-repair mandates, or breakthrough battery technology enabling cordless outdoor operation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
United States Electric Kettle Market
Appliances
North America Personal Care Appliances Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Small Electric Kettles Market
Appliances
Toaster Ovens Market
Appliances
Laundry Dryer Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
APAC White Goods Market
Appliances
Electric Rice Cooker Market
Appliances
Hairdryer Market
Appliances
Household Side by Side Refrigerator Market
Appliances
US Electric Rice Cooker Market
Appliances
Japan Laundry Appliances Market
Appliances
Laundry Appliances Market
Appliances
South Africa Laundry Appliances Market
Appliances
French Door Refrigerator Market