
 Asia Pacific Induction Hobs Market | 2026-2036
Asia Pacific Induction Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Induction Hobs Market Outlook
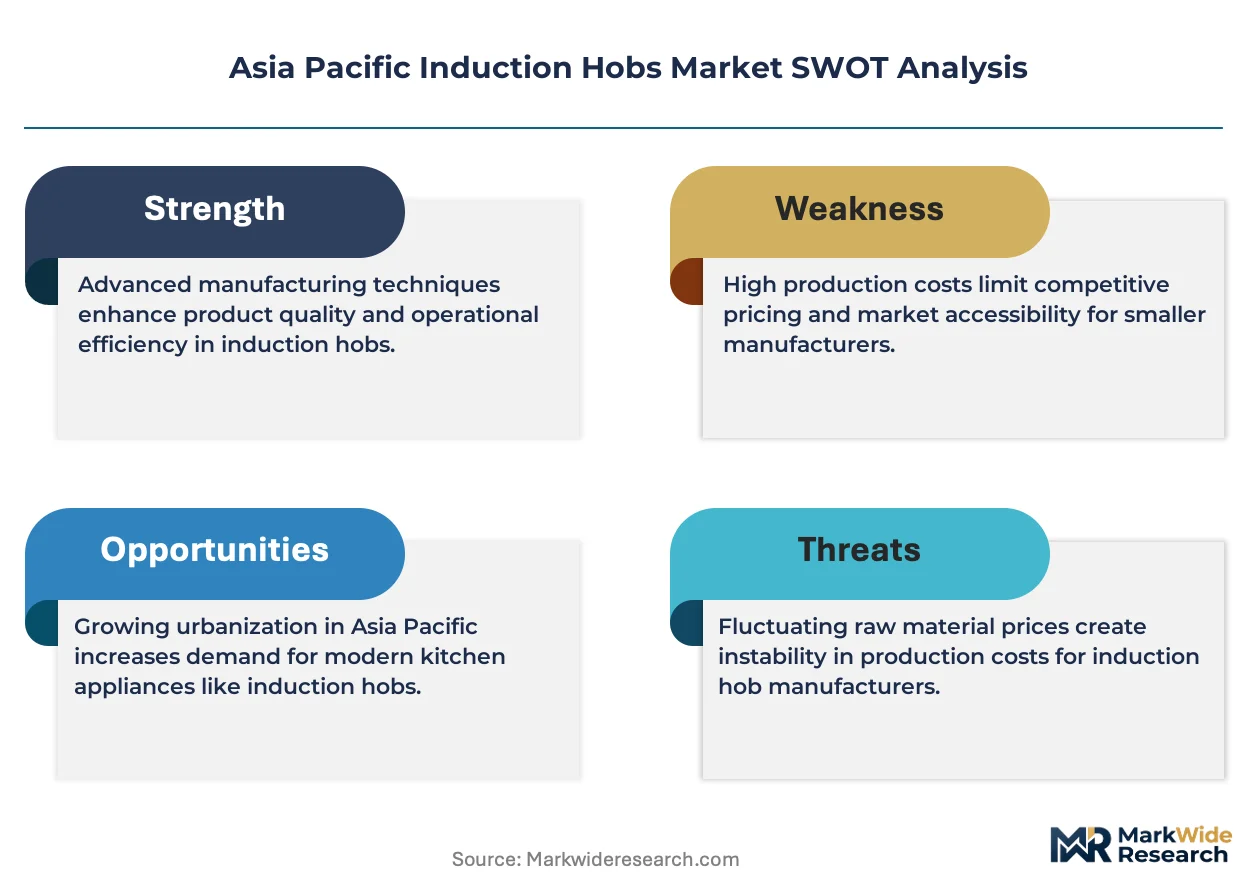
Residential buyer concentration in Southeast Asian metropolitan areas is consolidating around premium built-in induction hobs as apartment developers specify all-electric kitchens. Bosch leverages its German engineering pedigree to anchor specification-grade projects across Singapore and Hong Kong high-rises. Samsung competes through smart-home ecosystem integration, while Robam dominates Chinese domestic channels with localized burner configurations.
Asia Pacific induction hobs are electromagnetic cooking appliances operating at 20–50 kHz through copper coil assemblies beneath ceramic-glass surfaces, converting electrical energy directly into vessel heat without open flame. Built-in hobs capture the dominant margin pool as kitchen renovation cycles lengthen and homeowners prioritize seamless countertop integration. Smart technology variants with Wi-Fi connectivity and sensor-based temperature modulation represent the fastest-expanding technology segment, though manual controls sustain volume leadership in India's price-sensitive mass market.
China's MIIT enforces GB standards for electromagnetic compatibility and energy efficiency, while India's BIS certification mandates thermal performance testing for all imported cooking appliances. Australia's energy rating labels under the national Greenhouse and Energy Minimum Standards Act shape consumer comparison shopping and retailer assortment priorities. Stakeholders must monitor evolving refrigerant-phaseout timelines and building electrification codes across Australian states and Indian union territories to anticipate specification shifts before tender cycles finalize.
Market Dynamics
Building electrification mandates across Southeast Asian metropolitan corridors are compressing specification timelines for all-electric kitchen packages, forcing appliance manufacturers to synchronize product roadmaps with developer procurement cycles ahead of occupancy permits.
Growth Catalysts
- China's dual carbon goals:MIIT enforcement of GB energy-efficiency standards accelerates induction substitution for residential gas hobs in new construction and renovation pipelines.
- Apartment developer specifications:High-rise residential projects in Singapore and Hong Kong consolidate procurement around built-in induction systems as standard kitchen fit-outs.
- Sensor-based temperature modulation:Smart connectivity variants capture specification-grade demand from premium renovation segments seeking seamless countertop integration.
Market Restraints
- Copper coil assembly concentration:Electromagnetic component supply clusters in Chinese manufacturing zones expose procurement to regional logistics disruptions.
- Price sensitivity in mass-market India:Manual control variants sustain volume leadership as BIS certification costs compress margin pools for imported smart models.
- Legacy gas infrastructure:Established LPG distribution networks in Indonesian and Vietnamese residential markets delay full electrification conversion timelines.
Strategic Opportunities
- India's tier-two urban corridors:Underpenetrated cities beyond Mumbai and Delhi present white-space demand as BIS energy-efficiency mandates expand enforcement geography.
- Wi-Fi ecosystem convergence:Integration with home automation platforms enables specification capture in Australian urban renovation corridors targeting smart-ready dwellings.
- Greenhouse and Energy Minimum Standards Act:Australia's energy rating label system creates retailer-driven demand concentration around certified high-efficiency models.
Industry Challenges
- Electromagnetic compatibility certification:Divergent GB standards testing timelines between Chinese MIIT and Indian BIS create product launch synchronization friction.
- Skilled installation technician scarcity:Ceramic-glass surface mounting and copper coil calibration require certified trades absent in emerging Southeast Asian service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Induction Hobs Market |
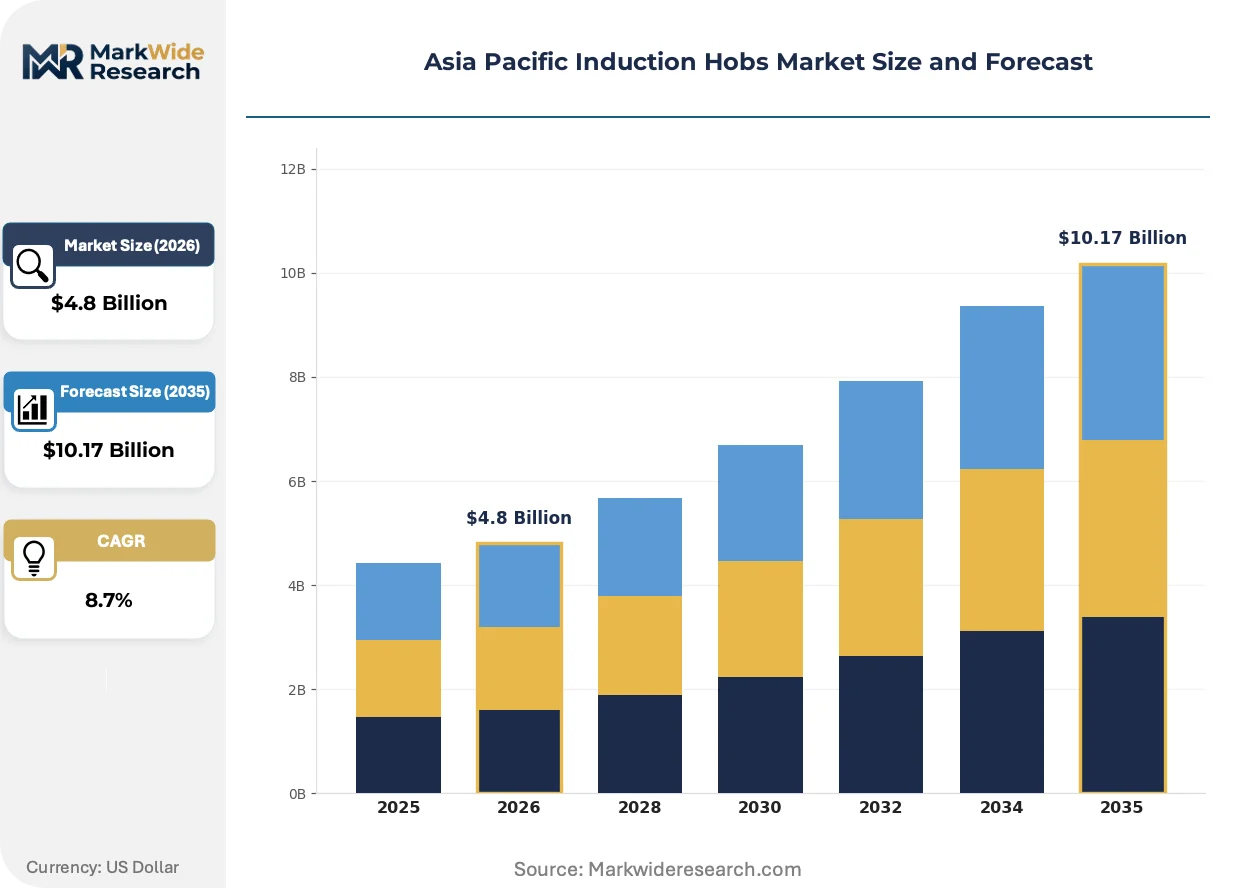
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in Hobs, Freestanding Hobs, Modular Hobs, Portable Hobs Technology: Touch Controls, Smart Technology, Manual Controls, Dual-Zone End User: Residential Use, Commercial Kitchens, Catering Services, Hotels Size: 30 cm, 60 cm, 70 cm, 90 cm |
| Companies Covered | Whirlpool Corporation, Bosch, Samsung, LG Electronics, Panasonic Corporation, Electrolux, Prestige, Fotile, Robam, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Induction Hobs Market Strategic Shifts
Induction technology is fragmenting competitive advantage away from pure hardware specifications toward integrated kitchen ecosystem control, as electromagnetic cooking becomes a data node within broader residential energy management architectures.
Sensor-based temperature modulation is decentralizing cooking control from manual dial interfaces toward automated heat management systems. Premium apartment developers in Singapore and Hong Kong specify these variants for smart-ready kitchen packages. The shift compresses specification power toward ecosystem-integrated suppliers capable of API-level building management system connectivity.
India's BIS certification mandates for thermal performance testing are restructuring import compliance workflows for all cooking appliances. Foreign manufacturers must establish local testing partnerships or face extended clearance timelines at Indian ports. The regulation most affects mid-market European brands without established Indian subsidiary laboratories.
Buyer concentration among Southeast Asian high-rise developers is compressing traditional distributor networks. Direct specification relationships between appliance manufacturers and property development groups displace retail channel influence in premium segments. This pattern concentrates most visibly in Bangkok and Jakarta condominium construction pipelines.
Asia Pacific Induction Hobs Market Segmentation
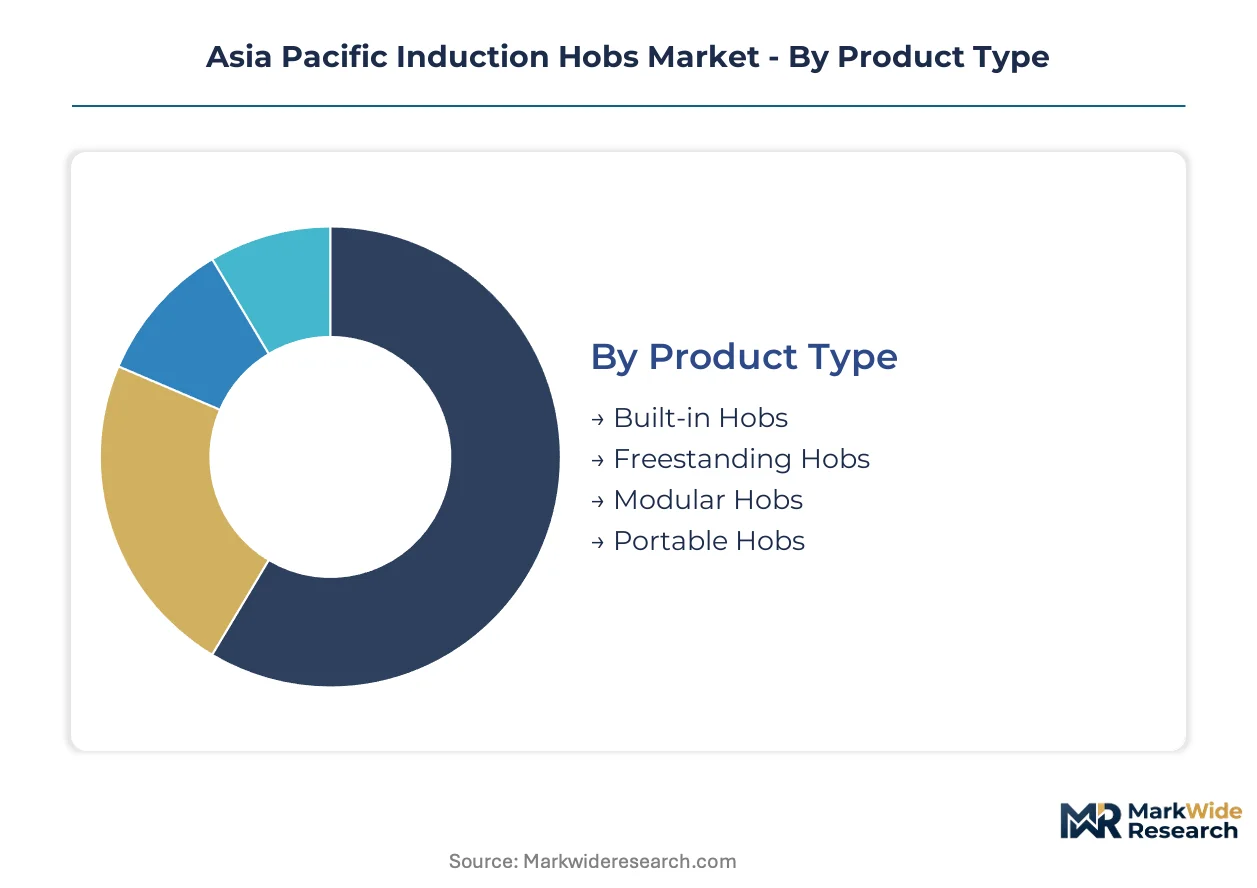
Segmentation reveals how procurement power concentrates across Asia Pacific's divergent kitchen renovation cycles. Developer specifications in Singapore and Hong Kong high-rises favor fundamentally different configurations than price-sensitive residential replacement markets in Indian tier-two cities.
Product Type:
Cost tier determines specification access, with premium built-in systems commanding project-level procurement while portable units address budget-constrained replacement demand.
- Built-in Hobs:These electromagnetic cooking systems integrate flush with ceramic-glass countertops through permanent cabinet mounting. Southeast Asian metropolitan developers specify these for all-electric kitchen packages in Singapore and Hong Kong high-rise residential towers.
- Freestanding Hobs:Self-contained units with integrated bases suit rental properties and temporary kitchen installations. Australia's urban renovation corridors favor these for retrofit applications where countertop modification is restricted by strata regulations.
- Modular Hobs:Component-based configurations allow burner zone customization. India's tier-one apartment renovations increasingly specify these for flexible spatial layouts.
- Portable Hobs:Compact single-zone units with plug-in operation address mass-market entry points. These dominate Indonesian and Vietnamese markets with limited residential electrification infrastructure.
Built-in hobs lead on scale; modular hobs lead on momentum.
Technology:
Application context separates automated ecosystem integration from basic thermal control, with commercial kitchens and premium residential segments diverging sharply on connectivity requirements.
- Touch Controls:Capacitive glass interfaces replace mechanical dials for seamless surface cleaning. These capture specification-grade demand across Australian urban renovation corridors targeting contemporary aesthetic standards.
- Smart Technology:Wi-Fi-enabled systems with sensor-based temperature modulation integrate with home automation platforms. These are gaining share fastest in Singapore and Hong Kong smart-ready dwelling specifications.
- Manual Controls:Rotary dial interfaces sustain volume leadership through lower manufacturing cost and repair simplicity. These dominate India's price-sensitive mass market where BIS certification costs compress smart model margins.
- Dual-Zone:Independent temperature management across paired cooking surfaces suits simultaneous multi-vessel preparation. Chinese domestic channels favor these for localized burner configurations addressing wok cooking traditions.
Manual controls lead on scale; smart technology leads on momentum.
End User:
Customer type dictates durability specifications and service network requirements, with commercial operators prioritizing thermal output consistency over residential buyers' aesthetic integration concerns.
- Residential Use:Individual household installations prioritize countertop integration and energy efficiency labeling. Australia's Greenhouse and Energy Minimum Standards Act shapes retailer assortment priorities for this segment.
- Commercial Kitchens:High-duty-cycle operations demand reinforced copper coil assemblies and extended warranty coverage. These concentrate in Bangkok and Jakarta food service clusters.
- Catering Services:Mobile food preparation requires portable or modular configurations with rapid deployment capability. India's event catering sector drives regional demand concentration.
- Hotels:Brand-standard kitchen fit-outs specify consistent electromagnetic performance across property portfolios. These procurement patterns concentrate most visibly in Southeast Asian hospitality development pipelines.
Residential use leads on scale; commercial kitchens lead on momentum.
Size:
Volume throughput and installation footprint create mutually exclusive optimization paths, with compact urban kitchens and professional food service occupying opposite ends of the dimensional spectrum.
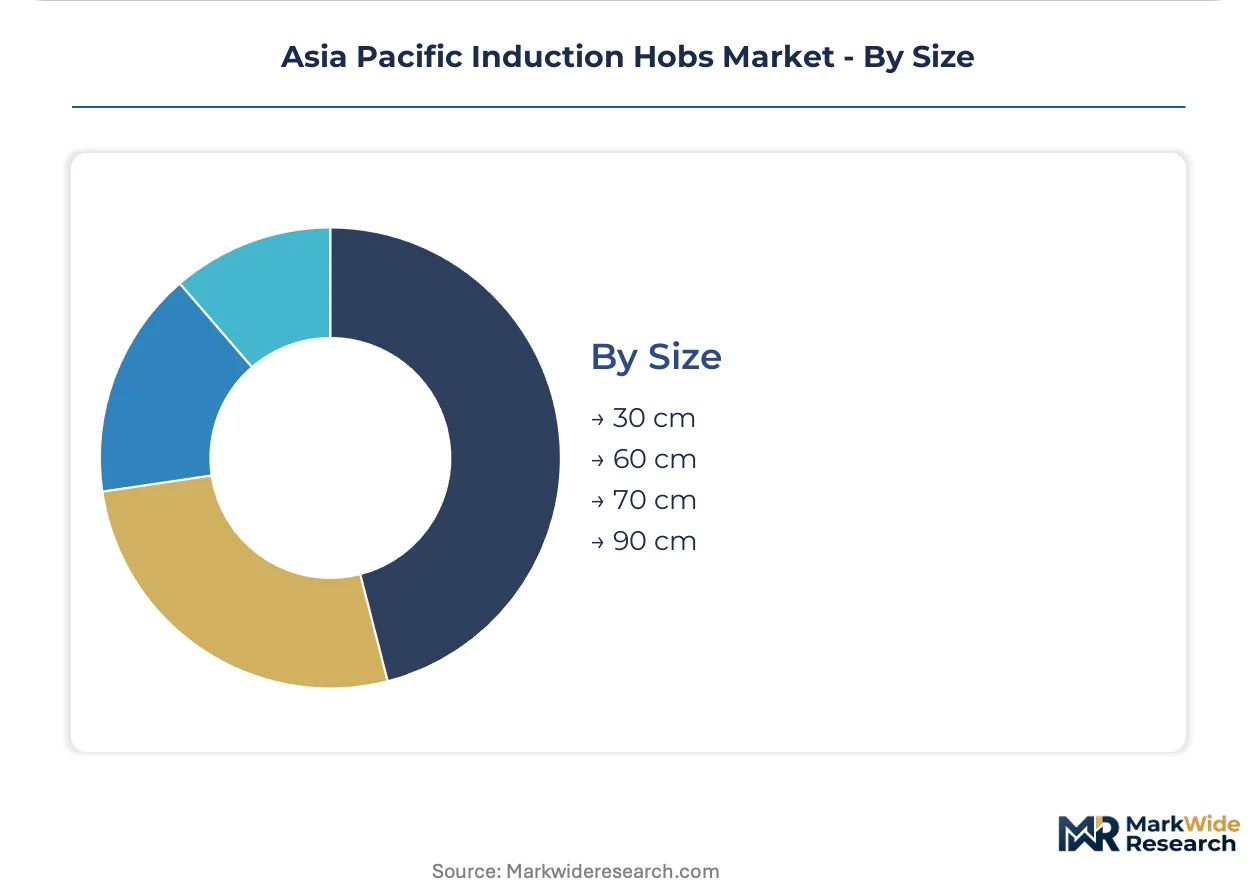
- 30 cm:Single-zone compact formats suit studio apartments and auxiliary cooking stations. These address space-constrained installations in Hong Kong micro-units and Singapore public housing renovations.
- 60 cm:Standard dual-zone configurations balance cooking flexibility with cabinet integration. These dominate replacement cycles across Australian and Indian urban residential markets.
- 70 cm:Extended dual-zone variants accommodate larger vessel diameters. Chinese domestic channels favor these for family-scale wok cooking requirements.
- 90 cm:Professional-grade triple or quad-zone systems serve high-throughput commercial operations. These concentrate in Bangkok and Jakarta hotel kitchen specifications.
60 cm leads on scale; 90 cm leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals accelerate induction substitution faster than India's BIS compliance timelines, creating divergent specification rhythms across the region's two largest residential markets.
China
MIIT enforcement of GB energy-efficiency standards and electromagnetic compatibility rules compresses product launch windows for domestic and foreign manufacturers. The Yangtze River Delta manufacturing cluster around Shanghai anchors copper coil assembly production, while Shenzhen-based developers specify smart-ready induction packages for high-rise residential towers.
India
BIS thermal performance testing mandates for imported cooking appliances restructure clearance workflows at Mumbai and Chennai ports. Maharashtra and Karnataka's tier-one apartment renovation corridors concentrate demand for modular hob configurations, though manual control variants sustain volume leadership in price-sensitive mass markets.
Australia
The national Greenhouse and Energy Minimum Standards Act shapes retailer assortment priorities through mandatory energy rating labels. New South Wales and Victoria's urban renovation corridors drive specification-grade demand for touch-control built-in systems targeting contemporary aesthetic standards in strata-regulated properties.
Singapore
Building electrification mandates for new high-rise residential developments consolidate procurement around all-electric kitchen packages. The Housing Development Board's renovation programs and private condominium developers specify premium built-in induction systems as standard fit-outs across metropolitan construction pipelines.
Thailand
Bangkok's condominium construction pipeline concentrates specification power among property development groups, displacing traditional retail channel influence. The Metropolitan Electricity Authority's building codes and hospitality sector procurement for hotel kitchen fit-outs drive commercial-grade demand in the capital region.
Asia Pacific Induction Hobs Market Competitive Environment
Chinese producers anchor one tier; German and Korean specialists hold specification-grade positions in premium segments. The vendor base fragments across three strategic tiers: ecosystem-integrated electronics conglomerates, engineering-pedigree appliance specialists, and domestic-market-focused manufacturers with localized burner configurations. Consolidation pressure concentrates most visibly in Southeast Asian metropolitan procurement, where direct developer relationships displace distributor networks. Competitive moves center on smart-home API integration and backward integration into copper coil assembly production.
Within the ecosystem-integrated tier, Samsung and LG Electronics exemplify platform convergence strategies, anchoring specification capture through home automation connectivity. Bosch occupies a position representing German engineering-pedigree positioning in high-rise developer procurement. Robam sits within the domestic-specialist archetype, leveraging localized product configurations for Chinese market penetration.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Bosch |
| Samsung |
| LG Electronics |
| Panasonic Corporation |
| Electrolux |
| Prestige |
| Fotile |
| Robam |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists across China's Yangtze River Delta manufacturing belt anchor copper coil assembly production, translating captive component supply into pricing discipline that resists margin erosion from Indian BIS certification cost absorption.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for entry-level portable hobs, compressing margins for manual-control variants. Pricing stratifies across premium smart-ready systems, standard touch-control built-ins, and economy portable units. Cost compression in India's mass market intensifies because BIS thermal testing mandates inflate landed costs for imported smart models. Developer specifications in Singapore and Hong Kong exhibit lowest price sensitivity, while Indonesian residential replacement buyers drive hardest bargain negotiations.
Supply Chain Analysis
India's phased domestic-content mandates for government procurement contracts are reshaping sourcing patterns for copper coil assemblies and ceramic-glass surfaces. Manufacturing concentrates in China, Vietnam, and Thailand. Electromagnetic component supply draws from Chinese industrial zones, Japanese precision ceramics producers, and Korean semiconductor foundries. Single-source vulnerability concentrates in Yangtze River Delta copper processing. Distribution runs through direct developer relationships in Southeast Asian metropolitan corridors, supplemented by appliance retailer networks in Australia and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-based temperature modulation adoption concentrates procurement power among ecosystem-integrated suppliers, expanding premium-tier margin pools as manual-control volume stagnates in price-sensitive segments.
For Market Incumbents: Acquire certified installation technician networks to address scarcity constraining Southeast Asian service coverage. Deepen backward integration into copper coil winding operations to mitigate Yangtze River Delta logistics exposure. Fortify direct specification relationships with Bangkok and Jakarta condominium developers before retail channel displacement accelerates.
For New Entrants and Emerging Players: Begin with modular hob configurations targeting India's tier-two urban corridors where BIS enforcement geography is expanding. Penetrate Australian strata-regulated renovation segments through touch-control built-in systems compliant with Greenhouse and Energy Minimum Standards Act labeling. Leverage local testing partnerships to compress Indian port clearance timelines.
For Investors and Strategic Acquirers: Home automation platform operators are the most active acquirer in this space, seeking API-compatible cooking appliance specialists. Five-to-ten year viability hinges on ecosystem integration depth rather than hardware specifications alone. Monitor Australian state-level building electrification code adoptions as inflection indicator for specification-grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Home API Integration | Enables specification capture in Singapore and Hong Kong smart-ready dwelling developments. |
| Backward Integration into Copper Coil Production | Secures captive supply from Yangtze River Delta electromagnetic component clusters. |
| Local Testing Partnership Establishment | Compresses BIS clearance timelines at Mumbai and Chennai ports for imported models. |
| Direct Developer Relationship Cultivation | Displaces traditional distributor networks in Bangkok and Jakarta condominium pipelines. |
| Sensor-Based Temperature Modulation Launch | Captures premium renovation demand seeking automated heat management systems. |
Study Parameters
Direct dialogue with appliance manufacturer product managers, high-rise developer procurement officers, certified installation technicians, and BIS compliance consultants grounded qualitative insights. Secondary validation drew from MIIT GB standard filings, Australian Greenhouse and Energy Minimum Standards registry data, Indian customs import records, and Singapore Housing Development Board tender documentation. Bottom-up unit shipment estimates triangulated against top-down construction pipeline valuations across metropolitan corridors.
Segmented outputs across product type, control technology, end-user category, and dimensional format fed into analytical framework spanning the projection horizon. CAGRs derived from regression against historical renovation cycle lengths, electrification mandate adoption curves, and smart-home penetration trajectories. Copper coil pricing volatility and BIS certification timeline distributions served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt refrigerant-phaseout timeline accelerations, sovereign trade restriction impositions, and pandemic-scale logistics disruptions. Forecasts reflect documented assumptions about electrification policy continuity and ceramic-glass surface supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
US Household Coffee Machine Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
Small Kitchen Appliances Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Electric Corkscrew Market