
 United States Small Kitchen Appliances Market | 2026-2036
United States Small Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United States Small Kitchen Appliances Market Analytics
Stainless steel is broadening its share in premium small kitchen appliances as manufacturers phase out lower-grade plastics to meet durability expectations and sustainability targets. Hamilton Beach leverages its domestic manufacturing footprint to sustain cost competitiveness in the mass-market tier. SharkNinja operates an aggressive direct-to-consumer channel that controls pricing and captures first-party data across the blender and multi-cooker segments. SMEG USA positions its retro-styled lineup to dominate design-conscious urban kitchens with above-average margin profiles.
Small kitchen appliances encompass electrically powered countertop devices typically operating below 1,500 watts, designed for food preparation, beverage brewing, or cooking assistance in residential and light-commercial settings. These units incorporate heating elements, motorized blades, or pump mechanisms housed in thermoplastic or metal enclosures, with primary purpose centered on automating repetitive kitchen tasks to reduce manual labor and standardize output quality. The coffee maker category anchors volume given entrenched American caffeine rituals, while smart appliances represent the fastest-expanding technology segment as Wi-Fi connectivity and app-based recipe integration reshape replacement cycles. Energy-efficient designs command widening retail shelf space as utility rebate programs and revised DOE test procedures elevate efficiency visibility in purchase decisions.
The Department of Energy administers minimum energy conservation standards under 10 CFR 430 that dictate standby power limits and active-mode efficiency thresholds for countertop cooking appliances. The Consumer Product Safety Commission enforces electrical safety requirements through UL 1082 and UL 1026 certifications that govern cord construction, heating-element isolation, and thermal cutoff performance. The Federal Trade Commission's EnergyGuide labeling mandates compel wattage disclosure and estimated annual energy cost visibility, shaping comparative shopping behavior. Stakeholders must monitor evolving DOE rulemaking timelines and state-level appliance efficiency preemptions to align inventory planning with compliance phase-ins.
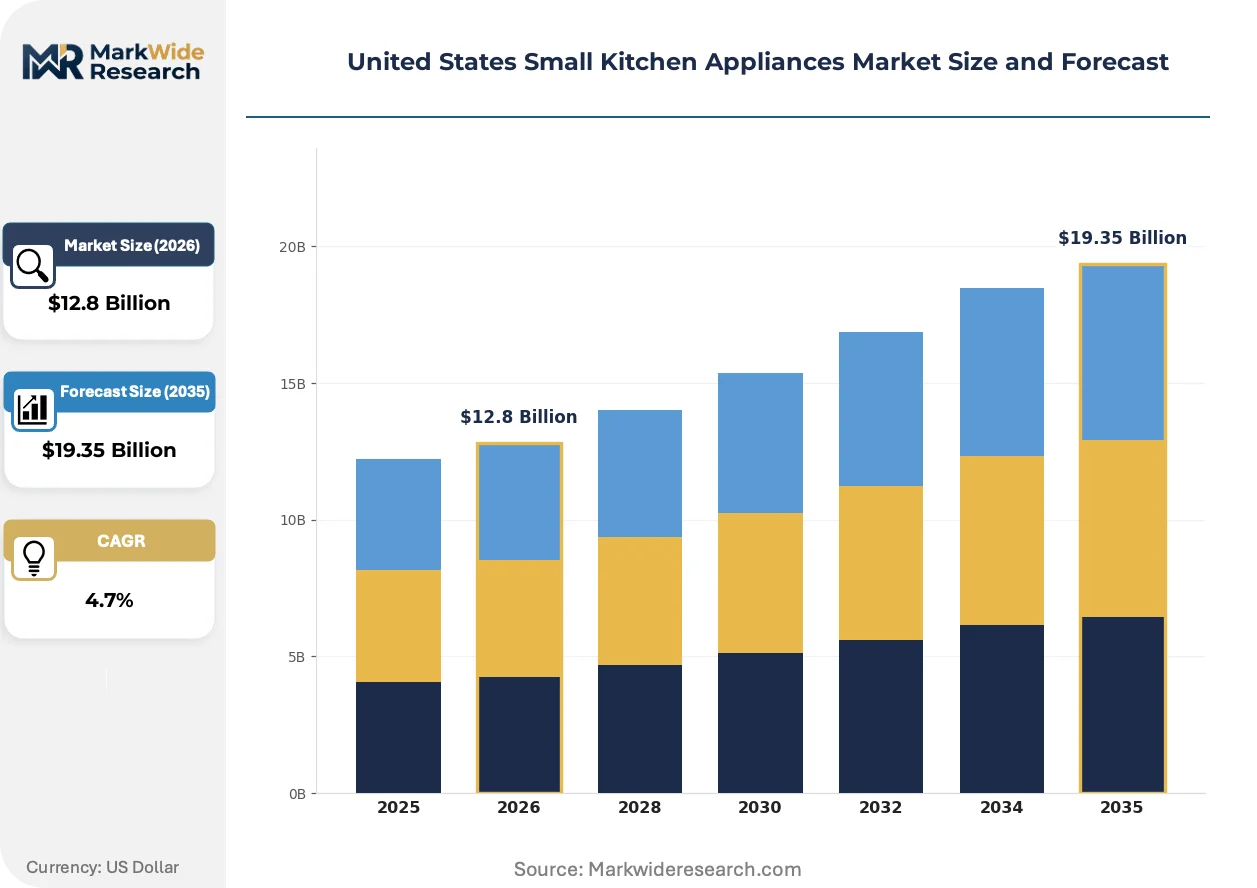
Market Dynamics
The Department of Energy's 10 CFR 430 efficiency standards are compressing power-consumption ceilings and forcing manufacturers to redesign thermal management systems, heating elements, and standby circuits across countertop cooking categories.
Growth Catalysts
- Urban Millennial Household Formation:California and Texas housing starts outpace national averages, concentrating demand for compact, smart-enabled devices in metro corridors.
- DOE Rebate Amplification:Utility-sponsored efficiency programs elevate EnergyGuide-labeled products in retail visibility, accelerating replacement cycles for aging units.
- Wi-Fi Module Cost Collapse:Embedded connectivity hardware now ships at mass-market price points, enabling app-integrated recipe automation across blender and multi-cooker segments.
Market Restraints
- Copper and Rare-Earth Magnet Volatility:Motor assemblies and heating elements face input cost pressure from concentrated Chilean copper and Chinese rare-earth processing.
- Standby Power Floor Technical Limits:Physics constraints on transformerless designs block further DOE threshold reductions without semiconductor architecture overhauls.
- Single-Source Wi-Fi Chip Dependency:Connectivity modules concentrate among three semiconductor foundries, creating supply vulnerability for smart appliance lines.
Strategic Opportunities
- Texas Suburban Expansion Corridors:Dallas-Fort Worth and Austin metro kitchen renovation spending exceeds national per-capita rates by substantial margins.
- Voice-Assistant Integration Convergence:Alexa and Google Home APIs are converging with appliance firmware, creating hands-free operation as a premium tier differentiator.
- Direct-to-Consumer Channel Infrastructure:First-party data capture through owned e-commerce bypasses retail margin stacking and enables dynamic warranty pricing.
Industry Challenges
- UL 1082 Thermal Cutoff Redesign Cycles:Updated cord-construction and heating-element isolation standards demand 18-24 month recertification timelines.
- Legacy Inventory Obsolescence:Pre-DOE-rulemaking stock requires discount-driven clearance, compressing margin recovery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Small Kitchen Appliances Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blenders, Toasters, Coffee Makers, Food Processors Technology: Smart Appliances, Traditional Appliances, Energy-Efficient Designs, Manual Controls End User: Households, Restaurants, Cafes, Catering Services Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Ninja (SharkNinja, LLC), Hamilton Beach, GE Appliances (a Haier Company), Panasonic Corporation, Cuisinart, SMEG USA, Inc, Tefal S.A.S. (T-fal), Bella Housewares (Gather), Whirlpool Corporation (KitchenAid), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Small Kitchen Appliances Market Evolving Landscape
Connectivity, materials science, and regulatory disclosure requirements are converging to redefine product development cycles and retail positioning across the countertop appliance landscape.
Induction heating modules are converging with compact form factors previously dominated by resistive coil designs. Urban apartment dwellers in California metros are adopting single-burner induction cooktops at accelerating rates. This convergence is compressing the addressable market for traditional hot plate manufacturers while elevating thermal efficiency as a purchase criterion.
The Federal Trade Commission's EnergyGuide labeling mandates now require estimated annual operating cost visibility alongside wattage disclosure. Retailers must display this data in comparative formats, reshaping shelf-space negotiations. The coffee maker category faces the most acute pressure, as high-wattage brewing cycles translate directly into visible cost penalties.
Millennial buyers are unbundling after-sales service expectations from initial purchase decisions, treating extended warranties as separate evaluation events. Big-box retail channels are losing attachment-rate leverage as manufacturer-direct registration portals capture post-purchase engagement. This behavioral shift is most pronounced in Texas and Florida markets, where housing turnover rates sustain higher replacement frequencies.
United States Small Kitchen Appliances Market Segmentation
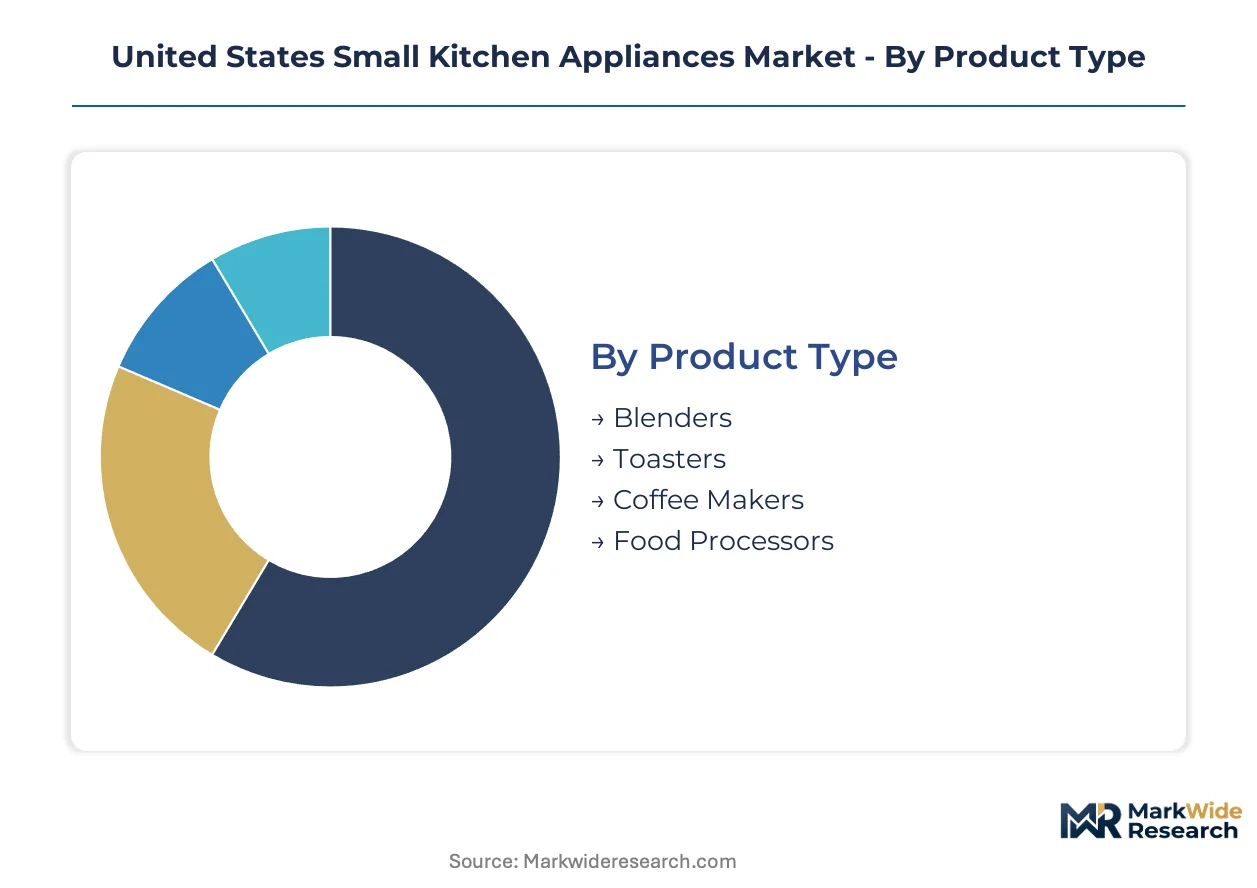
Segmentation in the United States small kitchen appliances market reveals how power ratings, connectivity integration, and channel economics fragment demand across countertop categories. Manufacturers must align thermal engineering and semiconductor architecture with distinct use-case specifications to capture volume and margin simultaneously.
Product Type:
Integration depth varies sharply across countertop formats, with standalone motorized units demanding higher wattage circuits than enclosed heating systems.
- Coffee Makers:Enclosed brewing systems with resistive heating elements operating between 800-1500 watts, featuring thermal carafes or single-serve pod compatibility. California metro households anchor replacement demand as kitchen renovation spending concentrates in Los Angeles and San Francisco corridors, with DOE EnergyGuide labeling elevating efficiency visibility in purchase decisions.
- Blenders:High-torque motorized assemblies with stainless steel blade clusters and variable-speed pulse controls, typically drawing 500-1400 watts during ice-crushing cycles. Texas suburban expansion in Dallas-Fort Worth and Austin metros sustains above-average adoption for smoothie-preparation routines, with Wi-Fi module integration enabling app-based recipe automation across premium tiers.
- Toasters:Compact resistive heating chambers with quartz or mica element configurations, generally operating below 1200 watts. Slot configurations and bagel-mode circuitry differentiate price tiers.
- Food Processors:Interchangeable blade systems with direct-drive motors housed in thermoplastic bases, designed for dough kneading and vegetable processing tasks. Bowl capacity and motor torque ratings segment commercial from residential specifications.
Coffee makers lead volumes today; blenders are gaining share fastest.
Technology:
Cost-tier stratification separates semiconductor-enabled connectivity from electromechanical simplicity, with efficiency certifications commanding retail shelf-space premiums.
- Smart Appliances:Embedded Wi-Fi modules and ARM-based microcontrollers enabling cloud recipe synchronization, firmware updates, and voice-assistant API integration. California and Texas urban millennial households concentrate demand as housing formation rates outpace national averages, with utility rebate programs amplifying retail visibility for connected EnergyGuide-labeled units.
- Energy-Efficient Designs:Transformerless standby circuits and induction heating modules engineered to DOE 10 CFR 430 thresholds, minimizing phantom load consumption. Texas metro corridors with elevated electricity rates show disproportionate adoption, with standalone induction cooktops displacing traditional resistive hot plates in apartment kitchens.
- Traditional Appliances:Electromechanical control interfaces without semiconductor connectivity, relying on bimetallic thermostats and analog timers. Price-sensitive mass-market segments sustain volume.
- Manual Controls:Purely mechanical actuation without powered assistance, encompassing hand-cranked or lever-operated devices. Specialty and emergency-preparedment niches retain limited demand.
Traditional appliances lead volumes today; smart-enabled designs are climbing the fastest.
End User:
Application intensity dictates duty-cycle specifications, with commercial environments demanding continuous-operation thermal management absent in residential designs.
- Households:Intermittent-use countertop devices with residential-grade cord construction and thermal cutoff ratings per UL 1082. California and Texas housing starts concentrate demand for compact, smart-enabled formats in metro corridors.
- Restaurants:NSF-certified commercial units with stainless steel enclosures, continuous-duty motors, and reinforced blade assemblies. High-throughput breakfast service drives blender and coffee maker specifications.
- Cafes:Specialized espresso and brewing equipment with precision temperature control and high-volume water reservoirs. Third-wave coffee culture elevates grind consistency and extraction pressure requirements.
- Catering Services:Portable, rapid-heat appliances with commercial power ratings and transport-safe enclosures. Event-frequency volatility demands rental-flexible procurement patterns.
Households lead volumes today; cafes are expanding most quickly.
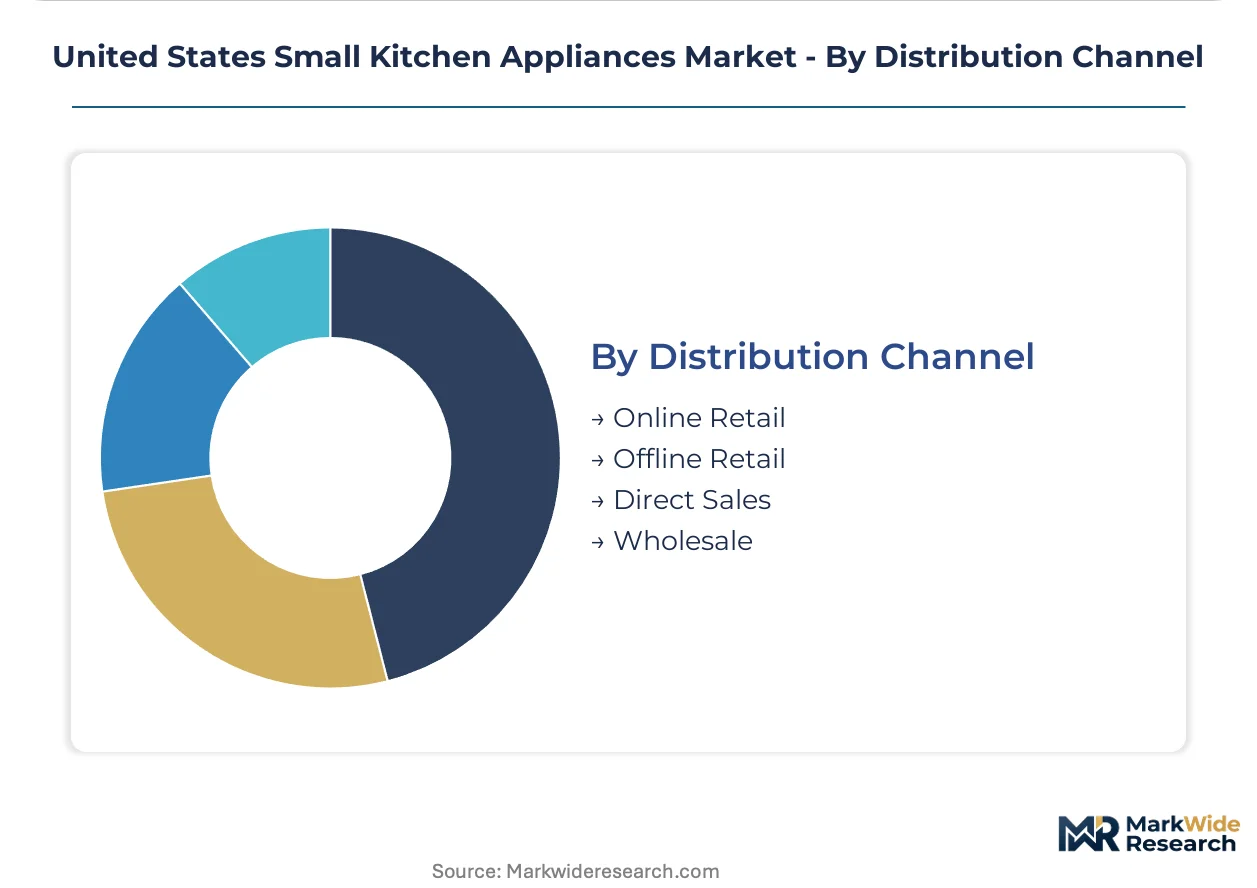
Distribution Channel:
Customer-type fragmentation separates data-capture economics from immediate fulfillment convenience, with channel choice correlating to warranty attachment and replacement frequency.
- Online Retail:Third-party marketplace and owned e-commerce platforms with algorithmic search placement and review-aggregate visibility. Texas and Florida markets show pronounced millennial preference for direct manufacturer registration portals, decoupling warranty decisions from initial purchase events.
- Direct Sales:Manufacturer-owned channels capturing first-party behavioral data and enabling dynamic warranty pricing. SharkNinja's blender and multi-cooker segments exemplify this model's margin and data advantages.
- Offline Retail:Big-box and specialty kitchen stores with tactile demonstration and immediate inventory takeaway. EnergyGuide label comparative displays reshape shelf-space negotiations under FTC mandates.
- Wholesale:Volume procurement for commercial end-users and institutional buyers, with specification customization and extended payment terms. Restaurant supply distributors dominate this tier.
Offline retail leads volumes today; direct sales are ascending the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors domestic small kitchen appliance demand through suburban housing formation and elevated kitchen renovation spending. Texas and California metros concentrate replacement cycles as millennial household formation outpaces national benchmarks. Regional performance fragments across electricity rate structures, building code stringency, and utility rebate program generosity.
California
Los Angeles and San Francisco corridors drive premium-tier adoption of smart-enabled and energy-efficient designs. The California Energy Commission's Title 20 appliance efficiency standards pre-empt federal baselines and accelerate obsolescence of high standby-power units. Sacramento's building electrification mandates are compressing demand for gas-adjacent countertop cooking formats.
Texas
Dallas-Fort Worth and Austin metros sustain above-average blender and multi-cooker penetration through smoothie-preparation routines and housing expansion. ERCOT grid volatility elevates consumer sensitivity to wattage disclosure under FTC EnergyGuide mandates. Houston's commercial foodservice density supports secondary demand for NSF-certified compact appliances.
Florida
Miami and Tampa housing turnover rates sustain higher replacement frequencies than national averages. The Florida Public Service Commission's utility rebate programs amplify retail visibility for EnergyGuide-labeled products. Orlando's vacation rental market creates niche demand for durable, compact formats suited to transient-occupancy kitchens.
New York Metro
Manhattan and Brooklyn apartment constraints favor compact induction cooktops and multi-function devices over single-purpose units. New York State's appliance efficiency standards align with DOE 10 CFR 430 thresholds while adding disclosure requirements. Westchester County's kitchen renovation spending concentrates demand for design-forward premium tiers.
Pacific Northwest
Seattle and Portland metros exhibit disproportionate adoption of connected appliances through tech-sector household income profiles. The Northwest Energy Efficiency Alliance's regional rebate programs elevate efficiency-certified product visibility. Boise's inbound migration flows are expanding addressable market footprint for mass-market smart-enabled formats.
United States Small Kitchen Appliances Market Competitive Landscape
Global majors compete with regional champions across channel architecture and price-tier positioning. The vendor base stratifies into three tiers: mass-market volume players, premium design specialists, and commercial-grade fabricators. Two strategic archetypes dominate—domestic manufacturers leveraging tariff-advantaged production footprints, and direct-to-consumer operators capturing first-party data through owned e-commerce infrastructure. Competitive moves concentrate on channel bypass strategies and voice-assistant API integration.
Among domestic mass-market specialists, Hamilton Beach exemplifies tariff-resilient manufacturing positioning through its US production footprint. SharkNinja anchors the direct-to-consumer archetype with aggressive channel control and data-capture infrastructure. SMEG USA occupies the design-premium tier, targeting margin-above-volume positioning in urban kitchen renovation channels.
| Leading Market Players |
|---|
| Ninja (SharkNinja, LLC) |
| Hamilton Beach |
| GE Appliances (a Haier Company) |
| Panasonic Corporation |
| Cuisinart |
| SMEG USA, Inc |
| Tefal S.A.S. (T-fal) |
| Bella Housewares (Gather) |
| Whirlpool Corporation (KitchenAid) |
| Others |
Value Network & Pricing Analysis
Copper futures volatility on the London Metal Exchange cascades through motor assembly costs into three-tier pricing structure across premium, standard, and economy levels. Chinese rare-earth magnet processing concentration feeds into heating element pricing, compressing margins for manufacturers without captive supply arrangements.
Pricing Analysis
Input-cost pass-through from Chilean copper and transformer semiconductor shortages stratifies pricing across Wi-Fi-enabled smart tiers, UL-certified safety tiers, and basic electromechanical units. Brand premium and certification level separate SMEG's design-forward positioning from Hamilton Beach's mass-market cost leadership. Pricing pressure stems from DOE efficiency mandate compliance costs, with California and Texas utility rebate programs amplifying price sensitivity for EnergyGuide-labeled purchases among millennial first-time buyers.
Supply Chain Analysis
Wi-Fi module supply rests on Taiwanese and Chinese semiconductor foundries, with ARM-based microcontroller fabrication concentrated in South Korea. Copper rod and rare-earth magnet inputs draw from Chilean mining and Chinese processing operations. Single-source chip vulnerability creates supply chain risk for smart appliance lines. Distribution runs through big-box retail, direct-to-consumer portals, and commercial wholesale channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States small kitchen appliances market functions as a regulatory compounder where DOE 10 CFR 430 efficiency standards accelerate replacement cycles and reshape competitive economics.
For Market Incumbents: Deploy voice-assistant API integration as the primary lever against direct-to-consumer entrants capturing first-party data. Backward integration into domestic motor assembly mitigates copper price volatility exposure. Recertification investment for UL 1082 thermal cutoff standards defends shelf-space positioning against private-label challengers. For New Entrants and Emerging Players: Texas suburban renovation contractors represent an underserved buyer archetype with above-average per-capita kitchen spending and lower smart-appliance penetration than California metros. Voice-controlled compact induction cooktops target apartment-constrained New York and Pacific Northwest urban households. Go-to-market through contractor referral programs bypasses established retail gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic manufacturing footprint owners tariff-shielded from import cost volatility. Five-to-ten year viability hinges on DOE rulemaking pace and state-level efficiency preemption patterns. Watch California Energy Commission Title 20 amendments as inflection indicator for national regulatory trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | SharkNinja's first-party data capture bypasses retail margin stacking and enables dynamic warranty pricing. |
| Voice-Assistant API Integration | Alexa and Google Home firmware convergence creates hands-free operation as premium tier differentiator. |
| Domestic Manufacturing Footprint | Hamilton Beach's US production sustains cost competitiveness under tariff pressure and DOE compliance timelines. |
| Energy-Efficient Design Repositioning | Utility rebate program alignment elevates EnergyGuide-labeled products in California and Texas retail visibility. |
| Retro-Styled Premium Tier Introduction | SMEG USA's design-forward positioning captures above-average margins in urban kitchen renovation channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged product development directors at Hamilton Beach and SharkNinja, category buyers at major big-box retailers, DOE regulatory affairs specialists, and kitchen renovation contractors in Dallas-Fort Worth and Los Angeles corridors. Secondary validation drew from DOE 10 CFR 430 rulemaking dockets, FTC EnergyGuide labeling databases, UL certification registries, and Circana retail audit data. Bottom-up shipment modeling and top-down housing formation projections were triangulated against utility rebate program participation rates.
Comparable-period anchoring linked the projection horizon to historical replacement cycle patterns, housing start correlations, and efficiency standard phase-in timelines. The analytical framework modeled segmentation across product type, technology tier, end-user intensity, and distribution channel economics. CAGRs were derived from regression analysis of housing formation, renovation spending, and regulatory compliance cost trajectories. Wi-Fi module cost curves and copper price elasticity informed smart-appliance adoption assumptions.
Underlying measurement precision varies by segment; smart-enabled and energy-efficient categories carry tighter precision than traditional electromechanical units due to connected product registration data availability. Forecasts reflect assumptions about DOE rulemaking timelines, semiconductor supply normalization, and utility rebate program continuity. Copper price volatility, rare-earth export restrictions, and single-source Wi-Fi chip concentration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Russia Household Electric Grill Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
US Smart Oven Market