
 Europe Household Appliances Market | 2026-2036
Europe Household Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Household Appliances Market Insights
Asset-light leasing and pay-per-use financing is fragmenting competitive access across the Europe household appliances sector, enabling challenger brands to scale without heavy balance-sheet commitments. Robert Bosch GmbH leverages its captive financing arm to lock in multi-year residential contracts across German metropolitan clusters. Electrolux AB anchors its position through specialized built-in kitchen portfolios that command specification control in Nordic renovation channels. BSH Hausgeräte GmbH sustains manufacturing scale advantages at its German and Polish production sites, competing on throughput reliability for mass-market dishwasher and refrigeration lines.
Europe household appliances encompass electrically powered domestic machines designed for food preservation, textile cleaning, meal preparation, and climate management, typically operating at 220-240V/50Hz with energy efficiency ratings scaled from A to G under EU standardized testing protocols. Refrigerators dominate value contribution due to compressor technology complexity and replacement cycle compression from Ecodesign mandates, while smart appliances represent the fastest structural expansion as Wi-Fi module integration and energy management APIs become baseline expectations in premium residential segments. Washers retain mature volume characteristics across Southern European markets where front-loading penetration nears saturation, though heat-pump dryer attachments are displacing vented alternatives in German and Dutch new-build specifications.
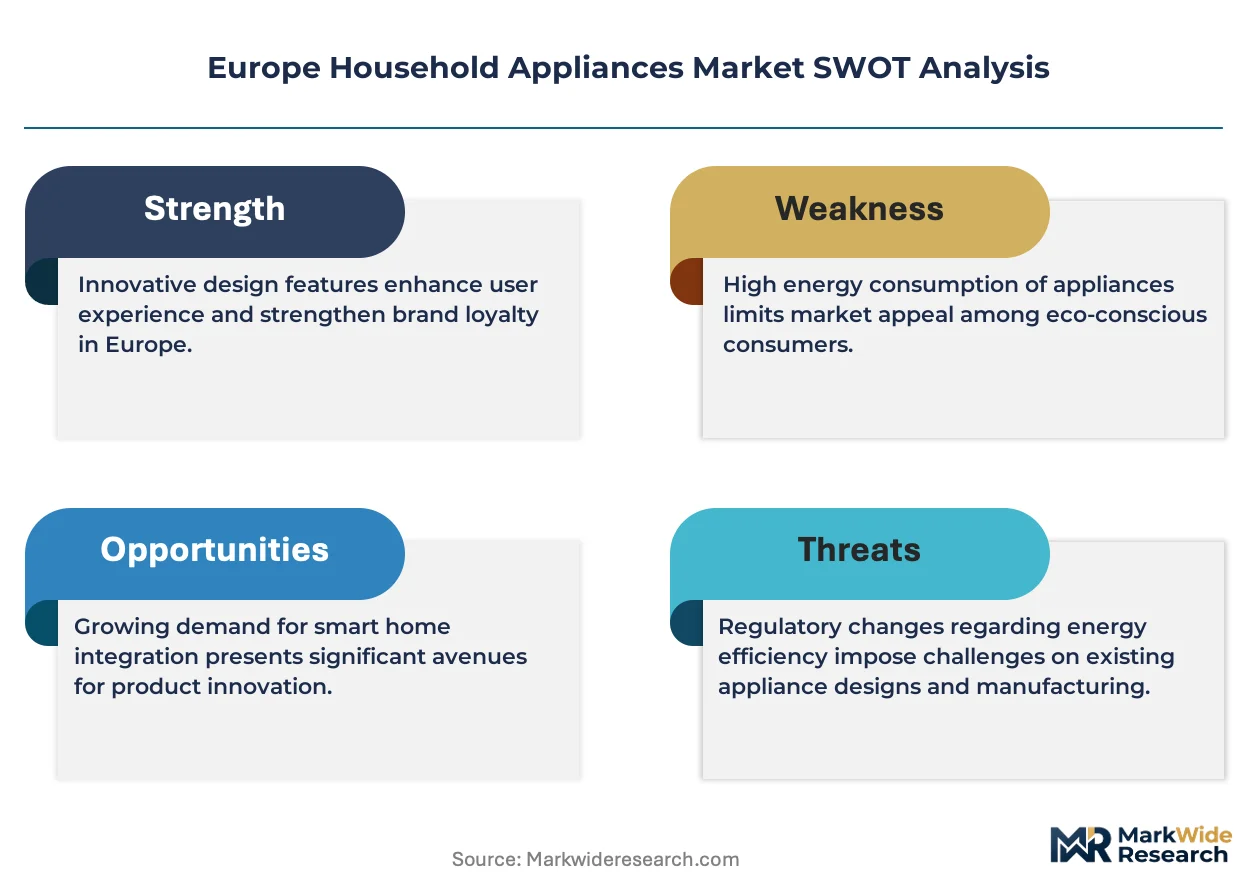
The EU Green Deal, Ecodesign Directive, and F-Gas Regulation collectively mandate refrigerant transitions and minimum efficiency thresholds that reshape product development budgets and factory retooling schedules across European manufacturing bases. CE marking and REACH compliance create non-tariff barriers that favor incumbents with established testing infrastructure and substance-tracking systems. Stakeholders must monitor how the EU AI Act and pending cybersecurity certification frameworks for connected devices will alter firmware development costs and liability structures for IoT-enabled appliance portfolios.
Market Dynamics
The EU Green Deal and Ecodesign Directive are compressing replacement cycles across European kitchens, forcing manufacturers to retool production lines for heat-pump and inverter-compressor platforms before legacy refrigerant stocks deplete.
Growth Catalysts
- Residential Retrofit Momentum:Urban households in Germany and France are replacing aging units with connected, energy-efficient models ahead of regulatory deadlines. Kitchen renovation channels in Milan and Madrid report accelerated specification of built-in refrigeration.
- EU Green Deal Mandates:Minimum efficiency thresholds under the Ecodesign Directive are pulling forward demand for A-rated appliances. Manufacturers must certify heat-pump dryers and inverter-compressor refrigerators to maintain market access.
- Heat-Pump Technology Diffusion:Heat-pump dryer attachments are displacing vented alternatives in Dutch and German new-build specifications. This technology convergence is expanding addressable market for premium laundry systems.
Market Restraints
- Refrigerant Transition Costs:F-Gas Regulation mandates phase-out of hydrofluorocarbon refrigerants, requiring factory retooling and new supply chain qualification for natural refrigerant handlers.
- Component Supply Concentration:Compressor manufacturing concentrates in German and Polish industrial clusters, creating vulnerability to single-source disruption for inverter-motor platforms.
- Copper and Steel Volatility:Raw material input costs for refrigeration coils and washing machine drums fluctuate with energy-intensive smelter economics across European metallurgical basins.
Strategic Opportunities
- Asset-Light Leasing Models:Pay-per-use financing is fragmenting competitive access, enabling challenger brands to scale without heavy balance-sheet commitments. German metropolitan clusters show early adoption of multi-year residential contracts.
- Smart Appliance APIs:Wi-Fi module integration and energy management interfaces are becoming baseline expectations in premium residential segments. Nordic renovation channels prioritize specification control through connected kitchen portfolios.
- Southern European Saturation Pivot:Front-loading washer penetration nears ceiling in Italy and Spain, creating aftermarket opportunity for heat-pump dryer attachments and service contract bundling.
Industry Challenges
- Firmware Development Cost Escalation:Pending EU AI Act and cybersecurity certification frameworks for connected devices are altering liability structures for IoT-enabled appliance portfolios. Manufacturers face talent scarcity in embedded systems security.
- REACH Compliance Complexity:Substance-tracking systems for restricted materials in plastics and coatings require documentation infrastructure that favors incumbents with established testing laboratories.
- CE Marking Timeline Compression:Accelerated Ecodesign implementation schedules compress product validation windows, forcing parallel rather than sequential certification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Household Appliances Market |
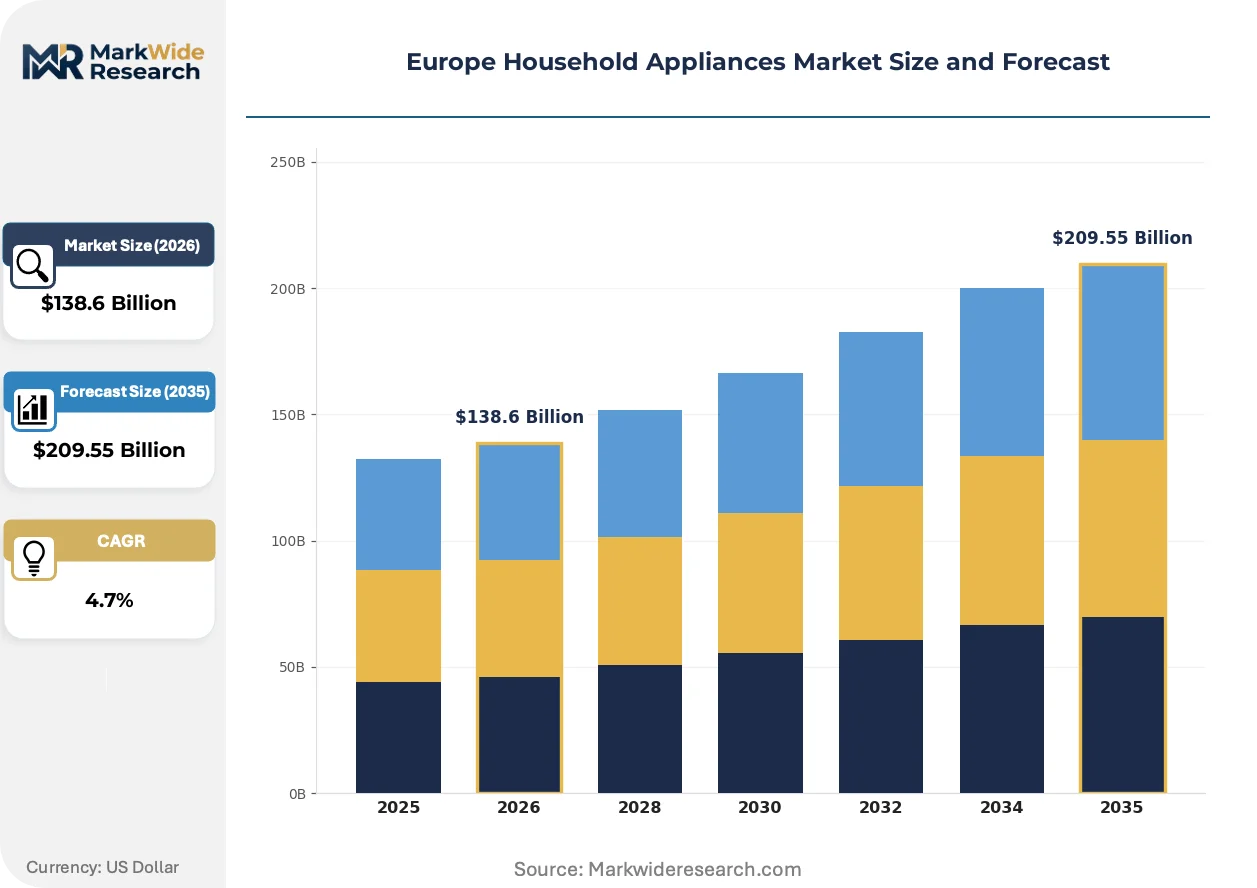
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $209.55 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
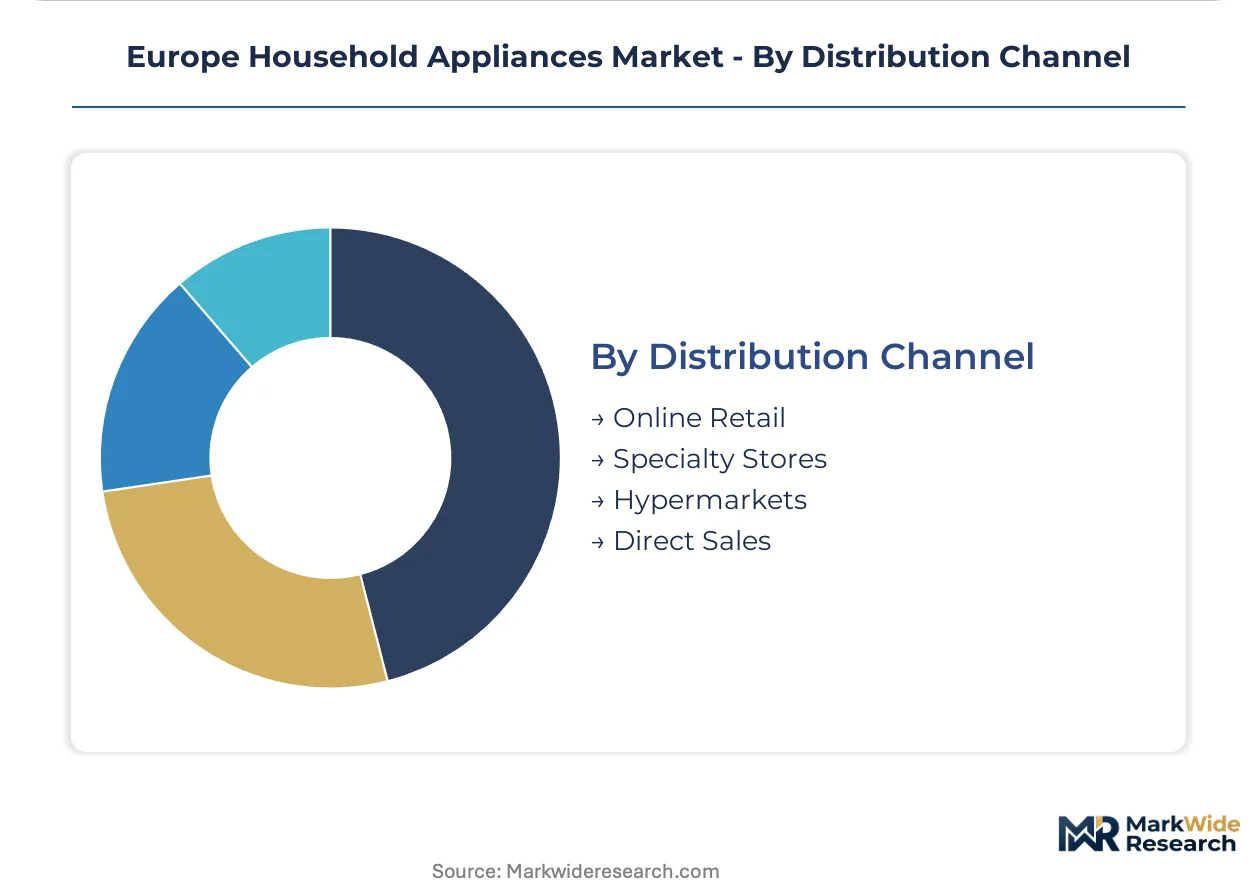
| Segmentation | Product Type: Refrigerators, Washers, Ovens, Microwaves Technology: Smart Appliances, Energy-Efficient, Conventional, IoT-Enabled End User: Residential, Commercial, Institutional, Rental Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Miele & Cie. KG, Robert Bosch GmbH, BSH Hausgeräte GmbH, Haier Europe, Liebherr Group, Electrolux AB, Arçelik A.Ş., De'Longhi S.p.A., Whirlpool Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Household Appliances Market Trends and Innovations
Connected appliance platforms and natural refrigerant transitions are redefining product architecture and service economics across European manufacturing bases, with regulatory compliance now inseparable from competitive positioning.
Heat-pump drying technology is rendering obsolete vented and condenser dryer architectures in Northern European markets. German and Dutch housing associations specify heat-pump attachments in new-build tenders, compressing payback periods through energy tariff differentials. This transition is rendering obsolete traditional heating-element manufacturing lines and rewiring supplier relationships toward refrigeration-component specialists.
REACH and the F-Gas Regulation are mandating substance transparency and refrigerant transitions that reshape product development budgets. Manufacturers must track restricted chemicals through multi-tier supply chains and qualify natural refrigerant handling protocols. Refrigeration platforms face the steepest compliance burden, with production sites in Germany and Poland retooling charging stations and technician certification programs.
Leasing and subscription models are displacing outright purchase in urban German and French metropolitan clusters. Property management firms and co-living operators bundle appliance access into monthly service fees, shifting capital expenditure off household balance sheets. This procurement evolution concentrates buyer power among portfolio operators and demands predictive maintenance capabilities from manufacturers.
Europe Household Appliances Market Segmentation
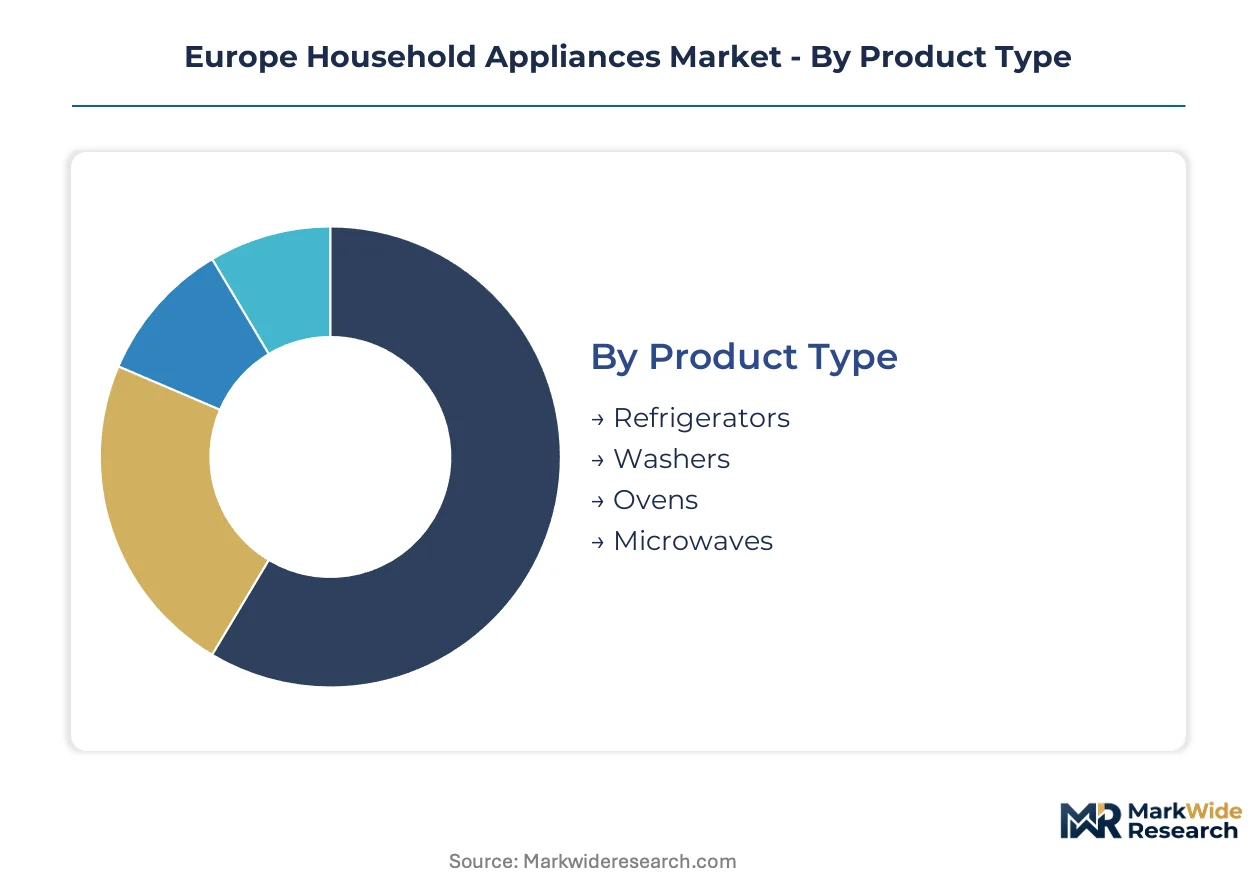
Segmentation across product architecture, connectivity specifications, procurement channels, and user categories reveals where margin pools concentrate and which technology transitions command capital allocation across European manufacturing bases.
Product Type:
Cost tier stratification separates premium compressor platforms from mass-market heating elements and basic mechanical systems.
- Refrigerators:Inverter-compressor architectures with variable-speed drives dominate specification sheets as Ecodesign mandates compress replacement cycles. German and French kitchen renovation channels prioritize A-rated built-in units with natural refrigerant charging protocols.
- Washers:Front-loading drum mechanisms with brushless direct-drive motors retain volume concentration across Southern European markets where Italian and Spanish households face saturation in base-model penetration.
- Ovens:Pyrolytic self-cleaning liners and steam-injection compartments define mid-tier differentiation.
- Microwaves:Inverter power control and flatbed cavity designs displace rotating turntable architectures.
Refrigerators hold installed capacity. Washers are rotating up the share rankings.
Technology:
Application-specific connectivity requirements split procurement between energy management integration and basic operational reliability.
- Smart Appliances:Wi-Fi module integration with cloud-based diagnostic APIs enables predictive maintenance contracts and remote firmware updates. Nordic housing associations specify connected kitchen portfolios for portfolio-wide energy optimization.
- Energy-Efficient:Heat-pump drying platforms and inverter-compressor refrigeration achieve A+++ ratings under EU standardized testing protocols. Dutch new-build specifications mandate heat-pump attachments ahead of regulatory deadlines.
- Conventional:Resistive heating elements and fixed-speed compressors serve price-sensitive replacement demand in Eastern European markets.
- IoT-Enabled:Matter protocol compatibility and cybersecurity certification frameworks reshape firmware development roadmaps under pending EU AI Act implementation.
Energy-Efficient platforms command specification control. Smart Appliances are climbing the fastest on renovation channel priority lists.
End User:
Customer type determines contract structure, with leasing penetration fragmenting traditional ownership models across urban clusters.
- Residential:Individual households drive replacement cycles through kitchen renovation triggers and regulatory compliance deadlines in German metropolitan areas.
- Commercial:Restaurants, hotels, and catering operations demand NSF-certified refrigeration and rapid-cook oven platforms with service contract bundling.
- Institutional:Hospitals, schools, and military facilities procure through framework agreements with extended warranty terms and preventive maintenance schedules.
- Rental:Co-living operators and property management firms in Paris and Berlin metropolitan clusters bundle appliance access into monthly service fees, shifting capital expenditure off household balance sheets.
Residential maintains volume concentration. Rental is expanding most quickly through asset-light financing proliferation.
Distribution Channel:
Volume concentration and margin capture diverge between specification-controlled renovation channels and transactional retail formats.
- Online Retail:Platform aggregators capture replacement demand for standardized SKUs with delivery-installation bundling and trade-in logistics.
- Specialty Stores:Kitchen studios and appliance galleries in Milan and Madrid control built-in specification for premium renovation projects with multi-year financing integration.
- Hypermarkets:Mass-market retailers move high-volume laundry and refrigeration through promotional pricing and private-label positioning.
- Direct Sales:Manufacturer-owned channels and captive financing arms lock in multi-year residential contracts across German metropolitan clusters with predictive maintenance service tiers.
Specialty Stores hold specification authority. Online Retail is gaining share fastest through delivery infrastructure scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's household appliances trade flows reveal a structural surplus in German-engineered refrigeration systems offset by import dependence on Asian-sourced electronic modules. Cross-border component sourcing concentrates procurement decisions in Rotterdam and Hamburg logistics hubs.
Germany
Residential retrofit demand accelerates across Berlin and Munich metropolitan clusters as households replace aging units ahead of Ecodesign deadlines. The EU Green Deal mandates pull forward replacement cycles for A-rated appliances. Manufacturing concentrates in Baden-Württemberg and North Rhine-Westphalia, where BSH Hausgeräte and Robert Bosch operate captive production lines for inverter-compressor platforms.
France
Urban renovation channels in Paris and Lyon drive specification of built-in kitchen portfolios with multi-year financing integration. REACH compliance requirements reshape substance-tracking systems for plastics and coatings. Industrial activity clusters in Île-de-France and Auvergne-Rhône-Alpes, where specialty retailers control premium specification for connected refrigeration systems.
Italy
Front-loading washer penetration nears saturation in Lombardy and Veneto, shifting volume toward heat-pump dryer attachments and service contract bundling. CE marking timeline compression forces parallel certification pathways for natural refrigerant charging protocols. Manufacturing heritage concentrates in Piedmont and Emilia-Romagna, where De'Longhi anchors small appliance production.
Netherlands
Housing associations specify heat-pump dryer attachments in Amsterdam and Rotterdam new-build tenders, compressing payback periods through energy tariff differentials. F-Gas Regulation mandates accelerate refrigerant transition timelines. Distribution infrastructure at Rotterdam port handles inbound Asian electronic modules for final assembly across German and Polish industrial corridors.
Poland
Mass-market dishwasher and refrigeration lines scale through Polish manufacturing bases serving Western European demand. Ecodesign implementation schedules compress product validation windows for export certification. Industrial parks near Wrocław and Poznań host retooling programs for natural refrigerant handling and inverter-motor platform assembly.
Europe Household Appliances Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on compressor and control module supply. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive financing arms, specialized built-in kitchen specialists with renovation channel control, and scale-driven mass-market manufacturers with Polish production advantages. Competitive moves center on multi-year residential leasing contracts and predictive maintenance service tier bundling.
Among German-based diversified manufacturers, Robert Bosch GmbH and BSH Hausgeräte GmbH exemplify the integrated platform archetype with manufacturing scale advantages. Electrolux AB represents the Nordic specialist position with built-in portfolio specification control. These three entities anchor the competitive structure through distinct channel access models rather than overlapping segment confrontation.
| Leading Market Players |
|---|
| Miele & Cie. KG |
| Robert Bosch GmbH |
| BSH Hausgeräte GmbH |
| Haier Europe |
| Liebherr Group |
| Electrolux AB |
| Arçelik A.Ş. |
| De'Longhi S.p.A. |
| Whirlpool Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Polish dishwasher assembly lines is compressing supplier margins and forcing tier-two component vendors to absorb cost volatility rather than pass through steel and copper escalations to German OEM buyers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in European household appliances. Price differentiation rests on A+++ energy certification grade and after-sales service bundling rather than base hardware specifications. Pricing pressure stems from F-Gas Regulation compliance costs that manufacturers cannot fully recover in mass-market refrigeration tiers. Property management firms show lowest price sensitivity through leasing contract structures, while Eastern European replacement demand remains most elastic to promotional discounting.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment limit flows of high-performance control modules from Asian foundries to European appliance assembly plants. Component sourcing concentrates in Germany, Poland, and China for compressor platforms, electronic controllers, and Wi-Fi connectivity modules. Raw material dependencies span copper refrigeration coils, rare-earth permanent magnets for brushless motors, and specialized steel alloys for washing machine drums. Single-source vulnerability concentrates in German inverter-motor manufacturing clusters. Distribution runs through Rotterdam and Hamburg logistics hubs for inbound Asian electronic modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe household appliances market is experiencing high-growth disruption as heat-pump technology convergence and EU Green Deal mandates compress replacement cycles and rewrite product architecture economics.
For Market Incumbents: Entrench specification control through captive financing arms and predictive maintenance service tiers that lock in multi-year residential contracts across German metropolitan clusters. Deepen backward integration into inverter-compressor manufacturing to defend margin position against refrigerant transition cost escalation. Prioritize CE marking and REACH compliance infrastructure as non-tariff barriers against Asian challengers. For New Entrants and Emerging Players: Eastern European leasing penetration represents underpenetrated white-space where asset-light financing models can scale without heavy balance-sheet commitments. Target co-living operators and property management firms in Warsaw and Prague metropolitan clusters with subscription-based appliance access bundled into monthly service fees. Deploy direct-to-consumer online channels with trade-in logistics to bypass entrenched specialty store networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with connected appliance platforms and predictive maintenance service tiers. Long-term viability favors acquisition targets with established natural refrigerant handling protocols and Matter protocol compatibility for smart home integration. Monitor F-Gas Regulation implementation timelines as the critical inflection signal for factory retooling investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Platform Expansion | Captures Dutch and German new-build specifications ahead of Ecodesign deadlines. |
| Captive Financing Arm Development | Locks in multi-year residential contracts through Robert Bosch GmbH's proven model. |
| Natural Refrigerant Retooling | Qualifies production sites for F-Gas Regulation compliance and CE marking access. |
| Smart Appliance API Integration | Enables predictive maintenance contracts through Wi-Fi module and cloud diagnostic platforms. |
| Polish Manufacturing Scale-Up | Exploits cost advantages for mass-market dishwasher and refrigeration export to Western Europe. |
Research Methodology
The analysis maps refrigeration compressors, heat-pump drying platforms, smart connectivity modules, and leasing service tiers, each validated through manufacturing plant managers, OEM procurement leads, specialty kitchen studio buyers, and property management portfolio operators. Primary interviews triangulate with secondary sources including EU Ecodesign regulatory filings, REACH substance-tracking databases, customs trade flow records, and energy efficiency certification registries. Bottom-up segment sizing cross-checks against top-down macroeconomic consumption indicators.
Assumption sets hold EU Green Deal implementation schedules and F-Gas Regulation phase-out timelines as fixed boundary conditions while varying residential retrofit intensity and leasing penetration rates across the projection horizon. Segmentation dimensions span product architecture, connectivity specification, procurement channel, and end-user contract structure. CAGRs derive from replacement cycle compression models and technology diffusion curves calibrated to Ecodesign mandate compliance deadlines. Forecast inputs include copper and steel price volatility indices and housing construction permit data.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese appliance manufacturers or accelerated refrigerant transition timelines by ECHA would shift outcomes. Material shifts in EU AI Act cybersecurity certification requirements or REACH substance restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Europe Smart Cooker Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
Smart Induction Cooktop Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
Residential Cooking Grills Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market