
 India Electric Vegetable Choppers Market | 2026-2036
India Electric Vegetable Choppers Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Vegetable Choppers Market Insights
Gujarat's manufacturing corridor is reshaping component sourcing for electric vegetable chopper assembly, with Ahmedabad and Surat emerging as plastics and motor winding hubs. Prestige leverages its southern India dealer network to sustain deep retail penetration in Kerala and Tamil Nadu. Bajaj anchors the mass-market tier through aggressive pricing and rural distribution reach. Philips differentiates via copper-wound motor technology and extended warranty positioning in premium metro channels.
India electric vegetable choppers are compact countertop appliances employing stainless steel twin-blade assemblies or quad-blade configurations powered by 250-500 watt universal motors, designed to reduce vegetable preparation time for domestic and commercial kitchens. The product type spectrum shows multi-functional choppers capturing margin pools through attachment versatility while mini choppers dominate volume in space-constrained urban apartments. End user demand splits sharply between households seeking daily meal prep convenience and restaurants requiring continuous-duty cycle performance. Distribution channel dynamics favor online retail for discovery and price comparison, though offline retail still closes the majority of transactions in Tier-2 and Tier-3 cities.
BIS mandates ISI marking for all electrical kitchen appliances above specified wattage thresholds, compelling manufacturers to upgrade thermal fuse protection and insulation grades. The Food Safety and Standards Authority of India (FSSAI) guidelines for commercial food preparation equipment indirectly shape blade material specifications and cleanability standards for restaurant-targeted models. BIS also governs power cord safety and plug configurations under separate harmonized standards. Stakeholders must monitor evolving energy efficiency labeling requirements and the pace of smart technology integration as variable speed and app-connected models test price elasticity in premium segments.
Market Dynamics
Dual-income nuclear families in Maharashtra and Gujarat are compressing meal preparation windows, forcing appliance manufacturers to prioritize wattage efficiency and blade speed in compact form factors. This demand compression is restructuring competitive priorities across the value chain.
Growth Catalysts
- FSSAI commercial guidelines:Restaurant-grade cleanability standards are elevating stainless steel blade specifications, opening premium tier expansion for domestic manufacturers targeting food service procurement.
- Copper-wound motor technology:Extended thermal durability is reducing replacement frequency in high-duty cycle environments, locking in commercial kitchen loyalty and warranty-driven repeat purchases.
- Ahmedabad-Surat manufacturing corridor:Plastics and motor winding component clustering is shortening lead times for assembly operations, compressing working capital cycles for regional producers.
Market Restraints
- Copper price volatility:Motor winding input costs fluctuate with commodity markets, squeezing margin stability for mid-tier producers unable to pass through pricing adjustments.
- BIS certification timelines:ISI marking requirements for electrical kitchen appliances create 4-6 month product launch delays, freezing inventory deployment during peak seasonal demand windows.
- Manual chopping substitutes:Traditional knife-and-board methods persist in price-sensitive rural households and elderly demographics, capping penetration rates in Tier-3 towns and below.
Strategic Opportunities
- Kerala and Tamil Nadu retail networks:Southern India dealer infrastructure remains underutilized for electric chopper categories, offering whitespace for brands with existing appliance distribution relationships.
- Smart variable speed integration:App-connected motor control systems are testing price elasticity among Mumbai and Delhi metro consumers, creating premium segment architecture.
- PLI scheme for white goods:Production-linked incentive structures for electrical appliance manufacturing are reducing effective capital costs for domestic assembly capacity expansion.
Industry Challenges
- Certification testing bottlenecks:BIS laboratory capacity constraints for thermal fuse and insulation grade validation are extending product approval cycles beyond commercial planning horizons.
- After-sales service network gaps:Motor repair and blade replacement capabilities remain sparse outside Tier-1 cities, eroding brand trust in warranty claim fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Vegetable Choppers Market |
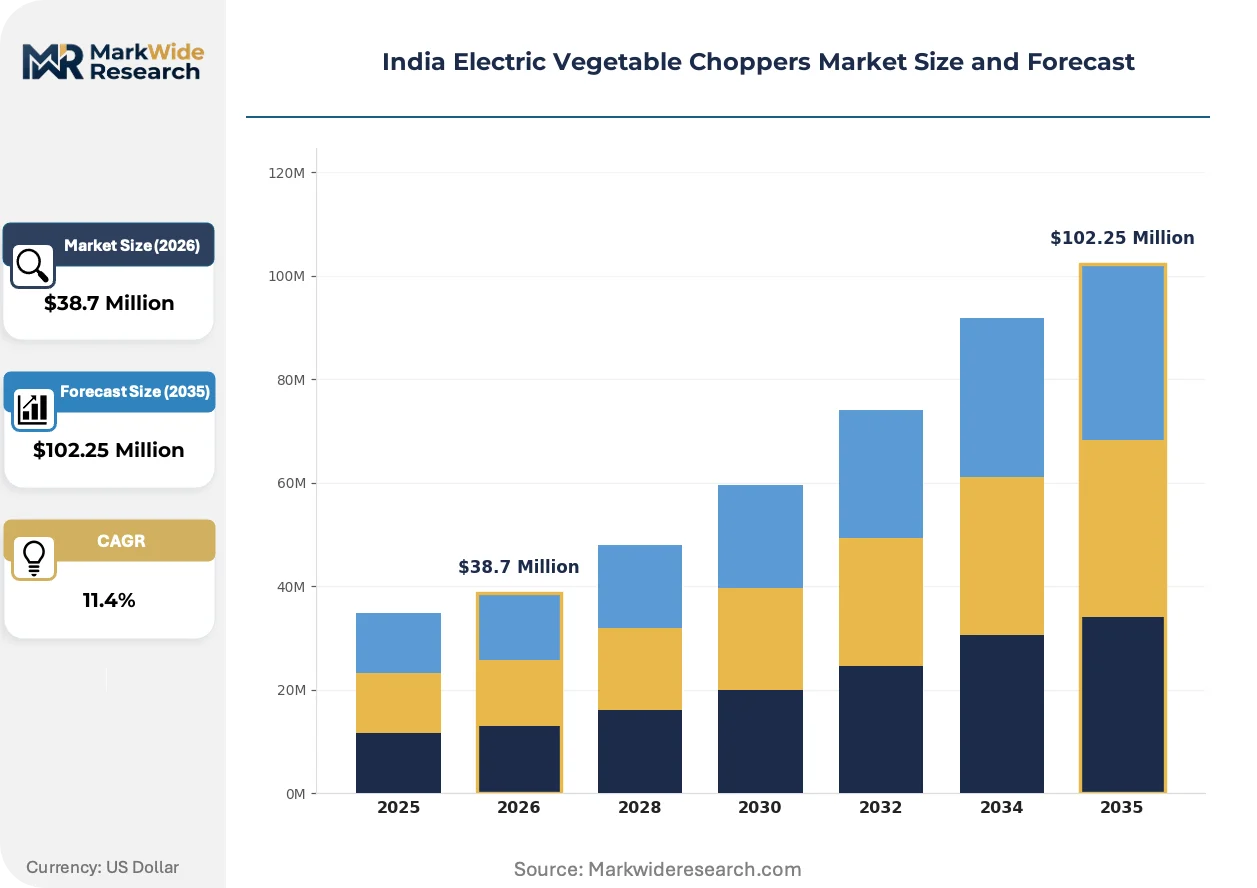
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Choppers, Standard Choppers, Heavy-Duty Choppers, Multi-Functional Choppers End User: Households, Restaurants, Catering Services, Food Processing Units Technology: Manual Control, Smart Technology, Single-Speed, Variable Speed Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Prestige, Bajaj, Philips, Wonderchef, Glen, Inalsa, Havells, Morphy Richards, Usha, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Vegetable Choppers Market Trends and Innovations
Digital integration and material science advances are restructuring how electric vegetable choppers deliver value, with connectivity features and regulatory compliance becoming primary differentiation vectors rather than secondary specifications.
Variable speed motor control systems are virtualizing traditional mechanical switching interfaces, replacing physical dials with electronic pulse-width modulation. Metro households in Mumbai and Delhi are adopting these interfaces at accelerating rates, drawn by precision control over texture outcomes. This virtualization is compressing the mechanical component count in premium tier assemblies, reducing failure points while elevating software dependency in product architecture.
BIS harmonized standards for power cord safety and plug configurations are mandating upgraded insulation grades across all electrical kitchen equipment categories. Manufacturers are reconfiguring supply chains to source certified cable assemblies from Gujarat-based component producers. Commercial kitchen operators targeting restaurant certification are most affected, with procurement specifications now explicitly requiring ISI-marked cord sets as a qualifying criterion.
Channel fragmentation is reshaping how households discover and purchase electric choppers, with online platforms dominating initial research and price comparison while offline retail closes transactions in Tier-2 and Tier-3 cities. Traditional appliance dealers in Kerala and Tamil Nadu are integrating digital catalog tools to bridge this gap, blending physical touchpoints with virtual inventory access. This hybrid model is most visible in nuclear family dense districts where time-constrained buyers prioritize convenience without sacrificing tactile evaluation.
India Electric Vegetable Choppers Market Segmentation
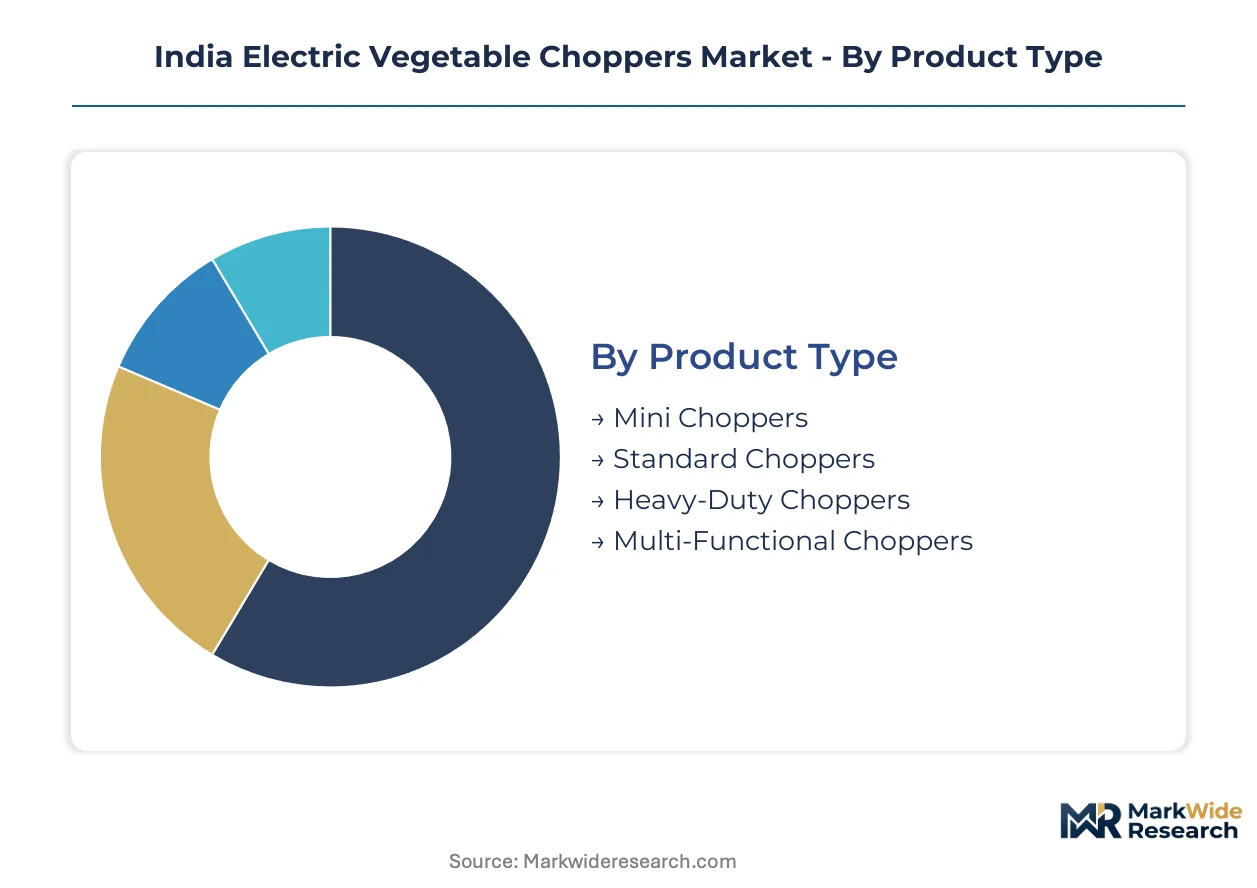
Segmentation in the India electric vegetable choppers market reveals how purchase cycles, replacement frequencies, and usage intensity vary dramatically across user profiles. Manufacturers align R&D spend and channel investments to these differential velocity patterns rather than treating demand as uniform.
Product Type:
Mini choppers turn inventory fastest in Mumbai and Delhi retail, with replacement cycles compressed by motor burnout in high-frequency daily use. Heavy-duty units rotate slowest, locked into commercial kitchen depreciation schedules.
- Mini Choppers:Compact 250-watt units with twin-blade assemblies dominate space-constrained urban apartments. Demand concentrates in Maharashtra and Gujarat nuclear families where counter space scarcity forces trade-offs between capacity and footprint.
- Multi-Functional Choppers:Attachment-versatile platforms with whisk and kneading modules command premium positioning. Kerala and Tamil Nadu households drive adoption, leveraging existing southern India appliance dealer networks for post-purchase attachment procurement.
- Standard Choppers:Mid-wattage 350-watt configurations balance blade speed with thermal tolerance for moderate-duty cycles.
- Heavy-Duty Choppers:500-watt continuous-duty motors with quad-blade arrays serve restaurant procurement specifications under FSSAI cleanability guidelines.
Mini choppers dominate installed base. Multi-functional choppers are where expansion concentrates.
End User:
Cost tier stratification separates warranty-backed commercial procurement from price-sensitive household replacement markets. Food service buyers amortize equipment over depreciation schedules; households absorb sticker shock directly.
- Households:Dual-income nuclear families in Ahmedabad and Surat prioritize wattage efficiency and blade speed in compact form factors. BIS certification requirements for ISI marking filter out uncertified imports in this safety-conscious segment.
- Restaurants:Continuous-duty cycle requirements and FSSAI commercial guidelines elevate stainless steel blade specifications. Copper-wound motor technology locks in loyalty through extended thermal durability and warranty-driven repeat purchases.
- Catering Services:Mobile food preparation demands balance portability against volume throughput, with power cord safety standards governing field deployment.
- Food Processing Units:Industrial-scale throughput requirements push demand toward heavy-duty configurations with standardized blade geometries for batch consistency.
Households dominate installed base. Restaurants are gaining share fastest.
Technology:
Volume concentration favors electromechanical simplicity, though margin pools concentrate in digitally integrated platforms testing price elasticity among metro consumers.
- Variable Speed:Electronic pulse-width modulation replaces mechanical switching interfaces, enabling precision texture control. Mumbai and Delhi metro adoption accelerates as software-dependent architecture reduces mechanical failure points.
- Smart Technology:App-connected motor control systems with usage tracking and recipe integration target premium segments. Price elasticity testing in nuclear family dense districts determines whether connectivity justifies cost premiums.
- Manual Control:Physical dial interfaces persist in Tier-2 and Tier-3 cities where tactile reliability outweighs feature sophistication.
- Single-Speed:Fixed RPM universal motors anchor mass-market tier through manufacturing simplicity and repairability.
Manual control dominates installed base. Variable speed is climbing the fastest.
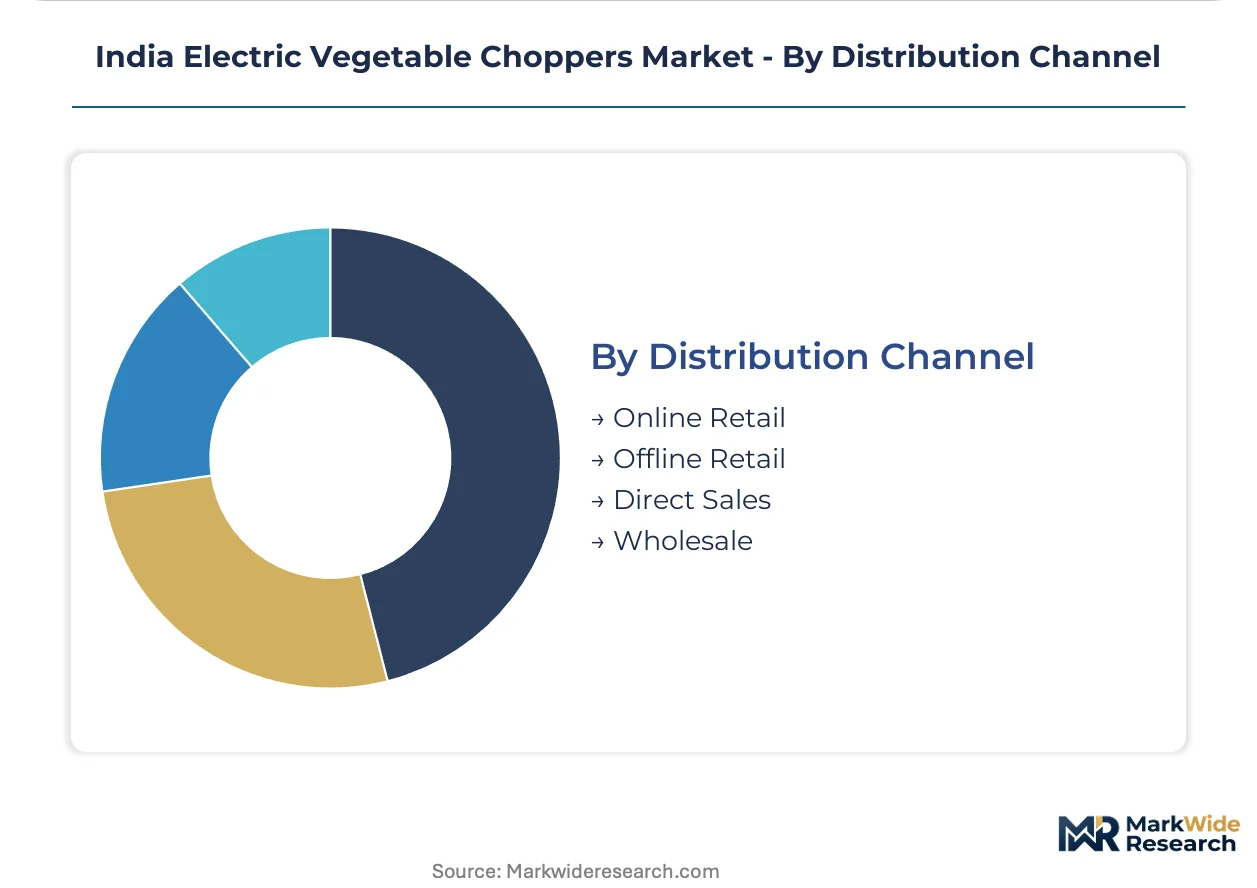
Distribution Channel:
Geography determines channel effectiveness, with digital discovery preceding physical transaction in urban corridors while traditional retail retains closure dominance in peripheral markets.
- Online Retail:Discovery and price comparison platforms capture research-phase consumer attention. Metro households leverage virtual inventory access before finalizing specifications.
- Offline Retail:Tier-2 and Tier-3 city transactions close through tactile evaluation and immediate fulfillment. Kerala and Tamil Nadu dealer networks integrate digital catalog tools to bridge hybrid purchase journeys.
- Direct Sales:Commercial kitchen procurement bypasses retail markup through manufacturer-direct relationships with restaurant chains and catering cooperatives.
- Wholesale:Regional distributors aggregate demand from smaller food service operators, compressing logistics costs through consolidated shipment.
Offline retail dominates installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements for electrical kitchen equipment anchor Maharashtra's market dominance, with ISI marking mandates filtering out uncertified imports and compressing product launch timelines across western India.
Maharashtra
Mumbai's nuclear family density and dual-income household concentration compress meal preparation windows, forcing wattage efficiency prioritization in compact form factors. BIS thermal fuse protection standards govern all electrical kitchen appliances above specified wattage thresholds. Pune-Ahmednagar industrial corridor hosts plastics molding and motor winding component suppliers serving assembly operations.
Gujarat
Ahmedabad and Surat manufacturing clusters shorten lead times for electric chopper assembly through localized plastics and copper winding sourcing. PLI scheme incentives for white goods manufacturing reduce effective capital costs for domestic capacity expansion. Surat's component producers reconfigure supply chains to source certified cable assemblies meeting harmonized power cord safety standards.
Delhi-NCR
Metro households accelerate adoption of variable speed and smart-connected models, testing price elasticity for software-dependent architecture. FSSAI commercial guidelines indirectly shape blade material specifications for restaurant-targeted procurement. Gurugram-Noida electronics assembly corridor attracts premium-tier brands seeking proximity to northern India distribution infrastructure.
Kerala and Tamil Nadu
Southern India dealer networks sustain deep retail penetration for multi-functional chopper categories with attachment versatility. Traditional appliance dealers integrate digital catalog tools to bridge online discovery with tactile transaction closure. Coimbatore-Chennai manufacturing belt supplies stainless steel blade assemblies and motor components to national assembly operations.
Karnataka
Bengaluru's tech-forward household profile drives early adoption of app-connected motor control systems with usage tracking features. BIS laboratory capacity constraints for insulation grade validation extend product approval cycles beyond commercial planning horizons. Mysuru-Hubballi component corridor specializes in thermal fuse protection and certified power cord sourcing.
India Electric Vegetable Choppers Market Competitive Landscape
Capability concentration sits with heritage kitchen appliance specialists; scale advantage sits with diversified electrical goods conglomerates. The vendor base stratifies across three tiers: premium international brands with copper-wound motor positioning, mass-market domestic players with rural distribution reach, and regional specialists with southern India retail density. Two dominant competitive moves reshape positioning: dealer network integration in underserved geographies and PLI scheme leveraged capacity expansion for component backward integration.
Within the heritage kitchen appliance tier, Prestige and Bajaj exemplify divergent scale-capability tradeoffs. Prestige leverages its southern India dealer infrastructure to sustain whitespace penetration in Kerala and Tamil Nadu multi-functional segments. Bajaj anchors mass-market positioning through aggressive pricing architecture and rural distribution depth. Among diversified electrical goods players, Havells occupies a position bridging premium feature sets with national retail footprint expansion.
| Leading Market Players |
|---|
| Prestige |
| Bajaj |
| Philips |
| Wonderchef |
| Glen |
| Inalsa |
| Havells |
| Morphy Richards |
| Usha |
| Others |
Pricing and Supply Chain Analysis
Underutilized motor winding capacity in Gujarat's component corridor is compressing supplier pricing power while simultaneously accelerating inventory turnover for regional assemblers. This utilization slack permits aggressive cost positioning in mass-market tiers without sacrificing margin stability for premium copper-wound configurations.
Pricing Analysis
Metro-to-rural price spreads exceed two-to-one across Maharashtra and Gujarat, with Mumbai households absorbing premiums for ISI-marked certification and extended warranty bundles. Three-tier pricing structure across premium, standard, and economy levels anchors the market, with copper-wound motor technology and BIS compliance grading the tiers. Cost compression in economy segments intensifies because of commodity copper volatility and import component exposure. Tier-3 rural buyers exhibit highest price sensitivity, while restaurant procurement teams prioritize thermal durability over sticker price.
Supply Chain Analysis
Copper price volatility between Chilean mining output and Indian manufacturing demand dominates input cost instability for motor winding operations. Component sourcing concentrates in China for electronic pulse-width modulation controllers, India for plastics molding and stainless steel blade forging, and Vietnam for certified cable assemblies. Single-source vulnerability in semiconductor-based motor controllers creates procurement risk for variable-speed model ramps. Distribution runs through Gujarat-based regional distributors aggregating Tier-2 and Tier-3 demand, with direct manufacturer relationships serving commercial kitchen accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of BIS-certified testing laboratory capacity is constraining product launch velocity and amplifying first-mover advantages for incumbents with established regulatory relationships. This bottleneck justifies defensive investment in certification infrastructure and pre-emptive filing strategies.
For Market Incumbents: Pre-empt emerging competition by locking in Ahmedabad-Surat component supplier exclusives before PLI scheme incentives attract new entrants. Invest in captive BIS pre-testing capabilities to compress approval cycles below competitor timelines. Defend against manual chopper substitution in rural markets by embedding blade replacement services within existing dealer networks. For New Entrants and Emerging Players: Kerala and Tamil Nadu dealer infrastructure remains underpenetrated for electric chopper categories, offering whitespace for brands with complementary appliance distribution relationships. Target multi-functional attachment platforms where southern India households already demonstrate willingness to pay for versatility. Enter through digital catalog partnerships with established appliance dealers rather than building proprietary retail footprints. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart-connected motor control sub-segments as software development costs amortize across expanding unit volumes. Long-term viability favors acquirers of regional component specialists with BIS certification relationships and copper winding technical depth. Monitor BIS laboratory capacity expansion announcements as the critical inflection signal for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Winding | Captive copper winding capacity insulates margin stability against commodity price spikes in Gujarat manufacturing clusters. |
| Smart Variable Speed Platform Launch | Electronic pulse-width modulation architectures test price elasticity among Mumbai and Delhi metro nuclear families. |
| BIS Certification Pre-Investment | Early ISI marking filing compresses product launch delays before peak seasonal demand windows. |
| Southern India Dealer Network Expansion | Kerala and Tamil Nadu appliance dealer relationships unlock multi-functional chopper attachment revenue streams. |
| Commercial Kitchen Direct Procurement | Manufacturer-direct relationships with restaurant chains bypass retail markup and lock in FSSAI-compliant specifications. |
Research Methodology
A standing panel of product development managers at kitchen appliance manufacturers, BIS certification consultants, commercial kitchen procurement officers, and plastics molding plant engineers provided ongoing calibration throughout the study. This primary intelligence combined with secondary validation from BIS harmonized standards documentation, FSSAI commercial equipment guidelines, PLI scheme white goods notifications, and customs import data for electrical kitchen appliance components. Bottom-up unit shipment estimates triangulated against top-down household penetration models across Maharashtra, Gujarat, Delhi-NCR, and southern India states.
Scenario-bracketing framed the analytical approach, with demand trajectories tested across variable speed adoption curves and copper price volatility bands throughout the projection horizon. Segmentation dimensions modeled include product type tier, end-user category, motor control technology, and distribution channel structure, with regional nuclear family density and dual-income concentration as India-specific demand drivers. CAGRs derived from logistic diffusion curves fitted to appliance replacement cycle data and commercial kitchen depreciation schedules.
Practitioners should monitor BIS laboratory capacity expansion timelines and copper commodity futures for early signals of competitive dynamics shifts. Forecasts reflect assumptions regarding PLI scheme incentive continuity and FSSAI guideline evolution without anticipating specific regulatory amendments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Small Kitchen Appliances Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Colombia Kitchen Appliances Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
Electric Countertop Griddles Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
United States Electric Vegetable Choppers Market