
 China Mixer Grinder Market | 2026-2036
China Mixer Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
China Mixer Grinder Market Insights
Brushless DC motor integration is rewriting the engineering economics of mixer grinder production, replacing universal motors with quieter, more energy-dense platforms that extend product lifespans. Midea Group leverages its in-house motor manufacturing to control component costs across the value chain. Joyoung anchors its position through deep R&D in intelligent speed-control algorithms. Supor competes on brand recognition in tier-two and tier-three cities where replacement cycles are shortening.
A mixer grinder is an electrically powered food preparation appliance employing rotating blades or beaters to reduce solid ingredients to homogeneous pastes, powders, or emulsions, typically operating at speeds between 10,000 and 22,000 RPM with stainless steel or hardened alloy cutting assemblies. Its primary commercial purpose spans domestic meal preparation, commercial food service batch processing, and specialized bakery dough conditioning. Tabletop units dominate residential volume due to compact footprints suited to urban Chinese kitchen dimensions, while commercial mixer configurations command disproportionate margin contribution from food service and catering procurement channels. Smart technology adoption is accelerating fastest among premium residential buyers, though electric technology still occupies the mass-market core by unit economics.
MIIT energy-efficiency labeling requirements and NMPA electrical safety certification (CCC mark) create compliance thresholds that filter out subscale manufacturers and consolidate shelf access for certified brands. GB standards for electromagnetic compatibility and food-contact material safety further shape product design specifications and testing burdens. Stakeholders must monitor how SAMR enforcement of updated small-appliance quality regulations affects import substitution dynamics and domestic brand premiumization trajectories.
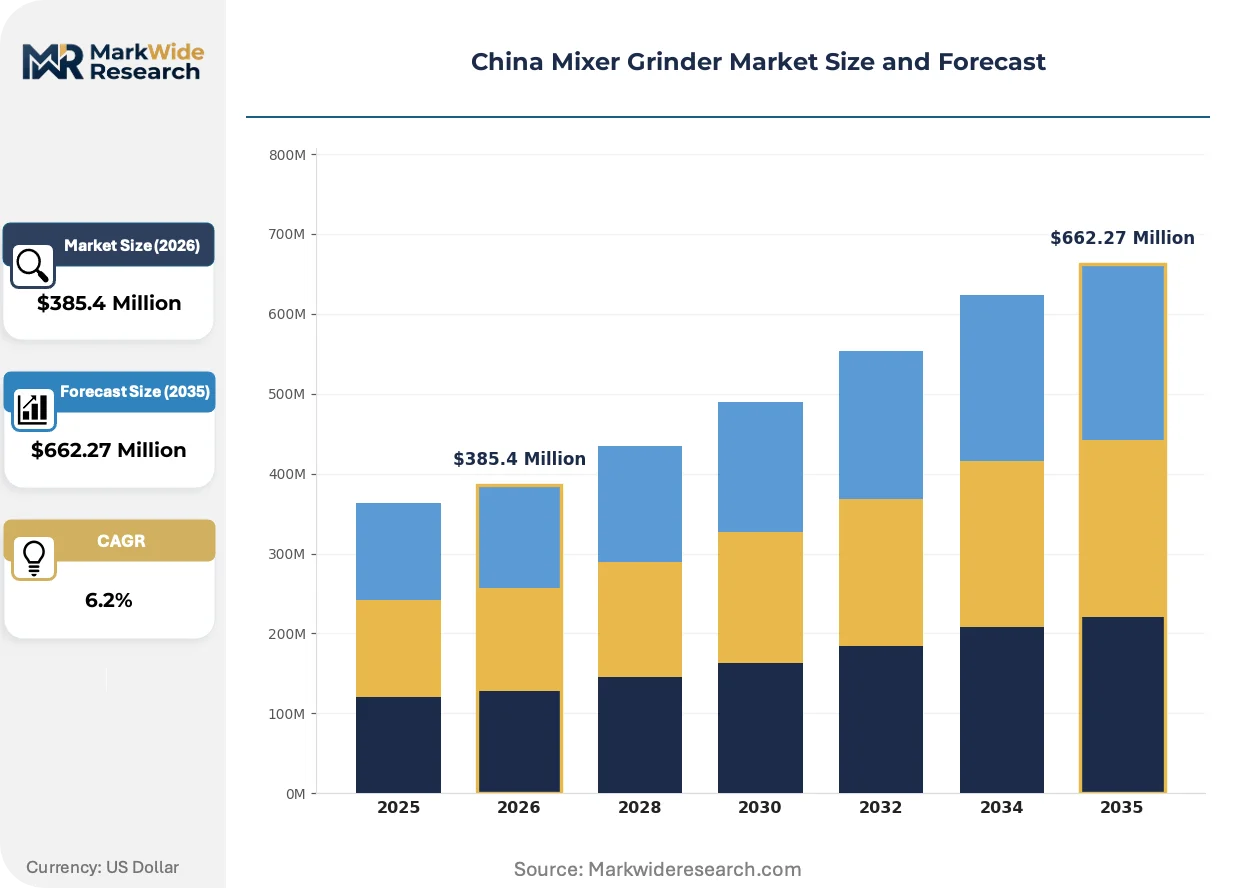
Market Dynamics
Brushless DC motor integration is compressing replacement cycles while MIIT energy-efficiency labeling forces component-level redesign across the value chain. This dual pressure is fragmenting competitive positioning between motor-integrated incumbents and assembly-dependent challengers.
Growth Catalysts
- MIIT Energy-Efficiency Labeling:Mandatory tiered efficiency ratings for small appliances create procurement preference for certified products in state-affiliated retail channels. This accelerates shelf rotation toward compliant manufacturers.
- Urban Kitchen Downsizing:Shanghai and Guangzhou residential unit footprints below 70 square meters drive demand for compact tabletop configurations with multi-function attachments.
- Food-Contact Material Safety Standards:Updated GB standards for stainless steel blade alloys and polymer housing materials filter subscale producers from modern trade distribution.
Market Restraints
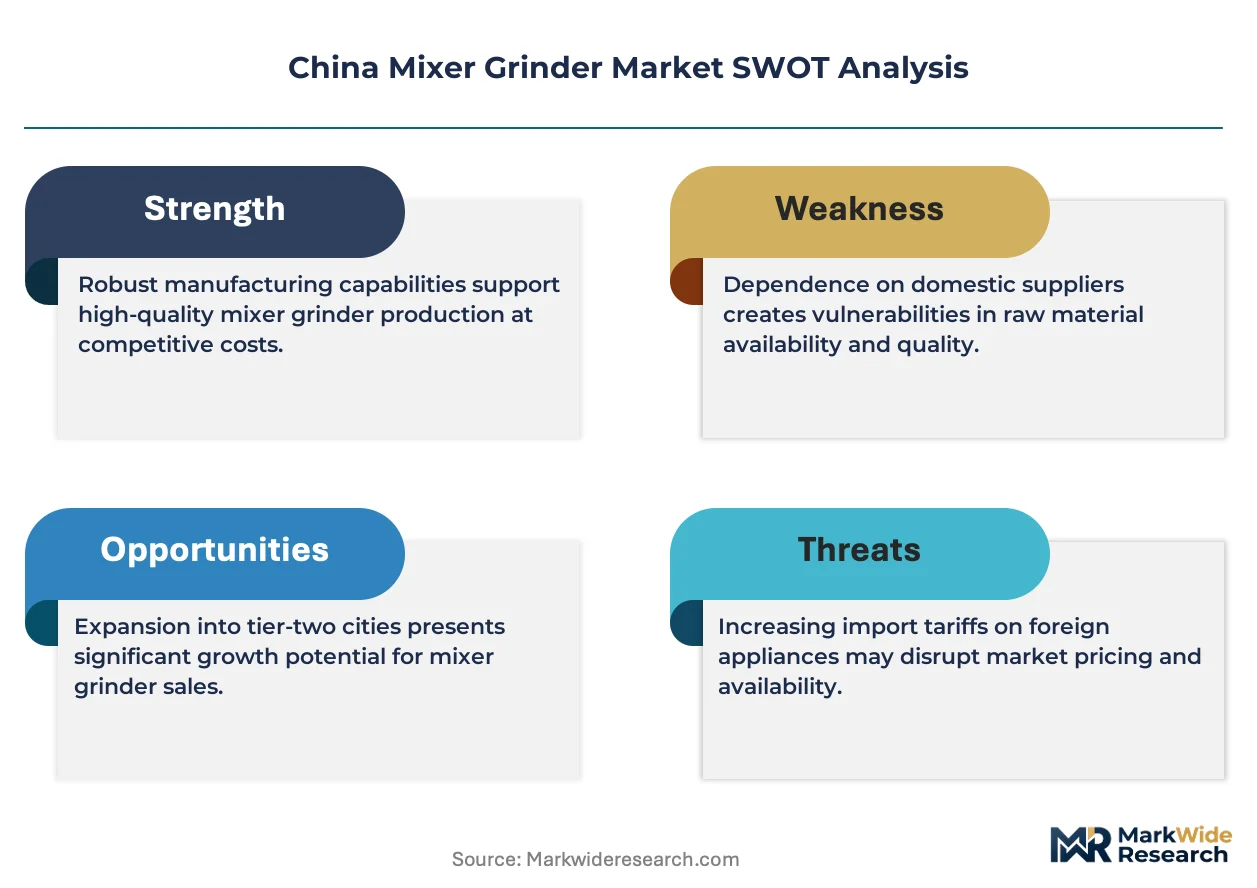
- Copper Winding Cost Volatility:Stator and rotor copper content exposes motor production to London Metal Exchange price swings that compress assembly margins during commodity spikes.
- Coastal Province Demand Concentration:Jiangsu, Zhejiang, and Guangdong provinces absorb disproportionate volume, leaving interior provinces with underdeveloped service infrastructure and elongated replacement cycles.
- Induction Cooktop Substitution:Built-in grinding attachments in premium induction ranges displace standalone units in new-build residential installations.
Strategic Opportunities
- Central Province Penetration:Henan and Hubei urban clusters show appliance ownership gaps of 30-40% versus coastal benchmarks, creating first-mover advantage for distribution infrastructure investment.
- SAMR Quality Regulation Enforcement:Tightened small-appliance inspection protocols post-2023 create shelf access for certified brands as uncertified competitors exit traditional retail.
- Smart-Mechanical Convergence:Integration of load-sensing algorithms with mechanical speed governors enables premium pricing for intelligent torque management in dough-conditioning applications.
Industry Challenges
- CCC Certification Timeline Compression:NMPA electrical safety testing queues extend lead times for new product introductions, forcing inventory pre-positioning ahead of seasonal demand windows.
- Motor-Controller Firmware Integration:Shortage of embedded systems engineers with appliance-specific experience delays intelligent feature rollout and increases reliance on third-party module suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Mixer Grinder Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop, Stand Mixer, Hand Mixer, Commercial Mixer End User: Residential, Food Service, Catering, Bakery Capacity: Low Capacity, Medium Capacity, High Capacity, Multi-functional Technology: Electric, Manual, Hybrid, Smart |
| Companies Covered | Midea Group, Joyoung, Hisense, TCL, Gree Electric Appliances, Haier, Supor, Galanz, Heshan Zilong Home Appliance Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Mixer Grinder Market Trends and Innovations
Intelligent speed control and food-safety material traceability are reshaping product architecture. Manufacturers must now engineer for algorithmic performance alongside mechanical durability.
Brushless DC motor platforms are hybridizing with universal motor supply chains as tier-one producers internalize stator winding and magnet assembly. Premium residential buyers in Shanghai and Shenzhen adopt these configurations for noise reduction below 65 decibels. The technology is hybridizing procurement patterns, with motor-integrated manufacturers capturing margin that previously flowed to discrete component suppliers.
SAMR enforcement of updated small-appliance quality regulations is tightening CCC mark renewal protocols and expanding factory inspection scope. This is compressing the viable supplier base to vertically integrated producers with captive testing laboratories. Tier-two city distributors are responding by consolidating supplier relationships around certified brands with documented GB compliance histories.
After-sales service unbundling is accelerating as e-commerce platforms displace traditional retail for replacement purchases. JD.com and Tmall channels now dominate volume in coastal provinces, compressing brand-owned service network economics. This shift is most visible in Guangdong, where independent repair technicians capture 60% of out-of-warranty maintenance through platform-mediated dispatch.
China Mixer Grinder Market Segmentation
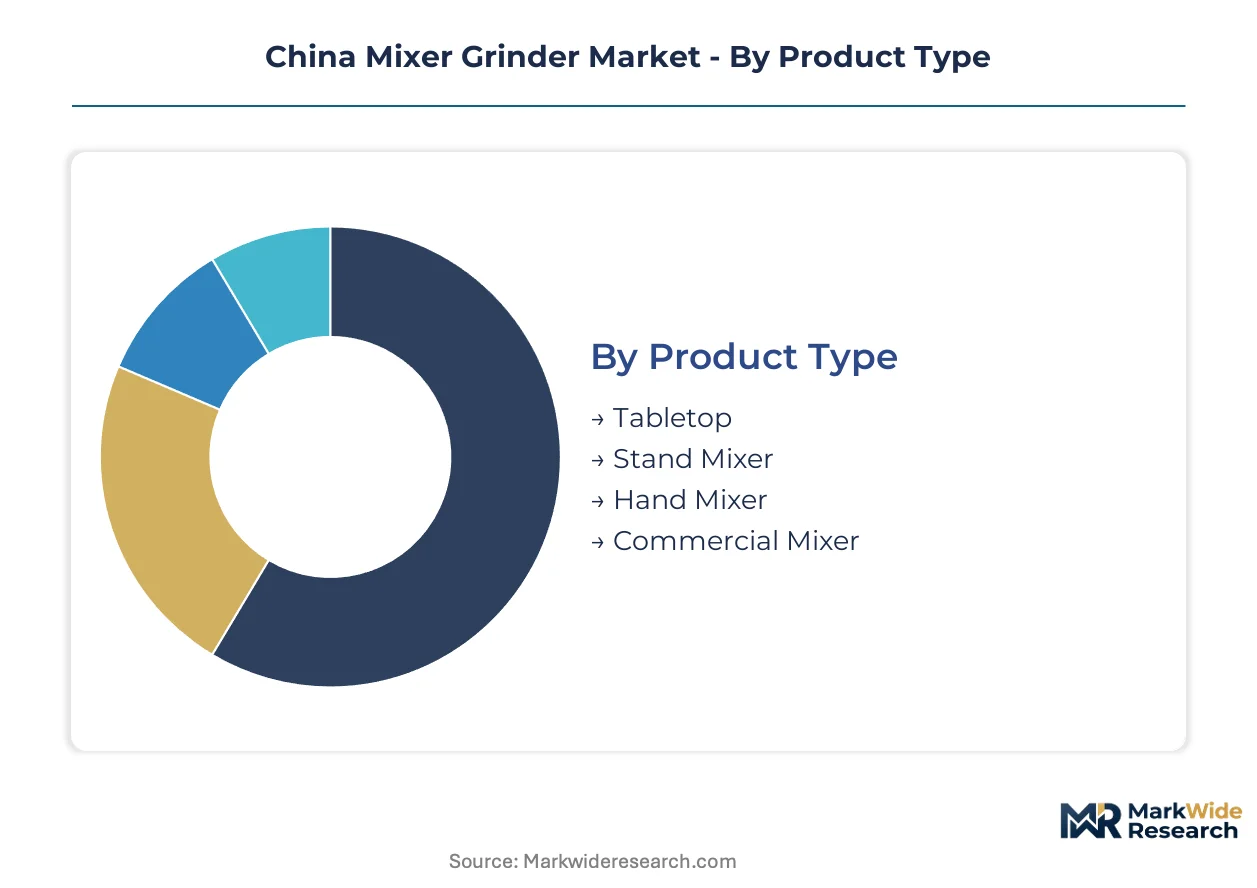
Mixer grinder segmentation in China reflects divergent engineering requirements across residential density gradients and food safety compliance tiers. Product architecture, end-use intensity, and motor technology each create distinct procurement channels with separate margin structures.
Product Type:
Cost tier differentiation separates compact urban solutions from commercial-grade batch processing equipment.
- Tabletop:Compact units with 500-750 watt universal or brushless DC motors dominate Shanghai and Guangzhou apartments under 70 square meters. MIIT energy-efficiency labeling drives procurement preference toward certified configurations in state-affiliated retail channels.
- Stand Mixer:Countertop units with planetary mixing action and 4-7 liter bowl capacity serve multi-generational households in tier-two cities. Replacement cycles are shortening as GB standards for food-contact materials filter subscale producers from modern trade distribution.
- Hand Mixer:Lightweight 200-300 watt units with detachable beaters address occasional-use households in interior provinces with underdeveloped service infrastructure.
- Commercial Mixer:Heavy-duty 1000+ watt configurations with stainless steel bowls and overload protection serve food service batch processing in Guangdong catering clusters.
Tabletop holds installed capacity. Commercial Mixer is rotating up the share rankings.
End User:
Application intensity determines motor specification, duty cycle rating, and after-sales service bundling.
- Residential:Daily meal preparation drives demand for noise reduction below 65 decibels in premium Shanghai and Shenzhen segments. Smart technology adoption accelerates fastest among buyers seeking algorithmic torque management for dough conditioning.
- Food Service:High-frequency batch processing in Jiangsu and Zhejiang restaurant chains requires continuous-duty motors with thermal cutoff protection and rapid blade replacement protocols.
- Catering:Mobile event operators in Henan and Hubei urban clusters prioritize portable medium-capacity units with generator-compatible power draws.
- Bakery:Specialized dough-conditioning applications demand precise speed control and reinforced gearboxes for gluten development in commercial production environments.
Residential commands volume concentration. Food Service is climbing the fastest on margin contribution.
Capacity:
Volume segmentation aligns with household size distribution and commercial batch economics.
- Low Capacity:Sub-1 liter bowls target single-person households in compact urban units where kitchen counter space measures under 1.5 linear meters.
- Medium Capacity:1.5-2.5 liter configurations serve standard three-person families across coastal provinces with established modern retail infrastructure and replacement purchase channels via JD.com and Tmall.
- High Capacity:3+ liter bowls address multi-generational households and small commercial operators in tier-two cities where centralized food preparation persists.
- Multi-functional:Modular attachment systems with interchangeable bowls, blades, and beaters capture premium positioning through versatility claims in Shenzhen and Guangzhou.
Medium Capacity anchors replacement revenue. Multi-functional is gaining share fastest on attachment economics.
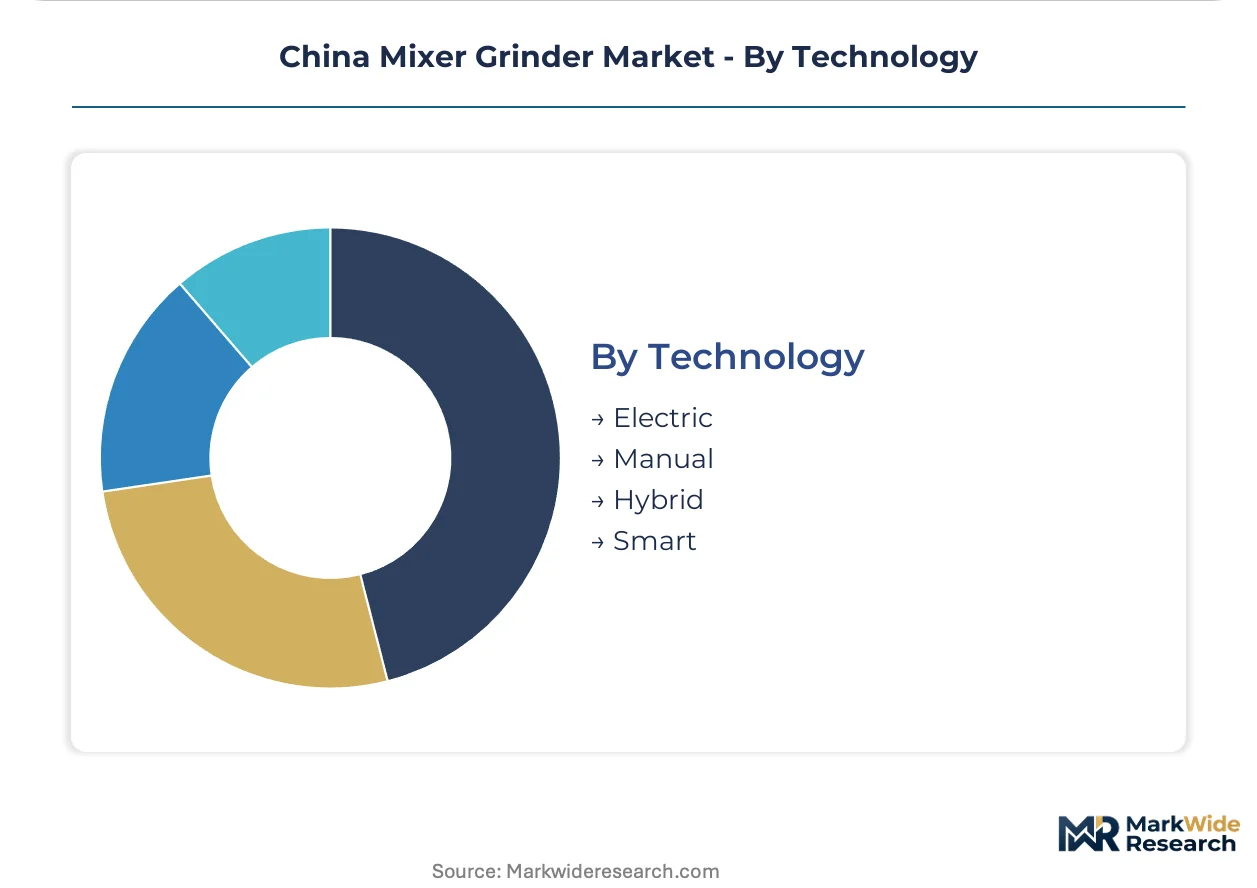
Technology:
Customer type stratification separates algorithmic performance seekers from cost-optimized mass market buyers.
- Electric:Universal motor platforms with carbon brush commutation occupy the mass-market core by unit economics, though brushless DC integration is compressing their share in premium tiers.
- Manual:Hand-cranked units persist in rural interior provinces with unreliable grid connectivity and elongated replacement cycles driven by underdeveloped service infrastructure.
- Hybrid:Dual-power configurations with manual override appeal to emergency preparedness segments and outdoor catering operators requiring operational redundancy.
- Smart:Load-sensing algorithms with Bluetooth connectivity and app-based recipe integration command premium pricing in Shanghai and Guangzhou residential segments seeking intelligent torque management.
Electric retains volume dominance. Smart is expanding most quickly on firmware differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium residential buyers in Shanghai and Guangzhou drive smart-feature adoption while tier-two cities in Henan and Hubei present ownership gaps of 30-40% below coastal benchmarks.
Yangtze River Delta
Shanghai's sub-70 square meter apartments compress demand toward compact tabletop units with multi-function attachments. MIIT energy-efficiency labeling creates procurement preference for certified products in state-affiliated retail channels. Suzhou and Hangzhou manufacturing clusters supply brushless DC motor components to domestic appliance brands.
Pearl River Delta
Guangzhou and Shenzhen households lead adoption of intelligent speed-control algorithms for dough-conditioning applications. SAMR enforcement of updated small-appliance quality regulations tightens CCC mark renewal protocols. Dongguan's electronics assembly corridor feeds component supply chains for premium residential segments.
Beijing-Tianjin-Hebei
Multi-generational households in Beijing drive demand for stand mixer configurations with 4-7 liter bowl capacity. NMPA electrical safety certification requirements filter subscale manufacturers from modern trade distribution. Tianjin's port infrastructure handles imported stainless steel alloys for blade assemblies.
Sichuan-Chongqing
Chongqing's hot pot culture sustains commercial mixer demand for high-frequency batch processing in restaurant chains. GB standards for food-contact material safety shape procurement specifications for stainless steel blade alloys. Chengdu's growing middle class accelerates replacement cycles for residential units.
Shandong Peninsula
Qingdao and Jinan urban clusters show rising penetration of medium-capacity 1.5-2.5 liter configurations among three-person families. Dual carbon goals pressure manufacturers toward energy-dense motor platforms. Weifang's small-appliance component ecosystem supports regional assembly operations.
China Mixer Grinder Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market consolidating around certified manufacturers with captive testing laboratories. The competitive structure stratifies into motor-integrated incumbents, assembly-dependent challengers, and smart-technology specialists. Dominant moves include backward integration into stator winding operations and geographic expansion into central province distribution infrastructure.
Within the motor-integrated tier, Midea Group and Joyoung exemplify vertically positioned manufacturers controlling component costs across value chains. Supor occupies a position anchored in brand recognition across tier-two and tier-three cities where replacement cycles compress. Heshan Zilong Home Appliance Technology represents the specialist fabricator archetype serving regional procurement channels with documented GB compliance histories.
| Leading Market Players |
|---|
| Midea Group |
| Joyoung |
| Hisense |
| TCL |
| Gree Electric Appliances |
| Haier |
| Supor |
| Galanz |
| Heshan Zilong Home Appliance Technology |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor magnet procurement from Jiangsu and Zhejiang manufacturing clusters concentrates upstream margin capture among vertically integrated appliance brands, compressing assembly-dependent challengers into price-taking positions downstream. MIIT energy-efficiency labeling creates tiered certification premiums that separate motor-integrated incumbents from component-assembling competitors in state-affiliated retail channels.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate motor component procurement, transferring commodity volatility risk to downstream manufacturers. Pricing stratifies across premium smart-feature tiers, standard MIIT-certified configurations, and economy universal motor segments. Price erosion runs through economy tiers as brushless DC platforms capture replacement volume in Shanghai and Guangzhou. Food service buyers show lowest price sensitivity due to continuous-duty reliability requirements, while occasional-use households in interior provinces drive hard bargaining on entry-level units.
Supply Chain Analysis
Neodymium magnet feedstock draws from Chinese rare earth processing facilities in Inner Mongolia and Jiangxi, with winding copper anchored in Chilean and Peruvian concentrate imports. Stator lamination steel sources from Baosteel and Shougang mills in Shanghai and Beijing. Single-source vulnerability concentrates in specialized motor controller firmware from Dongguan electronics corridors. Distribution runs through JD.com and Tmall platform ecosystems in coastal provinces, with traditional retail holding residual share in tier-three city networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against built-in grinding attachments in premium induction cooktops that displace standalone units in new-build residential installations across Guangdong and Jiangsu provinces.
For Market Incumbents: Harden defensive moats by internalizing stator winding operations to neutralize copper cost volatility and compress component lead times. Deepen captive testing laboratory investments ahead of SAMR inspection protocol expansions. Motor-controller firmware development represents the critical capability gap; acquiring embedded systems engineering capacity insulates against third-party module supplier bottlenecks. For New Entrants and Emerging Players: Henan and Hubei urban clusters present appliance ownership gaps of 30-40% below coastal benchmarks, offering first-mover terrain for distribution infrastructure investment. Medium-capacity 1.5-2.5 liter configurations serve underpenetrated three-person family segments in these interior provinces. A certified-brand partnership strategy with established GB compliance documentation accelerates shelf access faster than organic certification timelines permit. For Investors and Strategic Acquirers: Capital is best deployed toward motor-integrated mid-cap specialists with documented CCC mark renewal histories and captive magnet assembly operations. Long-term viability hinges on algorithmic torque management capabilities that command premium positioning in dough-conditioning applications. Watch SAMR enforcement intensity against uncertified competitors as the inflection signal for shelf consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captures margin previously flowing to discrete component suppliers in Jiangsu corridors. |
| CCC Certification Pre-Positioning | Compresses inventory risk ahead of NMPA testing queue bottlenecks during seasonal windows. |
| Smart-Mechanical Feature Integration | Enables premium pricing for load-sensing algorithms in Shanghai residential segments. |
| Central Province Distribution Buildout | Secures first-mover positioning in Henan and Hubei ownership gap markets. |
| After-Sales Service Platform Partnership | Adapts to JD.com and Tmall channel dominance in Guangdong repair dispatch networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with appliance brand product managers, motor component procurement leads, MIIT certification laboratory directors, JD.com category buyers, and independent repair technician networks. Secondary validation drew from MIIT energy-efficiency labeling databases, SAMR quality inspection bulletins, NMPA CCC mark registration records, and customs trade data for copper and rare earth imports. Bottom-up channel volume estimates and top-down manufacturing capacity assessments were triangulated against retail audit data.
Calibration against historical replacement cycle data and urban household formation rates anchored the analytical framework across the projection horizon. Segmentation modeling spanned product type tiers, end-use intensity categories, motor technology platforms, and regional income distribution patterns. CAGRs were derived from installed base dynamics and penetration rate trajectories. Brushless DC motor cost curves and GB standard implementation timelines served as industry-specific forecast inputs.
Practitioners should monitor copper price volatility, SAMR enforcement intensity, and induction cooktop attachment penetration for early signals of forecast revision. Cross-checking against MIIT shipment data and provincial retail audit benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
South Korea Kitchen Appliances Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
India Electric Vegetable Choppers Market