
 Household Appliance Market | 2026-2036
Household Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Household Appliance Market Outlook
Chinese white-goods manufacturing clusters is restructuring global component sourcing as domestic producers scale inverter-compressor and brushless-motor output. Haier Smart Home leverages its intercontinental factory network to anchor supply across Europe, North America, and Southeast Asia. Whirlpool Corporation sustains its North American installed-base advantage through captive service infrastructure and replacement-part revenue streams. Midea Group competes on vertical cost discipline, extending from steel-stamping and injection-molding through final assembly.
Household appliances comprise electromechanical devices designed for domestic tasks including food preservation, textile cleaning, meal preparation, and ambient comfort, typically operating on alternating-current mains power at 110–240 volts and 50–60 hertz depending on regional standards. Refrigerators dominate product-type value pools due to compressor-system complexity and replacement-cycle premiums, while smart-appliance technology segments attract disproportionate R&D allocation as Wi-Fi modules and voice-protocol integration become baseline expectations. Online retail channels are gaining share in distribution-channel structures, though specialty stores retain influence in premium-tier transactions where tactile evaluation and installation-service bundling matter.
EPA ENERGY STAR specifications in the United States, EU Ecodesign requirements administered by the European Commission, and China's GB standards enforced by SAMR collectively tighten minimum-efficiency thresholds and reshape product-development roadmaps. These frameworks elevate compliance costs for smaller manufacturers while creating specification advantages for scaled producers with in-house test laboratories. Stakeholders must monitor regulatory divergence between efficiency-labeling regimes and smart-appliance cybersecurity certification as the next frontier of market-access differentiation.
Market Dynamics
Energy-efficiency mandates under the EU Ecodesign Directive and parallel frameworks are compressing replacement cycles and forcing component-level redesigns across compressor systems and motor drives, restructuring competitive advantage toward scaled producers with captive testing infrastructure.
Growth Catalysts
- Urban household formation:Developing economies in India, Brazil, and Indonesia are driving first-time refrigerator and washing machine purchases as middle-class expansion accelerates appliance penetration rates.
- EU Ecodesign Directive:Mandatory minimum-efficiency thresholds for cold appliances and washing machines are accelerating replacement demand across European households.
- Inverter-compressor technology:Variable-speed refrigeration systems are reducing energy consumption by 30-50% versus conventional compressors, creating specification premiums in replacement markets.
Market Restraints
- Copper and steel price volatility:Input cost swings for compressor windings and stamped cabinet components compress margin visibility for manufacturers without long-term supply contracts.
- Semiconductor dependency:Brushless-motor controllers and Wi-Fi modules concentrate sourcing in Taiwan and South Korea foundries, exposing production schedules to foundry allocation constraints.
- Refrigerant transition friction:F-Gas Regulation phase-down schedules in Europe and Kigali Amendment implementation timelines create compliance cost uncertainty for cold-chain appliance portfolios.
Strategic Opportunities
- Rural electrification corridors:India's Saubhagya scheme and Brazil's Luz para Todos program are creating addressable demand for basic refrigeration in previously off-grid households.
- Voice-protocol integration:Natural-language processing modules from Amazon Alexa and Google Assistant ecosystems are enabling premium-tier differentiation through hands-free appliance control.
- China's dual carbon goals:National mandates for peak emissions by 2030 are accelerating subsidies for super-efficient appliances, creating procurement advantages for inverter-equipped product lines.
Industry Challenges
- Power electronics talent scarcity:Shortages of firmware engineers with motor-control algorithm expertise are extending development timelines for variable-speed drive systems.
- Cybersecurity certification fragmentation:Divergent IoT security standards between ETSI EN 303 645 in Europe, NIST IR 8259 in the United States, and GB/T standards in China multiply compliance engineering burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Appliance Market |
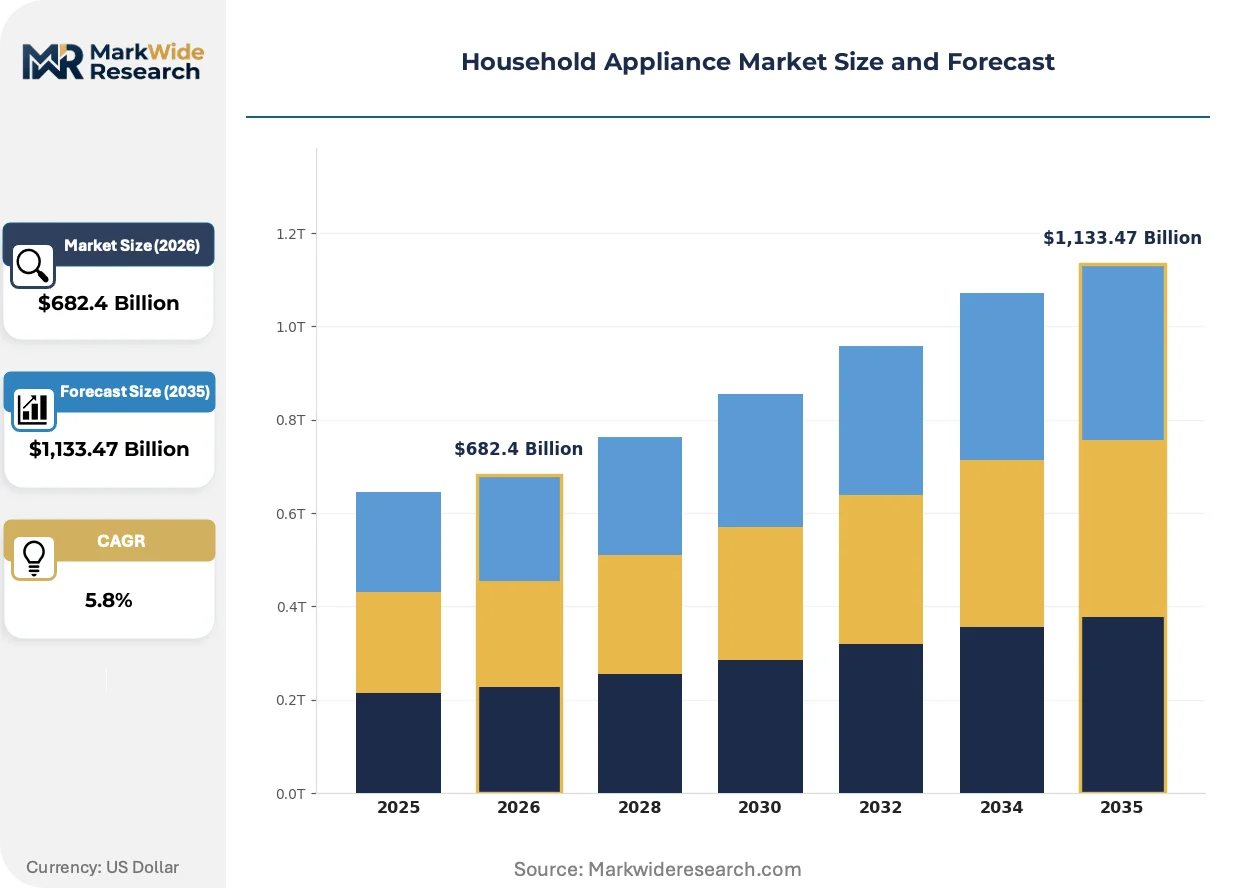
| Market Size in 2026 | $682.4 Billion |
| Market Size in 2035 | $1,133.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwave Ovens, Dishwashers End User: Households, Apartments, Hotels, Offices Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Technology: Smart Appliances, Energy-Efficient, IoT-Enabled, Eco-Friendly |
| Companies Covered | Haier Smart Home, Whirlpool Corporation, Midea Group, Samsung Electronics, LG Electronics, BSH Hausgeräte, Electrolux Group, Panasonic Holdings Corporation, Arçelik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Appliance Market Strategic Shifts
Connected appliance architectures and refrigerant chemistry transitions are converging to redefine product roadmaps, with efficiency mandates and digital service layers simultaneously reshaping hardware specifications and aftermarket revenue models.
Heat-pump drying technology is integrating into mainstream washing machine and standalone dryer portfolios, replacing resistive heating elements with vapor-compression cycles that recover waste heat. European and East Asian manufacturers are scaling production of R290 propane-based heat-pump systems to meet 2025 efficiency tiers. This shift is integrating humidity-sensing controls and variable-speed compressors as standard configurations, compressing the addressable market for conventional vented dryers.
Revisions to the EU F-Gas Regulation are mandating accelerated phase-down of hydrofluorocarbon refrigerants with GWP above 150 for domestic cold appliances. Manufacturers are retooling compressor platforms for R600a isobutane and R290 propane alternatives, requiring redesign of charge sizes and safety systems. Cold appliance portfolios destined for European markets are absorbing the bulk of compliance engineering resources, diverting attention from other regulatory domains.
Direct-to-consumer subscription models for appliance maintenance and predictive replacement are displacing traditional warranty and extended-service-plan structures. Younger cohorts in North American and Western European urban markets are prioritizing access over ownership, with bundled energy-management services gaining traction. Germany and the Netherlands exhibit the highest penetration of appliance-as-a-service pilots, where efficiency guarantees and proactive failure detection justify recurring fee structures over capital purchase.
Household Appliance Market Segmentation
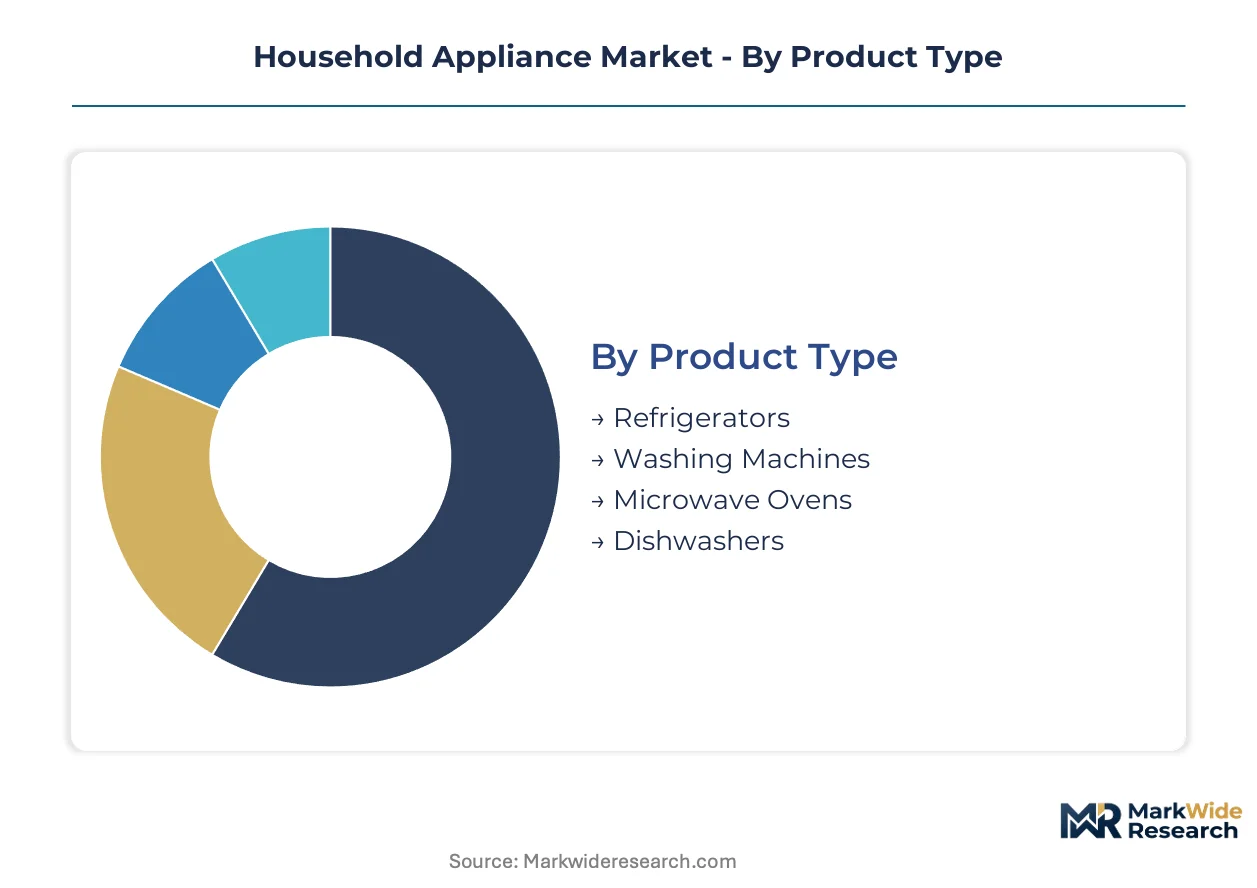
Segmentation in the household appliance market reveals divergent replacement-cycle economics across product categories and technology tiers. Upgrade triggers range from regulatory efficiency mandates to smart-home integration demands, creating distinct addressable pools within each segment dimension.
Product Type:
Upgrade cycles vary dramatically across product categories, with compressor-based systems commanding longer replacement intervals than heating-element appliances.
- Refrigerators:Compressor-system complexity and refrigerant chemistry transitions drive 12-15 year replacement cycles. Chinese and Indian urban households anchor first-time purchase volume as cold-chain penetration deepens in developing economies.
- Washing Machines:Heat-pump drying integration and variable-speed motor drives are compressing European replacement timelines. Germany and the Netherlands exhibit accelerated upgrade rates as efficiency tiers tighten under EU Ecodesign.
- Microwave Ovens:Magnetron-based heating systems face shorter replacement cycles of 7-9 years. Urban apartment dwellers in Brazil and Indonesia drive volume through compact countertop formats.
- Dishwashers:Water-heating element corrosion and pump seal degradation define 10-12 year lifespans. Western European households maintain highest installed-base density.
Refrigerators sit at the top of the volume ranking, with washing machines climbing the fastest on heat-pump technology adoption.
End User:
Customer-type segmentation exposes divergent procurement patterns between ownership models and service-based access.
- Households:Single-family dwellings prioritize energy-efficiency certifications and smart-home compatibility. India's expanding middle-class drives first-time refrigerator and washing machine acquisitions.
- Apartments:Space-constrained urban units demand compact form factors and stackable configurations. Brazilian metropolitan markets favor slim-depth refrigeration and front-loading washers.
- Hotels:Commercial durability specifications and uniform fleet aesthetics govern procurement. Mini-bar refrigeration and in-room coffee systems represent high-frequency replacement categories.
- Offices:Break-room appliances emphasize low-maintenance operation and basic functionality. Water dispensers and compact refrigeration dominate corporate facility budgets.
Households command the dominant share of unit volume, with apartments expanding most quickly on urban densification trends.
Distribution Channel:
Channel structure reflects varying need for tactile evaluation, installation complexity, and after-sales service bundling.
- Online Retail:E-commerce platforms capture growing share in replacement purchases where specifications are standardized. China's JD.com and Tmall anchor volume through festival-period discounting.
- Specialty Stores:Appliance-focused retailers retain influence in premium-tier transactions requiring demonstration and consultation. Germany's MediaMarkt Saturn network sustains showroom-based conversion for built-in kitchen systems.
- Supermarkets:Mass-merchant channels concentrate on entry-level price points and impulse replacement purchases. Walmart's US appliance aisles move high volumes of microwave ovens and compact refrigeration.
- Direct Sales:Manufacturer-owned channels bypass margin stacking for full-line kitchen packages. Haier Smart Home's direct-to-consumer platforms in China integrate smart-home ecosystem sales.
Specialty stores maintain the highest average transaction value, with online retail gaining share fastest on logistics network maturation.
Technology:
Technology tiers increasingly determine market access, with efficiency and connectivity specifications becoming baseline rather than premium differentiators.
- Smart Appliances:Wi-Fi module integration and voice-protocol compatibility enable remote monitoring and energy management. Amazon Alexa and Google Assistant ecosystems drive specification convergence in North American markets.
- Energy-Efficient:Inverter-compressor and brushless-motor systems reduce power consumption 30-50% versus conventional alternatives. EU Ecodesign thresholds and China's dual carbon subsidies accelerate specification mandates.
- IoT-Enabled:Predictive maintenance algorithms and usage-pattern analytics support subscription-based service models. Dutch and German pilots demonstrate appliance-as-a-service viability.
- Eco-Friendly:R600a isobutane and R290 propane refrigerants replace high-GWP hydrofluorocarbons under EU F-Gas phase-down schedules. Safety-system redesigns absorb engineering resources for European-bound production.
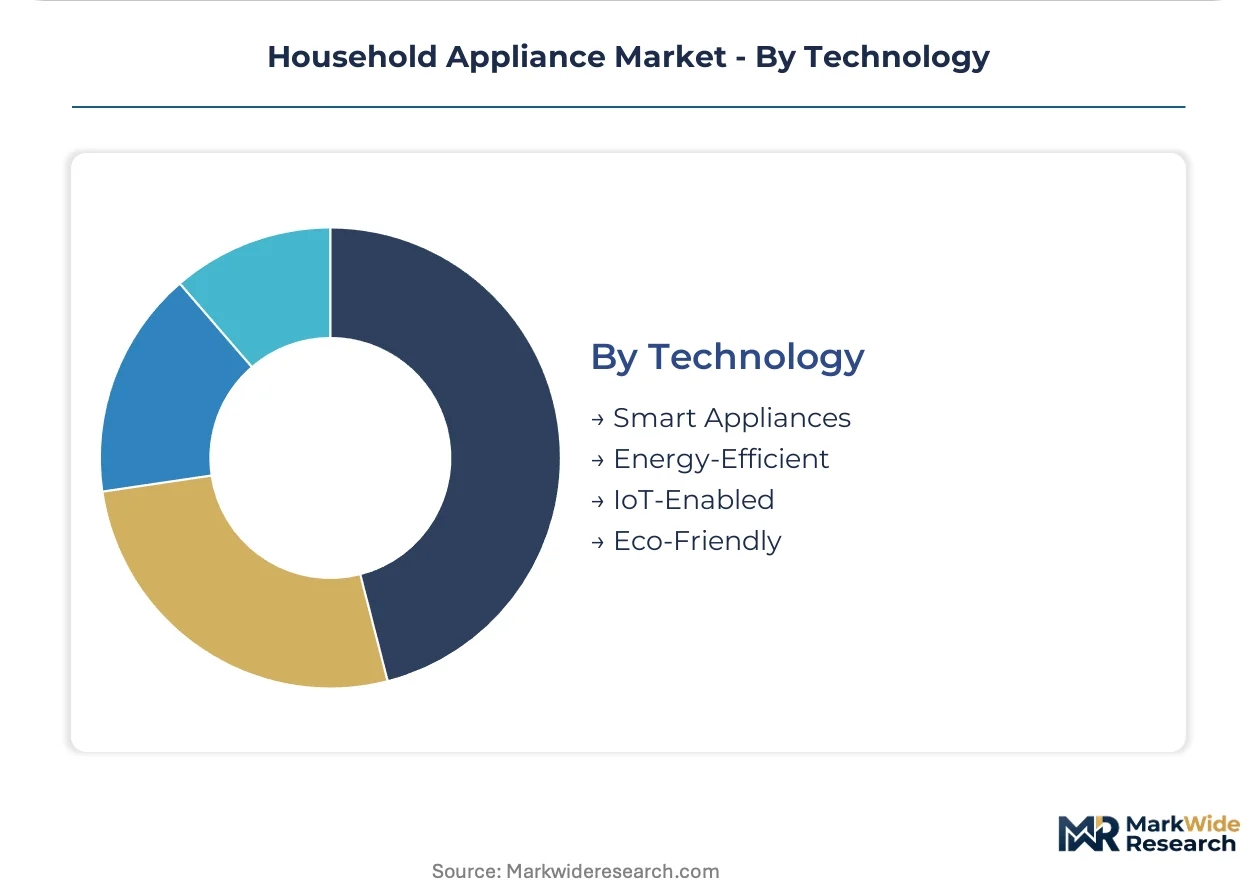
Energy-efficient models dominate current shipment volumes, with IoT-enabled configurations showing the steepest expansion trajectory on predictive service model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as manufacturers relocate assembly to jurisdictions with lower compliance-cost burdens. The EU Ecodesign Directive's stringent efficiency thresholds push final assembly toward export platforms with lighter domestic mandates.
China
Urban household formation and middle-class expansion drive refrigerator and washing machine penetration in tier-2 and tier-3 cities. SAMR enforces GB standards that increasingly align efficiency benchmarks with export-market requirements. Qingdao and Foshan manufacturing clusters concentrate inverter-compressor and brushless-motor production for global supply.
United States
Replacement demand dominates as installed-base saturation limits first-time purchases to household formation and disaster-driven replacement. EPA ENERGY STAR specifications tighten minimum-efficiency thresholds for cold appliances entering the market. Midwest industrial corridors around Chicago and Detroit retain stamping and injection-molding capacity for domestic assembly.
Germany
EU Ecodesign mandates compress replacement cycles for washing machines and refrigerators as efficiency tiers render older units economically obsolete. The F-Gas Regulation accelerates refrigerant chemistry transitions toward R290 propane and R600a isobutane alternatives. Bavaria and North Rhine-Westphalia host testing laboratories and engineering centers serving European compliance requirements.
India
Saubhagya rural electrification and urban middle-class expansion create dual demand tracks for basic refrigeration and premium inverter-equipped models. BIS certification requirements and PLI scheme subsidies for component manufacturing reshape local sourcing economics. Gujarat and Tamil Nadu industrial zones attract compressor and motor-drive assembly investments.
Brazil
Luz para Todos electrification programs extend addressable demand into previously off-grid rural households while metropolitan markets upgrade to inverter technology. ANVISA and INMETRO efficiency-labeling frameworks tighten market-access requirements. São Paulo state manufacturing parks serve Mercosur distribution with regionally adapted product specifications.
Household Appliance Market Competitive Environment
Chinese producers anchor the scale-driven tier; European and North American specialists hold premium positions through service infrastructure and brand equity. The vendor base concentrates around integrated manufacturers with captive component production and testing capabilities. Three archetypes dominate: vertically integrated full-line suppliers, regional specialists with deep installed-base relationships, and technology licensors monetizing motor-control and compressor IP. Competitive moves center on intercontinental factory-network expansion and predictive-service subscription models.
Among Asia-Pacific-based fabricators, Haier Smart Home, Midea Group, and Samsung Electronics exemplify the integrated-scale archetype. These entities occupy positions spanning component production through final assembly, with factory networks distributed across multiple continents to hedge regulatory and logistics exposures. Their competitive posture rests on inverter-compressor and brushless-motor manufacturing depth rather than brand premium extraction.
| Leading Market Players |
|---|
| Haier Smart Home |
| Whirlpool Corporation |
| Midea Group |
| Samsung Electronics |
| LG Electronics |
| BSH Hausgeräte |
| Electrolux Group |
| Panasonic Holdings Corporation |
| Arçelik |
| Others |
Value Chain & Pricing Dynamics
Compressor-motor control firmware engineers concentrated in China's Pearl River Delta and Germany's Bavaria anchor labor-cost differentials that spread pricing tiers across premium inverter-equipped and basic fixed-speed appliance lines. These talent pools command wage premiums that manufacturers pass through to specification-tier spreads, compressing margins on mid-range configurations.
Pricing Analysis
Distributor margin layers absorb 15-25 points before retailer markup, with direct-to-OEM volume discounts compressing channel economics for bulk fleet sales. Three-tier pricing structure across premium, standard, and economy levels separates Wi-Fi-enabled inverter systems from basic fixed-speed units, with certification grade under EU Ecodesign and EPA ENERGY STAR driving tier boundaries. Price erosion runs through entry-level refrigerator and washing machine segments as Chinese producers scale inverter-compressor output. Households in India's tier-2 cities exhibit highest price sensitivity, while German apartment dwellers prioritize efficiency certification over first cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns that feed specialty retail and direct-sales channels. Component sourcing concentrates in China for inverter-compressor platforms, Taiwan for brushless-motor controllers, and South Korea for display modules. Steel coil and copper winding dependencies expose margin visibility to commodity exchanges in London and Shanghai. Single-source vulnerability in Taiwan foundry capacity for power semiconductors threatens production schedules during allocation crunches. Distribution runs through manufacturer-owned logistics networks for built-in kitchen systems, while mass-merchant channels rely on third-party warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The household appliance market compounds steadily as regulatory efficiency mandates force replacement cycles regardless of macroeconomic conditions. This structural demand floor supports predictable revenue streams for positioned participants.
For Market Incumbents: Hedge semiconductor sourcing exposure by qualifying second-source foundries for motor-control ICs outside Taiwan. Capture inverter-compressor service revenue through predictive maintenance subscriptions that lock in replacement-part demand. Defend against white-label entrants from Chinese manufacturing clusters by deepening captive testing laboratory accreditation for EU Ecodesign compliance.
For New Entrants and Emerging Players: EU F-Gas Regulation phase-down schedules in Europe open a window for R290 propane-based heat-pump dryer specialists to capture share from incumbents retooling legacy platforms. Target India's rural electrification corridors with basic refrigeration units certified to BIS standards at price points below established brands. Pursue direct-to-consumer online launch with festival-period discounting synchronized to JD.com and Tmall promotional calendars.
For Investors and Strategic Acquirers: Component manufacturers with captive inverter-compressor IP are the most active acquirer category in this space, consolidating motor-control algorithm assets. Long-term viability rests on service-revenue attachment rates rather than hardware shipment volumes. Monitor appliance-as-a-service pilot conversion rates in Germany and the Netherlands as the inflection signal for subscription-model scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Inverter-Compressor Platform Expansion | Captures EU Ecodesign efficiency tiers and China's dual carbon subsidy eligibility. |
| Predictive Maintenance Service Launch | Converts installed-base data into recurring revenue through proactive failure detection. |
| R290 Propane Heat-Pump Scale-Up | Meets 2025 EU F-Gas Regulation requirements for domestic cold appliances. |
| Direct-to-Consumer Channel Buildout | Bypasses margin stacking for full-line kitchen packages in China's urban markets. |
| Second-Source Semiconductor Qualification | Reduces Taiwan foundry concentration risk for brushless-motor controller supply. |
Study Parameters
Coverage spans China, the United States, Germany, India, and Brazil, with primary inputs from each market's stakeholder ecosystem. Interviews with appliance manufacturer product managers, retail category buyers, compressor platform engineers, and regulatory compliance officers combined with secondary validation from SAMR GB standard filings, EPA ENERGY STAR certification databases, EU Ecodesign implementing measure texts, and customs trade records. Bottom-up shipment estimates triangulated against top-down household penetration models.
Rate-of-change decomposition separates volume growth from mix-shift and pricing components across the projection horizon. Segmentation dimensions modeled include product type, technology tier, distribution channel, and end-user configuration, with regulatory compliance tier and refrigerant chemistry platform as industry-specific stratifiers. CAGRs derive from fitted adoption curves applied to household formation forecasts and replacement-cycle compression factors. Inverter-compressor penetration rates and smart-appliance connectivity attachment serve as key forecast inputs.
Revisions become necessary when regulatory implementation timelines shift, foundry allocation crises disrupt semiconductor supply, or refrigerant chemistry transitions accelerate beyond modeled schedules. Forecasts reflect documented assumptions regarding efficiency mandate enforcement consistency and subsidy program continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Australia Washing Machine Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Connected Home Appliances Market
Home Appliances
Europe White Goods Market
Home Appliances
Steam Clothing Care System Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Undercounter Refrigerators Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Major Home Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Portable Dehumidifier Market