
 Poland Data Center Rack Market | 2026-2036
Poland Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Data Center Rack Market Insights
The divergence between premium and commodity tiers is hardening as hyperscale operators demand customized 48U enclosures with integrated power distribution and thermal management, while smaller colocation providers prioritize cost-optimized open frame configurations. Schneider Electric leverages its European manufacturing footprint to anchor premium cabinet supply chains serving Warsaw's expanding cloud corridor. Rittal competes through modular enclosure architectures that accommodate liquid cooling retrofits. Beyond.pl sustains its position as a domestic operator with deep integration into Polish enterprise and government data center buildouts.
Data center racks are standardized metal frameworks designed to house servers, networking equipment, and power distribution units, typically conforming to 19-inch mounting widths with vertical rail spacing measured in rack units. These structures enable organized cable management, airflow optimization, and physical security within controlled environment facilities. Enclosed rack and cabinet configurations command margin premiums as thermal containment and acoustic isolation requirements intensify across Polish hyperscale deployments. Open frame segments retain volume leadership among telecommunications operators prioritizing accessibility and rapid equipment swap capacity. Custom size configurations represent the fastest-growing dimension as non-standard IT loads proliferate in AI training clusters.
Polish data center construction falls under EU Green Deal energy performance frameworks and national building codes administered by the country's energy regulatory authority, while CE marking requirements govern electrical and mechanical safety compliance for rack-mounted power distribution components. The EU F-Gas Regulation constrains cooling system refrigerant choices, indirectly shaping rack-level thermal design specifications and vendor qualification criteria. Stakeholders must monitor how forthcoming EU AI Act infrastructure transparency requirements could mandate rack-level energy consumption disclosure and reshape procurement evaluation protocols for Polish facility operators.
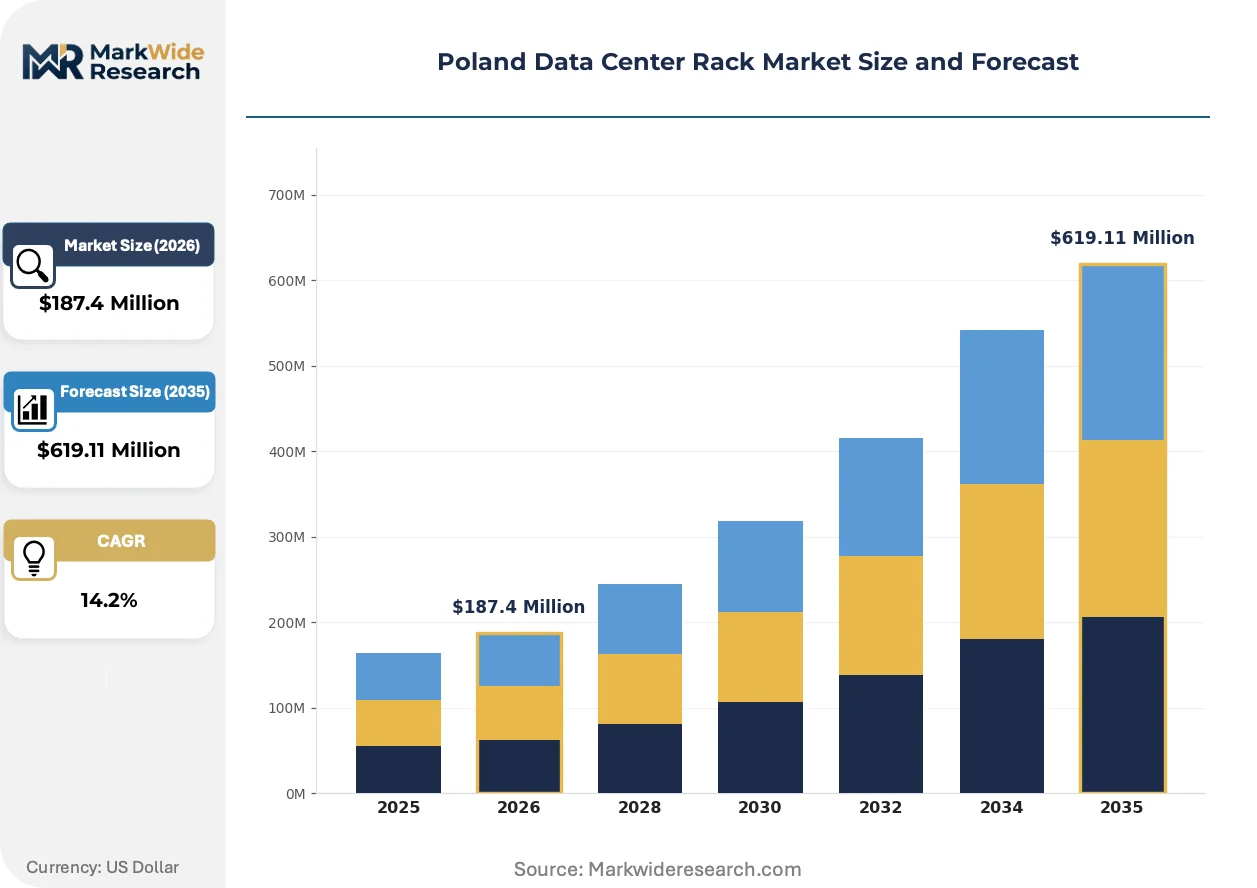
Market Dynamics
Hyperscale cloud operators in Warsaw and Krakow are driving a specification divergence that splits the Poland data center rack market between customized 48U enclosures with integrated power and thermal systems versus cost-optimized open frame configurations for smaller colocation providers.
Growth Catalysts
- EU Green Deal compliance mandates:Poland's alignment with EU energy efficiency directives is reshaping procurement standards, forcing facility operators to specify racks with advanced thermal containment and power monitoring capabilities.
- Hyperscale facility construction:Warsaw's metropolitan corridor is experiencing concentrated demand from cloud service providers deploying AI training infrastructure requiring non-standard rack configurations.
- Liquid cooling retrofit compatibility:Modular enclosure architectures that accommodate direct-to-chip cooling systems are capturing premium positioning as thermal densities rise in Polish deployments.
Market Restraints
- Steel and aluminum input volatility:Rack manufacturing faces margin compression from fluctuating commodity metal prices, particularly affecting domestic fabricators serving cost-sensitive telecommunications operators.
- CE marking certification timelines:Electrical and mechanical safety compliance requirements for power distribution components create extended qualification periods that delay vendor entry.
- EU F-Gas Regulation constraints:Cooling system refrigerant restrictions indirectly limit rack-level thermal design options, compressing vendor flexibility in specifying integrated cooling solutions.
Strategic Opportunities
- AI infrastructure transparency requirements:Forthcoming EU AI Act provisions mandating rack-level energy consumption disclosure will create demand for smart monitoring-integrated enclosures.
- Government and enterprise buildouts:Domestic operators with established relationships in Polish public sector data center projects are positioned to capture standardized procurement contracts.
- Edge computing distribution models:Regional colocation providers outside Warsaw are adopting prefabricated modular rack systems to accelerate deployment timelines in secondary markets.
Industry Challenges
- Thermal engineering specialization gap:Polish facilities lack sufficient expertise in liquid cooling integration, forcing reliance on foreign system integrators for high-density deployments.
- Legacy infrastructure interoperability:Retrofitting existing data centers with new rack standards requires complex cable management and power distribution reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Data Center Rack Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mount, Cabinet End User: Telecommunication, IT Service Providers, Enterprises, Government Size: 42U, 45U, 48U, Custom Mounting Type: Floor-Mount, Wall-Mounted, Sliding, Portable |
| Companies Covered | Schneider Electric, Hewlett Packard Enterprise, Eaton Corporation, Rittal, Black Box Corporation, Atman, Beyond.pl, Equinix, Data4, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Data Center Rack Market Trends and Innovations
Poland's data center rack landscape is undergoing rapid specification evolution as thermal density requirements from AI workloads clash with EU-mandated sustainability frameworks and procurement centralization among hyperscale operators.
Liquid-ready rack architectures with pre-installed manifolds and blind-mate quick disconnects are overtaking air-cooled-only designs in Warsaw's cloud corridor. Hyperscale operators specify these configurations for 30-50kW per rack densities. The shift is compressing lead times for traditional air-cooled cabinet suppliers.
The EU AI Act's infrastructure transparency provisions are forcing Polish facility operators to specify racks with embedded power metering at the branch circuit level. This regulatory pressure is elevating vendors with native monitoring capabilities over pure mechanical fabricators. Colocation providers in Krakow are responding by unbundling rack specifications from broader facility contracts.
Consolidated procurement by cloud service providers is fragmenting the vendor base serving mid-market colocation operators. These smaller buyers are shifting toward distributor channels for standardized open frame configurations rather than direct manufacturer relationships. The behavioral shift is most pronounced among telecommunications operators prioritizing rapid equipment swap capacity over thermal optimization.
Poland Data Center Rack Market Segmentation
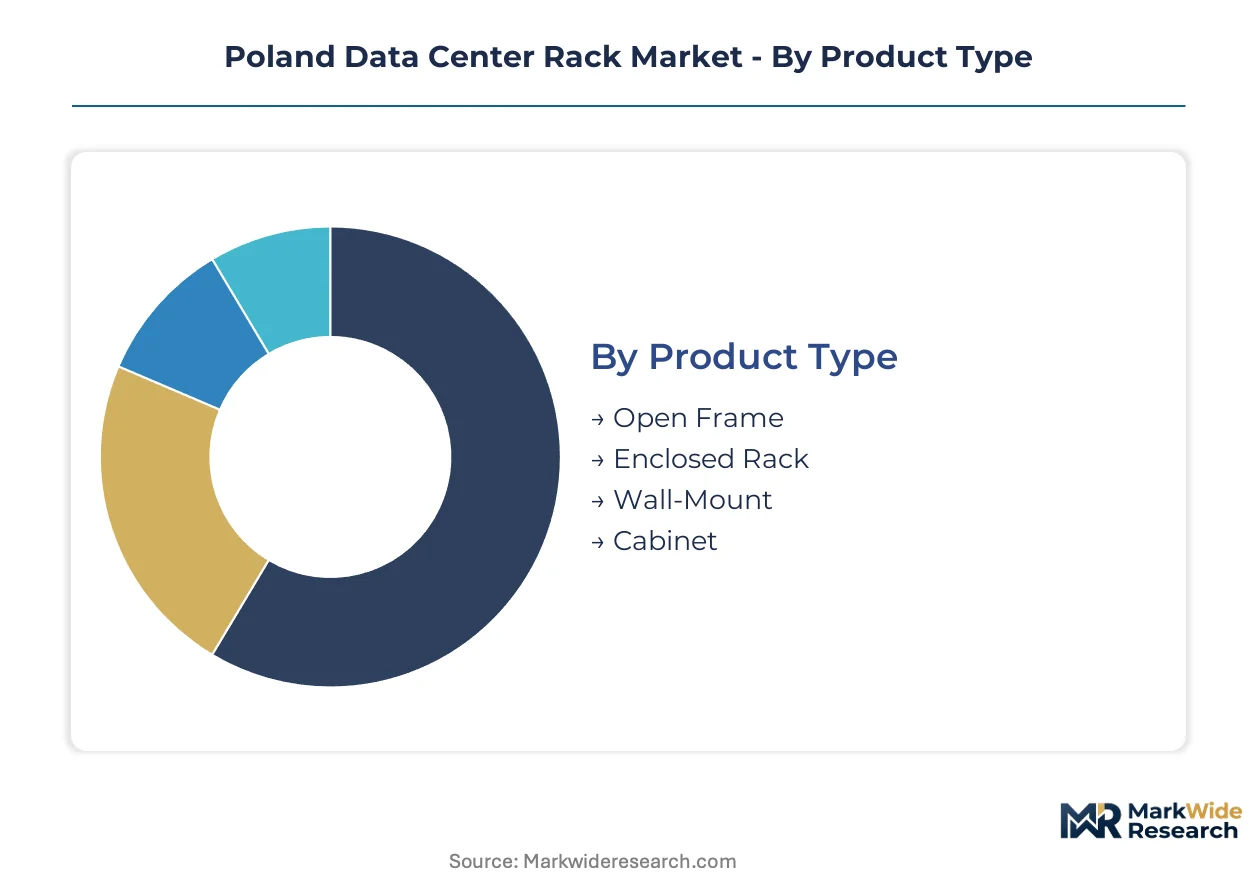
Segmentation in Poland's data center rack market reveals divergent procurement patterns between hyperscale cloud operators demanding integrated thermal and power systems versus cost-sensitive telecommunications providers prioritizing rapid equipment accessibility. Specification fragmentation across Warsaw's cloud corridor and Krakow's emerging facilities creates distinct vendor positioning opportunities.
Product Type:
Open frame configurations dominate volume shipments while enclosed cabinets capture premium margins as thermal containment requirements intensify under EU Green Deal compliance.
- Open Frame:Four-post and two-post metal frameworks without side panels or doors, optimized for cable accessibility and rapid server swaps. Telecommunications operators in Warsaw's metro corridor deploy these for network equipment requiring frequent maintenance access, constrained by steel price volatility compressing domestic fabricator margins.
- Enclosed Rack:Fully enclosed cabinets with lockable doors, side panels, and integrated cable management channels. Hyperscale cloud providers across Warsaw's expanding facilities specify these with advanced thermal containment for AI training clusters, driven by EU energy efficiency directives mandating airflow optimization.
- Wall-Mount:Compact enclosures secured to vertical surfaces for space-constrained edge deployments. Regional colocation providers outside major metros adopt these for distributed infrastructure.
- Cabinet:Heavy-duty enclosed units with reinforced frames supporting higher static loads. Polish enterprise data centers specify these for high-density storage arrays.
Mature deployment sits with Open Frame configurations in legacy telecommunications infrastructure. Newer deployment is concentrated in Enclosed Rack systems for hyperscale cloud facilities.
End User:
Procurement centralization among cloud service providers is fragmenting vendor relationships with smaller buyers who increasingly source through distributor channels.
- Telecommunication:Network operators prioritizing equipment accessibility and rapid swap capacity over thermal optimization. These buyers favor standardized open frame configurations sourced through distributors rather than direct manufacturer relationships, responding to compressed capital expenditure cycles.
- IT Service Providers:Colocation and managed hosting operators serving mid-market enterprises. Facilities in Krakow unbundle rack specifications from broader facility contracts to capture procurement flexibility, adapting to EU AI Act transparency requirements mandating branch-circuit power metering.
- Enterprises:Polish corporations building captive data center capacity. These buyers balance cost optimization with compliance requirements under national building codes administered by the energy regulatory authority.
- Government:Public sector data center buildouts with standardized procurement protocols. Domestic operators with established relationships capture these contracts through formal tender processes.
Volume procurement concentrates with Telecommunication operators. Margin expansion is concentrated in IT Service Providers deploying liquid-ready architectures.
Size:
Standard height specifications face displacement as non-standard IT loads from AI infrastructure proliferate across Polish deployments.
- 42U:Traditional industry standard height for server and networking equipment. Legacy facilities in Poland's secondary markets continue specifying these for replacement cycles, constrained by existing power distribution and cooling infrastructure designed around this footprint.
- 48U:Extended height enclosures enabling higher equipment density per floor tile. Hyperscale operators in Warsaw's metropolitan corridor demand customized 48U configurations with integrated power distribution and thermal management systems, climbing the fastest as cloud providers maximize space efficiency.
- 45U:Intermediate height offering density gains without full infrastructure redesign. Mid-market colocation providers adopt these for incremental upgrades.
- Custom:Non-standard dimensions accommodating specialized AI training hardware and liquid cooling manifolds. These configurations expand most quickly as thermal densities reach 30-50kW per rack in Warsaw's cloud corridor.
Standardized deployment dominates 42U specifications. Accelerated deployment is concentrated in Custom configurations for AI infrastructure.
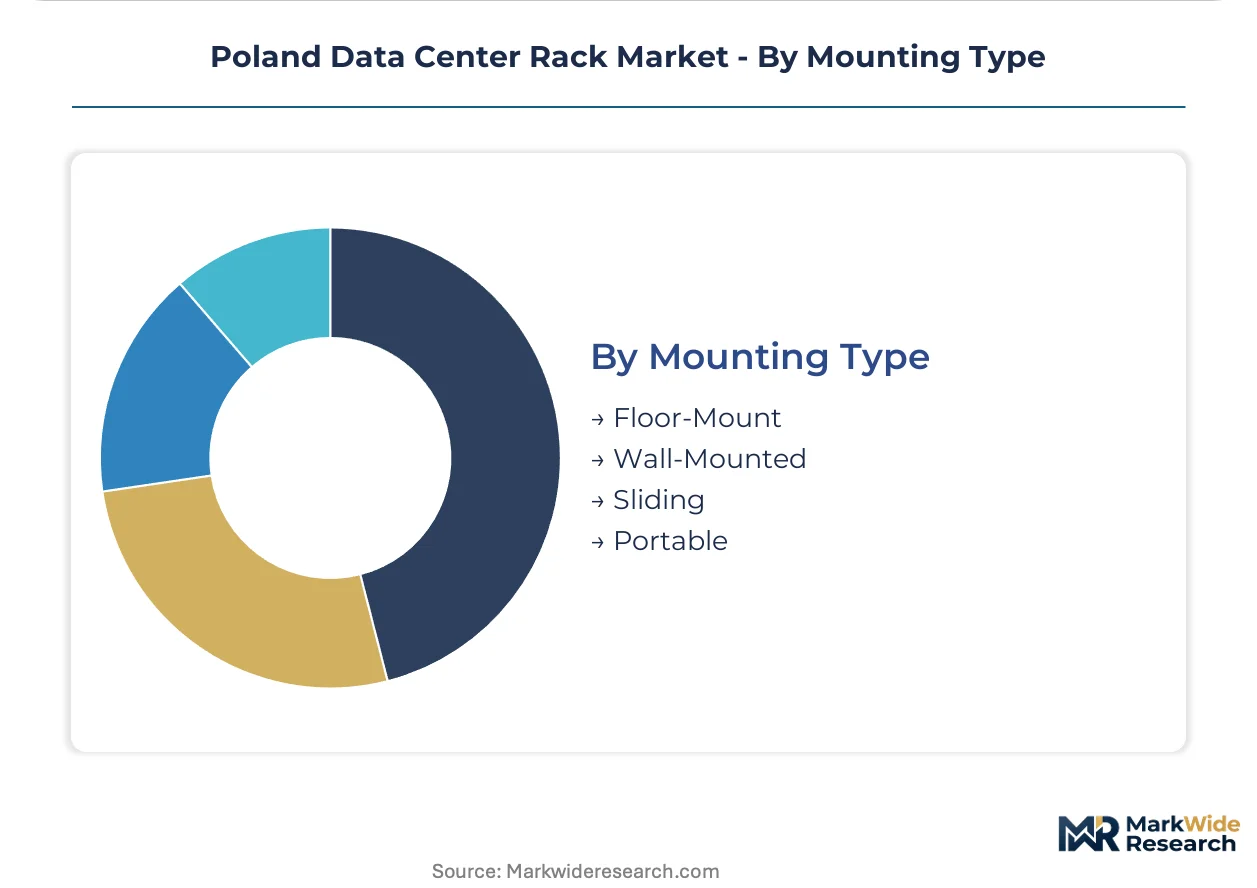
Mounting Type:
Floor space constraints and modular construction trends are reshaping physical installation methods across Polish data center builds.
- Floor-Mount:Standard four-point anchored installations supporting full-height cabinets. Hyperscale facilities in Warsaw specify these for primary compute halls with seismic bracing and raised floor integration.
- Wall-Mounted:Vertical surface installations for network closets and edge locations. Secondary market colocation providers adopt these to maximize usable floor space in converted industrial facilities.
- Sliding:Rail-mounted systems enabling equipment extraction for maintenance. Enterprise data centers specify these for high-availability environments requiring minimal downtime.
- Portable:Castor-mounted units for temporary or reconfigurable deployments. Test and development environments utilize these for rapid infrastructure reorganization.
Permanent infrastructure relies on Floor-Mount systems. Flexible deployment is concentrated in Portable configurations for dynamic environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw's metropolitan corridor concentrates Poland's data center rack demand as hyperscale cloud operators expand AI training infrastructure across the capital region. The EU Green Deal's energy efficiency mandates reshape procurement standards nationwide, while regional colocation providers in secondary markets adopt modular deployment strategies.
Masovian Voivodeship
Hyperscale facility construction in Warsaw drives specification divergence toward customized 48U enclosures with integrated power distribution. CE marking requirements for electrical safety compliance extend vendor qualification timelines. The Warsaw metropolitan corridor hosts concentrated cloud provider deployments requiring liquid-ready rack architectures for 30-50kW densities.
Lesser Poland Voivodeship
Krakow's emerging data center cluster attracts mid-market colocation operators unbundling rack specifications from facility contracts. EU AI Act transparency provisions mandate branch-circuit power metering in new deployments. Regional providers in Krakow adopt prefabricated modular systems to accelerate edge computing distribution.
Silesian Voivodeship
Industrial data center conversions in Katowice prioritize cost-optimized open frame configurations for telecommunications infrastructure. Steel price volatility compresses margins for domestic fabricators serving this price-sensitive segment. Legacy facility retrofits dominate rack replacement cycles in this historically industrial region.
Pomeranian Voivodeship
Gdansk's port-adjacent facilities exploit submarine cable landing points for international connectivity-dependent deployments. National building codes administered by the energy regulatory authority govern facility construction standards. Edge computing nodes in Gdansk utilize wall-mount enclosures for space-constrained network closets.
Greater Poland Voivodeship
Poznan's enterprise data center buildouts balance cost optimization with EU F-Gas Regulation compliance for cooling system integration. Government procurement protocols favor domestic operators with established public sector relationships. Regional enterprises specify heavy-duty cabinets for high-density storage arrays in captive facilities.
Poland Data Center Rack Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Poland's data center rack market, with integrated system vendors holding premium positioning against commodity fabricators. The vendor base splits between multinational electrical equipment conglomerates with European manufacturing footprints and domestic operators serving localized procurement channels. Three archetypes dominate: premium integrated solution providers, modular enclosure specialists, and cost-optimized open frame suppliers. Competitive moves concentrate on liquid cooling retrofit compatibility and smart monitoring integration ahead of EU AI Act compliance deadlines.
Among premium-tier integrated solution providers, Schneider Electric anchors supply chains serving Warsaw's cloud corridor through its European manufacturing footprint. Rittal occupies a position within the modular enclosure specialist tier, with architectures accommodating thermal management retrofits. Beyond.pl exemplifies the domestic operator archetype, leveraging established relationships in Polish government and enterprise buildouts. These three represent distinct competitive vectors: multinational scale, technical modularity, and localized procurement access.
| Leading Market Players |
|---|
| Schneider Electric |
| Hewlett Packard Enterprise |
| Eaton Corporation |
| Rittal |
| Black Box Corporation |
| Atman |
| Beyond.pl |
| Equinix |
| Data4 |
| Others |
Pricing and Supply Chain Analysis
Liquid-ready rack architectures with pre-installed cooling manifolds simultaneously compress manufacturing cost curves and concentrate supply relationships among European fabricators with thermal engineering capabilities. This production-method transition elevates procurement power for hyperscale operators in Warsaw while squeezing domestic open-frame suppliers dependent on volatile steel inputs.
Pricing Analysis
Outcome-based pricing tied to thermal containment performance and power monitoring uptime anchors premium tier valuations for enclosed cabinets serving AI infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates liquid-ready 48U configurations with integrated PDUs from commodity open frames and basic wall-mount units. Cost compression in the open frame segment is intensifying because telecommunications operators prioritize rapid equipment swap capacity over thermal optimization. Mid-market colocation providers exhibit highest price sensitivity, while hyperscale cloud operators demonstrate lowest sensitivity given their focus on density optimization and EU Green Deal compliance.
Supply Chain Analysis
Refurbishment flows for legacy 42U enclosures and remanufactured power distribution components create secondary supply channels that buffer lead time volatility for cost-sensitive buyers. Manufacturing concentrates in Germany, Poland, and the Czech Republic for premium integrated cabinets, while commodity open frame fabrication sources from Turkey and domestic Polish metalworkers. Steel and aluminum input costs, alongside CE marking certification timelines for electrical safety components, constitute primary raw material and compliance dependencies. Single-source vulnerability sits with specialized liquid cooling manifold suppliers serving Warsaw's hyperscale corridor. Distribution runs through direct manufacturer relationships for cloud providers and distributor channels for telecommunications operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's data center rack market operates under supply constraints from limited domestic liquid cooling integration expertise, a capacity bottleneck that sustains premium pricing for thermal-ready enclosures. This structural shortage propped by foreign system integrator dependence creates defendable positioning for vendors with in-house thermal engineering capabilities.
For Market Incumbents: Acquire liquid cooling system integration capabilities to defend against foreign specialist encroachment into Warsaw's hyperscale corridor. Secure backward integration into power distribution component manufacturing to compress CE marking timelines and accelerate vendor qualification cycles. Capacity addition in Silesian Voivodeship for cost-optimized open frame production counters margin pressure from Turkish import competition. For New Entrants and Emerging Players: The price-point gap between premium liquid-ready enclosures and economy open frames creates entry space for modular thermal retrofit kits targeting mid-market Krakow colocation providers. Secondary metropolitan areas outside Warsaw-Krakow axis present most penetrable geography given prefabricated modular rack adoption for edge computing distribution. Channel partnership with established electrical distributors accelerates market access without direct hyperscale procurement qualification burdens. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational electrical equipment conglomerates seeking European manufacturing footprint expansion. Long-term viability favors vendors with demonstrated EU AI Act compliance capabilities and established government procurement relationships. Monitor CE marking regulatory enforcement intensity and hyperscale capex commitment announcements for early signals of vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Integration Partnership | Direct-to-chip thermal architectures address 30-50kW rack densities in Warsaw's cloud corridor. |
| Smart Monitoring Platform Development | Embedded branch-circuit metering satisfies forthcoming EU AI Act infrastructure transparency mandates. |
| CE Marking Acceleration Program | Compressed electrical safety certification timelines reduce vendor entry barriers for power distribution components. |
| Prefabricated Modular System Launch | Regional colocation providers outside Warsaw adopt rapid-deployment rack configurations for edge infrastructure. |
| Domestic Fabricator Consolidation | Scale economies in open frame production counter steel price volatility affecting Polish metalworkers. |
Research Methodology
Document review covered regulatory filings with Poland's energy regulatory authority and EU Green Deal implementation guidance, complemented by interviews with data center facility operators, rack system procurement managers, thermal engineering specialists, and electrical equipment distributors. Secondary validation drew from CE marking databases, national building code amendments, and hyperscaler capex disclosure filings. Bottom-up shipment estimates triangulated against top-down facility construction pipeline analysis.
Segmentation outputs across product type, end user, size configuration, and mounting method were generated over the projection horizon. CAGRs were derived from facility deployment timelines and replacement cycle assumptions. Forecast inputs incorporated EU F-Gas Regulation compliance costs, steel price volatility indices, and AI infrastructure transparency requirement implementation schedules.
Inputs from facility operator interviews and regulatory documentation were available through the study window; gaps in real-time hyperscale procurement contract terms introduce uncertainty bands around premium tier volume assumptions. Forecasts reflect documented assumptions regarding EU AI Act enforcement timing and thermal density trajectories. Practitioners should monitor CE marking regulatory guidance updates and hyperscale facility construction permit approvals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
France Data Center Server Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Russia Data Center Rack Market