
 UAE Data Center Server Market | 2026-2036
UAE Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Data Center Server Market Insights
Hyperscale cloud operators are redrawing procurement patterns away from traditional enterprise IT departments in the UAE server market. Dell Inc. leverages its direct-to-hyperscale supply chain to secure large-scale rack server deployments across Dubai and Abu Dhabi facilities. Huawei Technologies Co Ltd anchors its position through integrated offerings spanning servers, networking, and storage tailored to Middle East latency requirements. Super Micro Computer Inc. differentiates via liquid-cooled architectures that address the UAE's extreme ambient temperature challenges.
Data center servers are high-performance computing platforms engineered with multi-socket CPU configurations, ECC memory subsystems, and redundant power supplies designed for continuous operation in controlled environments. These systems process, store, and distribute digital workloads for enterprise applications, cloud services, and telecommunications infrastructure. Rack servers dominate physical deployments due to density optimization in limited floor space across UAE facilities, while hyper-converged systems capture expanding share by collapsing compute, storage, and networking into unified nodes that reduce cabling complexity. Edge computing deployments are accelerating fastest as UAE telecom operators position micro data centers closer to 5G base stations and IoT endpoints.
MOHAP and NESA compliance requirements mandate data localization and cybersecurity certification for servers processing sensitive national information, directly influencing vendor qualification and procurement criteria. The UAE's implementation of ISO 27001-aligned frameworks through the Dubai Electronic Security Center and Abu Dhabi Digital Authority elevates product validation thresholds for market entry. Stakeholders must monitor evolving federal data classification rules and cooling efficiency standards as the Emirates advances its net-zero commitments for digital infrastructure.
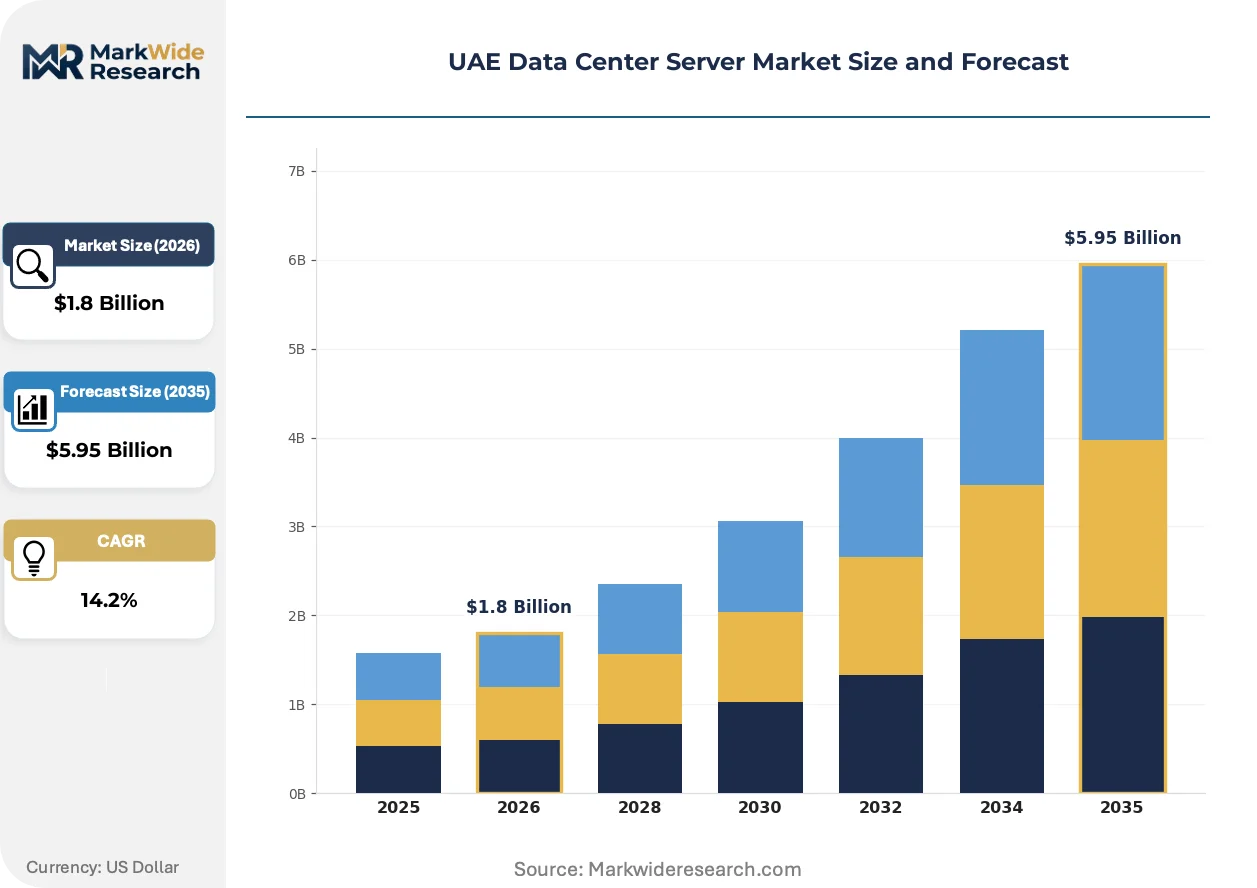
Market Dynamics
Hyperscale cloud operators are consolidating procurement authority away from traditional enterprise IT departments, fundamentally restructuring vendor relationships and volume commitments across UAE data center developments.
Growth Catalysts
- NESA Data Sovereignty Mandates:Federal cybersecurity frameworks require local data processing for sensitive national workloads, compelling government agencies and financial institutions to expand on-premise server capacity.
- 5G Network Rollouts:Etisalat and du are deploying edge computing nodes adjacent to base stations, generating demand for compact, high-density server configurations optimized for low-latency workloads.
- Liquid Cooling Adoption:Direct-to-chip thermal management systems are mitigating ambient temperature constraints that previously limited compute density in Dubai and Abu Dhabi facilities.
Market Restraints
- Semiconductor Supply Concentration:Advanced CPU and GPU fabrication depends on a narrow supplier base concentrated in East Asia, exposing UAE deployments to extended lead times and allocation constraints.
- Power Infrastructure Bottlenecks:Grid interconnection approvals for multi-megawatt facilities face procedural delays from the Emirates Water and Electricity Company, compressing project timelines.
- Skilled Technician Scarcity:Local labor markets lack sufficient density of certified data center engineers, forcing operators to import talent at premium compensation levels.
Strategic Opportunities
- Abu Dhabi AI Clusters:G42 and related sovereign AI initiatives are commissioning specialized GPU server farms for large language model training, opening premium hardware segments.
- Free Zone Incentives:Dubai Internet City and Masdar City offer customs duty exemptions and 100% foreign ownership structures that reduce total cost of ownership for server importers.
- Sustainability Certification:ADNOC and other state enterprises are mandating carbon-neutral digital infrastructure, creating preference for energy-efficient server architectures that qualify for green procurement frameworks.
Industry Challenges
- Multi-Vendor Integration Complexity:Hyperscale operators are sourcing compute, storage, and networking from distinct suppliers, increasing interoperability testing burdens and deployment risk.
- Compliance Certification Timelines:MOHAP and NESA security validation processes extend product qualification cycles by four to six months, delaying revenue recognition for new server platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Data Center Server Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Hyper-Converged Systems Technology: Virtualization, Cloud Computing, Edge Computing, Big Data End User: Telecommunications, Government, BFSI, Healthcare Deployment: On-Premises, Colocation, Cloud-Based, Hybrid |
| Companies Covered | Lenovo Group Limited, Super Micro Computer Inc., Dell Inc., Huawei Technologies Co Ltd, Quanta Computer Inc., Hewlett Packard Enterprise, Cisco Systems Inc., Inspur Group, International Business Machines (IBM) Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Data Center Server Market Trends and Innovations
Server architecture decisions in the UAE are increasingly governed by thermal constraints and data localization requirements rather than pure compute economics. Three developments are reshaping procurement patterns and facility design standards.
Direct liquid cooling is displacing traditional air-handling units as the dominant thermal management approach in Dubai and Abu Dhabi hyperscale facilities. Operators including Khazna Data Centers are adopting cold-plate and immersion systems to sustain 50kW-plus rack densities despite ambient temperatures exceeding 45°C. This transition is compressing mechanical infrastructure footprints while enabling higher revenue per square meter.
NESA's implementation of Tier III security classifications for critical national infrastructure is mandating hardware-level encryption and secure boot capabilities across all server procurement for government and regulated entities. The framework requires vendors to maintain UAE-based support centers and supply chain documentation. Financial services and healthcare providers are now prioritizing certified configurations over uncertified alternatives with superior price-performance metrics.
Enterprise buyers are consolidating server purchasing authority into centralized procurement functions reporting to chief digital officers, displacing the traditional model where individual business units maintained independent IT budgets. This concentration is visible across UAE banking and real estate conglomerates, where group-level frameworks now govern technology capital expenditure. Vendor account teams are restructuring to engage C-suite sponsors rather than departmental infrastructure managers.
UAE Data Center Server Market Segmentation
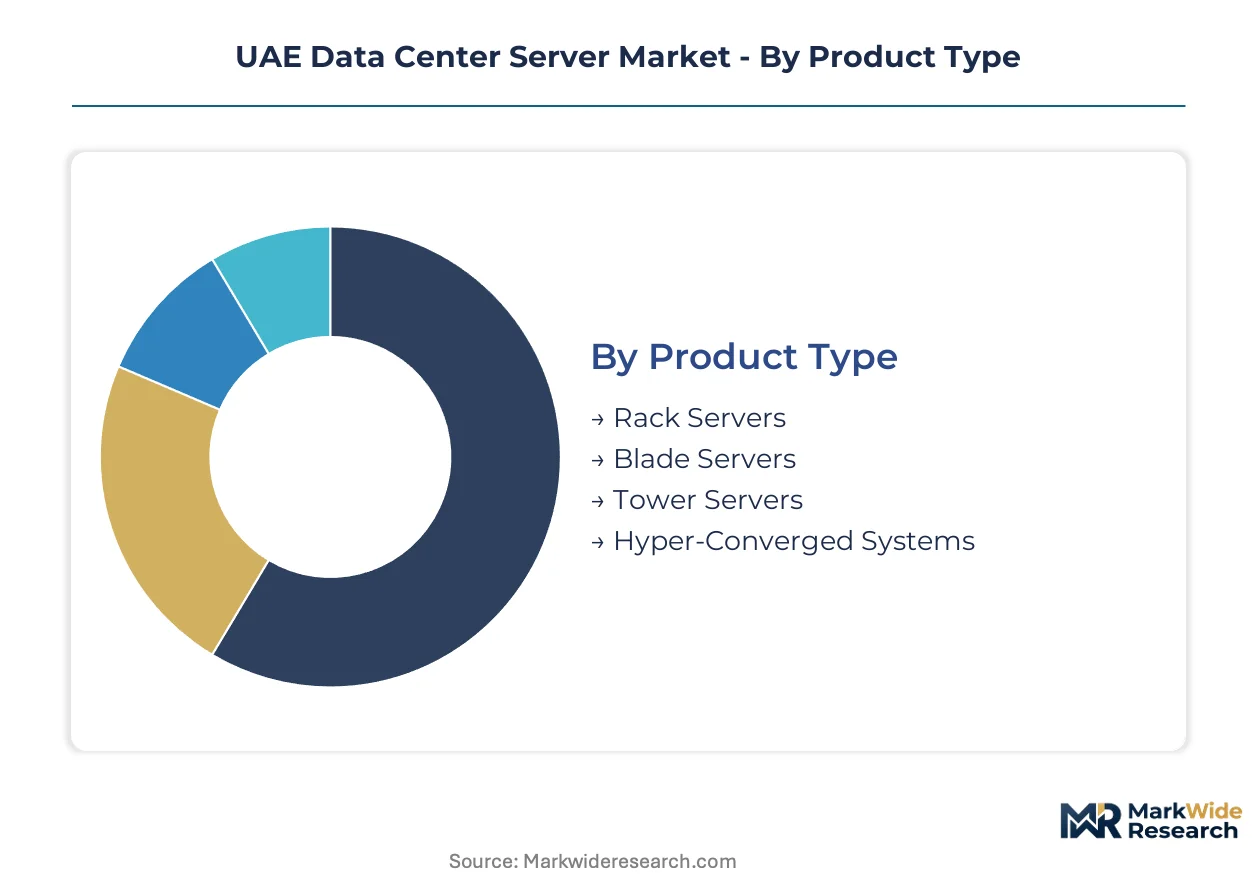
Segmentation in the UAE data center server market reveals distinct procurement channels and technical requirements across hyperscale cloud operators, government entities, and enterprise buyers. Understanding these divides illuminates where vendor relationships consolidate and where specialized configurations command premium positioning.
Product Type:
Rack servers flow predominantly through direct-to-hyperscale channels, while blade and tower configurations reach end-users via systems integrators and value-added resellers serving mid-market enterprises.
- Rack Servers:Standardized 1U-4U form factors with multi-socket CPU architectures and hot-swappable drive bays designed for density-optimized hyperscale deployments. Demand concentrates in Dubai Internet City and Masdar City facilities where Khazna Data Centers and similar operators prioritize vertical space efficiency over per-unit cost.
- Blade Servers:Modular chassis-based systems sharing redundant power and cooling infrastructure across multiple compute nodes. Government and BFSI procurement through ADNOC-linked frameworks favors these for consolidated management of classified workloads under NESA Tier III requirements.
- Tower Servers:Standalone pedestal configurations with limited density optimization but simplified deployment for remote edge locations. Small healthcare clinics and branch banking operations across Ras Al Khaimah and Fujairah deploy these where rack infrastructure is unavailable.
- Hyper-Converged Systems:Unified compute-storage-networking nodes collapsing three-tier architecture into software-defined infrastructure. Mid-market real estate and logistics conglomerates in Dubai South are adopting these to reduce cabling complexity and accelerate provisioning timelines.
Rack servers dominate installed base across UAE hyperscale facilities. Hyper-converged systems are where expansion concentrates as enterprise buyers consolidate fragmented infrastructure.
Technology:
Technology segmentation maps directly to workload economics, with virtualization and cloud computing serving high-volume transactional applications while edge and big data configurations address latency-sensitive and analytics-intensive use cases.
- Virtualization:Hypervisor-based server abstraction enabling multiple operating system instances on shared physical hardware. Legacy enterprise data centers in Dubai Media City rely on VMware and Hyper-V deployments to extend hardware refresh cycles amid semiconductor supply constraints.
- Cloud Computing:On-demand compute resource pooling with API-driven orchestration and metered consumption models. AWS, Azure, and GCP hyperscale regions in the UAE route procurement through direct vendor relationships rather than traditional distribution.
- Edge Computing:Distributed micro data centers positioned proximal to 5G base stations and IoT endpoints. Etisalat and du are deploying these adjacent to radio access networks across Abu Dhabi and Sharjah to support autonomous vehicle telemetry and smart city sensors.
- Big Data:Scale-out architectures with high-memory configurations and GPU acceleration for distributed analytics. G42's AI training clusters in Masdar City represent the most demanding segment, requiring liquid-cooled GPU servers for large language model development.
Cloud computing anchors volume procurement through hyperscale operator frameworks. Edge computing is climbing the fastest as telecom infrastructure densification accelerates.
End User:
End-user segmentation determines compliance burden and procurement authority concentration, with government and BFSI buyers maintaining centralized frameworks while healthcare and telecom operate through distributed technical specifications.
- Telecommunications:Etisalat and du drive demand for edge-optimized servers with NEBS-compliant thermal specifications and carrier-grade availability. These operators source through consolidated procurement functions with direct vendor engineering support requirements.
- Government:Federal and emirate-level entities under MOHAP and NESA jurisdiction mandate hardware-level encryption and UAE-based supply chain documentation. The Dubai Electronic Security Center certifies configurations before deployment across critical national infrastructure.
- BFSI:Banks and insurance operators regulated by the Central Bank of the UAE and ADGM maintain on-premise capacity for core banking systems while shifting customer-facing applications to cloud. First Abu Dhabi Bank and Emirates NBD represent concentrated demand for high-availability rack configurations.
- Healthcare:Hospital networks and diagnostic chains including SEHA and private operators in Dubai Healthcare City require HIPAA-aligned data localization with specialized imaging workstation integration. Procurement fragments across individual facility IT departments with limited group-level consolidation.
Government and BFSI segments concentrate procurement authority through centralized frameworks. Healthcare represents the most fragmented purchasing pattern with significant consolidation potential.
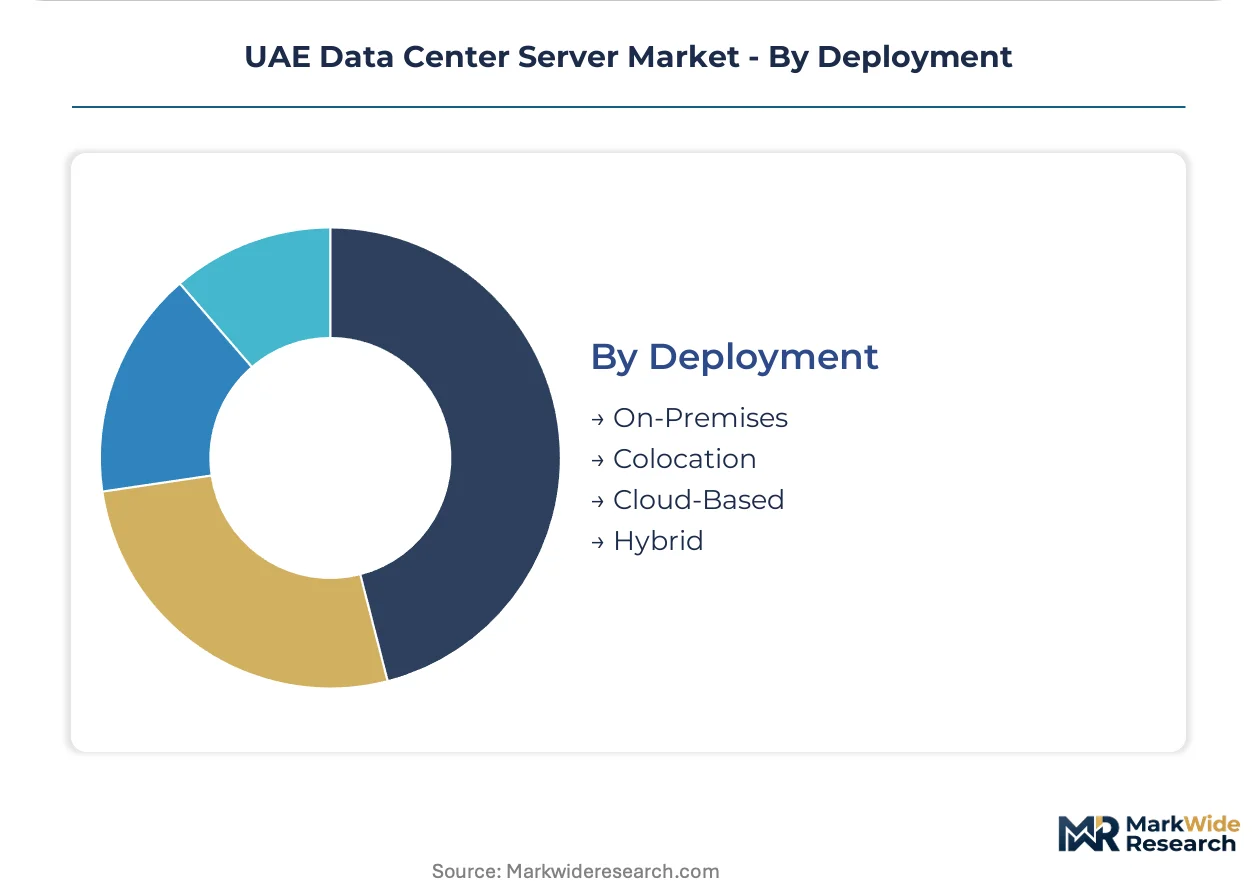
Deployment:
Deployment mode segmentation reflects capital structure preferences, with colocation and cloud-based models transferring facility risk to specialized operators while on-premise and hybrid retain direct infrastructure control.
- On-Premises:Customer-owned data centers with dedicated mechanical and electrical infrastructure. ADNOC and other sovereign entities maintain these for classified upstream operations where physical security and air-gapped networking are non-negotiable.
- Colocation:Leased space in multi-tenant facilities with shared power, cooling, and connectivity infrastructure. Khazna, Khazna Data Centers, and Gulf Data Hub serve multinational enterprises seeking UAE presence without facility construction timelines.
- Cloud-Based:Fully outsourced compute with no customer-managed hardware. Regional software-as-a-service providers and fintech startups route all infrastructure through hyperscale IaaS, bypassing server procurement entirely.
- Hybrid:Orchestrated workload placement across on-premise and cloud resources with unified management planes. Emirates Airlines and similar conglomerates deploy this model to retain sensitive passenger data locally while bursting transactional workloads to cloud.
Colocation dominates new capacity additions as enterprises defer capital expenditure. Hybrid deployments are gaining share fastest as workload portability requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Server procurement across the UAE clusters in emirate-level jurisdictions with distinct regulatory frameworks and infrastructure maturity. Dubai and Abu Dhabi dominate hyperscale capacity, while secondary emirates capture edge computing and specialized deployments.
Dubai
Dubai Internet City and Dubai South anchor hyperscale server demand from cloud operators and multinational enterprises. The Dubai Electronic Security Center enforces ISO 27001-aligned certification for hardware deployed in critical infrastructure. Khazna Data Centers operates multiple facilities here with direct liquid cooling systems sustaining 50kW-plus rack densities.
Abu Dhabi
Masdar City concentrates sovereign AI training clusters and government data centers requiring NESA Tier III security classifications. The Abu Dhabi Digital Authority mandates hardware-level encryption and secure boot capabilities for all server procurement. G42 commissions specialized GPU server farms here for large language model development.
Sharjah
Sharjah hosts edge computing nodes adjacent to 5G base stations serving autonomous vehicle telemetry and industrial IoT. The emirate's media free zone incentives attract content delivery networks requiring localized server presence. Telecom operators deploy compact, NEBS-compliant configurations here for low-latency workloads.
Northern Emirates
Ras Al Khaimah and Fujairah capture tower server deployments for remote healthcare clinics and branch banking operations lacking rack infrastructure. Federal data localization requirements extend MOHAP compliance to these jurisdictions. Submarine cable landing points at Fujairah position the emirate for future hyperscale expansion.
UAE Data Center Server Market Competitive Landscape
Concentration sits with integrated technology conglomerates and direct-to-hyperscale specialists. Dell Inc. and Huawei Technologies Co Ltd anchor procurement relationships with cloud operators and government entities respectively. Three archetypes dominate: full-stack infrastructure vendors, component-optimized specialists, and contract manufacturers. Competitive moves center on liquid cooling technology partnerships and NESA certification acceleration.
Within the integrated infrastructure tier, Huawei Technologies Co Ltd occupies a position exemplifying regulatory-aligned supply chain localization. Dell Inc. and Super Micro Computer Inc. represent the direct-to-hyperscale archetype, with the latter anchoring thermal innovation positioning. Lenovo Group Limited sits within the diversified technology conglomerate category. Hewlett Packard Enterprise and Cisco Systems Inc. exemplify enterprise-focused incumbents adapting procurement centralization trends. Quanta Computer Inc., Inspur Group, and International Business Machines (IBM) Corporation represent manufacturing-scale and services-anchored alternatives respectively.
| Leading Market Players |
|---|
| Lenovo Group Limited |
| Super Micro Computer Inc. |
| Dell Inc. |
| Huawei Technologies Co Ltd |
| Quanta Computer Inc. |
| Hewlett Packard Enterprise |
| Cisco Systems Inc. |
| Inspur Group |
| International Business Machines (IBM) Corporation |
| Others |
Pricing and Supply Chain Analysis
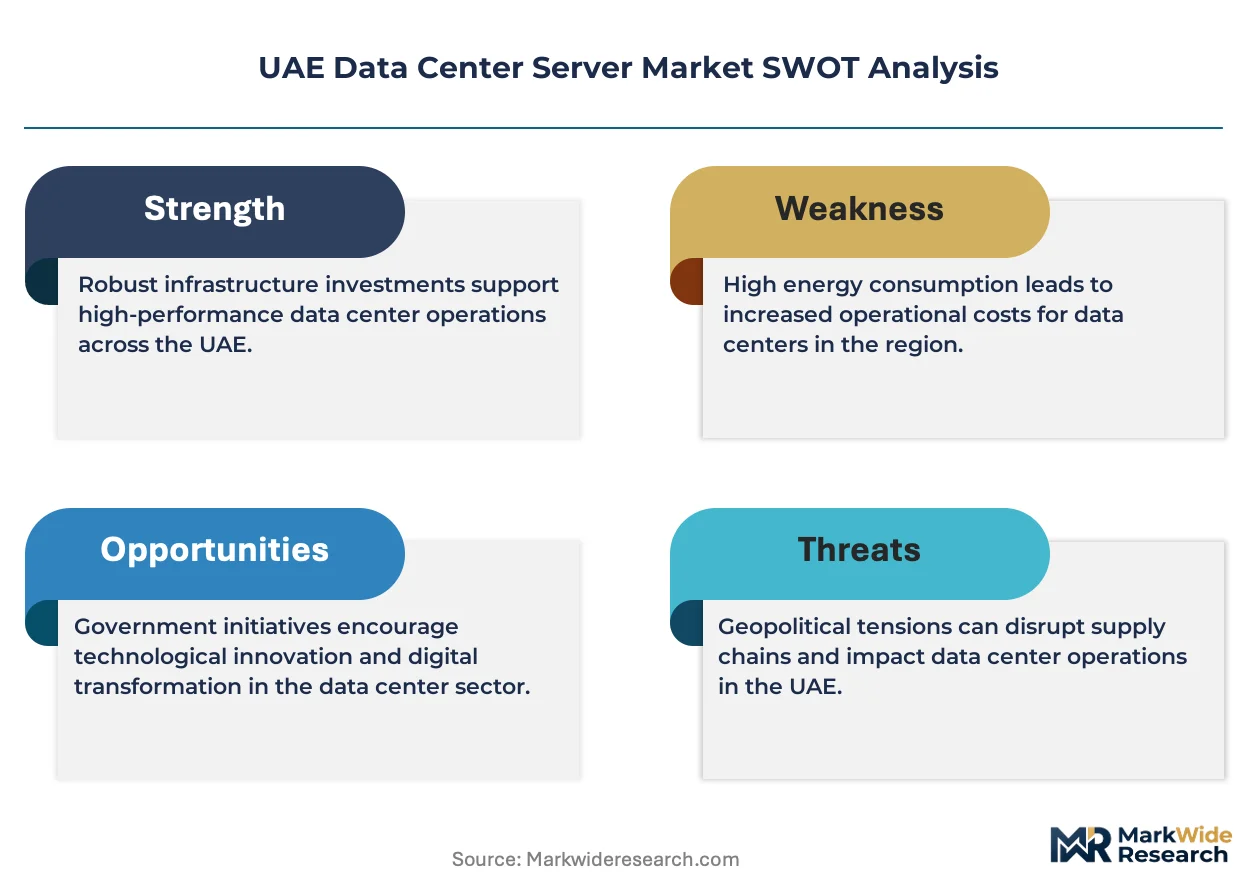
NESA Tier III security certification gates both vendor qualification and price differentiation simultaneously, compressing supplier pools while stratifying procurement budgets across government, financial, and hyperscale buyer archetypes. Compliance validation timelines and UAE-based support requirements embed premium pricing for certified configurations, while uncertified alternatives compete on raw compute economics in less regulated segments.
Pricing Analysis
NESA Tier III dictates the pricing tier structure across the UAE data center server market, separating premium-certified configurations from standard enterprise hardware and economy-grade uncertified alternatives. Price differentiation rests on certification grade and volume scale, with hyperscale direct procurement commanding standard-tier discounts unavailable to fragmented healthcare buyers. Cost compression in the economy tier is intensifying because Chinese vendors are flooding mid-market channels with uncertified high-density rack servers. Government entities exhibit the lowest price sensitivity due to sovereign data mandates, while regional real estate conglomerates negotiate aggressively on per-unit costs.
Supply Chain Analysis
Strait of Hormuz transit underwrites critical semiconductor logistics lanes feeding UAE hyperscale construction timelines, exposing deployments to geopolitical friction and maritime insurance volatility. Advanced CPU and GPU fabrication draws from Taiwan, South Korea, and the United States, while memory subsystems and power management components source predominantly from China and Japan. Single-source vulnerability concentrates in leading-edge node production, where TSMC and Samsung anchor global supply. Distribution runs through direct vendor relationships with hyperscale operators, bypassing traditional distribution for cloud and AI training cluster procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE data center server market operates as a defensive-moat arena where regulatory entrenchment creates durable incumbent advantages through NESA certification barriers and sovereign data localization mandates.
For Market Incumbents: Compound certification head starts by accelerating Dubai Electronic Security Center pre-approval for next-generation liquid-cooled platforms before competitors complete validation cycles. Deepen backward integration into UAE-based spare parts logistics to compress mean-time-to-repair commitments that government tenders weight heavily. Threat substitution from Chinese vendors offering uncertified high-density alternatives demands proactive Tier III portfolio expansion. For New Entrants and Emerging Players: NESA fast-track partnerships with Abu Dhabi Digital Authority offer the most penetrable regulatory pathway for specialized GPU server configurations targeting G42 sovereign AI clusters. White-space concentrates in edge-optimized NEBS-compliant compact servers for Etisalat and du 5G densification programs across Sharjah and northern emirates. Go-to-market execution should anchor on direct engineering engagement with telecom procurement functions rather than channel distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-cooled hyperscale deployments as mechanical infrastructure costs compound with compute density scaling. Long-term viability favors vendors with captive thermal management technology and established UAE service footprints. Acquisition target archetype: mid-scale specialists with NESA certification in place but limited hyperscale reference customers. Signal to watch: Khazna Data Centers and Gulf Data Hub capex acceleration as colocation demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| NESA Tier III Certification Acceleration | Pre-approval with Dubai Electronic Security Center locks out uncertified competitors from government tenders. |
| Liquid Cooling Technology Partnership | Cold-plate and immersion alliances with Khazna Data Centers enable 50kW-plus rack density deployments. |
| UAE-Based Support Center Establishment | Local spare parts logistics satisfy NESA supply chain documentation requirements for sovereign workloads. |
| Edge Computing NEBS Compliance | Carrier-grade thermal specifications capture Etisalat and du 5G infrastructure procurement. |
| Direct Hyperscale Vendor Relationship | Bypassing distribution channels secures volume commitments from AWS, Azure, and GCP regional expansions. |
Research Methodology
Operator-level perspectives from data center facility managers, hyperscale cloud procurement officers, NESA compliance auditors, and telecom infrastructure engineers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against SEC filings from Dell and Super Micro, hyperscaler capex disclosures from AWS and Azure, and UAE federal procurement databases tracking MOHAP and ADNOC server awards. Bottom-up unit economics from rack-level deployments triangulated against top-down market sizing from Emirates Water and Electricity Company interconnection approvals.
Sensitivity analysis across deployment mode preferences, certification timeline scenarios, and semiconductor supply disruption cases informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product form factor, technology architecture, end-user vertical, and emirate-level regulatory jurisdiction. CAGRs derived from installed base evolution and replacement cycle compression across cloud, colocation, and on-premise environments. Forecast inputs incorporated Etisalat and du 5G rollout schedules alongside G42 AI cluster commissioning timelines.
Decision-makers should treat outputs as directional under assumptions of sustained NESA enforcement and hyperscale capacity expansion; material deviation in regulatory stringency or cloud demand would warrant model refresh. Practitioners should keep alternative scenarios live as semiconductor supply concentration and Emirates Water and Electricity Company grid interconnection timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Middle East Data Center Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
Australia Data Center Construction Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Singapore Data Center Server Market