
 Data Center Containment Solution Market | 2026-2036
Data Center Containment Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Containment Solution Market Insights
Aluminum framing is consolidating its position over steel in containment aisle assemblies, cutting weight and installation labor for large-scale deployments. Vertiv Group Corp. leverages its integrated power and thermal portfolio to bundle containment with cooling infrastructure. Schneider Electric SE anchors its offering through EcoStruxure software layers that tie physical containment to digital monitoring. Eaton Corporation plc competes on electrical safety integration, embedding arc-flash containment within aisle architectures.
Data center containment solutions enclose either cold or hot aisles using rigid or soft-panel barriers, typically rated to specific static pressure thresholds and fire-resistance standards, to eliminate thermal mixing and reduce cooling energy overhead. Cold aisle containment dominates installed base volume due to its compatibility with legacy raised-floor designs, while hot aisle containment captures premium positioning as direct liquid cooling and rear-door heat exchangers expand. Modular installation methods sustain faster deployment cycles than custom builds, particularly for hyperscale operators standardizing across multiple sites.
ASHRAE thermal guidelines, the EU Energy Efficiency Directive, and China's GB standards for data center power usage effectiveness collectively mandate measurable containment performance, forcing retrofit demand among facilities built before current efficiency codes. EPA ENERGY STAR certification for data centers further tightens operational benchmarks in the United States. Stakeholders must weigh upfront modular costs against regulatory penalty exposure and energy arbitrage when selecting containment architectures.
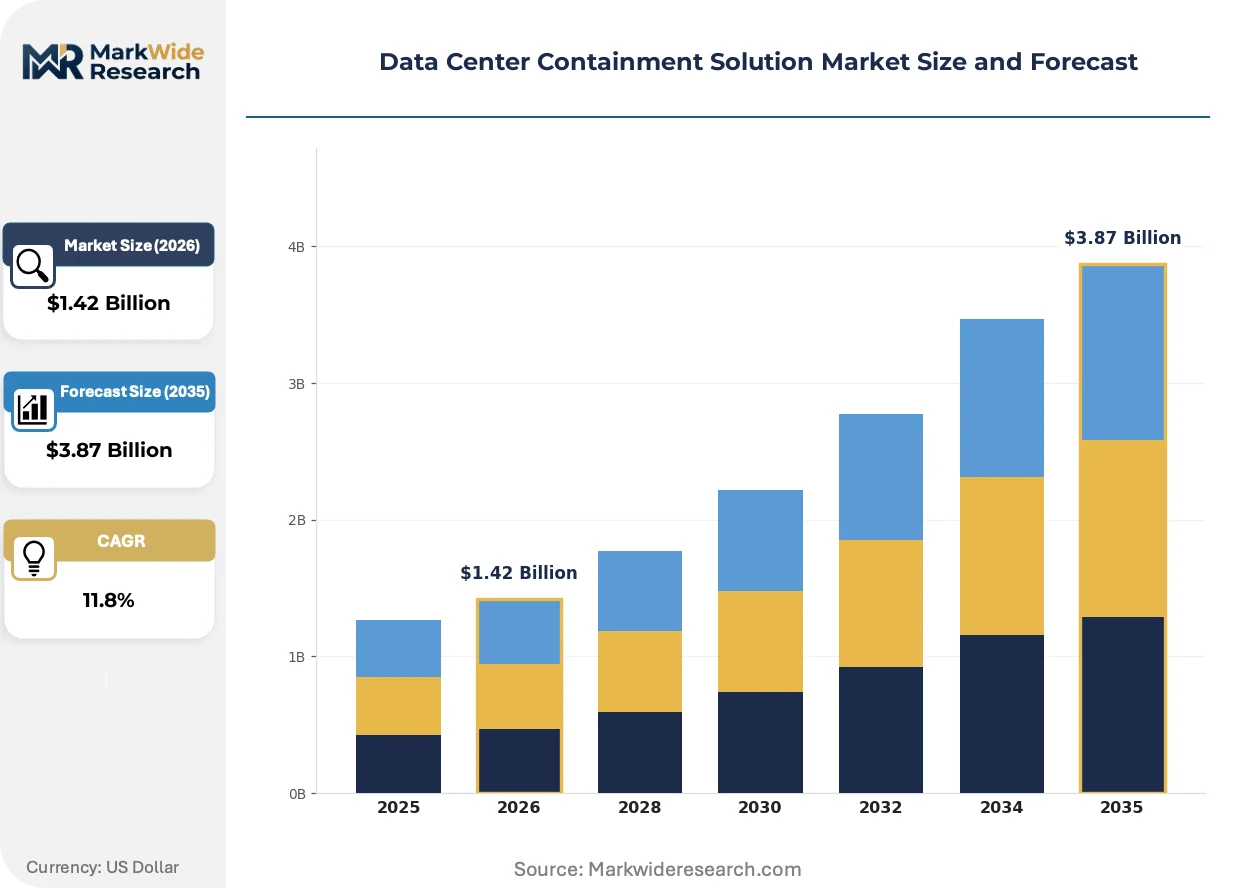
Market Dynamics
Hyperscale cloud operators are consolidating procurement power and mandating modular containment architectures that compress deployment cycles across multi-site rollouts, forcing suppliers to standardize component libraries or exit the tier-one supply base.
Growth Catalysts
- EU Energy Efficiency Directive:Mandatory power usage effectiveness thresholds for data centers above 500kW capacity are triggering retrofit waves across legacy facilities in Germany, France, and the Netherlands.
- Liquid cooling integration:Rear-door heat exchangers and direct-to-chip cooling systems require hot aisle containment as a thermal boundary layer, pulling containment into high-performance computing builds.
- China's dual carbon goals:Provincial energy intensity caps in Beijing, Shanghai, and Shenzhen are accelerating containment adoption as the lowest-capex path to GB-standard PUE compliance.
Market Restraints
- Aluminum price volatility:Containment framing costs track London Metal Exchange aluminum futures, exposing margins to commodity swings without effective hedging instruments at project scale.
- Steel tariff regimes:Section 232 duties in the United States and EU carbon border adjustment mechanisms inflate input costs for suppliers without captive rolling mill capacity.
- Fire-resistance certification lag:UL 723 and EN 13501-1 testing timelines extend 14-18 weeks, gating product launches and freezing design iterations mid-development.
Strategic Opportunities
- India's data center buildout:Mumbai, Chennai, and Hyderabad clusters lack mature containment supply chains, creating first-mover advantage for modular system integrators with local assembly partnerships.
- AI training facility surge:GPU-dense racks exceeding 50kW per cabinet demand containment-integrated thermal management, opening premium pricing tiers for pressure-rated hard-panel systems.
- US Inflation Reduction Act:Energy efficiency tax credits for data center retrofits lower payback periods for containment upgrades, expanding addressable market to Class B and C facilities.
Industry Challenges
- Commissioning engineer scarcity:Specialized containment airflow balancing and pressurization testing requires technicians certified to ASHRAE standards, with training pipeline gaps in secondary markets.
- Raised-floor legacy entanglement:Cold aisle containment retrofits in 1990s-era facilities face slab elevation mismatches, cable tray conflicts, and fire suppression rerouting that inflate installation labor 40-60% above greenfield estimates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Containment Solution Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.87 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Aisle Containment, Hot Aisle Containment, In-Row Cooling, Raised Floor Systems Installation Method: Modular Systems, Retrofit Solutions, Integrated Solutions, Custom Builds End User: Hyperscale Data Centers, Enterprises, Colocation Facilities, Telecommunication Providers Technology: Airflow Management, Monitoring Systems, Energy Efficiency Solutions, Fire Suppression Systems |
| Companies Covered | Vertiv Group Corp., Schneider Electric SE, Eaton Corporation plc, Rittal GmbH & Co. KG, nVent Electric PLC, STULZ GmbH, Legrand SA, The Siemon Company, Airedale International Air Conditioning Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Containment Solution Market Trends and Innovations
Containment architecture is pivoting from static barrier systems to dynamic, software-coupled thermal envelopes that respond to real-time rack load variations. This shift compresses the boundary between physical infrastructure and building management systems.
Soft-panel fabric containment is decentralizing thermal management authority away from centralized CRAH units toward row-level and rack-level cooling decisions. Hyperscale operators in the United States and Germany are deploying tensile membrane systems with magnetic edge seals that enable rapid reconfiguration without structural modification. This technology is decentralizing cooling plant capital allocation by allowing incremental capacity adds matched to actual server deployment rather than speculative oversizing.
The EU F-Gas Regulation and its phasedown of high-GWP refrigerants are forcing cooling system redesigns that elevate containment performance from efficiency accessory to thermal necessity. Operators can no longer compensate for air mixing with lower-temperature supply air, making separation integrity mandatory for compliance. Northern European facilities with free cooling advantages are most exposed, driving demand for pressure-rated containment that maintains separation at minimal fan energy.
Buying committees at colocation providers are unbundling containment procurement from mechanical and electrical packages, issuing separate RFPs for aisle architecture and demanding lifecycle cost guarantees. This pattern displaces bundled EPC contracts with direct supplier relationships and shifts risk allocation onto containment vendors for performance shortfalls. The trend is most pronounced in the United States, where REIT-owned data centers face shareholder pressure to demonstrate operational expenditure control through vendor diversification.
Data Center Containment Solution Market Segmentation
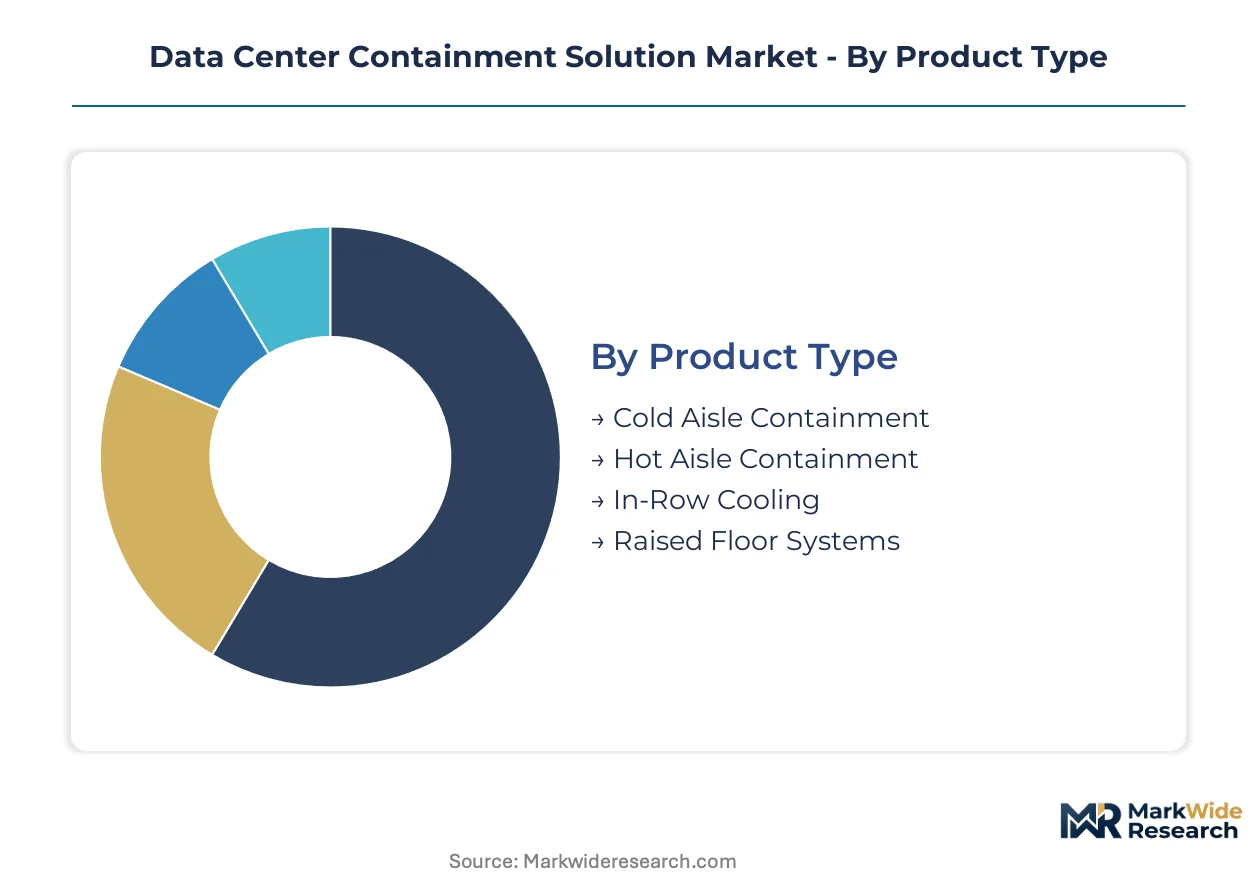
Containment procurement decisions split across thermal architecture, deployment speed, and compliance burden. Each segmentation axis carries distinct certification requirements and margin profiles that reshape supplier positioning.
Product Type:
UL 723 and EN 13501-1 fire-resistance certifications apply differentially across containment architectures, with hard-panel systems facing stricter testing timelines than soft-panel alternatives.
- Cold Aisle Containment:Rigid or soft-panel barriers enclosing supply air pathways, typically deployed over raised-floor plenum configurations. Demand concentrates in legacy facility retrofits across Germany and the United States, where ASHRAE thermal guidelines mandate measurable separation integrity for ENERGY STAR certification eligibility.
- Hot Aisle Containment:Exhaust-focused enclosures capturing server heat for direct rejection or liquid cooling integration. Installations in Beijing and Shanghai hyperscale clusters accelerate as China's GB standards for power usage effectiveness tighten and direct-to-chip cooling penetration deepens.
- In-Row Cooling:Proximity cooling units integrated within aisle architectures, eliminating ductwork losses. Modular configurations dominate new builds in Mumbai and Chennai where raised-floor legacy constraints are absent.
- Raised Floor Systems:Plenum-based air distribution with containment-compatible elevation standards. Deployment persists in 1990s-era facilities facing slab mismatch challenges during retrofit integration.
Cold aisle containment sits at the top of the volume ranking, with hot aisle containment climbing the fastest.
Installation Method:
Cost tier separation between standardized and bespoke approaches determines procurement committee composition and vendor qualification thresholds.
- Modular Systems:Pre-engineered component libraries enabling rapid multi-site replication. Hyperscale operators in the United States and Germany mandate this approach to compress deployment cycles across standardized facility footprints.
- Retrofit Solutions:Containment integration into operational facilities without workload migration. Demand surges in Northern Europe under EU Energy Efficiency Directive retrofit mandates for facilities above 500kW capacity.
- Integrated Solutions:Bundled containment-with-cooling packages from single-source suppliers. Vertiv and Schneider Electric anchor this tier through captive power and thermal portfolios.
- Custom Builds:Site-specific engineering for non-standard slab elevations or fire suppression architectures. Labor costs run 40-60% above modular baselines due to commissioning engineer scarcity in secondary markets.
Modular systems command the largest revenue share, while retrofit solutions are expanding most quickly under regulatory compliance pressure.
End User:
Customer type dictates performance specification stringency and lifecycle guarantee expectations, with colocation providers unbundling procurement most aggressively.
- Hyperscale Data Centers:Self-operated cloud infrastructure requiring standardized containment across dozens of simultaneous builds. These operators consolidate procurement power and mandate component library standardization from tier-one suppliers.
- Enterprises:Corporate-owned facilities with heterogeneous IT loads and longer depreciation horizons. Energy efficiency tax credits under the US Inflation Reduction Act lower payback thresholds for containment upgrades in Class B and C facilities.
- Colocation Facilities:Multi-tenant operations facing shareholder pressure for operational expenditure control. REIT-owned data centers in the United States issue separate RFPs for aisle architecture, displacing bundled EPC contracts.
- Telecommunication Providers:Edge and central office conversions with space-constrained footprints. Deployment concentrates in Hyderabad and Chennai clusters lacking mature local containment supply chains.
Hyperscale data centers lead volume absorption, with colocation facilities gaining share fastest through procurement unbundling.
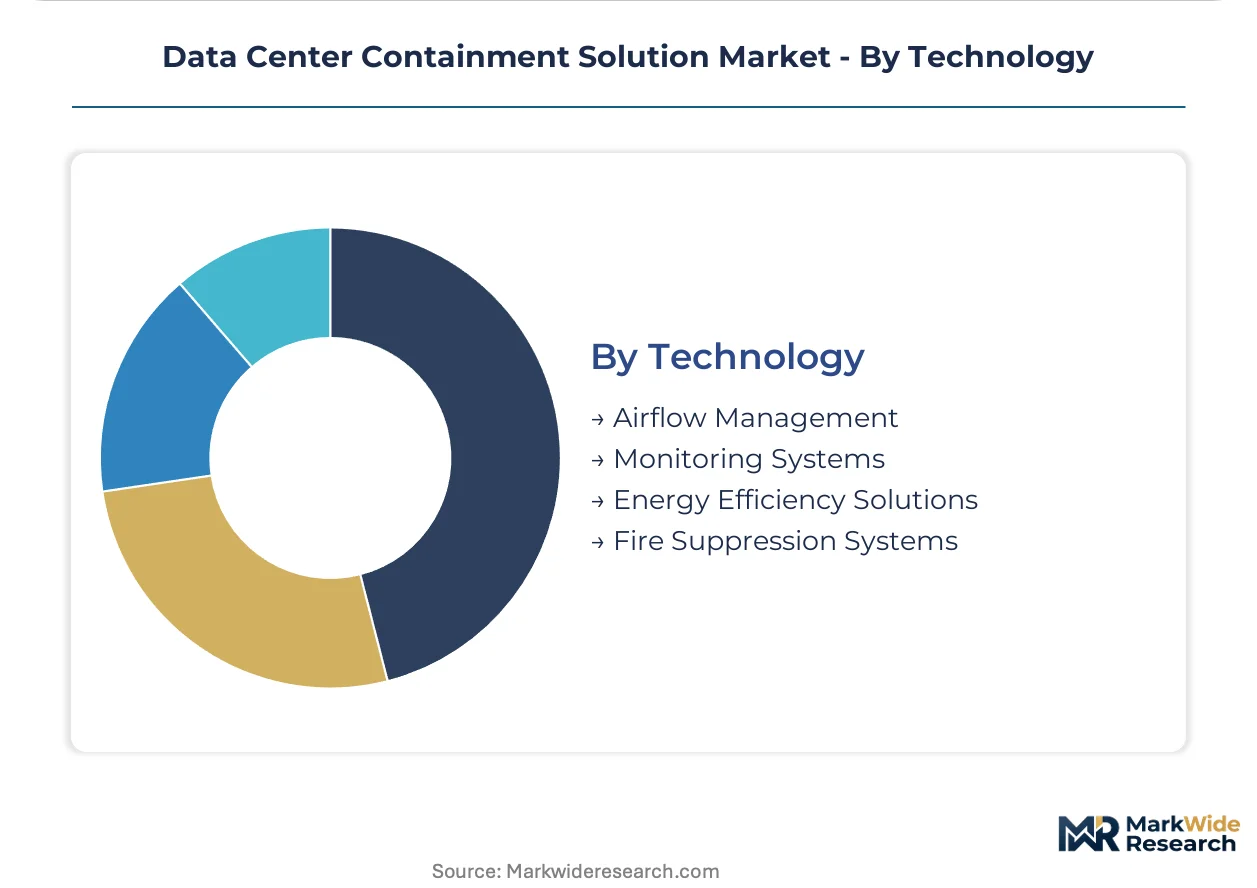
Technology:
Technology layering determines software coupling depth and building management system integration requirements.
- Airflow Management:Static pressure maintenance and thermal boundary integrity through physical barriers. Fundamental to all containment architectures regardless of cooling generation method.
- Monitoring Systems:Sensor networks feeding digital twin and predictive maintenance platforms. Schneider Electric's EcoStruxure software layers exemplify this integration, tying physical containment to real-time performance optimization.
- Energy Efficiency Solutions:Fan energy reduction and free cooling enablement through separation integrity. Northern European facilities with evaporative or economizer advantages depend on pressure-rated containment for F-Gas Regulation compliance.
- Fire Suppression Systems:Clean agent or inert gas distribution compatible with aisle architectures. UL 723 testing timelines extend 14-18 weeks, gating product launches for integrated suppression designs.
Airflow management holds the foundational volume position, with monitoring systems ascending fastest as software-coupled thermal envelopes displace static barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud campuses in Northern Virginia anchor global containment deployment volumes, while regulatory retrofit mandates in Germany and efficiency-driven new builds in China reshape regional demand trajectories.
United States
Dominant hyperscale operators in Ashburn and Phoenix standardize modular containment across multi-site rollouts. The EPA ENERGY STAR certification tightens operational benchmarks for legacy facility retrofits. Northern Virginia's data center corridor absorbs premium hard-panel systems for AI training facilities exceeding 50kW per cabinet.
Germany
The EU Energy Efficiency Directive triggers containment retrofit waves across Frankfurt and Berlin facilities above 500kW capacity. The F-Gas Regulation elevates separation integrity from efficiency accessory to thermal compliance necessity. Bavarian hyperscale clusters deploy pressure-rated containment to maintain free cooling advantages under refrigerant phase-down timelines.
China
Provincial energy intensity caps in Beijing, Shanghai, and Shenzhen accelerate adoption as the lowest-capex path to GB-standard PUE compliance. The Ministry of Ecology and Environment enforces dual carbon goals through data center efficiency audits. Yangtze River Delta facilities integrate hot aisle containment with direct liquid cooling for GPU-dense AI infrastructure.
India
Mumbai, Chennai, and Hyderabad clusters lack mature containment supply chains, creating first-mover positioning for modular system integrators. The Bureau of Energy Efficiency drafts data center performance standards modeled on ASHRAE guidelines. Maharashtra's cloud campus developments specify in-row cooling with integrated aisle architectures absent raised-floor constraints.
United Kingdom
Slough and London Docklands colocation providers unbundle containment procurement from mechanical packages under shareholder pressure for operational expenditure control. The Climate Change Agreement scheme rewards measurable cooling efficiency improvements. Thames Valley facilities retrofit cold aisle barriers to secure ENERGY STAR-equivalent certification for enterprise tenant retention.
Data Center Containment Solution Market Competitive Landscape
Portfolio diversification dominates the current landscape as electrical infrastructure specialists extend into thermal boundary systems. The vendor base stratifies across three tiers: integrated power-thermal platforms, standalone containment fabricators, and regional installation contractors. Two strategic archetypes anchor competitive positioning: full-stack infrastructure bundlers leveraging captive cooling portfolios, and modular specialists optimizing component standardization for hyperscale procurement committees. Geographic expansion and technology licensing represent the dominant competitive vectors as suppliers chase regulatory retrofit windows in Northern Europe and efficiency-driven new builds in Asia-Pacific.
Among integrated infrastructure platforms, Vertiv Group Corp., Schneider Electric SE, and Eaton Corporation plc exemplify the bundling archetype. Vertiv leverages its captive power and thermal portfolio to anchor containment within broader facility infrastructure. Schneider Electric positions through software-coupled architectures tying physical separation to digital monitoring layers. Eaton occupies the electrical safety integration vector, embedding arc-flash containment within aisle architectures. These three entities represent distinct competitive positioning strategies without implying specific market share claims or operational priorities.
| Leading Market Players |
|---|
| Vertiv Group Corp. |
| Schneider Electric SE |
| Eaton Corporation plc |
| Rittal GmbH & Co. KG |
| nVent Electric PLC |
| STULZ GmbH |
| Legrand SA |
| The Siemon Company |
| Airedale International Air Conditioning Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators concentrate procurement authority across multi-site rollouts, compressing supplier margins through standardized component library mandates and volume-scale price negotiations.
Pricing Analysis
Aluminum framing and tensile membrane costs pass through London Metal Exchange futures directly to project quotes, exposing containment margins to commodity volatility without effective hedging instruments at installation scale. Three-tier pricing structure across premium, standard, and economy levels separates pressure-rated hard-panel systems for AI training facilities from soft-panel fabric alternatives for legacy retrofits. Cost compression in standard-tier modular systems is intensifying because hyperscale procurement committees unbundle containment from mechanical packages and demand lifecycle cost guarantees. Enterprise Class B and C facilities exhibit highest price sensitivity due to capital constraint and longer depreciation horizons, while GPU-dense AI infrastructure buyers absorb premium pricing for fire-resistance certification and static pressure ratings.
Supply Chain Analysis
Single-source vulnerability sits with Chinese aluminum extrusion and German precision hardware suppliers, where regional energy intensity caps and carbon border adjustment mechanisms threaten input cost stability. Manufacturing concentrates in China, Germany, and the United States, with component sourcing drawn from Taiwan for sensor networks and South Korea for tensile membrane substrates. Supply chain risk centers on Section 232 steel tariff exposure and EU carbon border adjustment inflation for suppliers without captive rolling mill capacity. Distribution runs through direct supplier relationships with hyperscale procurement committees, displacing bundled EPC contracts and shifting performance risk onto containment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory retrofit mandates in Germany under the EU Energy Efficiency Directive create cost-arbitrage opportunities against greenfield construction in India's emerging Mumbai and Chennai clusters, where local assembly partnerships bypass mature supply chain premiums.
For Market Incumbents: Anticipate procurement unbundling by colocation REITs demanding separate RFPs for aisle architecture and lifecycle performance guarantees. Vertiv and Schneider Electric should deepen software-coupled thermal envelope integration to defend against standalone containment fabricators. Certification investment in UL 723 and EN 13501-1 fire-resistance testing represents the priority lever for product launch velocity. For New Entrants and Emerging Players: Telecommunication providers converting edge and central office footprints in Hyderabad and Chennai present the most penetrable buyer archetype, given absent mature local containment supply chains. Modular system integrators with local assembly partnerships capture first-mover positioning before integrated infrastructure platforms establish regional presence. Go-to-market execution should anchor on rapid deployment cycles absent raised-floor legacy constraints. For Investors and Strategic Acquirers: Electrical infrastructure specialists extending into thermal boundary systems represent the most active acquirer category in this space, with Eaton and nVent demonstrating platform extension appetite. Acquisition targets should exhibit captive aluminum framing capabilities or software-coupled monitoring integration. Long-term viability hinges on containment performance transitioning from efficiency accessory to thermal compliance necessity under F-Gas Regulation and GB-standard PUE enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Coupled Thermal Envelope Development | Schneider Electric's EcoStruxure integration exemplifies digital-physical convergence for real-time optimization. |
| Modular Component Library Standardization | Hyperscale procurement committees in Northern Virginia mandate cross-site replication to compress deployment cycles. |
| Local Assembly Partnership Establishment | Mumbai and Chennai clusters lack mature supply chains, creating first-mover positioning for system integrators. |
| Fire-Resistance Certification Acceleration | UL 723 testing timelines extending 14-18 weeks gate product launches and freeze design iterations. |
| Liquid Cooling Integration Architecture | Rear-door heat exchangers and direct-to-chip systems require hot aisle containment as thermal boundary layer. |
Research Methodology
Coverage spans the United States, Germany, China, India, and the United Kingdom, with primary inputs from each market cluster combining interviews with data center facility managers, hyperscale procurement executives, containment system commissioning engineers, and mechanical contracting firms. Secondary validation draws from EPA ENERGY STAR certification databases, EU Energy Efficiency Directive implementation reports, China's Ministry of Ecology and Environment efficiency audit disclosures, and ASHRAE thermal guideline publications. Bottom-up and top-down triangulation reconciles installation volume estimates with supplier revenue disclosures across the analysis window.
Rate-of-change decomposition separates volume expansion from price evolution across product type, installation method, end user, and technology segmentation dimensions. CAGRs derive from installed base growth curves, regulatory compliance deadline clustering, and hyperscale capex deployment patterns. Industry-specific forecast inputs include GPU rack density trajectories for AI training facilities and provincial energy intensity cap enforcement timelines in Beijing, Shanghai, and Shenzhen.
Underlying measurement precision varies by segment; modular systems and hyperscale deployments carry tighter precision than custom builds and enterprise retrofits where slab elevation mismatches and fire suppression rerouting introduce installation labor variability. Forecasts reflect assumptions on regulatory enforcement intensity, aluminum price volatility persistence, and commissioning engineer training pipeline development. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market