
 Server Operating Environments Market | 2026-2036
Server Operating Environments Market Size, Share, and Industry Trends Forecast 2026-2036
Server Operating Environments Market Analytics
The gap between premium enterprise server operating environments and commodity open-source distributions is expanding as IT procurement teams face sharper trade-offs between support guarantees and licensing costs. Microsoft Corporation leverages its hybrid cloud integration to sustain premium pricing across large enterprise accounts. Red Hat Inc. anchors its position through subscription-backed enterprise Linux with certified container orchestration. Canonical Ltd. competes aggressively on zero-license-cost Ubuntu deployments that appeal to cost-conscious SME segments.
Server operating environments encompass the software layers—operating systems, hypervisors, container runtimes, and virtual machine monitors—that abstract physical hardware resources and allocate compute, memory, and storage to workloads. These environments typically support x86-64 and ARM instruction set architectures, with kernel-level resource scheduling measured in microsecond latencies for deterministic performance. Deployment model segmentation reveals hybrid architectures capturing the fastest expansion as organizations retain sensitive workloads on-premises while bursting to cloud infrastructure. Container platform adoption outpaces traditional hypervisor growth where microservices architectures demand sub-second provisioning cycles and immutable infrastructure patterns.
NIST, FedRAMP, and ISO 27001 compliance requirements shape server operating environment selection in regulated industries by mandating auditable patch cycles, hardware-rooted trust chains, and documented supply chain provenance. The EU AI Act and GDPR data residency rules in Europe further constrain cross-border workload placement and operating system configuration choices. Stakeholders must monitor how sovereignty-driven certification schemes fragment previously unified procurement standards across jurisdictions.
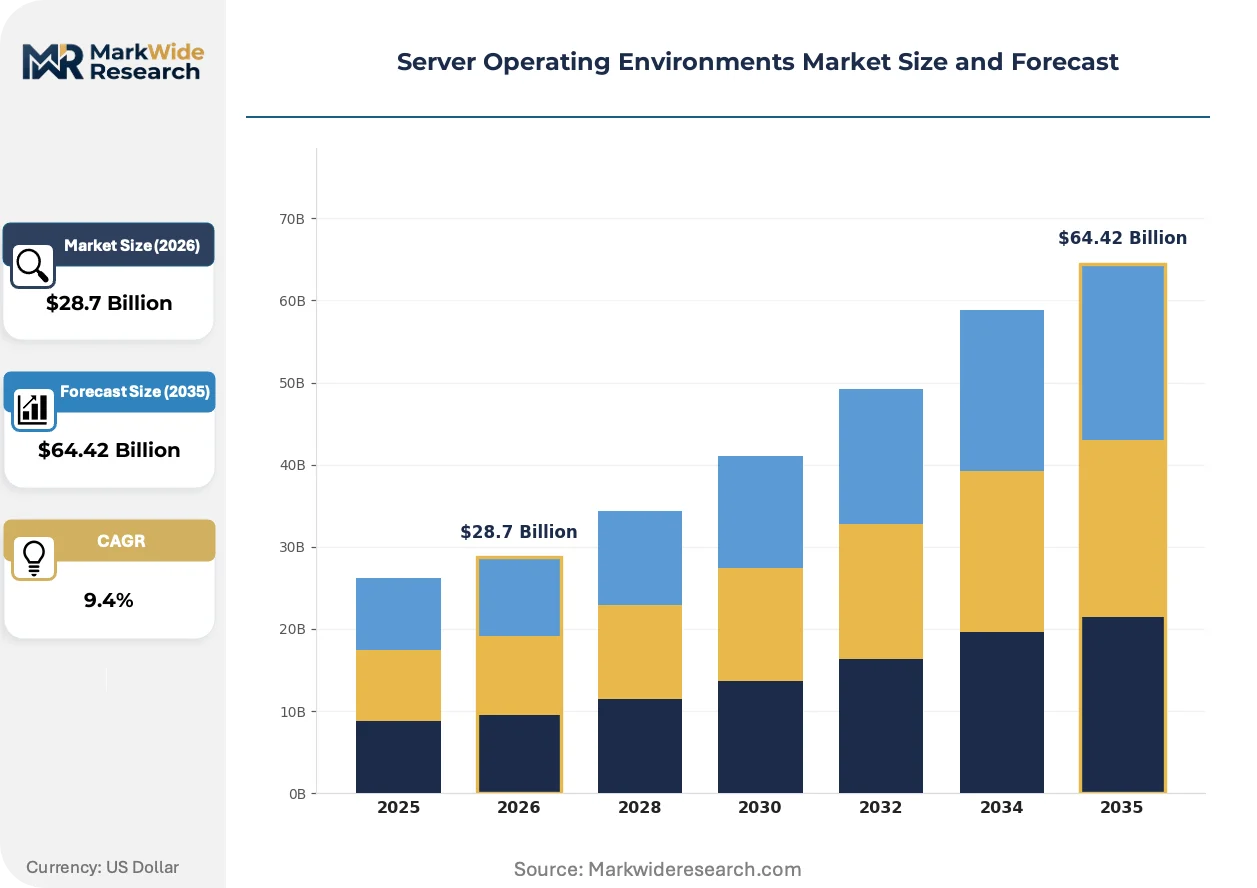
Market Dynamics
Container-first architectures and sovereignty-driven compliance mandates are fragmenting procurement standards across federal and enterprise data centers, forcing vendors to maintain parallel certification tracks for identical technology stacks.
Growth Catalysts
- FedRAMP Authorization:US federal cloud procurement now requires standardized security assessments, accelerating vendor investment in compliant server operating environment distributions for government workloads.
- Container Orchestration:Kubernetes-native platforms enable sub-second provisioning cycles that microservices architectures demand, pulling enterprise migration away from traditional hypervisor stacks.
- India's Data Localization:RBI and CERT-In directives mandate domestic data residency, stimulating local server operating environment deployment and indigenous certification programs.
Market Restraints
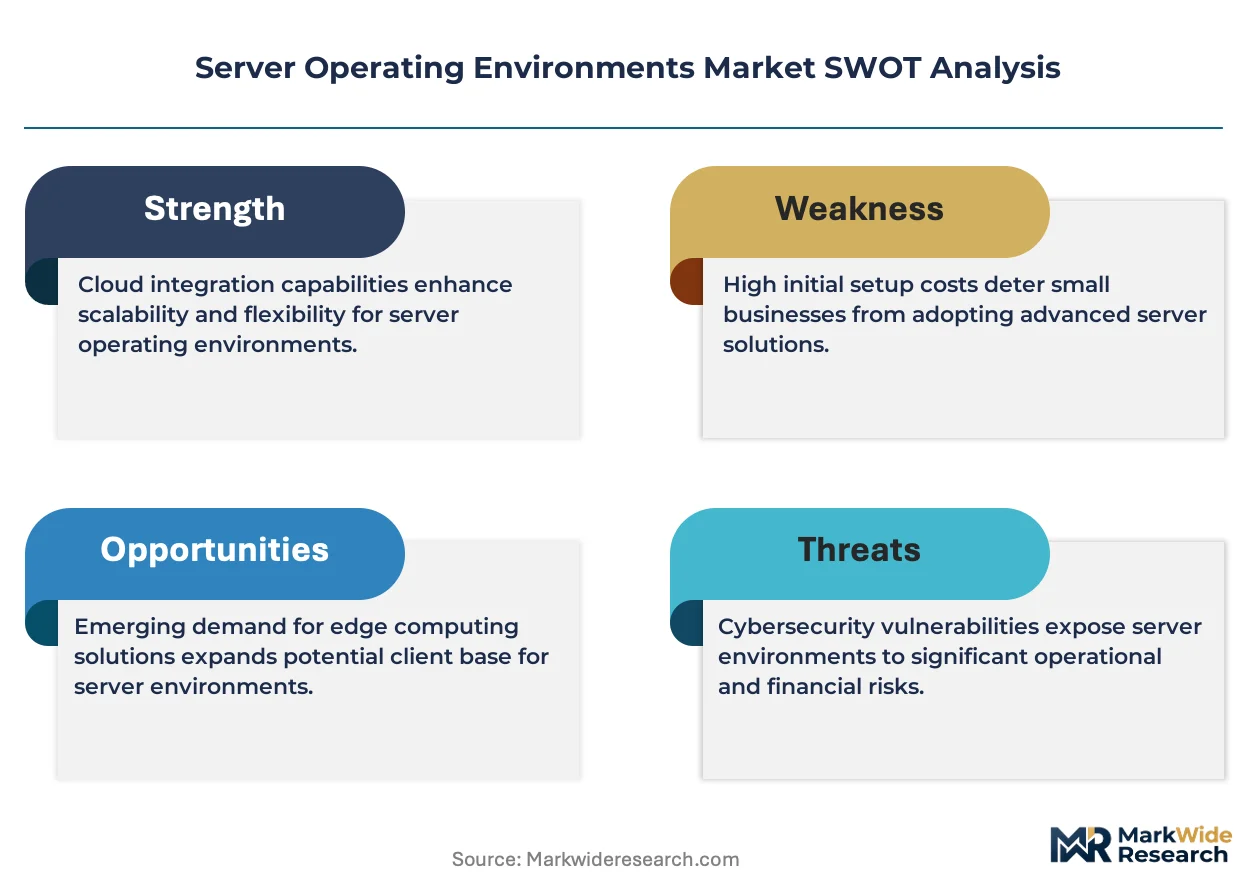
- License Cost Volatility:Per-core pricing models from dominant enterprise vendors create unpredictable TCO escalations as core densities rise in ARM and x86-64 silicon.
- Supply Concentration:Certified hardware trust chain dependencies concentrate among three major OEM root-of-trust providers, creating single-source fragility for attestation services.
- Technical Debt:Legacy monolithic applications resist containerization without substantial refactoring, slowing operating environment transitions in established enterprise accounts.
Strategic Opportunities
- EU AI Act Compliance:Conformity assessment requirements for high-risk AI systems create demand for auditable operating environment configurations with immutable logging and hardware-backed attestation.
- Edge-Native Distributions:Lightweight container runtimes optimized for constrained compute nodes address manufacturing and telecommunications deployments previously unserved by datacenter-centric platforms.
- Subscription-to-Consumption Pivot:Usage-based billing models for serverless workloads unlock SME segments previously priced out of enterprise support tiers.
Industry Challenges
- Kernel Engineering Talent:Deep expertise in scheduler optimization and memory subsystem tuning for deterministic latency remains scarce relative to demand from financial services and autonomous systems sectors.
- Cross-Jurisdiction Certification:Reconciling NIST, ETSI, and BIS security frameworks requires redundant audit cycles that extend product launch timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Server Operating Environments Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operating System, Hypervisor, Container Platform, Virtual Machine Monitor Deployment Model: On-Premises, Cloud, Hybrid, Edge End User: SMEs, Large Enterprises, Government, Educational Institutions Technology: Virtualization, Containerization, Microservices, Serverless |
| Companies Covered | Microsoft Corporation, Red Hat Inc., Amazon Web Services Inc., Oracle Corporation, Alphabet Inc., Fujitsu Ltd., Hewlett Packard Enterprise, Dell Technologies Inc., Canonical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Server Operating Environments Market Evolving Landscape
Immutable infrastructure patterns and hardware-rooted security are converging to redefine how operating environments establish and maintain trust boundaries across distributed compute fabrics.
eBPF instrumentation is decentralizing observability and security enforcement by embedding programmable kernel hooks directly into runtime environments. Cloud-native enterprises and telecommunications operators are deploying eBPF-based sidecars at scale to replace traditional agent-based monitoring. This architecture is decentralizing security policy enforcement from centralized control planes to per-node execution contexts, compressing response latencies for threat detection.
EU AI Act risk classification tiers are mandating documented provenance chains for training data and inference workloads operating on server environments. High-risk AI system deployers must now demonstrate hardware-backed isolation and tamper-evident logging. Financial services and healthcare verticals in Germany and France are restructuring procurement specifications to prioritize operating environments with pre-certified compliance modules.
FinOps-driven accountability is compressing cloud commitment cycles and unbundling support tiers from base licensing. Enterprise buyers now demand granular cost attribution by workload rather than blanket enterprise agreements. This behavioral shift is most pronounced among technology and media companies in the United States, where platform teams negotiate direct contracts with container runtime providers independent of historical vendor relationships.
Server Operating Environments Market Segmentation
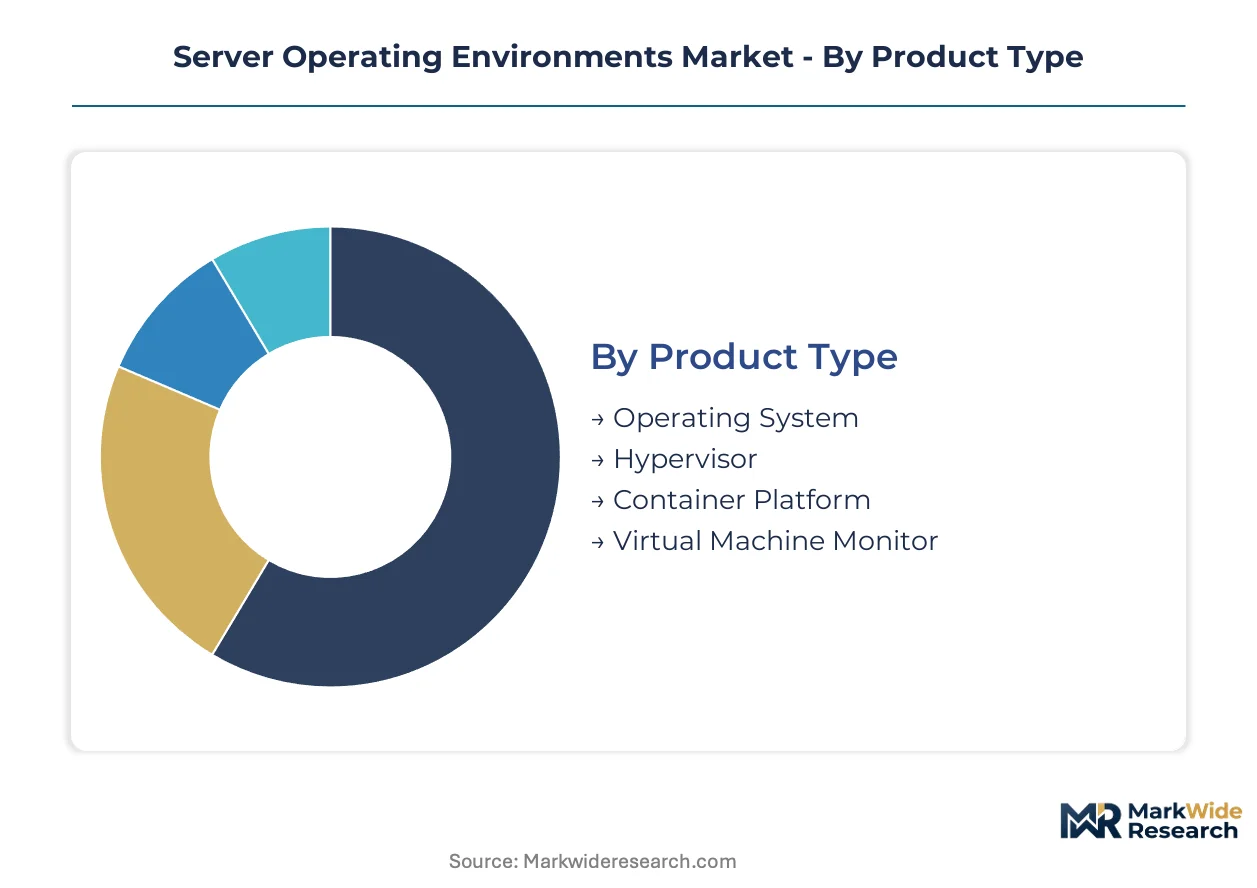
Server operating environment procurement diverges sharply across workload types and compliance postures. Segmentation reveals where container-native architectures displace legacy virtualization and how sovereignty mandates reshape deployment geography.
Product Type:
Upgrade cycles for server infrastructure software accelerate where hardware refresh timelines compress and security certification windows tighten.
- Operating System:Kernel-level resource abstraction with scheduler optimization for x86-64 and ARM silicon. Large enterprises in Germany prioritize subscription-backed enterprise Linux with FedRAMP-aligned patch cycles over zero-license alternatives.
- Hypervisor:Type-1 and Type-2 virtualization layers managing hardware resource partitioning. On-premises data centers in regulated US sectors retain hypervisor stacks for legacy monolithic workloads resisting containerization.
- Container Platform:Kubernetes-native orchestration with sub-second provisioning cycles. Microservices architectures pull demand from financial services clusters in India.
- Virtual Machine Monitor:Lightweight hypervisor variants for embedded and edge-constrained nodes. Telecommunications deployments in manufacturing corridors favor stripped-down resource isolation.
Operating System sits at the top of the volume ranking, with Container Platform climbing the fastest.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises buildouts from consumption-metered cloud alternatives.
- On-Premises:Dedicated hardware stacks with full operational control over patch cycles and trust chain attestation. US federal data centers mandate on-premises hosting for classified workloads under NIST frameworks.
- Cloud:Third-party managed infrastructure with shared responsibility models for security patching. Technology companies in the United States burst ephemeral workloads to hyperscale providers.
- Hybrid:Workload portability across owned and leased infrastructure with unified orchestration planes. European enterprises navigate GDPR data residency rules through policy-driven placement automation.
- Edge:Distributed compute nodes with constrained power, cooling, and connectivity profiles. Manufacturing facilities in Germany deploy lightweight runtimes for real-time quality control systems.
Hybrid deployments gain share fastest as organizations retain sensitive data on-premises while bursting elastic demand to cloud infrastructure.
End User:
Application complexity and compliance exposure segment procurement sophistication across organizational scale.
- SMEs:Cost-conscious deployments favoring zero-license operating systems with community support tiers. Canonical Ubuntu captures share in India where CERT-In directives intersect with budget constraints.
- Large Enterprises:Multi-year enterprise agreements with certified support SLAs and dedicated technical account management. Microsoft sustains premium pricing through hybrid cloud integration across Fortune 500 accounts.
- Government:Mandated security frameworks requiring documented supply chain provenance and hardware-rooted attestation. FedRAMP authorization gates federal cloud procurement in the United States.
- Educational Institutions:Research computing clusters with specialized licensing concessions and academic tier pricing. Supercomputing centers in Germany prioritize kernel customization for HPC workloads.
Large Enterprises anchor procurement volume, with Government segments expanding most quickly as sovereignty mandates proliferate.
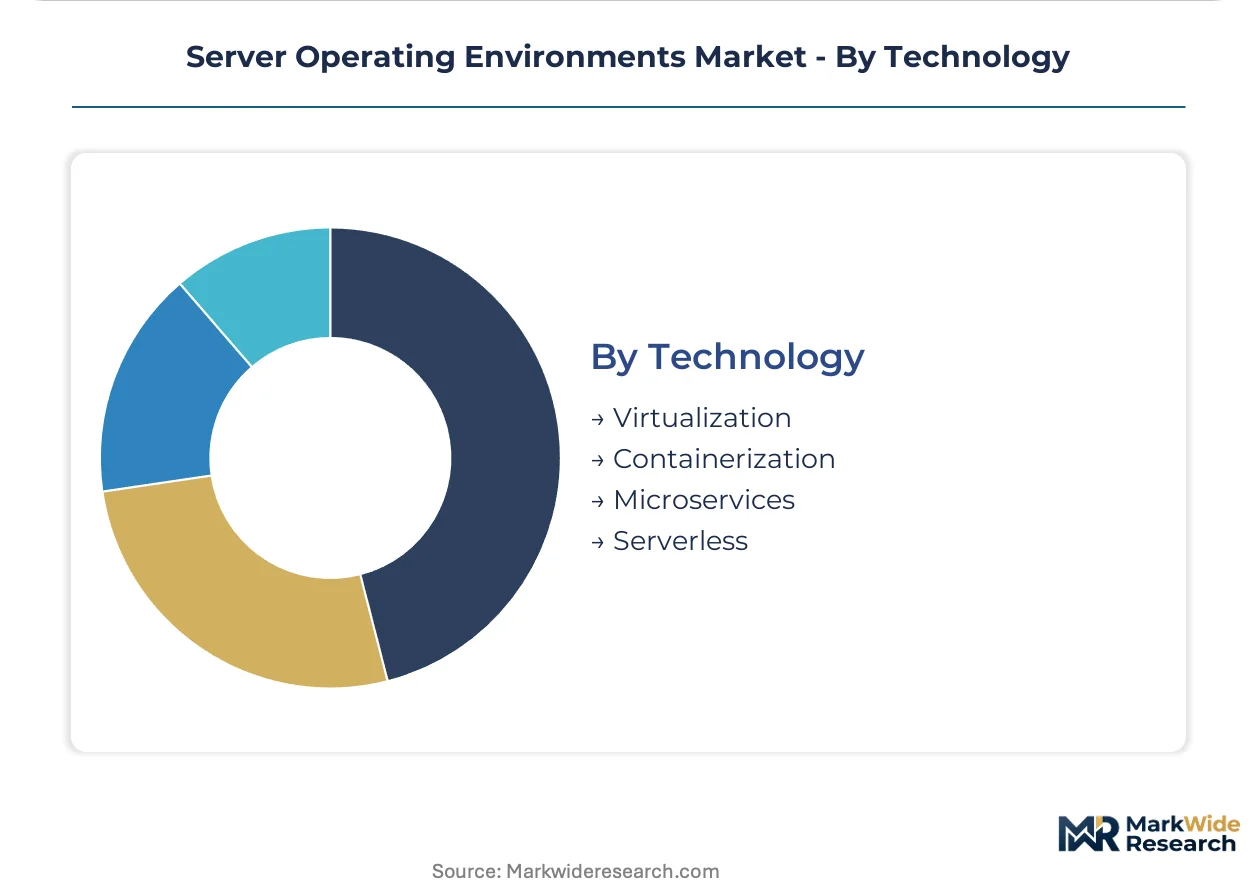
Technology:
Maturity curves separate established virtualization from emerging serverless paradigms with divergent talent requirements.
- Virtualization:Hardware abstraction through hypervisor-mediated resource partitioning. Legacy enterprise accounts maintain VMware and KVM stacks for monolithic applications resisting refactoring.
- Containerization:OS-level isolation with immutable image distribution and orchestrated lifecycle management. Kubernetes dominates new workload deployment across technology and media verticals.
- Microservices:Decomposed application architectures demanding sub-second provisioning and service mesh connectivity. Financial services in the United States restructure development pipelines around container-native patterns.
- Serverless:Event-driven compute with metered execution and zero infrastructure management. SME segments access enterprise-grade scalability through consumption-based billing models.
Virtualization retains the largest installed base, with Serverless expanding most steeply as FinOps accountability compresses commitment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kernel engineering talent concentrates in the United States, Germany, and India, anchoring procurement decisions for server operating environments across federal, enterprise, and cloud-native segments. Sovereignty mandates and data residency rules are fragmenting certification requirements by jurisdiction.
United States
FedRAMP authorization gates federal cloud procurement, compelling vendors to maintain compliant distribution tracks for government workloads. NIST cybersecurity frameworks mandate auditable patch cycles and hardware-rooted trust chains for classified data centers. Northern Virginia's hyperscale corridor hosts the densest concentration of cloud infrastructure, driving demand for hybrid orchestration platforms.
Germany
GDPR data residency rules and EU AI Act conformity assessments constrain cross-border workload placement for financial services and healthcare verticals. ETSI security frameworks require redundant audit cycles that extend product launch timelines. Frankfurt's financial district anchors procurement for immutable logging and hardware-backed attestation systems.
India
RBI and CERT-In directives mandate domestic data residency, stimulating local server operating environment deployment and indigenous certification programs. Cost-conscious SME segments favor zero-license distributions with community support tiers. Bengaluru's technology corridor drives Kubernetes-native adoption for microservices architectures in financial services clusters.
United Kingdom
Post-Brexit data protection divergence creates parallel compliance tracks for UK-EU workload transfers. Financial regulators in the City of London emphasize deterministic latency for trading infrastructure. London's fintech concentration demands sub-second provisioning cycles and immutable infrastructure patterns.
Japan
METI industrial policy promotes sovereign cloud infrastructure for critical manufacturing systems. JIS standards and localized certification requirements favor domestic integration partners for enterprise deployments. Tokyo-Osaka manufacturing corridors deploy lightweight container runtimes for real-time quality control systems.
Server Operating Environments Market Competitive Landscape
Top-tier vendors anchor hybrid cloud integration and subscription-backed enterprise support, while specialized container runtime providers compete on zero-license cost structures. The market structure stratifies across three tiers: hyperscale cloud operators with captive distributions, enterprise Linux vendors with certified orchestration stacks, and community-backed distributions targeting cost-sensitive segments. Two strategic archetypes dominate: vertically integrated cloud providers bundling infrastructure with operating environments, and independent software vendors monetizing through support subscriptions. Competitive moves concentrate on FedRAMP certification investments and edge-native distribution development.
Within the enterprise subscription tier, Microsoft Corporation and Red Hat Inc. exemplify divergent approaches to hybrid cloud monetization. Microsoft leverages Windows Server and Azure Stack integration to sustain premium pricing across Fortune 500 accounts with multi-year enterprise agreements. Red Hat anchors its position through subscription-backed enterprise Linux with certified OpenShift container orchestration. Canonical Ltd. occupies a distinct position in the zero-license tier, competing aggressively on Ubuntu deployments that appeal to CERT-In-constrained budgets in India and SME segments globally.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Red Hat Inc. |
| Amazon Web Services Inc. |
| Oracle Corporation |
| Alphabet Inc. |
| Fujitsu Ltd. |
| Hewlett Packard Enterprise |
| Dell Technologies Inc. |
| Canonical Ltd. |
| Others |
Value Network & Pricing Analysis
Federal procurement officers and hyperscale cloud architects concentrate purchasing power for server operating environments, anchoring enterprise subscription pricing while SME segments drive zero-license alternatives. This buyer bifurcation shapes vendor strategies across certification-heavy government tracks and cost-optimized community support tiers.
Pricing Analysis
Bundled enterprise support subscriptions separate from unbundled community-tier distributions across the server operating environment landscape. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and patch-cycle guarantees as primary price differentiation drivers. Pricing pressure stems from ARM silicon core-density increases that inflate per-core licensing costs unpredictably. Government buyers exhibit lowest price sensitivity due to FedRAMP mandate compliance requirements, while Indian SME segments prioritize zero-license Ubuntu deployments under CERT-In budget constraints.
Supply Chain Analysis
Hardware-rooted trust chain dependencies rest on three major OEM root-of-trust providers concentrated in the United States, Taiwan, and Germany. Kernel engineering talent, certified patch distribution infrastructure, and attestation silicon feed from these geographic anchors. Single-source vulnerability in attestation services creates supply chain fragility for federal compliance workloads. Distribution runs through direct enterprise agreements with hyperscale cloud operators and certified systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Server operating environment vendors capture margin expansion through consumption-based billing pivots that compress SME entry costs while sustaining premium tiers for sovereign compliance mandates. FinOps accountability unbundles support from base licensing, creating pricing power for certified configurations.
For Market Incumbents:Cement hybrid cloud integration advantages through deeper Azure Stack and OpenShift orchestration binding. Invest in parallel FedRAMP and ETSI certification tracks to preempt jurisdiction fragmentation. Acquire kernel engineering talent pools in Bengaluru and Frankfurt to defend scheduler optimization capabilities against fintech and autonomous systems demand surges.
For New Entrants and Emerging Players:EU AI Act conformity assessment requirements in Germany and France open a window for auditable operating environment configurations with immutable logging modules. Target edge-native container runtimes for manufacturing quality control systems in Japan's Tokyo-Osaka corridor. Pursue direct platform team contracts with US technology and media companies bypassing historical vendor relationships.
For Investors and Strategic Acquirers:Hyperscale cloud operators with captive distributions are the most active acquirer in this space, consolidating orchestration stack control. Long-term viability favors container runtime specialists with certified government tracks and edge-optimized lightweight distributions. Watch for RBI and CERT-In directive expansion triggering indigenous certification program investments as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Certification Investment | Standardized security assessments gate federal cloud procurement for government workload vendors. |
| Edge-Native Distribution Launch | Lightweight container runtimes address manufacturing and telecommunications deployments beyond datacenter-centric platforms. |
| Consumption-Based Billing Pivot | Usage-based serverless models unlock SME segments previously priced out of enterprise support tiers. |
| Kernel Engineering Talent Acquisition | Deep scheduler optimization expertise remains scarce relative to financial services and autonomous systems demand. |
| Cross-Jurisdiction Certification Parallel Tracks | Reconciling NIST, ETSI, and BIS frameworks requires redundant audit cycles extending product launch timelines. |
Research Methodology
Multiple input streams — primary interviews with platform engineers and IT procurement officers, hyperscaler capex disclosures, and SEC filings — were reconciled with customs data and open-source project contribution metrics. Conversations with federal cloud architects, container runtime specialists, and channel integration partners informed demand-side validation. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Historical capacity expansion patterns were cross-referenced against expert panel inputs on containerization adoption curves. Segmentation dimensions modeled include deployment model, organization size, compliance posture, and regional sovereignty mandate intensity. CAGRs were derived from fitted growth curves calibrated to infrastructure software replacement cycles and hardware refresh timelines. Kernel engineering labor market tightness and certification window durations informed supply-side constraints.
Revisions become necessary when sovereign data residency mandates expand beyond current RBI, CERT-In, and GDPR footprints, or when ARM silicon core-density trajectories accelerate per-core licensing cost escalations. Forecasts reflect assumptions about FedRAMP authorization velocity and EU AI Act implementation timelines. A small set of named triggers — hyperscale cloud operator captive distribution expansion, edge-native workload proliferation, and cross-jurisdiction certification harmonization efforts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Netherlands Data Center Rack Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Malaysia Data Center Rack Market