
 Data Center Rack Power Distribution Unit Market | 2026-2036
Data Center Rack Power Distribution Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Rack Power Distribution Unit Market Intelligence
Intelligent power monitoring and remote outlet control is rewriting margin allocation across the data center rack PDU value chain. Schneider Electric leverages its integrated EcoStruxure platform to bundle software-defined power management with hardware sales. Vertiv Group Corp. anchors its position through thermal-electrical co-design capabilities that reduce deployment complexity for hyperscale operators. Eaton Corporation PLC competes on manufacturing scale, operating one of the largest North American production footprints for three-phase rack distribution units.
A data center rack power distribution unit is an electrical device mounted within a server rack that distributes alternating current from an uninterruptible power supply or utility feed to multiple servers, networking gear, and storage arrays, typically supporting 120V to 480V configurations with branch circuit protection via circuit breakers or fuses. Its primary purpose is to enable granular load monitoring, remote switching, and failover isolation at the rack level to optimize energy efficiency and uptime in dense compute environments. Smart PDUs now capture the fastest-growing margin pool as colocation providers and cloud operators demand outlet-level metering for chargeback accuracy and carbon reporting. Three-phase technology leads volume in facilities above 500 kW per rack, while single-phase units remain dominant in enterprise edge deployments and legacy retrofits where infrastructure refresh cycles lag.
UL 60950-1 and IEC 62368-1 safety standards govern product certification requirements for rack PDUs sold into North American and European data center markets, with the EU F-Gas Regulation indirectly shaping thermal-electrical integration specifications through refrigerant-based cooling constraints. The US Department of Energy and China's MIIT both enforce minimum efficiency thresholds for power distribution equipment that filter non-compliant vendors from procurement shortlists. Stakeholders must decide whether to prioritize intelligent PDU platforms with embedded AI-driven load balancing or to defend share through cost-optimized basic units as regional efficiency mandates diverge in stringency.
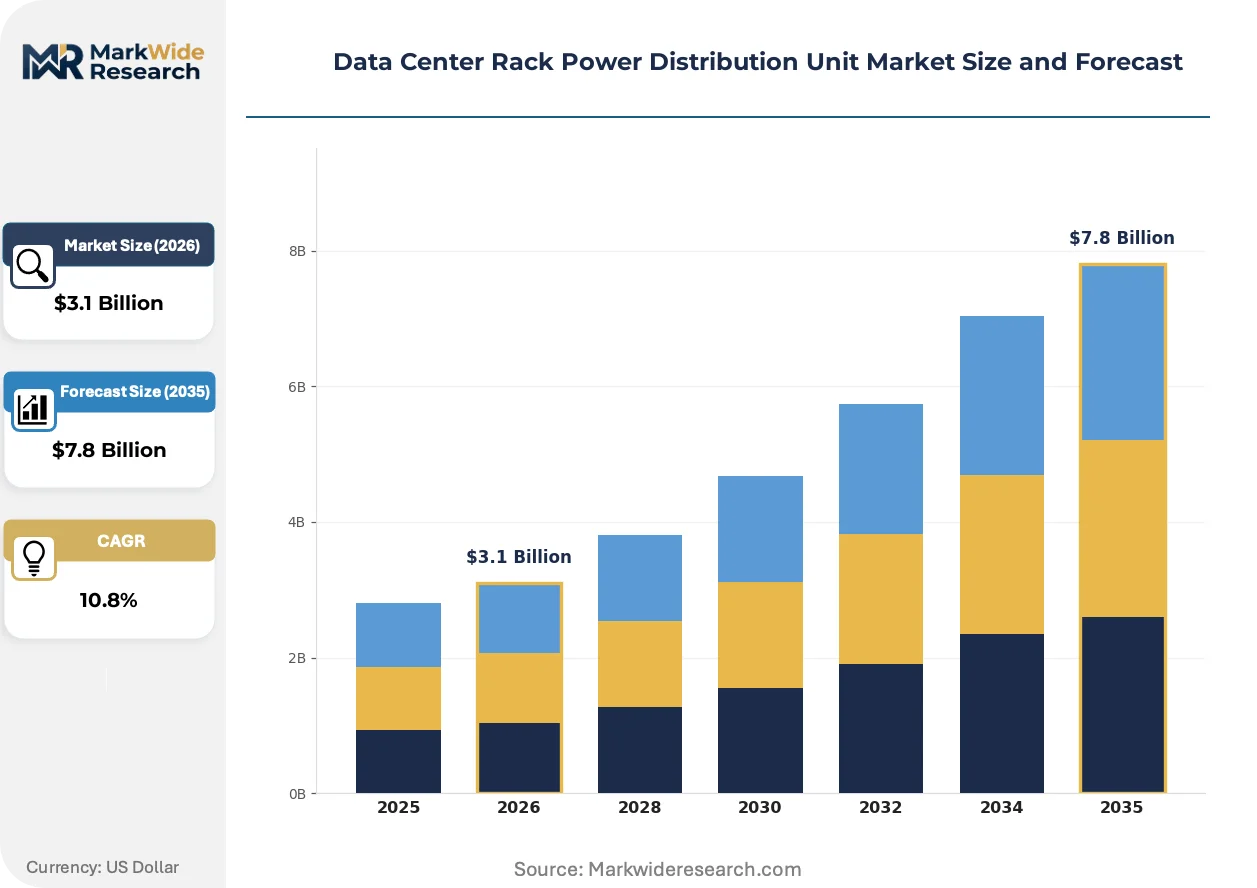
Market Dynamics
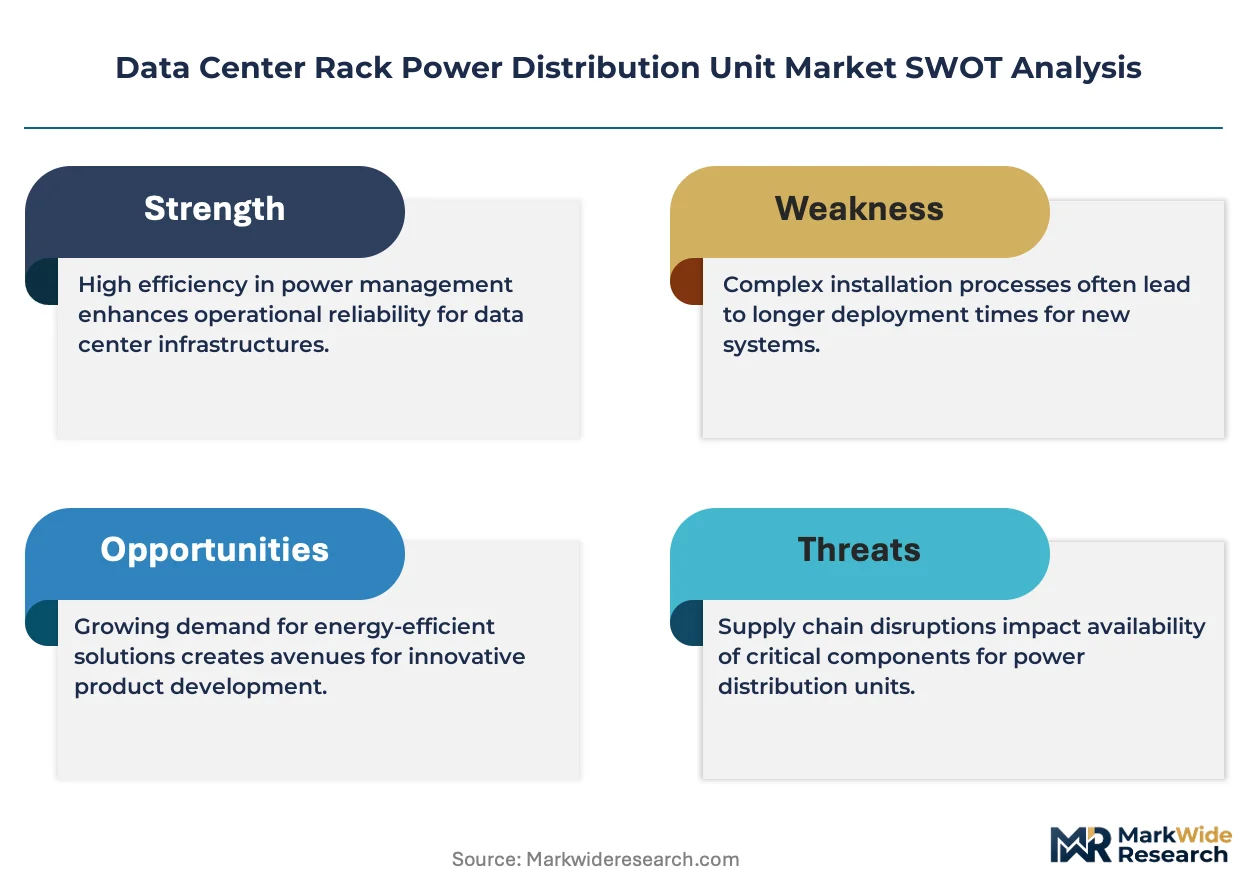
AI training clusters are forcing rack power densities past 50 kW per cabinet, collapsing the economic viability of basic PDUs and compressing replacement cycles for legacy infrastructure across hyperscale and colocation facilities.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates granular power monitoring in data centers above 500 kW, accelerating intelligent PDU deployment across German, French, and Dutch facilities.
- Hyperscale cloud expansion:Training clusters for large language models require outlet-level switching and failover isolation, driving three-phase intelligent unit demand.
- Carbon reporting frameworks:Scope 3 emissions disclosure requirements from CSRD and SEC climate rules force chargeback-grade metering accuracy.
Market Restraints
- Copper and semiconductor input costs:Volatility in busbar materials and PMIC chip supply constrains margin recovery for mid-tier manufacturers.
- Technical limitation of legacy busway integration:Existing overhead power distribution in older facilities cannot accommodate intelligent PDU monitoring without full electrical retrofit.
- China MIIT efficiency thresholds:Local content requirements and certification delays create procurement friction for non-domestic vendors.
Strategic Opportunities
- Edge computing nodes:Distributed AI inference in secondary US metros and tier-2 Chinese cities lacks intelligent power management penetration.
- Liquid cooling convergence:Integration of rack PDU monitoring with coolant flow management creates unified thermal-electrical platforms.
- India PLI scheme for electronics:Manufacturing incentives enable cost-competitive production for Southeast Asian and Middle Eastern export markets.
Industry Challenges
- Certification timeline compression:UL 60950-1 to IEC 62368-1 transition and evolving F-Gas thermal integration standards extend product validation cycles.
- Integration complexity:DCIM software interoperability gaps between vendor-specific protocols stall unified fleet management deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Rack Power Distribution Unit Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $7.8 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic PDUs, Smart PDUs, Metered PDUs, Switched PDUs Technology: Single Phase, Three Phase, Hybrid, Microgrid End User: Colocation Providers, Enterprises, Cloud Service Providers, Telecommunications Installation Type: Floor-Mounted, Wall-Mounted, Rack-Mounted, Modular |
| Companies Covered | Legrand S.A., Cyber Power Systems (USA), Inc., Schneider Electric SE, Leviton Manufacturing Co., Inc., Tripp Lite, Vertiv Group Corp., Hewlett Packard Enterprise Company, ABB Ltd, Eaton Corporation PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Rack Power Distribution Unit Market Strategic Shifts & Innovations
Software-defined power management is collapsing the boundary between electrical distribution and IT operations, enabling real-time load orchestration that was previously hardware-constrained.
Embedded controller firmware with outlet-level virtualization is virtualizing power allocation across shared infrastructure. Colocation providers in Amsterdam and Singapore deploy these systems to partition single physical circuits across multiple tenant billing zones. The technology is virtualizing traditional fixed-circuit electrical topology into dynamically assignable resource pools.
REACH substance restrictions and RoHS amendments are tightening material compliance for cable assemblies and connector housings. Manufacturers serving EU markets now face extended supplier qualification timelines for halogen-free compounds. German and French data center operators increasingly specify full material disclosure as a procurement gate.
Facility operators now bundle rack PDU procurement with long-term energy management service agreements rather than discrete hardware purchases. Channel partners in the United States and China assemble these combined offerings, displacing traditional distributor markup models. This pattern concentrates most visibly in hyperscale buildouts where capital efficiency metrics override upfront equipment cost minimization.
Data Center Rack Power Distribution Unit Market Segmentation
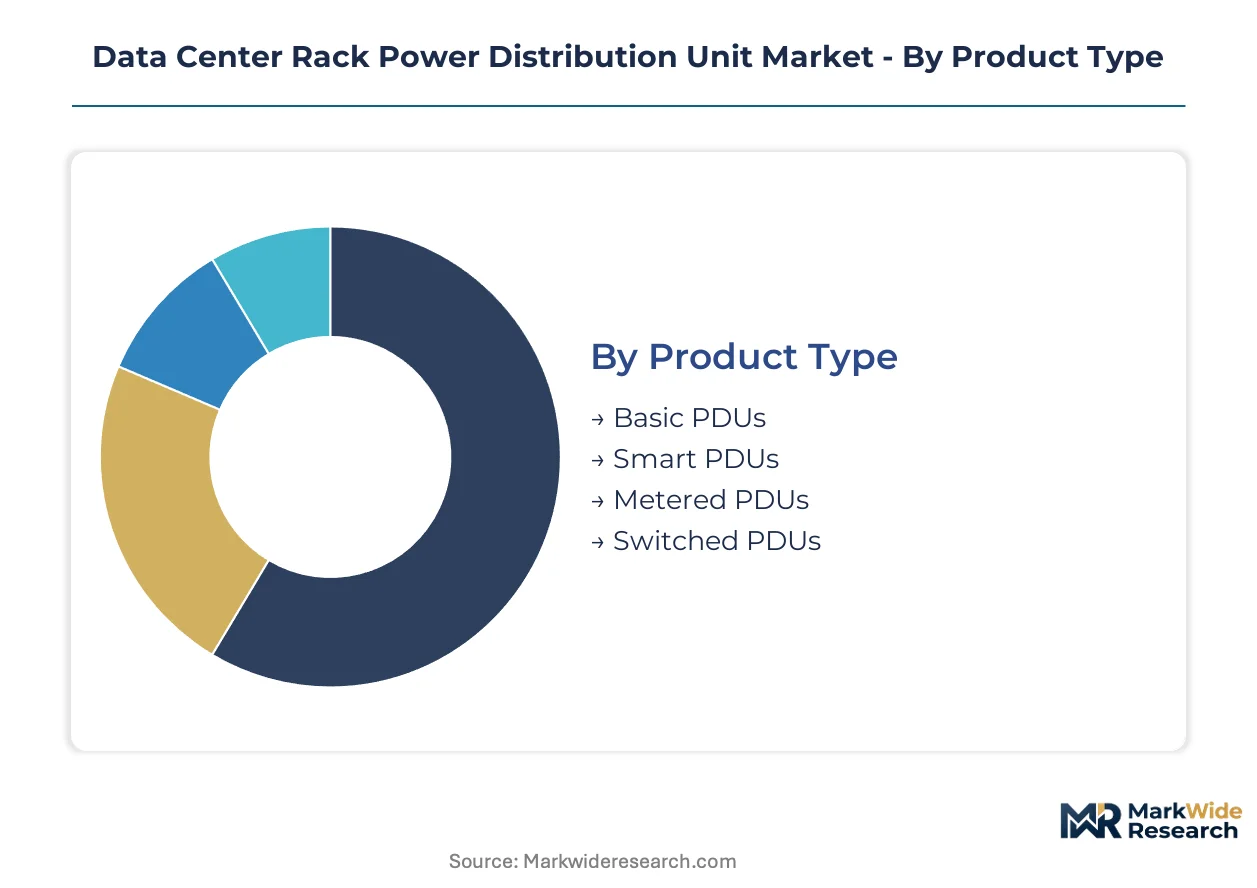
Rack PDU purchasing decisions diverge sharply between hyperscale operators seeking outlet-level telemetry and legacy facilities prioritizing capital preservation. The report examines four structural dimensions—product intelligence, electrical topology, customer archetype, and physical mounting—that collectively determine margin capture and replacement cycle velocity across deployment types.
Product Type:
Mature hardware categories dominate installed base volumes while intelligent variants capture replacement-driven expansion.
- Basic PDUs:Simple power distribution without metering or switching capability, constructed from steel housings with standard circuit breakers. Legacy enterprise facilities in secondary US metros and tier-2 Chinese cities defer intelligent upgrades, extending replacement cycles beyond typical infrastructure refresh timelines.
- Smart PDUs:Embedded controllers enable outlet-level metering, remote switching, and API integration with DCIM platforms. Hyperscale cloud service providers in Germany and the Netherlands mandate these units for CSRD-compliant carbon reporting and tenant chargeback accuracy.
- Metered PDUs:Aggregate branch-circuit monitoring without individual outlet control, occupying a mid-tier price position. Colocation providers in Singapore and Amsterdam deploy these for facility-level energy optimization without full switching infrastructure.
- Switched PDUs:Remote outlet control without granular metering, suited for failover isolation scenarios. Telecommunications operators in rural US markets specify these for unmanned edge site reliability.
Basic PDUs handle the majority of throughput; Smart PDUs are the fastest mover on share.
Technology:
Electrical topology selection tracks rack power density thresholds, with phase configuration directly constraining deployment feasibility.
- Single Phase:120V to 240V distribution for racks below 10 kW, employing standard NEMA or IEC connectors. Enterprise edge deployments in secondary German cities and legacy retrofits across US commercial real estate sustain residual demand despite density limitations.
- Three Phase:208V to 480V configurations supporting 50+ kW cabinets through balanced load distribution. AI training clusters operated by cloud providers in Northern Virginia and Frankfurt require these units for thermal-electrical co-design compatibility.
- Hybrid:Dual-mode units configurable for single or three-phase operation, reducing SKU complexity for multi-tenant facilities. Colocation operators in Amsterdam deploy these for flexible tenant onboarding across varying density requirements.
- Microgrid:Island-capable distribution with integrated energy storage coupling, enabling grid-independent operation. Experimental deployments at research facilities in Switzerland and Singapore test resilience architectures for critical workloads.
Three Phase technology commands the premium pricing tier; Hybrid configurations are climbing the fastest as colocation flexibility requirements intensify.
End User:
Customer archetype determines procurement sophistication, from capital-efficiency metrics to compliance-driven specification rigor.
- Colocation Providers:Multi-tenant operators requiring outlet-level metering for tenant billing and SLA enforcement. Facilities in Frankfurt and Singapore lead intelligent PDU penetration driven by carbon disclosure mandates and competitive differentiation.
- Enterprises:Single-occupant data centers with longer refresh cycles and basic PDU retention. Financial services firms in New York and manufacturing conglomerates in Stuttgart prioritize reliability over telemetry granularity.
- Cloud Service Providers:Hyperscale operators with standardized rack designs and direct manufacturer relationships. Training cluster deployments in Northern Virginia, Frankfurt, and Shanghai specify custom three-phase intelligent units with embedded firmware.
- Telecommunications:Edge and central office facilities with space-constrained, unmanned operational requirements. 5G infrastructure rollouts across rural US counties and tier-3 Chinese cities sustain demand for switched PDUs with remote management.
Cloud Service Providers drive specification innovation; Colocation Providers are expanding most quickly as multi-tenant construction accelerates.
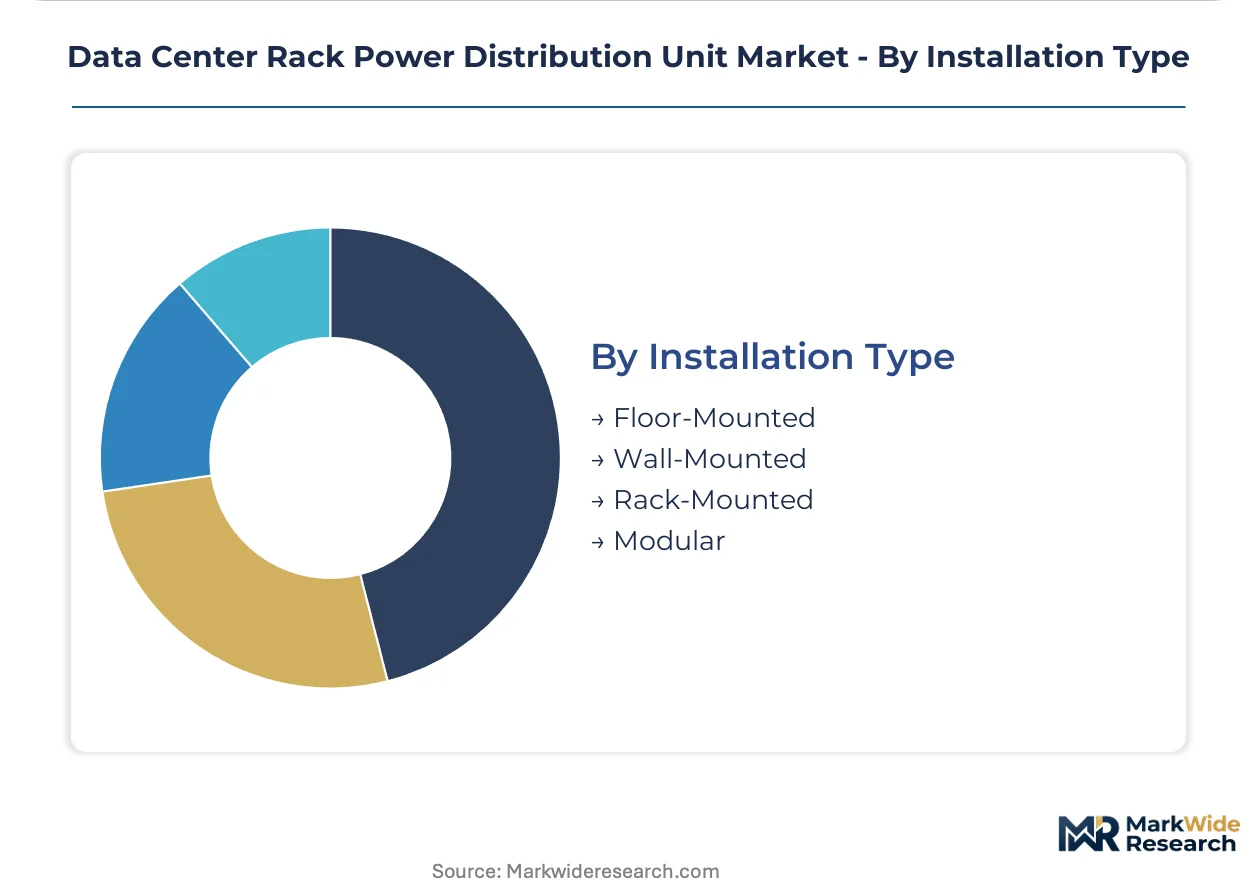
Installation Type:
Physical mounting topology reflects facility vintage, available floor space, and thermal management architecture.
- Floor-Mounted:Freestanding distribution units for open-frame compute halls without raised floor constraints. Hyperscale facilities in Phoenix and Querétaro deploy these for direct overhead busway integration.
- Wall-Mounted:Space-efficient vertical distribution for edge closets and telecommunications huts. Remote banking infrastructure across secondary Indian cities and Southeast Asian manufacturing zones specifies these for footprint minimization.
- Rack-Mounted:Zero-U or 1U/2U form factors integrated within server cabinets, the dominant configuration for standard data center builds. Every major cloud region—Northern Virginia, Frankfurt, Shanghai, Singapore—standardizes on this topology.
- Modular:Hot-swappable sub-assemblies enabling capacity expansion without full rack disruption. Flexible shell facilities in Amsterdam and Dallas adopt these for rapid reconfiguration between tenant density profiles.
Rack-Mounted units constitute the volume baseline; Modular systems are gaining share fastest among build-to-suit developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Germany exhibit the least price sensitivity, prioritizing intelligent PDU telemetry for AI cluster management, while operators in secondary Chinese cities and tier-2 Indian markets defer upgrades to preserve capital.
United States
Hyperscale cloud operators in Northern Virginia and Phoenix drive three-phase intelligent PDU specifications for training clusters exceeding 50 kW per rack. The SEC climate disclosure rules mandate granular power monitoring for Scope 3 emissions reporting. Dallas-Fort Worth and Atlanta data center corridors standardize on outlet-level metering for tenant chargeback accuracy.
Germany
Frankfurt's colocation density and the EU Energy Efficiency Directive create the strictest intelligent PDU penetration requirements in Europe. The CSRD carbon reporting framework forces outlet-level metering precision across facilities above 500 kW. Berlin-Brandenburg and Bavaria hyperscale campuses deploy three-phase units with embedded firmware for load balancing.
China
MIIT efficiency thresholds and local content requirements filter non-domestic vendors from procurement shortlists in Shanghai and Beijing. The dual carbon goals accelerate replacement cycles for legacy basic PDUs in state-owned data centers. Sichuan-Chongqing and Yangtze River Delta regions concentrate AI training cluster construction with custom three-phase specifications.
India
Mumbai and Bengaluru colocation providers adopt metered PDUs for facility-level optimization without full switching infrastructure. The PLI scheme for electronics manufacturing enables cost-competitive production for Southeast Asian export markets. Delhi-NCR and Hyderabad edge computing nodes remain underpenetrated by intelligent power management systems.
Singapore
Tropical climate constraints and limited land availability force thermal-electrical co-design integration in Marina Bay and Jurong facilities. The Energy Conservation Act mandates granular monitoring for data centers above specified consumption thresholds. Colocation operators deploy hybrid-phase PDUs for flexible tenant onboarding across varying density requirements.
Data Center Rack Power Distribution Unit Market Key Industry Players
Integrated platform providers and manufacturing-scale specialists split the market into distinct competitive spheres. The vendor base concentrates around electrical infrastructure conglomerates with captive distribution networks and pure-play power management specialists with software-defined capabilities. Three archetypes dominate: full-stack industrial conglomerates, thermal-electrical integration specialists, and component-scale manufacturers. M&A activity targets DCIM software interoperability, while capacity expansion focuses on three-phase intelligent unit production for AI cluster demand.
Among French electrical infrastructure conglomerates, Legrand S.A. exemplifies the full-stack archetype with integrated cable management and power distribution portfolios. Schneider Electric SE anchors the platform-integrated tier through its EcoStruxure software-hardware bundling. Vertiv Group Corp. represents the thermal-electrical co-design specialist archetype, occupying a position where power management converges with cooling system integration. These three entities illustrate how competitive positioning diverges between software-defined orchestration and manufacturing-scale hardware supply.
| Leading Market Players |
|---|
| Legrand S.A. |
| Cyber Power Systems (USA), Inc. |
| Schneider Electric SE |
| Leviton Manufacturing Co., Inc. |
| Tripp Lite |
| Vertiv Group Corp. |
| Hewlett Packard Enterprise Company |
| ABB Ltd |
| Eaton Corporation PLC |
| Others |
Cost & Logistics Intelligence
The Shanghai-to-Rotterdam container corridor's rate volatility feeds directly into landed cost spreads between Asian manufacturing hubs and European deployment sites, compressing margin recovery for mid-tier PDU vendors while amplifying price differentiation between integrated platform providers and commodity assemblers.
Pricing Analysis
After-sales service revenue from firmware subscriptions and DCIM integration contracts now drives lifetime value capture for intelligent PDU platforms. Three-tier pricing structure across premium intelligent, standard metered, and economy basic levels stratifies by telemetry granularity and certification tier. Cost compression in the basic segment is intensifying because copper busbar volatility and PMIC chip shortages squeeze assembler margins. Cloud service providers exhibit the least price sensitivity, while enterprise facilities in secondary US metros and tier-2 Chinese cities defer upgrades to preserve capital.
Supply Chain Analysis
Copper cathode feedstock draws from Chilean and Peruvian mining operations, while semiconductor controllers for embedded firmware rest on Taiwanese and South Korean foundry output. Steel housings and cable assemblies source predominantly from Chinese and Indian metalworking clusters. Single-source vulnerability concentrates in advanced PMIC supply for outlet-level switching controllers. Distribution runs through electrical infrastructure distributors and direct manufacturer relationships with hyperscale operators, displacing traditional channel markups in large deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rack PDU category is crossing into platform economics as DCIM interoperability becomes the primary switching cost for fleet-wide deployments, with API standardization efforts by the Green Grid consortium reshaping competitive moats around software integration depth rather than hardware specifications alone.
For Market Incumbents: Harden firmware security architectures against emerging cyber-physical threats targeting power infrastructure, as NERC CIP and EU NIS2 directives expand compliance scope. Deepen backward integration into semiconductor controller supply to insulate margin from PMIC allocation volatility. Consolidate channel control through exclusive service agreements with top-10 colocation operators in Frankfurt and Singapore.
For New Entrants and Emerging Players: Establish a beachhead in India's edge computing node deployments, where intelligent power management penetration lags behind facility construction velocity. Target telecommunications operators in rural US markets with switched PDU configurations optimized for unmanned site reliability. Lead with DCIM-agnostic API compatibility to bypass incumbent software lock-in.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant power distribution divisions lacking software-defined capabilities. Long-term viability hinges on intelligent PDU attach rates exceeding basic unit replacement volumes. The signal to watch is hyperscale direct procurement contract migration from distributor-led to manufacturer-direct models.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | EcoStruxure-style bundling collapses hardware-software boundaries for hyperscale procurement teams. |
| Backward Integration | Captive semiconductor controller supply insulates margin from PMIC allocation constraints. |
| DCIM Interoperability Investment | API standardization reduces customer switching costs and accelerates fleet-wide deployment velocity. |
| Thermal-Electrical Co-Design | Vertiv-style integration with liquid cooling systems creates unified infrastructure platforms for AI clusters. |
| Geographic Manufacturing Footprint | India PLI scheme enables cost-competitive export production for Southeast Asian and Middle Eastern markets. |
Research Approach
The analysis maps intelligent, metered, switched, and basic PDU sub-sectors, each validated through data center facility managers, electrical infrastructure procurement officers, and DCIM platform engineers. Primary interviews with colocation operators in Frankfurt, Singapore, and Northern Virginia combined with secondary validation from MIIT efficiency filings, SEC climate disclosure submissions, and EU Energy Efficiency Directive implementation reports. Bottom-up unit deployment tracking triangulates against top-down hyperscale capex analysis.
Assumptions held fixed include regulatory enforcement timelines and copper price banding, while AI training cluster density trajectories and DCIM adoption curves were varied across sensitivity scenarios. Segmentation dimensions modeled span product intelligence tier, electrical topology, end-user archetype, and installation type. CAGRs were derived from replacement cycle compression rates and new build penetration curves, with rack power density thresholds and carbon reporting mandate scope as key forecast inputs.
Sensitivities concentrate around MIIT certification timeline shifts and UL 60950-1 to IEC 62368-1 transition delays that could extend product validation cycles. Forecasts reflect assumptions about hyperscale construction pipeline continuity and copper-semiconductor input cost stability. Cross-checking against hyperscaler direct procurement disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
North America Hyperscale Data Center Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Germany Data Center Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Europe Data Center Physical Security Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
New Zealand Data Center Market