
 Norway Data Center Construction Market | 2026-2036
Norway Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Data Center Construction Market Insights
The EU Energy Efficiency Directive is decoupling data center construction from conventional fossil-dependent power sourcing across Norway. Bulk Infrastructure leverages its deep-water cooling access and renewable power contracts to anchor large-scale developments near Stavanger. Green Mountain sustains its competitive edge through hydroelectric-powered facilities in Telemark and Rjukan. CTS Nordics specializes in modular deployment architectures that compress commissioning timelines for cloud providers entering the Nordic corridor.
Data center construction encompasses the engineered assembly of mission-critical facilities housing servers, storage systems, and network equipment, typically requiring power densities exceeding 15 kW per rack and precision cooling within 1-2 degrees Celsius tolerance. These structures serve as the physical substrate for cloud computing, enterprise IT, and digital service delivery. Construction type segments reveal greenfield projects capturing premium margins due to custom power and cooling architectures, while modular approaches attract hyperscale operators seeking repeatable, factory-tested deployment cycles. Capacity segmentation shows enterprise-level facilities commanding the highest investment intensity per square meter, though medium-scale builds represent the broadest pipeline volume as regional cloud providers expand.
Enova SF, Norway's state enterprise for clean energy, channels capital toward facilities demonstrating substantial efficiency gains, while the Norwegian Water Resources and Energy Directorate regulates grid interconnection standards for new builds. DNV standards for structural resilience and fire safety shape facility certification requirements. Stakeholders must weigh sovereign data residency rules against the capital efficiency of standardized modular designs as European data localization pressures intensify.
Market Dynamics
Hyperscale cloud providers are compressing commissioning timelines for Norwegian data center builds, forcing construction firms to modularize power and cooling architectures while Enova SF tightens efficiency thresholds for state capital access.
Growth Catalysts
- EU Energy Efficiency Directive:Norway's alignment with EU mandates accelerates greenfield development standards, mandating renewable power sourcing and thermal efficiency thresholds that favor new builds over retrofits.
- Hydroelectric surplus:Telemark and Rjukan regions leverage deep reservoir cooling access to attract power-intensive computing workloads from AI training clusters.
- Deep-water cooling:Coastal facilities near Stavanger deploy fjord-based thermal exchange systems that slash mechanical cooling energy intensity below conventional air-cooled designs.
Market Restraints
- Grid interconnection queues:The Norwegian Water Resources and Energy Directorate processes new connection requests through capacity-constrained transmission corridors around Oslo, extending energization timelines.
- Copper and electrical steel volatility:Switchgear and transformer lead times stretch 18-24 months, compressing contractor margins on fixed-price EPC contracts.
- Land scarcity in Viken:Zoning restrictions around the capital region limit contiguous parcels suitable for 50+ MW campus developments.
Strategic Opportunities
- Modular deployment architectures:Factory-tested power and cooling skids enable hyperscale tenants to commission capacity in 6-month increments rather than traditional 24-month build cycles.
- Enova SF capital grants:Facilities demonstrating substantial efficiency gains qualify for direct state funding, offsetting premium costs for liquid cooling and waste heat recovery systems.
- Troms and Finnmark expansion:Northern latitudes offer natural cooling advantages and stranded renewable capacity that remains untapped by current development pipelines.
Industry Challenges
- High-voltage electrical specialist scarcity:Norway's power engineering workforce lacks depth in 132kV+ substation design for data center-scale loads, forcing reliance on imported contractor teams.
- DNV fire safety certification timelines:Mission-critical facility approvals require extended validation of gas suppression and structural resilience protocols, delaying revenue-ready dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Data Center Construction Market |
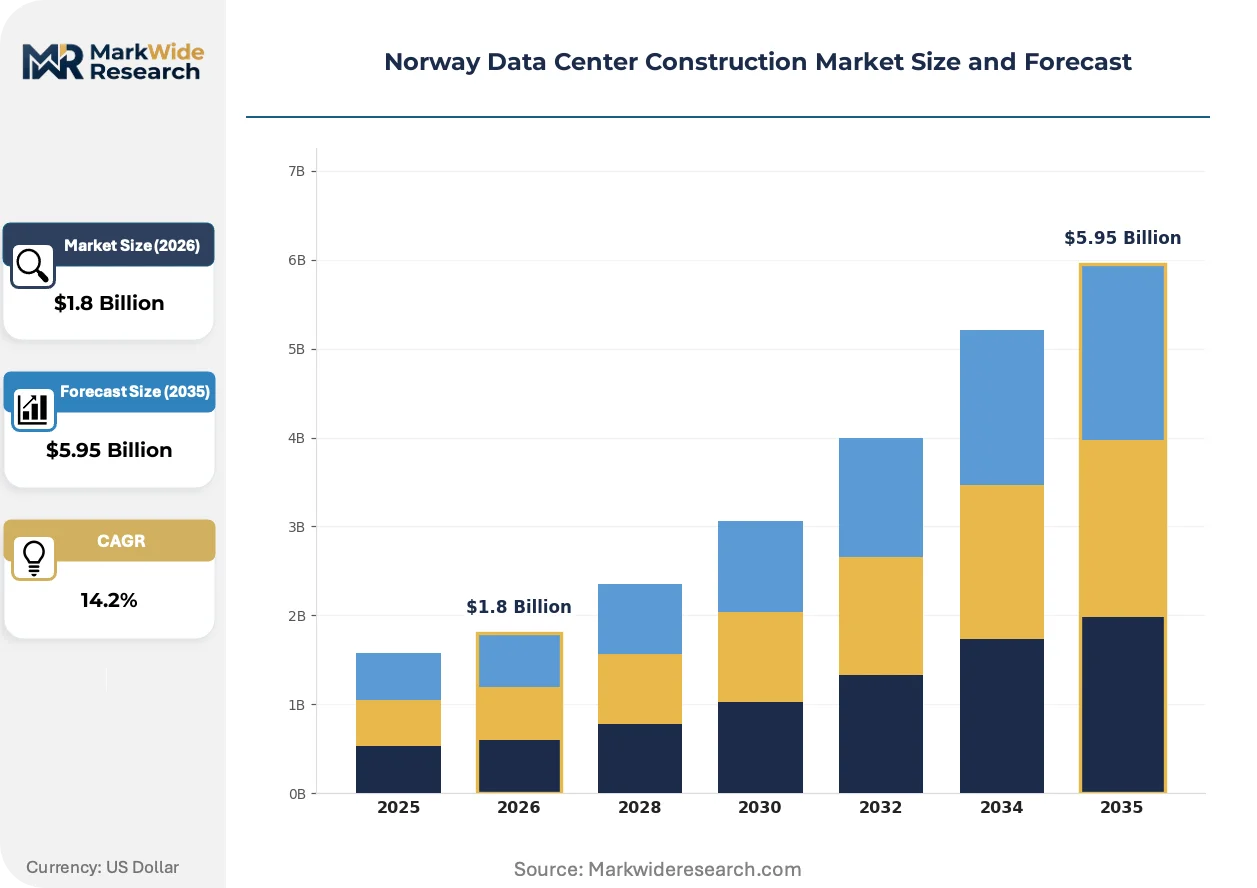
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Construction, Operation, Maintenance Capacity: Small Scale, Medium Scale, Large Scale, Enterprise Level Construction Type: Modular, Traditional, Hybrid, Greenfield End User: Tech Companies, Cloud Providers, Enterprises, Government |
| Companies Covered | CTS Nordics, Bulk Infrastructure, Skanska AB, Stack Infrastructure, Green Mountain, Coromatic AB, Rider Levett Bucknall, AQ Compute, COWI A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Data Center Construction Market Trends and Innovations
Liquid cooling infrastructure is displacing conventional air-handling units across Norwegian facilities, driven by rack densities exceeding 50kW in AI training environments. Construction firms now pre-plumb coolant distribution networks during shell erection.
Direct-to-chip liquid cooling is unifying thermal management with heat reuse architectures. Hyperscale operators in the Viken region are specifying this technology for all new 2025-2026 builds. The approach is unifying power density scaling with district heating export contracts, converting waste heat into revenue streams for municipal networks.
Norway's adoption of EU CSRD disclosure rules forces construction firms to document embodied carbon in concrete and steel selections. DNV certification protocols now require Environmental Product Declarations for structural materials. Enterprise colocation tenants in Oslo are prioritizing contractors with verified supply chain transparency.
Cloud providers are consolidating vendor relationships from fragmented mechanical-electrical contractor pools toward integrated design-build partnerships. Single-source accountability compresses interface risk between shell construction and precision cooling commissioning. This consolidation is most visible in Stavanger's energy corridor, where Equinor-legacy engineering firms dominate turnkey procurement.
Norway Data Center Construction Market Segmentation
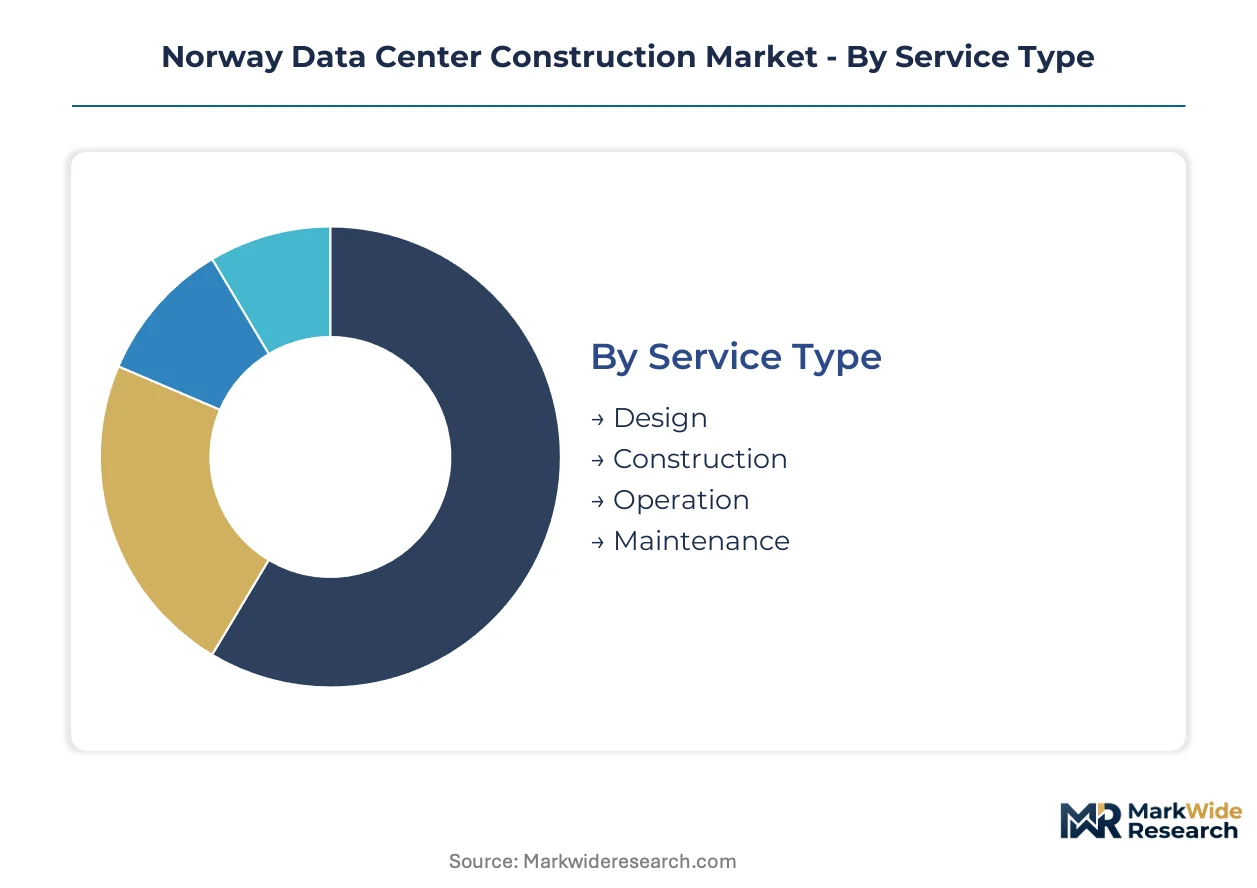
Segmentation in Norway's data center construction market reveals how distinct procurement patterns, technical specifications, and regulatory requirements fragment demand across service tiers and facility scales. Each segment carries unique margin profiles and capital intensity thresholds that shape contractor specialization.
Service Type:
Integration depth varies sharply across the service stack, with design and construction commanding standalone procurement while operation and maintenance embed within long-term facility management contracts.
- Design:Architectural and engineering specifications for power density exceeding 15 kW per rack and precision cooling within 1-2 degrees Celsius tolerance. Oslo and the broader Viken region concentrate design demand as hyperscale cloud providers expand their Nordic footprint to leverage Norway's renewable energy surplus.
- Construction:Physical assembly of mission-critical facilities housing servers, storage systems, and network equipment. Stavanger's energy corridor attracts integrated design-build partnerships where Equinor-legacy engineering firms dominate turnkey procurement.
- Operation:Ongoing facility management and uptime assurance.
- Maintenance:Preventive and corrective servicing of mechanical-electrical systems.
Construction leads volumes today; design is gaining share fastest as cloud providers consolidate vendor relationships toward single-source accountability.
Capacity:
Cost tier stratification separates boutique deployments from hyperscale campuses, with investment intensity per square meter peaking at enterprise level while medium-scale builds represent the broadest pipeline volume.
- Small Scale:Facilities under 1 MW of critical IT load serving edge computing and regional enterprise needs.
- Medium Scale:1-10 MW deployments attracting regional cloud providers expanding across the Nordic corridor. Telemark and Rjukan regions leverage deep reservoir cooling access to attract these power-intensive computing workloads.
- Large Scale:10-50 MW campuses requiring custom power and cooling architectures. Zoning restrictions around the capital region limit contiguous parcels suitable for these developments in Viken.
- Enterprise Level:Custom-built facilities exceeding 50 MW with the highest investment intensity per square meter. DNV fire safety certification timelines extend validation of gas suppression and structural resilience protocols, delaying revenue-ready dates for these mission-critical builds.
Medium-scale facilities lead volumes today; enterprise-level projects are climbing the fastest as AI training clusters drive rack densities beyond 50 kW.
Construction Type:
Application urgency determines methodology selection, with hyperscale operators prioritizing speed-to-market while sovereign data residency rules sustain demand for permanent infrastructure.
- Modular:Factory-tested power and cooling skids enabling hyperscale tenants to commission capacity in 6-month increments rather than traditional 24-month build cycles. CTS Nordics specializes in these deployment architectures that compress commissioning timelines for cloud providers entering the Nordic corridor.
- Traditional:Stick-built construction with extended on-site assembly timelines.
- Hybrid:Combinations of pre-fabricated and site-built elements balancing speed with customization.
- Greenfield:Custom developments on undeveloped land capturing premium margins due to bespoke power and cooling architectures. Green Mountain sustains its competitive edge through hydroelectric-powered greenfield facilities in Telemark and Rjukan.
Greenfield projects lead volumes today; modular approaches are expanding most quickly as hyperscale operators seek repeatable, factory-tested deployment cycles.
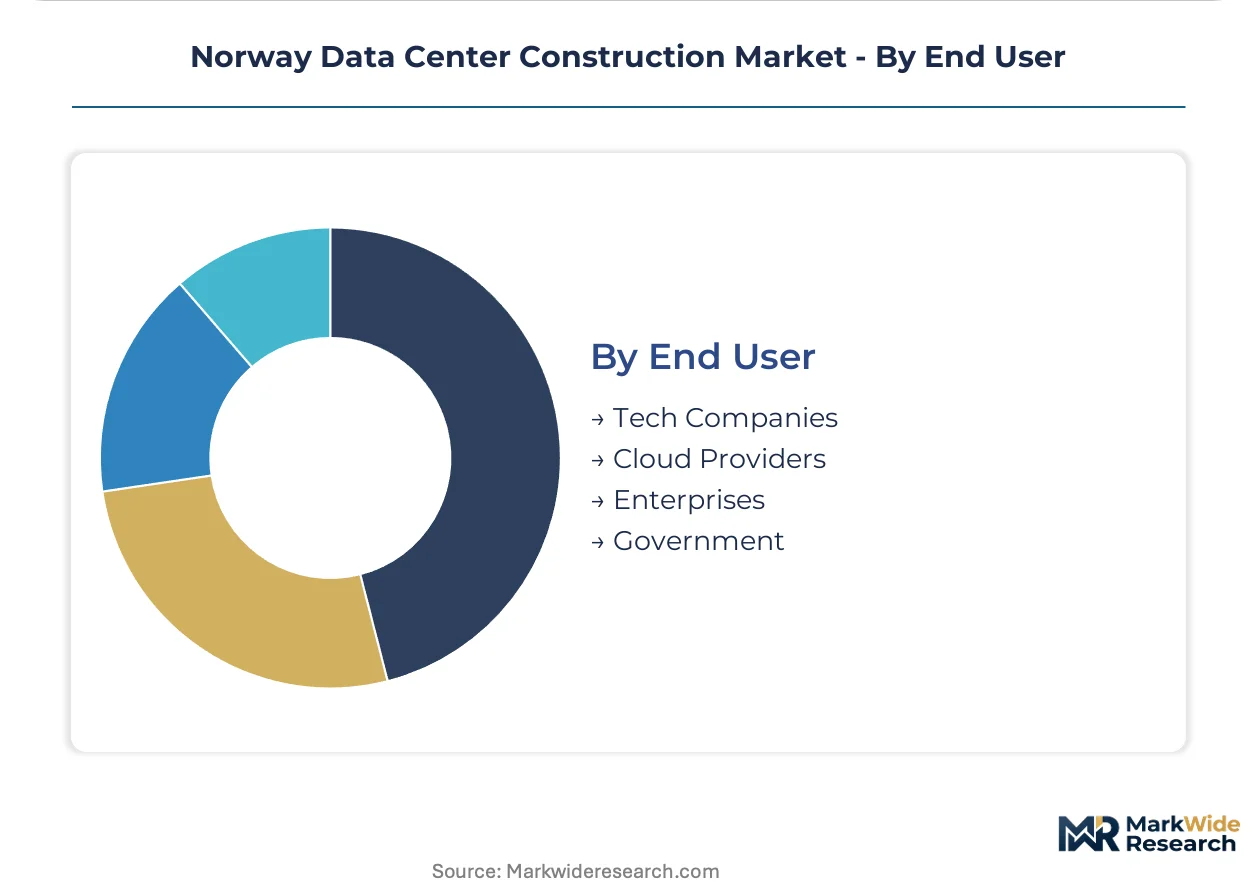
End User:
Customer type fragmentation reflects divergent uptime requirements, with cloud providers driving standardization while government mandates sustain bespoke security specifications.
- Tech Companies:Proprietary facility builds for internal platform infrastructure.
- Cloud Providers:Multi-tenant capacity serving distributed computing workloads. Bulk Infrastructure leverages deep-water cooling access and renewable power contracts to anchor large-scale developments near Stavanger for this segment.
- Enterprises:Colocation and dedicated builds supporting core IT operations. Norway's adoption of EU CSRD disclosure rules forces construction firms to document embodied carbon for enterprise tenants prioritizing supply chain transparency.
- Government:Sovereign facilities subject to data residency and security classifications. Stakeholders must weigh these rules against the capital efficiency of standardized modular designs as European data localization pressures intensify.
Cloud providers lead volumes today; government demand is gaining share fastest as data sovereignty regulations tighten across the European Economic Area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center construction in Norway traces its modern lineage to hydroelectric infrastructure built during the post-war industrialization era, when state-owned power development created surplus renewable capacity that now attracts compute-intensive workloads from international cloud platforms.
Oslo and Viken Region
Hyperscale cloud providers concentrate new capacity announcements in this corridor, drawn by dense fiber connectivity and proximity to European financial networks. The Norwegian Water Resources and Energy Directorate regulates grid interconnection standards, with processing queues extending energization timelines for large-scale builds. Zoning restrictions around the capital limit contiguous parcels suitable for 50+ MW campus developments, pushing some projects toward peripheral municipalities.
Stavanger and Rogaland
Coastal facilities deploy fjord-based thermal exchange systems that slash mechanical cooling energy intensity below conventional air-cooled designs. Bulk Infrastructure anchors large-scale developments here through deep-water cooling access and renewable power contracts. Equinor-legacy engineering firms dominate turnkey procurement in this energy corridor, consolidating vendor relationships from fragmented mechanical-electrical contractor pools.
Telemark and Rjukan
Deep reservoir cooling access attracts power-intensive computing workloads from AI training clusters seeking natural thermal management. Green Mountain sustains competitive positioning through hydroelectric-powered facilities in this region. Enova SF channels capital toward developments demonstrating substantial efficiency gains, offsetting premium costs for liquid cooling and waste heat recovery systems.
Troms and Finnmark
Northern latitudes offer natural cooling advantages and stranded renewable capacity that remains untapped by current development pipelines. Tromsø's academic and research computing infrastructure provides anchor demand for edge facilities. The region's distance from continental European fiber routes constrains hyperscale interest despite favorable power economics.
Trøndelag
Trondheim's technology cluster generates enterprise colocation demand from maritime and subsea engineering sectors. DNV standards for structural resilience and fire safety shape facility certification requirements across this central region. Modular deployment architectures from specialized contractors compress commissioning timelines for regional cloud providers expanding across the Nordic corridor.
Norway Data Center Construction Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the design-build integration spectrum, with single-source accountability compressing interface risk between shell construction and precision cooling commissioning. The vendor base stratifies into three tiers: integrated engineering firms with legacy energy sector expertise, modular specialists delivering factory-tested deployment cycles, and regional contractors competing on localized permitting speed. Consolidation pressure favors design-build partnerships over fragmented mechanical-electrical procurement. Geographic expansion into northern latitudes and portfolio diversification toward liquid-cooled AI-ready facilities represent the dominant competitive moves.
Within the integrated engineering tier, Skanska AB and COWI A/S exemplify Nordic construction conglomerates that have adapted energy sector project delivery models to mission-critical facility standards. CTS Nordics occupies a specialist position in modular deployment architectures that compress commissioning timelines for cloud providers entering the Nordic corridor. Green Mountain and Bulk Infrastructure represent developer-operators that have vertically integrated construction capabilities to secure renewable power contracting advantages and cooling infrastructure control. These named entities anchor the competitive structure without exhausting the participant pool.
| Leading Market Players |
|---|
| CTS Nordics |
| Bulk Infrastructure |
| Skanska AB |
| Stack Infrastructure |
| Green Mountain |
| Coromatic AB |
| Rider Levett Bucknall |
| AQ Compute |
| COWI A/S |
| Others |
Pricing and Supply Chain Analysis
Sovereign wealth-backed infrastructure specialists anchor Norway's data center construction pipeline, compressing contractor margins through consolidated procurement power while channeling state capital efficiency requirements into premium-tier pricing for certified green builds. Enova SF's grant disbursements create a bifurcated market where efficiency-validated developments command rate premiums unavailable to conventional stick-built competitors.
Pricing Analysis
Fixed-price EPC contracts with inflation-adjustment clauses dominate large-scale procurement, separating greenfield campus developments with bespoke liquid-cooling architectures from modular deployments with factory-standardized specifications. Price differentiation rests on DNV certification tier and waste-heat recovery integration, with enterprise colocation tenants absorbing premiums for documented embodied carbon transparency. Cost compression in copper-intensive electrical infrastructure is intensifying because switchgear and transformer lead times stretch procurement cycles. Regional cloud providers exhibit highest price sensitivity, while hyperscale operators prioritize speed-to-market over unit cost optimization.
Supply Chain Analysis
Norway's EU alignment on domestic-content thresholds for structural steel and concrete is reshaping sourcing patterns for mission-critical facilities. Manufacturing concentration for precision cooling equipment draws from Germany, Sweden, and Denmark, while high-voltage electrical components hinge on supply from Switzerland and Austria. Single-source vulnerability in 132kV+ substation design expertise forces reliance on imported contractor teams. Distribution runs through integrated design-build partnerships consolidating fragmented mechanical-electrical procurement into single-source accountability structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
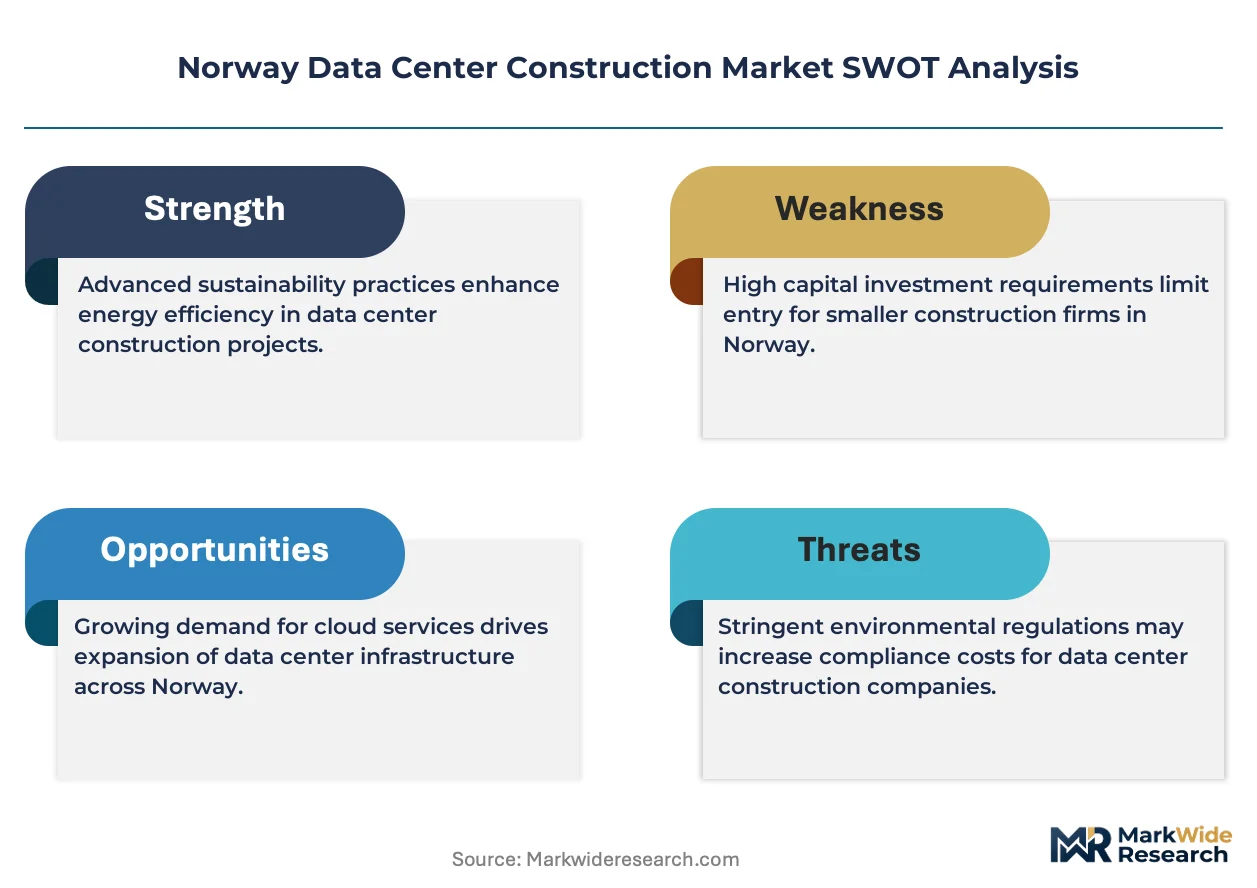
Norway's data center construction market reads as a late-cycle quality story where rack density specifications above 50kW for AI training clusters are filtering contractor viability toward liquid-cooling competency.
For Market Incumbents: Deploy backward integration into captive renewable power contracting to secure interconnection priority through the Norwegian Water Resources and Energy Directorate. Skanska AB and COWI A/S should deepen fjord-cooling engineering partnerships to defend against modular specialists compressing commissioning timelines. DNV fire safety certification capabilities represent a defendable moat as validation timelines extend revenue-ready dates. For New Entrants and Emerging Players: The 40-60% price-point spread between premium liquid-cooled enterprise facilities and air-cooled medium-scale builds opens white-space in Troms and Finnmark's stranded renewable corridor. Northern latitude natural cooling advantages remain underdeveloped by current pipelines. Target academic and research computing anchor demand in Tromsø with modular edge configurations before hyperscale interest materializes. For Investors and Strategic Acquirers: Valuations sit cheapest among regional contractors with localized permitting speed but without integrated design-build capabilities. Long-term viability over the coming decade rests on liquid-cooling infrastructure control and heat-export contract monetization. Watch Enova SF grant allocation velocity as the inflection signal for state-backed project finance availability.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Direct-to-chip systems from CTS Nordics enable 50kW+ rack densities for AI training clusters. |
| Fjord Thermal Exchange Partnership | Bulk Infrastructure's Stavanger deep-water access slashes mechanical cooling energy intensity below air-cooled benchmarks. |
| Modular Factory-Tested Skid Integration | CTS Nordics compresses hyperscale commissioning from 24-month cycles to 6-month increments. |
| Waste Heat Recovery System Installation | Telemark facilities convert thermal output into district heating revenue through municipal network contracts. |
| DNV Structural Resilience Certification | Gas suppression and fire safety validation extends facility approval timelines but secures premium tenant pricing. |
Research Methodology
Direct dialogue with data center developers, EPC contractors, and grid interconnection planners anchored qualitative grounding, supplemented by secondary validation against Enova SF grant disbursement records and the Norwegian Water Resources and Energy Directorate connection queue data. Bottom-up project pipeline tracking triangulated with top-down capital expenditure modeling from hyperscaler Nordic expansion disclosures. SEC filings from Stack Infrastructure and AQ Compute parent entities, alongside EU CSRD implementation guidance from the European Commission, provided demand-side calibration.
Segment-level capacity and investment intensity outputs emerged from modeling across service type, construction methodology, facility scale tier, and end-user category throughout the projection horizon. CAGRs derived from build-rate assumptions tied to grid interconnection approval velocity and liquid-cooling adoption curves in AI training environments. Copper and electrical steel price volatility indices, plus DNV certification timeline distributions, fed scenario-weighted forecast ranges.
Caveats apply where grid interconnection queue extensions or copper commodity spikes could materially shift the outlook for fixed-price EPC contract viability. Forecasts reflect documented assumptions on hyperscale commitment continuity to Nordic renewable corridors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Managed IT Infrastructure Services Market
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market