
 Data Center Asset Management Market | 2026-2036
Data Center Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Asset Management Market Analysis
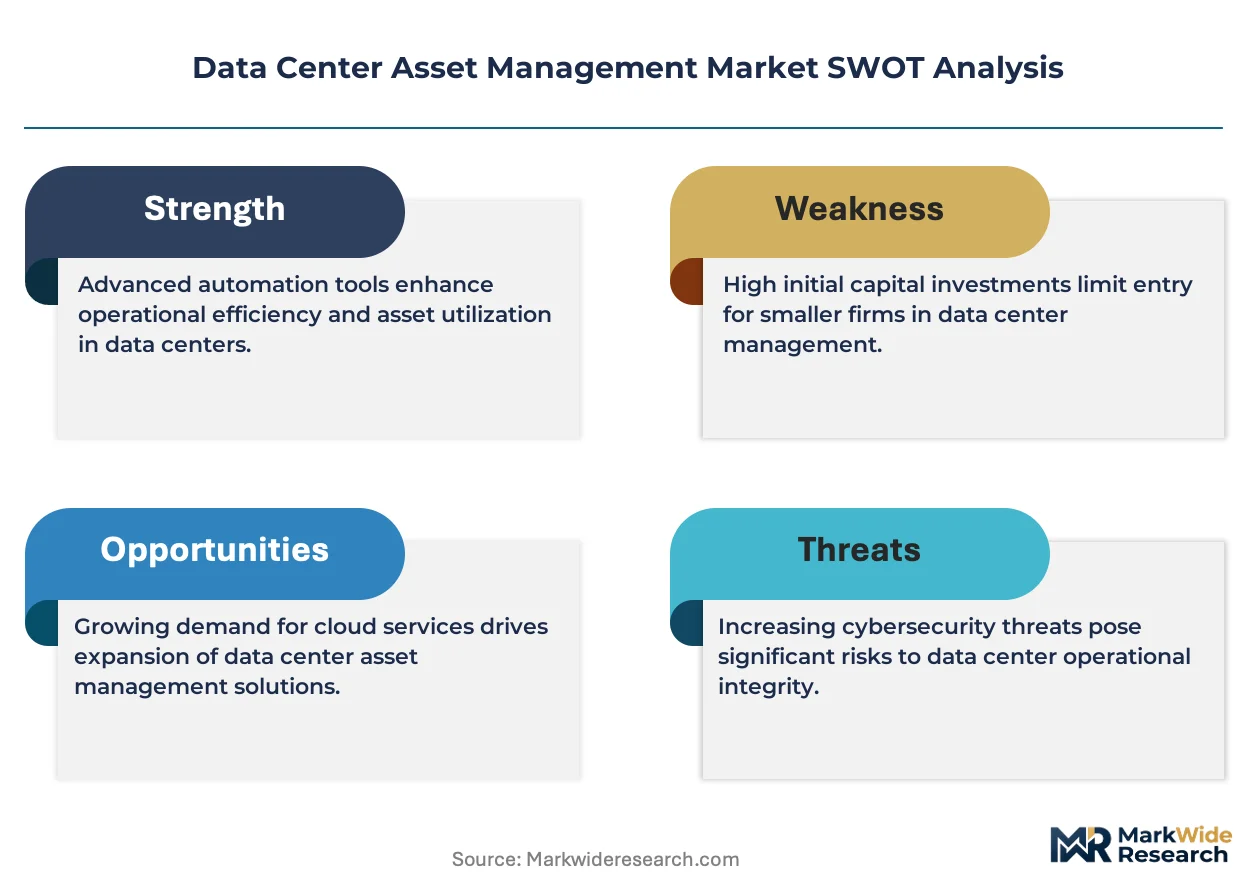
Buyer concentration among hyperscale cloud operators and large colocation providers is pivoting procurement power toward entities managing millions of assets across distributed geographies. Schneider Electric SE leverages its integrated power and software stack to anchor long-term service contracts with these consolidated buyers. Vertiv Holdings Co. competes through thermal and power infrastructure expertise that extends into lifecycle asset monitoring. IBM Corporation differentiates via AI-infused predictive maintenance modules embedded within broader IT service agreements.
Data center asset management encompasses the systematic tracking, monitoring, and optimization of physical infrastructure components—including servers, storage arrays, network switches, power distribution units, and cooling systems—through integrated hardware sensors and software platforms that maintain real-time visibility into location, condition, utilization rates, and maintenance status. Its primary commercial purpose is to eliminate stranded capacity, prevent unplanned downtime, and extend equipment useful life while ensuring compliance with energy and environmental commitments. Software and cloud-based deployment segments are capturing the fastest expansion as operators abandon spreadsheet-based inventory methods in favor of API-connected platforms that synchronize with IT service management workflows. Hardware sensors and on-premises installations retain dominance in regulated government and financial end-user settings where data sovereignty requirements restrict off-premise telemetry transmission.
The U.S. Environmental Protection Agency's ENERGY STAR certification for data centers and the European Union's Energy Efficiency Directive establish mandatory benchmarking and disclosure thresholds that directly shape asset instrumentation requirements and platform procurement decisions. Compliance with ISO 50001 energy management standards and the EU Corporate Sustainability Reporting Directive further tightens audit trails for infrastructure lifecycle data. Stakeholders must evaluate whether their current asset visibility depth satisfies emerging carbon accounting verification demands before regulators finalize enforcement protocols.
Market Dynamics
Hyperscale cloud operators consolidating procurement power around multi-site asset visibility platforms is compressing vendor margins while elevating API-first software architectures over legacy inventory systems.
Growth Catalysts
- EU Energy Efficiency Directive:The directive mandates granular power and cooling instrumentation across data center footprints, forcing operators to deploy sensor networks and telemetry platforms that feed automated asset optimization engines.
- AI inference clusters:GPU-heavy machine learning deployments in Northern Virginia and Dallas-Fort Worth are generating acute demand for real-time thermal and power monitoring to prevent stranded capacity in high-density racks.
- Carbon disclosure mandates:Emerging requirements in Germany and France are pressuring operators to instrument lifecycle data for audit-ready sustainability reporting, directly driving asset management platform procurement.
Market Restraints
- Sensor hardware cost volatility:Semiconductor input costs for power monitoring chips and wireless telemetry modules create margin pressure on integrated platform providers.
- Data sovereignty restrictions:Government and financial end-users in regulated jurisdictions block off-premise telemetry transmission, fragmenting cloud deployment growth.
- Legacy DCIM lock-in:Existing on-premises data center infrastructure management installations create switching friction that slows platform replacement cycles.
Strategic Opportunities
- Edge computing nodes:Distributed micro-data centers in secondary US metros lack systematic asset tracking, creating white space for lightweight SaaS platforms with simplified deployment.
- ISO 50001 convergence:Energy management certification requirements are opening integrated consulting and software bundles that combine audit preparation with continuous monitoring.
- Predictive maintenance AI:Machine learning modules trained on thermal and vibration sensor data are penetrating colocation provider contracts as value-added differentiators.
Industry Challenges
- OT-IT integration complexity:Bridging operational technology sensor networks with enterprise IT service management workflows demands scarce hybrid engineering talent.
- Multi-vendor protocol fragmentation:Inconsistent API standards across power, cooling, and server hardware vendors complicate unified platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Asset Management Market |
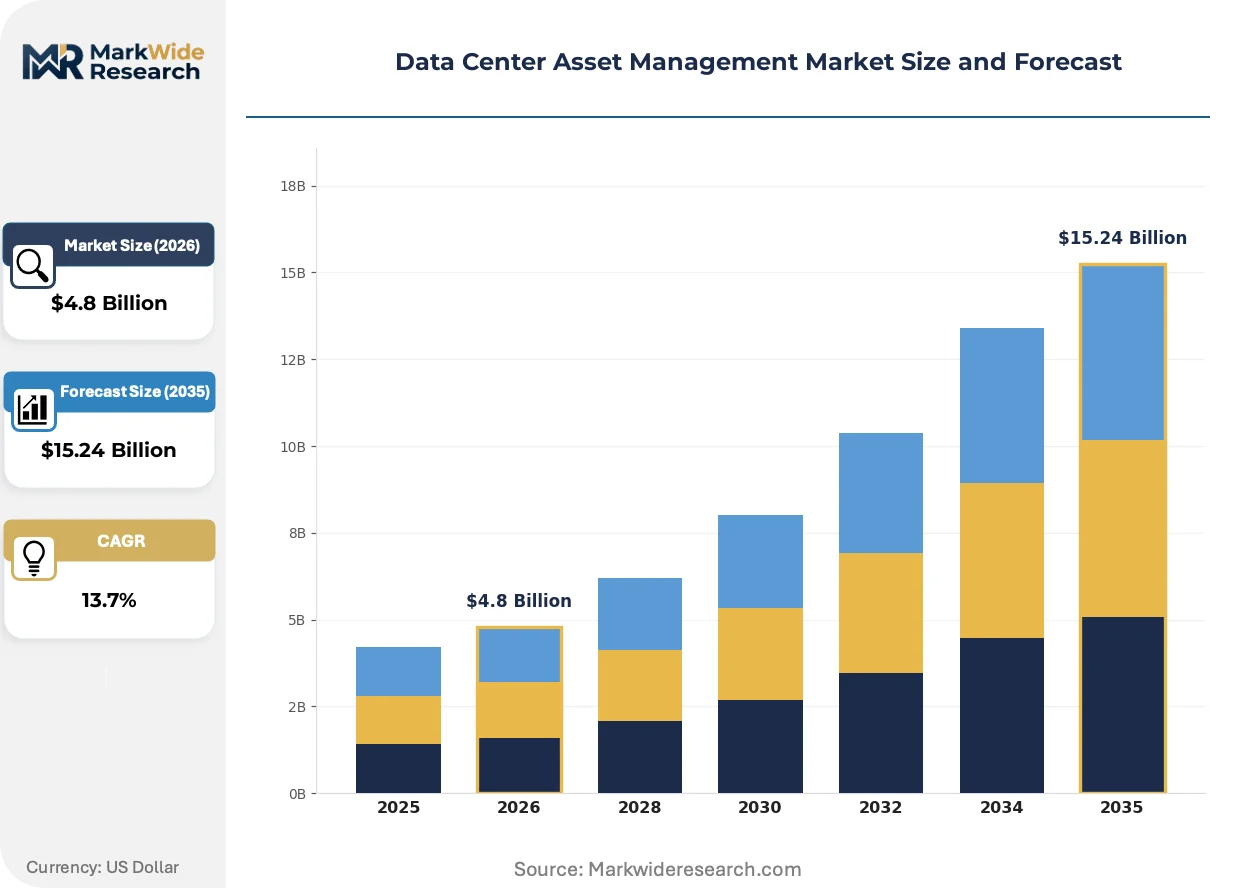
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Service, Consultation Deployment: On-Premises, Cloud-Based, Hybrid, Hosted End User: Enterprise, Colocation Providers, Managed Service Providers, Government Application: Capacity Planning, Asset Tracking, Energy Management, Inventory Management |
| Companies Covered | Schneider Electric SE, Vertiv Holdings Co., IBM Corporation, Dell Technologies Inc., Cisco Systems Inc., Hewlett Packard Enterprise Company, Eaton Corporation plc, Microsoft Corporation, Nlyte Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Asset Management Market Emerging Trajectories
Digital twin modeling is migrating from pilot programs to production deployment as operators seek to simulate thermal and power scenarios before physical infrastructure changes.
Digital twin software is expanding into live synchronization with building management systems and power distribution networks. Hyperscale operators in Northern Virginia are deploying these platforms across multi-building campuses to model airflow and rack density before capital deployment. The technology is expanding into procurement workflows by compressing physical commissioning timelines and reducing overprovisioning margins.
The EU Corporate Sustainability Reporting Directive tightens audit trail requirements for infrastructure lifecycle data. Operators must now maintain granular records of equipment installation dates, efficiency ratings, and decommissioning pathways for carbon accounting verification. Colocation providers in Frankfurt and Amsterdam are responding by embedding asset management platforms directly into customer billing and reporting portals.
Buying committees are consolidating vendor selection around platforms that synchronize asset data with IT service management ticketing systems. Enterprise IT procurement teams are displacing facilities-led purchasing processes that historically separated infrastructure monitoring from application lifecycle management. This behavioral shift is most visible in financial services verticals where CIO and CFO alignment on total cost of ownership metrics drives platform consolidation decisions.
Data Center Asset Management Market Segmentation
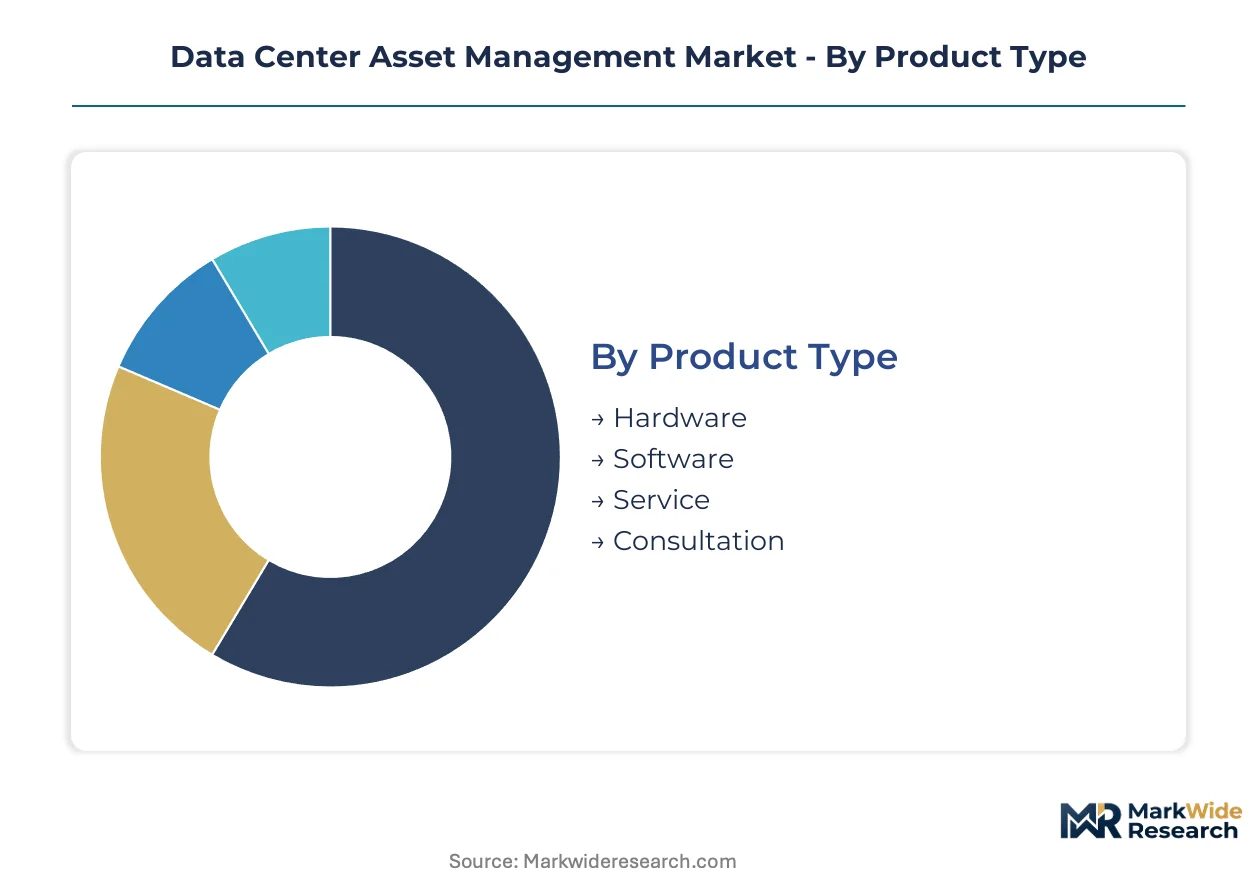
Segmentation in data center asset management reveals how procurement priorities diverge across infrastructure maturity levels and regulatory exposure. Buyers select product and deployment configurations based on whether their primary burden is carbon audit compliance, uptime assurance, or cost optimization.
Product Type:
ISO 50001 certification requirements and EU Energy Efficiency Directive mandates impose distinct instrumentation burdens across product categories, with hardware sensors carrying the heaviest audit trail obligations.
- Hardware:Power monitoring chips, wireless telemetry modules, and environmental sensors form the physical instrumentation layer. Hyperscale operators in Northern Virginia and Dallas-Fort Worth deploy these at rack-level density to feed real-time optimization engines for GPU-heavy AI clusters.
- Software:API-connected platforms replace spreadsheet inventory with automated discovery, CMDB synchronization, and predictive analytics. Colocation providers in Frankfurt embed these directly into customer billing portals to satisfy CSRD lifecycle data requirements.
- Service:Managed platform operations and remote monitoring subscriptions reduce in-house OT-IT integration burdens.
- Consultation:ISO 50001 audit preparation and carbon accounting advisory bundled with continuous monitoring deployments.
Hardware sits at the top of the volume ranking, with Software climbing the fastest.
Deployment:
Cost tier separation between capital-intensive on-premises installations and operational expenditure cloud models shapes buyer selection across end-user sophistication levels.
- On-Premises:Dedicated server installations with local data retention for regulated government and financial end-users. German and French operators facing strict data sovereignty requirements block off-premise telemetry transmission entirely.
- Cloud-Based:SaaS platforms with API connectivity to IT service management workflows. Enterprise buyers abandon legacy DCIM systems for these subscription models that synchronize asset data with ticketing systems.
- Hybrid:Split architectures keeping sensitive power telemetry on-site while pushing analytics to cloud tiers.
- Hosted:Single-tenant managed deployments in third-party facilities reducing internal infrastructure overhead.
On-Premises retains the largest installed base, though Cloud-Based deployments are expanding most quickly.
End User:
Customer type determines whether procurement centers on multi-site standardization or single-facility compliance depth.
- Enterprise:Internal IT and facilities teams managing owned data center footprints. CIO-CFO alignment on total cost of ownership metrics drives platform consolidation decisions in financial services verticals.
- Colocation Providers:Multi-tenant operators instrumenting shared infrastructure for per-customer billing and reporting. Amsterdam and Frankfurt providers embed asset visibility into customer portals to satisfy carbon disclosure mandates.
- Managed Service Providers:Third-party operators delivering monitoring-as-a-service to mid-market clients lacking internal OT-IT expertise.
- Government:Federal and state agencies with strict data sovereignty and security classification requirements.
Enterprise commands the greatest procurement volume, with Colocation Providers gaining share fastest.
Application:
Functional use case maturity separates legacy inventory tracking from AI-enabled predictive capabilities.
- Capacity Planning:Digital twin modeling and scenario simulation before physical infrastructure deployment. Northern Virginia hyperscale campuses use these tools to compress commissioning timelines and reduce overprovisioning margins.
- Asset Tracking:Real-time location and condition monitoring of servers, storage, and network equipment. RFID and sensor networks eliminate stranded capacity in high-density racks.
- Energy Management:Granular power and cooling instrumentation feeding automated optimization engines. EU Energy Efficiency Directive mandates directly force adoption across member state operators.
- Inventory Management:Lifecycle records for installation dates, efficiency ratings, and decommissioning pathways. CSRD audit trail requirements tighten record-keeping standards for carbon accounting verification.
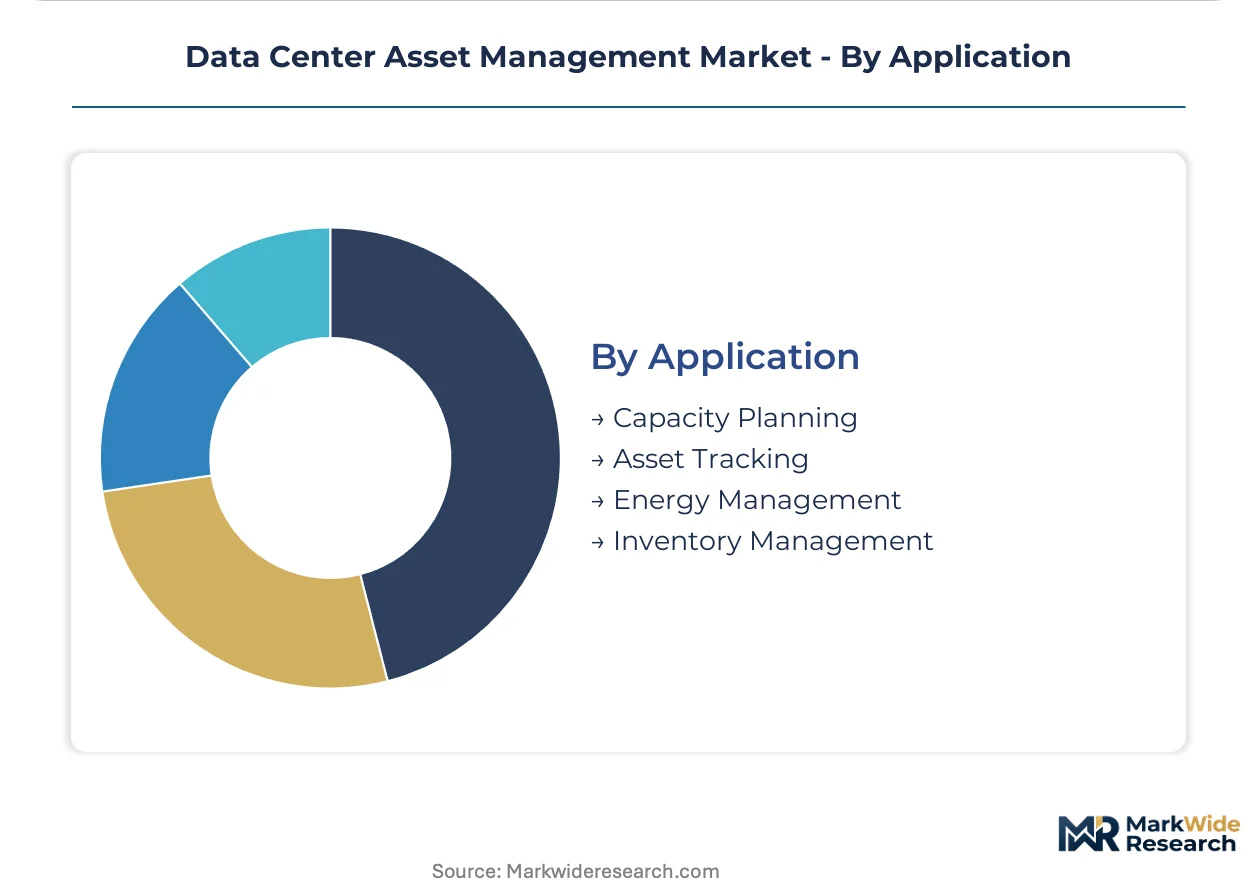
Asset Tracking holds the top volume position, while Energy Management is climbing fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's carbon disclosure mandates are tightening audit requirements faster than France's phased implementation, while both trail the United States in hyperscale deployment velocity. Procurement patterns diverge sharply between EU regulatory compliance markets and North American capacity expansion markets.
United States
GPU-heavy AI inference clusters in Northern Virginia and Dallas-Fort Worth are driving rack-level thermal instrumentation demand. The EPA's ENERGY STAR certification for data centers mandates benchmarking thresholds that shape platform procurement. Virginia's Loudoun County data center corridor hosts the densest concentration of hyperscale asset management deployments globally.
Germany
The national implementation of EU Energy Efficiency Directive requirements is forcing granular power monitoring across Frankfurt and Berlin metro facilities. The Federal Environment Agency enforces carbon disclosure protocols that exceed baseline EU Corporate Sustainability Reporting Directive standards. Frankfurt's banking sector colocation providers are embedding asset visibility into customer portals to satisfy audit-ready sustainability reporting.
France
Datacenter operators in Île-de-France face emerging lifecycle data instrumentation mandates under national carbon accounting regulations. The national energy regulator applies efficiency disclosure requirements that pressure legacy DCIM replacement cycles. Paris-region hyperscale campuses are deploying digital twin modeling to compress physical commissioning timelines before capital deployment.
United Kingdom
Financial services verticals in London are consolidating CIO-CFO procurement alignment around total cost of ownership metrics. The national energy efficiency framework imposes benchmarking obligations on large data center operators. Slough and Docklands data center clusters are standardizing API-first asset platforms that synchronize with IT service management ticketing systems.
Netherlands
Amsterdam's colocation providers are integrating asset management platforms into customer billing portals to satisfy EU Corporate Sustainability Reporting Directive audit trails. The national environmental agency enforces strict data sovereignty requirements that favor on-premises telemetry retention. The Amsterdam Science Park data center cluster is piloting live digital twin synchronization with building management systems.
Data Center Asset Management Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated power infrastructure providers, AI-enabled predictive maintenance platforms, and lightweight SaaS specialists. Consolidation pressure from hyperscale procurement is elevating API-first architectures over legacy inventory systems. Dominant competitive moves include strategic partnerships with IT service management vendors and geographic expansion into edge computing node markets.
Within the integrated infrastructure tier, Schneider Electric SE and Vertiv Holdings Co. exemplify diversified conglomerates that anchor long-term service contracts through combined hardware-software stacks. IBM Corporation occupies a distinct position among AI-infused predictive maintenance providers, embedding machine learning modules within broader IT service agreements. These three companies represent the dominant competitive archetypes: power-thermal integration, AI-enabled lifecycle management, and enterprise service bundling.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Holdings Co. |
| IBM Corporation |
| Dell Technologies Inc. |
| Cisco Systems Inc. |
| Hewlett Packard Enterprise Company |
| Eaton Corporation plc |
| Microsoft Corporation |
| Nlyte Software |
| Others |
Supply Flow & Price Mechanics
Copper and rare-earth price indices on the London Metal Exchange cascade through sensor manufacturing tiers into three distinct pricing levels for data center asset management platforms. Procurement teams at hyperscale operators in Northern Virginia negotiate volume-based SaaS subscriptions that compress per-unit hardware costs, while German colocation providers absorb premium instrumentation expenses to satisfy Federal Environment Agency audit requirements.
Pricing Analysis
Capacity additions in Malaysia and Vietnam are reshaping price floors for wireless telemetry modules and power monitoring chips. Three-tier pricing structure across premium API-first platforms, standard DCIM integrations, and economy sensor-only deployments dominates procurement. ISO 50001 certification tier and volume scale differentiate price bands most sharply. Cost compression in the economy tier is intensifying because semiconductor foundries are expanding output. Mid-market colocation providers in secondary US metros exhibit the highest price sensitivity, whereas hyperscale cloud operators in Northern Virginia prioritize integration depth over unit cost.
Supply Chain Analysis
Freight cost volatility on Asia-North America routes is elevating landed costs for Taiwanese power monitoring semiconductors and Chinese environmental sensors. Manufacturing concentrates in Taiwan, China, and South Korea for telemetry chips; Mexico and Germany for rack-level power distribution hardware. Raw material dependencies include copper for busbars, neodymium for sensor magnets, and silicon carbide for power monitoring circuits. Single-source vulnerability around Taiwanese semiconductor foundries poses the dominant structural risk. Distribution runs through direct OEM channels to hyperscale operators, with regional system integrators serving mid-market colocation providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU regulatory compliance costs in Germany and France run substantially above US capacity expansion economics, creating divergent vendor margin structures across Atlantic versus European procurement.
For Market Incumbents: Deepen API-first platform architectures to defend against lightweight SaaS entrants targeting edge computing nodes. Anchor long-term service contracts through integrated power-software stacks that embed predictive maintenance modules. The threat of OT-IT integration complexity creates switching friction that favors incumbents with hybrid engineering depth. Certification investment in ISO 50001 audit preparation capabilities locks in German banking sector colocation providers. For New Entrants and Emerging Players: EU Energy Efficiency Directive in Germany opens a window for lightweight SaaS platforms with rapid deployment cycles targeting secondary metro edge nodes. The most penetrable segment is distributed micro-data centers in US secondary metros lacking systematic asset tracking. A go-to-market angle through managed service providers reduces direct OT-IT integration burdens on mid-market clients. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-enabled predictive maintenance specialists possessing trained thermal and vibration sensor datasets. Long-term viability hinges on platform consolidation into IT service management workflows rather than standalone DCIM replacement. Acquisition target archetype: pure-play digital twin software vendors with live building management system synchronization. The signal to watch is CIO-CFO procurement committee consolidation around total cost of ownership metrics in financial services verticals.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Schneider Electric and Vertiv anchor hyperscale contracts through synchronized IT service management workflows. |
| Predictive Maintenance AI Development | IBM embeds machine learning modules trained on Northern Virginia thermal sensor data into enterprise service agreements. |
| Digital Twin Synchronization | Amsterdam Science Park pilots live building management system integration to compress commissioning timelines. |
| Edge Computing Node Expansion | Lightweight SaaS vendors target Dallas-Fort Worth secondary metros lacking rack-level instrumentation. |
| ISO 50001 Consulting Bundles | Frankfurt colocation providers embed audit preparation into customer portals to satisfy Federal Environment Agency requirements. |
Methodological Framework
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with data center facilities directors, IT procurement officers, colocation provider operations heads, and OT-IT integration engineers. Secondary validation draws from EPA ENERGY STAR certification databases, EU Energy Efficiency Directive implementation reports, SEC filings from publicly traded infrastructure vendors, and hyperscaler capital expenditure disclosures. Bottom-up sensor shipment tracking and top-down platform revenue triangulation anchor market size estimation.
Rate-of-change decomposition separates hardware sensor volume trends from software subscription value expansion across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, end-user category, and application function, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from installed base growth rates multiplied by average revenue per unit trajectories, calibrated against GPU cluster deployment densities in Northern Virginia and carbon disclosure mandate enforcement timelines in Germany.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EU Corporate Sustainability Reporting Directive enforcement or sustained semiconductor input cost volatility. Forecasts reflect documented assumptions about hyperscale procurement consolidation velocity and edge computing node deployment rates. A model refresh is warranted upon material change in EPA ENERGY STAR certification threshold adjustments or Federal Environment Agency carbon accounting protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Chennai Data Center Market
Data Center Infrastructure
Hong Kong Data Center Construction Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
Israel Data Center Rack Market