
 Global Mega Data Center Market | 2026-2036
Global Mega Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mega Data Center Market Foresight
Copper busbar infrastructure is hardening as the dominant power distribution architecture inside mega data centers, displacing traditional cable trays to reduce energy loss at scale. Amazon Web Services leverages custom silicon and proprietary cooling designs to sustain margin advantages in hyperscale builds. Microsoft Azure anchors its expansion strategy around liquid-cooled AI training clusters across multiple continents. Google Cloud differentiates through renewable energy matching and advanced thermal management patents.
A mega data center is a facility exceeding 15 megawatts of critical IT power capacity, typically housed in purpose-built structures with modular power and cooling architectures designed for continuous operation at 99.999% uptime. These installations integrate thousands of server racks, redundant substations, and direct liquid cooling loops to support high-density compute workloads for cloud services and artificial intelligence training. Hyperscale deployment dominates capital allocation as cloud service providers self-build rather than lease capacity. Liquid cooling technology is capturing the fastest expansion trajectory as processor thermal design power exceeds 500 watts per socket. Enterprise data centers within the end-user category face structural pressure to outsource or retrofit as efficiency standards tighten.
The EPA Energy Star program and OSHA electrical safety standards govern facility certification and worker protection in the United States, while the EU Green Deal and F-Gas Regulation restrict refrigerant choices and mandate carbon disclosure for European builds. China's MIIT enforces GB standards for data center power usage effectiveness, creating compliance barriers for foreign operators seeking market access. Stakeholders must monitor evolving cooling technology roadmaps and regulatory thresholds for renewable energy procurement to preserve buildout timelines and capital efficiency.
Market Dynamics
Processor thermal design power exceeding 500 watts per socket is forcing hyperscale operators to abandon air-cooled architectures entirely. This thermal ceiling is compressing facility design cycles and redistributing capital toward liquid cooling infrastructure.
Growth Catalysts
- AI Training Clusters:Cloud service providers are self-building capacity for foundation model training, eliminating the leasing intermediary and accelerating bare-metal deployment timelines.
- EU Green Deal Mandates:Carbon disclosure requirements and F-Gas refrigerant restrictions are retrofitting European facility standards, creating compliant-ready demand for next-generation thermal systems.
- Copper Busbar Architecture:Power distribution losses in traditional cable trays are driving adoption of solid conductor busway systems for megawatt-scale rack feeds.
Market Restraints
- Electrical Steel Supply:Transformer core material concentration in Asian smelters creates input cost volatility for on-site substation construction.
- GB Standards Compliance:China's MIIT power usage effectiveness thresholds impose technical barriers for foreign operators seeking domestic buildout permits.
- Liquid Cooling Integration:Retrofit incompatibility with legacy raised-floor air-cooled facilities limits brownfield expansion options for enterprise operators.
Strategic Opportunities
- German Industrial Corridor:Frankfurt and Berlin clusters offer proximity to renewable generation and EU regulatory alignment for AI training workloads.
- Direct Liquid Cooling Convergence:Immersion systems paired with waste heat recovery are opening district heating revenue streams for Nordic facilities.
- US IRA Clean Energy Credits:Investment tax credits for renewable-powered construction are improving project returns for domestic hyperscale builds.
Industry Challenges
- Thermal Engineering Talent:Scarcity of specialists fluent in both chip-level heat flux management and facility-scale hydronics is extending commissioning schedules.
- OSHA Electrical Certification:High-voltage busbar installation and live-work protocols require extended safety training programs that constrain workforce scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mega Data Center Market |
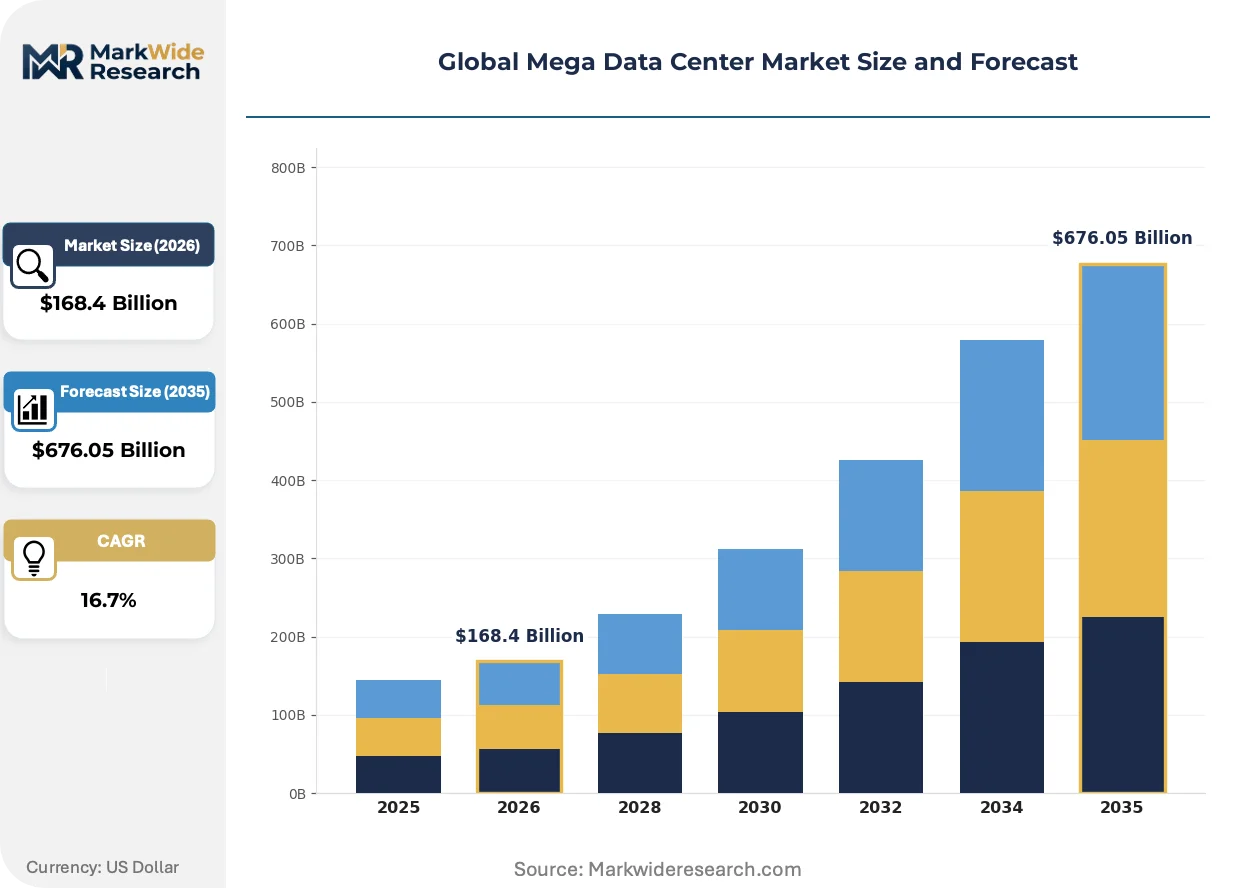
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $676.05 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Hyperscale, Colocation, Edge, Modular Technology: Liquid Cooling, Air Cooling, Immersion Cooling, Free Cooling Application: Cloud Computing, Content Delivery, Big Data Analytics, AI Training, High Performance Computing End User: Cloud Service Providers, Enterprise Data Centers, Telecommunications, Research Institutions |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Equinix, Digital Realty, IBM Corporation, Dell Technologies, Hewlett Packard Enterprise, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mega Data Center Market Shifts & Advancements
Facility architecture is bifurcating between air-cooled legacy estates and liquid-cooled purpose-built structures. This divergence is fragmenting supplier ecosystems and compressing technology refresh cycles.
Direct-to-chip liquid cooling is rewriting rack density economics. Hyperscale operators are deploying cold plates and coolant distribution units to support 100-kilowatt cabinets. This infrastructure is compressing data hall footprints and shifting capital from real estate expansion to precision thermal hardware.
The EU AI Act risk classification framework is reshaping facility certification requirements. High-risk AI training workloads face audit trails for energy sourcing and water usage. German and French operators are responding with real-time sustainability telemetry integration.
Build-to-suit procurement is displacing speculative colocation development. Cloud service providers are contracting directly with construction firms for bespoke facilities, eliminating the wholesale leasing layer. This pattern concentrates most visibly in Virginia's Northern Virginia cluster and Amsterdam's Schiphol corridor.
Global Mega Data Center Market Segmentation
Mega data center segmentation reveals how capital allocation, thermal engineering choices, and customer procurement patterns fragment the buildout landscape. Understanding these axes exposes where margin concentrates and where technology transitions create displacement risk.
Deployment:
Facility ownership models determine construction timelines, financing structures, and operational control depth.
- Hyperscale:Purpose-built facilities exceeding 15 megawatts with single-tenant design, redundant substations, and direct liquid cooling loops. Cloud service providers in the United States, China, and Germany are self-building exclusively for AI training clusters, compressing bare-metal deployment from 18 months to 12 months by eliminating leasing intermediaries.
- Colocation:Multi-tenant facilities with shared power and cooling infrastructure operated by third-party providers. Demand is concentrating in Amsterdam's Schiphol corridor and Virginia's Northern Virginia cluster where wholesale leasing still serves mid-scale cloud and enterprise customers unable to justify dedicated construction.
- Edge:Distributed sub-5-megawatt facilities positioned for latency-sensitive workloads. Telecom operators in Germany and Japan are deploying these for autonomous vehicle telemetry and industrial IoT aggregation.
- Modular:Prefabricated power and cooling units enabling rapid capacity scaling. Mining and remote AI inference deployments in Nordic countries favor these for speed-to-power advantages.
Mature deployment sits with Colocation. Newer deployment is concentrated in Hyperscale.
Technology:
Thermal management specifications now dominate facility design economics as processor heat density crosses critical thresholds.
- Liquid Cooling:Direct-to-chip cold plates and coolant distribution units handling 100-kilowatt cabinets. Cloud service providers across multiple continents are abandoning air-cooled architectures entirely as thermal design power exceeds 500 watts per socket, redistributing capital toward precision thermal hardware.
- Air Cooling:Traditional raised-floor perimeter CRAC units with underfloor air distribution. Legacy enterprise estates in the United States face retrofit incompatibility pressures as efficiency standards tighten under EPA Energy Star and OSHA electrical safety protocols.
- Immersion Cooling:Dielectric fluid submersion of entire server assemblies. Nordic facilities in Iceland and Norway are pairing these systems with district heating waste heat recovery, opening secondary revenue streams.
- Free Cooling:Economizer systems leveraging ambient air or water for cooling without mechanical refrigeration. Northern European builds exploit this for EU Green Deal compliance, avoiding F-Gas refrigerant restrictions entirely.
Established infrastructure relies on Air Cooling. The steepest expansion trajectory belongs to Liquid Cooling.
Application:
Workload characteristics dictate power density, network topology, and sustainability telemetry requirements.
- AI Training:Foundation model clusters requiring 99.999% uptime and direct liquid cooling for sustained GPU utilization. German and French operators under EU AI Act risk classification frameworks face audit trails for energy sourcing and water usage, driving real-time sustainability integration.
- Cloud Computing:General-purpose virtualized infrastructure serving variable enterprise workloads. This remains the volume base across all major buildout locations, though growth rates lag specialized AI infrastructure.
- Content Delivery:Caching and streaming optimization requiring geographic distribution rather than centralized density. Edge deployment patterns favor this application.
- Big Data Analytics:Batch processing clusters with less stringent latency requirements. Research institutions and financial services in the United States and China deploy these in secondary markets.
- High Performance Computing:Scientific simulation and modeling with intermittent supercomputing bursts. Government-funded research institutions dominate this segment with specialized procurement.
Volume concentration rests with Cloud Computing. Capital intensity peaks with AI Training.
End User:
Customer type determines facility specification, contract structure, and regulatory exposure.
- Cloud Service Providers:Hyperscale operators with captive engineering teams and proprietary silicon designs. AWS, Microsoft Azure, and Google Cloud are driving copper busbar adoption and custom cooling patents, eliminating wholesale leasing layers through build-to-suit procurement.
- Enterprise Data Centers:Corporate-owned facilities facing structural pressure to outsource or retrofit. Efficiency mandates under EPA Energy Star and EU Green Deal disclosure requirements are accelerating migration to colocation or cloud.
- Telecommunications:Carrier-neutral and operator-captive facilities for 5G core and edge aggregation. Germany's industrial corridor and Japan's METI-guided builds concentrate this demand.
- Research Institutions:Government and university supercomputing centers with specialized procurement cycles. China's MIIT GB standards and US Department of Energy funding shape this segment's technical requirements.
Procurement scale sits with Cloud Service Providers. Regulatory complexity concentrates with Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virginia's Data Center Investment Program anchors North American concentration through sales and use tax exemptions on qualifying equipment. This fiscal architecture redirects hyperscale capital toward Loudoun and Prince William counties.
United States
AI training clusters and cloud service provider self-builds dominate demand. The EPA Energy Star program and OSHA electrical safety standards govern facility certification and worker protection. Northern Virginia's Loudoun County hosts the densest concentration of hyperscale builds, with Amazon Web Services and Microsoft Azure compressing deployment timelines through direct construction contracting.
Germany
Foundation model training workloads and EU regulatory alignment attract cloud investment. The EU AI Act and EU Green Deal mandate carbon disclosure and F-Gas refrigerant restrictions. Frankfurt and Berlin clusters offer proximity to renewable generation, with operators integrating real-time sustainability telemetry for high-risk AI workload audit trails.
China
Domestic cloud expansion and AI infrastructure buildouts drive facility construction. MIIT enforces GB standards for power usage effectiveness, creating compliance barriers for foreign operators. Yangtze River Delta and Beijing-Tianjin-Hebei corridors concentrate state-backed hyperscale projects serving domestic cloud service providers.
Netherlands
Wholesale colocation demand and submarine cable landing points sustain market relevance. The EU Green Deal and national spatial planning restrictions limit greenfield expansion. Amsterdam's Schiphol corridor retains concentration for mid-scale cloud customers unable to justify dedicated hyperscale construction.
Iceland
Waste heat recovery economics and renewable baseload power attract Nordic builds. EEA alignment with EU Green Deal standards enables regulatory passporting. Reykjavik-based facilities pair immersion cooling with district heating revenue streams, opening secondary income from thermal export contracts.
Global Mega Data Center Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Hyperscale cloud service providers self-build exclusively, eliminating traditional leasing intermediaries and compressing the vendor base. Three archetypes dominate: captive engineering divisions of cloud operators, specialized infrastructure contractors, and integrated equipment suppliers. Competitive moves center on build-to-suit procurement contracting and proprietary cooling technology patent accumulation.
Within the hyperscale operator tier, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions defined by custom silicon strategies and captive facility engineering. These entities exemplify vertical integration into power distribution and thermal management, with each anchoring distinct geographic clusters through direct construction relationships rather than third-party leasing.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Equinix |
| Digital Realty |
| IBM Corporation |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Schneider Electric |
| Others |
Supply & Pricing Matrix
Hyperscale cloud service provider self-builds concentrate procurement power among three dominant buyers, compressing supplier margins through direct construction contracting and multi-year equipment offtake agreements rather than spot-market transactions.
Pricing Analysis
Short lead-time premiums for liquid cooling infrastructure and electrical steel transformers command pricing premiums against standard delivery schedules. Build-to-suit procurement structures separate premium tier hyperscale direct contracts from standard tier colocation wholesale leasing and economy tier modular prefabricated units. Cost compression in air-cooled legacy retrofits is intensifying because efficiency mandates under EPA Energy Star and EU Green Deal disqualify older designs from new certifications. Enterprise data centers exhibit highest price sensitivity due to capital constraint pressures, while hyperscale operators demonstrate lowest sensitivity given captive engineering budgets.
Supply Chain Analysis
Domestic-content mandates under China's MIIT GB standards and US IRA clean energy credit localization requirements are reshaping sourcing patterns for transformer cores and cooling equipment. Supply concentrates in China, South Korea, and Germany for electrical steel and precision thermal hardware. Raw material dependencies center on copper cathode, grain-oriented electrical steel, and fluorinated refrigerants. Single-source vulnerability in Asian smelter concentration for transformer cores creates input cost volatility. Distribution runs through direct OEM contracting for hyperscale builds and integrator channels for mid-scale enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrical steel supply concentration and liquid cooling engineering talent scarcity prop pricing power for suppliers who can guarantee delivery timelines against compressed facility buildout schedules.
For Market Incumbents: Anchor market position through backward integration into copper busbar fabrication and captive thermal engineering talent pipelines. Threat substitution from immersion cooling specialists demands patent accumulation in direct-to-chip cold plate designs. Priority lever rests on locking multi-year transformer supply agreements with Korean and German electrical steel mills before capacity allocation tightens further. For New Entrants and Emerging Players: Direct-to-chip liquid cooling component channels offer the lowest barrier entry path against integrated hyperscale engineering divisions. White-space targets concentrate in Nordic waste heat recovery integration and German EU AI Act compliance telemetry systems. Most penetrable segment sits with mid-scale colocation operators retrofitting for AI training cluster demand. Go-to-market angle emphasizes rapid deployment modular units with pre-integrated sustainability reporting dashboards. For Investors and Strategic Acquirers: The window for entry favors specialized thermal engineering contractors with MIIT GB compliance experience and OSHA high-voltage certification programs. Long-term viability hinges on five-to-ten year renewable energy procurement lock-ins and district heating revenue stream diversification. Acquisition target archetype centers on Nordic immersion cooling specialists with existing waste heat export contracts. Signal to watch is F-Gas Regulation phase-out acceleration triggering refrigerant technology obsolescence across European installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Buildout | Direct-to-chip cold plate deployment enables 100-kilowatt cabinet density for AI training clusters. |
| Copper Busbar Vertical Integration | In-house busway fabrication reduces power distribution losses and secures supply against commodity volatility. |
| EU Green Deal Compliance Certification | Real-time carbon disclosure telemetry satisfies EU AI Act audit requirements for high-risk AI workloads. |
| Waste Heat Recovery Partnership | District heating revenue contracts with Nordic municipalities unlock secondary income streams from thermal export. |
| Electrical Steel Supply Agreement | Long-term offtake with Korean or German mills insulates transformer construction against smelter concentration risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hyperscale facility engineering directors, thermal hardware procurement managers, data center construction contractors, and EPC project developers combined with secondary validation from EPA Energy Star certification databases, EU ETS carbon disclosure registries, and MIIT GB standards documentation. Bottom-up facility buildout tracking and top-down cloud service provider capex disclosure triangulation established market sizing boundaries.
Granularity-level modeling operated at deployment mode, cooling technology type, and application workload density dimensions across the analysis window. CAGRs derived from facility pipeline tracking, power purchase agreement disclosure analysis, and processor thermal design power trajectory correlation. Forecast inputs incorporated liquid cooling adoption curves and electrical steel capacity expansion announcements without year-specific milestone anchoring.
The model holds under continued hyperscale self-build dominance and stable GB standards enforcement; deviation in F-Gas Regulation acceleration or transformer supply disruption would shift capacity deployment timelines. Forecasts reflect documented assumptions regarding AI training cluster demand persistence and renewable energy procurement cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Australia Data Center Construction Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Chennai Data Center Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market