
 Veterinary Orthopedic Medicine Market | 2026-2036
Veterinary Orthopedic Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Orthopedic Medicine Market Analytics
North American veterinary device manufacturers is pivoting toward biocompatible polymer systems for joint replacement platforms. Zoetis Inc leverages its pharmaceutical-distribution infrastructure to bundle orthopedic diagnostics with therapeutic protocols. Boehringer Ingelheim anchors its position through R&D intensity in regenerative medicine applications for equine and canine patients. Merck Animal Health differentiates via geographic dominance in European veterinary channels.
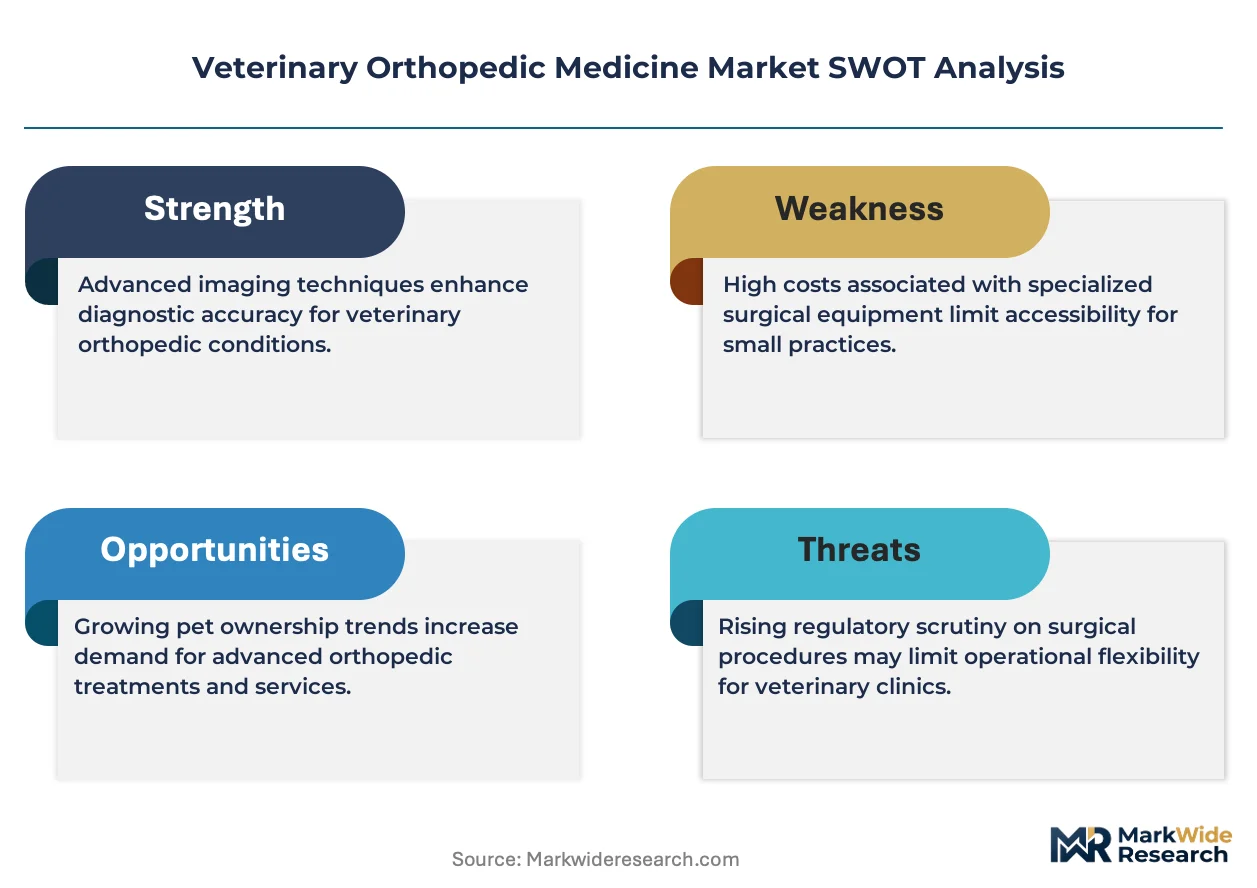
Veterinary orthopedic medicine encompasses surgical and non-surgical interventions for musculoskeletal disorders in animals, utilizing titanium alloy implants, polyetheretherketone anchors, and arthroscopic visualization systems with sub-millimeter resolution to restore mobility in weight-bearing joints. The field serves primarily companion animal hospitals and equine sports medicine centers where functional recovery determines economic return for owners. Implants command the largest revenue share due to recurring revision surgery requirements and premium pricing for corrosion-resistant fixation plates. Joint surgery procedures are expanding fastest as pet owners delay euthanasia for senior animals with osteoarthritis. Diagnostic equipment represents a concentrated margin pool where point-of-care imaging reduces referral leakage.
FDA Center for Veterinary Medicine regulates implant biocompatibility and sterilization validation, while ISO 10993 governs materials testing for devices marketed across multiple jurisdictions. USDA APHIS oversight of veterinary tissue products shapes demand for autologous stem cell therapies and allograft bone substitutes. Stakeholders must monitor evolving reimbursement pathways from pet insurance underwriters as these determine owner willingness to proceed with advanced surgical interventions.
Market Dynamics
The FDA Center for Veterinary Medicine's tightening biocompatibility validation requirements for titanium alloy implants is compressing product development timelines and elevating capital barriers for device manufacturers entering the companion animal orthopedic segment.
Growth Catalysts
- Pet insurance penetration:Specialty veterinary hospital networks in the United States are expanding service lines as reimbursement coverage reduces owner cost sensitivity for complex joint replacement procedures.
- ISO 10993 harmonization:Materials testing standardization across multiple jurisdictions is streamlining regulatory pathways for polymer-based fixation systems and accelerating cross-border commercialization.
- Equine sports medicine centers:Functional recovery economics in competitive racing and show circuits is driving demand for arthroscopic visualization systems with sub-millimeter resolution capabilities.
Market Restraints
- Titanium alloy supply concentration:Aerospace and medical device industries compete for corrosion-resistant metal feedstock, creating input cost volatility for fixation plate manufacturers.
- FDA sterilization validation:Extended biocompatibility testing timelines for novel implant surfaces delay revenue recognition and strain working capital positions.
- Autologous stem cell substitution:USDA APHIS oversight of veterinary tissue products is elevating allograft bone substitutes and regenerative therapies as alternatives to permanent hardware implantation.
Strategic Opportunities
- Point-of-care imaging expansion:Diagnostic equipment deployment in primary companion animal clinics reduces referral leakage to specialty hospitals and captures margin pool concentration.
- Senior animal osteoarthritis protocols:Delayed euthanasia decisions among aging pet populations are creating procedural volume expansion for revision surgery platforms.
- European veterinary channel development:Geographic dominance gaps in continental distribution networks present white space for orthopedic diagnostics bundled with therapeutic protocols.
Industry Challenges
- Veterinary orthopedic surgeon scarcity:Fellowship-trained specialists capable of arthroscopic joint replacement remain concentrated in urban academic centers, constraining service line expansion.
- Implant inventory carrying costs:Corrosion-resistant fixation plates require climate-controlled storage and expiration tracking, elevating working capital intensity for hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Orthopedic Medicine Market |
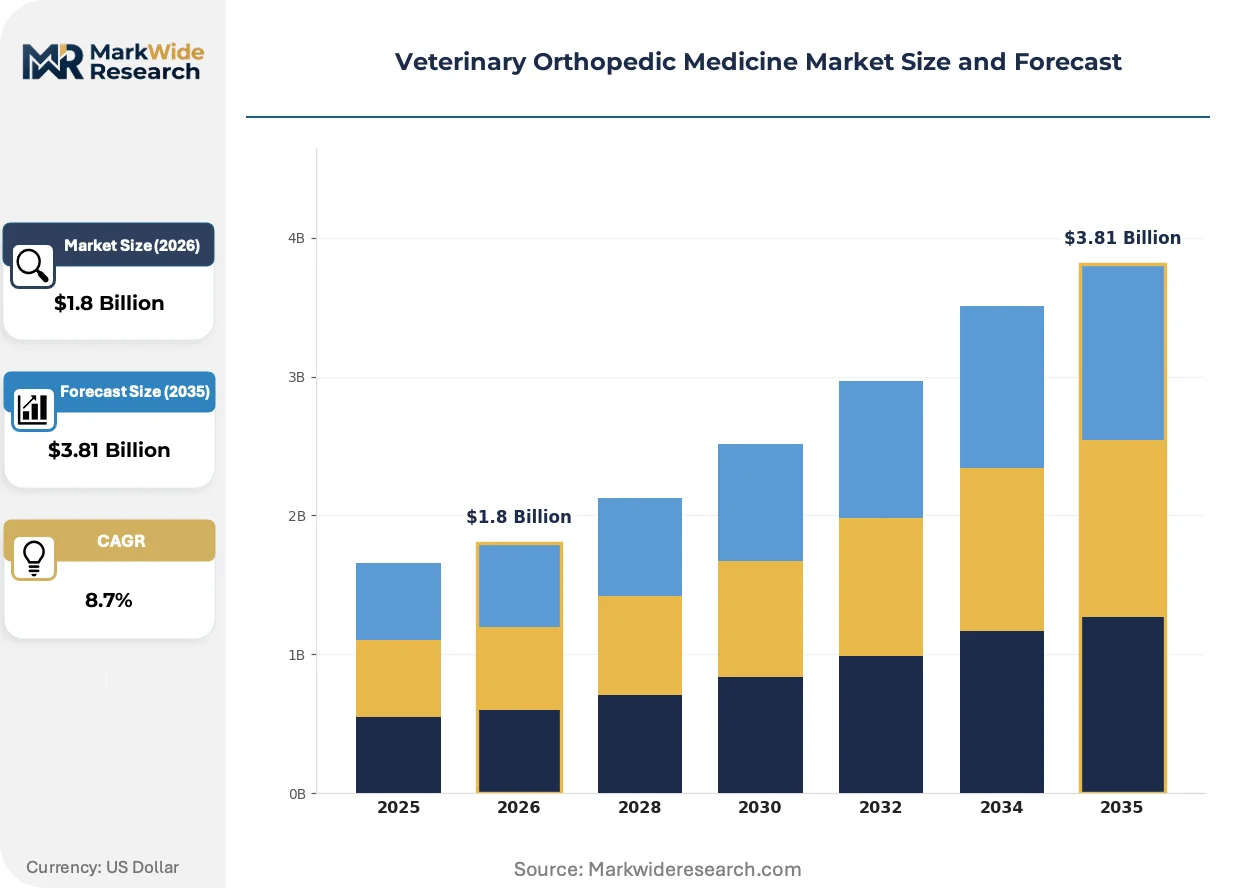
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Surgical Instruments, Orthopedic Devices, Diagnostic Equipment Procedure Type: Fracture Repair, Joint Surgery, Arthroscopy, Cartilage Repair Animal Type: Dogs, Cats, Horses, Exotic Pets Distribution Channel: Veterinary Clinics, Online Stores, Distributors, Hospitals |
| Companies Covered | Zoetis Inc, Boehringer Ingelheim, Elanco Animal Health, Merck Animal Health, Vetoquinol S.A., Ardent Animal Health, VetStem, BioMedtrix, KYON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Orthopedic Medicine Market Evolving Landscape
Biocompatible polymer systems and regenerative medicine applications are actively reconfiguring material selection criteria and therapeutic protocols across companion animal and equine orthopedic practice settings.
Polyetheretherketone anchors are displacing traditional metal fixation in weight-bearing joint applications due to modulus-of-elasticity matching with bone tissue. Specialty veterinary hospitals in the United States are adopting these polymer systems at accelerating pace for canine total hip replacement procedures. This material shift is decentralizing procurement decisions from centralized implant distributors toward direct manufacturer relationships with hospital networks.
EU MDR equivalence requirements for veterinary devices are extending quality management system obligations previously limited to human medical products. Manufacturers seeking CE marking must now demonstrate post-market surveillance capabilities and clinical data traceability. The diagnostic equipment segment faces the steepest compliance burden, with arthroscopic visualization systems requiring updated technical documentation and notified body engagement.
Pet owners are demanding transparent outcome reporting and procedural cost estimates prior to surgical commitment, compressing traditional consultation-to-treatment cycles. Specialty veterinary hospitals are responding with bundled pricing packages and telemedicine follow-up protocols. This behavioral shift is most pronounced in United States coastal metropolitan markets where pet insurance penetration exceeds national averages and digital-native client expectations dominate practice management priorities.
Veterinary Orthopedic Medicine Market Segmentation
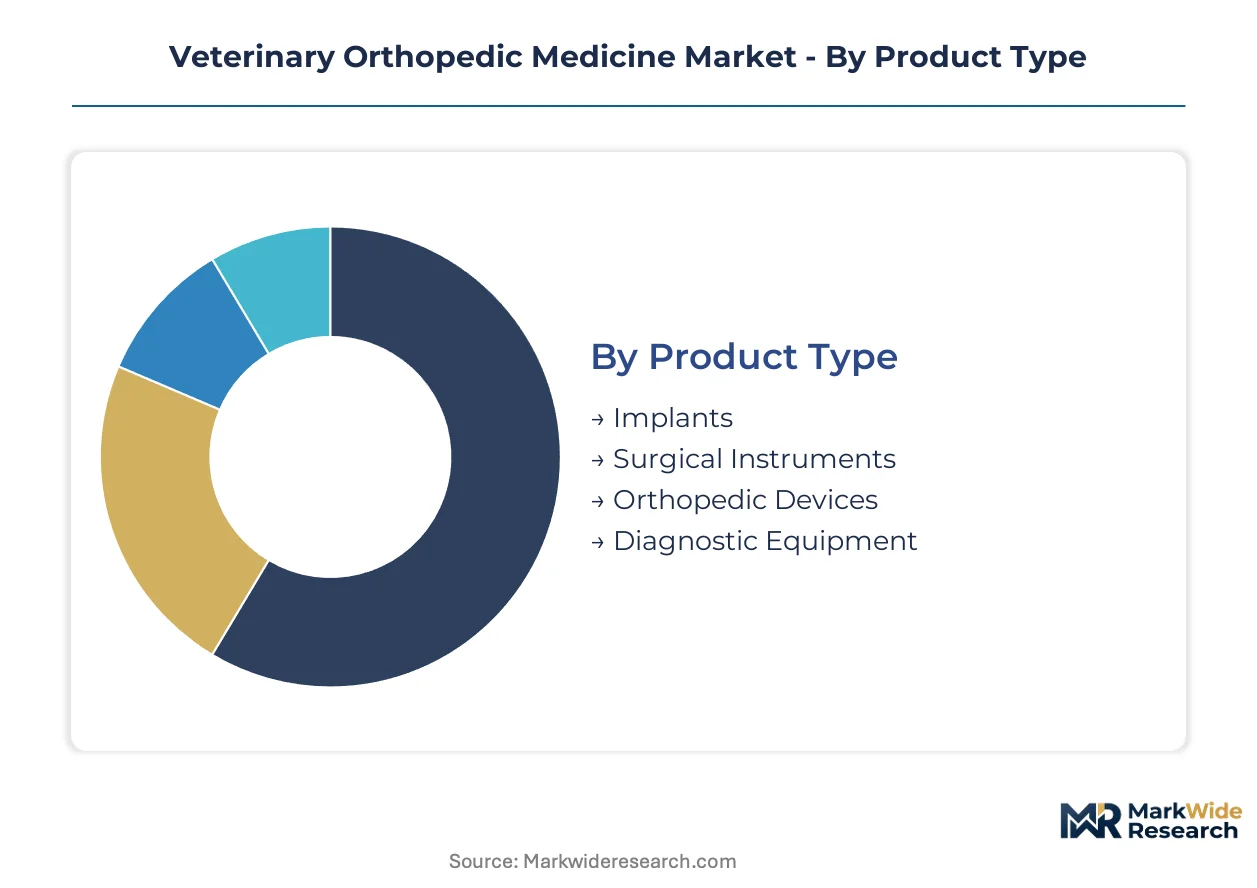
Orthopedic intervention selection in veterinary practice hinges on species-specific biomechanics, owner economic thresholds, and surgical infrastructure availability. Segmentation reveals where capital investment concentrates and which procedural categories attract manufacturer R&D prioritization.
Product Type:
Supply concentration among corrosion-resistant metal and polymer feedstock suppliers shapes competitive positioning across hardware categories.
- Implants:Titanium alloy fixation plates and polyetheretherketone anchors dominate revenue concentration due to revision surgery recurrence and premium pricing for biocompatible hardware. United States specialty veterinary hospitals absorb the majority of implant procurement volume as pet insurance coverage reduces owner cost sensitivity for permanent joint replacement.
- Surgical Instruments:Arthroscopic visualization systems with sub-millimeter resolution capabilities command concentrated margins from equine sports medicine centers where functional recovery determines competitive racing returns.
- Orthopedic Devices:External fixation frames and casting materials serve primary companion animal clinics with lower capital infrastructure requirements.
- Diagnostic Equipment:Point-of-care imaging systems reduce referral leakage to specialty hospitals by enabling in-clinic fracture assessment and pre-surgical planning.
Implants absorb the bulk of installed capacity; diagnostic equipment is expanding most quickly.
Procedure Type:
Cost tier differentiation separates emergency fracture stabilization from elective joint reconstruction in owner decision frameworks.
- Joint Surgery:Canine total hip replacement and stifle stabilization procedures generate the highest per-case revenue as aging pet populations delay euthanasia for osteoarthritis. United States coastal metropolitan markets with elevated pet insurance penetration drive procedural volume expansion.
- Fracture Repair:Trauma stabilization using intramedullary pins and external fixators represents the most frequent emergency orthopedic intervention across general veterinary practices.
- Arthroscopy:Minimally invasive joint exploration and debridement concentrates in academic veterinary medical centers with fellowship-trained surgical specialists.
- Cartilage Repair:Autologous stem cell therapies and allograft bone substitutes face USDA APHIS oversight constraints that elevate regenerative medicine alternatives to permanent hardware.
Joint surgery captures the steepest margin expansion; cartilage repair is gaining share fastest as biological substitutes advance.
Animal Type:
Volume concentration among companion species contrasts with value concentration in equine applications where performance economics justify premium intervention.
- Dogs:Large and giant breed canines drive cruciate ligament repair and hip dysplasia management volume, with breed-specific orthopedic disease patterns shaping implant size and material selection.
- Horses:Thoroughbred racing and show circuits generate demand for arthroscopic joint surgery where functional recovery timelines determine owner return on investment.
- Cats:Feline orthopedic intervention concentrates in trauma fracture repair rather than degenerative joint disease management due to species-specific activity patterns and owner cost thresholds.
- Exotic Pets:Avian and small mammal orthopedic procedures remain confined to specialized academic referral hospitals with exotic animal surgical expertise.
Dogs absorb the bulk of procedural volume; horses command the highest per-case value realization.
Distribution Channel:
Customer type segmentation separates institutional procurement from individual practice purchasing patterns with distinct working capital and inventory turnover profiles.
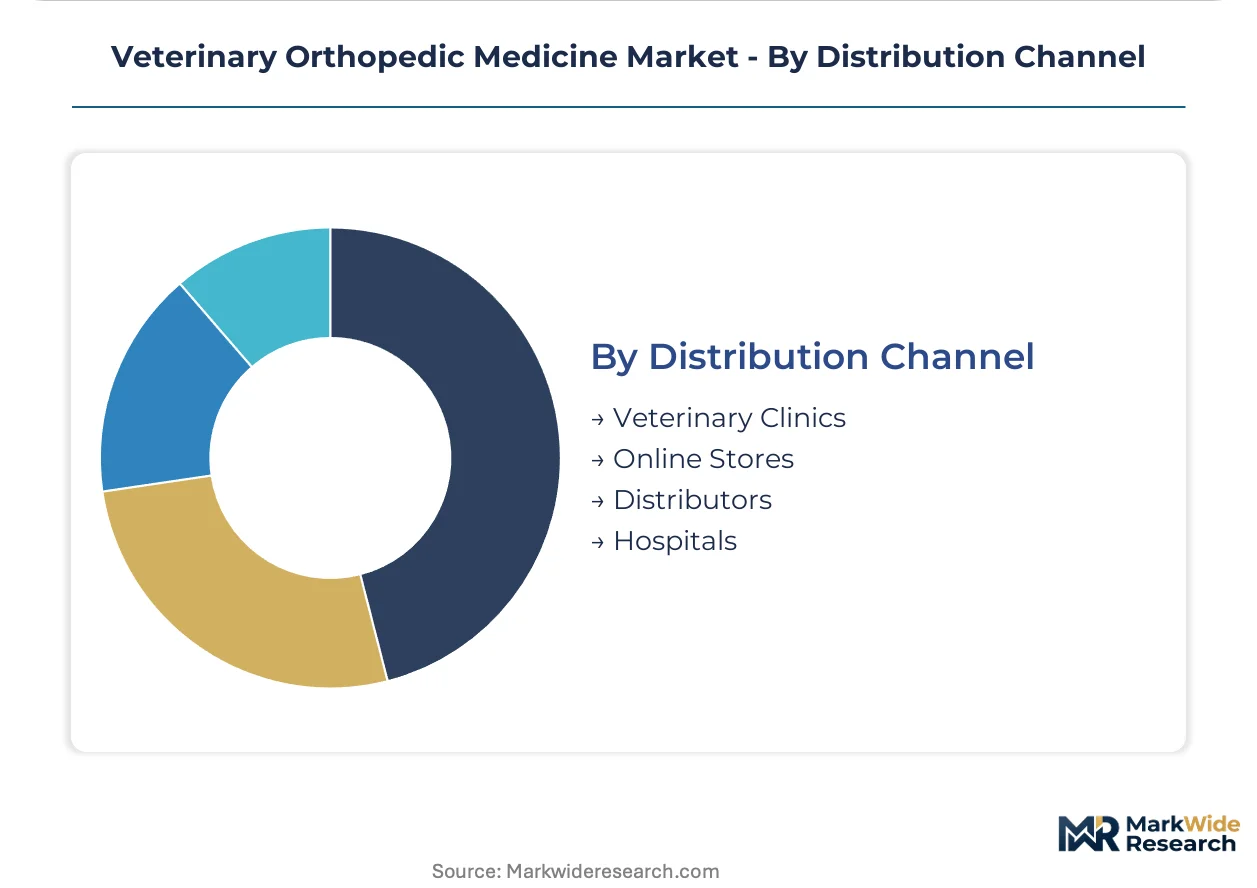
- Veterinary Clinics:Primary companion animal practices concentrate demand for diagnostic equipment and consumable fixation supplies with immediate clinical utility requirements.
- Hospitals:Specialty and academic veterinary medical centers drive implant procurement volume through centralized purchasing agreements with manufacturer direct relationships.
- Distributors:Traditional veterinary supply intermediaries face margin compression as hospital networks consolidate procurement and negotiate volume-based pricing arrangements.
- Online Stores:E-commerce penetration concentrates in consumable orthopedic supplies and post-operative rehabilitation products rather than capital equipment or sterile implants.
Specialty hospitals absorb the bulk of implant procurement value; online channels are climbing the fastest in consumable supply segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium alloy feedstock availability in the United States anchors veterinary orthopedic implant manufacturing capacity. Specialty veterinary hospital networks concentrate in metropolitan corridors with elevated pet insurance penetration.
United States
FDA Center for Veterinary Medicine biocompatibility validation requirements compress product development timelines for domestic manufacturers. Coastal metropolitan markets including Los Angeles, New York, and Boston drive procedural volume expansion through elevated pet insurance coverage. The Greater Boston corridor hosts academic veterinary medical centers advancing arthroscopic visualization system adoption.
Germany
EU MDR equivalence requirements extend quality management system obligations to veterinary device manufacturers seeking CE marking. The Baden-Württemberg industrial cluster concentrates precision polymer processing capabilities for polyetheretherketone anchor production. Stuttgart-based manufacturers leverage automotive sector materials expertise for veterinary orthopedic applications.
United Kingdom
Specialty veterinary hospital consolidation in London and Southeast England creates centralized procurement power for implant distributors. The country's national veterinary regulator enforces sterilization validation standards aligned with human medical device protocols. The Cambridge-Oxford corridor attracts regenerative medicine ventures developing autologous stem cell therapies.
Japan
PMDA oversight of veterinary medical devices shapes approval pathways for titanium alloy fixation systems. The Kanto region surrounding Tokyo concentrates companion animal specialty hospitals with advanced surgical infrastructure. Osaka-based manufacturers supply arthroscopic equipment to domestic equine sports medicine centers.
Australia
TGA regulation of veterinary devices governs import requirements for orthopedic implants from European and North American suppliers. The Sydney-Melbourne corridor hosts the majority of specialty veterinary referral hospitals performing joint replacement procedures. Queensland equine racing circuits generate concentrated demand for functional recovery surgical protocols.
Veterinary Orthopedic Medicine Market Competitive Landscape
Global majors compete with regional champions across distribution infrastructure and species-specific therapeutic portfolios. The market structure consolidates around pharmaceutical-origin conglomerates with veterinary divisions and specialized orthopedic device manufacturers with direct hospital relationships. Three archetypes dominate: diversified animal health conglomerates leveraging pharmaceutical distribution networks, pure-play orthopedic device specialists with surgeon training programs, and regenerative medicine ventures commercializing biological alternatives to permanent implants. Competitive moves concentrate on vertical integration into biocompatible polymer feedstock supply and strategic partnerships with specialty veterinary hospital networks for exclusive procurement agreements.
Among diversified animal health conglomerates, Zoetis Inc and Boehringer Ingelheim exemplify the pharmaceutical-distribution archetype with bundled diagnostic-therapeutic protocols. Merck Animal Health occupies a position emphasizing geographic channel development. Within the specialized orthopedic device tier, BioMedtrix and KYON represent manufacturers with direct hospital network relationships and surgeon education platforms. Elanco Animal Health and Vetoquinol S.A. sit within the mid-scale veterinary pharmaceutical segment expanding into surgical service lines. Ardent Animal Health and VetStem exemplify the regenerative medicine archetype developing biological substitutes to traditional hardware implantation.
| Leading Market Players |
|---|
| Zoetis Inc |
| Boehringer Ingelheim |
| Elanco Animal Health |
| Merck Animal Health |
| Vetoquinol S.A. |
| Ardent Animal Health |
| VetStem |
| BioMedtrix |
| KYON |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialty veterinary hospital networks in the United States are consolidating procurement power and compressing implant pricing through volume-based direct manufacturer contracts, while simultaneously elevating working capital requirements for climate-controlled inventory storage and expiration tracking systems.
Pricing Analysis
Warranty and surgeon training bundling separates premium-tier implant suppliers from unbundled economy alternatives in the veterinary orthopedic market. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 certification grade and titanium alloy purity specifications. Cost compression in the economy tier is intensifying because autologous stem cell therapies from Ardent Animal Health and VetStem are substituting permanent hardware in select procedures. General veterinary clinics exhibit the highest price sensitivity due to limited pet insurance reimbursement, while specialty hospitals absorb premium pricing for revision surgery platforms.
Supply Chain Analysis
Climate-controlled freight logistics for corrosion-resistant titanium alloy feedstock elevate landed costs for manufacturers distant from United States aerospace supply corridors. Production gravity centers on the United States, Germany, and Japan for precision polymer processing and arthroscopic visualization system assembly. Feedstock supply rests on aerospace industry competition for titanium alloy, polyetheretherketone resin availability, and optical component sourcing from Osaka-based manufacturers. Single-source vulnerability concentrates in titanium sponge processing capacity. Distribution runs through manufacturer-direct relationships with specialty hospital networks, bypassing traditional veterinary supply intermediaries facing margin compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary orthopedic medicine market is becoming a vertical-integration race as manufacturers pursue captive control over biocompatible polymer feedstock supply to secure margin protection against titanium alloy price volatility.
For Market Incumbents: Lock in exclusive procurement agreements with specialty veterinary hospital networks before regenerative medicine ventures scale biological substitutes. Backward integration into polyetheretherketone resin production in the Baden-Württemberg cluster reduces aerospace industry feedstock competition exposure. Prioritize ISO 10993 certification maintenance as EU MDR equivalence requirements extend quality management obligations. For New Entrants and Emerging Players: Begin with point-of-care imaging deployment in primary companion animal clinics outside coastal metropolitan corridors where pet insurance penetration lags. The most penetrable white space sits in European veterinary channel development where Merck Animal Health's geographic dominance remains incomplete. A bundled diagnostic-therapeutic protocol approach mirroring Zoetis Inc's pharmaceutical-distribution infrastructure accelerates clinic adoption. For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine biocompatibility validation timeline compression is the leading indicator that working capital intensity will filter out undercapitalized device manufacturers. The five-to-ten year viability window favors acquisition targets with established surgeon training platforms and direct hospital relationships over pure-play regenerative medicine ventures facing USDA APHIS oversight uncertainty. Monitor pet insurance underwriter reimbursement pathway expansion as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatible Polymer Feedstock Integration | Captive PEEK resin supply from Stuttgart-based processors insulates against aerospace titanium competition. |
| Surgeon Training Platform Expansion | BioMedtrix and KYON demonstrate that fellowship education programs lock in implant loyalty. |
| Point-of-Care Imaging Deployment | Diagnostic equipment placement in primary clinics reduces referral leakage to specialty hospitals. |
| Pet Insurance Reimbursement Strategy | Alignment with underwriters in coastal metropolitan markets reduces owner cost sensitivity. |
| Regenerative Medicine Pipeline Diversification | Autologous stem cell therapies from VetStem address USDA APHIS oversight constraints on permanent hardware. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this veterinary orthopedic medicine analysis, supplemented by primary interviews with veterinary surgeons, specialty hospital procurement directors, biomedical engineers at implant manufacturers, and pet insurance underwriters. FDA Center for Veterinary Medicine biocompatibility validation databases, ISO 10993 materials testing registries, and USDA APHIS veterinary tissue product filings provided regulatory pathway documentation. Bottom-up procedure volume estimates from companion animal clinics and equine sports medicine centers triangulated against top-down manufacturer revenue disclosures.
Segment-level modeling addressed product type granularity across implants, surgical instruments, orthopedic devices, and diagnostic equipment, with procedure type disaggregation into joint surgery, fracture repair, arthroscopy, and cartilage repair. Animal type splits across canines, horses, felines, and exotic species captured species-specific biomechanics and owner economic thresholds. Distribution channel dynamics separated veterinary clinics, specialty hospitals, distributors, and online stores. CAGRs were derived from installed base growth, revision surgery recurrence rates, and pet insurance penetration trajectories across the analysis window.
Underlying measurement precision varies by segment; implant revenue concentration and joint surgery procedural volume carry tighter precision than regenerative medicine adoption curves where USDA APHIS oversight evolution introduces uncertainty. Forecasts reflect assumptions regarding FDA sterilization validation timeline stability, titanium alloy feedstock availability, and specialty veterinary surgeon training pipeline expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
Live Attenuated Veterinary Vaccines Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Veterinary Wellness Market
Veterinary Medicine
Monoclonal Antibodies in Veterinary Health Market
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
Veterinary Skin Care Products Market