
 Hemostasis Analyzers Market | 2026-2036
Hemostasis Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Hemostasis Analyzers Market Outlook
Aftermarket service revenue is tilting toward integrated consumable-instrument contracts as labs seek predictable per-test economics. Werfen sustains its installed base through closed-system reagent loyalty programs across European and Latin American reference labs. Sysmex Corporation dominates high-volume coagulation lines in Japanese university hospitals with automated sample-handling architectures. Thermo Fisher Scientific Inc. leverages its diagnostic distribution network to place point-of-care hemostasis units in non-traditional settings including ambulatory surgical centers.
Hemostasis analyzers are electromechanical or optical instruments that quantify clotting times, platelet aggregation, and fibrinolytic markers in whole blood or plasma specimens, typically operating through turbidimetric, chromogenic, or electrochemical detection principles with throughput ranging from single-test cartridges to 400-plus samples per hour. Their primary commercial purpose is guiding therapeutic decisions for anticoagulant therapy, perioperative bleeding risk assessment, and disseminated intravascular coagulation screening in acute care environments. Coagulation analyzers occupy the mature core of the product portfolio where replacement cycles and reagent pull-through generate stable margin pools, while point-of-care devices represent the fastest-expanding category as emergency departments and catheterization labs prioritize turnaround time over laboratory centralization. Among end users, diagnostic laboratories command the largest installed instrument base, though blood banks are emerging as a concentrated growth vector driven by donor screening automation and extended platelet storage protocols.
The FDA's 510(k) pathway for coagulation analyzers mandates clinical validation against predicate devices, while the Clinical Laboratory Improvement Amendments establish personnel competency and quality control standards that shape product design for US commercialization. In Europe, the In Vitro Diagnostic Regulation's performance evaluation requirements and notified body capacity constraints are extending time-to-market for new hemostasis platforms, favoring incumbents with established technical documentation systems. Stakeholders must monitor how decentralized testing regulatory harmonization between national health technology assessment bodies and point-of-care quality standards determines competitive access across ambulatory and inpatient channels.
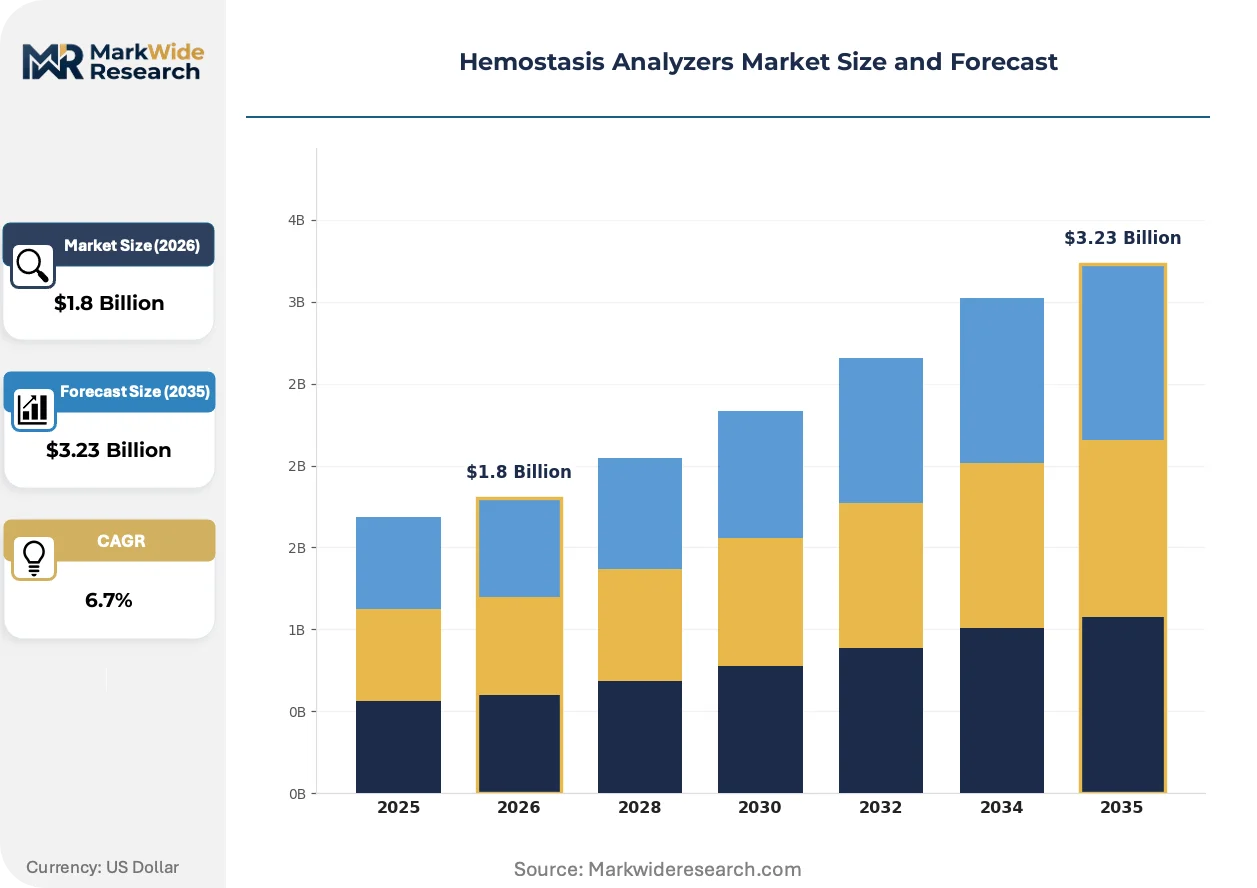
Market Dynamics
Integrated consumable-instrument contracts are compressing traditional service revenue models as diagnostic laboratories prioritize predictable per-test economics over capital-intensive instrument purchases. This shift is redistributing margin capture from hardware vendors toward reagent-anchored loyalty programs.
Growth Catalysts
- IVDR Performance Evaluation Requirements:Europe's tightened regulatory scrutiny is extending time-to-market for new entrants, entrenching incumbents with established technical documentation systems and certified quality management frameworks.
- Ambulatory Surgical Center Expansion:Non-traditional testing sites are deploying point-of-care coagulation units to bypass centralized laboratory workflows and reduce perioperative bleeding assessment turnaround times.
- Japanese University Hospital Automation:Automated sample-handling architectures are displacing manual pre-analytical processing in high-throughput academic medical centers, driving replacement cycles for legacy coagulation lines.
Market Restraints
- Notified Body Capacity Constraints:Europe's limited conformity assessment infrastructure is creating bottlenecks for hemostasis platform certifications, delaying commercialization timelines by 12-18 months for non-incumbent manufacturers.
- Optical Detection Component Concentration:Specialized turbidimetric sensors and chromogenic substrate supply chains cluster among German and Japanese component specialists, exposing assemblers to single-source fragility.
- Whole Blood Substitute Limitations:Lyophilized control materials and stabilized patient surrogates fail to replicate native platelet reactivity in aggregation assays, constraining quality assurance standardization across distributed testing networks.
Strategic Opportunities
- Blood Bank Donor Screening Automation:Extended platelet storage protocols and pathogen reduction mandates are creating instrument placement opportunities in transfusion services previously served by manual methods.
- CLIA-Waived Point-of-Care Expansion:The FDA's streamlined personnel competency standards for moderate-complexity testing are enabling catheterization lab deployment of cartridge-based coagulation devices without laboratory oversight.
- Artificial Intelligence-Enhanced Interpretation:Machine learning algorithms applied to thromboelastography waveforms are converging with cloud-based laboratory information systems to automate abnormal pattern flagging in understaffed overnight shifts.
Industry Challenges
- 510(k) Predicate Device Divergence:The FDA's narrowing acceptance of substantial equivalence claims for novel detection principles is forcing manufacturers toward de novo pathways with extended clinical validation burdens.
- Anticoagulant Polypharmacy Complexity:Direct oral anticoagulant proliferation has fragmented therapeutic monitoring protocols, requiring analyzer firmware updates and reagent reformulations that strain legacy instrument compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemostasis Analyzers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulation Analyzers, Platelet Function Test, Thromboelastography, Point-Of-Care Devices End User: Hospitals, Diagnostic Laboratories, Blood Banks, Outpatient Clinics Technology: Electrochemical, Optical, Mechanical, Clot Detection Application: Surgical Procedures, Cardiovascular Disorders, Trauma Care, Routine Testing |
| Companies Covered | Werfen, Thermo Fisher Scientific Inc., Sysmex Corporation, Instrumentation Laboratory, Abbott Laboratories, Siemens Healthineers AG, Diagnostica Stago Inc., Nihon Kohden Corporation, F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemostasis Analyzers Market Strategic Shifts
Digital integration is dissolving boundaries between centralized laboratory analyzers and distributed point-of-care devices, creating unified data architectures that span emergency departments, surgical suites, and reference laboratories.
Cloud-native hemostasis middleware is virtualizing result verification workflows by enabling remote hematopathologist review of abnormal coagulation profiles without physical sample transport. Academic medical centers in Germany and Japan are piloting these platforms for overnight coverage of satellite hospitals. This virtualization is compressing the competitive advantage of geographically concentrated specialist labor pools.
The FDA's evolving guidance on point-of-care coagulation devices is mandating expanded anticoagulant interference studies and lot-to-lot reagent consistency documentation. Manufacturers are restructuring clinical validation programs to include direct oral anticoagulant-spiked samples across multiple hematocrit ranges. Emergency department purchasers are prioritizing platforms with published DOA cross-reactivity matrices over legacy warfarin-centric systems.
Service contract unbundling is fragmenting the traditional instrument-reagent-service bundle as procurement teams at US health systems negotiate reagent supply agreements separate from maintenance coverage. Third-party independent service organizations are capturing calibration and quality control support contracts previously held by original equipment manufacturers. This disintermediation is most visible in integrated delivery networks with centralized biomedical engineering capabilities.
Hemostasis Analyzers Market Segmentation
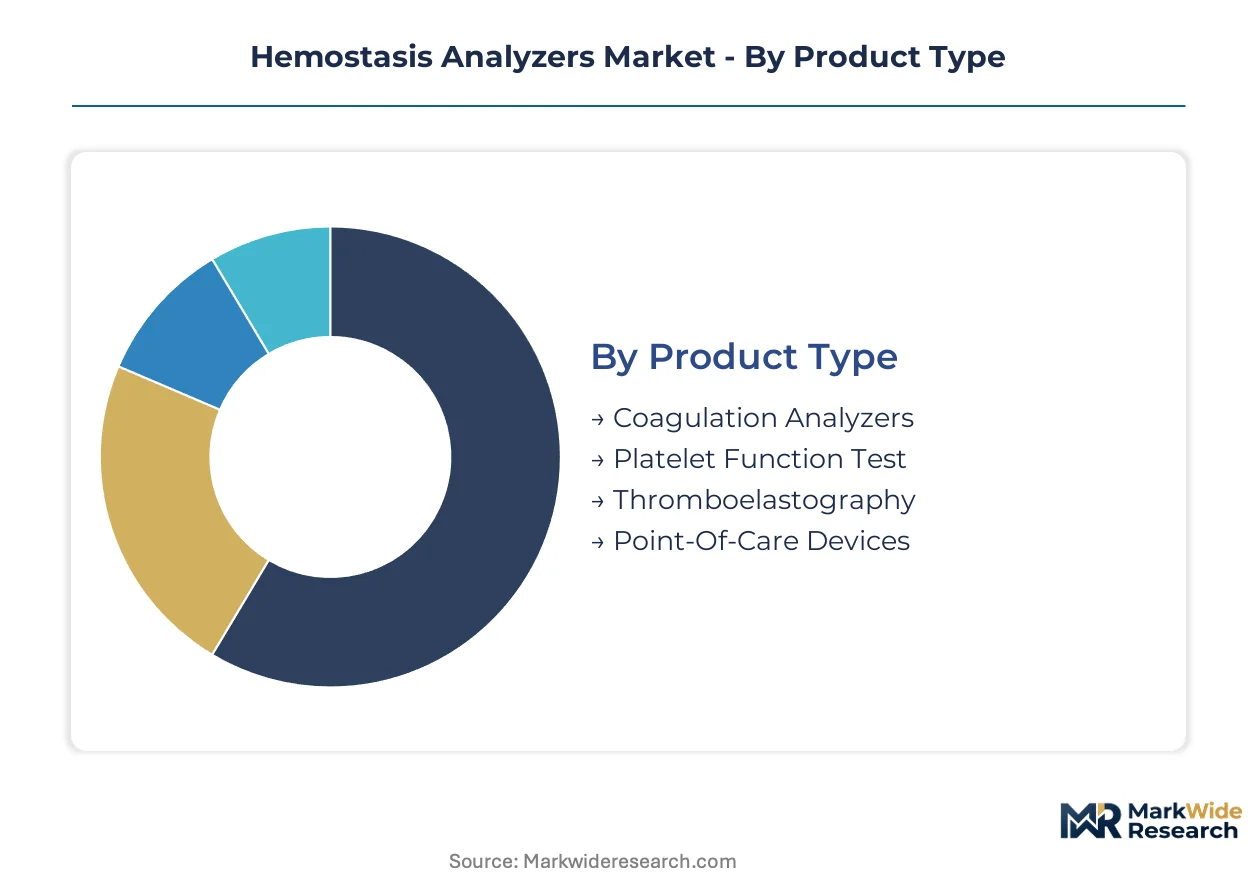
Hemostasis analyzer procurement cycles vary dramatically across product architectures, with centralized laboratory platforms operating on 7-10 year replacement timelines while point-of-care devices refresh every 3-5 years. Understanding these turnover rhythms helps manufacturers align R&D pipelines with predictable revenue windows and service contract structures.
Product Type:
Replacement velocity separates the product hierarchy, with cartridge-based systems cycling fastest and floor-standing laboratory workhorses persisting longest in installed bases.
- Coagulation Analyzers:Turbidimetric and chromogenic detection systems process 100-400 samples hourly through automated sample-handling architectures. German and Japanese reference laboratories anchor demand for high-throughput lines as they consolidate distributed testing into centralized core facilities.
- Point-Of-Care Devices:Cartridge-based electrochemical and mechanical detection units deliver results within minutes from whole blood samples without centrifugation. Ambulatory surgical centers in the United States are deploying these units to bypass laboratory workflows and compress perioperative bleeding assessment turnaround times.
- Platelet Function Test:Aggregometry systems measure platelet reactivity in response to agonists for antiplatelet therapy monitoring.
- Thromboelastography:Viscoelastic whole blood assays assess clot formation kinetics and fibrinolysis in trauma and cardiac surgery settings.
Coagulation analyzers anchor the volume base while point-of-care devices gain share at the steepest rate.
End User:
Capital deployment intensity creates distinct customer tiers, with integrated health systems favoring instrument-reagent bundles and standalone facilities prioritizing per-test economics.
- Diagnostic Laboratories:Centralized reference facilities operate the largest installed instrument bases with 24-hour throughput requirements and multi-site network standardization mandates. These facilities concentrate in the United States and Germany where reimbursement frameworks sustain high-complexity testing menus.
- Hospitals:Acute care institutions deploy hemostasis analyzers across emergency departments, catheterization labs, and surgical suites for real-time therapeutic decision support. Japanese university hospitals are driving replacement cycles through automated pre-analytical processing upgrades.
- Blood Banks:Transfusion services are emerging as concentrated growth vectors through donor screening automation and extended platelet storage protocol validation.
- Outpatient Clinics:Ambulatory settings deploy CLIA-waived devices for anticoagulant monitoring without laboratory oversight requirements.
Diagnostic laboratories command the deepest installed base while blood banks expand most quickly.
Technology:
Detection principle selection determines reagent compatibility, maintenance burden, and regulatory pathway complexity for manufacturers entering the market.
- Optical:Turbidimetric and chromogenic substrate detection dominates high-throughput laboratory platforms through established photometric measurement stability. German component specialists supply specialized optical sensors that create single-source dependencies for instrument assemblers.
- Electrochemical:Amperometric and potentiometric detection enables miniaturization for cartridge-based point-of-care devices with reduced sample volume requirements. These systems are displacing optical methods in emergency department deployments where speed outweighs analytical precision.
- Mechanical:Viscoelastic and impedance-based detection principles operate in thromboelastography and whole blood aggregation systems.
- Clot Detection:Mechanical endpoint detection through steel ball or vibrating probe methods persists in legacy platforms and specialized applications.
Optical detection anchors the installed base while electrochemical platforms climb the fastest.
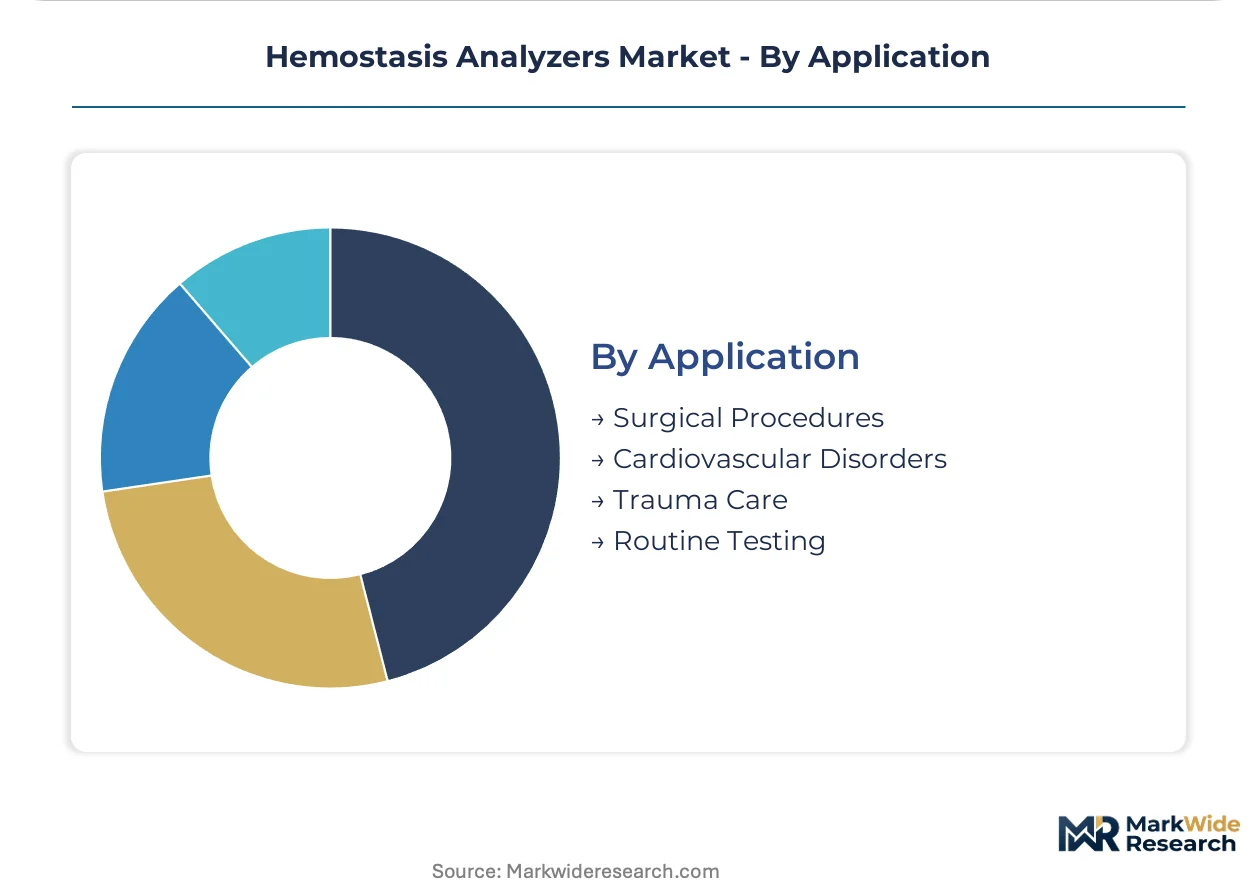
Application:
Clinical urgency and reimbursement intensity shape demand concentration, with acute interventions commanding premium pricing over routine surveillance testing.
- Surgical Procedures:Perioperative bleeding risk assessment and transfusion guidance drive high-value test utilization in cardiac, orthopedic, and trauma surgery settings. Ambulatory surgical centers in the United States are deploying point-of-care coagulation units to reduce pre-operative screening bottlenecks.
- Cardiovascular Disorders:Anticoagulant therapy monitoring for atrial fibrillation, venous thromboembolism, and mechanical valve patients generates recurring test volume. Direct oral anticoagulant proliferation has fragmented protocols and forced analyzer firmware updates.
- Trauma Care:Massive transfusion protocol activation and goal-directed resuscitation require rapid viscoelastic or point-of-care coagulation assessment.
- Routine Testing:Pre-operative screening and chronic disease surveillance generate high test volumes at lower per-test reimbursement.
Surgical applications anchor revenue concentration while trauma care shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: the United States favors decentralized point-of-care deployment, while Japan and Germany concentrate testing in automated core laboratories. This structural difference shapes instrument specifications, service contract structures, and regulatory submission strategies across markets.
United States
Ambulatory surgical centers and emergency departments drive cartridge-based coagulation analyzer demand to compress perioperative turnaround times. FDA 510(k) pathways mandate predicate device equivalence for novel detection platforms, extending validation timelines for non-incumbent manufacturers. Texas and Florida health systems are consolidating point-of-care networks across integrated delivery networks.
Germany
Reference laboratories in Bavaria and Baden-Württemberg anchor European demand for high-throughput optical detection systems processing 300-plus samples hourly. The In Vitro Diagnostic Regulation's performance evaluation requirements and notified body capacity constraints delay new platform certifications by 12-18 months. Berlin-based university hospitals are piloting cloud-native middleware for remote hematopathologist review.
Japan
Automated sample-handling architectures displace manual pre-analytical processing in Tokyo and Osaka university hospitals, driving replacement cycles for legacy coagulation lines. PMDA consultation procedures emphasize clinical validation against predicate devices for novel detection principles. Nagoya medical centers are deploying integrated consumable-instrument contracts to lock in reagent pull-through economics.
United Kingdom
NHS consolidation of hematology services into regional hub laboratories concentrates instrument placement decisions in Manchester and Birmingham procurement frameworks. MHRA recognition of EU MDR certificates post-Brexit creates parallel conformity assessment pathways for manufacturers. London teaching hospitals are unbundling service contracts from reagent supply agreements.
China
Domestic manufacturers are capturing mid-tier hospital coagulation analyzer placements through NMPA fast-track pathways for innovative devices. Shanghai and Beijing academic medical centers import high-throughput Japanese and German platforms for reference testing. Provincial procurement consortia in Guangdong and Jiangsu are standardizing reagent menus across distributed hospital networks.
Hemostasis Analyzers Market Competitive Environment
Capability concentration sits with specialized optical detection and reagent formulation specialists; scale advantage sits with diversified diagnostics conglomerates with captive distribution networks. The market structures around three tiers: closed-system incumbents with installed base lock-in, diversified life science platforms leveraging cross-selling infrastructure, and regional challengers competing on reagent cost. Dominant competitive moves include integrated consumable-instrument contract bundling and third-party service organization partnerships to capture maintenance revenue disintermediation.
Among diversified diagnostics platforms, Thermo Fisher Scientific Inc. and Siemens Healthineers AG occupy positions spanning centralized laboratory and point-of-care segments through distribution network leverage. Werfen exemplifies the closed-system archetype with reagent-anchored loyalty programs sustaining European and Latin American reference laboratory relationships. Sysmex Corporation represents the automation-focused tier with high-throughput architectures targeting Japanese university hospital replacement cycles.
| Leading Market Players |
|---|
| Werfen |
| Thermo Fisher Scientific Inc. |
| Sysmex Corporation |
| Instrumentation Laboratory |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Diagnostica Stago Inc. |
| Nihon Kohden Corporation |
| F. Hoffmann-La Roche Ltd. |
| Others |
Value Chain & Pricing Dynamics
Bavarian optical component clusters in southern Germany concentrate turbidimetric sensor manufacturing, and their capacity utilization rates directly determine pricing leverage for hemostasis analyzer assemblers negotiating reagent-instrument bundles.
Pricing Analysis
Long-term consumable-instrument contracts dominate procurement, with three-tier pricing structure across premium, standard, and economy levels anchored by throughput capacity and automation grade. Price differentiation hinges on FDA 510(k) clearance tier and reagent menu breadth, with closed-system loyalty programs commanding premiums over open-platform alternatives. Cost compression in mid-tier laboratory lines is intensifying because health system procurement teams are unbundling service contracts from reagent supply. Blood banks show highest price sensitivity due to constrained transfusion service budgets, while Japanese university hospitals prioritize automation over per-test economics.
Supply Chain Analysis
Specialized chromogenic substrates and electrochemical sensor membranes draw from German, Japanese, and United States component specialists. Raw material dependencies center on high-purity optical glass, noble metal electrodes, and stabilized thromboplastin reagents. Single-source vulnerability concentrates in turbidimetric photometer assemblies sourced from Bavarian precision optics manufacturers. Distribution runs through captive reagent logistics networks for closed-system incumbents, while open-platform vendors rely on third-party diagnostic distributors with regional cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemostasis analyzers market is recovering from pandemic-deferred replacement cycles, with hospital laboratory capital budgets normalizing alongside rescheduled surgical backlogs.
For Market Incumbents: Pre-empt third-party service organization encroachment by acquiring independent calibration and quality control specialists in Texas and Florida health systems. Consolidate reagent formulation capacity in European notified body jurisdictions to mitigate IVDR certification bottlenecks. Lock in blood bank instrument placements through extended platelet storage protocol validation partnerships before regional challengers capture transfusion service automation mandates.
For New Entrants and Emerging Players: Latin American reference laboratories present the most penetrable white-space, as Werfen's European-focused loyalty programs leave Brazilian and Mexican diagnostic networks underserved. Target CLIA-waived point-of-care deployment in United States ambulatory surgical centers where emergency department purchasers prioritize DOA cross-reactivity matrices over legacy warfarin-centric systems. Lead with cartridge-based electrochemical platforms that bypass German optical component dependencies.
For Investors and Strategic Acquirers: Long-term, this sits as a consumable-anchored recurring revenue play because reagent pull-through economics dominate hardware margin capture across 7-10 year instrument lifecycles. Target acquisition candidates with certified IVDR technical documentation systems and established Japanese PMDA consultation track records. Monitor FDA de novo pathway submission volumes for novel detection principles as an inflection indicator for competitive entry barriers tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | Accelerates European market access amid notified body capacity constraints. |
| Cloud-Native Middleware Development | Enables remote hematopathologist review for overnight satellite hospital coverage. |
| Reagent-Instrument Bundle Unbundling | Captures procurement team demand for separate maintenance and supply agreements. |
| CLIA-Waived Point-of-Care Expansion | Opens catheterization lab deployment without laboratory oversight requirements. |
| Artificial Intelligence-Enhanced Interpretation | Automates thromboelastography waveform flagging for understaffed overnight shifts. |
Study Parameters
The analysis maps coagulation analyzers, point-of-care devices, platelet function tests, and thromboelastography systems, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and reference laboratory directors. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, PMDA consultation records, IVDR notified body certification databases, and hospital procurement contract repositories. Bottom-up instrument placement counts and top-down reagent consumption estimates were triangulated to anchor market sizing.
Assumptions held surgical volume recovery trajectories and anticoagulant therapy monitoring protocols fixed across the projection horizon, while direct oral anticoagulant interference study requirements and cloud-native middleware adoption rates were varied in sensitivity scenarios. Segmentation dimensions modeled include product architecture, detection technology, end-user facility type, and clinical application urgency. CAGRs were derived from replacement cycle timing and per-test economics evolution, with Japanese university hospital automation upgrade rates and United States ambulatory surgical center point-of-care deployment curves serving as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified diagnostics conglomerates into blood bank automation would shift outcomes through accelerated consolidation. Cross-checking against CMS Medicare laboratory utilization data and Japanese Ministry of Health hospital equipment procurement statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Microplate System Market
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Hematology Analyzers and Reagents Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Blood Bank Analyzers Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Global Pipette Tips Market