
 Global Coagulation Testing Market | 2026-2036
Global Coagulation Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coagulation Testing Market Foresight
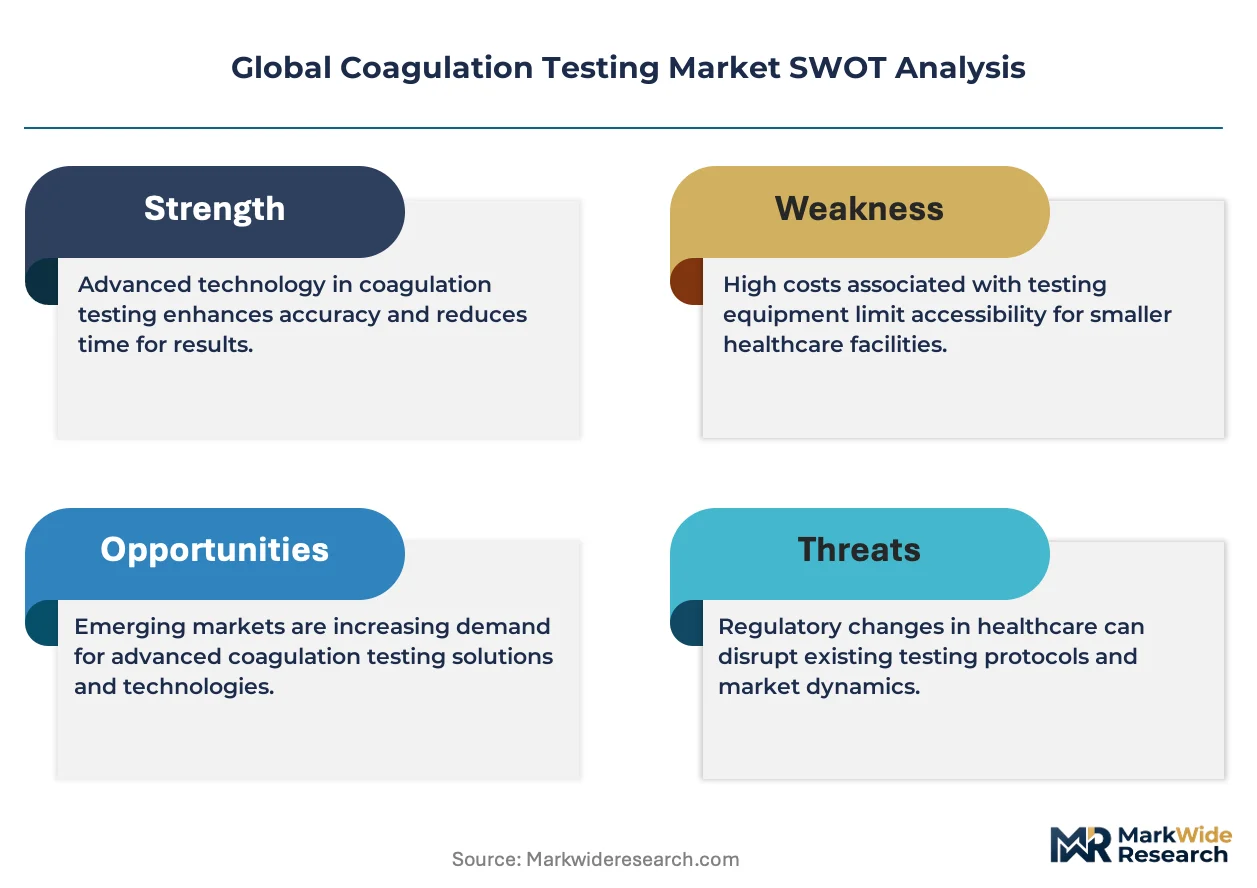
CLIA-waived testing capability is rotating toward the premium tier of coagulation platforms, pulling average selling prices upward as laboratories seek consolidated workflow solutions. Siemens Healthineers leverages its installed base in large reference labs to sustain recurring reagent revenue. Sysmex Corporation dominates hematology-coagulation integration, while Abbott Laboratories specializes in portable point-of-care coagulation meters for ambulatory settings.
Coagulation testing encompasses analytical methods that quantify blood clotting parameters including prothrombin time, activated partial thromboplastin time, and D-dimer concentration through optical, chromogenic, or immunoturbidimetric detection principles. These assays guide anticoagulant dosing decisions, perioperative screening, and thrombotic risk stratification in clinical practice. The technology segment shows optical coagulometry occupying the largest installed base while fluorescence-based methods represent the fastest-expanding category due to sensitivity advantages in low-volume samples. Application demand clusters in anticoagulant therapy management where direct oral anticoagulant monitoring creates new testing protocols beyond traditional warfarin surveillance.
FDA 510(k) clearance requirements and the EU In Vitro Diagnostic Regulation reshape product development timelines and clinical evidence standards for coagulation assay manufacturers. ISO 15189 accreditation pressures diagnostic laboratories to standardize pre-analytical variables and instrument calibration protocols. Stakeholders must monitor how CLIA complexity categorization and regional reimbursement thresholds determine accessible market volume for near-patient coagulation platforms.
Market Dynamics
The FDA's updated guidance on coagulation system monitoring devices is compressing product development timelines while forcing manufacturers to front-load clinical evidence generation, fundamentally restructuring how automated hemostasis platforms reach commercialization.
Growth Catalysts
- CLIA-waived platform consolidation:Hospital laboratories are replacing discrete analyzers with integrated systems that combine optical coagulometry and immunoturbidimetric detection, reducing bench space requirements and technician training overhead.
- Direct oral anticoagulant surveillance protocols:Cardiology departments in Germany and Japan have established routine D-dimer and anti-Xa activity monitoring for patients on apixaban and rivaroxaban, creating sustained reagent consumption curves independent of warfarin volume decline.
- Perioperative screening mandates:The EU In Vitro Diagnostic Regulation's emphasis on pre-surgical hemostasis assessment has accelerated replacement of manual tilt-tube methods with automated platforms in ambulatory surgical centers.
Market Restraints
- Optical component supply concentration:Precision photomultiplier tubes and specialized LED arrays for chromogenic detection rely on a limited supplier base concentrated in Japan and Germany, exposing manufacturers to extended lead times.
- ISO 15189 accreditation burden:Diagnostic laboratories must maintain continuous instrument calibration traceability and participate in external quality assessment schemes, elevating operational overhead for smaller facilities.
- Point-of-care accuracy limitations:Capillary whole blood samples introduce pre-analytical variables including hematocrit effects and tissue fluid contamination that compromise correlation with venous plasma reference methods.
Strategic Opportunities
- Home-based anticoagulant self-monitoring:The United Kingdom's National Health Service has initiated pilot programs reimbursing patient-operated INR meters for stable warfarin users, establishing precedent for decentralized testing reimbursement.
- Fluorescence-based low-volume detection:Convergence of microfluidic sample handling with fluorescence resonance energy transfer chemistry enables pediatric and neonatal coagulation assessment using sub-50 microliter specimen volumes.
- Veterinary hemostasis expansion:Specialty animal hospitals in the United States are adopting species-specific coagulation panels for companion animal thromboprophylaxis during orthopedic and oncologic procedures.
Industry Challenges
- Multidisciplinary calibration expertise:Automated coagulation platforms require simultaneous competency in hematology, immunochemistry, and optical engineering, creating recruitment friction for clinical laboratory science programs.
- Legacy LIS integration complexity:Hospital information systems built on HL7 v2.x standards demand middleware development for bidirectional communication with modern hemostasis analyzers, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coagulation Testing Market |
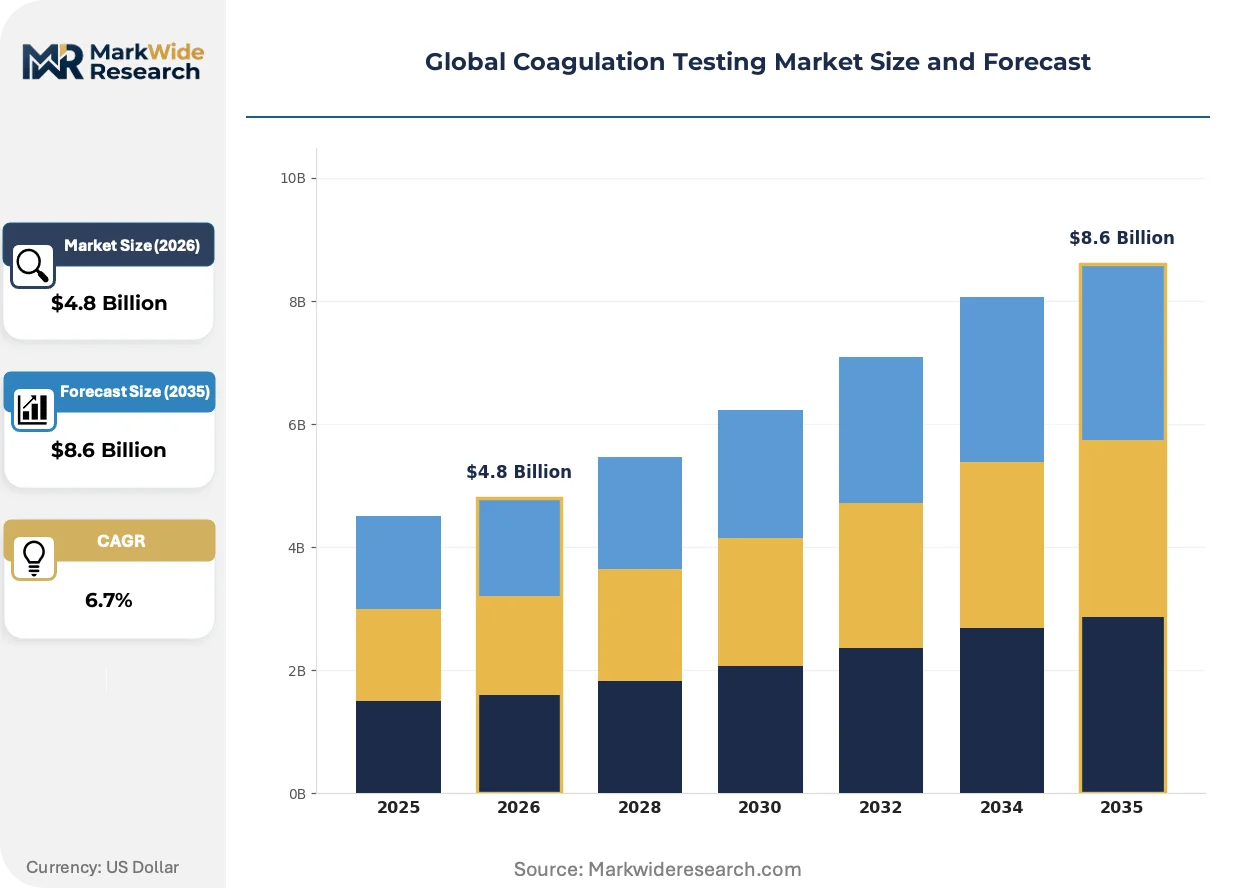
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Partial Thromboplastin Time, Prothrombin Time, Fibrinogen Test, D-Dimer Test, Thrombin Time Technology: Optical Coagulometry, Chromogenic Assays, Immunoturbidimetry, Electrochemical, Fluorescence-Based Application: Bleeding Disorder Diagnosis, Stroke Risk Assessment, Surgical Screening, Thrombosis Monitoring, Anticoagulant Therapy Management End User: Diagnostic Laboratories, Blood Banks, Specialty Clinics, Research Institutes, Home Healthcare |
| Companies Covered | F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Sysmex Corporation, Werfen (Instrumentation Laboratory), Thermo Fisher Scientific Inc., Abbott Laboratories, Danaher Corporation (Beckman Coulter), Diagnostica Stago, Helena Laboratories Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coagulation Testing Market Shifts & Advancements
Fluorescence-based detection methods are compressing the sensitivity gap between central laboratory and near-patient platforms, while regulatory convergence across the FDA and EU MDR is harmonizing clinical evidence requirements for novel coagulation biomarkers.
Microfluidic cartridge technology is miniaturizing traditional optical coagulometry into handheld devices weighing under 500 grams. Community anticoagulation clinics in the United States are deploying these systems for same-visit INR verification, eliminating venipuncture and central lab send-out delays. The technology is miniaturizing the testing footprint from benchtop analyzers requiring dedicated laboratory space to pocket-sized units operable in pharmacy and primary care settings.
The EU In Vitro Diagnostic Regulation's Class C risk classification for coagulation testing devices mandates notified body involvement in quality management system audits and post-market surveillance. Manufacturers must now generate clinical performance data specific to the intended purpose statement, elevating documentation burden but reducing predicate device reliance. Hemostasis assay developers targeting European market access are restructuring regulatory affairs teams to manage parallel FDA 510(k) and EU MDR technical file submissions.
Hospital procurement committees are unbundling reagent supply contracts from instrument placement agreements, forcing manufacturers to compete on per-test economics rather than capital equipment subsidies. Large integrated delivery networks in the United States are consolidating hemostasis testing across multiple hospital sites into centralized core laboratories with automated track-based sample handling. This concentration is most visible in Medicare-dependent regions where laboratory reimbursement compression makes scale economies decisive in vendor selection.
Global Coagulation Testing Market Segmentation
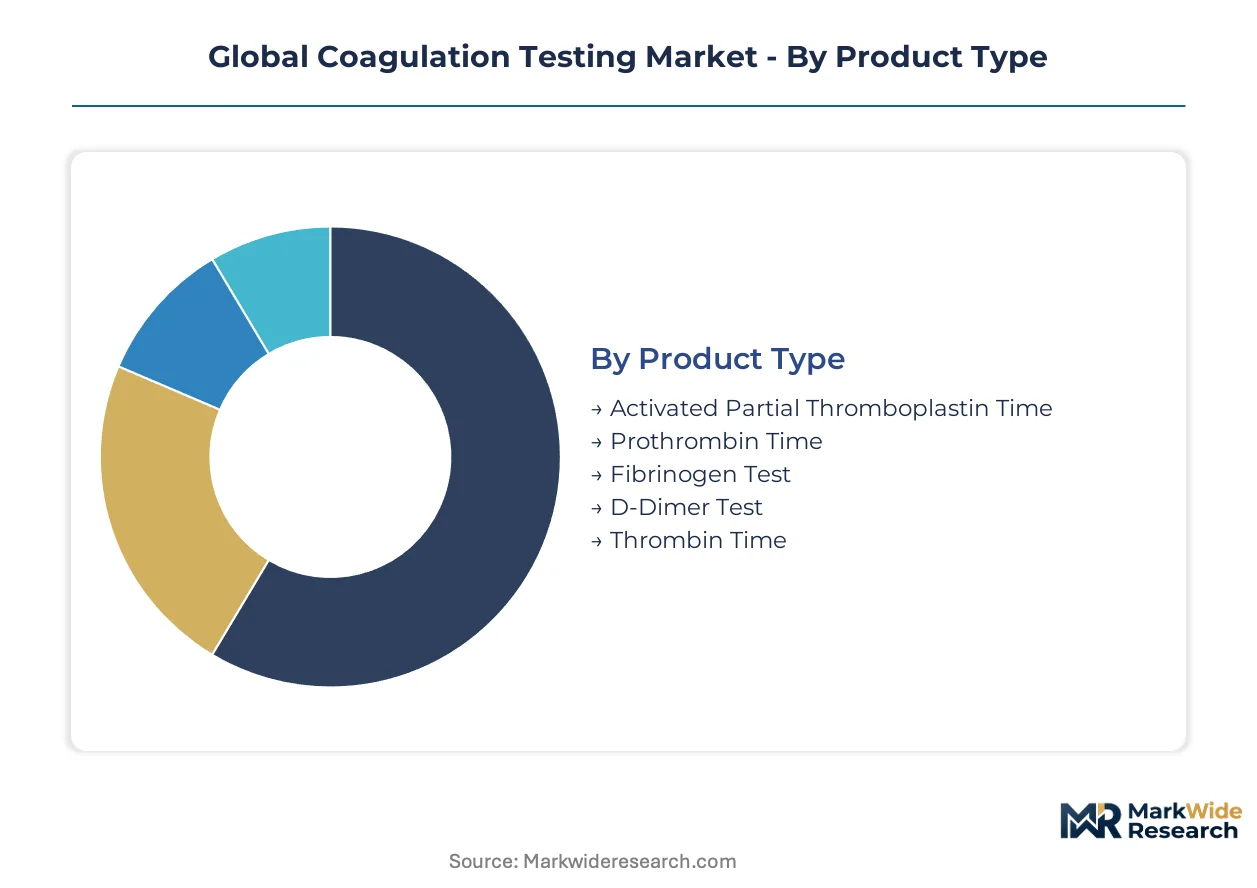
Coagulation testing segmentation reveals distinct procurement patterns across clinical settings. Product portfolios, detection technologies, and care delivery sites each command specialized commercial strategies and regulatory pathways.
Product Type:
Demand for specific coagulation assays concentrates in hospital laboratories across Germany and Japan, while export volumes from US manufacturers supply emerging clinical networks in Brazil and India.
- Prothrombin Time:The foundational assay for warfarin monitoring quantifies extrinsic pathway activity through tissue factor activation. Demand clusters in United States anticoagulation clinics where Medicare reimbursement sustains high testing frequency among elderly populations on chronic vitamin K antagonist therapy.
- D-Dimer Test:This fibrin degradation product assay enables rapid exclusion of thrombotic events through immunoturbidimetric quantification. German emergency departments have standardized D-dimer protocols for pulmonary embolism rule-out, creating sustained reagent consumption independent of hospital admission volume fluctuations.
- Activated Partial Thromboplastin Time:Intrinsic pathway assessment for heparin monitoring dominates perioperative screening in Japanese surgical centers.
- Fibrinogen Test:Quantitative functional assays guide massive transfusion protocols in United States trauma centers.
- Thrombin Time:Direct thrombin inhibitor surveillance supports dabigatran therapy management in United Kingdom hematology units.
Prothrombin Time holds the largest share; momentum sits with D-Dimer Test.
Technology:
Detection methodology determines instrument footprint, sensitivity thresholds, and capital investment requirements across laboratory tiers.
- Optical Coagulometry:Light scattering detection of fibrin clot formation occupies the largest installed base in centralized laboratories. United States reference labs in North Carolina and California maintain multi-thousand sample daily throughput on track-based optical platforms where reagent cost efficiency outweighs capital depreciation schedules.
- Fluorescence-Based:Resonance energy transfer chemistry enables sub-50 microliter sample volumes with enhanced sensitivity for low-concentration analytes. Pediatric hospitals in Boston and Tokyo are adopting fluorescence platforms for neonatal coagulopathy assessment where specimen volume constraints prohibit traditional optical methods.
- Chromogenic Assays:Colorimetric substrate cleavage quantifies specific coagulation factors in German hemostasis reference laboratories.
- Immunoturbidimetry:Antigen-antibody complex detection supports D-dimer and von Willebrand factor quantification in United Kingdom district hospital labs.
- Electrochemical:Amperometric sensing enables handheld point-of-care prothrombin time meters for United States pharmacy-based anticoagulation clinics.
Optical Coagulometry dominates current revenue; Fluorescence-Based platforms are climbing the fastest.
Application:
Clinical use case determines testing frequency, reimbursement coding, and required turnaround time specifications.
- Anticoagulant Therapy Management:Chronic monitoring of warfarin, apixaban, and rivaroxaban therapy generates recurring testing volumes in United States Medicare populations. Cardiology practices in Florida and Arizona operate dedicated anticoagulation clinics where weekly or monthly INR surveillance produces predictable reagent consumption curves.
- Surgical Screening:Preoperative hemostasis assessment mandates have expanded under EU In Vitro Diagnostic Regulation requirements. Ambulatory surgical centers in Bavaria and Baden-Württemberg have replaced manual tilt-tube methods with automated platforms to comply with documented pre-analytical standardization.
- Thrombosis Monitoring:Post-operative deep vein thrombosis surveillance drives D-dimer testing in Japanese orthopedic hospitals.
- Bleeding Disorder Diagnosis:Comprehensive coagulation panels for hemophilia and von Willebrand disease evaluation concentrate in United Kingdom specialized hemophilia treatment centers.
- Stroke Risk Assessment:Atrial fibrillation patient stratification supports point-of-care testing in United States neurology practices.
Anticoagulant Therapy Management commands the largest share; Surgical Screening shows the steepest expansion trajectory.
End User:
Site-of-care differentiation shapes instrument form factor, connectivity requirements, and service support models.
- Diagnostic Laboratories:High-volume centralized facilities in the United States, Germany, and Japan consolidate hemostasis testing through automated track-based systems. Integrated delivery networks in Texas and Pennsylvania have concentrated coagulation testing into single core laboratories serving multiple hospital sites to capture scale economies under reimbursement compression.
- Home Healthcare:Patient-operated INR meters enable decentralized warfarin monitoring with pharmacy or telephone-based dose adjustment. The United Kingdom National Health Service pilot programs in Birmingham and Manchester have established reimbursement precedent for home-based testing among stable anticoagulation patients.
- Specialty Clinics:Cardiology and hematology ambulatory practices in United States metropolitan areas deploy CLIA-waived platforms for same-visit result availability.
- Blood Banks:Donor screening and component therapy quality control drive coagulation testing in German Red Cross regional centers.
- Research Institutes:Academic medical centers in Boston and Tokyo utilize specialized coagulation research assays for thrombosis mechanism studies.
Diagnostic Laboratories retain the largest share; Home Healthcare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical component suppliers cluster in Japan and Germany, concentrating precision photomultiplier tube and LED array manufacturing for chromogenic detection systems. This geographic concentration shapes procurement timelines and calibration standard availability for hemostasis platform manufacturers worldwide.
United States
Medicare reimbursement sustains high-frequency INR surveillance among elderly populations on chronic warfarin therapy. FDA 510(k) clearance requirements compress development timelines while mandating front-loaded clinical evidence. Anticoagulation clinics in Florida and Arizona generate predictable reagent consumption through weekly or monthly testing protocols.
Germany
Emergency departments in Bavaria and Baden-Württemberg have standardized D-dimer protocols for pulmonary embolism rule-out. EU MDR Class C risk classification mandates notified body involvement in quality management audits. Reference laboratories in North Rhine-Westphalia maintain multi-thousand sample daily throughput on track-based optical platforms.
Japan
Aging demographics drive chronic anticoagulant therapy volumes in cardiology departments nationwide. PMDA regulatory frameworks align with international standards while maintaining distinct post-market surveillance requirements. Tokyo pediatric hospitals adopt fluorescence platforms for neonatal coagulopathy assessment where specimen volume constraints prohibit traditional methods.
United Kingdom
NHS pilot programs in Birmingham and Manchester have established reimbursement precedent for patient-operated INR meters among stable warfarin users. ISO 15189 accreditation pressures diagnostic laboratories to standardize pre-analytical variables and instrument calibration. District hospital labs deploy immunoturbidimetric detection for D-dimer and von Willebrand factor quantification.
Global Coagulation Testing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the coagulation testing landscape. The market structure consolidates around integrated diagnostic conglomerates with installed base advantages and recurring reagent revenue streams, while specialized hemostasis firms occupy niche positions in reference laboratory and research applications. Three archetypes dominate: diversified medtech conglomerates with cross-platform portfolios, hematology-coagulation integration specialists, and point-of-care portability innovators. Competitive moves concentrate on CLIA-waived platform consolidation and fluorescence-based low-volume detection capability expansion.
Among diversified conglomerates, F. Hoffmann-La Roche Ltd and Siemens Healthineers AG exemplify scale-driven positions anchored in large reference laboratory installed bases. Sysmex Corporation occupies a distinct tier specializing in hematology-coagulation integration, while Abbott Laboratories represents the portable point-of-care archetype for ambulatory settings. These three players collectively illustrate the strategic segmentation between centralized laboratory automation and decentralized near-patient testing.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Sysmex Corporation |
| Werfen (Instrumentation Laboratory) |
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| Danaher Corporation (Beckman Coulter) |
| Diagnostica Stago |
| Helena Laboratories Corporation |
| Others |
Supply & Pricing Matrix
Fluorescence resonance energy transfer chemistry replacing traditional optical coagulometry in pediatric applications simultaneously shifts component sourcing toward Japanese precision photonics clusters and compresses per-test economics through reduced reagent volumes. This substitution dynamic reconfigures procurement geography while pressuring legacy platform pricing in centralized laboratories.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across coagulation testing platforms, with CLIA-waived portable devices commanding premium positioning against laboratory-grade systems. Three-tier pricing stratifies across high-throughput reference lab installations, mid-tier hospital laboratory consolidations, and point-of-care economy units. Pricing pressure stems from Medicare reimbursement compression in United States anticoagulation clinics, where per-test economics now dominate procurement committee decisions. Diagnostic laboratories exhibit highest price sensitivity due to ISO 15189 accreditation overhead, while research institutes demonstrate lowest sensitivity given grant-funded capital budgets.
Supply Chain Analysis
Strategic stockpiling of precision photomultiplier tubes and specialized LED arrays characterizes inventory management among hemostasis platform manufacturers facing extended lead times from Japanese and German optical component suppliers. Raw material dependencies center on rare-earth phosphors for fluorescence detection, chromogenic substrates for enzymatic assays, and high-purity reagents for immunoturbidimetric quantification. Single-source vulnerability concentrates in photonics manufacturing clusters concentrated around Osaka and Munich. Distribution runs through specialized diagnostic distributors serving hospital systems and direct manufacturer relationships with large integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Simultaneous competency gaps across hematology, immunochemistry, and optical engineering constrain platform development velocity, creating asymmetric returns for organizations that consolidate multidisciplinary calibration expertise. This capability scarcity favors incumbents with established training pipelines and punishes entrants lacking clinical laboratory science partnerships.
For Market Incumbents: Secure recurring reagent revenue streams by unbundling instrument placement agreements from supply contracts, responding to hospital procurement committee demands for per-test transparency. Invest in backward integration into chromogenic substrate manufacturing to defend margin position against raw material cost volatility. Prioritize fluorescence-based platform development to preempt substitution threats from pediatric and neonatal testing segments where specimen volume constraints favor sensitivity advantages. For New Entrants and Emerging Players: CLIA-waived certification fast-tracks offer the most penetrable pathway for handheld coagulometry devices targeting United States pharmacy-based anticoagulation clinics underserved by venipuncture-dependent workflows. Target ambulatory surgical centers in Germany's Bavaria and Baden-Württemberg regions where EU In Vitro Diagnostic Regulation mandates have accelerated replacement of manual tilt-tube methods. Pursue direct-to-clinic distribution bypassing traditional diagnostic distributors to capture pricing flexibility. For Investors and Strategic Acquirers: EU MDR Class C risk classification implementation reshapes the acquisition landscape by elevating documentation burden for European market access and rewarding targets with established notified body relationships. Five-to-ten year viability favors hemostasis assay developers with parallel FDA 510(k) and EU MDR technical file capabilities over pure-play point-of-care portability innovators facing reimbursement uncertainty. Monitor United Kingdom National Health Service home-based INR meter pilot program expansion as signal for decentralized testing reimbursement precedent viability.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorescence Platform Development | Enables pediatric coagulopathy assessment in Boston and Tokyo neonatal intensive care units. |
| CLIA-Waived Certification Investment | Unlocks pharmacy-based anticoagulation clinic access in United States Medicare-dependent regions. |
| Reagent Supply Contract Unbundling | Aligns vendor economics with hospital procurement committee per-test transparency demands. |
| Optical Component Supplier Diversification | Mitigates lead time exposure from Osaka and Munich photonics manufacturing concentration. |
| Home Healthcare Reimbursement Strategy | Captures Birmingham and Manchester NHS pilot program precedent for patient-operated INR meters. |
Research Methodology
Cross-validation between hospital procurement database analysis and clinical laboratory director interviews anchors the qualitative findings in operational reality. Primary fieldwork encompassed hemostasis platform engineers, biomedical equipment procurement managers, GPO contracts specialists, and regulatory affairs leads at diagnostic manufacturers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body technical file registries, CMS Medicare reimbursement schedules, and hospital accreditation audit records. Bottom-up instrument installation tracking and top-down reagent revenue estimates triangulate market sizing.
Sensitivity analysis around reimbursement compression scenarios and optical component supply disruption probabilities stress-tests base case projections across the analysis window. Segmentation modeling incorporates product type tiers, detection technology footprints, clinical application frequencies, and end-user site-of-care differentiation. CAGRs derive from reagent consumption curve analysis tied to anticoagulant therapy population demographics and surgical screening mandate implementation timelines. Forecast inputs include PMDA regulatory alignment trajectories and fluorescence platform adoption rates in specimen-volume-constrained settings.
Decision-makers should treat outputs as directional under assumptions of sustained Medicare reimbursement for INR surveillance and stable Japanese-German optical component trade flows; material deviation would warrant model refresh. Revision becomes warranted when CLIA complexity reclassification or EU MDR implementation delays cross threshold levels affecting platform commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Efficacy Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Fungal Testing Kits Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Middle East and Africa IVD Regulatory Affairs Outsourcing Market
Testing Services
Americas Sterility Testing Market
Testing Services
US Cannabis Testing Market
Testing Services
Point of Care Lipid Test Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Blood Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Lab Screening Test Kit Market
Testing Services
Pyrogen Testing Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Pharmaceutical Dissolution Testing Services Market