
 Capillary Blood Collection Tubes Market | 2026-2036
Capillary Blood Collection Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Capillary Blood Collection Tubes Market Analysis
The EU MDR is decoupling legacy plastic tube formulations from European hospital procurement lists as biocompatibility documentation requirements tighten. Becton, Dickinson and Company leverages its vertically integrated polymer supply chain to sustain certification breadth across multiple tube formats. Greiner Bio-One International GmbH anchors Central European manufacturing capacity while SARSTEDT AG & Co. KG differentiates through specialized hemostasis measurement tube designs.
Capillary blood collection tubes are cylindrical vessels engineered to collect small-volume blood samples through capillary action or micro-vacuum draw, typically manufactured from medical-grade polyethylene terephthalate or borosilicate glass with interior coatings that prevent clot activation or promote serum separation. Their primary purpose is to preserve sample integrity from collection through laboratory analysis for hematological, biochemical, and immunological assays. Plastic tubes occupy the dominant volume position due to breakage resistance and cost efficiency in high-throughput diagnostic labs, while gel separator technology captures expanding margin pools as laboratories automate pre-analytical processing workflows. Infectious disease testing represents the fastest-growing application segment as decentralized screening programs multiply collection points beyond traditional hospital settings.
The FDA enforces quality system regulation and 510(k) premarket notification pathways for capillary blood collection devices, while the EU MDR mandates clinical evidence and post-market surveillance documentation that smaller manufacturers struggle to assemble. ISO 6710 standards govern tube dimensions, draw volumes, and additive concentrations that ensure interoperability with automated analyzers. Stakeholders must monitor how evolving hemostasis measurement performance specifications reshape competitive positioning between integrated diagnostic platform vendors and standalone tube suppliers.
Market Dynamics
Decentralized diagnostic testing is fragmenting demand across home healthcare networks, pharmacy clinics, and remote screening sites, forcing manufacturers to reconfigure distribution architectures around micro-volume sampling workflows.
Growth Catalysts
- Point-of-care expansion:Home healthcare agencies and retail pharmacy clinics are deploying capillary collection devices for HbA1c monitoring and infectious disease screening, extending reach beyond hospital laboratories.
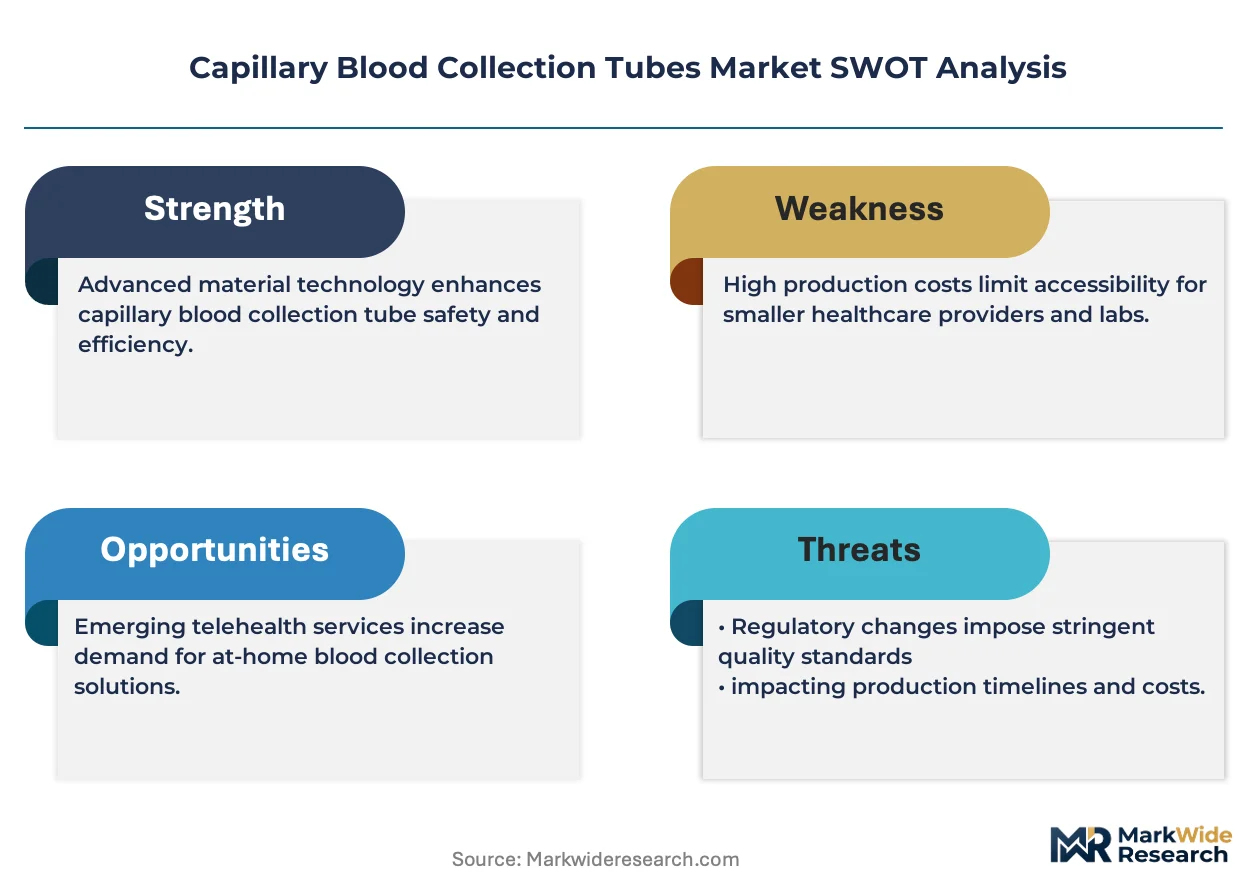
- EU MDR compliance pressure:Biocompatibility documentation requirements under the EU Medical Device Regulation are accelerating replacement of legacy plastic formulations with certified medical-grade polyethylene terephthalate alternatives.
- Gel separator automation:Pre-analytical processing automation in high-throughput hematology labs is driving specification upgrades toward integrated serum separation technologies.
Market Restraints
- Petrochemical input volatility:Medical-grade polymer resin prices fluctuate with crude oil markets, compressing margin stability for tube manufacturers without captive supply arrangements.
- Central European production concentration:Manufacturing clusters in Germany and Austria create geographic risk exposure for pan-European distribution networks facing logistics disruptions.
- Glass-to-plastic substitution ceiling:Borosilicate glass retains irreplaceable performance in specific coagulation assays, limiting full material conversion despite plastic cost advantages.
Strategic Opportunities
- Asia-Pacific regulatory harmonization:China's NMPA and Japan's PMDA are converging toward ISO 6710 dimensional standards, opening pathway for unified product platforms across East Asian markets.
- Hemostasis measurement specialization:Specialized tube designs for thrombophilia screening and perioperative coagulation monitoring command premium positioning in reference laboratory segments.
- Direct-to-patient channel development:Telehealth platforms and at-home testing subscription services are creating new procurement pathways bypassing traditional hospital supply chains.
Industry Challenges
- Additive chemistry expertise scarcity:Formulation of clot activators, anticoagulants, and gel separators requires specialized polymer chemistry talent that diagnostic device manufacturers struggle to recruit.
- 510(k) pathway timeline compression:FDA quality system regulation documentation requirements for new tube formats extend development cycles, delaying revenue realization from design iterations.
- Analyzer interoperability verification:Automated hematology and chemistry platforms from Beckman Coulter, Roche, and Siemens demand proprietary fit testing that fragments standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capillary Blood Collection Tubes Market |
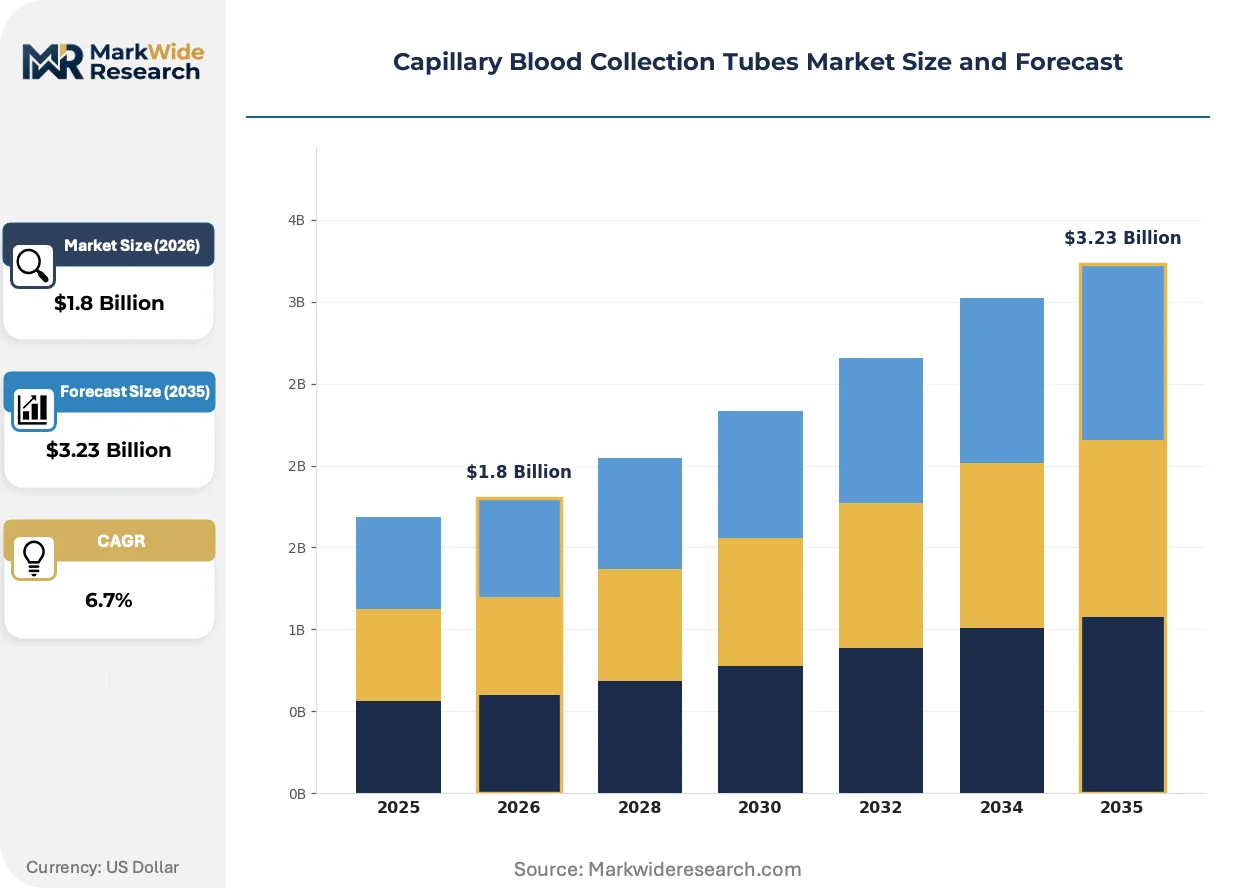
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Tubes, Glass Tubes, Coagulation Tubes, Serum Tubes Application: Clinical Diagnostics, Blood Typing, Therapeutic Drug Monitoring, Infectious Disease Testing End User: Hospitals, Diagnostic Labs, Home Healthcare, Blood Banks Technology: Vacuum Technology, Capillary Action, Gel Separators, Hemostasis Measurement |
| Companies Covered | Becton, Dickinson and Company, Greiner Bio-One International GmbH, SARSTEDT AG & Co. KG, Terumo Medical Corp., Cardinal Health, B. Braun Melsungen AG, Abbott Laboratories, Improve Medical, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capillary Blood Collection Tubes Market Emerging Trajectories
Micro-volume sampling architectures are converging with connected health infrastructure, reshaping how specimen integrity is maintained from fingerstick to laboratory information system.
Microfluidic-integrated capillary tubes are integrating embedded sensors for real-time sample quality monitoring during transport. Emergency medicine departments and air ambulance services are piloting these devices to flag hemolysis or temperature excursions before laboratory handoff. This convergence is compressing the pre-analytical error window that traditionally accounted for the majority of diagnostic test failures.
The EU MDR's post-market surveillance requirements are mandating clinical evidence documentation for all legacy tube formats sold in European Economic Area member states. Manufacturers must now maintain vigilance databases tracking adverse events across distributed collection networks. Hematology tube categories face the steepest compliance burden due to their direct impact on transfusion safety decisions.
Hospital procurement departments are consolidating vendor panels around full-line suppliers capable of delivering tube-additive-analyzer compatibility guarantees. Group purchasing organizations in the United States are awarding sole-source contracts to manufacturers with vertically integrated polymer compounding and coating capabilities. This concentration is most pronounced in integrated delivery networks operating across multiple states under unified supply chain governance.
Capillary Blood Collection Tubes Market Segmentation
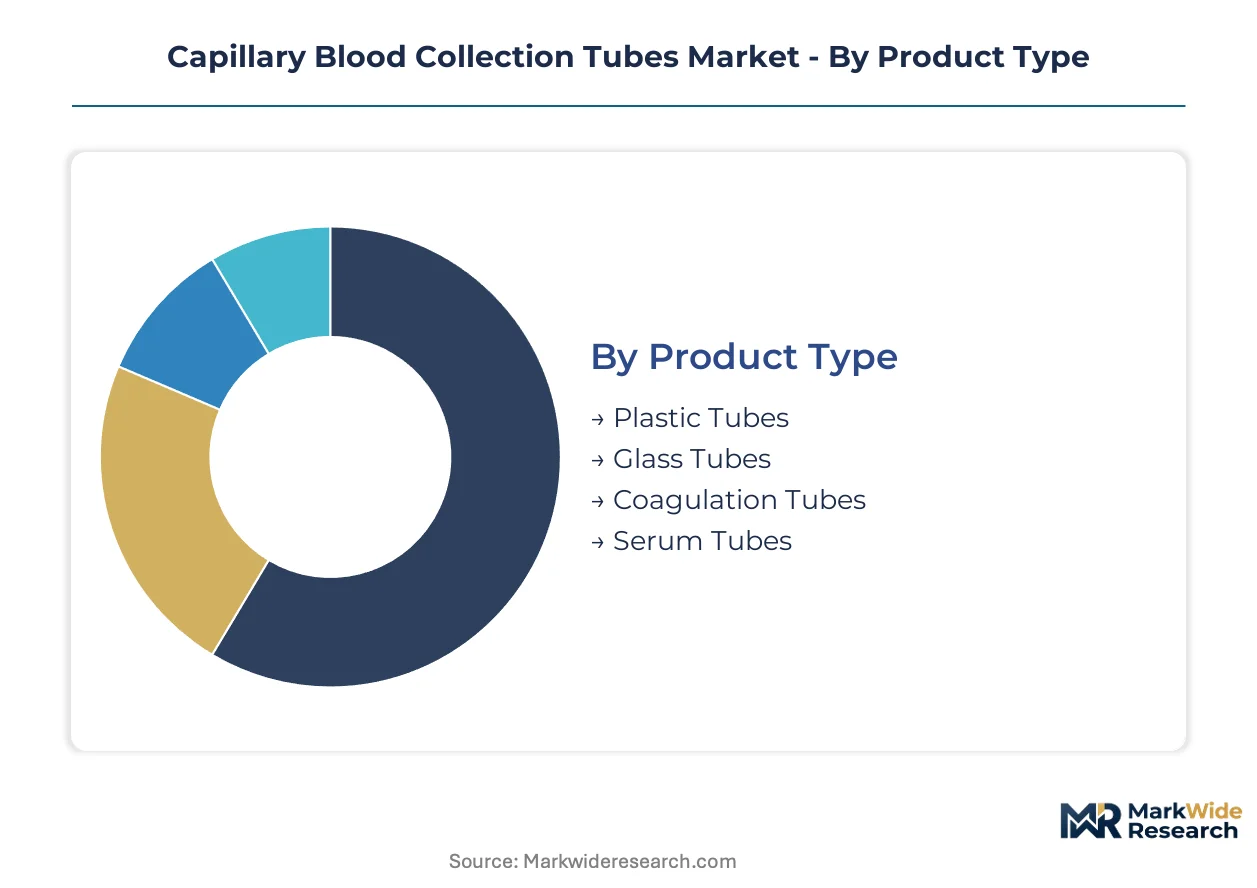
Tube material chemistry and collection mechanism specifications determine compatibility with automated analyzers and point-of-care workflows. Segmentation reveals where procurement budgets are concentrating across hospital networks, reference laboratories, and decentralized testing sites.
Product Type:
Replacement cycles accelerate where legacy formulations fail EU MDR biocompatibility documentation requirements.
- Plastic Tubes:Medical-grade polyethylene terephthalate construction delivers breakage resistance and cost efficiency for high-throughput diagnostic labs. Demand concentrates in Germany and Austria, where Greiner Bio-One and SARSTEDT anchor manufacturing clusters serving pan-European distribution networks facing logistics disruption risks.
- Glass Tubes:Borosilicate glass retains irreplaceable performance in specific coagulation assays, limiting full material conversion despite plastic cost advantages. Central European production concentration creates geographic exposure for supply chains dependent on German and Austrian manufacturing nodes.
- Coagulation Tubes:Specialized additive formulations for hemostasis measurement command premium positioning in reference laboratory segments.
- Serum Tubes:Gel separator integration supports pre-analytical processing automation in high-volume hematology workflows.
Volume placements concentrate in Plastic Tubes; the faster expansion belongs to Coagulation Tubes.
Application:
Cost tier stratification separates high-frequency screening programs from low-volume specialty testing.
- Clinical Diagnostics:Comprehensive metabolic panels and routine hematology assays drive baseline consumption across hospital and laboratory networks. Procurement concentrates in integrated delivery networks consolidating vendor panels around full-line suppliers with vertically integrated polymer capabilities.
- Infectious Disease Testing:Decentralized screening programs multiply collection points beyond traditional hospital settings. Point-of-care expansion in home healthcare agencies and retail pharmacy clinics accelerates micro-volume sampling device adoption for rapid pathogen detection.
- Blood Typing:Transfusion safety protocols mandate precise sample integrity standards in blood bank networks.
- Therapeutic Drug Monitoring:Specialized assays for immunosuppressant and antiepileptic drug levels serve transplant and neurology patient populations.
Clinical Diagnostics captures the highest absolute placement volumes; Infectious Disease Testing is climbing the fastest as decentralized testing fragments demand.
End User:
Customer type differentiation separates centralized high-throughput facilities from distributed low-volume sites.
- Diagnostic Labs:Automated pre-analytical processing workflows drive specification upgrades toward integrated serum separation technologies. Beckman Coulter, Roche, and Siemens platforms demand proprietary fit testing that fragments standardization efforts across independent laboratory networks.
- Home Healthcare:Telehealth platforms and at-home testing subscription services create procurement pathways bypassing traditional hospital supply chains. Fingerstick-to-laboratory workflows require micro-volume architectures compatible with connected health infrastructure.
- Hospitals:Emergency medicine departments and air ambulance services pilot microfluidic-integrated devices for real-time sample quality monitoring.
- Blood Banks:Transfusion safety decisions impose the steepest EU MDR post-market surveillance compliance burden on hematology tube categories.
Diagnostic Labs maintain the dominant placement share; Home Healthcare is gaining share fastest as point-of-care networks extend reach.
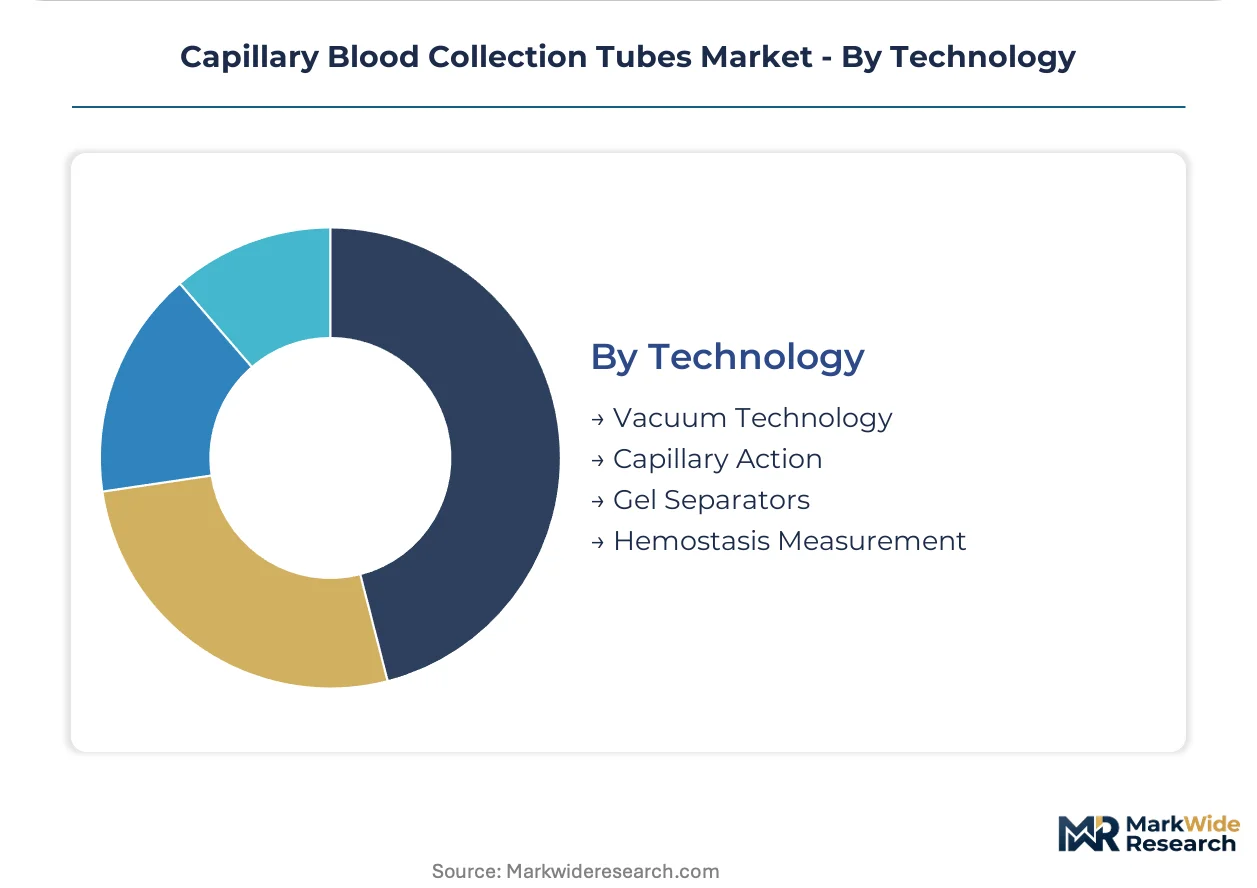
Technology:
Margin structure varies sharply by additive chemistry complexity and analyzer interoperability requirements.
- Gel Separators:Pre-analytical processing automation in high-throughput settings drives premium positioning. Formulation expertise for serum separation media requires specialized polymer chemistry talent that diagnostic device manufacturers struggle to recruit.
- Hemostasis Measurement:Thrombophilia screening and perioperative coagulation monitoring command specialized tube designs. SARSTEDT differentiates through proprietary hemostasis measurement tube architectures serving reference laboratory segments.
- Vacuum Technology:Micro-vacuum draw mechanisms enable standardized fill volumes across variable collection conditions.
- Capillary Action:Passive collection through surface tension physics supports minimal-equipment deployment in resource-limited settings.
Gel Separators dominate current revenue contribution; Hemostasis Measurement shows the steepest expansion trajectory as specialized coagulation testing proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kremsmünster and Nümbrecht anchor European manufacturing density for capillary blood collection tubes, while regulatory divergence across major economies fragments certification pathways for tube manufacturers seeking multi-jurisdictional placement.
Germany
Diagnostic laboratory automation and blood bank network consolidation drive specification upgrades toward gel separator technologies. The EU MDR mandates clinical evidence documentation for legacy tube formats, accelerating replacement cycles in hospital procurement. Kremsmünster and Frickenhausen production clusters serve pan-European distribution through Greiner Bio-One and SARSTEDT manufacturing nodes.
United States
Point-of-care expansion in retail pharmacy clinics and home healthcare agencies multiplies collection points beyond traditional hospital settings. FDA quality system regulation and 510(k) premarket notification pathways govern tube format approvals, extending development timelines. North Carolina and New Jersey host manufacturing and distribution infrastructure serving integrated delivery networks under unified supply chain governance.
China
Decentralized screening programs and telehealth platform proliferation accelerate micro-volume sampling device adoption. The NMPA converges toward ISO 6710 dimensional standards, opening pathways for unified product platforms. Yangtze River Delta manufacturing corridors concentrate domestic production capacity for hospital and diagnostic laboratory networks.
Japan
Aging demographics and chronic disease monitoring protocols sustain demand for home-based blood collection workflows. PMDA regulatory frameworks emphasize post-market surveillance documentation aligned with international standards. Kanto region diagnostic device manufacturing clusters support precision tube specifications for automated analyzer interoperability.
India
Infectious disease screening program scale-up and rural healthcare network extension create procurement volume in decentralized settings. CDSCO medical device regulations tighten quality system requirements for imported and domestically manufactured tubes. Maharashtra and Karnataka host diagnostic reagent and consumable manufacturing corridors serving South Asian distribution networks.
Capillary Blood Collection Tubes Market Vendor Landscape
Premium-margin players sit above commodity-margin players across additive chemistry complexity and analyzer interoperability certification breadth. The vendor base stratifies between full-line suppliers with captive polymer compounding capabilities and specialized tube designers serving reference laboratory segments. Three archetypes dominate: vertically integrated polymer compounders, hemostasis measurement specialists, and platform-agnostic commodity suppliers. Competitive moves concentrate on M&A for additive chemistry expertise and capacity expansion in Central European manufacturing corridors.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Abbott Laboratories occupy positions spanning diagnostic platforms and consumable supply chains. Greiner Bio-One International GmbH and SARSTEDT AG & Co. KG exemplify the Central European manufacturing archetype, with geographic naming conventions indicating Austrian and German origins respectively. Terumo Medical Corp. and B. Braun Melsungen AG represent Japanese and German precision manufacturing traditions in blood management devices.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Greiner Bio-One International GmbH |
| SARSTEDT AG & Co. KG |
| Terumo Medical Corp. |
| Cardinal Health |
| B. Braun Melsungen AG |
| Abbott Laboratories |
| Improve Medical |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Gel separator technology migration toward automated pre-analytical processing workflows is compressing cost structures for high-throughput laboratories while simultaneously concentrating procurement power among full-line suppliers with captive polymer compounding capabilities in Germany and Austria.
Pricing Analysis
Throughput-based pricing anchors procurement negotiations as hospital networks and diagnostic laboratories prioritize total cost-per-test over unit tube costs. Three-tier pricing structure across premium, standard, and economy levels separates gel separator tubes with analyzer compatibility guarantees from commodity plastic formats and glass specialty products. Pricing pressure stems from petrochemical input volatility in medical-grade polyethylene terephthalate resins, squeezing margin stability for manufacturers without backward integration into polymer supply. Group purchasing organizations exhibit highest price sensitivity through consolidated vendor panels, while reference laboratories serving hemostasis measurement applications demonstrate lowest sensitivity due to premium positioning of specialized additive formulations.
Supply Chain Analysis
EU MDR biocompatibility documentation requirements function as qualification gates that exclude legacy plastic tube formulations from European hospital procurement lists, filtering supplier eligibility toward manufacturers with certified medical-grade polymer capabilities. Manufacturing concentrates in Germany, Austria, and the United States, with Kremsmünster and Frickenhausen clusters anchoring European capacity and North Carolina infrastructure serving integrated delivery networks. Raw material dependencies center on medical-grade polyethylene terephthalate resin, borosilicate glass, and proprietary gel separator formulations. Single-source vulnerability in Central European production nodes creates geographic risk exposure for pan-European distribution networks facing logistics disruptions. Distribution runs through group purchasing organizations and hospital supply chains in developed markets, with direct-to-patient channels emerging through telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capillary blood collection tube supply is tightening around additive chemistry expertise scarcity, with specialized polymer formulation talent bottlenecks propping pricing power for incumbent manufacturers with established R&D benches.
For Market Incumbents: Deepen backward integration into medical-grade polymer resin supply to insulate margin stability from petrochemical input volatility. Expand gel separator formulation capacity in Kremsmünster manufacturing corridors to capture specification upgrades toward automated pre-analytical processing workflows. Fortify EU MDR clinical evidence documentation for legacy tube formats before post-market surveillance deadlines accelerate replacement cycles. For New Entrants and Emerging Players: The mid-tier price-point gap between premium gel separator tubes and economy plastic formats offers white-space entry through hemostasis measurement specialization. Target Asia-Pacific regulatory harmonization opportunities as China's NMPA and Japan's PMDA converge toward ISO 6710 dimensional standards. Pursue direct-to-patient channel partnerships with telehealth platforms and at-home testing subscription services bypassing traditional hospital supply chain gatekeepers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified diagnostic conglomerates seeking additive chemistry expertise and Central European manufacturing footprint. Long-term viability favors manufacturers with vertically integrated polymer compounding capabilities and analyzer interoperability certification breadth across Beckman Coulter, Roche, and Siemens platforms. Monitor EU MDR post-market surveillance compliance burden as inflection indicator for supplier consolidation velocity in hematology tube categories.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Documentation | Post-market surveillance requirements accelerate replacement cycles for legacy tube formats in European Economic Area member states. |
| Gel Separator Formulation Expansion | Pre-analytical processing automation in high-throughput hematology labs drives specification upgrades toward integrated serum separation technologies. |
| Asia-Pacific Regulatory Harmonization | Convergence toward ISO 6710 dimensional standards opens pathway for unified product platforms across China's NMPA and Japan's PMDA jurisdictions. |
| Direct-to-Patient Channel Development | Telehealth platforms and at-home testing subscription services create procurement pathways bypassing traditional hospital supply chain governance. |
| Hemostasis Measurement Specialization | Thrombophilia screening and perioperative coagulation monitoring command premium positioning in reference laboratory segments. |
Methodological Framework
Document review covered FDA 510(k) premarket notification databases, EU MDR clinical evidence documentation, and ISO 6710 dimensional standards, complemented by interviews with hospital procurement managers, diagnostic laboratory directors, biomedical engineers, and group purchasing organization contracts specialists. Secondary validation drew from hospital procurement databases, GPO contract filings, and regulatory submission records. Bottom-up unit economics triangulated against top-down market sizing across product type, application, end user, and technology segmentation dimensions.
Segment-level projections across plastic tubes, glass tubes, coagulation tubes, and serum tubes were generated through analyzer interoperability demand modeling and point-of-care expansion trajectory analysis. CAGRs were derived from replacement cycle timing tied to EU MDR compliance deadlines and infectious disease testing program scale-up patterns. Industry-specific inputs included automated hematology platform installation rates and microfluidic-integrated tube pilot program adoption curves.
Inputs from hospital procurement databases and regulatory filing records were available through the study window; gaps in real-time additive chemistry formulation cost data introduce uncertainty bands around margin structure projections. Forecasts reflect assumptions regarding EU MDR enforcement consistency and petrochemical input price stabilization. A model refresh is warranted upon material change in FDA quality system regulation documentation timelines or Central European logistics disruption frequency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Laboratory Equipment and Disposables Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
South Korea Pipette Tips Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Blood Bank Analyzers Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Hotplate Stirrers Market